
 Global Thin Film Solar Cells Market | 2026-2036
Global Thin Film Solar Cells Market Size, Share, and Industry Trends Forecast 2026-2036
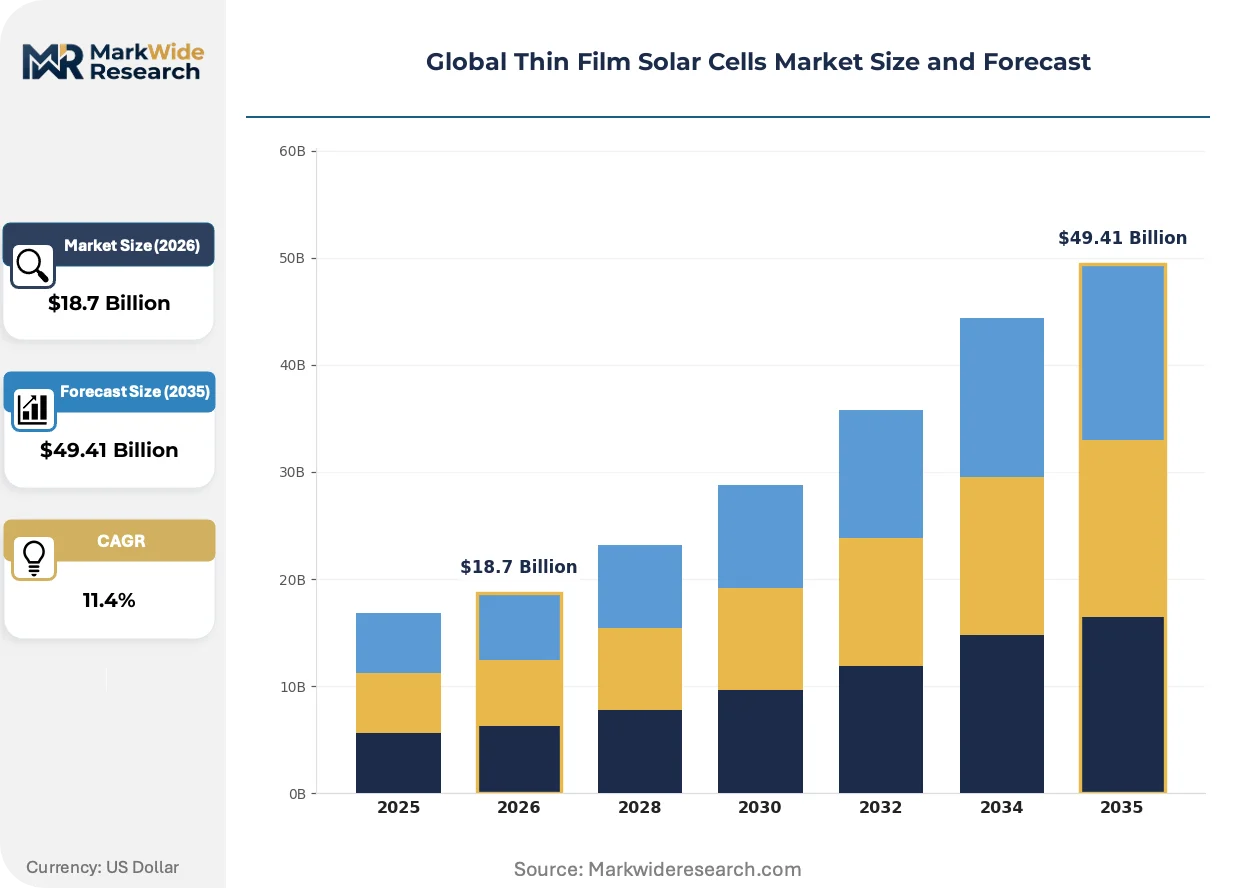
Global Thin Film Solar Cells Market Outlook
Perovskite tandem architectures are repositioning thin film economics toward higher conversion efficiencies at lower temperature coefficients. First Solar leverages vertically integrated cadmium-telluride manufacturing across Ohio and Malaysia to dominate utility-scale procurement in North America. Hanwha Qcells anchors its competitive position through rigid-technology R&D intensity in South Korea, while Oxford Photovoltaics specializes in perovskite-silicon tandem commercialization for building-integrated applications in Europe.
Thin film solar cells comprise photovoltaic layers deposited onto glass, metal, or polymer substrates through chemical vapor deposition or sputtering, typically achieving thicknesses below ten micrometers while converting sunlight at module efficiencies ranging from ten to twenty-two percent depending on semiconductor chemistry. Cadmium telluride captures the largest installed base among product types due to its mature manufacturing ecosystem and low levelized cost of energy. Copper indium gallium selenide occupies premium niche applications where lightweight flexible form factors justify higher unit costs, while organic photovoltaics remain in pilot-scale deployment for building-integrated and portable power segments.
The EU Green Deal and F-Gas Regulation are tightening fluorinated gas controls across European thin film manufacturing, while India's PLI scheme and BIS certification mandate are reshaping import substitution and domestic module assembly requirements. The IRA production tax credits in the United States are redirecting capital toward domestic thin film capacity expansion. Stakeholders must monitor evolving perovskite stability standards and cadmium handling protocols as these regulatory and technical thresholds determine market access and project finance eligibility across jurisdictions.
Market Dynamics
Perovskite-silicon tandem architectures are compressing the efficiency gap with crystalline silicon while cadmium-telluride manufacturers exploit IRA production incentives to reshore supply chains. This dual-track technology evolution is fragmenting procurement patterns across utility-scale and distributed generation segments.
Growth Catalysts
- IRA Production Tax Credits:Domestic manufacturing incentives in the United States are redirecting capital toward Ohio and Alabama thin film facilities. First Solar's vertically integrated cadmium-telluride operations exemplify this reshoring momentum.
- EU Green Deal Carbon Border Adjustments:European import tariffs on carbon-intensive solar modules are privileging locally produced thin film alternatives. German and French project developers now specify low-carbon supply chain documentation.
- Building-integrated photovoltaics:Perovskite lightweight substrates enable facade and skylight applications previously inaccessible to rigid silicon. Oxford Photovoltaics targets commercial real estate retrofits across the Netherlands and Switzerland.
Market Restraints
- Tellurium supply concentration:Over ninety percent of refined tellurium originates as copper smelting byproduct from Chinese and Canadian mining operations. This upstream bottleneck constrains cadmium-telluride capacity expansion regardless of downstream demand.
- Perovskite stability degradation:Moisture and thermal cycling induce phase transitions in methylammonium lead iodide formulations. Unencapsulated laboratory cells degrade below eighty percent rated output within months of outdoor exposure.
- F-Gas Regulation compliance costs:European manufacturing facilities face escalating expenses for sulfur hexafluoride alternatives in chemical vapor deposition processes. German and Belgian plants report fifteen to twenty percent equipment retrofit requirements.
Strategic Opportunities
- India PLI scheme localization:Production-linked incentives for solar module assembly create captive demand for thin film glass and polymer substrates. Reliance Industries and Tata Power are evaluating domestic cadmium-telluride licensing.
- Agrivoltaics dual-use deployment:Semi-transparent organic photovoltaics enable simultaneous crop cultivation and electricity generation. Japanese strawberry farms and French vineyard cooperatives pilot flexible CIGS installations.
- Perovskite-silicon tandem commercialization:Oxford Photovoltaics and Swift Solar pursue manufacturing scale-up for twenty-eight percent efficiency modules. Building-integrated applications in Munich and Milan command premium pricing for architectural integration.
Industry Challenges
- Tandem cell manufacturing yield:Perovskite deposition uniformity across silicon wafer surfaces remains below crystalline silicon standards. Massachusetts and Oxford cleanroom facilities struggle with pinhole defects and interfacial recombination losses.
- Cadmium handling certification:OSHA and EU REACH protocols mandate specialized waste management infrastructure for telluride manufacturing. Malaysian and Ohio facilities face inspection backlogs for hazardous material permits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thin Film Solar Cells Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cadmium Telluride, Amorphous Silicon, Copper Indium Gallium Selenide, Organic Photovoltaics End User: Residential, Commercial, Industrial, Utility Technology: Flexible, Rigid, Bifacial, Monofacial Installation Type: Roof-mounted, Ground-mounted, Building-integrated, Others |
| Companies Covered | First Solar, Kaneka Corporation, Oxford Photovoltaics, Ascent Solar Technologies, Global Solar, MiaSole Hi-Tech Corp., Hanwha Qcells, Sharp Corporation, Solar Frontier, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thin Film Solar Cells Market Strategic Shifts
Deposition equipment automation and laser scribing precision are compressing manufacturing cycle times while perovskite formulation chemistry extends operational lifespans. These parallel advances are repositioning thin film economics against incumbent silicon.
Perovskite tandem architectures are consolidating competitive positioning in high-value building-integrated segments. Commercial real estate developers in Germany and the Netherlands specify semi-transparent modules for facade retrofits. This technology is consolidating architectural photovoltaic applications previously dominated by opaque crystalline alternatives.
F-Gas Regulation phase-down schedules are forcing European manufacturers toward sulfur hexafluoride-free chemical vapor deposition. German and Belgian production lines retrofit with fluorinated nitrile alternatives at capital costs exceeding standard equipment replacement. Cadmium-telluride and CIGS segments absorb disproportionate compliance burden relative to imported silicon modules.
Utility procurement specifications now mandate domestic content quotas and carbon intensity disclosures rather than pure levelized cost optimization. Independent power producers in India and the United States rewrite tender documents to privilege thin film modules with verified supply chain documentation. This behavioral pivot disadvantages Chinese crystalline silicon imports in favor of Malaysian and domestically manufactured alternatives.
Global Thin Film Solar Cells Market Segmentation
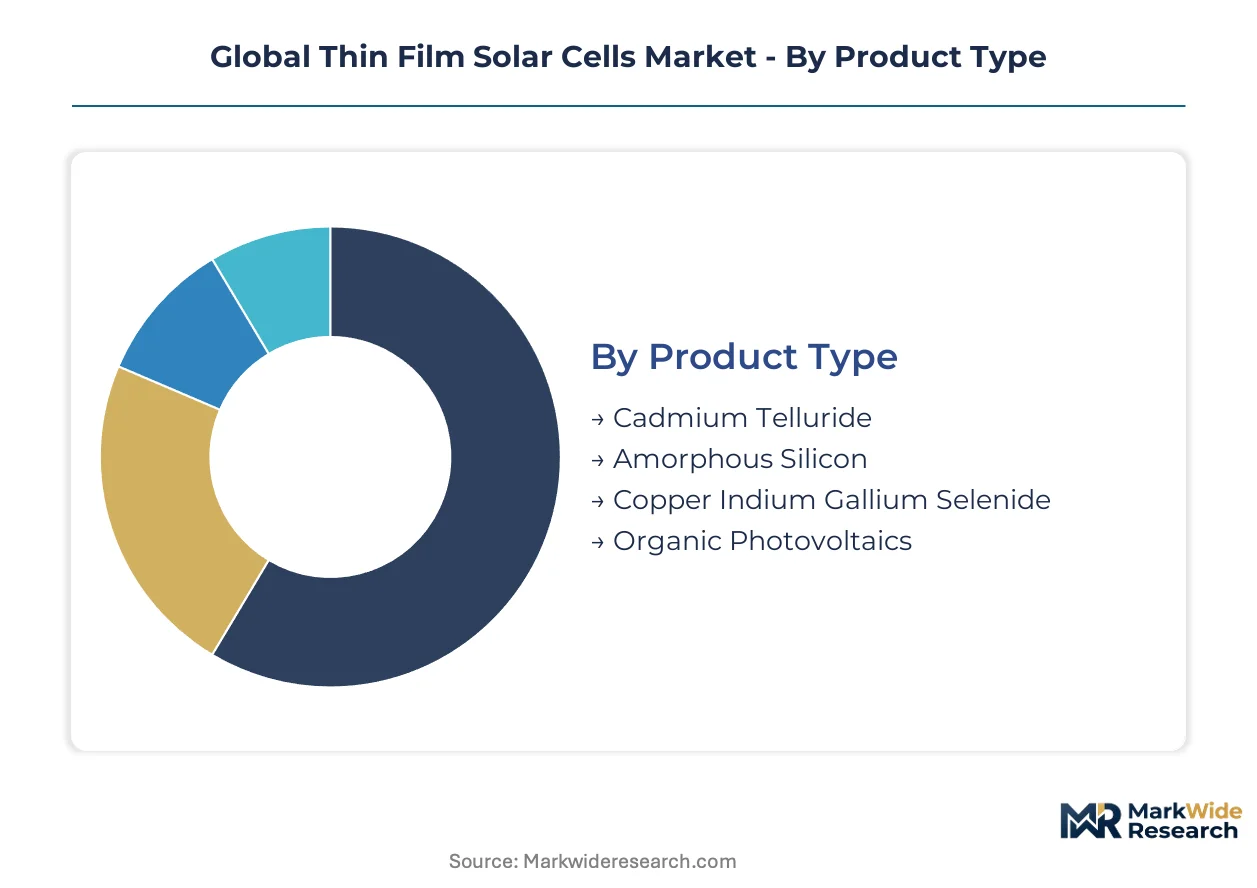
Technology chemistry and installation configuration determine project economics and regulatory compliance pathways across thin film deployments. Procurement specifications increasingly weight efficiency profiles against carbon intensity disclosures and domestic content quotas.
Product Type:
Chemistry selection dictates manufacturing temperature, substrate compatibility, and long-term degradation mechanisms.
- Cadmium Telluride:Deposited at lower temperatures than silicon alternatives onto glass substrates, achieving module efficiencies above twenty percent with mature vapor transport deposition processes. Utility-scale developers in the United States and India specify this chemistry for its levelized cost advantages and IRA-compliant domestic supply chains.
- Copper Indium Gallium Selenide:Flexible substrate compatibility enables weight-sensitive applications where rigid glass modules impose structural penalties. Japanese agrivoltaic pilots and European building-integrated installations absorb premium pricing for co-evaporation manufactured CIGS films.
- Amorphous Silicon:Plasma-enhanced chemical vapor deposition onto stainless steel or polymer substrates produces lower efficiency outputs suitable for consumer electronics and portable power segments.
- Organic Photovoltaics:Solution-processed donor-acceptor blends enable semi-transparent architectural glazing with sub-fifteen percent efficiency trade-offs.
Cadmium Telluride leads on scale; Organic Photovoltaics leads on momentum.
End User:
Customer type determines financing structures, certification requirements, and module efficiency thresholds.
- Utility:Independent power producers negotiate multi-hundred megawatt procurement contracts with domestic content riders and carbon border documentation. Ohio and Alabama manufacturing facilities supply cadmium-telluride modules under IRA production tax credit structures.
- Commercial:Real estate developers specify building-integrated perovskite tandems for facade retrofits across Munich, Milan, and Amsterdam where architectural integration commands premium tariffs.
- Industrial:On-site generation requirements drive rooftop installations with rapid payback horizons and simplified interconnection protocols.
- Residential:Distributed generation subsidies in Germany and Australia accelerate rooftop deployment with simplified permitting pathways.
Utility procurement dominates absolute volume; Commercial applications are climbing the fastest.
Technology:
Form factor flexibility determines substrate material selection and installation labor intensity.
- Flexible:Polyimide or metal foil substrates enable roll-to-roll manufacturing and conformal mounting on curved surfaces. CIGS manufacturers in South Korea and Japan target portable electronics and vehicle-integrated segments.
- Rigid:Glass superstrate configurations dominate cadmium-telluride and amorphous silicon production with proven weathering resistance and standardized mounting hardware.
- Bifacial:Transparent back contacts capture albedo reflection from ground surfaces, improving yield in high-reflectivity desert and snow environments.
- Monofacial:Opaque back contacts simplify manufacturing and reduce material costs for standard rooftop and ground-mount applications.
Rigid technology leads on scale; Flexible formats are expanding most quickly.
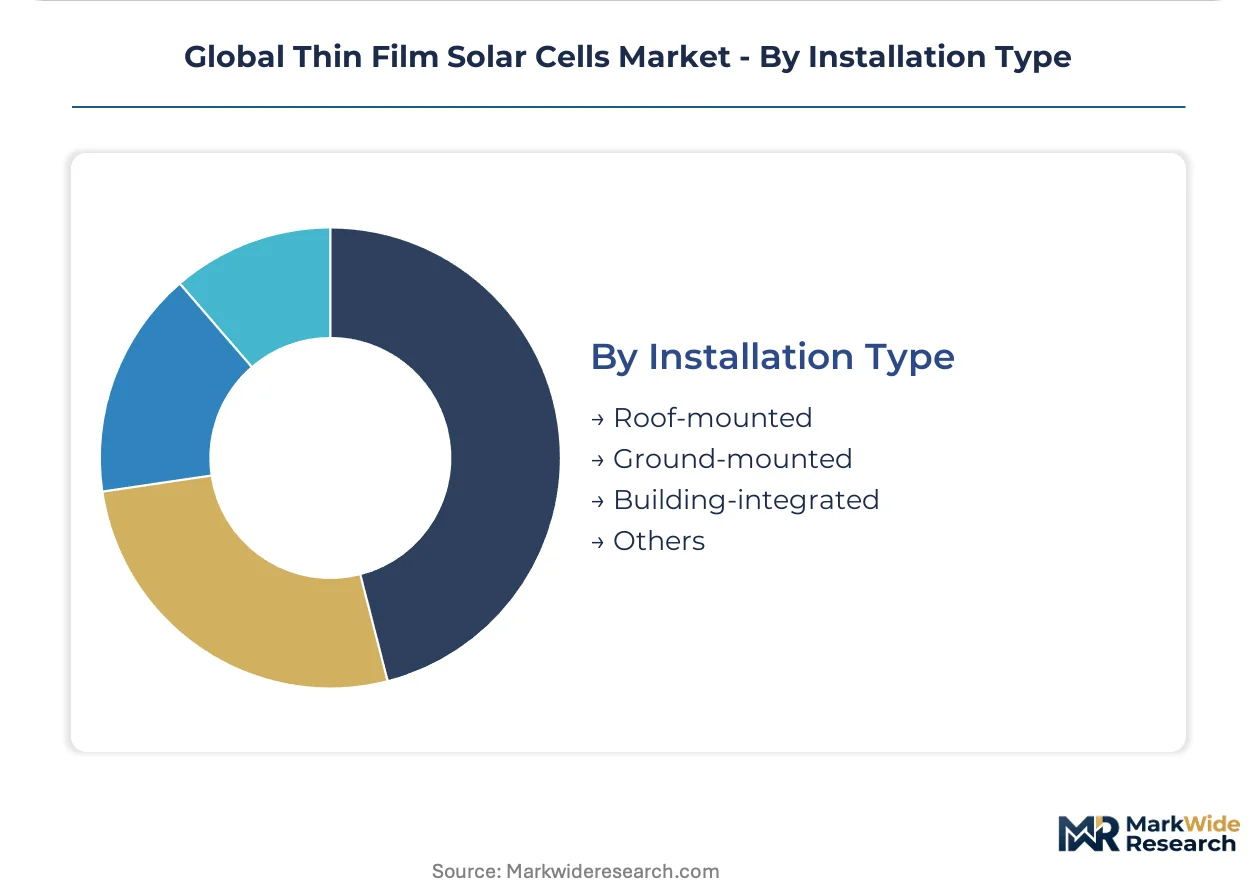
Installation Type:
Mounting configuration determines structural loading, electrical architecture, and regulatory jurisdiction.
- Ground-mounted:Utility-scale arrays on tracking systems maximize energy harvest per hectare across Arizona, Rajasthan, and Saudi Arabia with standardized civil engineering and O&M protocols.
- Building-integrated:Perovskite and organic photovoltaics replace conventional glazing in curtain wall and skylight applications. Swiss and Dutch building codes now recognize photovoltaic facades as structural envelope elements.
- Roof-mounted:Distributed generation on commercial and residential structures requires rapid shutdown compliance and fire classification ratings under IEC and UL standards.
- Others:Floating solar and vehicle-integrated applications remain pilot-scale with specialized encapsulation and moisture barrier requirements.
Ground-mounted deployment leads on scale; Building-integrated applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ohio anchors thin film manufacturing concentration through vertically integrated cadmium-telluride facilities serving North American utility procurement. IRA production tax credits redirect capital toward domestic module assembly across multiple jurisdictions.
United States
Utility-scale independent power producers negotiate multi-hundred megawatt contracts with domestic content riders. IRA production tax credits and FERC interconnection reforms accelerate Ohio and Alabama facility expansion. First Solar's vertically integrated operations in Perrysburg, Ohio exemplify reshoring momentum.
Germany
Real estate developers specify building-integrated perovskite tandems for Munich and Berlin facade retrofits. EU Green Deal carbon border adjustments and F-Gas Regulation phase-downs privilege low-carbon supply chain documentation. Saxony-Anhalt hosts chemical vapor deposition equipment retrofits for fluorinated nitrile alternatives.
India
Reliance Industries and Tata Power evaluate domestic cadmium-telluride licensing under PLI scheme incentives. BIS certification mandates and CEA grid integration standards reshape import substitution requirements. Gujarat and Rajasthan host ground-mounted utility arrays with tracking systems.
Japan
METI agrivoltaic pilots deploy flexible CIGS installations across strawberry farms and vineyard cooperatives. JIS standards govern module efficiency thresholds for distributed generation subsidies. Kyushu and Chubu regions concentrate co-evaporation manufacturing for weight-sensitive applications.
Malaysia
OSHA-compliant hazardous material permits support cadmium-telluride manufacturing for North American export markets. DGFT trade facilitation aligns with IRA-compliant supply chain documentation requirements. Kulim hosts vertically integrated thin film facilities serving international procurement.
Global Thin Film Solar Cells Market Competitive Environment
Global majors compete with regional champions across technology chemistry and manufacturing scale. The vendor base stratifies between cadmium-telluride scale operators, perovskite tandem specialists, and flexible substrate fabricators. Three archetypes dominate: vertically integrated utility-scale suppliers, building-integrated technology licensors, and flexible format niche players. Capacity expansion and strategic technology licensing represent the dominant competitive moves.
Among vertically integrated operators, First Solar exemplifies the utility-scale archetype through captive cadmium-telluride manufacturing. Oxford Photovoltaics occupies a specialist position in perovskite-silicon tandem commercialization for architectural applications. Hanwha Qcells represents the diversified conglomerate model with rigid-technology R&D intensity across multiple chemistries.
| Leading Market Players |
|---|
| First Solar |
| Kaneka Corporation |
| Oxford Photovoltaics |
| Ascent Solar Technologies |
| Global Solar |
| MiaSole Hi-Tech Corp. |
| Hanwha Qcells |
| Sharp Corporation |
| Solar Frontier |
| Others |
Value Chain & Pricing Dynamics
Utility-scale independent power producers concentrate procurement authority across North American and Indian markets, anchoring contract-based long-term offtake structures that lock in module pricing across multi-year deployment horizons. This buyer archetype's volume aggregation power compresses supplier margins while privileging domestic content documentation over pure unit cost optimization.
Pricing Analysis
Input-cost pass-through from tellurium and cadmium feedstock volatility shapes module pricing dynamics, with vapor transport deposition equipment and glass substrate costs comprising the dominant cost stack. Price differentiation rests on certification tier—modules meeting IRA domestic content thresholds command premium positioning against imported alternatives—and volume scale, with multi-hundred megawatt contracts securing preferential rates. Pricing pressure stems from crystalline silicon cost compression in utility procurement, squeezing cadmium-telluride margins in head-to-head tenders. Distributed generation buyers in commercial building-integrated segments show lowest price sensitivity, accepting per-watt premiums for architectural integration and semi-transparent form factors.
Supply Chain Analysis
Dual-sourcing requirements from North American project developers mandate qualified supplier rosters spanning Ohio, Alabama, and Malaysia manufacturing bases, insulating procurement against single-facility disruption. Geographic supply concentration centers on Malaysia for OSHA-compliant cadmium handling, the United States for IRA-certified domestic content, and Japan for co-evaporation CIGS equipment. Raw material dependencies draw from Chinese and Canadian copper smelting byproduct for refined tellurium, German chemical vapor deposition equipment, and Belgian fluorinated nitrile process gases. Supply chain risk concentrates in tariff exposure from potential trade remedy actions against Malaysian module imports. Distribution runs through utility EPC contractors and independent power producer direct procurement channels, with building-integrated segments adding architectural specifier intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Thin Film Solar Cells Market compounds steadily as decarbonization mandates harden across OECD and emerging economies, embedding solar procurement into utility resource planning and building code compliance with durable regulatory tailwinds.
For Market Incumbents: Acquire tellurium refining capacity and copper smelter offtake agreements to secure feedstock against Chinese supply concentration. Expand Ohio and Alabama manufacturing footprints to capture IRA production tax credit arbitrage against imported crystalline silicon. Invest in perovskite tandem R&D partnerships to defend technology positioning against silicon efficiency convergence.
For New Entrants and Emerging Players: Architectural engineering firms represent the most penetrable channel partner for building-integrated perovskite commercialization, bypassing established utility procurement gatekeepers. Target Dutch and Swiss commercial real estate retrofit markets where facade-integrated specifications command premium tariffs and face limited incumbent competition. Pursue technology licensing from Oxford Photovoltaics or Swift Solar to shortcut manufacturing scale-up timelines.
For Investors and Strategic Acquirers: Diversified energy conglomerates with existing utility relationships are the most active acquirer in this space, seeking thin film capacity to round out renewable portfolios. Five-to-ten year viability hinges on perovskite stability certification and tandem manufacturing yield convergence with crystalline silicon. Monitor BIS certification timeline acceleration in India and F-Gas Regulation enforcement stringency in Germany as inflection indicators for regional demand shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Ohio and Alabama facilities capture IRA production tax credits for domestic module assembly. |
| Technology Licensing | Perovskite tandem patents from Oxford Photovoltaics accelerate building-integrated commercialization timelines. |
| Backward Integration | Tellurium smelter partnerships reduce dependency on Chinese copper byproduct supply concentration. |
| Green Certification Program | EU Green Deal carbon border documentation privileges low-carbon thin film against imported silicon. |
| Power Purchase Agreement | Utility-scale offtake contracts with domestic content riders anchor manufacturing capacity utilization. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with utility procurement officers, thin film manufacturing plant managers, EPC contractors, and architectural engineering firms with secondary validation. Secondary sources include EIA capacity data, IEA technology roadmaps, FERC interconnection filings, SEC 10-K disclosures from listed solar manufacturers, and BIS certification registries. Bottom-up module shipment data triangulates against top-down utility procurement contract announcements to anchor volume estimates.
Rate-of-change decomposition separates technology efficiency gains, manufacturing cost curves, and policy incentive evolution across the projection horizon. Segmentation dimensions modeled include technology chemistry, installation configuration, end-user category, and regional regulatory framework. CAGRs derive from installed capacity buildout trajectories and module pricing trend extrapolation, with perovskite commercialization timelines and IRA credit phase-down schedules as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to perovskite stability certification breakthroughs and tellurium supply expansion from copper smelting capacity. Deviation in EU carbon border adjustment implementation timing or Indian PLI scheme disbursement rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Mexico Rooftop Solar Market
Solar Power Systems
Solar Power Tracker Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
South America Solar Tracker Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Photovoltaic Mounting System Market