
 PERC Solar Panels Market | 2026-2036
PERC Solar Panels Market Size, Share, and Industry Trends Forecast 2026-2036
PERC Solar Panels Market Analysis
Utility procurement is rebalancing toward fewer, larger-scale developers with multi-gigawatt pipelines. LONGi Green Energy Technology anchors this shift through in-house wafer-to-module production. JinkoSolar Holding leverages its distributed manufacturing footprint across Southeast Asia to sustain cost competitiveness. Trina Solar differentiates through integrated tracker and energy storage bundling.
Passivated Emitter and Rear Contact solar cells employ a dielectric passivation layer on the rear surface to reduce electron recombination, achieving conversion efficiencies above 23 percent in commercial monocrystalline formats. The technology serves utility and commercial installations where levelized cost of electricity determines project viability. Bifacial configurations command premium positioning as they capture reflected irradiance from albedo surfaces. Utility-scale system size categories attract the deepest margin pools due to volume procurement and standardized installation protocols.
FERC interconnection standards in the United States, EU Green Deal taxonomy requirements in Europe, and India's CEA grid code compliance collectively shape module certification and bankability criteria. These frameworks elevate efficiency thresholds and carbon footprint disclosure obligations for market access. Stakeholders must monitor which regulatory jurisdictions tighten domestic content rules first, as this determines factory location strategy and supply chain restructuring priorities.
Market Dynamics
Utility-scale developers are consolidating procurement around multi-gigawatt pipelines, compressing supplier margins while elevating efficiency and bankability requirements. China's updated GB standards and dual carbon goals are tightening conversion benchmarks, forcing module manufacturers to accelerate cell architecture upgrades or exit volume tiers.
Growth Catalysts
- India PLI scheme incentives:Domestic manufacturing commitments are attracting capital into cell and module capacity, reducing import dependency for utility-scale installations.
- Bifacial module configurations:Capturing reflected irradiance from albedo surfaces commands premium positioning in commercial and utility segments where levelized cost of electricity determines project viability.
- FERC interconnection standards:US grid compliance requirements are elevating module certification thresholds, filtering out sub-scale suppliers and concentrating volume with bankable manufacturers.
Market Restraints
- Polysilicon input cost volatility:Feedstock price swings compress module margins unpredictably, particularly for manufacturers without captive polysilicon supply.
- Supply concentration in wafering:China's dominance in ingot and wafer production creates geographic risk exposure for non-Chinese module assemblers.
- TOPCon cell substitution threat:Tunnel oxide passivated contact architectures are achieving higher commercial efficiencies, displacing PERC in premium utility tenders.
Strategic Opportunities
- Underpenetrated distributed commercial rooftop:India's CEA grid code compliance is unlocking behind-the-meter installations for mid-scale manufacturing and logistics facilities.
- EU Green Deal taxonomy alignment:Carbon footprint disclosure obligations for European market access favor manufacturers with vertically integrated, low-carbon supply chains.
- Tracker and storage bundling:Integrated system offerings are expanding into utility-scale procurement, differentiating module suppliers beyond cell efficiency metrics.
Industry Challenges
- Cell metallization skill scarcity:Fine-line screen printing and laser doping expertise concentrates in East Asian equipment supplier ecosystems, constraining capacity scaling elsewhere.
- CEA and FERC certification timeline compression:Parallel compliance pathways for Indian and US market entry extend product qualification cycles, delaying revenue recognition.
- Legacy fleet repowering integration:Retrofitting existing solar farms with higher-wattage PERC modules requires inverter compatibility verification and structural load reassessment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PERC Solar Panels Market |
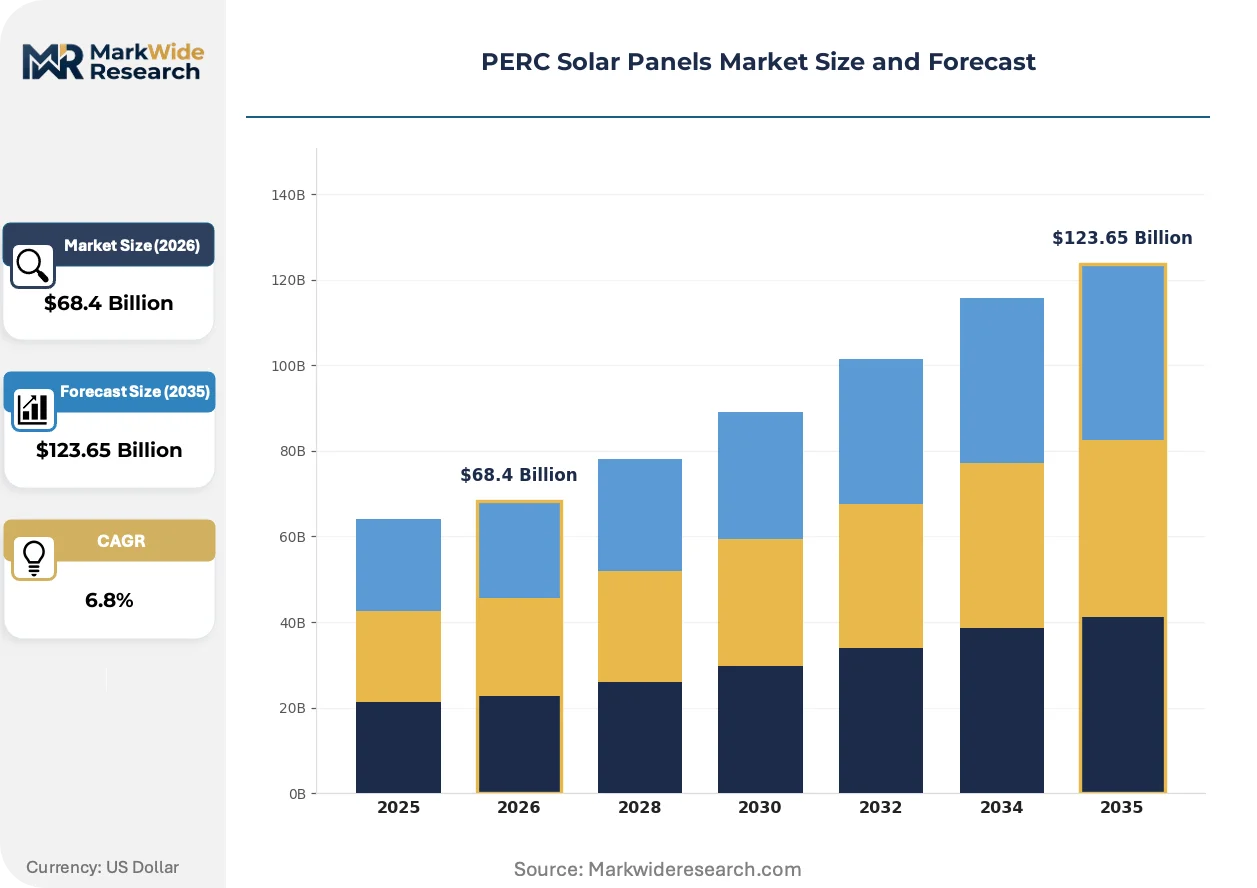
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Bifacial, Thin-Film End User: Residential, Commercial, Industrial, Utility Installation Type: Ground-Mounted, Rooftop, Building-Integrated, Off-Grid System Size: Small-Scale, Medium-Scale, Large-Scale, Utility-Scale |
| Companies Covered | JA Solar Technology, Astronergy (CHINT New Energy Technology), JinkoSolar Holding, Canadian Solar (CSI Solar), Waaree Energies, LONGi Green Energy Technology, Tongwei Solar, Boviet Solar, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PERC Solar Panels Market Emerging Trajectories
Cell metallization and passivation techniques are advancing rapidly, enabling higher conversion efficiencies while manufacturing footprints consolidate around integrated wafer-to-module facilities. These shifts are compressing technology cycles and redefining supplier competitive moats.
Multi-busbar interconnection is expanding into commercial and utility module formats, reducing silver consumption per watt while improving current collection uniformity. Major Chinese cell producers are adopting 9-12 busbar designs at scale. This architecture is expanding into bifacial glass-glass laminates, enabling higher power ratings that command premium positioning in European and Indian utility tenders.
EU Green Deal taxonomy requirements are mandating lifecycle carbon footprint disclosure for solar module bankability, forcing manufacturers to document embodied emissions from polysilicon through module assembly. European institutional investors are now screening projects against these thresholds. Developers in Germany, Spain, and the Netherlands are prioritizing suppliers with verified low-carbon supply chains, compressing market access for manufacturers without granular emissions data.
Buyer concentration among multi-gigawatt utility developers is compressing contract negotiation cycles and unbundling engineering-procurement-construction services from module supply. Independent power producers in the US and India are now procuring modules directly through long-term framework agreements, bypassing traditional distributor channels. This disintermediation is most visible in Rajasthan and Gujarat solar parks, where developers negotiate cell-to-module pricing directly with integrated manufacturers.
PERC Solar Panels Market Segmentation
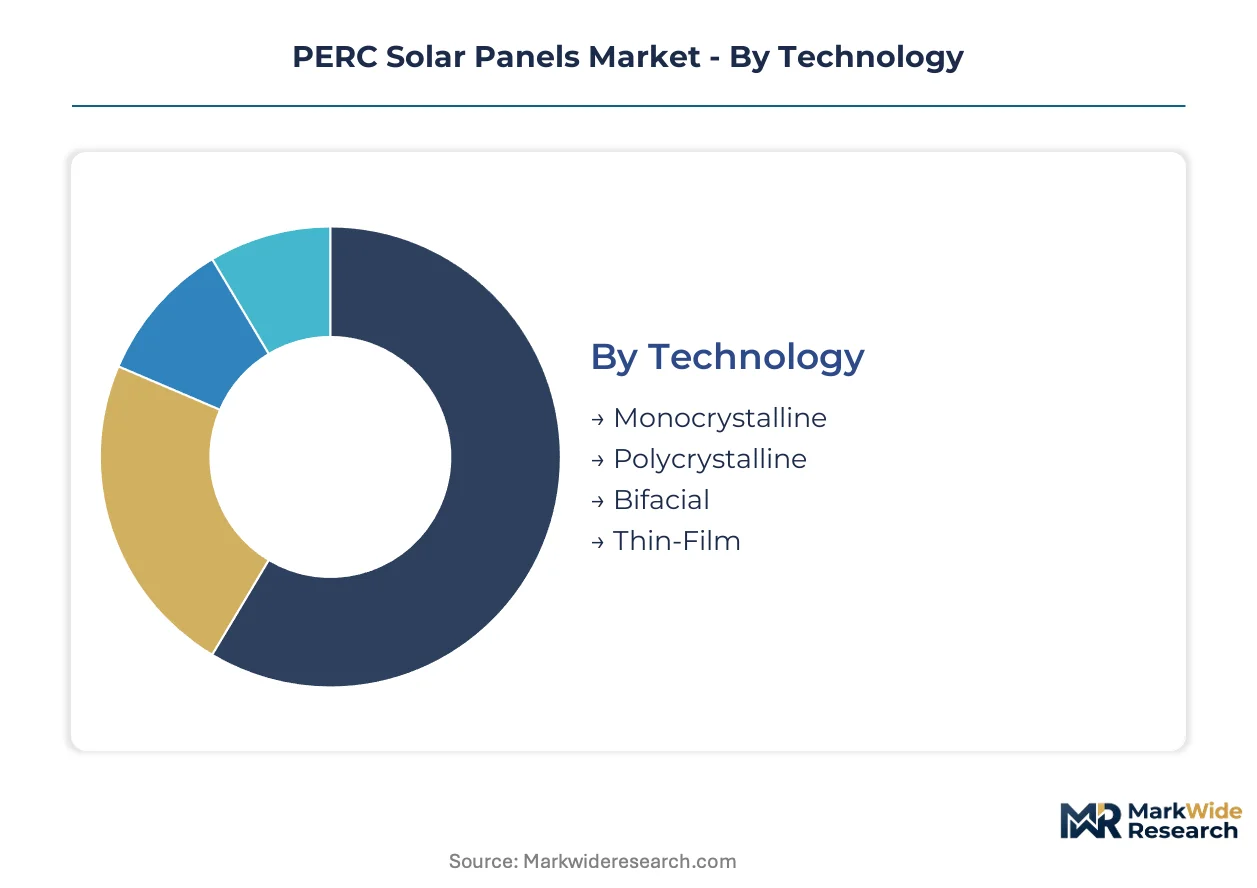
PERC cell architecture creates distinct value propositions across technology tiers, installation contexts, and procurement scales. Module specifications must align with end-use efficiency requirements, mounting constraints, and grid interconnection standards that vary sharply by segment.
Technology:
Integration depth varies sharply: monocrystalline and polycrystalline formats serve standalone module applications, while bifacial and thin-film configurations embed into integrated system designs with tracker or building envelope integration.
- Monocrystalline:Single-crystal silicon ingots yield higher electron mobility and conversion efficiencies above 23 percent in commercial PERC formats. Utility-scale developers in India and the United States specify these modules for multi-gigawatt solar parks where levelized cost of electricity drives procurement decisions.
- Bifacial:Dual-sided light capture harvests direct and reflected irradiance from albedo surfaces, boosting effective output 10-20 percent over monofacial equivalents. Ground-mounted installations in Rajasthan and Gujarat solar parks favor glass-glass laminates for durability and rear-side gain.
- Polycrystalline:Multi-crystal silicon structures trade efficiency for lower manufacturing cost, serving price-sensitive distributed commercial rooftops.
- Thin-Film:Cadmium telluride and CIGS architectures occupy niche building-integrated and flexible mounting applications outside silicon supply chains.
Monocrystalline leads volumes today; bifacial is gaining share fastest.
End User:
Cost tier stratification separates premium efficiency requirements from standardized procurement, with industrial and utility segments commanding volume-scale pricing while residential absorbs distribution markups.
- Utility:Independent power producers negotiate direct cell-to-module contracts with integrated manufacturers, bypassing distributor channels. FERC interconnection standards and multi-gigawatt procurement pipelines concentrate supply with bankable producers capable of multi-year framework agreements.
- Residential:Behind-the-meter installations depend on installer networks and net metering policy stability, with module selection driven by roof space constraints and local incentive structures.
- Commercial:Mid-scale manufacturing facilities and logistics centers in India leverage CEA grid code compliance for captive power procurement.
- Industrial:Heavy electricity consumers source modules through engineering-procurement-construction contractors with integrated project development capabilities.
Utility commands absolute shipment volumes; residential shows steepest expansion trajectory in underpenetrated distributed markets.
Installation Type:
Application context determines module form factor, mounting hardware compatibility, and electrical architecture requirements across fixed and tracking configurations.
- Ground-Mounted:Fixed-tilt and single-axis tracker arrays dominate utility-scale deployment, with bifacial modules capturing rear-side albedo gains from gravel or sand surfaces. Rajasthan solar parks exemplify this configuration at scale.
- Rooftop:Distributed commercial and industrial installations require lightweight framing and rapid mounting systems compatible with existing structural loads.
- Building-Integrated:Facade and skylight applications demand custom form factors and aesthetic constraints outside standard module dimensions.
- Off-Grid:Remote industrial sites and rural electrification projects prioritize DC-coupled storage integration and simplified maintenance protocols.
Ground-mounted leads volumes today; rooftop is gaining share fastest.
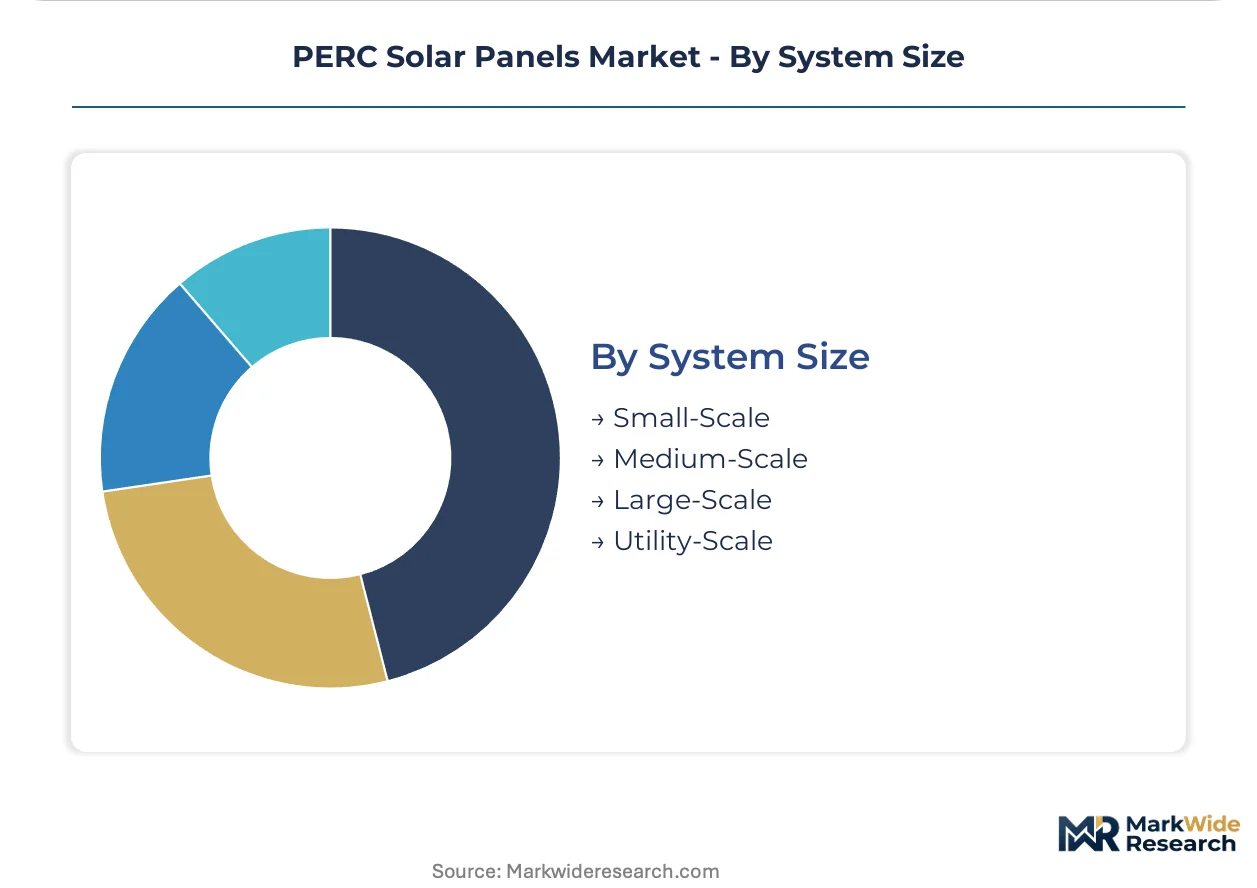
System Size:
Volume concentration shapes margin structures and supplier relationships, with procurement scale determining direct manufacturer negotiation access versus distributor channel dependency.
- Utility-Scale:Installations exceeding 100 megawatts attract deepest margin pools through standardized installation protocols and direct procurement from wafer-to-module integrated producers. India's PLI scheme incentives concentrate domestic manufacturing capacity to serve this segment.
- Large-Scale:Commercial and industrial projects between 10-100 megawatts balance customization requirements with volume pricing, often bundling tracker and inverter procurement.
- Medium-Scale:Distributed generation clusters and commercial rooftops rely on regional installer networks and distributor inventory.
- Small-Scale:Residential and rural electrification projects absorb highest per-watt soft costs through fragmented installation channels.
Utility-scale leads volumes today; large-scale is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing scale contrasts sharply with India's incentive-driven capacity buildout, while the United States and Germany anchor premium demand through stringent certification regimes.
China
Dual carbon goals and updated GB standards are tightening conversion efficiency benchmarks for module exports. MIIT production quotas favor integrated wafer-to-cell manufacturers with captive polysilicon supply. Yangtze River Delta clusters around Jiangsu and Zhejiang provinces concentrate PERC cell metallization capacity serving both domestic utility-scale parks and overseas procurement.
United States
Independent power producers are consolidating multi-gigawatt procurement pipelines around FERC interconnection compliance. IRA domestic content adders are reshaping factory location decisions for cell and module assembly. Texas and California solar parks are driving bifacial module specification for single-axis tracker compatibility.
India
PLI scheme incentives are attracting domestic manufacturing commitments for cell and module capacity expansion. CEA grid code compliance is unlocking behind-the-meter commercial installations across industrial corridors. Rajasthan and Gujarat solar parks are concentrating ground-mounted bifacial deployment with direct manufacturer negotiation.
Germany
EU Green Deal taxonomy requirements are mandating lifecycle carbon footprint disclosure for module bankability. EPC contractors are prioritizing suppliers with verified low-carbon supply chains for utility tenders. Bavaria and North Rhine-Westphalia industrial zones are integrating rooftop PERC installations with manufacturing facility electrification.
Vietnam
Southeast Asia manufacturing relocation is accelerating as Chinese producers diversify export capacity to avoid tariff exposure. Local content rules for solar project licensing are tightening module sourcing requirements. Northern industrial provinces around Hai Phong are emerging as cell assembly hubs serving regional utility-scale demand.
PERC Solar Panels Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base stratifies into three concentration levels: integrated wafer-to-module producers commanding utility-scale procurement, regional assemblers serving distributor channels, and technology licensors capturing margin through equipment sales. Strategic moves center on backward integration into polysilicon and multi-busbar cell architecture licensing.
Among China-based integrated producers, LONGi Green Energy Technology and JinkoSolar Holding exemplify the wafer-to-module archetype with in-house production spanning ingot pulling through module assembly. Canadian Solar represents the geographically diversified fabricator model with manufacturing footprints across multiple continents to serve local content requirements. These three anchors illustrate how scale concentration and regulatory arbitrage define competitive positioning in utility-scale procurement.
| Leading Market Players |
|---|
| JA Solar Technology |
| Astronergy (CHINT New Energy Technology) |
| JinkoSolar Holding |
| Canadian Solar (CSI Solar) |
| Waaree Energies |
| LONGi Green Energy Technology |
| Tongwei Solar |
| Boviet Solar |
| Trina Solar |
| Others |
Supply Flow & Price Mechanics
Captive polysilicon supply anchors both cost position and margin defense for integrated wafer-to-module producers competing in utility-scale procurement. China's MIIT production quotas and India's PLI scheme incentives are compressing price floors for non-integrated assemblers while elevating bankability premiums for manufacturers with verified low-carbon supply chains.
Pricing Analysis
Capacity additions in India are reshaping price floors for standard-efficiency modules as domestic cell and module factories reach commercial operation. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with FERC-compliant and EU Green Deal-aligned products commanding spreads over unrated equivalents. Cost compression in the standard tier is intensifying because polysilicon input volatility feeds through to spot-market module pricing. Utility-scale independent power producers exhibit lowest price sensitivity due to long-term offtake security, while distributed commercial installers absorb highest per-watt soft costs through fragmented procurement channels.
Supply Chain Analysis
Domestic content rules in India and the United States are reshaping sourcing patterns for cell metallization equipment and module assembly capacity. Manufacturing gravity centers on China for ingot pulling and wafering, Vietnam for tariff-diversified cell assembly, and India for PLI-supported module finishing. The supply chain draws from polysilicon feedstock, silver paste for screen printing, and aluminum framing as core inputs. Single-source vulnerability concentrates in East Asian equipment supplier ecosystems for laser doping and fine-line metallization tools. Distribution runs through direct manufacturer negotiation for utility-scale volumes and regional installer networks for distributed commercial rooftops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratchet effects, with India's CEA grid code compliance and the United States IRA domestic content adders accelerating procurement velocity for certified manufacturers.
For Market Incumbents: Lock in multi-year polysilicon offtake agreements and captive wafering capacity to defend margin position against TOPCon cell substitution threats. Prioritize backward integration into metallization paste formulation to reduce silver consumption exposure. Accelerate EU Green Deal carbon footprint disclosure documentation to sustain premium positioning in European utility tenders. For New Entrants and Emerging Players: Engineering-procurement-construction contractors in underpenetrated distributed commercial rooftop segments offer the most penetrable channel for module placement without competing directly against integrated giants. Target mid-scale manufacturing facilities in India's industrial corridors where CEA compliance unlocks captive power procurement. Lead with rapid-installation mounting system bundling to differentiate beyond cell efficiency metrics. For Investors and Strategic Acquirers: Consolidation pressure builds where cell metallization skill scarcity constrains capacity scaling outside East Asian equipment supplier ecosystems. Frame long-term viability around manufacturers with demonstrated FERC and CEA certification timelines and verified low-carbon supply chains. Watch for inflection where TOPCon conversion cost parity displaces PERC in premium utility tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive feedstock supply insulates margin from spot price volatility affecting non-integrated competitors. |
| Multi-Busbar Cell Architecture Licensing | 9-12 busbar designs reduce silver consumption while improving current collection for higher wattage ratings. |
| EU Green Deal Carbon Disclosure Program | Verified lifecycle emissions documentation secures bankability with European institutional investors screening projects. |
| Tracker and Storage Bundling | Integrated system offerings differentiate module suppliers beyond cell efficiency in utility-scale procurement. |
| India PLI Scheme Capacity Buildout | Domestic manufacturing commitments reduce import dependency for Rajasthan and Gujarat solar park developers. |
Methodological Framework
Bottom-up utility and commercial installation modeling reconciled against top-down cell and module production tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors, grid operators, and polysilicon procurement specialists combined with secondary validation from EIA data, IEA reports, FERC filings, and project development databases. Supply-side capacity announcements and equipment order backlogs triangulate against demand-side tender awards and interconnection queue data.
Input-output matrices map polysilicon throughput to wafer, cell, and module output across technology tiers, end-use segments, installation types, and system size categories. CAGRs derive from segment-level volume trajectories and pricing trend extrapolation across the projection horizon. Forecast inputs incorporate MIIT production quotas, PLI scheme incentive disbursement schedules, and FERC interconnection standard evolution.
Revisions become necessary when TOPCon conversion cost parity accelerates beyond modeled timelines or when domestic content rule enforcement tightens faster than factory relocation permits. Forecasts reflect documented assumptions about equipment utilization rates and silver paste consumption coefficients. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
Solar Roof Tiles Market
Solar Power Systems
Rooftop Solar Panels Market
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Asia-Pacific Distributed Solar Power Generation Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Malaysia Solar Energy Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Solar Photovoltaic Ribbon Market