
 Asia Pacific Side Channel Pumps Market | 2026-2036
Asia Pacific Side Channel Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Side Channel Pumps Market Analysis
China's GB 19762 standard for pump energy efficiency is pivoting procurement criteria toward higher-efficiency side channel designs. Grundfos Holding A/S leverages its vertical integration in motor and control systems to sustain margin advantage across East Asian water utilities. KSB SE & Co. KGaA anchors its position through localized production facilities and aftermarket service networks in China and India. HERMETIC-Pumpen GmbH specializes in hermetically sealed configurations that navigate stringent chemical processing requirements in Japan and South Korea.
Asia Pacific side channel pumps are self-priming, regenerative turbomachines employing multiple impeller-volute interactions to generate high heads at low flow rates, typically achieving discharge pressures up to 40 bar across single-stage configurations. Multistage variants dominate petrochemical and boiler feed applications where extreme pressure ratios offset higher capital costs. Electric-drive systems lead technology adoption across municipal water treatment installations, while diesel configurations retain share in remote mining and construction sites lacking grid infrastructure. Solar-powered units represent the fastest-expanding technology segment, particularly across Australian agricultural districts and Southeast Asian island communities where diesel logistics burden operating economics.
Japan's METI enforces Top Runner efficiency standards that continuously escalate minimum performance thresholds for industrial pumps sold domestically. Australia's Water Efficiency Labelling and Standards scheme shapes demand by mandating disclosure of hydraulic efficiency ratings at point-of-sale. India's Bureau of Energy Efficiency extends parallel requirements through its Standards and Labeling program for agricultural and industrial pumping equipment. Stakeholders must monitor how divergent national efficiency regimes fragment product platform strategies and whether regional harmonization initiatives emerge through ASEAN technical cooperation frameworks.
Market Dynamics
China's GB 19762 pump efficiency standard is forcing wholesale replacement of legacy rotating equipment across municipal water networks and industrial facilities, compressing procurement cycles and elevating specification thresholds for side channel designs.
Growth Catalysts
- Water treatment infrastructure:India's Bureau of Energy Efficiency Standards and Labeling program for agricultural and industrial pumping equipment is accelerating capital deployment across Gujarat and Maharashtra industrial corridors.
- GB 19762 compliance cycles:China's tightening energy efficiency mandates are triggering systematic equipment refresh programs among state-owned water utilities and chemical processors.
- Solar-electric hybridization:Australian agricultural districts and Southeast Asian island communities are adopting photovoltaic-driven side channel pumps to displace diesel logistics burdens.
Market Restraints
- Permanent magnet motor cost volatility:Rare earth element price swings, particularly neodymium and dysprosium sourced through concentrated Chinese refining capacity, squeeze margin structures for high-efficiency pump-motor packages.
- Multistage fabrication complexity:Precision machining requirements for interstage sealing and hydraulic balancing limit viable supplier pools to specialized turbomachinery workshops.
- Submersible centrifugal substitution:Flooded suction centrifugal designs with integrated variable frequency drives are capturing share in low-head municipal applications where side channel advantages diminish.
Strategic Opportunities
- Vietnam chemical processing corridor:Greenfield petrochemical investments along the southern coast present specification windows for hermetically sealed multistage configurations.
- Indonesia archipelago water security:Decentralized desalination and brackish water treatment projects favor self-priming side channel architectures with solar-battery hybrid drives.
- Japan METI Top Runner alignment:Premium efficiency tier positioning enables margin capture among semiconductor and pharmaceutical facilities with continuous-duty reliability requirements.
Industry Challenges
- Hydraulic design talent scarcity:Specialized computational fluid dynamics expertise for regenerative turbomachinery optimization concentrates among aging engineer cohorts in Germany and Japan.
- Cross-border certification latency:Divergent ASEAN national testing protocols for rotating equipment create duplicate validation burdens for manufacturers seeking multi-country market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Side Channel Pumps Market |
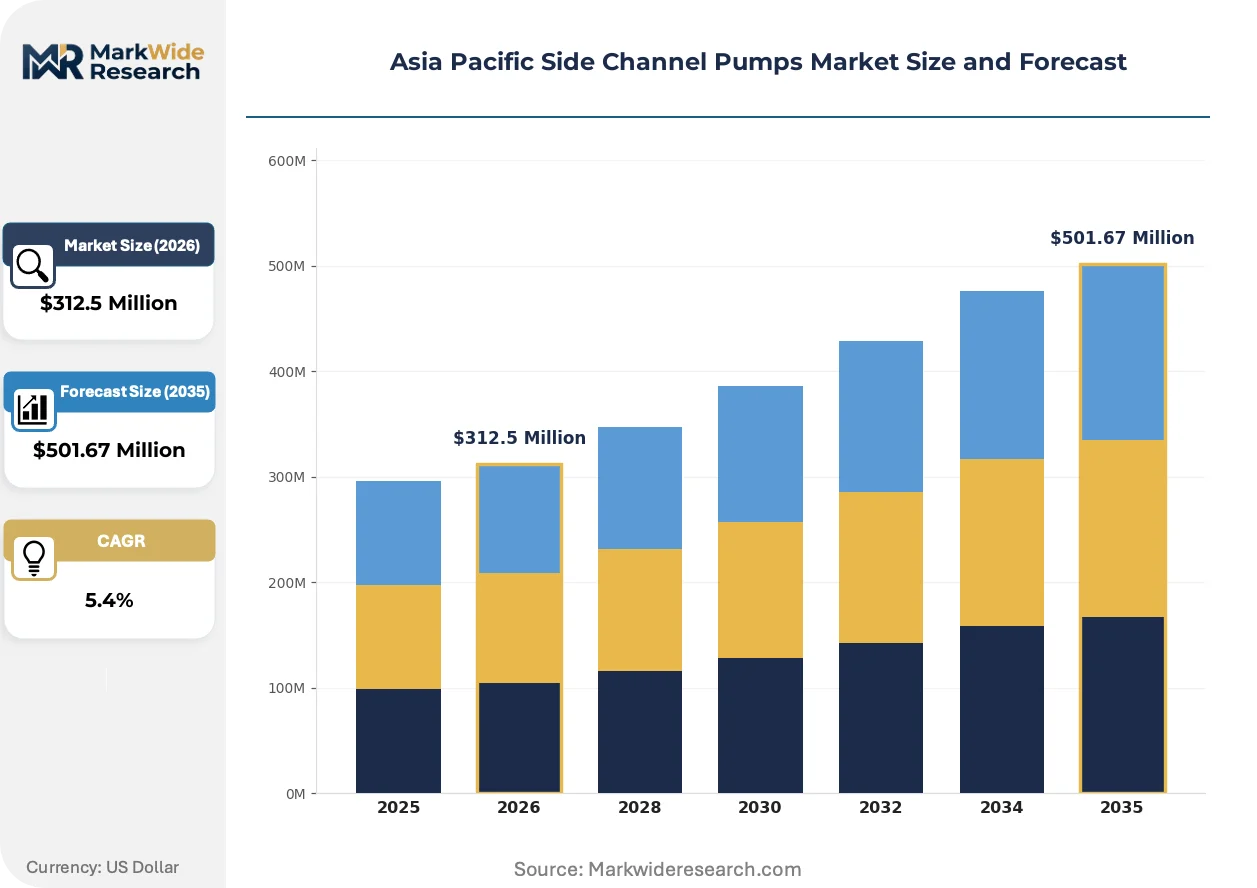
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Multistage, Mobile, Vertical Application: Water Treatment, Chemical Processing, Oil & Gas, Food & Beverage End User: Manufacturing, Agriculture, Mining, Construction Technology: Electric, Diesel, Pneumatic, Solar |
| Companies Covered | Flowserve Corporation, Grundfos Holding A/S, KSB SE & Co. KGaA, Sulzer Ltd, ITT Inc., CP Pumpen AG, HERMETIC-Pumpen GmbH, Klaus Union, Sundyne, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Side Channel Pumps Market Emerging Trajectories
Digital twin integration and predictive maintenance architectures are reshaping how operators specify and lifecycle-manage side channel pump assets across Asia Pacific industrial water systems.
Integrated motor-drive packages with embedded power electronics are overtaking conventional separate-component installations. Japanese semiconductor fabrication facilities and Korean battery manufacturing plants are specifying these compact configurations to reduce footprint and eliminate alignment-related bearing failures. The technology is compressing traditional channel margins on standalone motor and variable frequency drive sales.
Australia's Water Efficiency Labelling and Standards scheme now mandates point-of-sale disclosure of hydraulic efficiency ratings for all pumping equipment above specified power thresholds. Industrial buyers in Queensland and New South Wales are incorporating these ratings into total cost of ownership models, shifting specification authority from procurement departments to energy management functions. Municipal water authorities are responding by pre-qualifying only Tier 1 efficiency-rated products for framework agreements.
Water utilities are unbundling aftermarket service contracts from initial equipment supply, creating independent service provider markets. Korean metropolitan water agencies and Thai provincial utilities are separating capital and operating expenditure budgets, enabling specialized maintenance firms to capture long-term service revenues. This restructuring is most advanced in Australia, where performance-based availability contracts now dominate large treatment facility procurements.
Asia Pacific Side Channel Pumps Market Segmentation
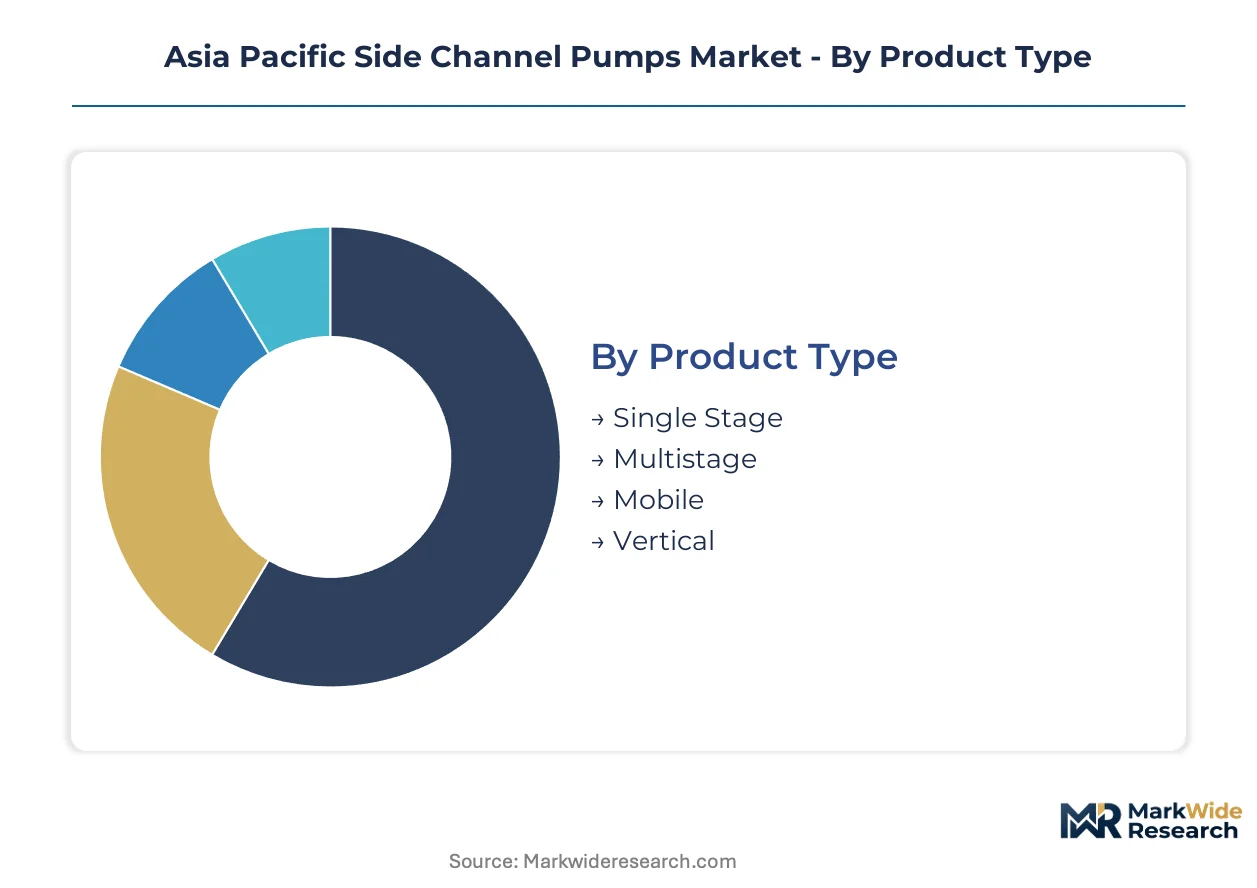
Side channel pump procurement patterns diverge sharply across pressure requirements, duty cycles, and energy access constraints. Specification authority varies by end-use: municipal water utilities prioritize lifecycle efficiency, while chemical processors emphasize hermetic integrity under corrosive conditions.
Product Type:
Volume concentration favors standardized single-stage units, while premium engineering concentrates in multistage configurations for extreme pressure ratios.
- Multistage:Precision-machined interstage sealing enables discharge pressures exceeding 100 bar across petrochemical and boiler feed installations. Demand clusters in Japan's pharmaceutical corridors and Korea's semiconductor fabrication facilities where continuous-duty reliability commands specification priority.
- Single Stage:Self-priming regenerative turbomachines achieve heads up to 40 bar through multiple impeller-volute interactions. India's Gujarat and Maharashtra industrial corridors are deploying these for brackish water treatment where capital constraints limit multistage adoption.
- Mobile:Skid-mounted configurations serve remote mining and construction sites lacking permanent infrastructure.
- Vertical:Space-constrained installations in urban water treatment plants favor compact column-mounted geometries.
Mature deployment sits with single-stage architectures across municipal networks. Newer deployment is concentrated in multistage systems for process industries.
Application:
Specification intensity escalates with fluid hazard classification, separating commodity water handling from engineered chemical containment.
- Chemical Processing:Hermetically sealed configurations navigate stringent containment requirements for corrosive and volatile media. Japan's METI-enforced safety protocols and Korea's petrochemical expansion along the Ulsan complex are elevating demand for sealless magnetic drive architectures.
- Water Treatment:Self-priming capability eliminates suction lift limitations across decentralized desalination and brackish groundwater projects. Indonesia's archipelago communities and Australia's agricultural districts specify solar-electric hybrid drives to displace diesel logistics.
- Oil & Gas:Explosion-proof motor enclosures and API-compliant materials handling dominate upstream and midstream specifications.
- Food & Beverage:Sanitary-grade stainless steel construction with EHEDG or 3-A certification addresses clean-in-place requirements.
Water treatment commands the broadest installed base. Chemical processing exhibits the steepest expansion trajectory as Southeast Asian capacity builds accelerate.
End User:
Capital intensity and operating duty cycles separate continuous-process manufacturing from intermittent construction applications.
- Manufacturing:Semiconductor fabrication and battery cell production facilities specify integrated motor-drive packages to reduce footprint and eliminate alignment failures. Korean and Japanese electronics corridors are standardizing predictive maintenance architectures.
- Agriculture:India's Bureau of Energy Efficiency Standards and Labeling program is redirecting procurement toward labeled efficiency tiers across Gujarat and Maharashtra irrigation districts.
- Mining:Diesel-retrofit programs and solar-battery hybridization are displacing conventional fuel logistics at remote Australian and Indonesian extraction sites.
- Construction:Mobile dewatering applications favor rental fleet economics over capital ownership.
Manufacturing anchors premium specification development. Agricultural deployment is gaining share fastest under efficiency mandate compliance cycles.
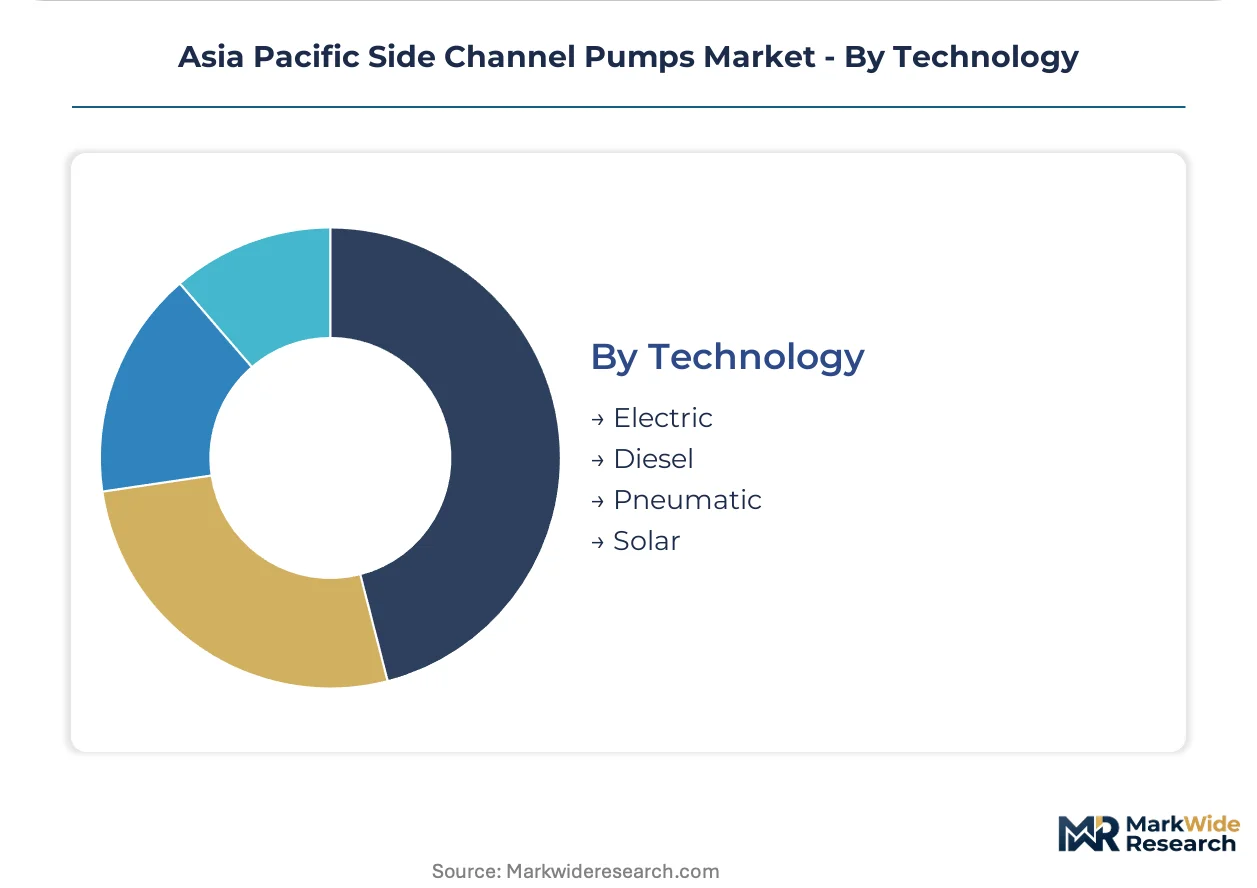
Technology:
Grid access and fuel logistics economics determine drive technology selection across archipelago and continental geographies.
- Solar:Photovoltaic-driven units with battery buffering eliminate diesel supply chain burdens across Southeast Asian island communities and Australian pastoral regions. Capital cost parity is approaching for sub-10kW installations.
- Electric:Integrated permanent magnet motor and variable frequency drive packages dominate municipal and industrial installations where grid reliability permits. China's GB 19762 efficiency standard is disqualifying induction motor legacy configurations.
- Diesel:Retains share in remote mining and construction applications lacking grid infrastructure or where peak load flexibility outweighs fuel cost premiums.
- Pneumatic:Explosion-safe compressed air drives serve hazardous zone classifications in chemical and hydrocarbon processing.
Electric systems anchor established infrastructure. Solar configurations represent the fastest-growing technology segment as photovoltaic module costs decline and battery integration improves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's industrial corridor tax incentives and China's special economic zones for water infrastructure are concentrating side channel pump procurement authority in state-backed procurement frameworks across the Asia Pacific region.
China
State-owned water utilities in the Yangtze River Delta are executing systematic equipment refresh programs. GB 19762 pump efficiency standards are disqualifying induction motor legacy configurations from municipal framework agreements. Shanghai and Jiangsu province chemical processors are specifying multistage hermetic designs for high-pressure boiler feed applications.
India
Gujarat and Maharashtra industrial corridors are deploying single-stage self-priming units for brackish water treatment under Bureau of Energy Efficiency Standards and Labeling compliance cycles. The country's national energy efficiency regulator is redirecting agricultural procurement toward labeled efficiency tiers. Ahmedabad and Mumbai metropolitan water authorities are separating capital and operating expenditure budgets for treatment facility upgrades.
Japan
Semiconductor fabrication facilities in the Kansai and Kyushu regions are specifying integrated motor-drive packages with predictive maintenance architectures. METI-enforced Top Runner efficiency standards continuously escalate minimum performance thresholds for industrial pumps sold domestically. Osaka and Nagoya pharmaceutical corridors demand sealless magnetic drive configurations for continuous-duty reliability.
Australia
Queensland and New South Wales agricultural districts are adopting photovoltaic-driven side channel pumps to displace diesel logistics burdens. The country's national water efficiency labeling scheme mandates point-of-sale disclosure of hydraulic efficiency ratings. Murray-Darling Basin irrigation authorities are pre-qualifying only Tier 1 efficiency-rated products for framework agreements.
Vietnam
Greenfield petrochemical investments along the southern coast near Ba Ria-Vung Tau are creating specification windows for hermetically sealed multistage configurations. The country's national industrial development zones are offering tax incentives for energy-efficient rotating equipment procurement. Ho Chi Minh City metropolitan water utilities are expanding decentralized desalination capacity with self-priming architectures.
Asia Pacific Side Channel Pumps Market Vendor Landscape
German and Swiss producers anchor the premium hermetic tier; Danish and Japanese specialists hold positions in integrated motor-drive systems. The vendor structure concentrates around three strategic archetypes: vertically integrated pump-motor fabricators, sealless magnetic drive specialists, and regional service-anchored distributors. Competitive dynamics center on backward integration into permanent magnet motor production and geographic expansion through localized assembly facilities.
Within the hermetic seal tier, HERMETIC-Pumpen GmbH and Klaus Union exemplify precision-engineered configurations for chemical containment. Grundfos Holding A/S occupies a position among integrated system architects with captive control electronics capabilities. These three anchors represent distinct competitive vectors: German engineering depth, Swiss manufacturing precision, and Danish vertical integration across the electromechanical stack.
| Leading Market Players |
|---|
| Flowserve Corporation |
| Grundfos Holding A/S |
| KSB SE & Co. KGaA |
| Sulzer Ltd |
| ITT Inc. |
| CP Pumpen AG |
| HERMETIC-Pumpen GmbH |
| Klaus Union |
| Sundyne |
| Others |
Supply Flow & Price Mechanics
Specialized computational fluid dynamics expertise concentrated among aging engineer cohorts in Germany and Japan widens labor-cost differentials between premium hermetic fabricators and standard single-stage assemblers, compressing pricing-tier spreads across Asia Pacific procurement frameworks.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory commands discounts against standard delivery schedules. Three-tier pricing structure across premium hermetic, standard single-stage, and economy mobile configurations reflects GB 19762 certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because rare earth element price swings squeeze permanent magnet motor margins. Municipal water utilities exhibit highest price sensitivity due to separated capital and operating expenditure budgets, while semiconductor fabrication facilities prioritize reliability over unit cost.
Supply Chain Analysis
Permanent magnet motor supply rests on Chinese rare earth refining concentration, German precision machining capacity, and Japanese integrated drive electronics production. Raw material dependencies span neodymium and dysprosium for high-efficiency motors, specialty stainless steels for hermetic containment, and silicon carbide for power electronics. Single-source vulnerability in rare earth element processing creates exposure to export restriction shocks. Distribution runs through regional service-anchored distributor networks with localized assembly facilities reducing landed cost for municipal framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia Pacific side channel pump procurement operates as a cost-of-compliance story where China's GB 19762 efficiency standard erects a barrier-to-entry moat favoring pre-certified incumbents with established testing protocols.
For Market Incumbents: Hedge against submersible centrifugal substitution by deepening backward integration into permanent magnet motor production and expanding captive control electronics capabilities. Anchor position through localized assembly facilities in Vietnam's chemical processing corridor and Indonesia's archipelago water security projects. Pressure from flooded suction centrifugal designs with integrated variable frequency drives demands specification authority reinforcement through predictive maintenance architecture bundling. For New Entrants and Emerging Players: Direct-to-utility digital platforms offer route-to-market acceleration for solar-electric hybrid configurations targeting Australian agricultural districts and Southeast Asian island communities. White-space concentration sits with decentralized desalination specifications in Indonesia and diesel-retrofit mining applications in remote Australian extraction sites. Specification capture through pre-qualification for Tier 1 efficiency ratings under Australia's Water Efficiency Labelling and Standards scheme enables framework agreement access. For Investors and Strategic Acquirers: Re-rating potential sits with hermetic seal specialists given Japan METI Top Runner alignment and Korea petrochemical expansion along the Ulsan complex. Long-term viability over a multi-year horizon favors sealless magnetic drive fabricators with pharmaceutical corridor relationships. Watch for ASEAN technical cooperation framework emergence as harmonization catalyst reducing cross-border certification latency burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Permanent Magnet Motors | Captive neodymium supply hedges rare earth price volatility for GB 19762-compliant packages. |
| Predictive Maintenance Architecture Development | Digital twin integration captures Korean semiconductor facility lifecycle management contracts. |
| Localized Assembly Facility Expansion | Vietnam and Indonesia production reduces landed cost for municipal framework agreements. |
| Solar-Battery Hybrid Drive Certification | Australian Water Efficiency Labelling Tier 1 pre-qualification opens agricultural procurement channels. |
| Hermetic Seal Technology Licensing | Magnetic drive IP partnerships penetrate Japan pharmaceutical and Korea battery manufacturing corridors. |
Methodological Framework
Independent corroboration across plant engineers at chemical processing facilities, procurement leads at state-owned water utilities, aftermarket service heads at regional distributors, and technical R&D directors at motor-drive integrators underwrites the qualitative findings. Secondary validation draws from customs and trade data, Bureau of Energy Efficiency labeling databases, METI efficiency standard filings, and SEC disclosures from listed pump manufacturers. Bottom-up installation tracking across Gujarat and Maharashtra industrial corridors triangulates against top-down market sizing from equipment refresh program announcements.
Comparable-period anchoring to historical equipment replacement cycles and efficiency mandate compliance windows structures the projection horizon. Segmentation modeling spans product type, application intensity, end-user capital structure, and drive technology adoption patterns. CAGRs derive from regression against industrial water treatment investment flows and petrochemical capacity expansion announcements. Industry-specific inputs incorporate rare earth element price trajectory assumptions and photovoltaic module cost decline curves.
The model holds under sustained regulatory enforcement of GB 19762 and METI Top Runner standards; deviation in ASEAN harmonization progress or rare earth export restrictions would shift competitive positioning. Forecasts reflect documented assumptions regarding solar-electric hybrid adoption rates and municipal budget separation trends. A small set of named triggers—ASEAN technical cooperation framework emergence, permanent magnet motor cost parity inflection, and submersible centrifugal VFD performance advancement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Double Suction Pump Market
Pumps and Control Devices
US Industrial Pump Market
Pumps and Control Devices
Droplet Separator Market
Pumps and Control Devices
Rotary Pump Market
Pumps and Control Devices
Centrifugal Water Pump Market
Pumps and Control Devices
Fine Bubble Diffusers Market
Pumps and Control Devices
Chemical Metering Pumps Market
Pumps and Control Devices
Vacuum Pump Stations Market
Pumps and Control Devices
Solar Pump Market
Pumps and Control Devices
Ion Pump Market
Pumps and Control Devices
APAC Centrifugal Pumps Market
Pumps and Control Devices
Asia-Pacific Cryogenic Pump Market
Pumps and Control Devices
Paint Pump Market
Pumps and Control Devices
Global Diaphragm Pump Market
Pumps and Control Devices
Global Solar Water Pump Systems Market
Pumps and Control Devices
Water Pump Market