
 Solar Cell Busbar Market | 2026-2036
Solar Cell Busbar Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Cell Busbar Market Intelligence
Multi-source procurement of high-purity copper and silver-coated ribbon is hardening across tier-one solar module manufacturers. Trina Solar leverages captive metallization capabilities to insulate margin pools from volatile precious metal costs. JinkoSolar anchors its busbar strategy through direct partnerships with Chinese copper refiners. LONGi Green Energy Technology differentiates via proprietary low-temperature soldering alloys that reduce cell breakage rates during interconnection.
A solar cell busbar is a metallic conductor strip, typically copper or silver-plated copper measuring 0.8–1.2 millimeters in width, that collects and transports electrical current generated by photovoltaic cells to external junction boxes. The component must maintain resistivity below 0.0175 ohm-millimeter squared while surviving thermal cycling between minus 40 and plus 85 degrees Celsius across a 25-year service life. Copper busbars now dominate procurement volumes for monocrystalline PERC and TOPCon architectures due to their conductivity-to-cost ratio, though silver-coated variants command premium positioning in heterojunction lines where soldering temperatures must stay below 150 degrees Celsius. Tin-plated busbars are gaining share in utility-scale power plants as anti-corrosion specifications intensify for desert and coastal installations.
China's SAMR enforces updated GB standards for photovoltaic interconnection materials that mandate accelerated electrochemical corrosion testing, while the MEE implements dual carbon goals requiring supply chain carbon footprint disclosure for subsidized solar projects. The EU's F-Gas Regulation and CE marking directives for electrical safety indirectly shape export-bound busbar specifications for module manufacturers serving European utility-scale developers. Stakeholders must monitor how metallization thickness standards evolve as cell architectures shift toward zero-busbar and multi-busbar designs with finer line widths.
Market Dynamics
The transition from multi-busbar to zero-busbar cell architectures is compressing metallization line widths below 30 microns, forcing ribbon manufacturers to recalibrate conductivity-to-thickness ratios for TOPCon and heterojunction production lines.
Growth Catalysts
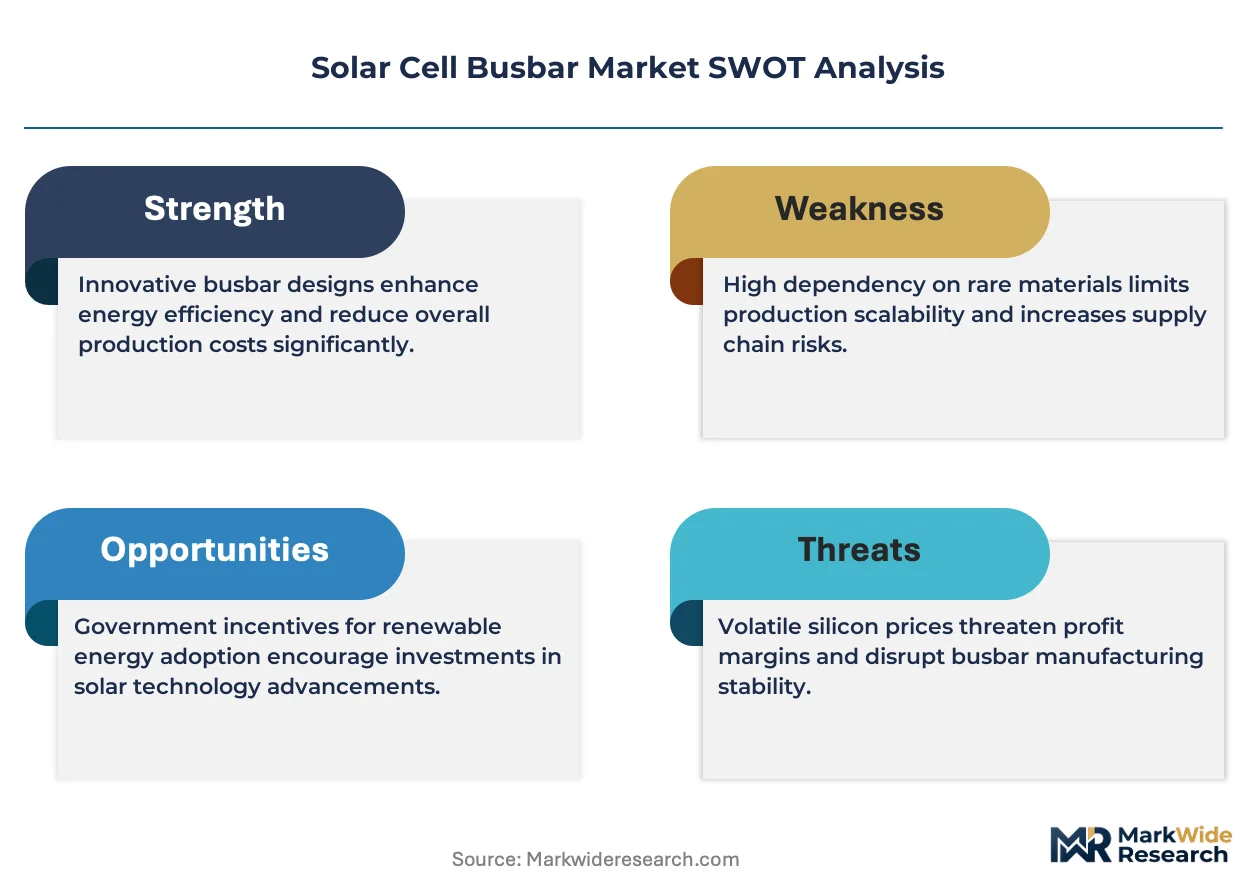
- Utility-scale power plant expansion:Developers in desert and coastal regions are specifying tin-plated busbars with enhanced anti-corrosion coatings to meet 25-year performance warranties under extreme thermal cycling.
- China's dual carbon goals:The MEE mandates supply chain carbon footprint disclosure for subsidized solar projects, accelerating demand for low-carbon copper refining and recycled content verification.
- GB standards tightening:SAMR-enforced accelerated electrochemical corrosion testing is disqualifying legacy busbar formulations and opening procurement slots for certified premium suppliers.
Market Restraints
- Silver price volatility:Silver-coated busbar production remains exposed to London Bullion Market Association spot price swings, compressing margins for heterojunction-dedicated lines.
- Jiangsu-Anhui supply concentration:Integrated cell-to-module clusters in these provinces control over 60% of procurement volumes, creating dependency risk for non-captive ribbon suppliers.
- Zero-busbar substitution threat:Copper-plated cell designs with direct finger-to-tab interconnection are eliminating ribbon requirements in pilot production lines.
Strategic Opportunities
- Desert utility installations:Saudi Arabia's renewable tender pipeline is specifying busbars with enhanced UV and sand-abrasion resistance for gigawatt-scale projects.
- Low-temperature soldering alloys:Proprietary formulations reducing cell breakage below 150°C are creating premium positioning for heterojunction module manufacturers.
- EU F-Gas Regulation alignment:Export-bound Chinese manufacturers are certifying busbar assemblies to CE marking directives for European utility-scale developers.
Industry Challenges
- Metallization thickness standardization:Competing zero-busbar and multi-busbar cell architectures lack unified line-width specifications, forcing ribbon suppliers to maintain parallel production tooling.
- Electrochemical certification timelines:SAMR's updated GB testing protocols extend qualification cycles by 4-6 months, delaying new product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Cell Busbar Market |
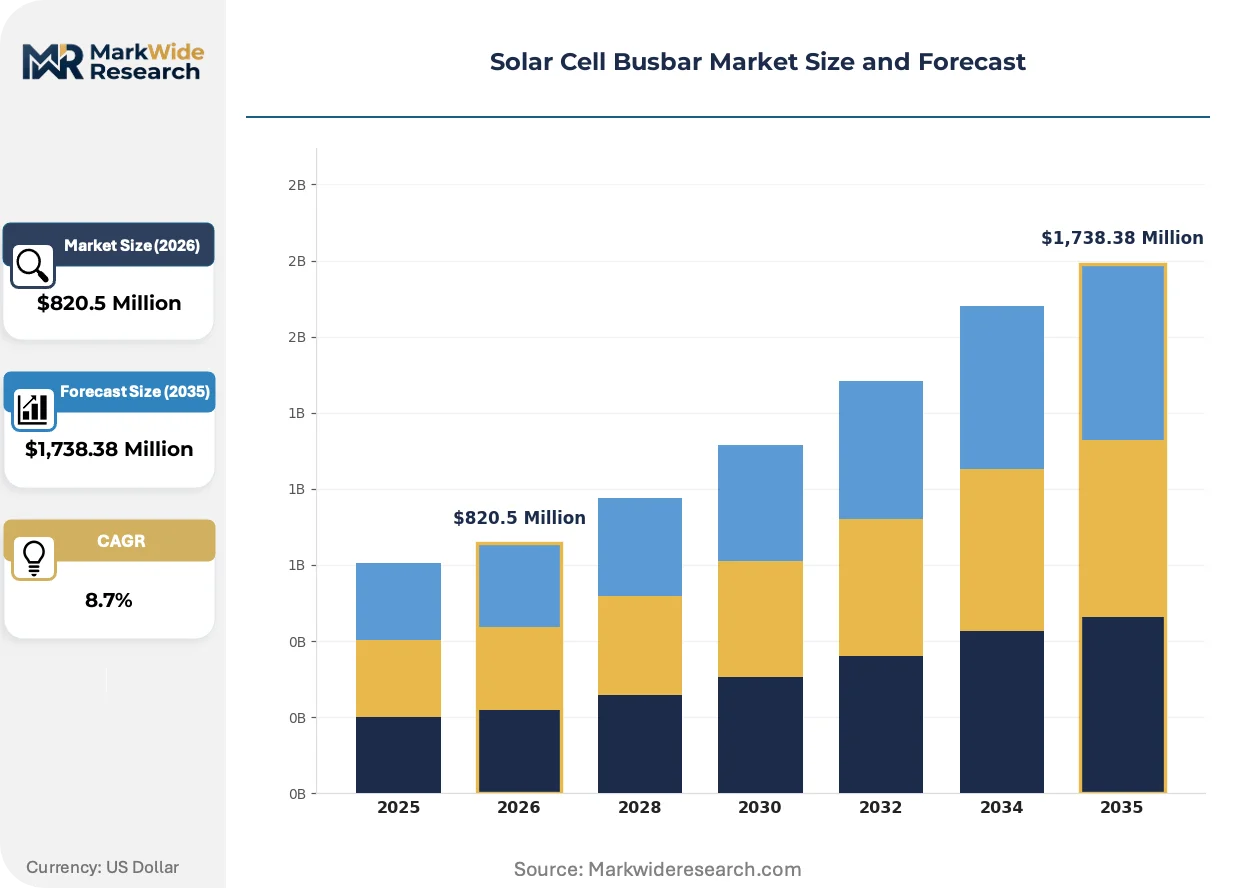
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,738.38 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Coated Busbars, Copper Busbars, Tin Plated Busbars, Aluminum Busbars, Nickel Coated Busbars Technology: Monocrystalline, Polycrystalline, Thin Film, Perovskite, Multi-junction Application: Residential Solar Systems, Commercial Solar Installations, Utility-scale Power Plants, Off-grid Solar Systems, Agricultural Solar Projects End User Industry: Power Generation Companies, Solar Module Manufacturers, EPC Contractors, Energy Storage Providers, Renewable Energy Service Firms |
| Companies Covered | Trina Solar, Astronergy, JinkoSolar, GCL System Integration, DAS Solar, LONGi Green Energy Technology, Tongwei Solar, Risen Energy, JA Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Cell Busbar Market Strategic Shifts & Innovations
Cell architecture evolution is fragmenting busbar design requirements across PERC, TOPCon, and heterojunction production lines, creating parallel technology tracks rather than unified industry standards.
Round wire interconnection is integrating into heterojunction module assembly as a direct replacement for flat ribbon designs. Japanese and European manufacturers are adopting this geometry for its reduced shading ratio and improved solder joint reliability. The technology is integrating with existing tabbing-stringing equipment through minimal retrofit, lowering capital barriers for conversion.
REACH substance restrictions on lead-bearing solder alloys are forcing European module manufacturers to certify tin-silver-copper formulations for junction box attachments. Industrial consequence includes accelerated qualification of lead-free busbar plating chemistries. Heterojunction lines serving European utility-scale developers are most affected, with suppliers submitting expanded technical documentation to notified bodies.
Consolidated procurement contracts are compressing supplier bases for tier-one solar module manufacturers. Direct metallization partnerships with copper refiners are replacing spot-market ribbon purchases in high-volume production. China and Southeast Asia exhibit this pattern most visibly, where integrated manufacturers leverage captive supply relationships to lock in conductivity specifications.
Solar Cell Busbar Market Segmentation
Busbar procurement decisions pivot on conductivity requirements, soldering temperature constraints, and corrosion resistance specifications that vary sharply across cell architectures. Understanding how these technical parameters map to segment boundaries enables suppliers to align metallization capabilities with buyer procurement criteria.
Product Type:
Conductivity-to-cost ratios dominate buyer selection, with cell architecture dictating plating chemistry and thermal tolerance requirements.
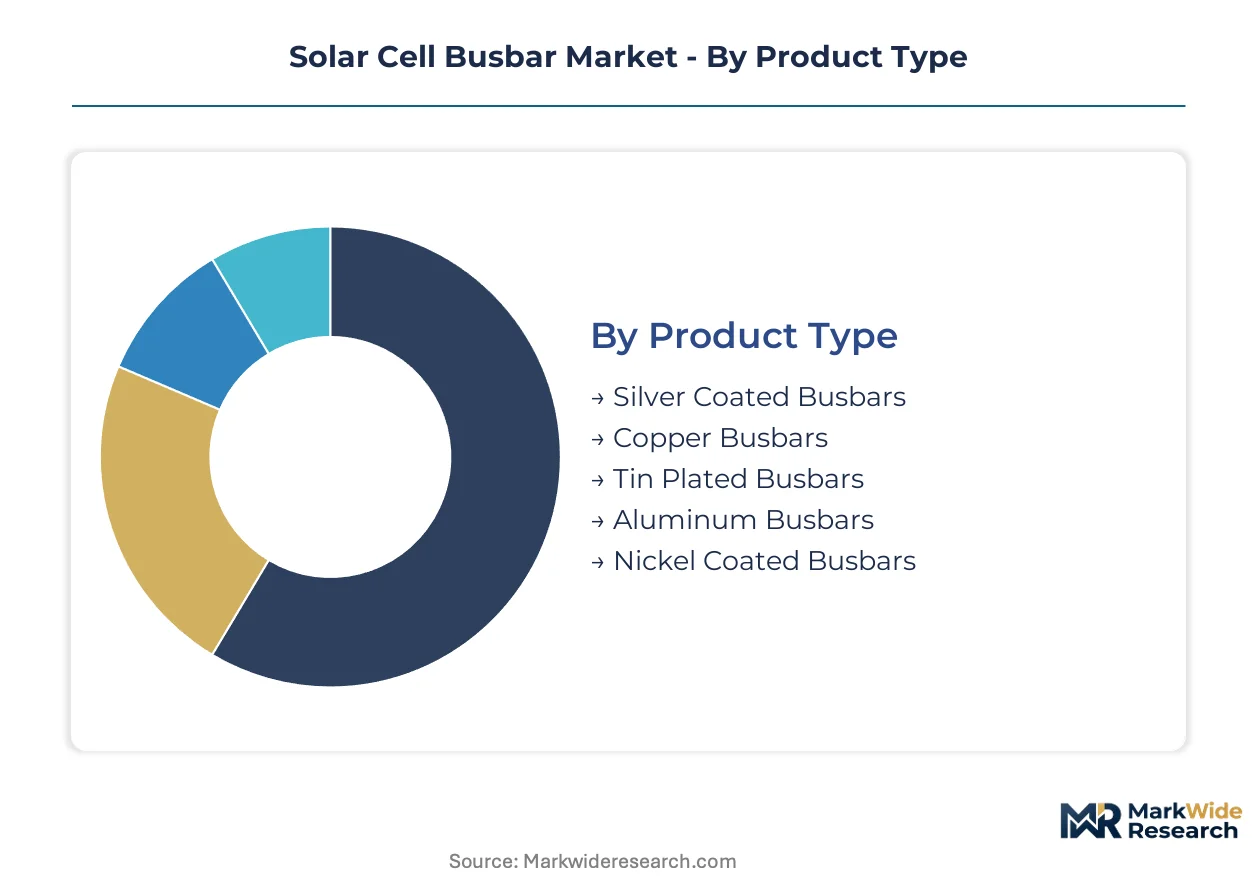
- Silver Coated Busbars:Silver-plated copper ribbons maintain resistivity below 0.0175 ohm-millimeter squared while enabling low-temperature soldering below 150 degrees Celsius. Heterojunction production lines in Jiangsu province specify these busbars exclusively to prevent cell breakage during interconnection, though London Bullion Market Association spot price swings compress margins.
- Copper Busbars:Unplated copper strips measuring 0.8–1.2 millimeters in width deliver optimal conductivity-to-cost ratios for monocrystalline PERC and TOPCon architectures. Demand concentrates with tier-one solar module manufacturers pursuing captive metallization partnerships with Chinese copper refiners to insulate against metal price volatility.
- Tin Plated Busbars:Anti-corrosion coatings satisfy 25-year performance warranties for desert and coastal utility-scale installations. Saudi Arabia's renewable tender pipeline specifies enhanced UV and sand-abrasion resistance.
- Aluminum Busbars:Lightweight alternative for rooftop residential systems where structural load limits constrain module weight. Emerging qualification for BIPV applications.
- Nickel Coated Busbars:Barrier plating chemistry for aggressive industrial environments with high sulfur or salt exposure. Limited penetration outside specialty chemical processing zones.
Volume sits with Copper Busbars; growth tilts toward Tin Plated Busbars.
Technology:
Cell efficiency roadmaps fragment metallization specifications, with each architecture imposing distinct line-width and thermal cycling requirements.
- Monocrystalline:PERC and TOPCon production lines drive standardization around 9-12 busbar designs with line widths compressing below 30 microns. Anhui province integrated cell-to-module clusters anchor procurement volumes for this segment.
- Polycrystalline:Legacy multi-busbar configurations persist in cost-sensitive distributed generation markets. Procurement volumes declining as manufacturers retool for higher-efficiency architectures.
- Thin Film:Cadmium telluride and CIGS modules eliminate traditional ribbon interconnection through integrated monolithic circuitry. Busbar demand limited to junction box terminations.
- Perovskite:Emerging tandem architectures require low-temperature processing compatible with organic-inorganic hybrid layers. Pilot lines testing silver-coated and specialized conductive adhesives.
- Multi-junction:III-V compound semiconductor cells for concentrated photovoltaic systems demand ultra-high conductivity busbars with precision thickness control. Aerospace and satellite applications dominate.
Procurement concentrates in Monocrystalline; Perovskite lines are expanding most quickly.
Application:
Scale and environmental exposure determine anti-corrosion specifications, with utility developers imposing the most stringent qualification protocols.
- Utility-scale Power Plants:Gigawatt-scale projects in desert and coastal regions mandate tin-plated busbars with accelerated electrochemical corrosion certification under SAMR GB standards. 25-year thermal cycling between minus 40 and plus 85 degrees Celsius drives premium plating thickness requirements.
- Commercial Solar Installations:Rooftop and carport systems balance conductivity requirements with installation labor efficiency. Standard copper busbars dominate procurement.
- Residential Solar Systems:Distributed generation installers prioritize cost minimization and supply chain availability over specialized metallization.
- Off-grid Solar Systems:Remote installations with limited maintenance access specify enhanced durability coatings.
- Agricultural Solar Projects:Agrivoltaic configurations expose busbars to fertilizer runoff and elevated humidity, driving nickel and tin plating adoption.
Utility-scale Power Plants command the steepest expansion trajectory; Residential Solar Systems maintain volume leadership.
End User Industry:
Integration depth and technical specification authority separate captive producers from merchant market buyers.
- Solar Module Manufacturers:Tier-one producers with in-house cell fabrication drive consolidated procurement contracts and direct copper refiner partnerships. Jiangsu and Anhui province clusters control dominant procurement volumes.
- EPC Contractors:Engineering-procurement-construction firms specify busbar grades in utility-scale tenders, creating qualification gatekeeping for ribbon suppliers.
- Power Generation Companies:State-owned and independent power producers impose warranty terms that cascade into metallization thickness requirements.
- Energy Storage Providers:Hybrid solar-plus-storage systems create secondary demand for busbar assemblies in DC-coupled configurations.
- Renewable Energy Service Firms:O&M contractors influence replacement and upgrade specifications for degraded interconnection components.
Supply relationships concentrate with Solar Module Manufacturers; specification authority is shifting toward EPC Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity in Jiangxi province and Zhejiang province anchors metallization supply chains for photovoltaic interconnection components. These raw-material localities feed integrated cell-to-module manufacturing clusters that dominate procurement volumes across multiple geographies.
China
Utility-scale tender pipelines in Ningxia and Qinghai provinces drive demand for tin-plated busbars with enhanced anti-corrosion specifications. SAMR-enforced GB standards for accelerated electrochemical corrosion testing disqualify legacy formulations and open procurement slots for certified suppliers. Jiangsu province and Anhui province host integrated manufacturing clusters where tier-one module producers consolidate direct copper refiner partnerships.
United States
Domestic content requirements under the Inflation Reduction Act incentivize localized busbar assembly for utility-scale photovoltaic projects. FERC interconnection queue reforms accelerate gigawatt-scale solar deployments in Texas and California, tightening delivery timelines for metallization components. Arizona and Nevada desert installations specify UV-resistant plating chemistries to survive 25-year thermal cycling warranties.
Germany
REACH substance restrictions on lead-bearing solder alloys force module manufacturers to certify tin-silver-copper formulations for European utility-scale developers. The EU F-Gas Regulation and CE marking directives shape export-bound busbar specifications for manufacturers serving utility-scale tenders. Saxony-Anhalt and Brandenburg host assembly operations supplying heterojunction production lines with low-temperature soldering-compatible ribbons.
Saudi Arabia
Gigawatt-scale renewable tender pipelines under Vision 2030 specify busbars with enhanced sand-abrasion and UV resistance for desert utility installations. The country's national renewable energy program mandates 25-year performance warranties that cascade into premium plating thickness requirements. Industrial City of Yanbu and King Abdullah Economic City concentrate module assembly operations serving domestic and regional export markets.
India
Production-linked incentive schemes for solar module manufacturing accelerate domestic busbar qualification for PERC and TOPCon production lines. BIS standards for photovoltaic interconnection materials tighten metallization specifications for subsidized projects. Gujarat and Rajasthan host integrated cell-to-module clusters where procurement concentrates for western and northern utility-scale deployments.
Solar Cell Busbar Market Key Industry Players
Global majors compete with regional champions across metallization capabilities and captive copper supply relationships. The vendor base stratifies into tier-one integrated manufacturers with in-house ribbon production, specialized metallization suppliers serving merchant markets, and copper refiners extending downstream into photovoltaic interconnection components. Strategic moves center on backward integration into copper refining and direct partnerships with cell manufacturers to lock in conductivity specifications.
Among Chinese integrated manufacturers, Trina Solar, JinkoSolar, and LONGi Green Energy Technology occupy positions spanning captive metallization capabilities and direct raw-material partnerships. These companies exemplify the tier-one archetype where in-house busbar production insulates margin pools from precious metal volatility. Specialized suppliers without integrated cell manufacturing sit within a distinct tier, competing on qualification speed and flexibility across PERC, TOPCon, and heterojunction line requirements. The competitive dynamic between these archetypes is reshaping procurement patterns as consolidated contracts displace spot-market ribbon purchases.
| Leading Market Players |
|---|
| Trina Solar |
| Astronergy |
| JinkoSolar |
| GCL System Integration |
| DAS Solar |
| LONGi Green Energy Technology |
| Tongwei Solar |
| Risen Energy |
| JA Solar |
| Others |
Cost & Logistics Intelligence
Zero-busbar cell architecture migration below 30-micron line widths simultaneously compresses metallization thickness tolerances and concentrates procurement power with Jiangsu-Anhui integrated manufacturers capable of captive ribbon production. This dual squeeze elevates conductivity specification precision as the dominant cost driver while locking out merchant suppliers lacking direct copper refinery partnerships.
Pricing Analysis
Warranty bundling separates utility-scale tenders requiring 25-year electrochemical corrosion certification from unbundled spot-market transactions serving distributed generation installers. Three-tier pricing structure across premium, standard, and economy levels tracks plating chemistry complexity—silver-coated ribbons for heterojunction lines command substantial premiums over tin-plated utility specifications, while unplated copper serves cost-sensitive residential segments. Pricing pressure stems from London Bullion Market Association silver spot volatility compressing margins on heterojunction-dedicated lines. Distributed generation installers exhibit highest price sensitivity; utility-scale EPC contractors prioritize certification compliance over unit cost.
Supply Chain Analysis
Freight cost differentials between Jiangxi-Zhejiang copper refining corridors and Anhui-Jiangsu cell-to-module clusters determine landed cost competitiveness for non-captive ribbon suppliers. Metallization supply chains draw from Chinese copper smelters, South Korean specialty alloy formulators, and German plating chemistry specialists. Raw material dependencies center on high-purity cathode copper, silver bullion, and tin ingot for anti-corrosion coatings. Single-source vulnerability concentrates in Jiangsu-Anhui procurement clusters controlling dominant procurement volumes. Distribution runs through direct metallization partnerships replacing spot-market ribbon purchases at tier-one integrated manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified copper refining capacity and accelerated electrochemical certification throughput prop pricing premiums as structural bottlenecks, constraining supply elasticity even as cell architecture fragmentation multiplies metallization specifications.
For Market Incumbents: Acquire captive copper refining assets or direct offtake agreements with Jiangxi-Zhejiang smelters to insulate margin pools from metal price volatility. Expand low-temperature soldering alloy R&D capabilities to defend heterojunction line positioning against silver-coated ribbon substitution. Certification investment in SAMR GB standards accelerates electrochemical testing protocols, creating qualification moats against merchant competitors lacking testing infrastructure. For New Entrants and Emerging Players: Begin with perovskite tandem pilot line metallization partnerships, where low-temperature processing requirements and absence of entrenched supplier relationships create penetrable white space. Target Saudi Arabian utility-scale EPC specifications for desert-optimized tin-plated busbars with enhanced UV resistance. Position through specialized plating chemistry technical service rather than volume commodity competition. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by tier-one integrated module manufacturers seeking backward integration into metallization capabilities. Long-term viability favors suppliers with dual certification capability across multi-busbar and zero-busbar architectures. Watch SAMR electrochemical certification timeline compression as inflection signal—accelerated qualification cycles favor scaled testing infrastructure over laboratory-stage formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Direct Jiangxi smelter partnerships lock in conductivity specifications and margin insulation. |
| Low-Temperature Soldering Alloy Development | Proprietary formulations below 150°C secure heterojunction line exclusivity with Japanese and European module manufacturers. |
| Accelerated Electrochemical Certification Investment | SAMR GB testing infrastructure reduces 4-6 month qualification cycles to capture procurement slots. |
| Desert Utility Specification Product Line | Saudi Vision 2030 tender compliance opens gigawatt-scale project access with premium plating thickness requirements. |
| Round Wire Interconnection Retrofit Program | Minimal capital conversion of existing tabbing-stringing equipment lowers barriers for heterojunction adoption. |
Research Approach
Independent corroboration across module manufacturer procurement directors, copper refinery technical sales leads, and EPC contractor metallization specifiers underwrites the qualitative findings in this study. Primary fieldwork encompassed tier-one solar module executives, Jiangsu-Anhui cluster operations managers, and SAMR certification laboratory directors. Secondary validation drew from customs trade data, GB standards documentation, FERC interconnection queue filings, and EU F-Gas Regulation implementation guidance. Bottom-up segmentation modeling triangulated against top-down copper consumption estimates from smelter discharge records.
Rate-of-change decomposition across cell architecture transitions, plating chemistry adoption curves, and regional tender pipelines structured the analytical framework. Segmentation dimensions encompassed product type, cell technology, application scale, and end-user integration depth. CAGRs were derived from installed capacity buildout trajectories weighted by busbar intensity per watt across PERC, TOPCon, and heterojunction lines. Forecast inputs incorporated silver price volatility scenarios and SAMR certification timeline scenarios.
Underlying measurement precision varies by segment; utility-scale power plant and monocrystalline technology projections carry tighter precision than emerging perovskite tandem estimates. Forecasts reflect assumptions regarding cell architecture transition speed and electrochemical certification throughput capacity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
United States Solar Energy Market
Solar Power Systems
Greece Solar Energy Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Solar Thermal Collector Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Photovoltaic Solar Kits Market
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
United Arab Emirates Solar Energy Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Europe Solar Backsheet Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Biohybrid Solar Cell Market