
 Global Concentrating Solar Power Market | 2026-2036
Global Concentrating Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concentrating Solar Power Market Analysis
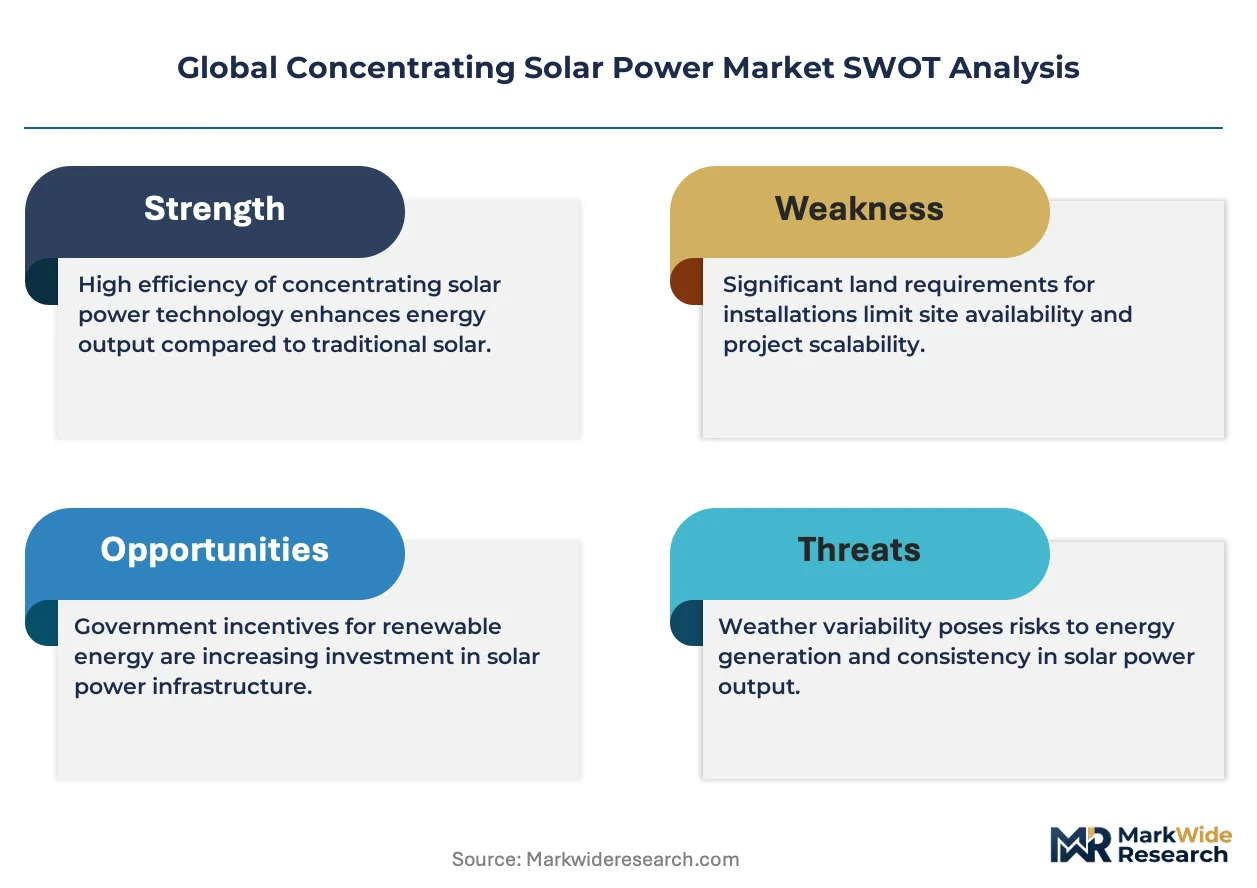
Molten salt is rebalancing heat transfer economics in new parabolic trough and power tower installations. ACWA Power leverages its Saudi project pipeline to anchor long-term offtake contracts across the Middle East and North Africa. BrightSource Energy specializes in power tower architectures with direct steam generation, while Abengoa Solar sustains manufacturing scale across Spanish and international EPC workflows.
Concentrating solar power harnesses mirrors or lenses to focus sunlight onto a receiver, generating temperatures exceeding 400°C to drive conventional steam turbines or store thermal energy in molten salt for dispatchable generation. Parabolic trough technology dominates installed capacity due to decades of operational maturity, though power tower configurations capture attention for higher temperature ceilings and improved storage integration. Utility-scale application leads procurement volumes, while industrial heat segments attract interest from cement and chemical processors seeking decarbonized process temperatures.
The EU Green Deal and F-Gas Regulation shape equipment standards and refrigerant choices for European project developers, while China's MEE enforces emission intensity thresholds for new thermal plant approvals. The IRA extends production tax credits that improve project finance structures for US developers. Stakeholders must monitor regulatory phase-out timelines for fossil backup fuels and storage mandate expansions that redefine plant configuration requirements.
Market Dynamics
Molten salt thermal storage is automating dispatch profiles across new concentrating solar power installations, compressing the cost gap between renewable and fossil baseload while forcing developers to reconfigure heat transfer architectures.
Growth Catalysts
- EU Green Deal emission benchmarks:The framework tightens carbon intensity thresholds for dispatchable power, mandating thermal storage integration in new European projects.
- Industrial heat decarbonization:Cement and chemical processors in Spain and Morocco are procuring concentrated solar thermal for process temperatures above 400°C.
- China's dual carbon goals:MEE enforcement of emission intensity thresholds accelerates molten salt tower approvals over oil-trough designs.
Market Restraints
- Heliostat supply concentration:Precision mirror manufacturing clusters in China and Germany create vulnerability for power tower developers in the Middle East and North Africa.
- Nitrate salt price volatility:Potassium nitrate and sodium nitrate input costs fluctuate with fertilizer market cycles, pressuring 12-15 hour storage economics.
- Direct normal irradiance requirements:Site selection limits viable project geography to arid belts between 15° and 40° latitude.
Strategic Opportunities
- Green hydrogen integration:High-temperature steam electrolysis pairs with power tower output to produce industrial hydrogen in Saudi Arabia and the United Arab Emirates.
- US IRA production tax credits:The 30% investment credit improves project finance structures for Southwestern developers with molten salt storage.
- Desalination co-location:Thermal output from trough plants supplies multi-effect distillation in Morocco's coastal provinces.
Industry Challenges
- Molten salt system commissioning:Specialized thermal engineering talent scarcity extends plant startup timelines in emerging markets.
- Grid interconnection queues:Transmission access delays in Spain and California strand completed solar field capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concentrating Solar Power Market |
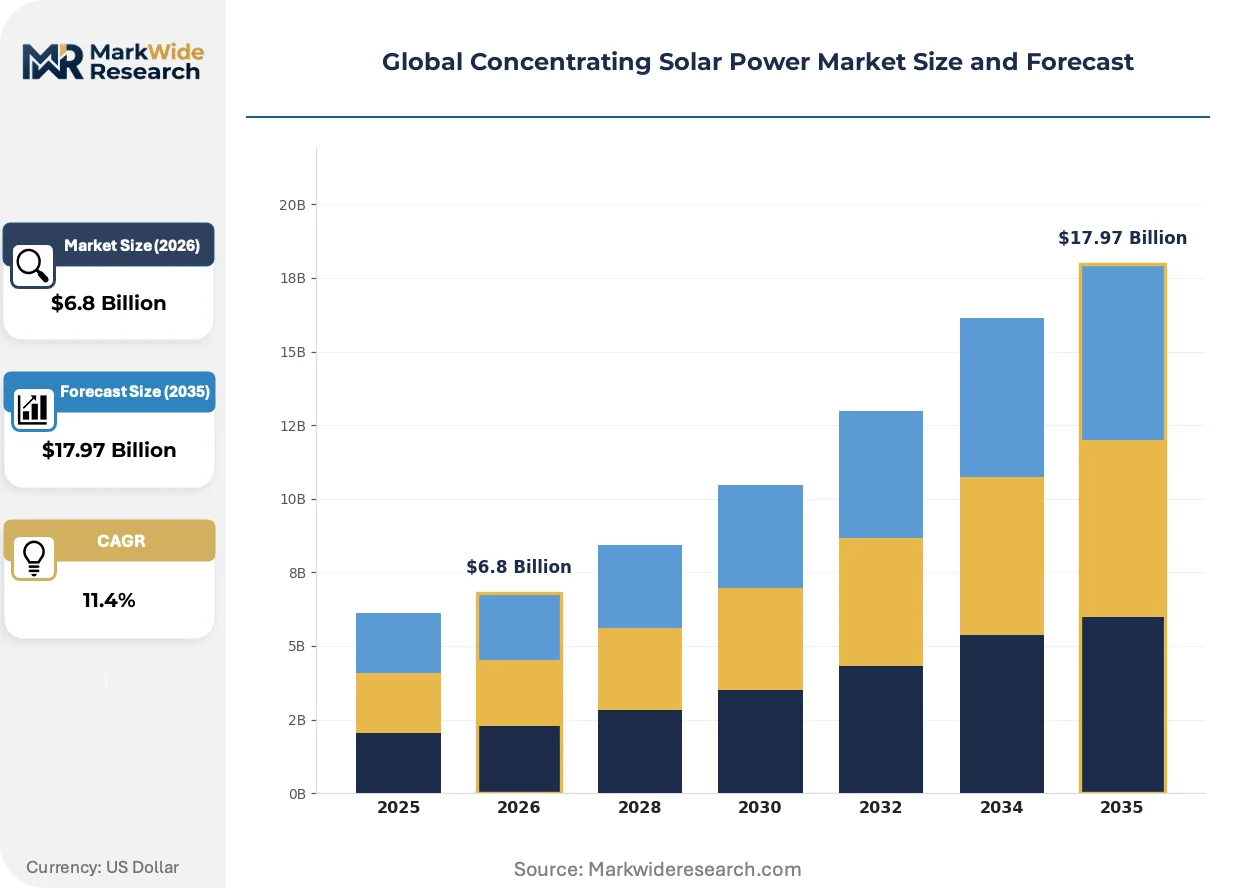
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Thermal Storage, Molten Salt, Parabolic Trough, Power Tower Application: Utility-Scale, Hybrid Systems, Industrial Heat, Desalination End User: Energy Providers, Industrial Manufacturers, Government Agencies, Commercial Enterprises System Size: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | ACWA Power, BrightSource Energy, Abengoa Solar, SENER, Acciona, Siemens Energy, Aalborg CSP, SolarReserve, TSK Flagsol, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concentrating Solar Power Market Emerging Trajectories
Automation of thermal storage dispatch is compressing the operational gap between solar thermal and conventional peaking plants. Three developments are restructuring competitive positioning.
Artificial intelligence-driven heliostat field control is automating solar tracking precision. ACWA Power and Saudi project developers deploy machine learning algorithms to optimize mirror alignment in real-time. The technology is automating operational expenditure reduction while extending receiver lifetime through thermal stress management.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants used in organic Rankine cycle plants. Equipment manufacturers must redesign heat rejection systems for alternative working fluids. Spanish EPC workflows face compressed certification timelines as 2027 phase-out deadlines approach.
Long-term offtake contracting is consolidating buyer concentration among utility and industrial offtakers. Twenty-year power purchase agreements with sovereign-backed counterparties in Morocco and the United Arab Emirates displace merchant risk exposure. Procurement teams now prioritize dispatchability guarantees over levelized cost minimization.
Global Concentrating Solar Power Market Segmentation
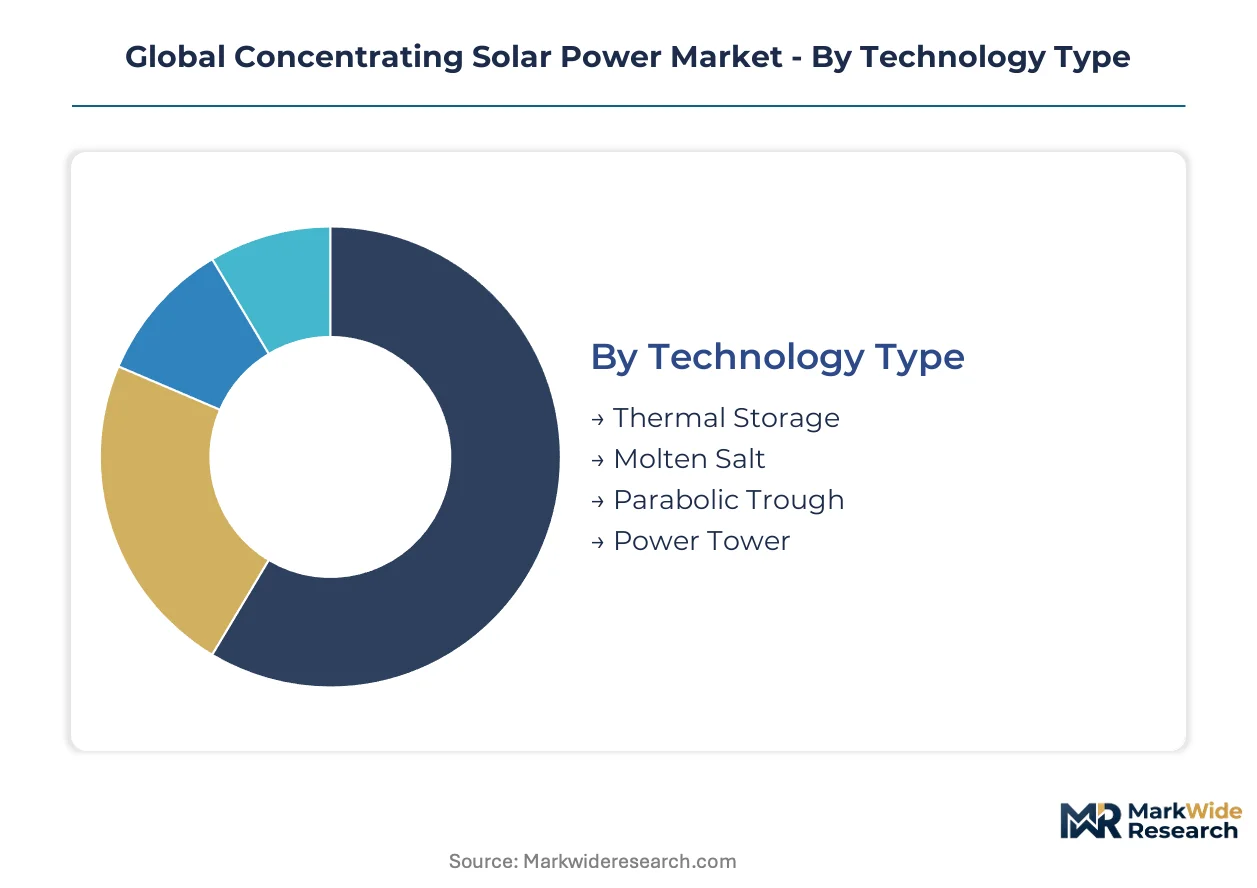
Technology architecture and application scale define competitive positioning in concentrating solar power procurement. Developers configure heat transfer systems and storage duration against specific offtaker dispatch requirements and site irradiance profiles.
Technology Type:
Parabolic trough dominates installed megawatts while power tower commands premium economics through higher temperature ceilings and integrated molten salt storage.
- Parabolic Trough:Curved mirror arrays focus sunlight onto evacuated tube receivers containing synthetic oil or molten salt heat transfer fluid. Spanish and Moroccan utility-scale plants anchor procurement volumes for this mature technology with proven operational track records across two decades of commercial deployment.
- Power Tower:Heliostat fields concentrate solar flux onto a central receiver atop a tower, achieving temperatures exceeding 565°C for supercritical steam cycles. Saudi Arabia and the United Arab Emirates developers favor this architecture for green hydrogen integration and extended thermal storage dispatch.
- Molten Salt:Binary nitrate mixtures enable 12-15 hour thermal storage at 290-565°C operating range, displacing oil-based systems in new plant designs. China's MEE emission benchmarks accelerate approvals for salt-based configurations over conventional heat transfer fluids.
- Thermal Storage:Sensible heat storage in insulated tanks automates dispatch profiles and compresses the cost gap with fossil baseload. Nitrate salt price volatility tied to fertilizer market cycles pressures project economics in procurement planning.
Today's leader: Parabolic Trough. Tomorrow's challenger: Power Tower.
Application:
Utility-scale generation absorbs capital deployment while industrial heat applications attract cement and chemical processors seeking decarbonized process temperatures above 400°C.
- Utility-Scale:Grid-connected plants exceeding 50 MW capacity supply dispatchable renewable power under long-term offtake contracts. ACWA Power leverages its Saudi project pipeline to anchor twenty-year power purchase agreements across the Middle East and North Africa.
- Industrial Heat:Concentrated solar thermal delivers process steam and high-temperature heat for cement kilns and chemical reactors. Spanish cement manufacturers in Andalusia procure trough systems to displace natural gas in clinker production.
- Hybrid Systems:Solar thermal integrates with photovoltaic arrays or fossil backup to firm output profiles and optimize land use. California developers combine power towers with gas turbines to meet evening peak demand.
- Desalination:Thermal output from trough plants supplies multi-effect distillation for freshwater production. Morocco's coastal provinces deploy co-located solar fields and desalination infrastructure to address water scarcity.
Utility-Scale captures current investment flows. Industrial Heat is climbing the fastest as carbon pricing tightens.
End User:
Energy providers structure project finance around sovereign-backed offtake while industrial manufacturers prioritize thermal output predictability over electricity market exposure.
- Energy Providers:State utilities and independent power producers procure dispatchable renewable capacity to meet renewable portfolio standards and emission reduction commitments. Morocco's ONEE and Saudi Arabia's SEC anchor regional procurement volumes.
- Industrial Manufacturers:Cement, chemical, and mining processors purchase concentrated solar thermal for process heat applications. Spain's cement sector leads European industrial deployment with operational plants in Extremadura and Andalusia.
- Government Agencies:Sovereign wealth funds and development authorities finance demonstration projects and strategic energy security infrastructure. The UAE's Masdar and Saudi Arabia's PIF capitalize utility-scale development pipelines.
- Commercial Enterprises:Large electricity consumers contract directly for renewable thermal or power supply under corporate power purchase agreements. Aluminum smelters and desalination operators in the Gulf states negotiate bilateral offtake structures.
Energy Providers dominate contract volumes. Industrial Manufacturers are gaining share fastest as process heat electrification accelerates.
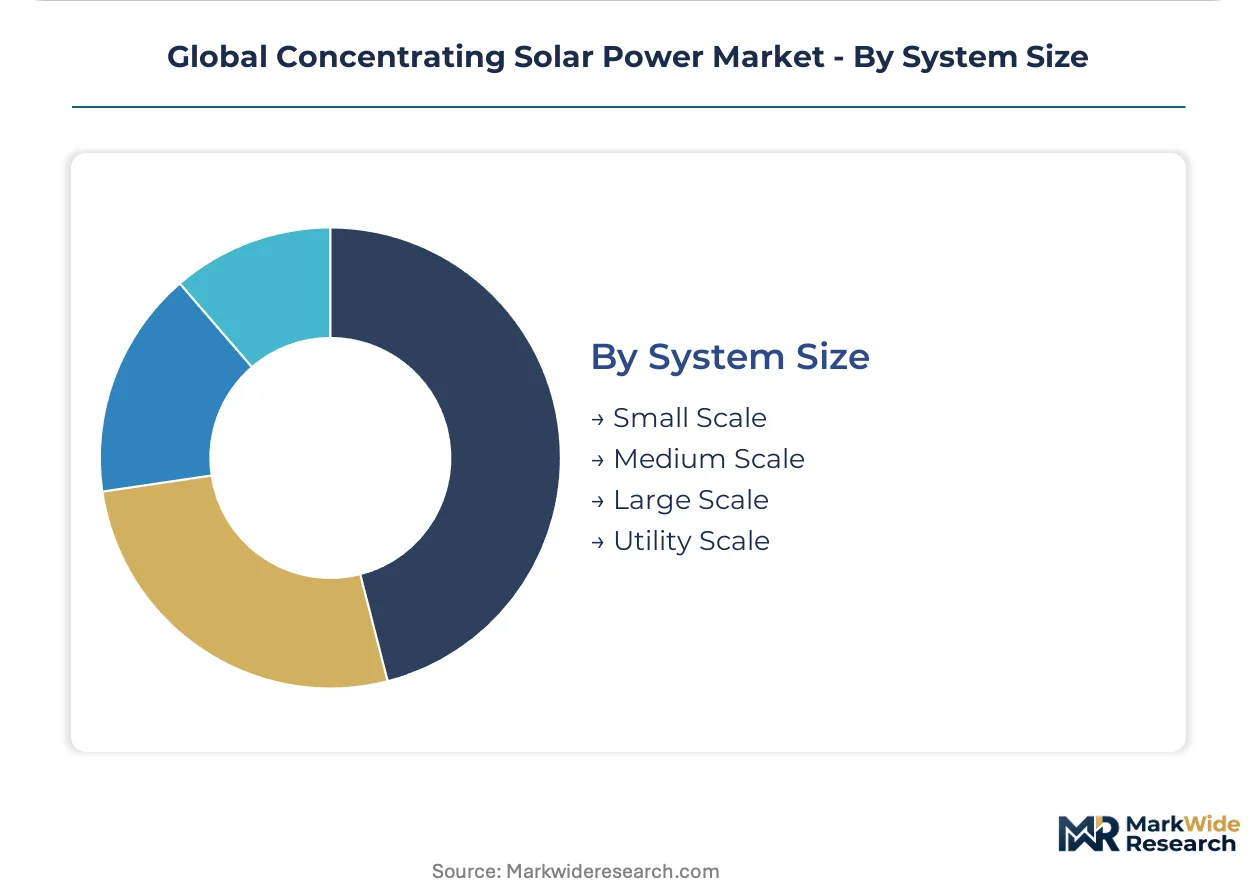
System Size:
Utility-scale configurations achieve lowest levelized cost through thermal storage economies of scale while small-scale systems serve isolated industrial facilities.
- Utility Scale:Plants exceeding 100 MW with 6-15 hour thermal storage optimize heat transfer infrastructure and grid interconnection costs. Noor Energy and Mohammed bin Rashid Al Maktoum Solar Park anchor global capacity additions.
- Large Scale:50-100 MW installations balance capital efficiency with site-specific constraints in markets with transmission access limitations. Spanish developers configure this scale for regional grid integration.
- Medium Scale:10-50 MW systems serve industrial parks and municipal utilities with moderate thermal or power demand. Moroccan chemical processors deploy medium trough fields for process steam supply.
- Small Scale:Sub-10 MW installations address isolated industrial heat loads and remote desalination requirements. Mining operations in Chile's Atacama Desert pilot small tower systems for mineral processing.
Utility Scale commands capital deployment. Small Scale holds steepest expansion trajectory for off-grid industrial applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's ACWA Power anchors the Middle East project pipeline while Spain's Andalusian solar belt sustains European manufacturing scale. China's dual carbon enforcement accelerates molten salt tower approvals. The United States, Morocco, and the United Arab Emirates concentrate procurement volumes across distinct regulatory environments.
Spain
Andalusian trough plants supply process heat to cement kilns in Extremadura while Spanish EPC workflows sustain manufacturing scale. The EU Green Deal and F-Gas Regulation tighten emission benchmarks and phase out hydrofluorocarbon refrigerants by 2027. Seville-based engineering clusters anchor parabolic trough technology exports across Mediterranean markets.
United States
Southwestern developers leverage molten salt storage configurations for evening peak dispatch in California and Arizona. The IRA extends production tax credits that improve project finance structures for dispatchable renewable capacity. Mojave Desert installations combine power towers with gas turbines to firm output profiles under FERC interconnection standards.
China
MEE emission intensity thresholds accelerate approvals for salt-based tower designs over conventional oil-trough configurations. The dual carbon goals enforce dispatchable renewable benchmarks for new thermal plant approvals. Qinghai and Gansu provinces host concentrated solar thermal clusters integrated with high-temperature industrial processes.
Morocco
ONEE procurement anchors twenty-year power purchase agreements for Noor Energy complexes while coastal provinces deploy desalination co-location. Sovereign-backed offtake structures displace merchant risk exposure for international developers. Ouarzazate solar fields supply multi-effect distillation capacity alongside grid-connected generation.
United Arab Emirates
Masdar and sovereign wealth financing capitalize the Mohammed bin Rashid Al Maktoum Solar Park expansion with power tower architectures. Green hydrogen integration projects pair high-temperature steam electrolysis with thermal storage dispatch. Dubai and Abu Dhabi clusters concentrate heliostat field deployment under MOHAP industrial permitting frameworks.
Global Concentrating Solar Power Market Vendor Landscape
Global majors compete with regional champions across technology architecture and offtake contracting. The vendor base spans Saudi project developers, Spanish EPC specialists, and American power tower architects. Three archetypes dominate: integrated developers with sovereign-backed pipelines, technology licensors with proprietary receiver designs, and engineering contractors with manufacturing scale. Competitive moves center on long-term offtake anchoring and molten salt storage integration partnerships.
Among Middle East-based integrated developers, ACWA Power exemplifies the sovereign-pipeline archetype through Saudi project origination. BrightSource Energy and Abengoa Solar occupy distinct technology-specialist positions, with the former representing power tower architecture and the latter sustaining Spanish manufacturing workflows across international EPC contracts.
| Leading Market Players |
|---|
| ACWA Power |
| BrightSource Energy |
| Abengoa Solar |
| SENER |
| Acciona |
| Siemens Energy |
| Aalborg CSP |
| SolarReserve |
| TSK Flagsol |
| Others |
Supply Flow & Price Mechanics
Nitrate salt procurement costs cascade from fertilizer market volatility through project developer margins, with potassium nitrate and sodium nitrate price swings transmitted directly into 12-15 hour thermal storage economics across Spanish and Middle Eastern installations.
Pricing Analysis
Input-cost pass-through from nitrate salt commodity cycles dominates project-level pricing, with molten salt thermal storage configurations commanding premium tariffs over oil-trough designs due to dispatchability guarantees. Price differentiation separates utility-scale developers securing sovereign-backed twenty-year power purchase agreements from industrial heat buyers facing merchant exposure in cement and chemical applications. Pricing pressure stems from heliostat supply concentration in China and Germany, which amplifies mirror procurement costs for power tower developers in Saudi Arabia and the United Arab Emirates. Industrial manufacturers in Spain demonstrate highest price sensitivity due to carbon pricing exposure, while sovereign utilities in Morocco and the UAE prioritize dispatchability over levelized cost minimization.
Supply Chain Analysis
Local-content rules in Saudi Arabia and the UAE reshape heliostat sourcing, mandating domestic manufacturing participation for Mohammed bin Rashid Al Maktoum Solar Park contractors. Geographic supply concentration clusters precision mirror fabrication in China and Germany, with nitrate salt extraction anchored to Chilean and Israeli fertilizer producers. Raw material dependencies center on potassium nitrate, sodium nitrate, and specialized steel alloys for receiver towers. Supply chain risk crystallizes around single-source vulnerability for heliostat drive mechanisms. Distribution runs through EPC contractors with Spanish manufacturing workflows exporting trough components across Mediterranean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where China's MEE emission intensity thresholds accelerate molten salt tower approvals while EU F-Gas Regulation phase-outs compress Spanish organic Rankine cycle equipment timelines.
For Market Incumbents: Acquire molten salt thermal engineering talent pools to compress commissioning timelines in emerging markets. Defensive consolidation centers on backward integration into nitrate salt supply contracts to hedge fertilizer market volatility, and capacity addition in Qinghai province to capture China's dual carbon enforcement tailwinds. Substitute technology threat from photovoltaic-plus-battery configurations demands dispatchability guarantee reinforcement in offtake contracting. For New Entrants and Emerging Players: The IRA in the United States opens a window for Southwestern developers to structure project finance around production tax credits for molten salt storage configurations. White-space targets concentrate in Chilean mining operations seeking small-scale tower systems for mineral processing heat loads, and Moroccan coastal desalination co-location where thermal output supplies multi-effect distillation. Go-to-market execution hinges on bilateral offtake negotiation with aluminum smelters and desalination operators in Gulf states. For Investors and Strategic Acquirers: Consolidation pressure builds where heliostat supply concentration meets sovereign-backed procurement scale in Saudi Arabia and the UAE. Long-term viability over the next decade rests on thermal storage integration depth rather than generation capacity alone. Acquisition target archetype: Spanish EPC specialists with Andalusian manufacturing workflows and Mediterranean export relationships. Signal to watch: grid interconnection queue clearance rates in California and Spain as stranded solar field capacity indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Power Purchase Agreement | Sovereign-backed offtake structures in Morocco and UAE displace merchant risk exposure. |
| Backward Integration into Storage | Nitrate salt supply contracts hedge fertilizer market volatility for project developers. |
| Technology Licensing | Power tower receiver designs transfer to Saudi developers for green hydrogen integration. |
| Capacity Buildout | Qinghai province clusters capture China's MEE emission intensity enforcement tailwinds. |
| Green Certification Program | EU Green Deal benchmarks mandate thermal storage integration for European project approvals. |
Methodological Framework
Multiple input streams — utility planning interviews, EPC contractor field assessments, and sovereign wealth fund investment committee discussions — were reconciled against secondary validation from EIA data, IEA reports, and FERC filings. Primary engagement spanned IPP project developers, grid operators, and molten salt thermal engineering specialists. Secondary sources included project development databases tracking Noor Energy and Mohammed bin Rashid Al Maktoum Solar Park milestones, customs records for heliostat import flows, and SEC filings from listed EPC contractors. Bottom-up capacity addition tallies were triangulated against top-down regulatory pipeline assessments.
Data-stream reconciliation anchored analytical frameworks across technology architecture, application scale, and regional regulatory clusters over the projection horizon. Segmentation dimensions modeled encompassed parabolic trough versus power tower configurations, utility-scale versus industrial heat end-use, and sovereign-backed versus merchant offtake structures. CAGRs were derived from capacity deployment trajectories, tariff evolution patterns, and nitrate salt cost curve projections. Industry-specific forecast inputs incorporated China's MEE enforcement timelines and EU F-Gas Regulation phase-out deadlines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nitrate salt price spike conditions or grid interconnection queue extensions in Spain and California. Analytical boundaries exclude photovoltaic technology substitution effects and fossil fuel price collapse scenarios. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
US Solar Market
Solar Power Systems
Boat Solar Panel Market
Solar Power Systems
Global EV Solar Modules Market
Solar Power Systems
Solar Updraft Tower Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
Building Applied Photovoltaics (BAPV) Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
United Kingdom Solar Power Market