
 Italy Solar Energy Market | 2026-2036
Italy Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Solar Energy Market Outlook
Utility procurement fragmentation is restructuring Italy's solar demand base as regional energy providers and industrial off-takers displace traditional large-utility dominance. Enel Green Power SpA anchors national pipeline development through its integrated development-to-generation model across multiple Italian regions. Falck Renewables (Renantis) SpA differentiates through specialized agrivoltaic and floating solar expertise in constrained land markets. ERG SpA sustains competitive position via its concentrated southern Italian asset base and operational scale advantages.
Italy solar energy encompasses photovoltaic and concentrated solar power systems that convert electromagnetic radiation into electrical energy through semiconductor junctions or thermal cycles, typically operating at module efficiencies between 19% and 22% for crystalline silicon technologies deployed across residential rooftops to utility-scale ground arrays. The technology dimension spans photovoltaic, concentrated solar power, thin film, and bifacial categories, with bifacial modules capturing incremental margin pools as albedo-sensitive designs penetrate Italy's high-reflectivity agricultural and industrial installations. Application segments split across residential, commercial, industrial, and utility-scale deployments, where utility-scale projects absorb the dominant capital allocation under PNIEC-aligned auction mechanisms while commercial rooftop installations exhibit the fastest capacity growth rate among behind-the-meter categories.
Italy's solar regulatory architecture operates under the Ministry of Environment and Energy Security (MASE) permitting frameworks, supplemented by Gestore dei Servizi Energetici (GSE) incentive administration and Terna grid connection protocols, collectively shaping project development timelines and revenue certainty structures. The National Integrated Energy and Climate Plan binds Italy to specific renewable capacity trajectories reviewed under EU Green Deal compliance monitoring, while local authority zoning under Piano Paesaggistico Regionale constraints affects siting feasibility in heritage-sensitive territories. Stakeholders must monitor the convergence of EU Net-Zero Industry Act domestic content requirements with Italy's thin domestic manufacturing base to assess supply chain exposure and procurement strategy adjustments.
Market Dynamics
PNIEC auction mechanisms are concentrating capital flows toward utility-scale arrays while bifacial module specifications restructure procurement criteria across Italian industrial offtakers.
Growth Catalysts
- MASE Permitting Streamlining:Consolidated environmental authorization timelines compress project development cycles for ground-mounted installations in southern regions.
- Agricultural Land Dual-Use:Agrivoltaic deployments unlock constrained real estate in Lombardy and Emilia-Romagna while preserving crop productivity.
- Terna Grid Modernization:Transmission infrastructure upgrades in Puglia and Sicily reduce curtailment risk for utility-scale generators.
Market Restraints
- Polysilicon Supply Concentration:Chinese ingot and wafer manufacturing dominance exposes Italian developers to input cost volatility and trade policy uncertainty.
- Piano Paesaggistico Regionale Zoning:Heritage protection frameworks in Tuscany and Umbria restrict siting feasibility for visually prominent ground arrays.
- Grid Interconnection Queues:Terna connection protocol backlogs extend commercial operation dates for projects in saturated nodal zones.
Strategic Opportunities
- Floating Solar on Irrigation Reservoirs:Unexploited water surface area in Po Valley agricultural districts offers capacity expansion without land-use conflict.
- EU Net-Zero Industry Act Domestic Content:Incentive bonuses for European-manufactured modules create procurement strategy pivot points for auction participants.
- Industrial Self-Consumption Aggregation:Northern manufacturing clusters are forming energy communities to optimize behind-the-meter economics.
Industry Challenges
- Electrical Engineering Talent Scarcity:Specialized inverter commissioning and grid-code compliance expertise shortages delay commercial operation across project portfolios.
- GSE Incentive Administration Complexity:Registration and verification protocol navigation consumes disproportionate development resources relative to neighboring markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Solar Energy Market |
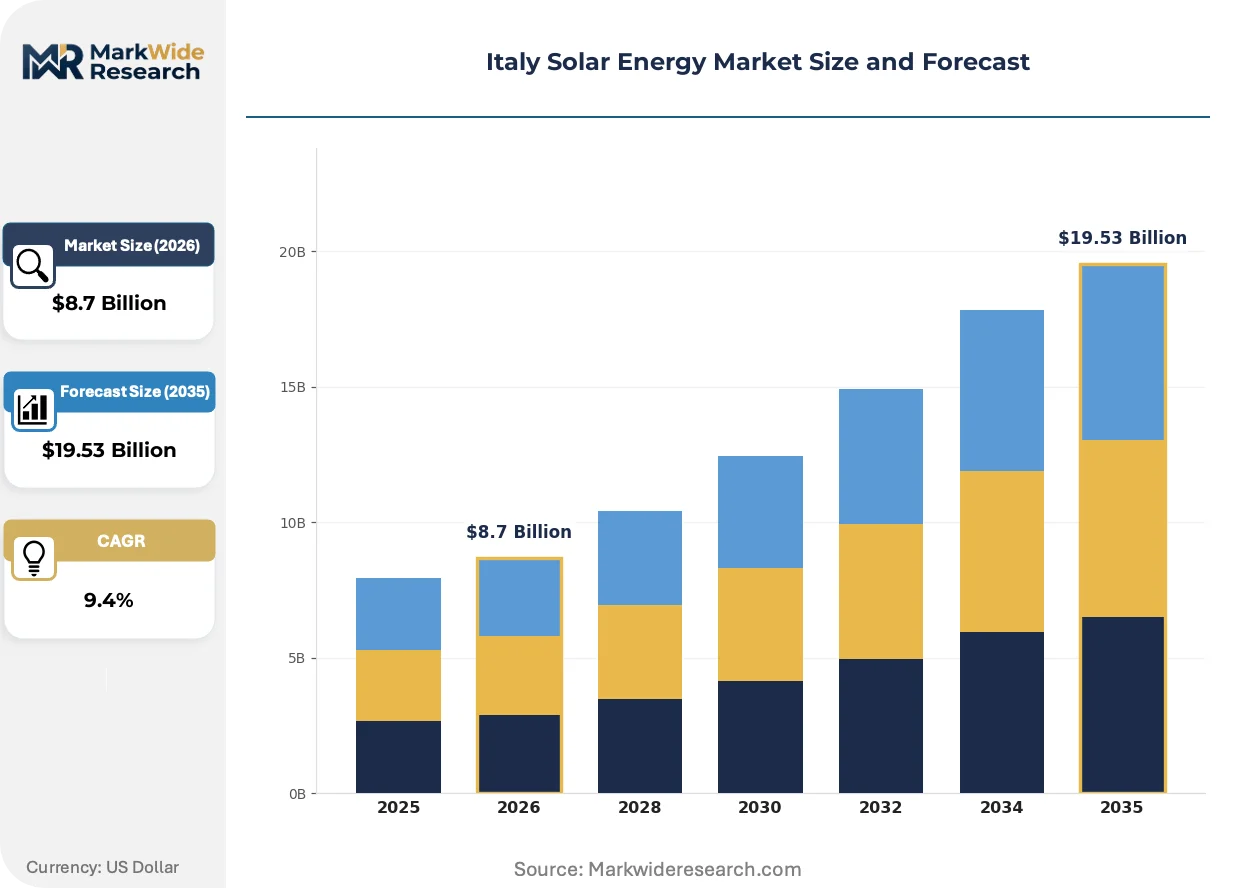
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Residential, Commercial, Industrial, Utility-scale Technology: Photovoltaic, Concentrated Solar Power, Thin Film, Bifacial End User: Homeowners, Businesses, Government, Energy Providers Installation Type: On-grid, Off-grid, Roof-mounted, Ground-mounted |
| Companies Covered | Falck Renewables (Renantis) SpA, Peimar SRL, Enel Green Power SpA, Sorgenia SpA, Gruppo STG SRL, EF Solare Italia SpA, A2A Rinnovabili SpA, Plenitude (Eni Renewables), ERG SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Solar Energy Market Strategic Shifts
Bifacial module architectures and agrivoltaic system designs are reconfiguring deployment economics while regulatory compliance requirements reshape procurement specifications.
Bifacial photovoltaic modules capture reflected irradiance from high-albedo surfaces to boost energy yield per installed watt. Italian agricultural and industrial installers with reflective ground conditions are specifying bifacial glass-glass constructions for new ground-mount projects. Monofacial designs are overtaking traditional configurations in premium procurement segments where levelized cost optimization drives specification decisions.
EU Green Deal compliance monitoring binds Italy to renewable capacity trajectories with binding review mechanisms. PNIEC revision cycles tighten deployment timelines and accelerate auction frequency to close gap-to-target scenarios. Utility-scale developers in Puglia and Basilicata are compressing engineering timelines to align with accelerated authorization windows.
Industrial offtakers are consolidating procurement decisions through direct power purchase agreements rather than regulated tariff schemes. Large manufacturing facilities in Lombardy and Veneto are negotiating bilateral contracts with project sponsors to secure price certainty. This contracting model rotation is most visible across automotive and food processing supply chains where energy cost exposure directly impacts margin structures.
Italy Solar Energy Market Segmentation
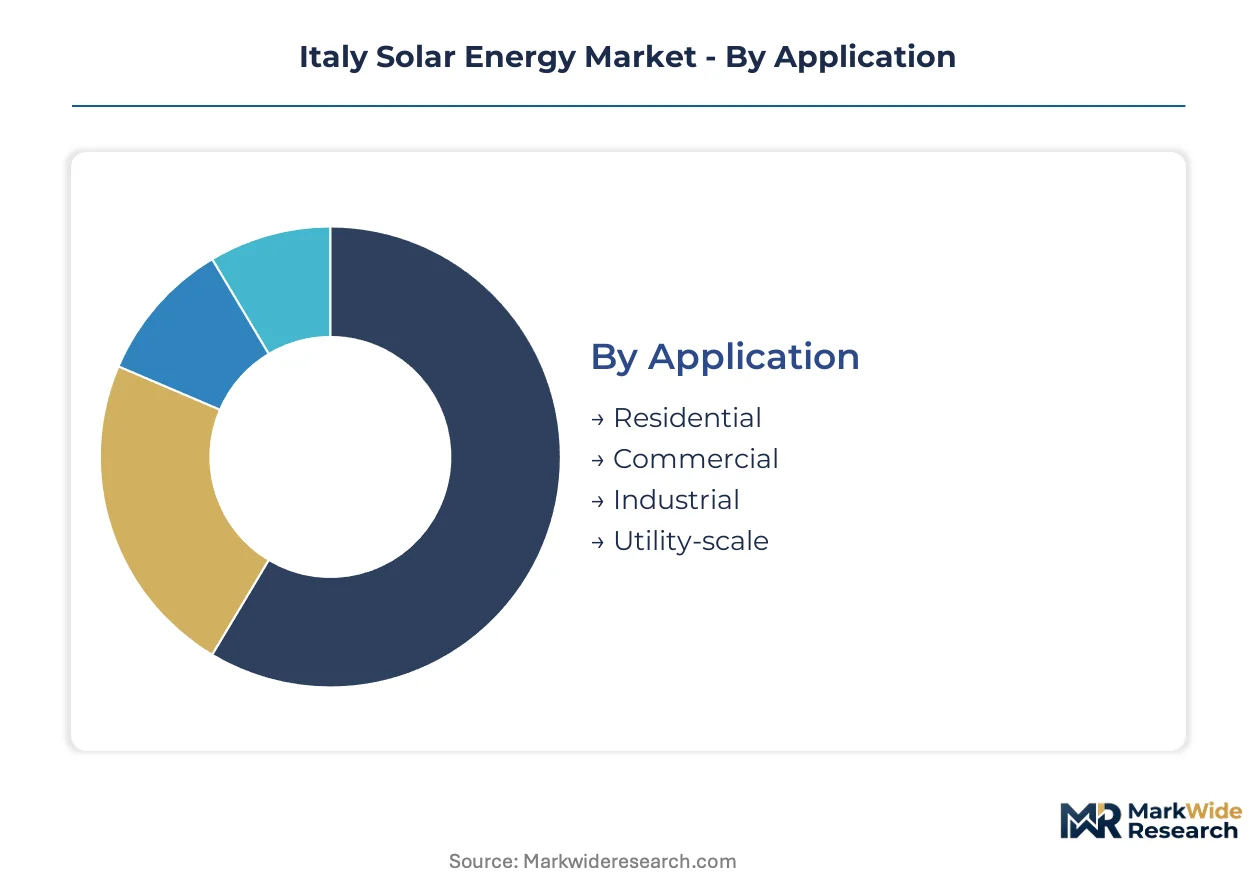
Segmentation in Italy's solar market reveals how PNIEC-aligned incentives and regional grid conditions reshape capital allocation across buyer categories. Procurement patterns diverge sharply between northern industrial clusters and southern utility-scale zones.
Application:
Capital deployment intensity varies by offtaker scale and regulatory access, with auction mechanisms favoring volume concentration in specific installation categories.
- Residential:Rooftop systems under 20 kW dominate Lombardy and Veneto installations. Homeowners in these regions leverage Gestore dei Servizi Energetici (GSE) net metering schemes to optimize self-consumption economics against rising retail tariffs.
- Commercial:Behind-the-meter arrays for retail and logistics facilities absorb the steepest expansion trajectory among application segments. Northern manufacturing belts drive procurement as energy communities aggregate demand across multi-tenant industrial parks.
- Industrial:Large manufacturing facilities in automotive and food processing verticals negotiate direct power purchase agreements. Procurement concentrates where grid parity eliminates subsidy dependence.
- Utility-scale:Ground-mounted arrays above 1 MW absorb dominant capital flows under PNIEC auction mechanisms. Puglia and Basilicata host concentrated development pipelines due to superior irradiance profiles and available land.
Utility-scale leads on scale; commercial leads on momentum.
Technology:
Module specification decisions pivot on albedo conditions, land constraints, and EU domestic content requirements reshaping procurement criteria.
- Photovoltaic:Crystalline silicon configurations at 19-22% module efficiency constitute the baseline technology. Lombardy agricultural installers specify these for standard ground-mount and rooftop deployments where reflectivity remains moderate.
- Bifacial:Glass-glass constructions capture rear-side irradiance from high-albedo surfaces. Po Valley agrivoltaic projects and industrial installations with reflective roofing specify these modules for incremental yield per installed watt.
- Concentrated Solar Power:Thermal cycle systems with molten salt storage suit Sicily and Sardinia utility applications. High direct normal irradiance requirements limit deployable geography to southern insolation corridors.
- Thin Film:Cadmium telluride and copper indium gallium selenide configurations penetrate niche building-integrated applications. Lower efficiency tolerances restrict adoption to facade and lightweight roof structures in heritage-sensitive urban zones.
Photovoltaic leads on scale; bifacial leads on momentum.
End User:
Contracting model selection depends on balance sheet capacity, regulatory sophistication, and exposure to wholesale price volatility.
- Homeowners:Individual residential offtakers navigate GSE registration protocols for net metering authorization. Lombardy and Emilia-Romagna concentrations reflect income demographics and roof ownership patterns.
- Businesses:Corporate procurement teams negotiate bilateral power purchase agreements directly with project sponsors. Food processing and automotive supply chains in northern regions drive aggregate demand.
- Government:Public sector entities including municipal utilities procure through centralized auction mechanisms. Ministry of Environment and Energy Security (MASE) frameworks structure tender participation requirements.
- Energy Providers:Regional utilities and independent power producers develop pipeline assets for merchant or contracted revenue streams. Terna grid connection queues shape project commercialization timelines.
Energy providers lead on scale; businesses lead on momentum.
Installation Type:
Grid interconnection protocols and land availability constraints determine feasible configurations across Italian regions.
- On-grid:Grid-connected systems with Terna-synchronized inverters constitute the dominant installation category. PNIEC-aligned projects require standardized grid-code compliance certification.
- Off-grid:Battery-coupled standalone systems penetrate isolated agricultural operations and mountain refuges. Alpine and Apennine micro-installations where distribution infrastructure extension proves uneconomical drive niche demand.
- Roof-mounted:Building-applied photovoltaic configurations exploit existing structural surfaces without land-use conflict. Urban density in Milan and Turin corridors restricts ground-mount feasibility.
- Ground-mounted:Field-array installations on agricultural or brownfield sites enable utility-scale capacity deployment. Piano Paesaggistico Regionale zoning constraints in Tuscany and Umbria limit siting feasibility for visually prominent configurations.
On-grid leads on scale; roof-mounted leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Milan and Bologna anchor Italy's solar development pipeline, with specialized electrical contractors and project financiers concentrating in northern industrial corridors. Technical workforce availability shapes regional deployment velocity more than irradiance differentials alone.
Lombardy
Industrial self-consumption demand from automotive and machinery manufacturers drives commercial rooftop installations. Gestore dei Servizi Energetici administers net metering schemes that optimize behind-the-meter economics for Milan-area manufacturing facilities. The Po Valley corridor hosts concentrated agrivoltaic development where agricultural land dual-use preserves crop productivity.
Puglia
Superior irradiance profiles and available agricultural land attract utility-scale capital allocation under PNIEC auction mechanisms. Terna grid modernization investments reduce curtailment risk for generators in this southern deployment zone. The Brindisi-Taranto industrial cluster accommodates ground-mounted arrays above 50 MW capacity.
Sicily
High direct normal irradiance conditions suit concentrated solar power applications with molten salt storage configurations. Piano Paesaggistico Regionale heritage frameworks restrict visually prominent siting in Val di Noto protected zones. Catania-based engineering firms specialize in thermal cycle system commissioning.
Emilia-Romagna
Food processing supply chains negotiate direct power purchase agreements to hedge energy cost exposure. MASE permitting streamlining compresses authorization timelines for agrivoltaic deployments in the Po Delta. Parma and Modena industrial parks aggregate demand through energy community structures.
Veneto
Port and logistics facilities drive commercial segment procurement with flat-roof photovoltaic specifications. Regional authority zoning under Piano Paesaggistico Regionale constraints affects ground-mount feasibility in heritage-sensitive Verona and Vicenza territories. Treviso-based installers dominate residential rooftop deployment in the northeastern quadrant.
Italy Solar Energy Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Italy's solar value chain, creating a tiered competitive structure where integrated energy groups leverage balance sheet capacity against nimble regional developers. The market fragments across development-stage specialists, independent power producers with operational scale, and utility-affiliated renewable platforms. Three archetypes dominate: vertically integrated developers controlling pipeline-to-generation assets, regional specialists exploiting local permitting relationships, and corporate off-taker aggregators structuring energy communities. Competitive dynamics center on land access contracting and Terna grid connection queue positioning rather than manufacturing integration.
Among Italy-based renewable platforms, Enel Green Power SpA and ERG SpA exemplify the integrated developer archetype with multi-regional asset bases. Falck Renewables (Renantis) SpA occupies a specialized position within constrained land markets. These entities represent distinct strategic postures: national pipeline scale, southern concentration with operational advantages, and agrivoltaic-floating solar technical specialization respectively.
| Leading Market Players |
|---|
| Falck Renewables (Renantis) SpA |
| Peimar SRL |
| Enel Green Power SpA |
| Sorgenia SpA |
| Gruppo STG SRL |
| EF Solare Italia SpA |
| A2A Rinnovabili SpA |
| Plenitude (Eni Renewables) |
| ERG SpA |
| Others |
Value Chain & Pricing Dynamics
Utility-scale developers participating in PNIEC auction mechanisms operate through long-term power purchase agreements that fix revenue streams across project lifecycles, compressing procurement margins for EPC contractors while crystallizing module cost exposure at bid submission. This contract structure concentrates price negotiation leverage with tier-one module suppliers capable of delivering bankable supply commitments.
Pricing Analysis
Unbundled equipment procurement dominates utility-scale deployments where developers separately source modules, inverters, and balance-of-system components, while integrated EPC contracts prevail in commercial rooftop segments. Price differentiation rests on module efficiency tier and GSE incentive registration support services, with premium crystalline silicon configurations commanding margin premiums. Cost compression in standard mono modules is intensifying because Chinese ingot oversupply feeds through to European spot markets. Industrial offtakers in Lombardy exhibit highest price sensitivity due to thin manufacturing margins, while utility developers absorbing long-term offtake risk show lowest sensitivity to upfront capital costs.
Supply Chain Analysis
Container freight rates from Chinese manufacturing hubs to Italian ports directly impact landed module costs for developers without European warehousing arrangements. Module supply concentrates in China, Vietnam, and Malaysia, with polysilicon sourcing anchored in Xinjiang and Inner Mongolia. Italian developers draw from glass-glass bifacial configurations, aluminum racking systems, and string inverter assemblies. Single-source vulnerability around polysilicon ingot supply exposes project timelines to trade policy disruption. Distribution runs through Rotterdam and Hamburg port hubs into Milan-based logistics centers serving northern industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's solar market represents a late-cycle quality story where module specification premiums are widening as agricultural land constraints and heritage zoning elevate performance-per-watt requirements over pure cost minimization.
For Market Incumbents: Lock in agrivoltaic land access contracts across Emilia-Romagna and Lombardy before regional zoning frameworks tighten further. Prioritize backward integration into European module assembly to capture EU Net-Zero Industry Act domestic content bonuses in PNIEC auctions. Falck Renewables and ERG possess operational scale to execute this pivot while regional specialists face balance sheet constraints.
For New Entrants and Emerging Players: Capture floating solar development rights on Po Valley irrigation reservoirs where land-use conflicts are minimal and Terna grid connection queues remain manageable. Target commercial energy community aggregation in Veneto industrial parks where multi-tenant demand pooling reduces customer acquisition costs. Lead with technical agrivoltaic expertise rather than pure price competition to differentiate procurement pitches.
For Investors and Strategic Acquirers: Integrated European utilities are the most active acquirer in this space, seeking development-stage pipelines to meet PNIEC-mandated capacity additions. Long-term viability hinges on grid connection queue positioning and land lease duration rather than short-term merchant price exposure. Watch Terna transmission investment announcements in Puglia and Sicily as inflection signals for utility-scale project commercialization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Agrivoltaic Land Banking | Secures constrained real estate in Lombardy before Piano Paesaggistico Regionale restrictions tighten. |
| Bifacial Module Specification | Captures albedo yield premiums in Po Valley agricultural and high-reflectivity industrial installations. |
| Terna Grid Queue Positioning | Determines commercial operation sequencing for PNIEC-aligned auction winners in saturated nodal zones. |
| Energy Community Aggregation | Optimizes behind-the-meter economics for northern manufacturing clusters through GSE incentive structures. |
| Domestic Content Compliance | Unlocks EU Net-Zero Industry Act incentive bonuses for European-manufactured module procurement. |
Study Parameters
Direct dialogue with utility planning officers, IPP project developers, EPC contractors, and grid operators anchored qualitative assessment of deployment timelines and interconnection bottlenecks. Secondary validation drew from Terna grid development plans, GSE incentive administration data, MASE permitting statistics, and IEA renewable deployment trackers. Bottom-up project pipeline enumeration triangulated against top-down PNIEC capacity trajectory requirements to reconcile supply-side and demand-side market sizing.
Installed capacity and revenue estimates across the projection horizon reflect segmentation by application tier, technology configuration, and regional grid type. The analytical framework modeled residential, commercial, industrial, and utility-scale deployment trajectories against PNIEC auction schedules and net metering scheme evolution. CAGRs were derived from regression analysis of historical capacity additions correlated with irradiance-adjusted LCOE movements and regulatory incentive availability windows.
MASE authorization delays, EU trade policy shifts on Chinese module imports, and Terna transmission investment pacing are the dominant revision risks that could compress or extend deployment timelines. Stakeholders should weight assumptions against their own permitting relationships and grid connection queue positioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
India Residential Solar Inverter Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Bulgaria Solar Energy Market
Solar Power Systems
Global Airport Solar Power Market