
 Iran Solar Energy Market | 2026-2036
Iran Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Iran Solar Energy Market Foresight
Project finance through build-own-operate structures is reconfiguring competitive entry in Iranian solar deployment. Mapna Renewable Energy leverages its power sector heritage to anchor large-scale engineering contracts. JinkoSolar competes through module supply agreements that sustain cost advantages for EPC contractors. Kahkeshan Energy Khorshid differentiates by specializing in distributed installations for agricultural and industrial offtakers.
Iran solar energy encompasses photovoltaic and concentrated thermal systems that convert irradiance into electricity, with monocrystalline silicon modules achieving conversion efficiencies above 21 percent in desert conditions. These installations primarily displace fossil-fuel generation for grid-connected power and off-grid industrial loads. Photovoltaic Modules command the dominant share of hardware expenditure, though Batteries are gaining structural importance as developers address grid instability and curtailment risk. Utility-Scale applications concentrate margin pools through economies of scale, while Residential adoption remains constrained by financing access and net-metering implementation gaps.
SUNA governs licensing and tariff structures, while the Iran National Standards Organization (ISIRI) sets module performance and safety benchmarks that shape procurement specifications. The central bank's foreign exchange allocation policies directly determine import feasibility for inverters and tracking equipment. Stakeholders must monitor currency volatility and sanctions-related payment channel disruptions as determinants of project viability and supplier selection.
Market Dynamics
SUNA's feed-in tariff revisions are redirecting private capital toward utility-scale desert installations while currency volatility constrains equipment import feasibility.
Growth Catalysts
- Natural gas displacement pressure:Industrial facilities in Isfahan and Kerman provinces are scaling photovoltaic arrays to reduce fossil-fuel dependency for process heat and power.
- SUNA licensing streamlining:Accelerated permitting timelines for build-own-operate structures are unlocking project finance for independent power producers.
- Monocrystalline silicon efficiency gains:Module conversion rates above 21 percent in desert irradiance conditions are improving project returns for central region developers.
Market Restraints
- Foreign exchange allocation constraints:Central bank currency controls limit import feasibility for inverters and single-axis tracking equipment.
- Payment channel disruptions:Sanctions-related banking restrictions complicate supplier settlements and raise transaction costs for EPC contractors.
- Grid instability:Transmission infrastructure limitations in desert regions create curtailment risk that depresses capacity factor realizations.
Strategic Opportunities
- Agricultural distributed generation:Unmet demand for irrigation pumping and cold-chain electrification in rural Khorasan creates openings for small-scale developers.
- Battery storage pairing:Lithium-ion integration with solar parks is addressing evening peak demand and improving dispatch economics for off-takers.
- Industrial self-consumption:Net-metering implementation gaps present first-mover advantages for steel and cement producers seeking behind-the-meter solutions.
Industry Challenges
- PV system engineering expertise:Shortage of qualified technicians for desert climate installation and O&M constrains deployment velocity.
- ISIRI certification timelines:Module performance and safety benchmarking delays extend procurement cycles for imported hardware.
- Legacy gas plant integration:Grid code compliance for hybrid solar-gas facilities requires specialized control system retrofitting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iran Solar Energy Market |
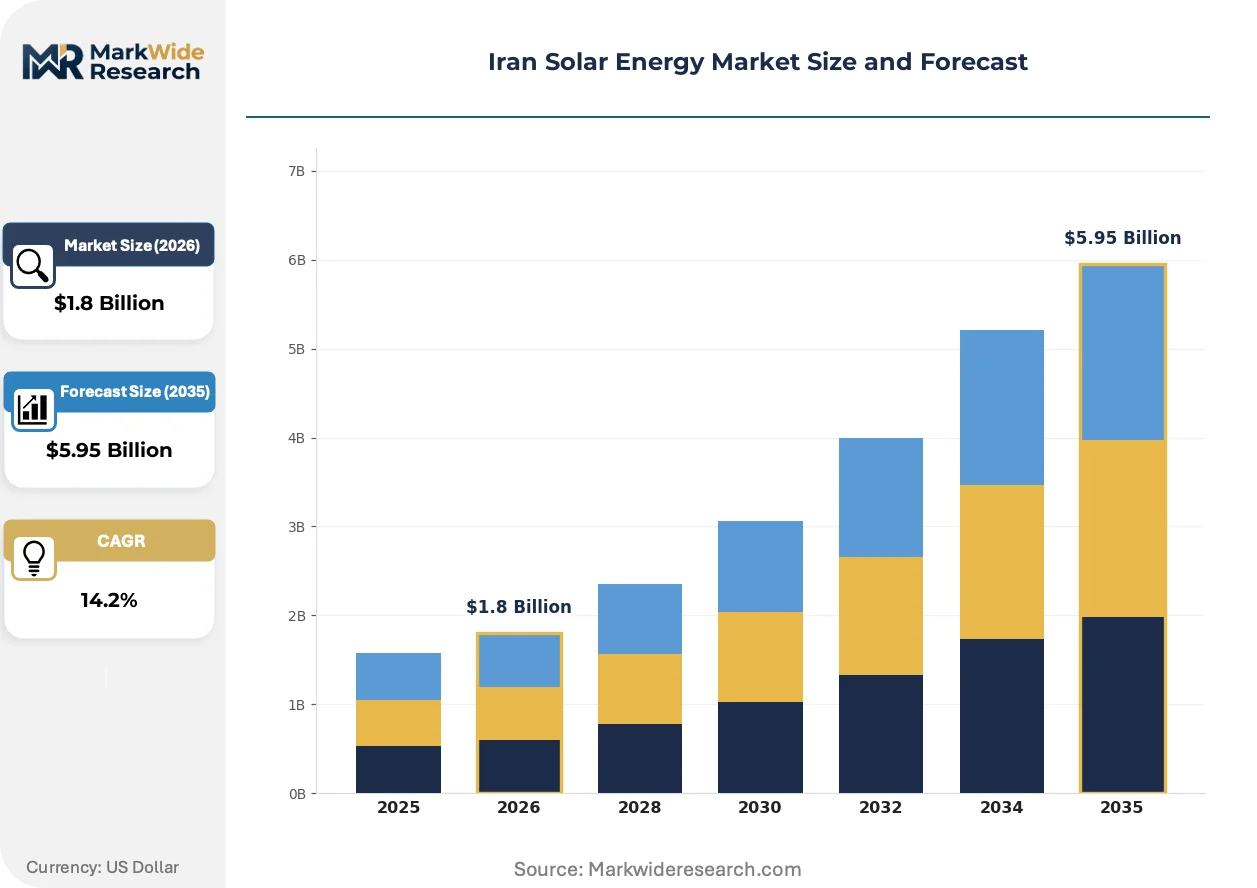
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Modules, Inverters, Mounting Systems, Batteries Application: Residential, Commercial, Industrial, Utility-Scale Technology: C-Si, Thin Film, Bifacial, Concentrated Solar Power End User: Governments, Private Sector, Institutions, Homeowners |
| Companies Covered | KPV Solar GmbH, Hanau Energies, Mapna Renewable Energy, Kahkeshan Energy Khorshid, Yekta Behineh Tavan, Ghadir Solar, Carlo Maresca SpA, Sunir Co., JinkoSolar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iran Solar Energy Market Shifts & Advancements
Digital twin modeling and bifacial module architectures are compressing LCOE trajectories while reshaping developer-engineer relationships.
Cloud-based performance monitoring is virtualizing traditional O&M contracts. EPC contractors are adopting predictive analytics platforms to manage dispersed desert portfolios. This shift is compressing response times for inverter faults and reducing truck-roll frequency across remote Yazd and Semnan installations.
SUNA's revised feed-in tariff structures are mandating domestic content thresholds for module assembly. Developers are responding by qualifying local manufacturing partners rather than relying on direct import channels. This policy is redirecting capital toward joint-venture production facilities in central industrial zones.
Industrial offtakers are unbundling engineering and procurement functions from traditional EPC wraps. Large cement and steel producers are hiring direct technical staff to specify equipment and manage contractor selection. This pattern is most visible in Isfahan province where energy-intensive manufacturers seek greater capital control over solar self-generation assets.
Iran Solar Energy Market Segmentation
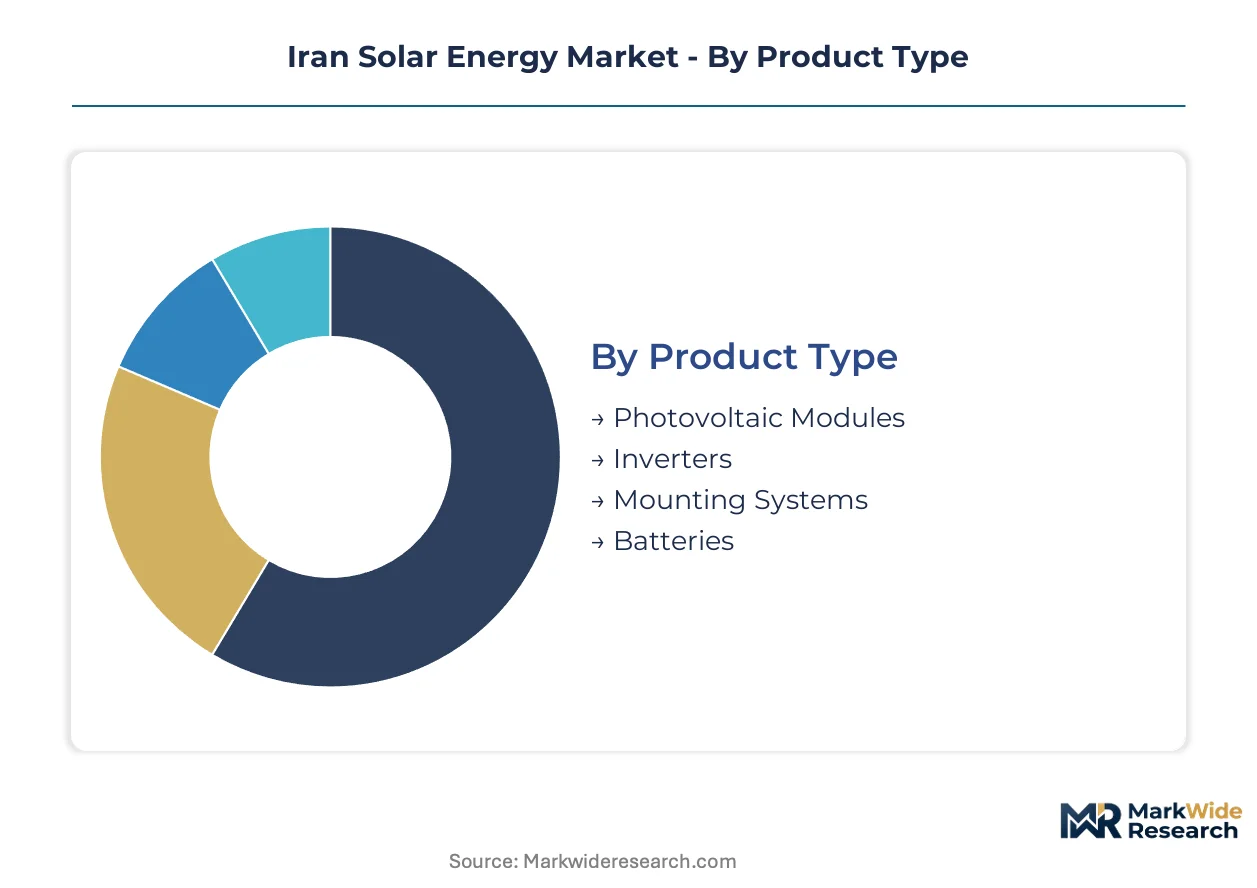
Segmentation reveals how capital flows and technical requirements diverge across the Iranian solar value chain. Equipment procurement cycles, offtake contract structures, and regulatory exposure vary substantially by product category and end-use application.
Product Type:
Photovoltaic Modules turn over fastest as efficiency improvements and tariff revisions trigger replacement demand, while Batteries exhibit the longest procurement cycles due to ISIRI certification requirements and foreign exchange allocation delays.
- Photovoltaic Modules:Monocrystalline silicon units achieving conversion efficiencies above 21 percent in desert irradiance conditions. Demand concentrates in utility-scale desert parks across Yazd and Kerman provinces where SUNA feed-in tariffs anchor project finance. Procurement accelerates when central bank currency windows open for import settlements.
- Inverters:Power electronics converting DC module output to grid-synchronous AC power. String inverters dominate distributed commercial installations in Isfahan industrial zones while central inverters anchor utility-scale configurations. Currency volatility constrains supplier selection more severely than any other hardware category.
- Mounting Systems:Fixed-tilt and single-axis tracking structures positioning modules for optimal irradiance capture. Single-axis systems gain traction in desert regions with high direct normal irradiance.
- Batteries:Lithium-ion storage systems addressing evening peak demand and grid instability. Procurement cycles extend due to ISIRI safety certification timelines and foreign exchange allocation bottlenecks.
Photovoltaic Modules anchor the volume base while Batteries gain share at the steepest rate.
Application:
Capital intensity and contract duration separate the application tiers, with Utility-Scale deployments requiring 20-year power purchase agreements and Residential installations facing financing access gaps.
- Residential:Rooftop systems serving individual homeowners with net-metering arrangements. Deployment concentrates in Tehran and Shiraz suburbs where middle-income households access microfinance channels.
- Commercial:Medium-scale installations for retail, hospitality, and office buildings. Demand clusters in urban centers seeking demand charge reduction.
- Industrial:Behind-the-meter systems for cement, steel, and manufacturing facilities. Isfahan and Kerman provinces lead as energy-intensive producers offset natural gas dependency for process heat and power.
- Utility-Scale:Grid-connected solar parks exceeding 10 MW capacity. Central desert regions capture developer attention through SUNA licensing streamlining and build-own-operate project finance structures.
Utility-Scale installations anchor the volume base while Industrial self-consumption gains share at the steepest rate.
Technology:
Technology selection tracks irradiance conditions and capital availability, with Bifacial modules commanding premium positioning in high-albedo desert environments.
- C-Si:Crystalline silicon technology dominating module supply through established manufacturing scale. Monocrystalline variants achieve superior performance in Iranian desert conditions.
- Thin Film:Cadmium telluride and amorphous silicon alternatives suited to high-temperature environments. Niche deployment in distributed agricultural pumping applications.
- Bifacial:Dual-sided modules capturing reflected irradiance from desert ground surfaces. Yazd and Semnan developers prioritize this architecture for capacity factor improvement.
- Concentrated Solar Power:Thermal systems using mirrors to concentrate irradiance for steam generation. Limited deployment due to water scarcity constraints and higher capital intensity.
C-Si technology anchors the volume base while Bifacial architectures gain share at the steepest rate.
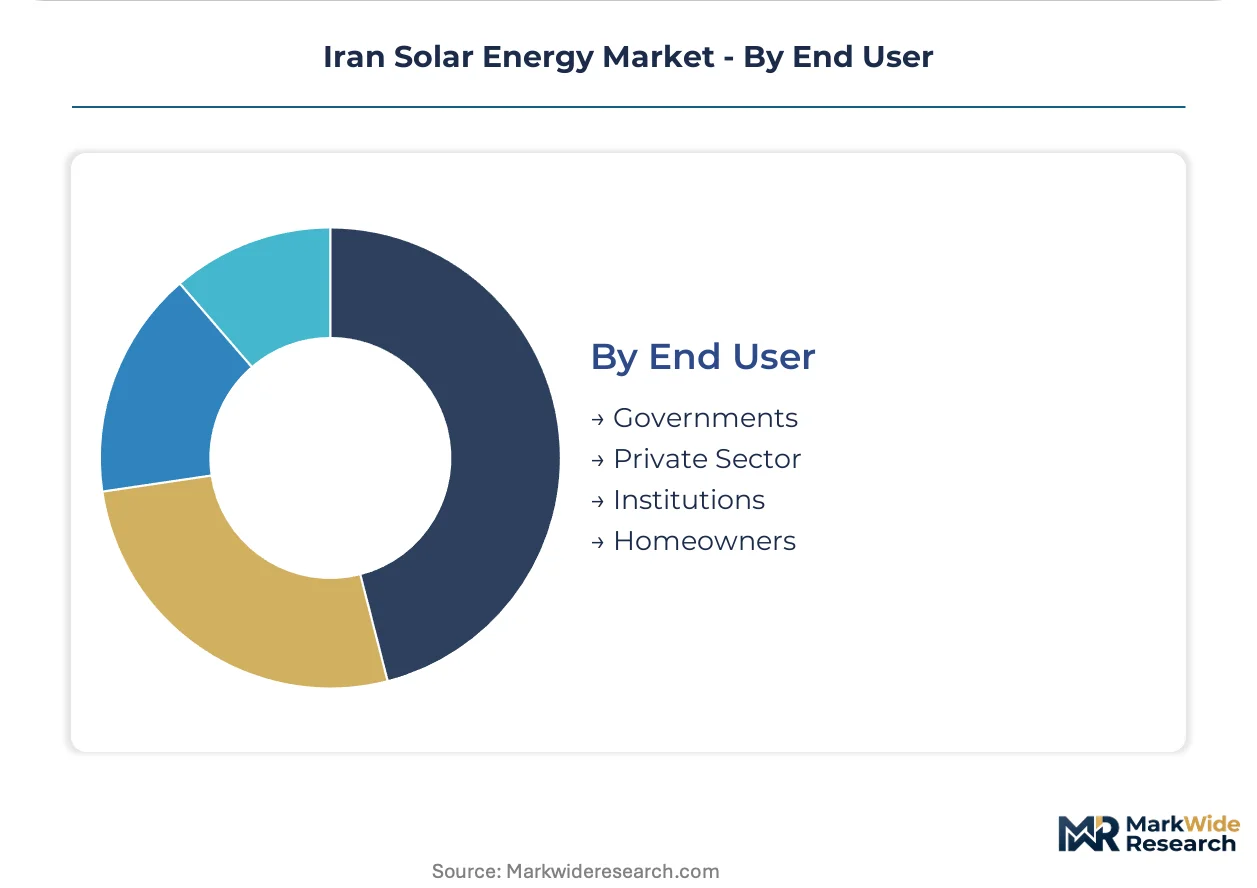
End User:
Contracting sophistication and risk tolerance distinguish end user categories, with Private Sector offtakers driving procurement innovation.
- Governments:Public sector procurement through SUNA tender mechanisms. Provincial development priorities shape geographic allocation.
- Private Sector:Corporate offtakers including cement, steel, and mining groups. Isfahan industrial clusters lead self-generation investment.
- Institutions:Universities, hospitals, and municipal facilities with stable load profiles. Tehran academic medical centers pilot solar-plus-storage configurations.
- Homeowners:Individual residential adopters facing financing access constraints. Net-metering implementation gaps limit deployment velocity outside major urban centers.
Private Sector offtakers anchor the volume base while Institutions gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SUNA's feed-in tariff revisions and build-own-operate licensing frameworks are concentrating solar investment in Iran's central desert belt, where irradiance levels and land availability align with utility-scale economics.
Isfahan Province
Energy-intensive cement and steel producers are deploying behind-the-meter photovoltaic arrays to offset natural gas dependency for process heat. The Renewable Energy Organization of Iran streamlines permitting for industrial self-consumption projects above 5 MW capacity. The Isfahan Steel Complex and surrounding industrial clusters anchor the province's distributed generation pipeline.
Kerman Province
Mining operations and copper smelters are scaling solar installations to secure power supply amid gas allocation constraints. SUNA licensing for build-own-operate structures unlocks project finance for independent power producers serving extractive industry offtakers. The Sarcheshmeh Copper Complex and Rafsanjan agricultural belt concentrate developer activity.
Yazd Province
High direct normal irradiance conditions attract utility-scale developers seeking optimal capacity factors for grid-connected solar parks. The central bank's foreign exchange allocation windows determine import feasibility for single-axis tracking equipment. Desert installations around Ardakan and Meybod capture the bulk of provincial financing flows.
Tehran and Alborz Provinces
Residential rooftop deployment concentrates in middle-income suburbs where microfinance channels enable system acquisition. Net-metering implementation gaps limit velocity outside the capital corridor. Academic medical centers and municipal facilities in Tehran pilot solar-plus-storage configurations for demand charge management.
Iran Solar Energy Market Competitive Landscape
On the supply side, the industry is bifurcated between international module suppliers and domestic engineering specialists navigating currency volatility and sanctions-related payment friction. The competitive terrain separates three strategic archetypes: state-affiliated power sector incumbents leveraging legacy infrastructure relationships, Chinese module manufacturers sustaining cost advantages through supply agreements, and local distributed generation specialists targeting agricultural and industrial offtakers. Capacity expansion through joint-venture production facilities and strategic partnerships with qualified local manufacturers dominate competitive maneuvering.
Among Iranian-based power sector entities, Mapna Renewable Energy anchors large-scale engineering contracts through its heritage in thermal generation infrastructure. Kahkeshan Energy Khorshid occupies a position within the distributed installation tier, specializing in agricultural and industrial behind-the-meter projects. JinkoSolar represents the international module supply archetype, competing through procurement agreements that sustain cost advantages for domestic EPC contractors.
| Leading Market Players |
|---|
| KPV Solar GmbH |
| Hanau Energies |
| Mapna Renewable Energy |
| Kahkeshan Energy Khorshid |
| Yekta Behineh Tavan |
| Ghadir Solar |
| Carlo Maresca SpA |
| Sunir Co. |
| JinkoSolar |
| Others |
Supply & Pricing Matrix
Chinese module manufacturing concentration anchors hardware procurement economics, with JinkoSolar supply agreements determining margin distribution between EPC contractors and project developers across Iranian desert installations.
Pricing Analysis
ISIRI certification tier creates the primary spread between import-qualified and domestically assembled modules, with premium pricing attaching to UL-verified string inverters and economy tiers capturing fixed-tilt mounting systems without tracking capability. Cost compression in battery storage is intensifying because foreign exchange allocation bottlenecks extend lithium-ion procurement cycles. Industrial offtakers in Isfahan and Kerman exhibit lowest price sensitivity due to natural gas displacement urgency, while residential adopters in Tehran suburbs face financing access constraints that amplify sensitivity to upfront system costs.
Supply Chain Analysis
Extended payment terms from Chinese module suppliers are restructuring working capital requirements for domestic EPC contractors navigating sanctions-related settlement friction. Hardware procurement draws from China for monocrystalline cells, South Korea for power electronics, and domestic assembly partners for module qualification under SUNA domestic content thresholds. Single-source vulnerability concentrates in inverter supply where central bank currency windows determine import feasibility. Distribution runs through Mapna Renewable Energy engineering contracts and Kahkeshan Energy Khorshid distributed installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iran solar energy represents an early-cycle expansion story where SUNA feed-in tariff revisions are accelerating private capital deployment ahead of grid infrastructure maturation.
For Market Incumbents: Build regulatory relationship moats through accelerated ISIRI certification investment for joint-venture module assembly facilities. Deepen backward integration into domestic cell manufacturing to offset currency volatility exposure for hardware imports. Counter emerging Chinese supplier direct-contracting threats by anchoring build-own-operate project finance structures.
For New Entrants and Emerging Players: Rural Khorasan agricultural electrification presents the most penetrable white-space for distributed generation specialists targeting irrigation pumping and cold-chain offtakers. Battery-solar pairing for evening peak demand captures unmet utility-scale storage demand. Partner with provincial agricultural cooperatives for land access and anchor tenant acquisition.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated EPC-platforms with established SUNA licensing relationships and qualified local manufacturing partnerships. Long-term viability hinges on currency risk hedging capability and grid code compliance expertise for hybrid solar-gas facilities. Monitor central bank foreign exchange allocation policy shifts as inflection indicators for import-dependent hardware exposure.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Content Qualification | Joint-venture module assembly secures SUNA tariff eligibility for Yazd and Kerman developers. |
| Build-Own-Operate Licensing | Project finance structures unlock independent power producer entry in central desert regions. |
| Battery Storage Integration | Lithium-ion pairing addresses grid instability and evening peak dispatch economics. |
| Industrial Self-Consumption | Behind-the-meter installations capture Isfahan steel and cement producer demand. |
| Single-Axis Tracking Deployment | High direct normal irradiance optimization improves capacity factors for Semnan utility parks. |
Research Methodology
The analysis maps photovoltaic module supply chains, battery storage procurement cycles, and EPC contractor economics, each validated through IPP project developers, EPC technical directors, and SUNA licensing officers. Primary interviews with industrial offtakers in Isfahan and Kerman provinces combined with secondary validation from IEA renewable energy databases, EIA country analysis briefs, and central bank foreign exchange policy disclosures. Bottom-up project pipeline aggregation triangulates against top-down macroeconomic assumptions.
Assumptions held fixed include SUNA feed-in tariff structures and domestic content thresholds, while currency volatility and sanctions-related payment channel disruption were modeled as scenario variables across the projection horizon. Segmentation dimensions include product type, application tier, technology architecture, and end-user category. CAGRs derive from installed capacity buildout trajectories, module efficiency improvement curves, and industrial electricity demand elasticity.
Practitioners should monitor central bank foreign exchange allocation windows and ISIRI certification timeline shifts for early signals of hardware import feasibility. Forecasts reflect assumptions of sustained SUNA licensing streamlining and grid infrastructure investment pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Mirror Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Solar Panel Glass Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market