
 United Arab Emirates Solar Photovoltaic (PV) Market | 2026-2036
United Arab Emirates Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Solar Photovoltaic (PV) Market Analytics
ESMA certification for solar module performance and safety is unwinding the competitive field, raising barriers for uncertified suppliers. JinkoSolar leverages its vertically integrated cell-to-module production to sustain cost competitiveness in UAE tenders. Masdar anchors domestic project development through its equity stakes in multiple gigawatt-scale plants. ACWA Power competes aggressively on levelized cost of energy bids across the Gulf Cooperation Council region.
Solar photovoltaic systems convert sunlight into direct-current electricity through semiconductor p-n junctions, with monocrystalline silicon cells achieving conversion efficiencies above 22% in commercial modules. These systems serve utility-scale power generation, commercial rooftop self-consumption, and residential net-metering applications across the Emirates. Bifacial technology captures reflected light from desert surfaces, boosting yield in ground-mounted installations across the UAE's arid interior. Utility-scale application dominates procurement volumes, while commercial segment growth accelerates as businesses seek electricity cost hedges against volatile fossil fuel pricing.
MOHAP building codes and ESMA product standards govern module importation, installation safety, and grid interconnection protocols across the seven emirates. The country's dual carbon goals and net-zero by 2050 strategic initiative shape long-term procurement mandates for government-backed developers. EDF Renewables and TotalEnergies Renewables navigate these regulatory requirements through joint ventures with local sponsors. Stakeholders must monitor evolving local content requirements and Emiratization targets that could reshape supplier qualification criteria and project ownership structures.
Market Dynamics
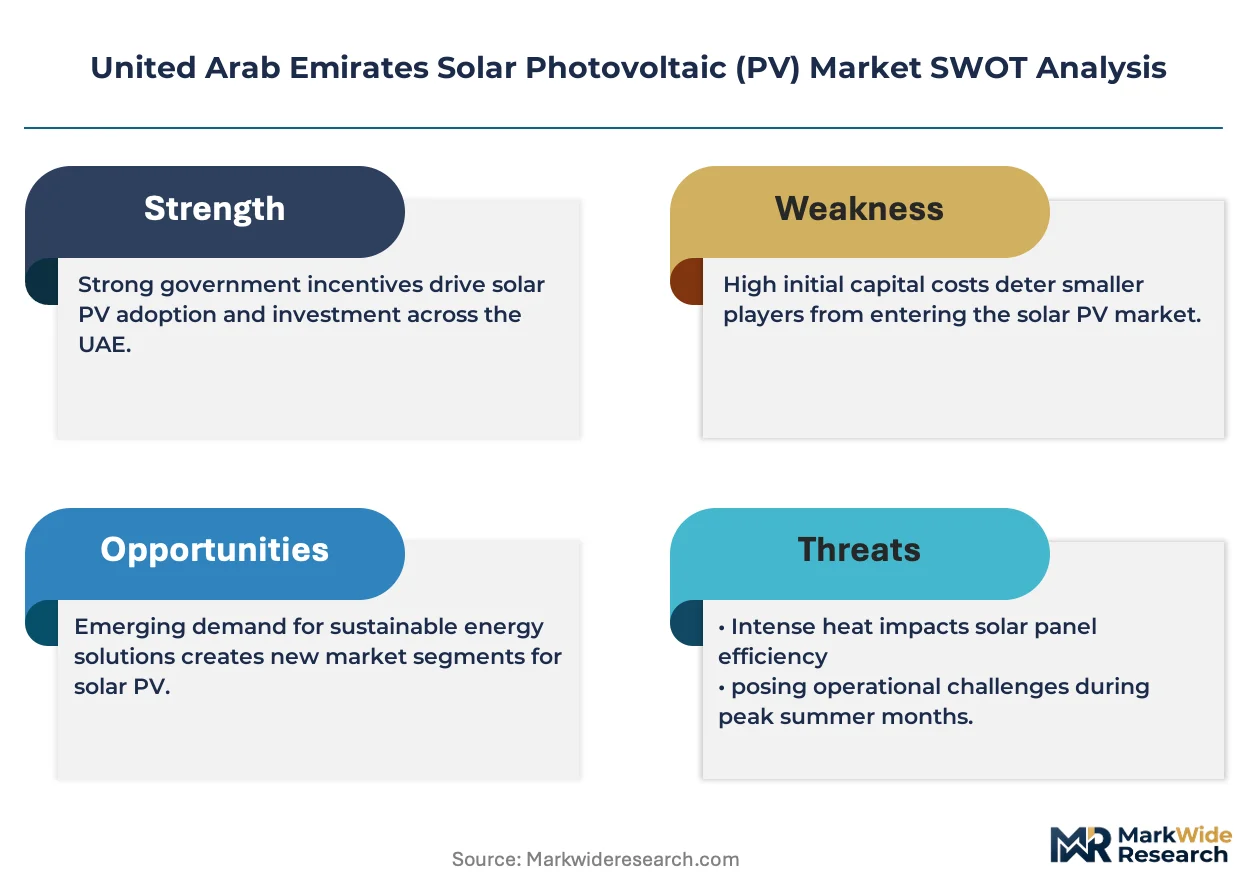
Utility-scale procurement concentration in Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park is compressing supplier margins while ESMA efficiency mandates filter out substandard module imports.
Growth Catalysts
- Net-zero 2050 mandate:Federal clean energy targets require 14 gigawatts of solar capacity by 2030, locking in decade-long procurement visibility for developers and equipment suppliers.
- Al Dhafra region:Gigawatt-scale solar park clustering creates demand density that attracts tier-one module manufacturers to establish local logistics hubs and technical service presence.
- Bifacial yield gains:Desert albedo conditions in Abu Dhabi's interior boost bifacial module output by 8-12% over monofacial equivalents, improving project returns without incremental land requirements.
Market Restraints
- Polysilicon price volatility:Raw material input costs for crystalline silicon cells fluctuate with Chinese production curbs and electricity pricing in Xinjiang manufacturing zones.
- Grid interconnection queues:Emirates Water and Electricity Company transmission upgrade timelines lag behind solar park commissioning schedules, delaying revenue recognition.
- Land use competition:Coastal urbanization pressure in Dubai and Abu Dhabi constrains greenfield solar development, pushing projects toward remote interior locations with higher transmission costs.
Strategic Opportunities
- Ras Al Khaimah and Fujairah:Northern emirates with underdeveloped renewable infrastructure offer first-mover advantages for distributed commercial and industrial rooftop installations.
- Green hydrogen offtake:Electrolyzer projects at Al Reyadah and TA'ZIZ industrial zone create anchor demand for behind-the-meter solar generation with 24/7 supply requirements.
- Building-integrated photovoltaics:MOHAP energy efficiency codes for new construction mandate solar-ready roofing, opening architectural glass and facade-integrated module applications.
Industry Challenges
- ESMA certification timelines:Module efficiency testing and safety verification procedures create 4-6 month product qualification delays that mismatch tender award cycles.
- Emiratization workforce targets:Project ownership structures must demonstrate technical and managerial roles filled by UAE nationals, constraining expatriate engineering deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Solar Photovoltaic (PV) Market |
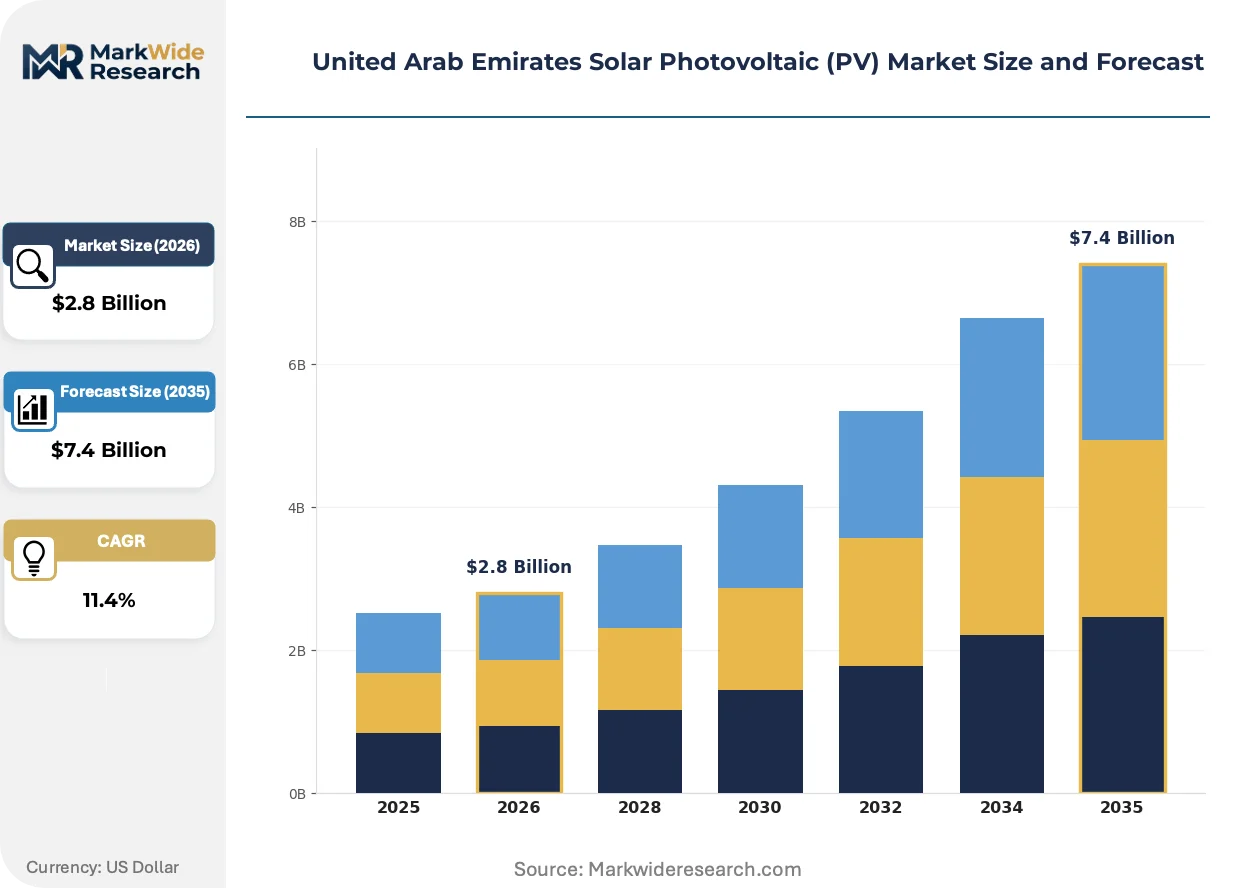
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Utility-Scale End User: Government, Developers, Businesses, Homeowners Installation Type: Roof-mounted, Ground-mounted, Building-integrated, Off-grid |
| Companies Covered | Abu Dhabi National Energy, JinkoSolar, Masdar (Abu Dhabi Future Energy Company), TotalEnergies Renewables, Engie, EDF Renewables, Marubeni, SirajPower, ACWA Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Solar Photovoltaic (PV) Market Evolving Landscape
Module efficiency thresholds and grid integration requirements are compressing technology refresh cycles while reshaping supplier qualification criteria across emirate-level procurement.
TOPCon cell architecture is miniaturizing passivated contact structures to sub-micron thicknesses, enabling 24%+ conversion efficiencies in commercial modules. Dubai Electricity and Water Authority tenders now specify n-type cell requirements, displacing legacy p-type PERC designs from premium tier eligibility. This efficiency compression is reducing balance-of-system costs per watt while tightening supplier qualification to vertically integrated manufacturers with in-house cell capacity.
MOHAP building codes now mandate solar-ready structural loadings and electrical rough-ins for all new commercial construction above 2,000 square meters. The regulation forces architectural firms to integrate photovoltaic specifications into design-phase documentation rather than retrofitting post-construction. Contractors in Dubai's Design District and Abu Dhabi's Masdar City are responding by embedding electrical engineering teams within project planning departments.
Commercial offtakers are consolidating procurement through multi-site power purchase agreements rather than individual rooftop leases. Property developers with portfolios across Dubai Industrial City and Khalifa Industrial Zone are aggregating demand to negotiate volume-based tariffs with independent power producers. This buyer concentration is visible most acutely in the logistics and cold storage vertical, where electricity constitutes 15-20% of operating costs and price hedging priorities dominate vendor selection.
United Arab Emirates Solar Photovoltaic (PV) Market Segmentation
Technology and application boundaries in the UAE solar PV market are blurring as efficiency mandates and project scale requirements reshape procurement patterns. Understanding segment substitution pressures helps stakeholders anticipate where capital will migrate next.
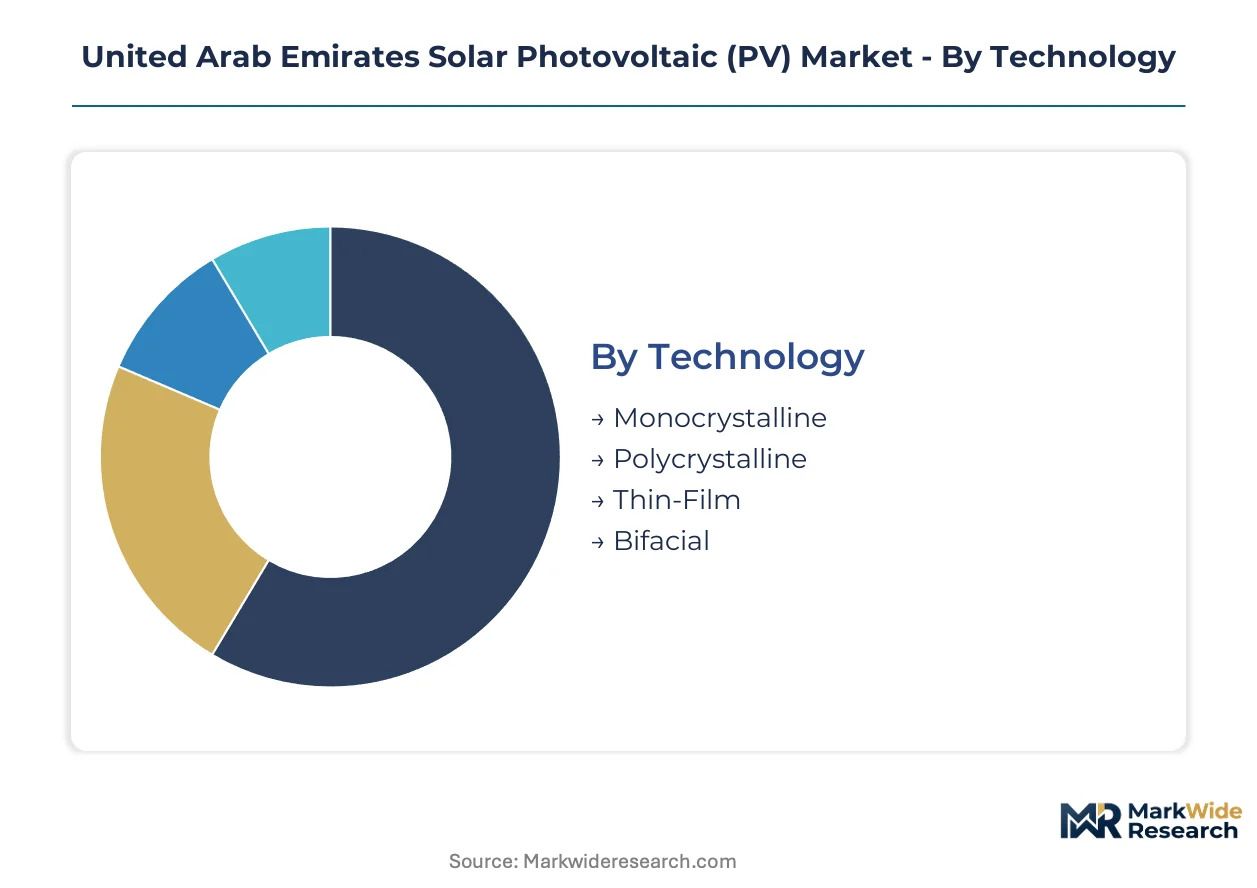
Technology:
Monocrystalline and bifacial formats face accelerating substitution pressure from n-type TOPCon architectures that ESMA efficiency thresholds increasingly favor.
- Monocrystalline:P-type PERC cells with 21-22% commercial efficiency dominate current installed base across Al Dhafra solar parks. Dubai Electricity and Water Authority tenders now specify n-type requirements, compressing legacy monocrystalline margins and forcing module suppliers to accelerate cell architecture transitions.
- Bifacial:Dual-glass constructions capture reflected irradiance from desert surfaces, delivering 8-12% yield uplift over monofacial equivalents without incremental land use. Ground-mounted installations in Abu Dhabi's interior increasingly specify bifacial modules as baseline requirement.
- Polycrystalline:Multi-crystalline silicon cells with 17-19% efficiency face elimination from utility-scale procurement as ESMA certification tightens minimum performance thresholds.
- Thin-Film:Cadmium telluride and CIGS technologies retain niche presence in building-integrated applications where weight constraints and partial shading tolerance matter.
Monocrystalline anchors the volume base while bifacial gains share at the steepest rate.
Application:
Cost tier differentiation separates utility-scale procurement with its gigawatt-scale aggregation from distributed segments where customer acquisition expenses dominate economics.
- Utility-Scale:Ground-mounted solar parks above 50 megawatts deliver lowest levelized cost of energy through standardized designs and bulk procurement. Mohammed bin Rashid Al Maktoum Solar Park and Al Dhafra projects concentrate national capacity targets and attract tier-one module manufacturers to establish local logistics presence.
- Commercial:Rooftop and carport installations serving 500 kilowatt to 5 megawatt loads are expanding most quickly as businesses seek electricity cost hedges against volatile fossil fuel pricing. Dubai Industrial City and Khalifa Industrial Zone aggregations are consolidating multi-site power purchase agreements.
- Industrial:Behind-the-meter generation for manufacturing and processing facilities faces interconnection queue delays at Emirates Water and Electricity Company that slow revenue recognition timelines.
- Residential:Net-metering systems below 10 kilowatts remain underpenetrated due to financing friction and awareness gaps among UAE homeowners.
Utility-scale commands procurement volumes while commercial applications climb the fastest as corporate offtakers consolidate demand.
End User:
Customer type concentration around government-backed developers creates procurement visibility that private sector participants struggle to match.
- Developers:Independent power producers and project sponsors like Masdar and ACWA Power anchor gigawatt-scale tender participation with long-term power purchase agreement structures.
- Government:Federal and emirate-level entities mandate clean energy procurement through net-zero strategic initiatives, locking in decade-long equipment demand visibility.
- Businesses:Commercial and industrial offtakers are aggregating multi-site demand to negotiate volume-based tariffs with independent power producers.
- Homeowners:Individual residential adopters face financing barriers and awareness gaps that constrain distributed generation penetration.
Government and developer segments anchor procurement scale while business offtakers are diversifying fastest across emirate-level markets.
Installation Type:
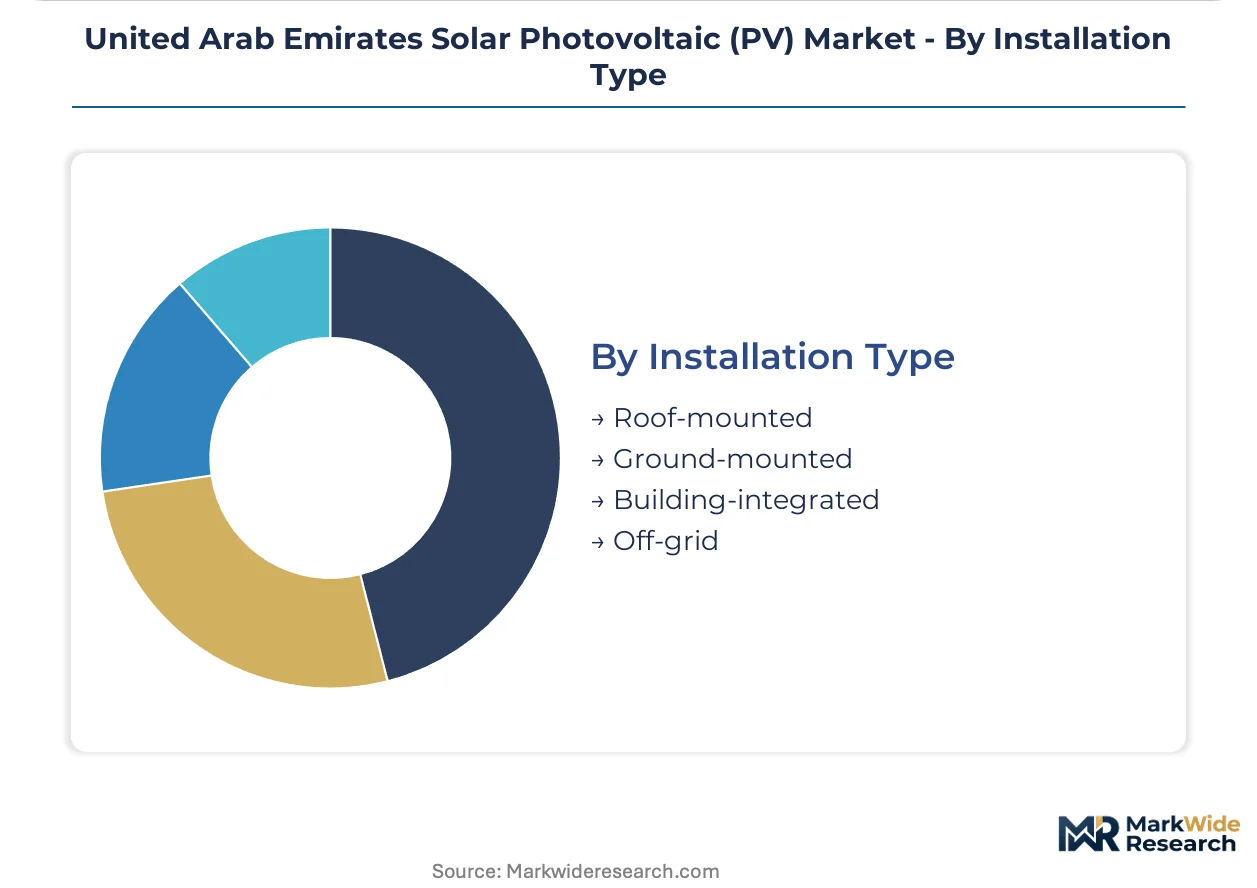
Geography and land availability constraints are pushing development toward remote interior ground-mounted configurations despite higher transmission infrastructure requirements.
- Ground-mounted:Fixed-tilt and tracking systems in desert interior locations dominate utility-scale capacity additions, with bifacial configurations optimizing albedo capture.
- Roof-mounted:Commercial and industrial rooftop installations face land use competition from coastal urbanization in Dubai and Abu Dhabi.
- Building-integrated:Photovoltaic glass and facade-integrated modules are gaining traction as MOHAP energy efficiency codes mandate solar-ready structural loadings for new construction above 2,000 square meters.
- Off-grid:Remote industrial and rural applications serve mining and agricultural loads outside Emirates Water and Electricity Company network coverage.
Ground-mounted configurations anchor capacity deployment while building-integrated applications are expanding most quickly through regulatory mandate penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal clean energy procurement mandates and emirate-level renewable targets are redistributing solar development across the UAE's seven emirates, with policy incentives concentrating capacity in designated solar parks while regulatory mandates push distributed generation into underpenetrated northern territories.
Abu Dhabi
Al Dhafra region hosts the world's largest single-site solar park, with gigawatt-scale procurement attracting tier-one module manufacturers to establish local logistics hubs. Emirates Authority for Standardization and Metrology certification requirements filter supplier participation, while Masdar anchors domestic project development through equity stakes in multiple plants. The industrial zone around Ruwais is emerging as a center for green hydrogen offtake agreements that require 24/7 solar supply.
Dubai
Mohammed bin Rashid Al Maktoum Solar Park drives utility-scale capacity additions with phased expansion targeting multi-gigawatt output. Dubai Electricity and Water Authority tenders now specify n-type cell requirements, displacing legacy designs from premium eligibility. Dubai Industrial City aggregations are consolidating multi-site power purchase agreements for commercial and industrial rooftops.
Sharjah
The emirate's renewable energy target of 30% clean power by 2030 is accelerating utility-scale procurement outside the Dubai-Abu Dhabi axis. Sharjah Electricity and Water Authority interconnection standards are being harmonized with federal grid codes to reduce project development friction. The Hamriyah Free Zone is attracting independent power producers seeking alternative development sites with lower land costs than coastal Dubai.
Northern Emirates
Ras Al Khaimah and Fujairah present first-mover opportunities for distributed commercial and industrial installations with underdeveloped renewable infrastructure. MOHAP building code enforcement varies across these emirates, creating regulatory arbitrage for developers familiar with federal standards. Fujairah's east coast location offers distinct solar irradiance profiles and reduced dust deposition compared to interior desert sites.
Al Ain and Interior Regions
Eastern Abu Dhabi emirate territories provide land availability for ground-mounted installations with superior solar resource quality. Emirates Water and Electricity Company transmission upgrade timelines lag behind development interest, creating interconnection queue delays. Agricultural and industrial loads outside main grid networks are driving off-grid solar-plus-storage applications for water pumping and processing facilities.
United Arab Emirates Solar Photovoltaic (PV) Market Competitive Landscape
Player mix skews toward government-backed developers and international independent power producers with established Gulf Cooperation Council track records. Market structure concentrates around entities capable of securing long-term power purchase agreements and navigating ESMA certification requirements. Three archetypes dominate: vertically integrated module suppliers with in-house cell capacity, project developers with sovereign wealth fund backing, and European-Japanese consortia bidding through joint ventures with local sponsors. Competitive dynamics center on levelized cost of energy positioning and strategic partnerships that satisfy Emiratization workforce targets.
Among government-backed developers, Masdar and Abu Dhabi National Energy exemplify the sovereign-anchored archetype that dominates gigawatt-scale tender participation. ACWA Power represents the independent power producer model competing aggressively on cost bids across the region. JinkoSolar occupies a position as the vertically integrated module supplier sustaining cost competitiveness through captive cell-to-module production.
| Leading Market Players |
|---|
| Abu Dhabi National Energy |
| JinkoSolar |
| Masdar (Abu Dhabi Future Energy Company) |
| TotalEnergies Renewables |
| Engie |
| EDF Renewables |
| Marubeni |
| SirajPower |
| ACWA Power |
| Others |
Value Network & Pricing Analysis
Ninety-day ESMA certification queues compress tender participation windows while concentrating pricing power among pre-certified module suppliers with established UAE logistics presence. This lead-time bottleneck feeds directly into procurement economics: developers facing fixed commissioning deadlines pay premium markups for certified inventory, while uncertified competitors absorb carrying costs or exit tender rounds entirely.
Pricing Analysis
Certification tier creates the primary spread across UAE solar module procurement, with ESMA-validated n-type TOPCon products commanding distinct premiums over legacy p-type PERC alternatives. Project-based long-term offtake contracts dominate utility-scale transactions, locking in price visibility across multi-year power purchase agreement structures. Price differentiation rests on cell efficiency thresholds and bifacial yield guarantees, with commercial rooftop aggregators showing highest price sensitivity due to fragmented demand consolidation. Margins are tightening among p-type specialists as Dubai Electricity and Water Authority tenders progressively exclude sub-22% efficiency designs from eligibility.
Supply Chain Analysis
Strait of Hormuz transit underwrites polysilicon feedstock security for UAE solar manufacturing, with Chinese ingot and wafer capacity anchoring upstream supply. Module assembly draws from Vietnam, Malaysia, and domestic Jebel Ali free zone facilities to satisfy local content preferences. Raw material dependencies center on metallurgical-grade silicon, silver paste metallization, and ethylene-vinyl acetate encapsulant films. Single-source vulnerability concentrates in Xinjiang polysilicon purification, where electricity pricing and production curbs transmit volatility downstream. Distribution runs through Emirates Water and Electricity Company tender platforms and direct EPC contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-site power purchase agreement aggregation, with logistics and cold storage verticals consolidating procurement across Dubai Industrial City and Khalifa Industrial Zone portfolios. This consolidation shifts negotiation leverage toward volume-committed offtakers and away from fragmented individual rooftop lessors.
For Market Incumbents: Secure captive cell-to-module capacity to sustain cost competitiveness as ESMA efficiency mandates accelerate technology refresh cycles. Anchor position through backward integration into polysilicon sourcing or forward integration into O&M service contracts. Defensive priority centers on pre-qualifying next-generation n-type architectures ahead of tender specification shifts. For New Entrants and Emerging Players: ESMA fast-track certification partnerships with established testing laboratories accelerate market entry timelines for tier-two manufacturers seeking UAE eligibility. Target Ras Al Khaimah and Fujairah distributed commercial segments where first-mover advantages persist and utility-scale procurement concentration is weakest. Go-to-market angle emphasizes building-integrated photovoltaic solutions under MOHAP solar-ready mandates for new construction above 2,000 square meters. For Investors and Strategic Acquirers: Long-term, this sits as a sovereign-anchored infrastructure play because federal net-zero 2050 mandates lock in decade-plus procurement visibility independent of merchant power price cycles. Acquisition archetype favors project developers with secured land banks and Emirates Water and Electricity Company interconnection agreements. Signal to watch is green hydrogen offtake contract velocity at Al Reyadah and TA'ZIZ industrial zones, which would inflect behind-the-meter solar demand.| Strategic Initiative | Industry Significance |
|---|---|
| ESMA Certification Pre-Qualification | Accelerates tender eligibility for n-type TOPCon module suppliers ahead of efficiency mandate tightening. |
| Multi-Site PPA Aggregation | Consolidates commercial offtaker demand across Dubai Industrial City and Khalifa Industrial Zone portfolios. |
| Green Hydrogen Offtake Partnership | Secures 24/7 solar supply contracts for electrolyzer projects at Al Reyadah and TA'ZIZ industrial zones. |
| Bifacial Yield Guarantee Structuring | Captures 8-12% albedo uplift premiums in Abu Dhabi interior ground-mounted installations. |
| Local Logistics Hub Establishment | Reduces lead times for tier-one manufacturers serving Al Dhafra and Mohammed bin Rashid Al Maktoum Solar Park clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers at Emirates Water and Electricity Company, independent power producer project developers, EPC contractors, and grid interconnection specialists. Secondary validation drew from IEA renewable energy deployment databases, IRENA project tracking registers, ESMA certification filings, and customs import records for solar module classifications. Bottom-up installation capacity tallies were triangulated against top-down federal clean energy target allocations.
Across the analysis window, the forecasting framework modeled capacity additions by technology architecture, application scale tier, and emirate-level regulatory jurisdiction. CAGRs were derived from regression-based trend extrapolation moderated by policy milestone constraints and grid interconnection queue backlogs. Key inputs included Emirates Water and Electricity Company transmission upgrade timelines, Masdar and ACWA Power project pipeline disclosures, and MOHAP building code enforcement schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained federal net-zero commitment and stable Chinese polysilicon supply; material deviation would warrant model refresh. Specific risks that could revise trajectories include Emirates Water and Electricity Company interconnection delays, ESMA certification timeline extensions, or Xinjiang production curbs transmitting upstream cost shocks. Revision becomes warranted when green hydrogen offtake contract velocity crosses threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
Solar Ribbon Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Egypt Solar Photovoltaic (PV) Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Solar Thermal Collector Market