
 Non-Concentrating Solar Collector Market | 2026-2036
Non-Concentrating Solar Collector Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Concentrating Solar Collector Market Outlook
Project developer channels across Southern Europe are fragmenting as regional installers bypass traditional distributors and source collectors directly from manufacturers. Greenonetec leverages its Austrian production base to sustain premium positioning in Alpine district heating networks. Viessmann Group anchors Central European demand through captive boiler-collector bundling programs. Bosch Thermotechnik competes on module interoperability with its existing heat pump installed base.
Non-concentrating solar collectors harvest diffuse solar radiation through stationary absorber surfaces, typically employing selectively coated copper or aluminum fins bonded to fluid-filled tubes with insulation backing and tempered glass glazing, achieving stagnation temperatures below 200°C for low-temperature thermal applications. Evacuated tube designs dominate cold-climate installations where reduced heat loss offsets higher first costs, while flat plate configurations occupy cost-sensitive residential water heating segments in temperate zones. Government procurement for municipal pool heating and district warmup loops represents an emerging margin pool as public decarbonization mandates harden.
The EU Green Deal and F-Gas Regulation shape product standards by mandating minimum thermal performance coefficients and restricting high-GWP insulation foams, while China's GB standards and dual carbon goals enforce domestic manufacturing efficiency benchmarks that ripple through export supply chains. Stakeholders must monitor whether building-integrated installation codes in Germany and retrofit subsidy thresholds in France shift procurement toward hybrid collector configurations or wall-mounted systems.
Market Dynamics
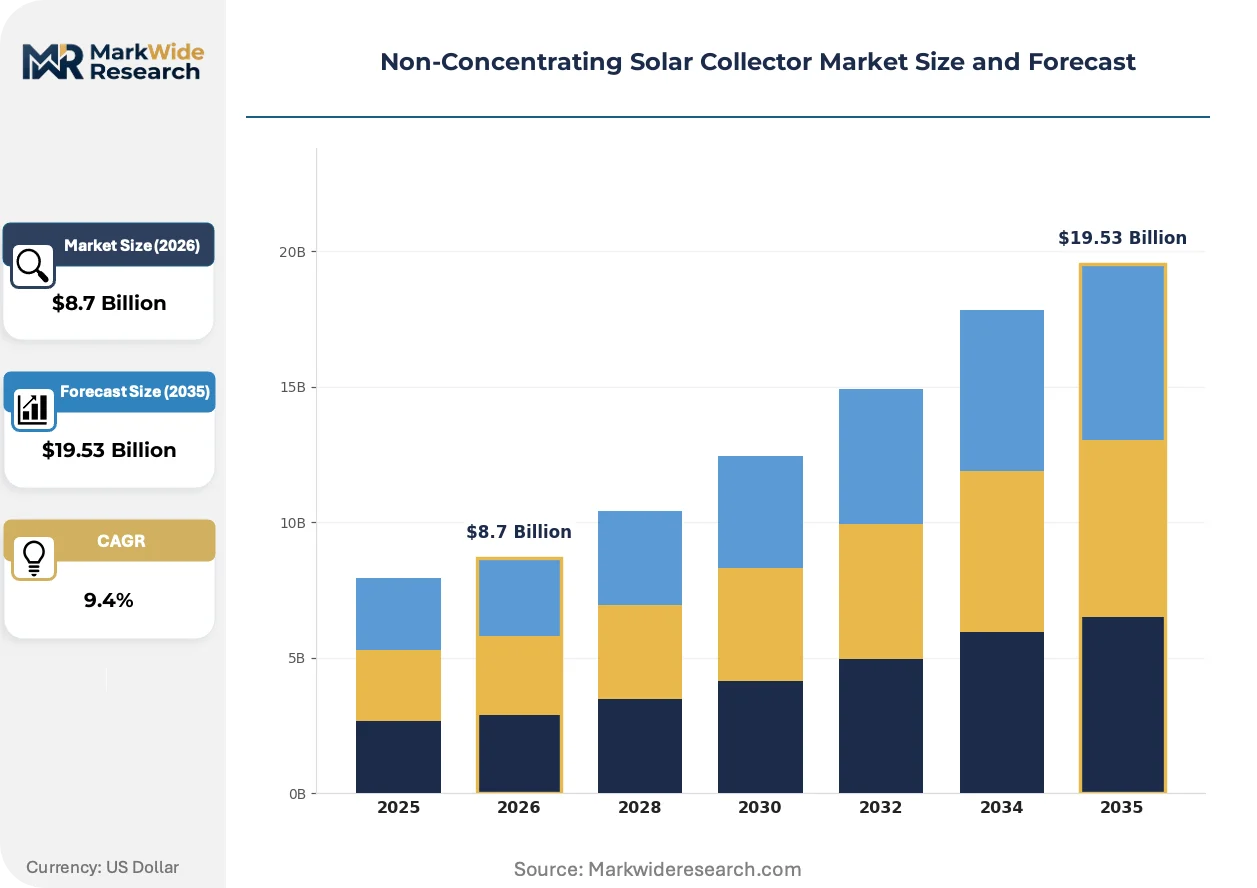
The Non-Concentrating Solar Collector Market is restructuring around regulatory tightening in thermal efficiency standards and the geographic consolidation of export manufacturing capacity in China's eastern corridor.
Growth Catalysts
- EU Green Deal thermal mandates:The framework mandates minimum performance coefficients for low-temperature solar systems, forcing replacement cycles across existing European building stock and expanding addressable market volume for certified collectors.
- Evacuated tube cold-climate penetration:Reduced heat loss coefficients enable viable deployment in Nordic and Alpine heating networks previously dominated by fossil alternatives, opening municipal district heating procurement pipelines.
- Suburban residential water heating:German suburban development codes increasingly require renewable thermal pre-heating, embedding collector specification into construction financing and standardizing bulk procurement volumes.
Market Restraints
- Copper and aluminum input volatility:Selectively coated absorber fins depend on base metal pricing that fluctuates with energy-intensive smelting costs, compressing margin buffers for flat-plate manufacturers.
- Single-region supply concentration:Export-oriented production clusters in China's eastern manufacturing corridor create vulnerability to port congestion, energy rationing, or trade policy adjustments affecting Southeast Asian and Middle Eastern project pipelines.
- Stagnation temperature ceiling:Non-concentrating designs cannot exceed 200°C thermal output, excluding industrial process heat applications above this threshold where concentrating solar thermal competes.
Strategic Opportunities
- Municipal pool heating mandates:Public decarbonization targets in Southern European municipalities are hardening procurement specifications for solar thermal warmup loops, creating a margin pool with standardized specification and repeat tender cycles.
- Heat pump-collector hybrid integration:Building-integrated installation codes in Germany and retrofit subsidy thresholds in France are shifting specification toward wall-mounted and hybrid configurations that combine solar thermal with electrically driven heat pumps.
- Direct manufacturer procurement:Regional installers across Southern Europe are bypassing traditional distribution channels, enabling margin capture through captive direct sales relationships and customized specification support.
Industry Challenges
- Skilled thermal installer scarcity:Proper bonding of copper fins to fluid-filled tubes and glazing assembly requires specialized craft training that lags deployment targets in rapidly scaling markets.
- F-Gas Regulation compliance timelines:Restrictions on high-GWP insulation foams force reformulation of collector backing materials, requiring recertification against EU thermal performance benchmarks before market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Concentrating Solar Collector Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Plate, Evacuated Tube, Hybrid Collector, Solar Air Heater End User: Residential, Commercial, Industrial, Government Application: Space Heating, Water Heating, Pool Heating, Drying Systems Installation Type: Roof Mounted, Ground Mounted, Wall Mounted, Building Integrated |
| Companies Covered | Greenonetec, Viessmann Group, Bosch Thermotechnik, SunMaxx Solar, Solahart, Apricus, Sunrain Group, Vaillant Group, Trina Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Concentrating Solar Collector Market Strategic Shifts
Product architecture and procurement pathways are diverging as manufacturers respond to divergent thermal performance mandates and installer channel fragmentation.
Selective coating deposition technology is digitizing quality control across absorber fin manufacturing. Austrian and German producers are deploying inline spectral measurement systems to verify emissivity coefficients during continuous roll-to-roll processing. This capability is digitizing batch traceability and compressing warranty claim resolution cycles for district heating network operators.
The EU F-Gas Regulation is restricting polyurethane foam blowing agents with GWP above 150, forcing collector manufacturers to reformulate insulation backing or switch to mineral wool alternatives. German and Austrian producers with captive foam operations face capital-intensive retooling, while smaller fabricators sourcing third-party insulation confront supply discontinuity and recertification delays.
Installer procurement behavior is fragmenting across Southern Europe as regional contractors build direct relationships with manufacturers. Spanish and Italian installers now specify collector configurations through digital portals that bypass traditional wholesale distributors, compressing lead times but shifting technical support burden onto producer field teams. This pattern concentrates in municipal and commercial segments where project scale justifies direct negotiation.
Non-Concentrating Solar Collector Market Segmentation
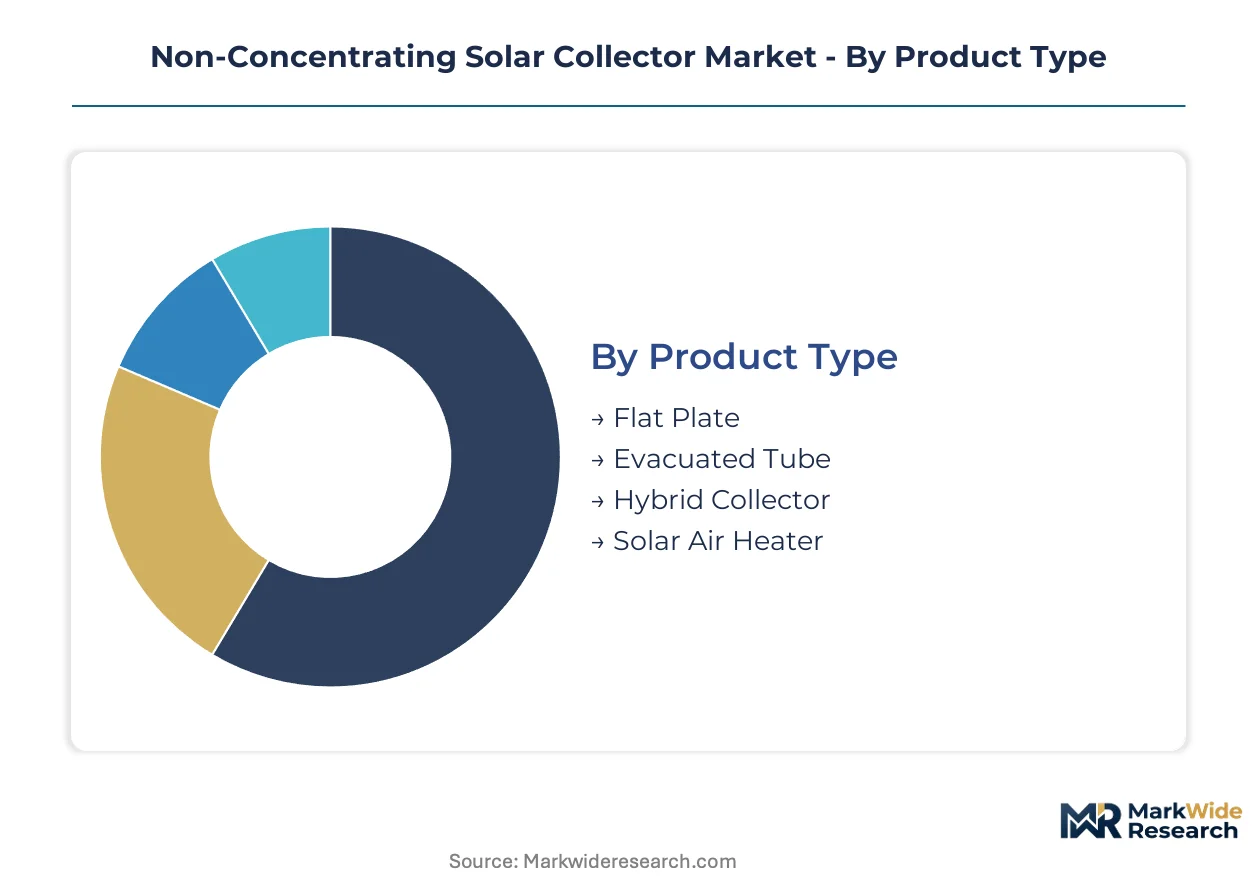
Non-concentrating solar collectors serve divergent thermal loads across temperature ranges, building typologies, and regulatory environments. Segmentation reveals where evacuated tube premiumization competes with flat-plate cost engineering, and which installation modalities capture subsidy flows in retrofit versus new-build construction cycles.
Product Type:
Mature configurations dominate volume, while emerging hybrid architectures capture policy-driven retrofit premiums.
- Flat Plate:Copper or aluminum absorber fins bonded to fluid-filled tubes sit beneath tempered glass glazing with insulated backing. German suburban residential developments specify these for bulk water heating procurement under renewable thermal pre-heating mandates.
- Evacuated Tube:Concentric glass tubes with vacuum insulation between layers achieve reduced heat loss coefficients. Nordic and Alpine district heating networks deploy these in municipal procurement pipelines where cold-climate performance offsets first-cost premiums.
- Hybrid Collector:Combines solar thermal absorption with photovoltaic electricity generation in shared aperture configurations. Wall-mounted and building-integrated codes in France and Germany are shifting specification toward these dual-output systems.
- Solar Air Heater:Perforated metal absorbers direct airflow for space conditioning and agricultural drying. Industrial process applications in China's eastern manufacturing corridor utilize these for low-temperature pre-heating.
Flat Plate handles the majority of throughput; Hybrid Collector is the fastest mover on share.
End User:
Cost tier stratification separates subsidy-dependent residential volumes from margin-rich commercial specifications.
- Residential:Suburban developments across Germany embed collector specification into construction financing, standardizing bulk procurement for water heating systems. EU Green Deal thermal mandates accelerate replacement cycles across existing building stock.
- Commercial:Hotels, hospitals, and multi-family housing specify higher-performance evacuated tube arrays. Southern European installers bypass distributors to negotiate direct manufacturer relationships at this scale.
- Industrial:Low-temperature process heat below 200°C stagnation thresholds serves food processing and textile applications. Stagnation temperature ceilings exclude higher-heat industrial segments from non-concentrating architectures.
- Government:Municipal pool heating and district warmup loops harden procurement specifications under public decarbonization mandates. Southern European municipalities generate repeat tender cycles with standardized specifications.
Residential absorbs the greatest unit volume; Government procurement is expanding most quickly as public decarbonization targets harden.
Application:
Geography determines which thermal load captures available solar resource, with water heating anchoring temperate zones and space heating penetrating cold climates.
- Space Heating:Evacuated tube configurations with reduced heat loss coefficients enable viable deployment in Nordic and Alpine heating networks. Austrian district heating operators specify these for municipal network integration.
- Water Heating:Flat-plate collectors dominate residential pre-heating applications across German suburban construction codes. Temperate zone insolation profiles match the thermal output characteristics of glazed flat-plate architectures.
- Pool Heating:Unglazed or low-cost glazed collectors serve municipal and commercial pool warmup loops. Southern European public procurement mandates are hardening specifications for solar thermal pre-heating.
- Drying Systems:Solar air heaters deliver low-temperature airflow for agricultural and industrial dehydration. China's eastern manufacturing corridor exports these configurations to Southeast Asian processing facilities.
Water Heating maintains the largest installed base; Space Heating is climbing the fastest as cold-climate evacuated tube penetration deepens.
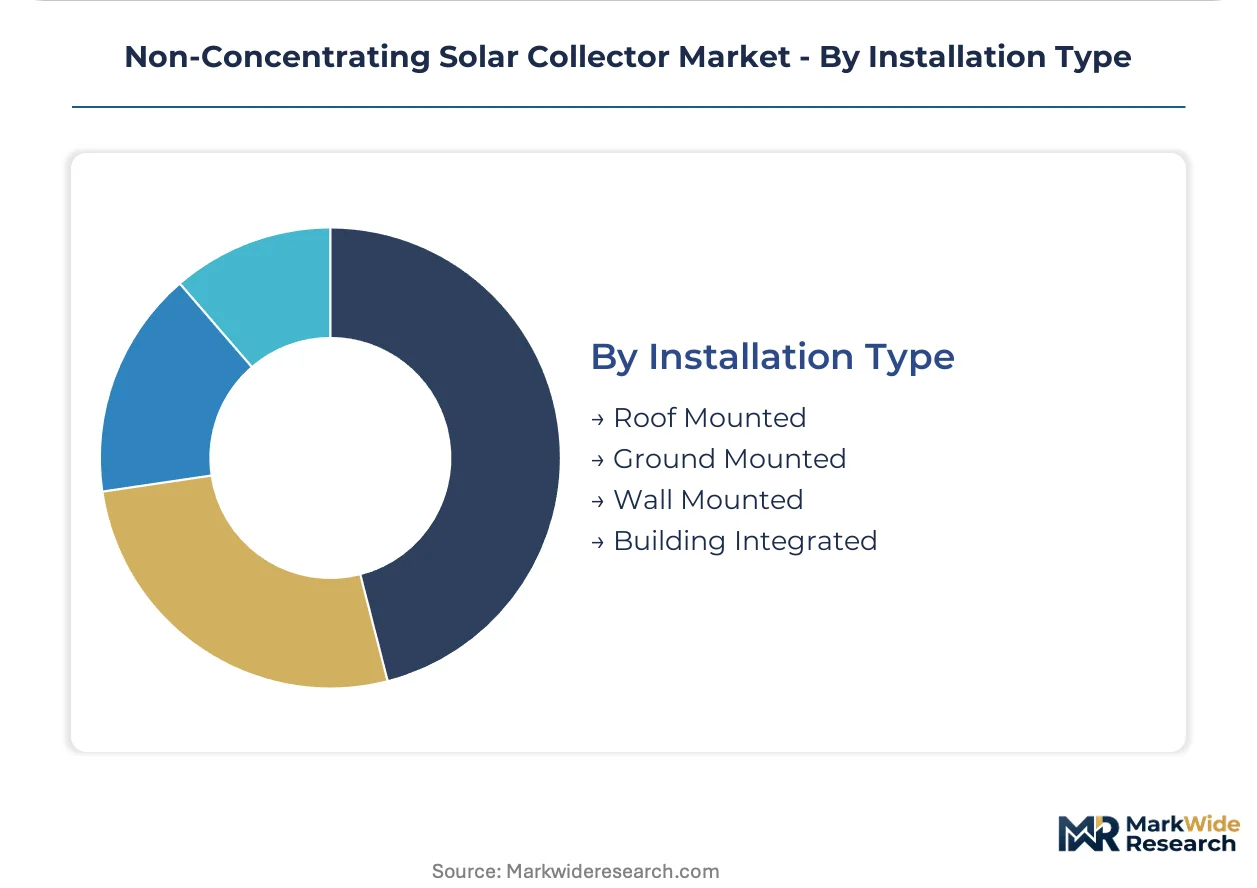
Installation Type:
Customer type and building vintage determine mounting architecture, with retrofit subsidies steering wall-mounted alternatives and new construction embedding roof-integrated systems.
- Roof Mounted:Tilted rack systems on pitched or flat roofs dominate residential and commercial new-build specifications. German building codes increasingly mandate renewable thermal pre-heating in suburban developments.
- Ground Mounted:Free-standing arrays serve industrial process heat and large-scale district heating feed-ins. Municipal procurement in Alpine regions deploys these for centralized thermal generation.
- Wall Mounted:Vertical collector configurations capture facade area in dense urban retrofits. French subsidy thresholds are shifting specification toward these configurations where roof area is constrained.
- Building Integrated:Collectors replace conventional cladding materials, satisfying aesthetic and thermal functions simultaneously. German building-integrated installation codes are embedding these into construction financing.
Roof Mounted retains the dominant share; Wall Mounted is gaining share fastest as urban retrofit subsidies expand accessible surface area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European demand for certified thermal systems, while China's dual carbon goals enforce manufacturing efficiency benchmarks that ripple through export supply chains serving Southeast Asian and Middle Eastern project pipelines.
Germany
Suburban development codes in Bavaria and North Rhine-Westphalia embed renewable thermal pre-heating into construction financing, standardizing bulk procurement volumes for residential water heating. The country's building-integrated installation codes tighten under EU F-Gas Regulation compliance timelines. Manufacturing clusters in Baden-Württemberg produce selectively coated absorber fins with inline spectral measurement systems for district heating network operators.
China
Export-oriented production corridors in the Yangtze River Delta and Pearl River Delta serve Southeast Asian municipal pool heating and Middle Eastern industrial process heat pipelines. GB standards and dual carbon goals enforce domestic manufacturing efficiency benchmarks. Zhejiang and Jiangsu provinces concentrate evacuated tube fabrication capacity that supplies cold-climate installations across Nordic markets.
France
Retrofit subsidy thresholds in Île-de-France and Auvergne-Rhône-Alpes shift procurement toward wall-mounted collector configurations where roof area is constrained. The country's national building regulator enforces thermal performance coefficients aligned with EU Green Deal mandates. Lyon-based installers negotiate direct manufacturer relationships, bypassing traditional wholesale distribution channels.
Italy
Southern municipalities in Sicily and Campania harden procurement specifications for solar thermal pool heating under public decarbonization mandates. Regional installers across Lombardy and Veneto build direct relationships with manufacturers through digital specification portals. Alpine district heating networks in South Tyrol specify evacuated tube arrays for cold-climate performance.
Austria
Alpine district heating operators in Vienna and Salzburg specify evacuated tube configurations for municipal network integration. The country's thermal efficiency standards exceed EU baseline requirements under national building codes. Styrian production bases serve premium positioning in Central European heating networks through captive boiler-collector bundling programs.
Non-Concentrating Solar Collector Market Competitive Environment
Vertically integrated heating conglomerates and specialized solar thermal fabricators split the market between bundled system sales and component specialization. The vendor base concentrates around three strategic archetypes: captive boiler-collector integrators, export-oriented tube manufacturers, and regional installation specialists. Competitive moves center on direct procurement channel development and F-Gas Regulation compliance certification acceleration.
Within the captive integration tier, Viessmann Group and Bosch Thermotechnik exemplify conglomerate positioning through boiler-collector bundling and heat pump interoperability. Greenonetec occupies a specialist position among Alpine fabricators serving district heating network operators. Sunrain Group represents scale-driven export manufacturing from China's eastern corridor.
| Leading Market Players |
|---|
| Greenonetec |
| Viessmann Group |
| Bosch Thermotechnik |
| SunMaxx Solar |
| Solahart |
| Apricus |
| Sunrain Group |
| Vaillant Group |
| Trina Solar |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion spreads cost volatility through evacuated tube supply chains, compressing margin buffers for flat-plate manufacturers while amplifying price differentiation between standard catalog products and configured-to-order district heating specifications. Copper and aluminum input costs from energy-intensive smelting operations in China's eastern corridor feed directly into absorber fin pricing, forcing European fabricators to recalibrate premium positioning against import competition.
Pricing Analysis
The customization-premium spread separates standard flat-plate catalog pricing from engineered evacuated tube configurations for Alpine district heating networks. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EU F-Gas Regulation compliance timelines and thermal performance coefficient benchmarks. Pricing pressure stems from copper and aluminum smelting cost volatility compressing absorber fin margins. Residential suburban developers in Germany exhibit highest price sensitivity through bulk procurement standardization, while municipal procurement in Southern Europe tolerates premium tiers for repeat tender reliability.
Supply Chain Analysis
Contract manufacturing concentration in Zhejiang and Jiangsu provinces holds dominant evacuated tube fabrication capacity serving Nordic cold-climate installations. Supply draws from selectively coated copper and aluminum absorber fin production in Baden-Württemberg, tempered glass glazing from China's eastern corridor, and polyurethane foam insulation facing F-Gas Regulation reformulation. Single-region concentration in China's manufacturing belt creates tariff exposure vulnerability for Southeast Asian and Middle Eastern project pipelines. Distribution runs through direct manufacturer portals bypassing traditional wholesale channels in Southern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
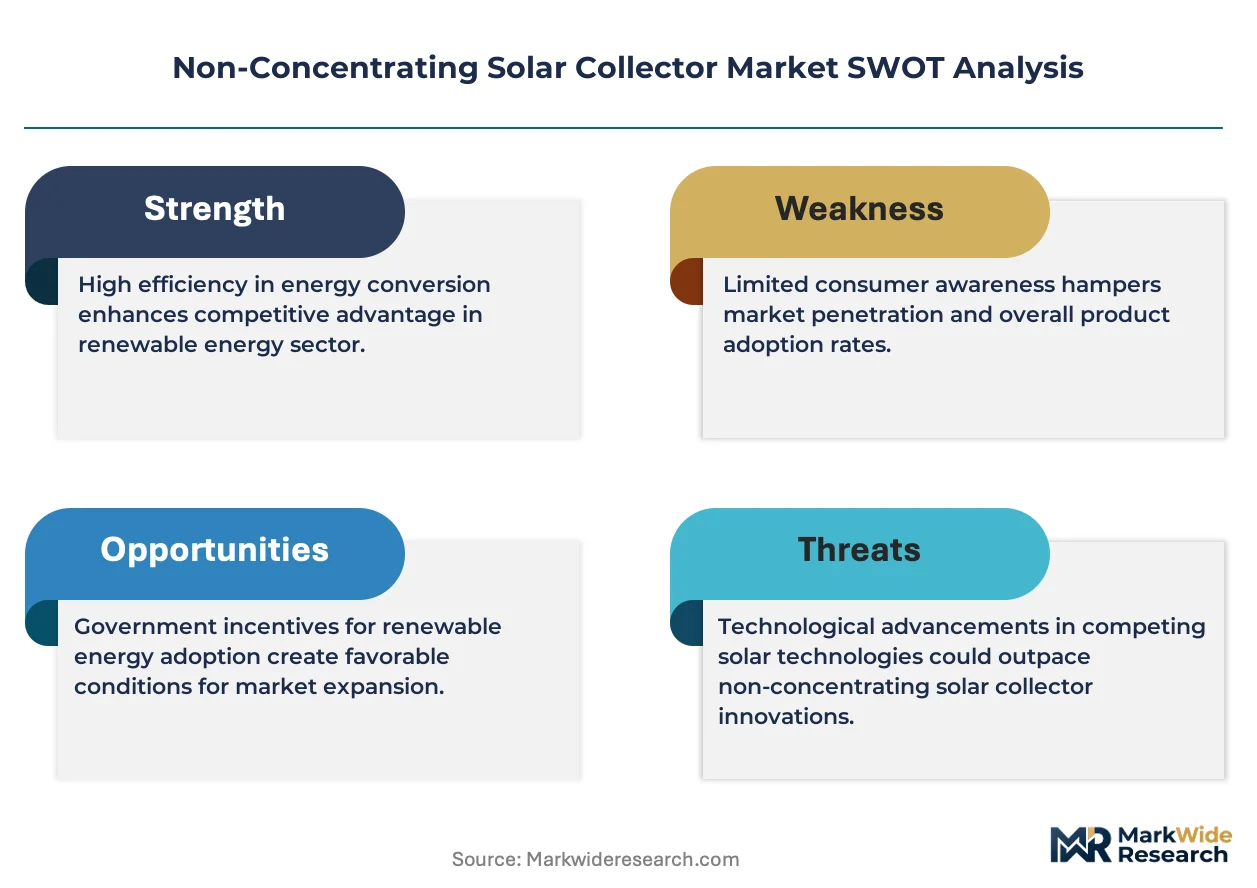
The Non-Concentrating Solar Collector Market functions as a defensive-moat story anchored in regulatory entrenchment: EU F-Gas Regulation compliance timelines and thermal performance certification create sticky switching costs for institutional buyers.
For Market Incumbents: Insulate premium positioning through captive boiler-collector bundling programs and accelerated F-Gas Regulation recertification. Backward integration into selective coating deposition technology with inline spectral measurement systems defends margin buffers against Chinese import competition. District heating network operator relationships in Alpine regions provide channel control leverage. For New Entrants and Emerging Players: Build out white-space presence in municipal pool heating procurement across Southern European municipalities where public decarbonization mandates harden specifications but incumbent coverage remains thin. Wall-mounted collector configurations for French urban retrofits offer the most penetrable installation modality. Direct digital portal engagement with regional installers bypasses entrenched distribution relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from heating conglomerates divesting non-core solar thermal divisions amid heat pump strategic prioritization. Long-term viability rests on regulatory tightening durability across EU member states and China's dual carbon goal enforcement. Watch GB standards alignment with EU thermal benchmarks as inflection signal for export manufacturing margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| F-Gas Regulation Compliance Acceleration | Recertification investment secures EU market access before competitor supply discontinuity. |
| Direct Installer Portal Development | Digital specification tools capture Southern European procurement channel fragmentation. |
| Selective Coating Technology Integration | Inline spectral measurement compresses warranty resolution cycles for district operators. |
| Hybrid Collector Configuration Launch | Dual-output systems align with German building-integrated installation code tightening. |
| Alpine District Heating Network Partnership | Evacuated tube specifications in municipal procurement generate repeat tender revenue. |
Study Parameters
A spread of perspectives from district heating network operators, solar thermal procurement managers at municipal utilities, regional installation contractors, and selective coating equipment manufacturers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against EU F-Gas Regulation implementation timelines, GB standards documentation, customs trade data for copper and aluminum inputs, and SEC filings from heating conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic thermal demand projections.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product architecture, end-user cost tier, application temperature range, and installation mounting modality. CAGRs derived from installation volume trajectories calibrated to regulatory mandate enforcement schedules and construction code adoption curves. Forecast inputs incorporated copper and aluminum price elasticity coefficients and EU Green Deal thermal performance coefficient phase-in schedules.
Sensitivities concentrate around F-Gas Regulation compliance timeline delays, copper smelting energy cost volatility, and Chinese export manufacturing energy rationing. Forecasts reflect documented assumptions on regulatory enforcement consistency and construction financing availability for suburban developments. Quarterly review of EU member state transposition deadlines and Yangtze River Delta port throughput metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Solar Tracker Installation Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Global Crystalline Solar Cells Market