
 Solar Powered Drones Market | 2026-2036
Solar Powered Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Drones Market Intelligence
A shift from outsourced component sourcing to in-house development of critical systems like power management and airframes is consolidating the supply chain. This trend favors companies with deep engineering capabilities. Airbus leverages its aerospace manufacturing scale to develop high-altitude pseudo-satellite (HAPS) platforms. AeroVironment specializes in smaller, tactical solar drones, while Skydweller Aero focuses on converting traditional aircraft into long-endurance solar-powered vehicles.
Solar powered drones are unmanned aerial vehicles (UAVs) equipped with photovoltaic cells integrated into their wing surfaces to harvest solar energy. This design significantly extends flight endurance for long-duration missions without conventional refueling. Fixed-wing designs dominate the market due to their superior aerodynamic efficiency for extended flights. Within applications, agriculture and surveillance represent the largest segments, driven by requirements for persistent aerial monitoring over vast areas.
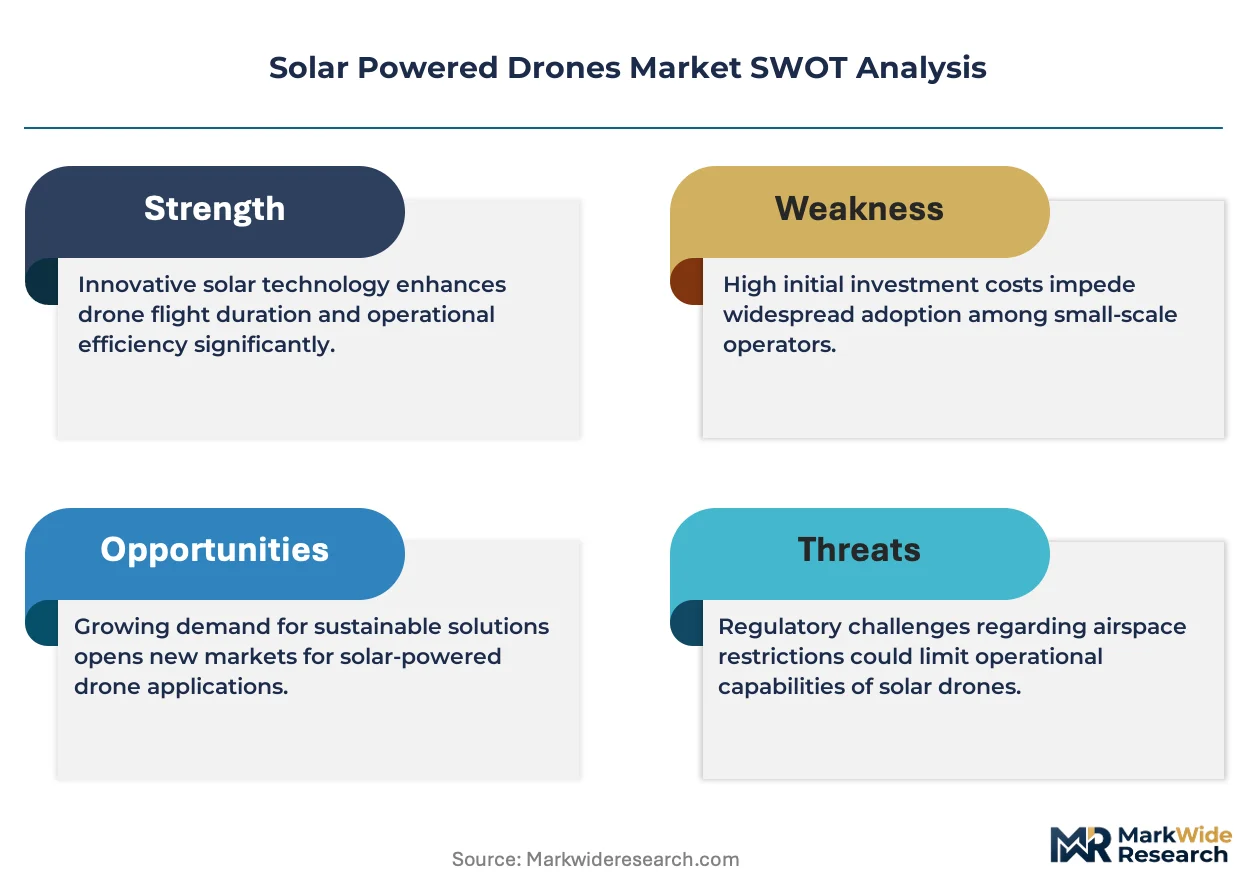
Regulatory frameworks from bodies like the US Federal Aviation Administration (FAA) and standards such as Europe's CE marking govern airworthiness and operational safety. These rules, along with directives from civil aviation authorities in Japan, define requirements for beyond-visual-line-of-sight (BVLOS) operations. Navigating this evolving international patchwork of airspace regulations is the primary challenge for commercial operators seeking to scale services.
Market Dynamics
The central force shaping the market is the rapid advancement in photovoltaic cell efficiency and energy storage density. This technological convergence is unlocking unprecedented flight endurance, transforming solar drones from niche concepts into viable platforms for persistent, wide-area commercial and military missions.
Growth Catalysts
- Photovoltaic Efficiency:Continuous improvements in the power-to-weight ratio of solar cells and supporting power management systems are extending mission durations, enabling new applications like persistent surveillance and multi-day environmental monitoring.
- Precision Agriculture Demand:The agriculture sector requires persistent, large-area monitoring for crop health, irrigation management, and yield optimization. Solar drones provide a cost-effective solution for this continuous data collection need over vast farmlands.
- BVLOS Regulation:Evolving regulations from authorities like the US Federal Aviation Administration (FAA) are gradually opening up airspace for beyond-visual-line-of-sight (BVLOS) operations, a critical enabler for realizing the long-endurance capabilities of solar UAVs.
Market Restraints
- Operational Limitations:Performance is inherently dependent on weather conditions and daylight, with cloud cover, seasonal changes in sun angle, and nighttime operations presenting significant constraints that require sophisticated battery storage and power management.
- High Initial Investment:The use of specialized, lightweight composite airframes and high-efficiency, space-grade photovoltaic cells results in a high upfront capital cost compared to conventionally powered drones, limiting broader adoption.
- Fragmented Airspace Rules:Navigating the complex and non-harmonized regulatory requirements for UAVs across different national jurisdictions, such as those from the FAA and EASA, creates significant compliance overhead for international operations.
Strategic Opportunities
- Infrastructure Inspection:A significant opportunity exists in using solar drones for the persistent, autonomous inspection of linear infrastructure like pipelines, power lines, and railways, where long-endurance capabilities are a primary requirement.
- Emerging Geographies:Markets like Australia and parts of Africa offer vast, sun-rich, and sparsely populated areas ideal for deploying solar-powered drones for applications in agriculture, environmental conservation, and border surveillance.
- AI-Powered Analytics:Integrating onboard AI processors for real-time data analysis allows service providers to move beyond raw data collection and offer value-added insights, such as automated anomaly detection or yield forecasting services.
Industry Challenges
- Data Integration Complexity:A primary operational hurdle is the integration of massive data volumes from long-endurance flights into existing enterprise resource planning (ERP) and geographic information system (GIS) software, which often requires custom development.
- Airworthiness Certification:Achieving type certification for large, high-altitude pseudo-satellite (HAPS) platforms from aviation authorities is a lengthy and capital-intensive process, delaying the commercial rollout of these advanced systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Drones Market |
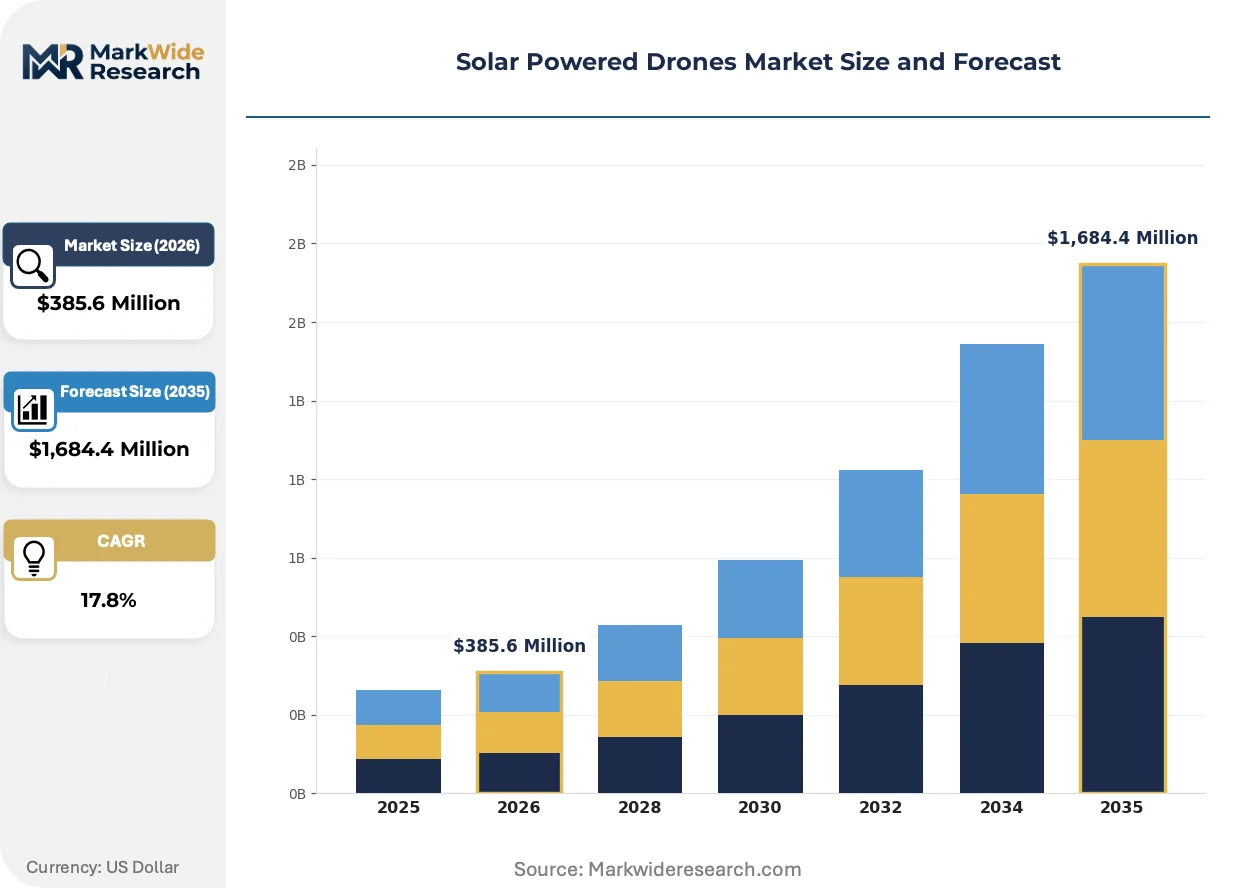
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,684.4 Million |
| CAGR (2026 – 2036) | 17.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multirotor, Single Rotor, Hybrid Application: Agriculture, Surveillance, Delivery, Environmental Monitoring End User: Agricultural Sector, Military, Logistics, Research Institutions Technology: Solar Cell, Lithium Battery, Hybrid Energy, Autonomous Navigation |
| Companies Covered | Google, Bye Aerospace, Airbus, Skydweller Aero, Atlantik Solar, Boeing, Facebook, QinetiQ, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Drones Market Strategic Shifts & Innovations
The market's evolution is defined by a convergence of hardware endurance and software intelligence. This transforms drones from passive data collectors into autonomous platforms capable of processing information and supporting decisions at the network edge, reducing reliance on ground-based infrastructure.
Onboard artificial intelligence, powered by dedicated processors, enables real-time data analysis directly on the drone. Defense and large-scale agricultural enterprises are the leading adopters, seeking immediate intelligence without data transmission latency. This onboard processing is automating tasks like target identification and crop disease detection, fundamentally changing the operational value proposition by delivering answers instead of just raw imagery.
Europe's U-space regulatory framework is establishing a digital infrastructure for managing dense drone traffic. This initiative aims to enable safe and scalable beyond-visual-line-of-sight operations through services like geofencing, electronic identification, and traffic information. Commercial operators in logistics and critical infrastructure monitoring are most affected, as compliance with U-space protocols becomes a prerequisite for obtaining flight permissions in controlled airspace.
A notable behavioral shift is occurring from asset ownership to service-based procurement models, often termed drones-as-a-service (DaaS). This trend disrupts traditional equipment sales channels, as customers opt for subscription contracts that bundle flight operations, data processing, and analytics. This model is most prominent in the environmental monitoring and precision agriculture sectors in North America, where end-users prioritize actionable insights over managing aviation hardware.
Solar Powered Drones Market Segmentation
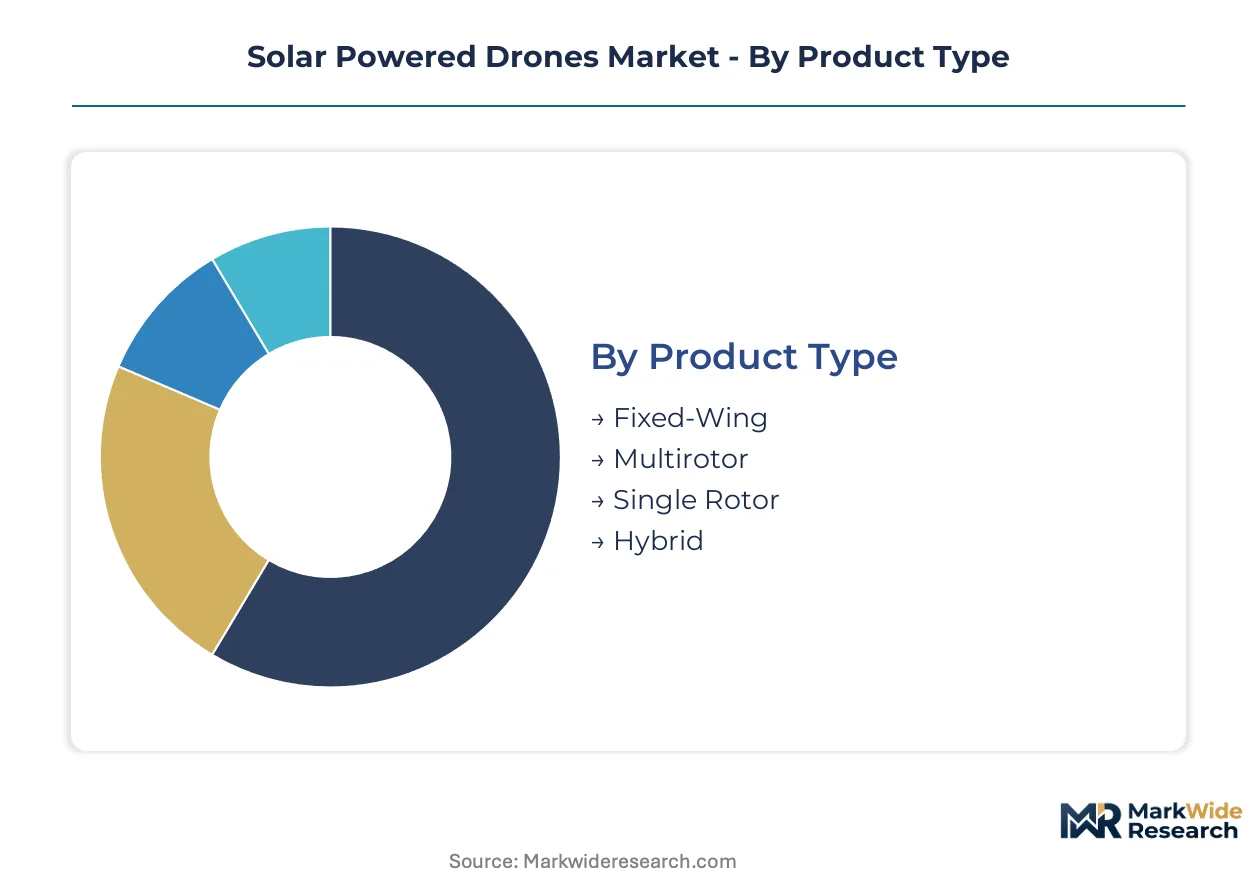
The solar powered drones market segments across diverse product types, applications, end-users, and core technologies. Understanding these divisions helps delineate where innovation is most impactful and where operational efficiencies are gained. Each segment reflects unique engineering challenges and distinct commercial opportunities within the broader drone ecosystem.
Product Type:
The integration depth of solar power systems into various drone architectures significantly influences flight characteristics and mission profiles.
- Fixed-Wing:These drones feature long, rigid wings integrated with photovoltaic cells, providing superior aerodynamic efficiency for extended flight durations. Demand concentrates in the United States for persistent surveillance and large-area agricultural monitoring, driven by requirements for continuous data collection.
- Multirotor:Characterized by multiple propellers for vertical take-off and landing, multirotor solar drones offer enhanced maneuverability and hovering capabilities. These systems are gaining traction in urban infrastructure inspection where precise positioning is critical.
- Single Rotor:Similar to traditional helicopters, single-rotor solar drones provide robust lift capacity and stable flight, often utilized for heavier payloads or in challenging wind conditions. Their use is emerging in specialized environmental sampling missions.
- Hybrid:Combining vertical take-off and landing with efficient forward flight, hybrid solar drones offer operational flexibility, enabling deployment from confined spaces and long-range missions. These platforms are increasingly adopted for remote logistics in geographically challenging areas.
Volume placements concentrate in Fixed-Wing platforms; the faster expansion belongs to Hybrid designs.
Application:
Operational impact drives the categorization of solar drone applications, reflecting distinct requirements for data acquisition and mission execution.
- Agriculture:Solar drones provide persistent aerial monitoring for crop health, irrigation management, and yield optimization over vast farmlands. The precision agriculture sector in North America requires continuous data collection for informed decision-making.
- Surveillance:These applications involve continuous, wide-area monitoring for security, border control, and intelligence gathering purposes. Defense-related surveillance in the United States and Europe leverages long-endurance solar drones for persistent observation.
- Delivery:Emerging use cases for solar drones include last-mile delivery services, particularly in remote or hard-to-reach locations. Regulatory evolution from bodies like the US FAA is slowly enabling commercial delivery operations.
- Environmental Monitoring:Solar drones support data collection for climate research, wildlife tracking, and pollution detection over large geographical expanses. Conservation efforts in Australia benefit from the extended range of these platforms.
Agriculture and Surveillance applications dominate current operational deployments, with Environmental Monitoring showing significant growth potential.
End User:
Procurement models and operational scale define the end-user segments, each with specific requirements for drone capabilities and data integration.
- Agricultural Sector:Farmers and large agribusinesses utilize solar drones for precision farming, requiring systems capable of covering extensive fields with high-resolution sensors. This sector prioritizes cost-effective, long-duration data collection.
- Military:Defense organizations deploy solar drones for long-endurance intelligence, surveillance, and reconnaissance (ISR) missions, demanding robust, high-altitude platforms. The US Department of Defense invests in persistent aerial platforms for strategic advantage.
- Logistics:Companies in the logistics and transportation sector explore solar drones for autonomous delivery and inventory management in large facilities. This segment seeks solutions for efficient and timely movement of goods.
- Research Institutions:Universities and scientific bodies employ solar drones for atmospheric research, ecological studies, and technology development. These institutions drive innovation in sensor integration and autonomous flight algorithms.
The Agricultural Sector and Military represent the largest end-user segments, while Logistics is poised for rapid expansion with regulatory clarity.
Technology:
The innovation trajectory in core technologies underpins the performance and endurance of solar powered drones, influencing design and operational limits.
- Solar Cell:Advancements in photovoltaic cell efficiency and power-to-weight ratio directly extend flight duration and energy harvesting capabilities. Gallium arsenide cells provide high efficiency for aerospace applications.
- Lithium Battery:High energy density lithium-ion and lithium-polymer batteries store excess solar energy, enabling nighttime operations and providing power during periods of low sunlight. Battery technology improvements reduce overall drone weight.
- Hybrid Energy:This technology integrates solar power with other energy sources, such as fuel cells or conventional batteries, for enhanced reliability and extended mission profiles. Hybrid systems offer redundancy for critical operations.
- Autonomous Navigation:Advanced AI-powered navigation systems enable drones to operate without constant human intervention, optimizing flight paths and mission execution. These systems are critical for beyond-visual-line-of-sight (BVLOS) operations.
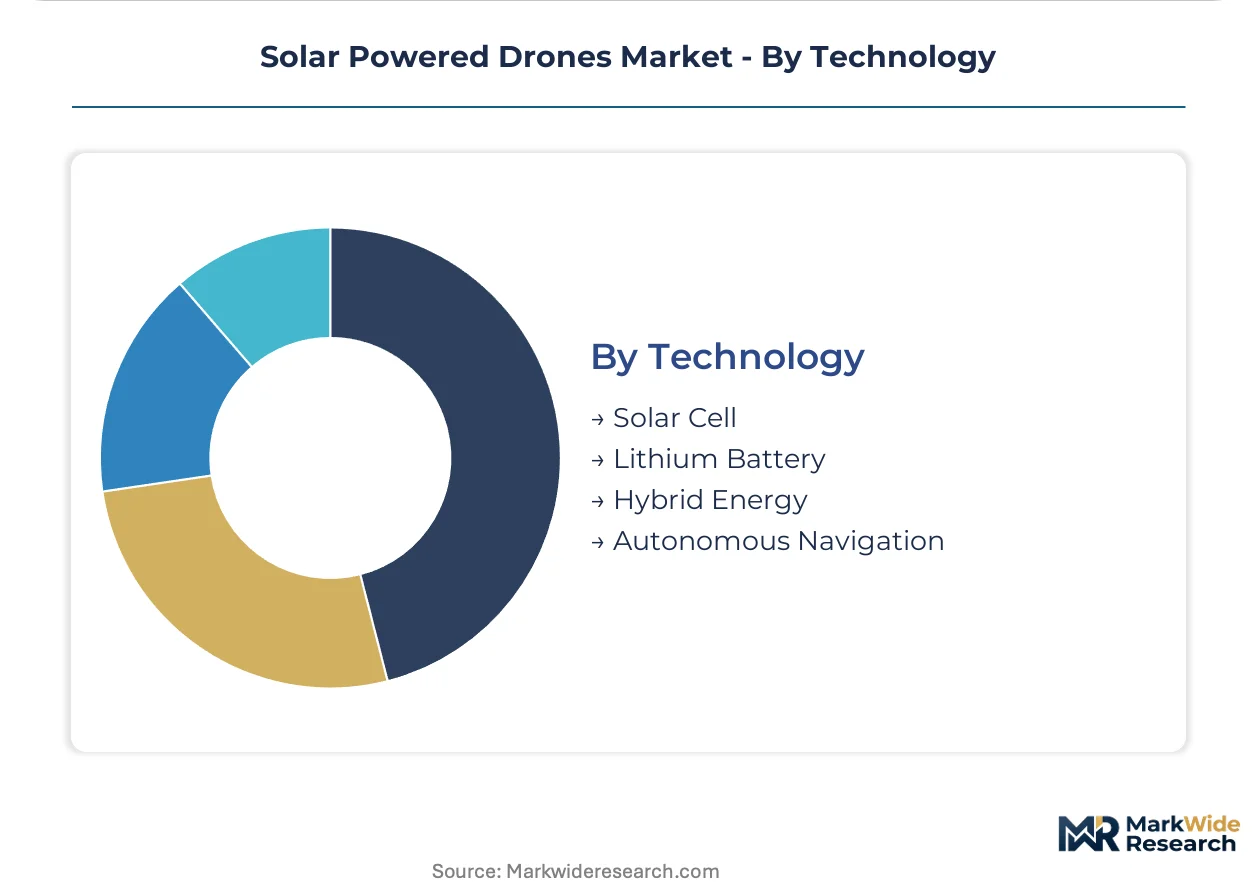
Solar Cell and Lithium Battery technologies are foundational to market development, with Autonomous Navigation driving the next wave of operational capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States anchors demand for solar powered drones, driven by its expansive agricultural sector and significant defense expenditure. Persistent aerial monitoring requirements across vast territories necessitate long-endurance UAV solutions. This global market sees varied regional uptake based on regulatory environments and application needs.
United States
United States demand for solar drones stems from precision agriculture and defense surveillance needs. The US Federal Aviation Administration (FAA) is gradually enabling beyond-visual-line-of-sight (BVLOS) operations, expanding commercial viability. California's aerospace industry, particularly around Los Angeles, leads in developing advanced HAPS platforms.
Germany
Germany shows strong demand for infrastructure inspection and environmental monitoring through solar drones. Europe's CE marking and the U-space regulatory framework guide safe operational deployment. Clusters in Bavaria, like Munich, focus on integrating AI analytics for real-time data processing.
Australia
Australia provides a significant market for environmental conservation and extensive agricultural monitoring due to its vast, sun-rich areas. The country's civil aviation authorities are developing frameworks for long-range, autonomous drone operations. Queensland's research institutions lead in deploying solar drones for wildlife tracking and land management.
Japan
Japan's market for solar drones is driven by infrastructure maintenance and disaster response applications. METI and its civil aviation authorities impose strict safety and airworthiness standards for UAV deployment. Tokyo-based technology firms are innovating in lightweight solar cell integration for extended flight endurance.
China
China's vast agricultural sector and industrial complexes create substantial demand for solar drones. The Ministry of Industry and Information Technology (MIIT) guides drone manufacturing standards and operational permits. Technology hubs in the Yangtze River Delta, like Shanghai, concentrate on developing advanced autonomous navigation systems.
Solar Powered Drones Market Key Industry Players
In-house development of critical systems dominates the current landscape, reshaping the solar powered drone market. The market exhibits a tiered structure, with established aerospace giants alongside specialized drone manufacturers. Strategic archetypes include large-scale platform developers, tactical drone specialists, and component innovators. Vertical integration into power management and airframe manufacturing is a primary competitive move, coupled with strategic partnerships for technology co-development.
On the premium-tier vector, Airbus SE, a European aerospace giant, represents developers leveraging extensive manufacturing scale for high-altitude pseudo-satellite (HAPS) platforms. AeroVironment, Inc., a US-based company, exemplifies specialists in smaller, tactical solar drones, focusing on specific mission profiles. Skydweller Aero, Inc., another US-based entity, occupies a unique position by converting traditional aircraft into long-endurance solar-powered vehicles, anchoring the conversion archetype. These companies collectively illustrate the diverse approaches to product development, from large-scale HAPS to specialized tactical systems and innovative conversions, shaping the market's competitive dynamics.
| Leading Market Players |
|---|
| Bye Aerospace |
| Airbus |
| Skydweller Aero |
| Atlantik Solar |
| Boeing |
| QinetiQ |
| AeroVironment |
| Others |
Cost & Logistics Intelligence
Europe's U-space regulatory framework, establishing digital infrastructure for drone traffic, gates both qualified supply of BVLOS-compliant systems and premium-tier pricing access for commercial operators. This framework mandates specific technical and operational standards for airspace integration.
Pricing Analysis
Warranty and service-level agreement bundling defines the pricing structure for solar drone solutions. Project-based pricing dominates for large-scale deployments, while subscription models gain traction for data-as-a-service offerings in precision agriculture. Price differentiation stems from airworthiness certification levels, such as FAA or EASA compliance, and the degree of onboard AI analytics integration. Pricing pressure stems from increasing competition among specialized drone manufacturers, particularly for tactical systems. Agricultural sector end-users exhibit higher price sensitivity compared to defense organizations.
Supply Chain Analysis
Airworthiness certification requirements, including CE marking and FAA approvals, gate the supply chain for critical components like high-efficiency photovoltaic cells and lightweight composite airframes. Geographic supply concentrations are notable in China for general drone components and in the United States and Japan for specialized aerospace-grade materials. Raw material dependencies include gallium arsenide for advanced solar cells and carbon fiber for airframes. Single-source vulnerability for specialized components presents a structural supply chain risk. Distribution runs through direct sales channels to large enterprises and government agencies, supplemented by specialized systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play, as the high initial investment in specialized hardware and regulatory compliance is forcing smaller, undercapitalized players out. Only companies with deep engineering capabilities can sustain the long development cycles.
For Market Incumbents: Hedge against emerging competition from specialized startups by deepening vertical integration into power management systems and advanced composite manufacturing. Invest in achieving type certification for HAPS platforms, leveraging existing aerospace manufacturing scale to secure high-margin defense contracts. Focus on developing proprietary AI analytics for real-time data processing, creating defensible intellectual property against generic software providers.
For New Entrants and Emerging Players: Digital service platforms that bundle data collection with AI-powered analytics represent a viable entry route for new players. Target the environmental monitoring and precision agriculture sectors in sun-rich, sparsely populated geographies like Australia, where persistent aerial data collection is highly valued. Offer flexible drones-as-a-service (DaaS) subscription models, focusing on outcome-based insights rather than hardware sales, to lower customer adoption barriers.
For Investors and Strategic Acquirers: The commercial rollout of large-scale BVLOS operations is the leading indicator that validates the long-term viability of persistent aerial platforms for commercial and defense applications. Seek out vertically integrated mid-cap specialists with proven flight endurance records and proprietary data analytics capabilities, especially those with strong intellectual property in power management or autonomous navigation. Monitor regulatory clarity from bodies like the FAA for expanded commercial drone operations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Airbus leverages its aerospace manufacturing scale to accelerate the production of high-altitude pseudo-satellite platforms for global deployment. |
| Technology Licensing | Specialized firms license advanced gallium arsenide solar cell designs to drone manufacturers, enhancing energy harvesting efficiency for longer missions. |
| Strategic Partnership | Drone operators form alliances with AI analytics providers to offer real-time data processing services, moving beyond raw imagery collection. |
| Vertical Integration | Companies like AeroVironment deepen in-house development of power management systems and composite airframes, securing critical component supply. |
| Geographic Expansion | Firms target sun-rich, sparsely populated markets like Australia and parts of Africa for deploying solar drones in agriculture and environmental monitoring. |
Research Approach
Secondary sources including regulatory filings from the US FAA and Europe's EASA, academic research on photovoltaic advancements, and defense procurement reports formed the secondary backbone of this analysis. Primary interviews were conducted with drone manufacturers, component suppliers, agricultural technology integrators, and defense contractors to gather qualitative insights. This approach facilitated bottom-up market sizing and top-down validation of market trends.
Historical trendline analysis, combined with a forward-looking assessment of technological advancements, underpinned the quantitative projections across the analysis window. The market was segmented by product type (fixed-wing, hybrid), application (agriculture, surveillance), end-user (military, agricultural sector), and core technology (solar cell, autonomous navigation). Compound annual growth rates were derived by modeling adoption rates, regulatory changes, and investment patterns in solar drone technology. Key forecast inputs included photovoltaic cell efficiency improvements and BVLOS operational permits.
The model holds under current regulatory frameworks and projected technological advancements; deviation in BVLOS policy or solar cell breakthroughs would shift market trajectories. Forecasts reflect assumptions documented regarding market dynamics. A model refresh is warranted upon material change in airspace regulations or energy storage density.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Small UAV Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Anti-Drone Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Autonomous Aircraft Cameras Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
UAV Payload and Subsystems Market
UAV
UAV Lidar Market
UAV
Drone Wireless Charging Station Market
UAV
Tactical UAV Market
UAV
Drone Roof Inspection Market
UAV
Global Target Drone Market
UAV
Europe Small UAV Market
UAV
Global Drone Autopilots Market
UAV
Global Multirotor UAV Market
UAV
Rc Helicopter Market