
 Drone Roof Inspection Market | 2026-2036
Drone Roof Inspection Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Roof Inspection Market Insights
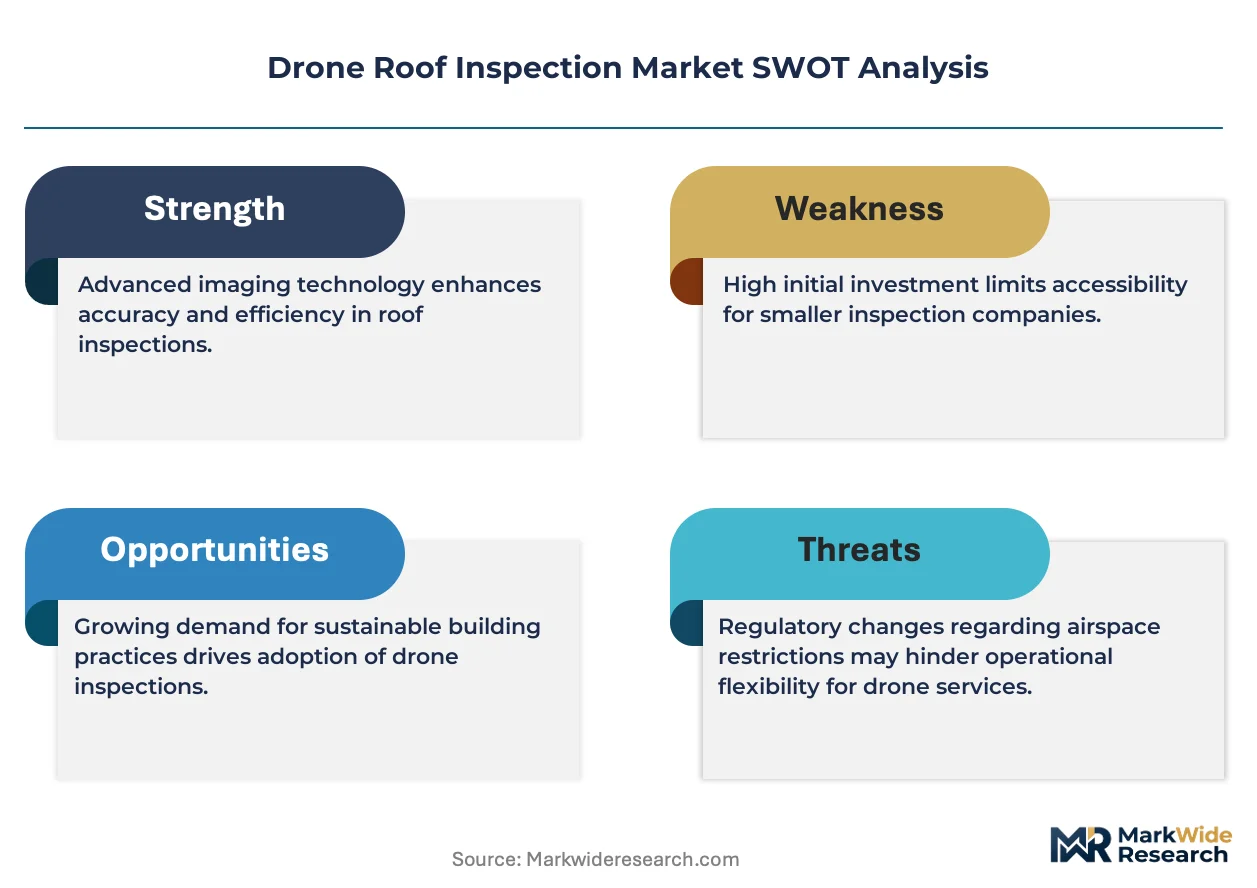
Commercial building portfolios is shifting toward drone-based assessment protocols, displacing traditional manual surveys in high-rise and industrial rooftop environments. Loveland Innovations dominates residential inspection software integration, while FlyPix AI leverages computer-vision analytics for automated damage detection. DroneAdair, Inc. anchors its position through specialized thermal-imaging services for insurance adjusters.
Drone roof inspection deploys unmanned aerial systems equipped with high-resolution cameras, thermal sensors, and LiDAR payloads to capture structural condition data without scaffolding or manned aircraft. These systems typically operate at altitudes below 400 feet with real-time telemetry transmission to ground stations, generating orthomosaic maps and 3D point clouds for engineering analysis. Multi-rotor platforms lead deployment frequency due to vertical takeoff precision in confined urban airspace, while LiDAR-enabled configurations command premium pricing for millimeter-accuracy surface mapping. Photogrammetry services occupy the broadest addressable base among technology segments, though thermal-sensor adoption accelerates fastest as insurers standardize moisture-intrusion documentation.
FAA Part 107 mandates and EASA open-category operational frameworks shape pilot certification requirements and airspace access permissions across North America and Europe. OSHA fall-protection regulations indirectly accelerate drone substitution by elevating liability costs associated with manual rooftop work. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings and insurance-carrier technology mandates to align fleet investments with compliance trajectories.
Market Dynamics
Insurance carriers now mandate aerial documentation for claims processing, converting drone roof inspection from contractor preference to contractual requirement and compressing adoption timelines across residential and commercial portfolios.
Growth Catalysts
- FAA Part 107 mandates:Commercial pilot certification requirements standardize operator competency across the United States, reducing liability exposure for inspection service buyers and accelerating fleet investment by roofing contractors.
- Moisture-intrusion documentation:Thermal-sensor adoption accelerates as carriers standardize water-damage evidence protocols, creating pull-through demand for FLIR-equipped multi-rotor platforms.
- Solar-installation surveys:Rooftop photovoltaic assessments drive contractor adoption in states with aggressive renewable deployment schedules, displacing manual measurement methods.
Market Restraints
- Battery chemistry volatility:Lithium-ion cell costs fluctuate with raw material markets, squeezing hardware margins for fleet operators dependent on extended flight endurance.
- Sensor supply concentration:High-resolution thermal and LiDAR modules concentrate among Japanese and German component suppliers, exposing procurement to single-source risk.
- Beyond-visual-line-of-sight friction:Pending FAA rulemakings delay automated corridor inspection deployment, forcing manual pilot retention for large commercial portfolios.
Strategic Opportunities
- EASA open-category frameworks:European harmonization of low-risk drone operations creates scalable deployment models for cross-border property management firms.
- Computer-vision convergence:Machine-learning damage classification paired with photogrammetry outputs enables automated report generation, reducing analyst labor intensity.
- Storm-damage corridors:Coastal and tornado-prone counties in Texas, Florida, and Oklahoma present concentrated demand spikes where rapid-response drone fleets capture premium pricing.
Industry Challenges
- Part 107 certification pipelines:FAA testing backlogs and recurrent training requirements constrain qualified pilot availability during peak storm seasons.
- Legacy system integration:Enterprise asset management platforms at major insurers lack native drone data ingestion, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Roof Inspection Market |
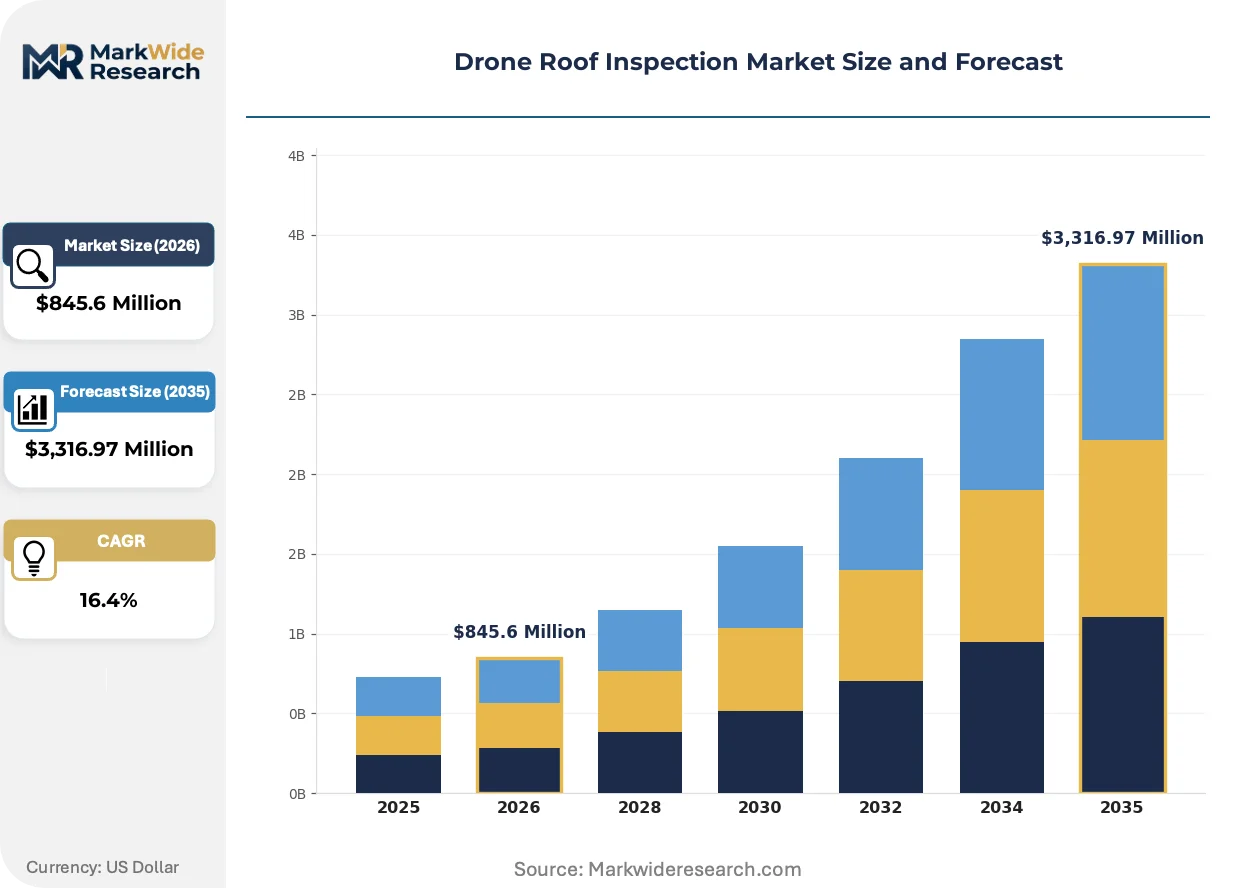
| Market Size in 2026 | $845.6 Million |
| Market Size in 2035 | $3,316.97 Million |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drone Type: Fixed-Wing, Multi-Rotor, Single-Rotor, Hybrid VTOL Technology: LiDAR, Infrared Imaging, Photogrammetry, Thermal Sensors, Ultrasonic Sensors Application: Commercial Buildings, Residential Structures, Agricultural Facilities, Warehouses, Historical Monuments End User: Roofing Contractors, Insurance Companies, Property Managers, Construction Firms, Facility Supervisors |
| Companies Covered | American Drone Industries, Air America Aerial Imagery & Analytics, FlyPix AI, Drone America, ISight Drone Services, Drones and Homes LLC, Action Drone USA, DroneAdair, Inc., Loveland Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Roof Inspection Market Trends and Innovations
Autonomous flight pathing and edge-computing analytics are compressing inspection cycle times from hours to minutes, reshaping labor economics and service pricing structures across the contractor base.
LiDAR-enabled surface mapping is electrifying millimeter-accuracy documentation for commercial and industrial rooftops where structural load calculations demand precise dimensional data. Engineering firms and solar developers now specify LiDAR deliverables in procurement contracts, compressing photogrammetry-only vendors into residential price tiers. The technology is electrifying premium service differentiation and expanding addressable contract values in high-rise environments.
EASA open-category operational frameworks are harmonizing cross-border drone deployment rules across European Union member states, reducing regulatory fragmentation for property portfolios spanning multiple jurisdictions. Standardized risk assessments and remote pilot certification reciprocity enable centralized fleet management from single operations centers. German and French regulators are aligning implementation timelines, accelerating vendor market entry.
Subscription-based inspection scheduling is displacing transactional project bidding among regional roofing contractors, locking recurring revenue streams and reducing customer acquisition costs. National insurance carriers now contract directly with drone service networks, bypassing traditional contractor intermediaries for catastrophe response. This channel compression concentrates volume with certified fleet operators in Florida and Texas storm corridors.
Drone Roof Inspection Market Segmentation
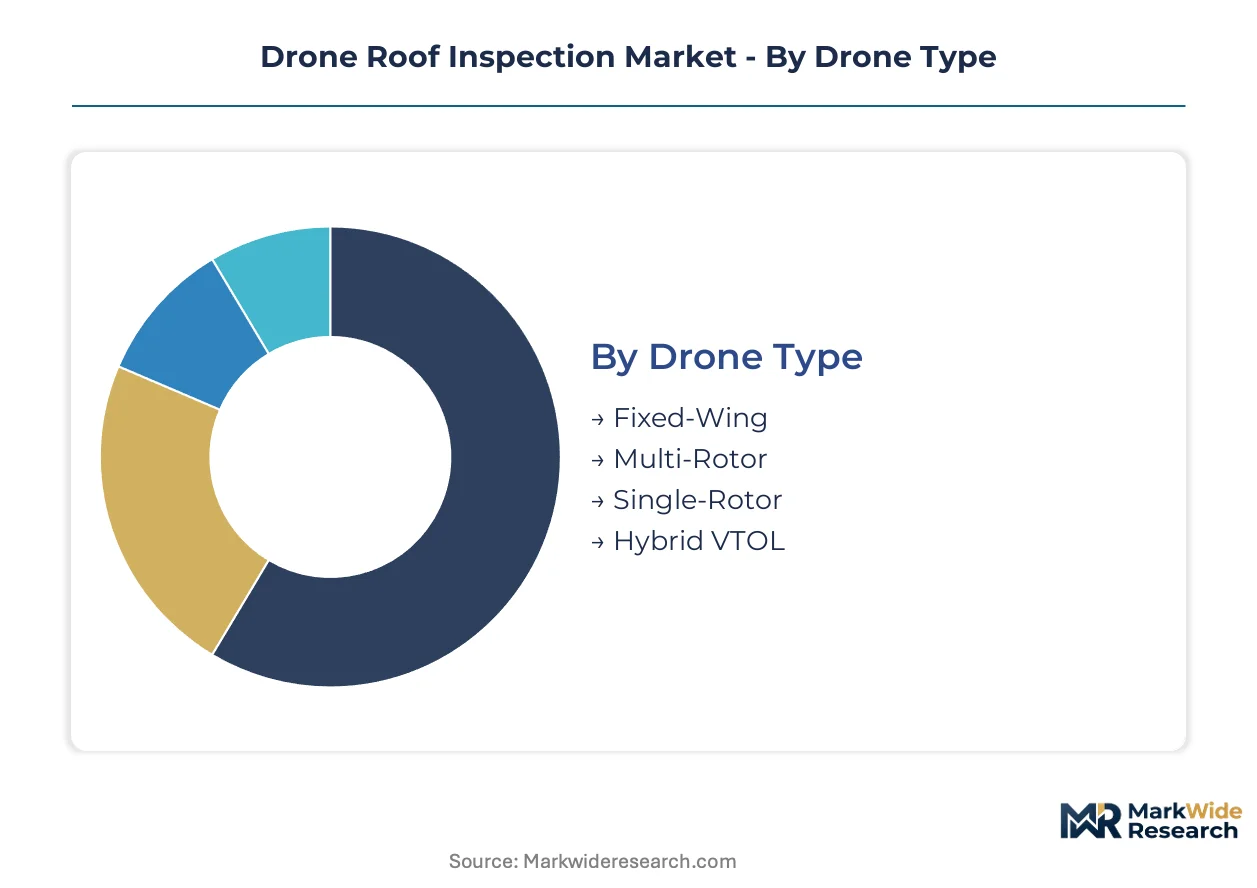
Drone roof inspection procurement diverges sharply across operational requirements, with certification burdens and payload specifications determining fleet composition. Segment boundaries reflect distinct regulatory pathways, sensor integration costs, and end-user technical sophistication levels.
Drone Type:
FAA Part 107 certification applies uniformly across all configurations, though operational complexity and airspace coordination requirements vary substantially by platform architecture.
- Multi-Rotor:Vertical takeoff capability enables precision positioning in confined urban airspace below 400 feet. Demand concentrates among roofing contractors in Texas and Florida storm corridors where rapid deployment for insurance documentation commands premium service fees.
- Fixed-Wing:Extended flight endurance supports corridor-scale commercial portfolio surveys with single-pass efficiency. Property management firms operating multi-state warehouse networks specify fixed-wing platforms to reduce per-acre pilot labor costs.
- Single-Rotor:Helicopter-style configurations deliver heavy LiDAR payloads with hour-plus endurance for industrial rooftop mapping.
- Hybrid VTOL:Dual-mode systems combine multi-rotor precision with fixed-wing range for mixed urban-suburban inspection routes.
Multi-Rotor sits at the top of the volume ranking, with Hybrid VTOL climbing the fastest as fleet operators seek operational flexibility across contract types.
Technology:
Sensor procurement costs stratify sharply, with thermal and LiDAR modules commanding multiples of photogrammetry-only configurations and determining margin structures across service tiers.
- Photogrammetry:High-resolution camera arrays generate orthomosaic maps through overlapping image stitching. Residential roofing contractors in Oklahoma and coastal counties deploy photogrammetry as the baseline deliverable for standard claims documentation.
- Thermal Sensors:FLIR-equipped payloads detect moisture intrusion through temperature differential mapping. Insurance carriers in hurricane-prone states now mandate thermal documentation for water-damage claims, accelerating hardware refresh cycles.
- LiDAR:Laser scanning produces millimeter-accuracy point clouds for structural load calculations on high-rise commercial installations.
- Infrared Imaging:Non-thermal infrared captures spectral signatures for material degradation assessment on historical monument restorations.
- Ultrasonic Sensors:Thickness-measurement payloads evaluate membrane integrity on flat commercial roofing systems.
Photogrammetry maintains the broadest installed base, while Thermal Sensors expand most quickly as carrier documentation standards tighten.
Application:
Building typology dictates flight pattern complexity, sensor payload requirements, and regulatory coordination intensity with municipal airspace authorities.
- Commercial Buildings:High-rise and industrial rooftop environments demand Part 107-certified pilots with night-operation waivers for thermal baseline establishment. Engineering firms in Chicago and Los Angeles specify LiDAR deliverables for structural load verification on solar installation projects.
- Residential Structures:Single-family and low-density multifamily roofs dominate transaction volume through insurance carrier direct contracting. Storm-response networks in Dallas-Fort Worth and Tampa Bay metropolitan areas concentrate residential fleet deployment.
- Agricultural Facilities:Barn and silo inspections require extended-range platforms for rural airspace operations.
- Warehouses:Large-footprint distribution centers favor automated flight pathing across repetitive roof sections.
- Historical Monuments:Preservation-grade documentation demands sub-centimeter accuracy with specialized heritage-compliant reporting formats.
Residential Structures anchor current volume leadership, with Commercial Buildings gaining share fastest as solar development accelerates.
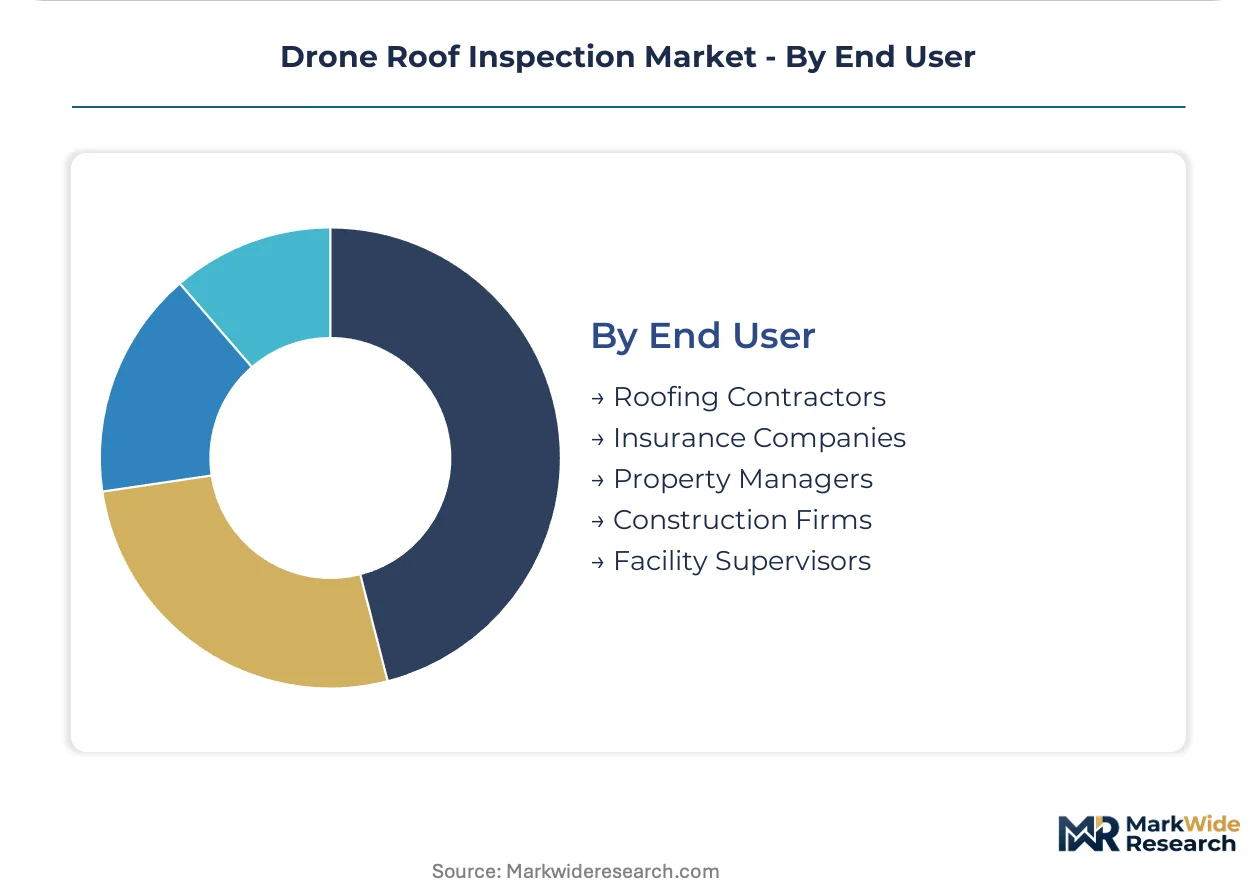
End User:
Procurement authority is shifting from contractor intermediaries to direct carrier contracting, reshaping vendor qualification requirements and pricing transparency.
- Insurance Companies:Carrier mandates for aerial documentation have converted drone inspection from optional contractor tool to contractual requirement. National carriers now operate certified vendor networks with direct storm-response deployment authority in Florida and Texas.
- Roofing Contractors:Traditional service providers face margin compression as carriers bypass intermediaries, forcing differentiation through repair-integration capabilities.
- Property Managers:Portfolio-scale operators centralize inspection scheduling across multi-state commercial assets.
- Construction Firms:New-build quality assurance and warranty documentation drive pre-occupancy survey adoption.
- Facility Supervisors:In-house maintenance teams at industrial campuses acquire entry-level platforms for routine condition monitoring.
Insurance Companies now lead segment expansion, with Property Managers showing the steepest adoption trajectory among traditional buyer categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping fleet deployment patterns as operators migrate toward jurisdictions with streamlined airspace access and lower certification burdens. The United States retains operational density leadership, while Germany and Australia emerge as alternative bases for cross-regional service networks.
United States
Storm-damage assessments and solar-installation surveys drive concentrated demand across Texas, Florida, and Oklahoma. FAA Part 107 mandates standardize pilot competency requirements while compressing liability exposure for carrier-contracted inspection networks. Dallas-Fort Worth and Tampa Bay metropolitan areas anchor rapid-response fleet positioning for insurance documentation surges.
Germany
Industrial rooftop mapping for engineering firms and solar developers sustains premium LiDAR service demand. EASA open-category frameworks harmonize operational rules across EU member states, enabling centralized fleet management from German operations centers. The Ruhr industrial corridor and Bavarian manufacturing zones concentrate high-accuracy inspection procurement.
United Kingdom
Commercial building portfolios in London and Manchester accelerate drone-based assessment protocols for high-rise environments. Civil Aviation Authority regulations align with EASA trajectory while maintaining distinct operational authorization pathways. The Southeast England property management cluster drives subscription-based inspection scheduling adoption.
Australia
Bushfire-damage documentation and rural agricultural facility inspections expand addressable use cases beyond urban roofing. Civil Aviation Safety Authority regulations permit extended-range operations across low-density airspace with reduced coordination overhead. Queensland and New South Wales coastal regions concentrate storm-response contractor networks.
Canada
Cold-climate infrastructure monitoring and remote industrial site access drive specialized thermal-sensor deployment. Transport Canada drone regulations mandate pilot certification while permitting beyond-visual-line-of-sight trials in designated corridors. Alberta oil-sands facilities and Ontario commercial portfolios anchor enterprise inspection contracts.
Drone Roof Inspection Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with software-integrated platforms commanding premium positioning against hardware-only fleet operators. The vendor base concentrates among three archetypes: residential inspection software integrators, thermal-imaging service specialists, and AI-enabled damage detection platforms. Consolidation pressure intensifies as national insurance carriers bypass contractor intermediaries for direct vendor contracting. Dominant competitive moves include strategic partnerships with carrier networks and vertical integration into report-generation software.
Within the AI-analytics tier, FlyPix AI exemplifies computer-vision convergence for automated damage classification. Thermal-imaging specialization is anchored by DroneAdair, Inc., which occupies a position serving insurance adjuster workflows. Residential software integration is represented by Loveland Innovations, sitting within the contractor-facing platform segment. These three companies illustrate the strategic archetype fragmentation shaping procurement authority shifts.
| Leading Market Players |
|---|
| American Drone Industries |
| Air America Aerial Imagery & Analytics |
| FlyPix AI |
| Drone America |
| ISight Drone Services |
| Drones and Homes LLC |
| Action Drone USA |
| DroneAdair, Inc. |
| Loveland Innovations |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between Part 107-compliant operators and uncertified contractors manifests in both pricing power and component sourcing strategies. Premium service tiers command hardware investments in FLIR thermal modules and LiDAR payloads from Japanese and German suppliers, while economy segments rely on photogrammetry-only configurations with concentrated Chinese camera array sourcing.
Pricing Analysis
Distributor margins on thermal sensor hardware compress direct-to-OEM pricing advantages for fleet operators above fifty units. Three-tier pricing structure across premium, standard, and economy levels reflects payload sophistication, with LiDAR-enabled inspections commanding multiples of photogrammetry baselines. Cost compression in the economy tier is intensifying because insurance carriers now mandate thermal documentation, forcing hardware refresh cycles. Roofing contractors exhibit highest price sensitivity, while national insurance carriers prioritize vendor network certification over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for multi-rotor platforms, bypassing regional distributor markups. Component manufacturing concentrates in China for airframes, Japan for high-resolution thermal sensors, and Germany for precision LiDAR modules. Raw material dependencies include lithium-ion cells, rare-earth magnets for brushless motors, and specialized optical glass. Single-source vulnerability in thermal sensor procurement from Japanese suppliers exposes fleet operators to allocation constraints during peak storm seasons. Distribution runs through certified pilot training networks and insurance carrier vendor qualification programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in drone roof inspection rests on automated report generation reducing analyst labor intensity, while LiDAR premiumization shifts contract values upward in commercial solar development.
For Market Incumbents: Deploy computer-vision software integration to differentiate against hardware-only fleet operators facing carrier direct-contracting displacement. Consolidate position through backward integration into pilot certification pipelines, addressing FAA Part 107 testing backlogs that constrain qualified operator availability. Thermal-sensor standardization by national carriers threatens photogrammetry-only service tiers with obsolescence. For New Entrants and Emerging Players: The premium-to-economy price-point gap in thermal-equipped versus camera-only inspections creates entry opportunity in underserved agricultural facility and rural warehouse segments. Target storm-response subcontracting relationships with established carrier networks in Oklahoma and coastal Florida counties where rapid deployment capacity remains constrained. Lead with subscription-based inspection scheduling to lock recurring revenue streams and reduce customer acquisition costs against transactional bidders. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-enabled damage detection platforms possessing trained computer-vision models on proprietary roof-condition datasets. Long-term viability favors vendors with software-integrated platforms over hardware-only fleet operators facing margin compression. Monitor EASA open-category implementation timelines across German and French regulators as inflection indicator for European market entry scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Computer-vision analytics from FlyPix AI automates damage classification for insurance adjusters. |
| Strategic Partnership | Direct carrier contracting bypasses roofing contractor intermediaries in Florida and Texas storm corridors. |
| Geographic Expansion | EASA open-category frameworks enable centralized fleet management from German operations centers. |
| Acquisition of Specialist Firm | Thermal-imaging service specialists like DroneAdair anchor insurance adjuster workflow integration. |
| Product Launch | Hybrid VTOL systems combine multi-rotor precision with fixed-wing range for mixed urban-suburban routes. |
Research Methodology
Bottom-up insurance carrier and roofing contractor modeling reconciled against top-down hardware shipment and pilot certification tracking forms the analytical core. Primary interviews with FAA-certified drone operators, insurance claims managers, solar development engineers, and roofing contractor fleet managers combined with secondary validation against FAA Part 107 certification databases, EASA regulatory filings, and customs records for thermal sensor and LiDAR module imports. Triangulation across these sources ensures segmentation integrity.
Input-output matrices map drone platform deployments by payload configuration against end-use application requirements and regulatory compliance tiers across the projection horizon. Segmentation dimensions include platform architecture, sensor technology, building typology, and procurement authority shifting from contractor to carrier. CAGRs derive from installation base expansion rates and service pricing trajectories. Forecast inputs incorporate storm frequency patterns in designated catastrophe corridors and solar deployment schedules in state renewable portfolios.
Caveats apply where pending FAA beyond-visual-line-of-sight rulemakings or lithium-ion raw material price volatility could materially shift the outlook. Forecasts reflect base-case assumptions regarding regulatory harmonization timelines and carrier technology mandate adoption curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Bubble Drone Market
UAV
North America Tactical UAV Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Industrial Drones Market
UAV
Drone Camera Market
UAV
Drone Flight Controller System Market
UAV
Auto-Follow Drone Market
UAV
FPV Drone Goggles Market
UAV
Racing Drone Market
UAV
North America Small UAV Market
UAV
Miniature Drone Market
UAV
UAV Drones Market
UAV
Electric Glider Market
UAV
Global Drone Sensor Market
UAV
Drones Market