
 Electronic Flight Instrument System Market | 2026-2036
Electronic Flight Instrument System Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Flight Instrument System Market Analysis
The EU Green Deal's aviation decarbonization targets are expanding pressure on fleet operators to upgrade legacy analog cockpits with lighter, more efficient digital interfaces. Honeywell International Inc. leverages its integrated flight deck architecture to anchor retrofit contracts across narrow-body platforms. Garmin Ltd. competes through specialized solutions in the general aviation segment, where owner-operators demand cost-effective glass cockpit transitions. Thales dominates European line-fit programs through its sustained R&D commitments to open-architecture avionics.
An Electronic Flight Instrument System comprises integrated digital displays that consolidate flight, navigation, engine, and warning data through redundant data buses and certified graphics processors, replacing electromechanical gauges to reduce pilot workload and instrument scan time. Primary Flight Display installations lead the product type category due to their role as the central attitude reference in both retrofit and new aircraft configurations, while Virtual Cockpit technology represents the fastest-growing technology segment as military and next-generation commercial programs demand immersive, reconfigurable interfaces. Engine Indication systems retain mature margin pools in regional turboprop and helicopter applications where powerplant monitoring remains critical.
The FAA's Part 25 airworthiness standards and EASA's CS-25 certification requirements shape product development timelines by mandating fault tolerance, display legibility under sunlight conditions, and software assurance levels per DO-178C. China's CAAC aligns with these frameworks through its own certification reciprocity agreements, though GB standards for avionics integration create additional testing protocols for suppliers. Stakeholders must monitor evolving cybersecurity mandates from regulators and assess whether their supply chains can accommodate dual-sourcing requirements for critical display components.
Market Dynamics
Fleet modernization mandates from the FAA and EASA are forcing operators to retire electromechanical flight instruments before airframe end-of-life, compressing replacement cycles and concentrating procurement authority with airline technical directors rather than maintenance shops.
Growth Catalysts
- Synthetic Vision Mandates:FAA terrain awareness protocols require enhanced flight vision systems in Part 121 operations, pulling forward display upgrades across narrow-body fleets.
- EU Green Deal Aviation Targets:Weight reduction incentives for digital cockpits align with carbon intensity benchmarks, accelerating glass retrofit programs in European short-haul networks.
- China's CAAC Reciprocity Framework:Harmonized certification with EASA CS-25 standards reduces requalification costs for imported avionics, expanding supplier access to Chinese MRO channels.
Market Restraints
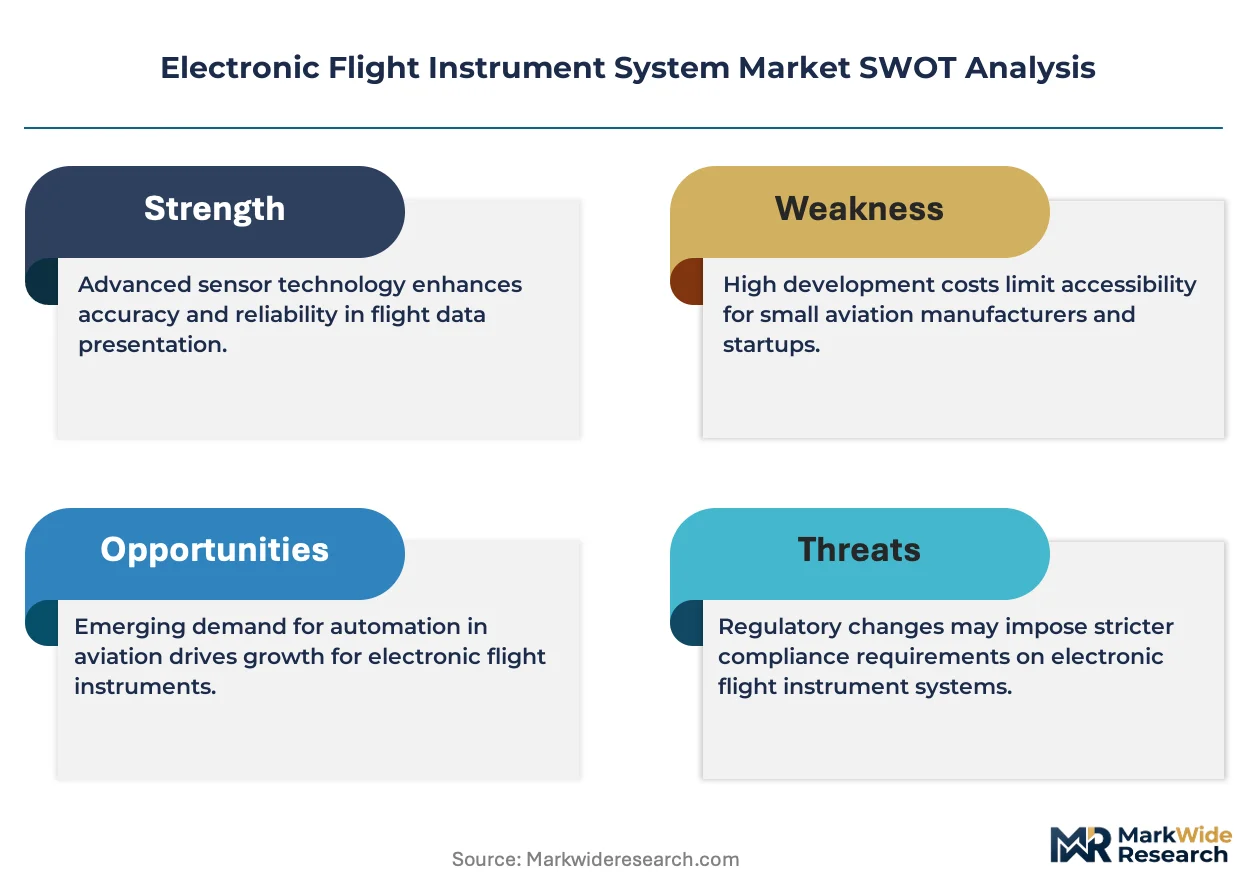
- Indium Supply Concentration:LCD backlight fabrication depends on indium tin oxide feedstock concentrated in Chinese refining operations, exposing display manufacturers to export quota volatility.
- DO-178C Compliance Burden:Software assurance Level A requirements for primary flight displays extend development timelines by 18-24 months versus commercial embedded systems.
- Electromechanical Gauge Longevity:Analog attitude indicators in legacy turboprops operate beyond 50,000 flight hours with minimal maintenance, delaying replacement economics for regional operators.
Strategic Opportunities
- Urban Air Mobility Cockpits:eVTOL platforms require reconfigurable touchscreen architectures without mechanical backup, opening greenfield specification battles absent incumbent lock-in.
- India's UDAN Regional Connectivity:Subsidized turboprop acquisitions under the government's regional aviation scheme create first-mover advantage for integrated flight deck suppliers.
- ARINC 653 Partitioning Convergence:Consolidation of safety-critical and non-critical functions onto shared multicore processors enables hardware cost reduction while maintaining isolation certification.
Industry Challenges
- DO-254 Hardware Verification Talent:FPGA design for graphics processing units requires engineers with both aviation certification experience and semiconductor verification skills, a combination scarce outside Texas and Toulouse clusters.
- Legacy Bus Integration Complexity:ARINC 429 and MIL-STD-1553 data architectures in aging airframes demand protocol bridge development that consumes 30% of retrofit engineering hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Flight Instrument System Market |
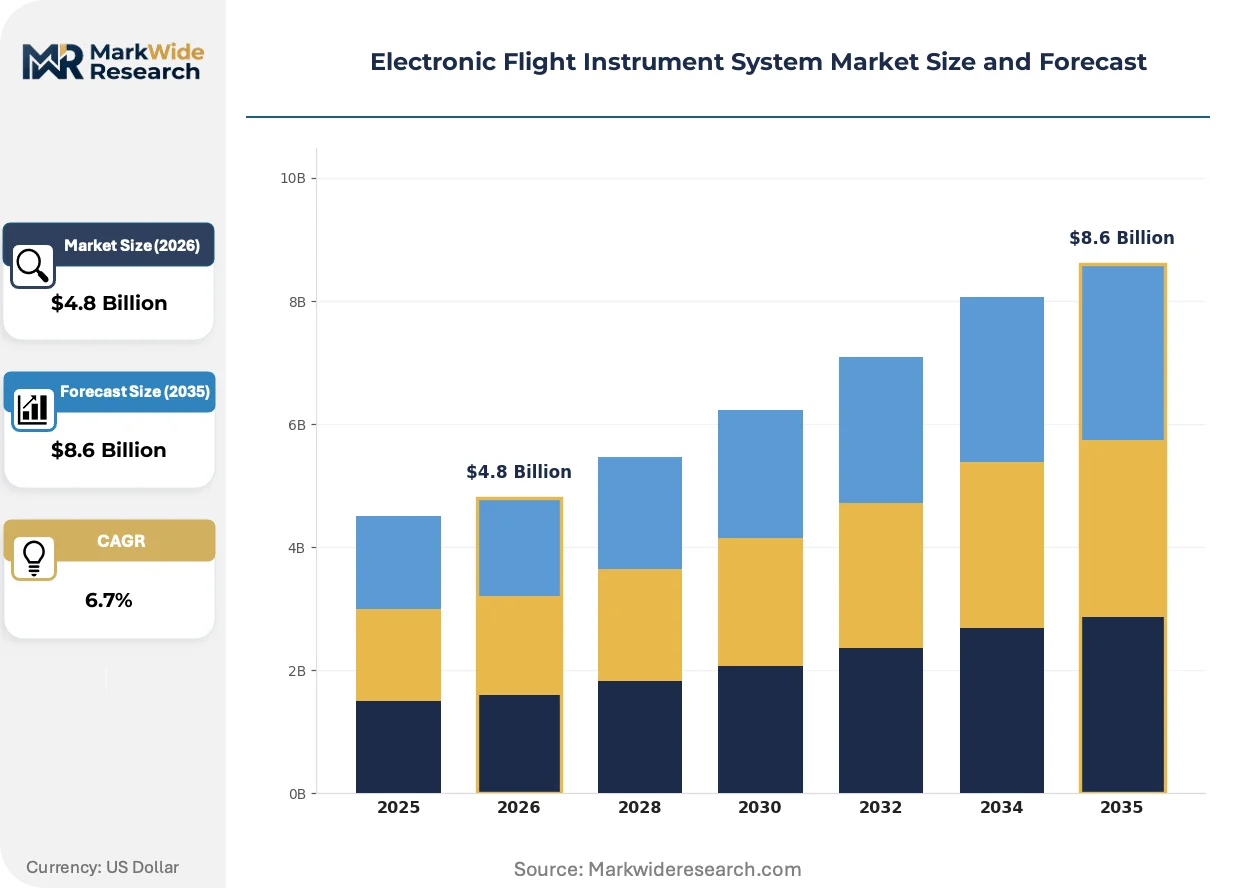
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Primary Flight Display, Multi-Function Display, Engine Indication, Attitude Indicator Technology: LCD, LED, OLED, Virtual Cockpit End User: Commercial Aviation, Military Aviation, General Aviation, UAV Installation Type: Retrofit, Line Fit, Modular, Embedded |
| Companies Covered | Honeywell International Inc., Raytheon Technologies Corporation, Garmin Ltd., Thales, L3Harris Technologies Inc., BAE Systems, Astronautics Corporation of America, General Electric Company, Aspen Avionics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Flight Instrument System Market Emerging Trajectories
Avionics architecture is converging toward consolidated computing platforms that replace federated line-replaceable units with modular software-defined functions, compressing hardware variety while expanding upgrade flexibility through over-the-air parameter loads.
Active matrix organic light-emitting diode (AMOLED) display technology is integrating high-contrast, wide-viewing-angle panels into military trainer and business jet applications where night vision goggle compatibility is mandatory. Gulfstream and Dassault Falcon operators are specifying these displays for retrofit programs beginning in 2024, citing sunlight readability improvements over legacy AMLCD units. The technology is integrating attitude and navigation symbology with sensor fusion overlays that previously required separate head-up display hardware.
EASA's CS-25 Amendment 25-148 introduces cybersecurity airworthiness objectives mandating threat assessment and mitigation verification for connected flight deck systems. The regulation requires suppliers to demonstrate isolation between safety-critical display functions and passenger connectivity networks, affecting architecture choices for integrated modular avionics. European line-fit programs at Airbus and ATR are responding by segregating graphics processor domains through hardware-enforced virtualization.
Airline procurement directors are consolidating avionics purchasing under fleet-wide lifecycle contracts that bundle initial installation, warranty extension, and predictive maintenance analytics. Lufthansa Technik and ST Engineering have displaced traditional distributor channels for narrow-body retrofits in Europe and Southeast Asia, capturing margin through volume commitments and technical support integration. The shift is most visible in single-aisle Boeing 737 and Airbus A320 programs where display commonality across 50+ aircraft unlocks spare pooling economics.
Electronic Flight Instrument System Market Segmentation
Electronic Flight Instrument System procurement patterns diverge sharply across operator types, with airline fleet directors prioritizing commonality and MRO integration while military buyers emphasize reconfigurability and night vision compatibility. Technology selection cascades through certification burden, supply chain availability, and retrofit versus greenfield installation economics.
Product Type:
Airline technical directors select display categories based on airworthiness criticality tiers and replacement cycle timing, with primary attitude references commanding capital allocation priority over supplementary information panels.
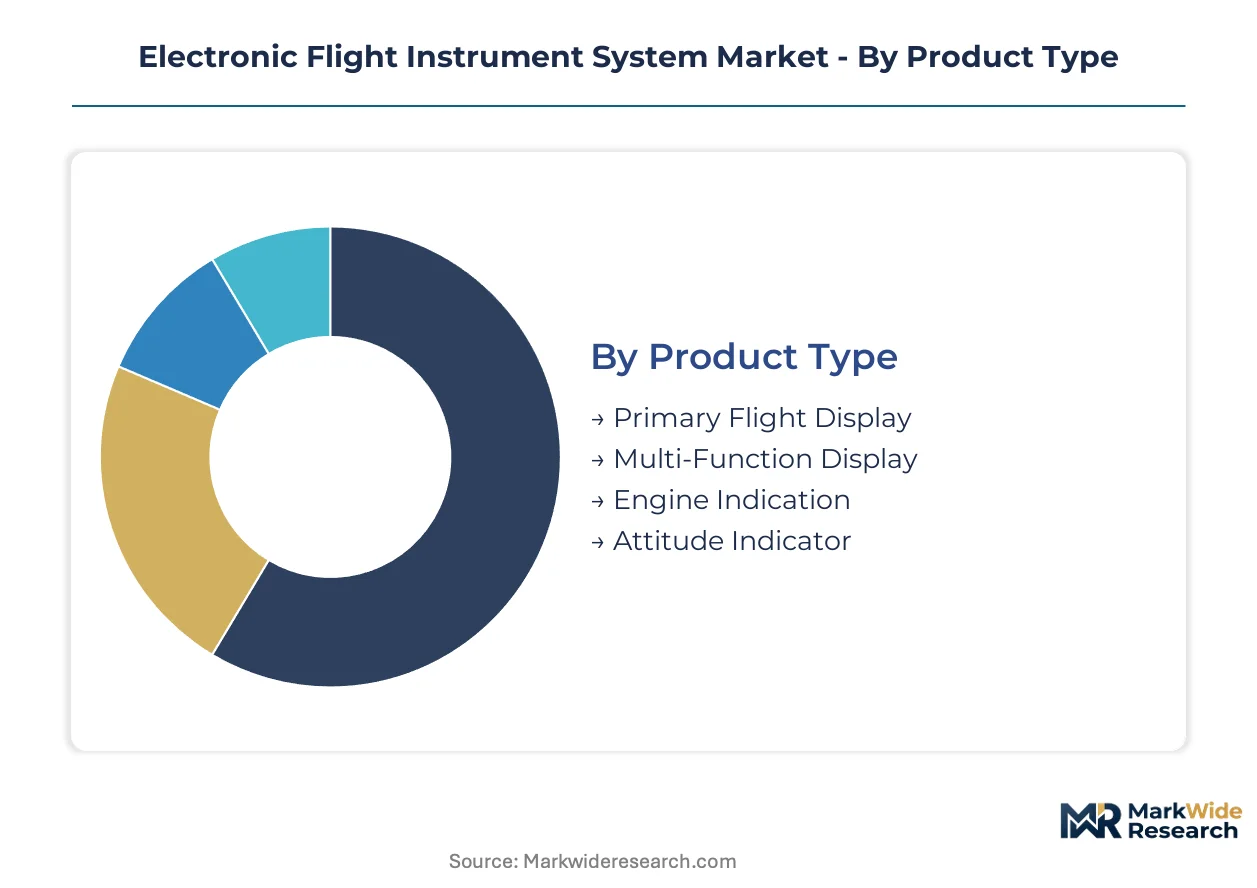
- Primary Flight Display:Central attitude reference integrating airspeed, altitude, heading, and vertical speed through certified graphics processors. Narrow-body retrofit programs across the United States, Germany, and China concentrate procurement here as operators phase out electromechanical gyroscopic instruments before regulatory deadlines.
- Multi-Function Display:Secondary panel consolidating navigation, weather radar, and traffic collision data through software-defined page selection. Regional turboprop operators in European short-haul networks prioritize these units for weight reduction compliance with EU Green Deal aviation benchmarks.
- Engine Indication:Powerplant parameter monitoring for turbine temperature, oil pressure, and vibration. Helicopter and regional aircraft applications retain steady replacement demand due to continuous engine monitoring requirements.
- Attitude Indicator:Standalone backup attitude reference for degraded primary display scenarios. Military trainer specifications and legacy business jet retrofits sustain niche procurement volumes.
Primary Flight Display leads volumes today; Virtual Cockpit technology (captured under Technology segmentation) is gaining share fastest through next-generation commercial and military programs.
Technology:
Display fabrication choices reflect trade-offs between sunlight readability, night vision goggle compatibility, and indium supply chain exposure from Chinese refining concentration.
- LCD:Dominant backlight technology using indium tin oxide transparent conductors and cold-cathode or LED edge lighting. Retrofit programs across aging narrow-body fleets specify LCD-based Primary Flight Displays for supply chain security and established DO-178C certification pathways.
- LED:Solid-state backlighting with improved luminance stability and reduced power draw. Regional aviation operators in India's UDAN-subsidized turboprop acquisitions specify LED-illuminated displays for operating cost reduction.
- OLED:Active matrix organic light-emitting diode panels delivering high contrast and wide viewing angles without backlight layers. Business jet and military trainer specifications in France and the United States integrate AMOLED for night vision goggle compatibility.
- Virtual Cockpit:Reconfigurable software-defined interfaces replacing physical displays with immersive, adaptable symbology. eVTOL platform developers and next-generation fighter programs specify these architectures to eliminate mechanical backup instruments entirely.
LCD captures the largest installed base; Virtual Cockpit exhibits the steepest expansion trajectory as urban air mobility and sixth-generation military programs advance.
End User:
Procurement authority structures diverge across operator categories, with commercial airline fleet directors consolidating volume contracts while general aviation owner-operators prioritize cost-effective single-aircraft upgrades.
- Commercial Aviation:Part 121 and Part 135 operators mandating synthetic vision and terrain awareness compliance. FAA terrain awareness protocols pull forward display upgrades across Boeing 737 and Airbus A320 fleets.
- Military Aviation:Defense procurement offices specifying mission reconfigurability and threat-resilient architectures. Night vision goggle compatibility and cybersecurity airworthiness per EASA CS-25 Amendment 25-148 drive specification requirements.
- General Aviation:Owner-operators and flight schools transitioning from steam gauge to glass cockpit configurations. Garmin and Aspen Avionics compete through certified cost-effective retrofit pathways for Cessna and Piper airframes.
- UAV:Unmanned platform developers requiring ground control station displays and optionally piloted vehicle interfaces. Beyond-visual-line-of-sight regulations shape display redundancy and control link requirements.
Commercial Aviation dominates current procurement volumes; UAV applications are climbing the fastest as regulatory frameworks mature for autonomous operations.
Installation Type:
Engineering resource allocation and certification pathway selection hinge on whether displays integrate during original airframe manufacture or replace legacy instruments in operational aircraft.
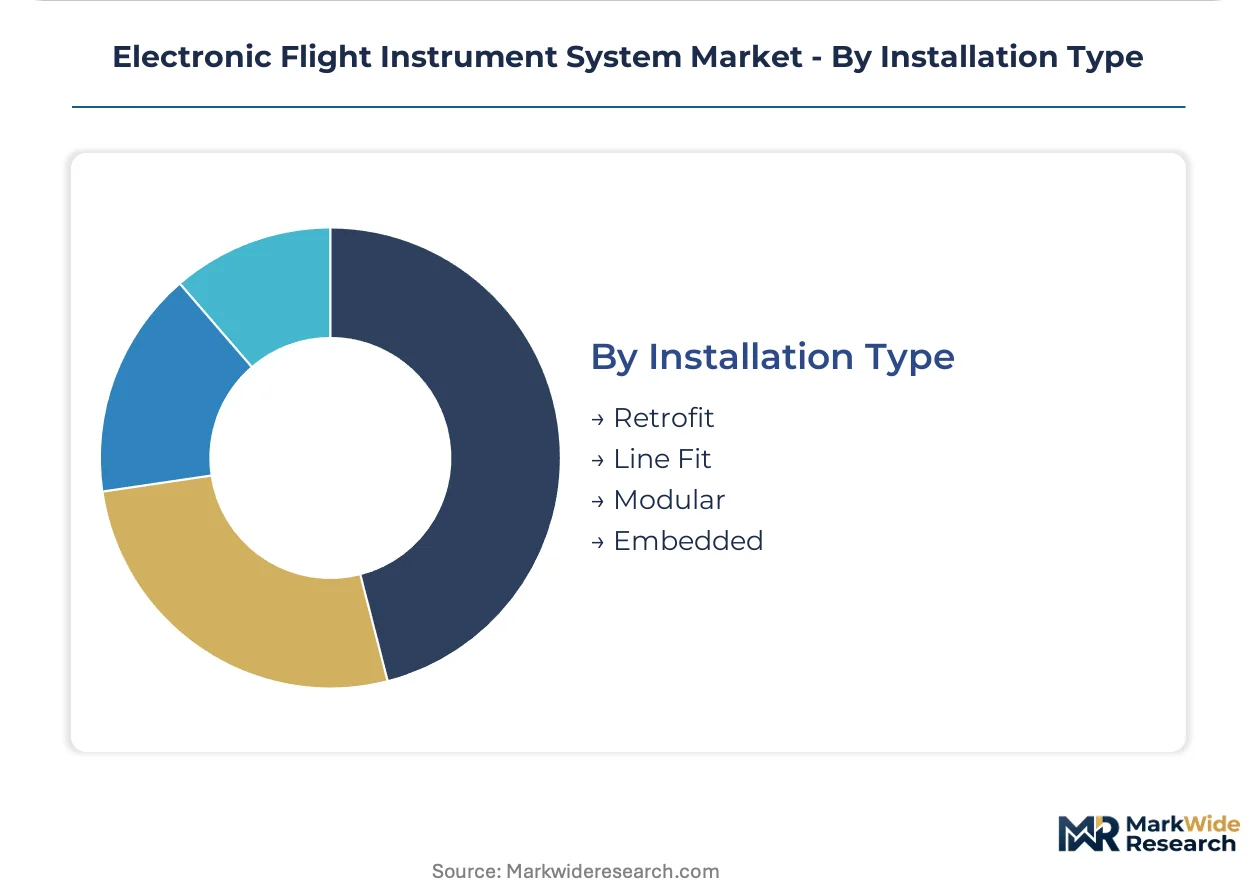
- Retrofit:Replacement of electromechanical gauges in operational aircraft through supplemental type certificate pathways. ARINC 429 and MIL-STD-1553 protocol bridge development consumes substantial engineering hours in aging airframe programs.
- Line Fit:Factory installation during original equipment manufacture with integrated modular avionics architectures. Airbus and ATR production lines in Toulouse consolidate purchasing through fleet-wide lifecycle contracts.
- Modular:Self-contained display units with standardized mechanical and electrical interfaces enabling field replacement. Regional operators prioritize modularity for AOG minimization and spare pooling economics.
- Embedded:Graphics processing functions integrated into consolidated computing platforms rather than discrete line-replaceable units. Next-generation avionics architectures employ multicore processors with ARINC 653 partitioning.
Retrofit commands immediate revenue concentration; Line Fit is expanding most quickly through production rate recovery at major airframe manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electronic flight instrument systems trace their commercial lineage to United States aerospace manufacturing clusters that pioneered glass cockpit technology during the 1980s. FAA certification frameworks established at that time continue shaping global product specifications. Regional demand patterns now reflect divergent fleet modernization timelines across major aviation markets.
United States
Narrow-body retrofit programs at American, Delta, and United Airlines drive procurement volumes as Part 121 operators phase out electromechanical gyroscopic instruments before FAA terrain awareness deadlines. The FAA's synthetic vision mandates for commercial operations compress replacement cycles. Dallas-Fort Worth and Seattle-Tacoma clusters concentrate avionics integration facilities serving domestic MRO networks.
Germany
Lufthansa Technik consolidates European retrofit purchasing through fleet-wide lifecycle contracts covering Boeing 737 and Airbus A320 display commonality. EU Green Deal aviation decarbonization targets incentivize weight reduction through digital cockpit upgrades. Hamburg and Munich house the continent's densest concentrations of EASA-certified avionics engineering talent.
China
CAAC certification reciprocity with EASA CS-25 standards reduces requalification costs for imported avionics, expanding supplier access to Chinese MRO channels. COMAC C919 production ramp-up creates line-fit demand for integrated flight deck architectures. Shanghai and Tianjin clusters specialize in display module assembly for both commercial and military programs.
France
Airbus and ATR production lines in Toulouse anchor European line-fit procurement through sustained R&D commitments to open-architecture avionics. EASA CS-25 Amendment 25-148 cybersecurity mandates reshape supplier qualification requirements. The Occitanie region hosts specialized graphics processor design teams serving military trainer specifications.
India
UDAN regional connectivity subsidies accelerate turboprop acquisitions, creating first-mover advantage for integrated flight deck suppliers targeting ATR-72 and Bombardier Q400 platforms. DGCA alignment with ICAO standards streamlines supplemental type certificate pathways. Bangalore and Hyderabad clusters develop software verification capabilities for ARINC 653 partitioning implementations.
Electronic Flight Instrument System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification burden and integration complexity. The vendor base organizes into three tiers: integrated flight deck architects owning narrow-body line-fit contracts, specialized retrofit suppliers capturing general aviation transitions, and modular display fabricators serving regional turboprop niches. Consolidation pressure intensifies as airline procurement directors centralize purchasing authority. Dominant competitive moves include strategic partnerships for multicore processor development and backward integration into graphics processing unit design.
Among United States-based diversified aerospace conglomerates, Honeywell International Inc. and Raytheon Technologies Corporation exemplify integrated flight deck architects with sustained retrofit contract positions. Garmin Ltd. occupies a distinct tier serving owner-operator general aviation segments where cost-effective glass cockpit transitions predominate. Thales represents European open-architecture specialists securing line-fit commitments through Toulouse-based engineering proximity.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Raytheon Technologies Corporation |
| Garmin Ltd. |
| Thales |
| L3Harris Technologies Inc. |
| BAE Systems |
| Astronautics Corporation of America |
| General Electric Company |
| Aspen Avionics |
| Others |
Supply Flow & Price Mechanics
Backward integration into graphics processing unit design anchors both supply security and pricing power for avionics suppliers serving FAA Part 25 and EASA CS-25 certification pathways. Captive semiconductor fabrication in Texas and Toulouse clusters insulates tier-one integrators from indium supply volatility while commanding premium positioning against modular display fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification burden and integration depth. Premium tiers capture DO-178C Level A primary flight displays with fault-tolerant architectures; standard tiers address multi-function displays for regional turboprops; economy tiers serve attitude indicator retrofits in general aviation. Cost compression in the standard tier intensifies as airline procurement directors consolidate fleet-wide lifecycle contracts. Regional operators in India's UDAN-subsidized acquisitions exhibit highest price sensitivity; military buyers specifying night vision goggle compatibility show lowest sensitivity.
Supply Chain Analysis
Regional distribution centers in Dallas-Fort Worth, Hamburg, and Shanghai orchestrate hub-and-spoke patterns for line-replaceable units. Indium tin oxide feedstock concentrates in Chinese refining operations; graphics processor silicon sources from Taiwan and South Korea; certified display assembly localizes in Germany and the United States. Single-source vulnerability in indium supply exposes manufacturers to export quota volatility. Distribution runs through airline MRO networks and airframe OEM production lines with spare pooling economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EASA CS-25 certification reciprocity with China's CAAC reduces requalification costs against stricter FAA pathway expenses in the United States.
For Market Incumbents: To counter emerging modular display fabricators from Asia, Honeywell and Thales should deepen captive GPU design in Toulouse and Phoenix clusters while securing exclusive line-fit commitments at COMAC and Airbus production lines. Certification investment in ARINC 653 multicore partitioning maintains technical moats against software-defined challengers. For New Entrants and Emerging Players: Owner-operators in general aviation represent an underserved buyer archetype where Garmin's dominance leaves gaps in cost-effective glass cockpit transitions for legacy Piper and Cessna airframes. India's UDAN-subsidized regional turboprop acquisitions offer penetrable volume entry. Partnership with Bangalore software verification shops enables ARINC 653 compliance without Toulouse talent premiums. For Investors and Strategic Acquirers: Roll-up economics work for specialized retrofit suppliers because airline procurement director consolidation displaces traditional distributor channels and rewards technical support integration. Targets with EASA-certified engineering teams in Hamburg or Munich command scarcity premiums. Watch for eVTOL platform development milestones as inflection indicators for virtual cockpit technology adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Multicore Processor Certification Investment | ARINC 653 partitioning enables hardware cost reduction while maintaining DO-178C isolation requirements. |
| Backward Integration into GPU Design | Captive graphics processing eliminates dependency on external semiconductor suppliers for primary flight displays. |
| Fleet-Wide Lifecycle Contracting | Lufthansa Technik and ST Engineering capture margin through bundled installation, warranty, and predictive maintenance. |
| Urban Air Mobility Cockpit Development | eVTOL platforms require reconfigurable touchscreen architectures without mechanical backup instruments. |
| Regional MRO Channel Partnership | CAAC-EASA reciprocity agreements expand supplier access to Chinese maintenance networks. |
Methodological Framework
Coverage spans the United States, Germany, China, France, and India, with primary inputs from each market cluster. The analysis combines structured interviews with airline fleet directors, avionics integration engineers, EASA certification specialists, and MRO procurement managers with secondary validation through FAA type certificate databases, EASA CS-25 amendment records, and airframe OEM production disclosures. Bottom-up triangulation across product type volumes and top-down reconciliation against fleet modernization schedules ensures consistency.
Granularity extends to individual display categories, technology fabrication methods, and installation type economics across the projection horizon. Segmentation dimensions include product criticality tier, certification burden level, and retrofit versus line-fit pathway. CAGRs derive from fleet replacement cycle modeling and regulatory deadline impacts. Forecast inputs incorporate CAAC-EASA reciprocity progression and indium supply quota trajectories.
Underlying measurement precision varies by segment; primary flight display volumes carry tighter precision than virtual cockpit projections given program immaturity. Forecasts reflect documented assumptions around certification timeline adherence and supply chain continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Avionics
Temperature Sensor in the Aerospace & Defense Market
Avionics
Commercial Aircraft Avionics Systems Market
Avionics
Europe Aircraft Avionics Market
Avionics
Europe Commercial Aircraft in-Flight Entertainment System Market
Avionics
Aircraft EMI Shielding Market
Avionics
Military Aircraft Avionics Market
Avionics
Display for Avionics Application Market
Avionics
Middle East Commercial Aircraft in-Flight Entertainment System Market
Avionics
Global Avionics Market
Avionics
Global Helicopter Avionics Market
Avionics
Asia-Pacific Semiconductor in Military and Aerospace Market
Avionics
Military Avionic Systems Market
Avionics
Asia-Pacific Aircraft Health Monitoring System Market
Avionics
Aircraft Computers Market
Avionics
Europe Military Aircraft Communication Avionics Market
Avionics
Asia-Pacific Aircraft Avionics Market