
 Space Battery Market | 2026-2036
Space Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Space Battery Market Intelligence
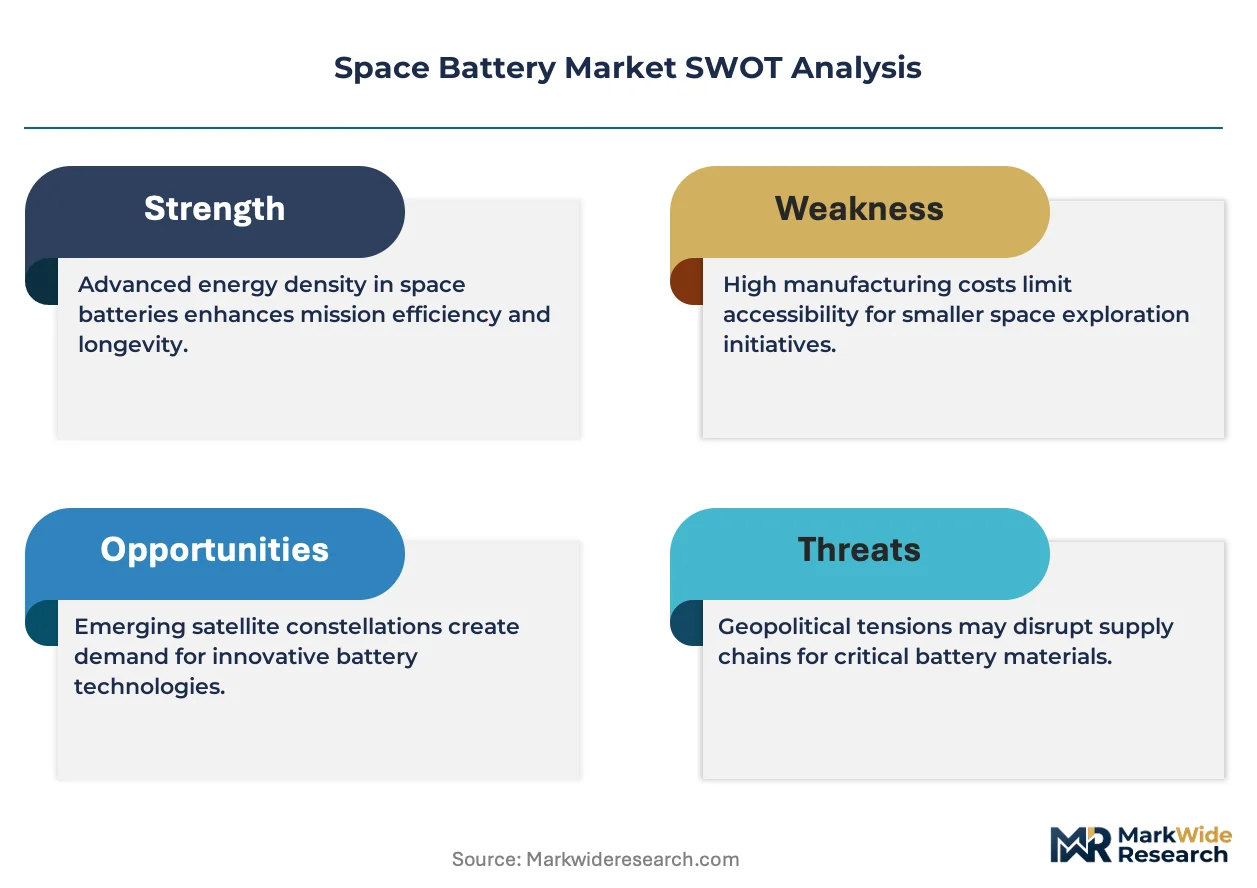
The capability gap between vertically integrated battery manufacturers and system integrators is collapsing as cell performance becomes more standardized. Saft Groupe SA leverages its extensive heritage in high-reliability cell production for long-duration missions. EaglePicher Technologies specializes in custom power solutions for defense and critical space applications. In contrast, GS Yuasa Corporation differentiates with its lithium-ion technologies developed for both automotive and aerospace sectors.
A space battery is an electrochemical energy storage device engineered for the extreme temperature, vacuum, and radiation conditions of space. It powers satellite subsystems, like communication systems, during eclipse periods when solar panels are not generating electricity. Lithium-ion chemistries lead in new satellite programs for their energy density, with the Low Earth Orbit class being the most dynamic orbital segment. Procurement from commercial satellite operators now outpaces that of traditional government agencies.
Product qualification is governed by stringent standards from space agencies like NASA in the United States and the European Space Agency. These regulations mandate extensive testing for radiation hardness and thermal cycling, directly influencing battery design and material selection. Stakeholders must now balance the pursuit of higher specific energy with the long-term reliability required for multi-year missions in increasingly crowded orbits.
Market Dynamics
The primary structural force shaping the space battery market is the demand inversion from government-led, long-duration missions to commercially driven, high-volume satellite constellations. This shift prioritizes manufacturability and cost-efficiency alongside traditional performance metrics like radiation hardness.
Growth Catalysts
- LEO Constellation Deployment:The rapid build-out of large-scale Low Earth Orbit satellite networks for global broadband internet access creates a high-volume, recurring demand for standardized battery modules.
- Solid-State Technology Advancement:Research into solid-state chemistries promises significant gains in specific energy and operational lifespan, attracting investment from both government agencies and private ventures seeking next-generation power solutions.
- National Space Exploration Programs:Renewed government investment in deep space missions, lunar exploration, and planetary science, particularly from NASA in the United States and ESA in Europe, fuels demand for highly reliable, long-life power systems.
Market Restraints
- Stringent Qualification Standards:The extensive and costly testing protocols mandated by space agencies like NASA and the European Space Agency create high barriers to entry and lengthen development timelines, slowing the introduction of new technologies.
- Critical Material Supply Chains:The supply of space-grade lithium, cobalt, and other high-purity materials is concentrated in a few geographic regions, exposing manufacturers to price volatility and geopolitical supply risks.
- Inherent Performance Trade-offs:Battery design is constrained by a fundamental conflict between maximizing energy density for performance and ensuring the robustness and longevity required to survive years of thermal cycling and radiation exposure in orbit.
Strategic Opportunities
- Emerging Deep Space Applications:Developing power systems for future lunar surface infrastructure, Martian rovers, and long-duration interplanetary probes represents a significant opportunity for specialized, high-performance battery technologies.
- Modular Battery Architectures:Creating standardized, scalable battery modules that can be configured for various satellite bus sizes and mission profiles allows manufacturers to reduce non-recurring engineering costs and serve a wider customer base. *New Entrant Space Programs: The growth of national space agencies in countries such as India, the United Arab Emirates, and South Korea creates new geographic markets for battery suppliers able to meet specific national requirements.
Industry Challenges
- Supply Chain Security:Ensuring a consistent and secure supply of radiation-hardened electronic components and high-purity electrochemical materials is a major operational challenge amid global semiconductor shortages and trade restrictions.
- Qualification Bottlenecks:The limited availability of specialized testing facilities capable of simulating the space environment creates bottlenecks, delaying mission schedules and increasing program costs for satellite manufacturers.
- Systems Engineering Talent Gap:A shortage of engineers with dual expertise in advanced battery chemistry and aerospace systems integration complicates the development of optimized power subsystems for complex satellites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Battery Market |
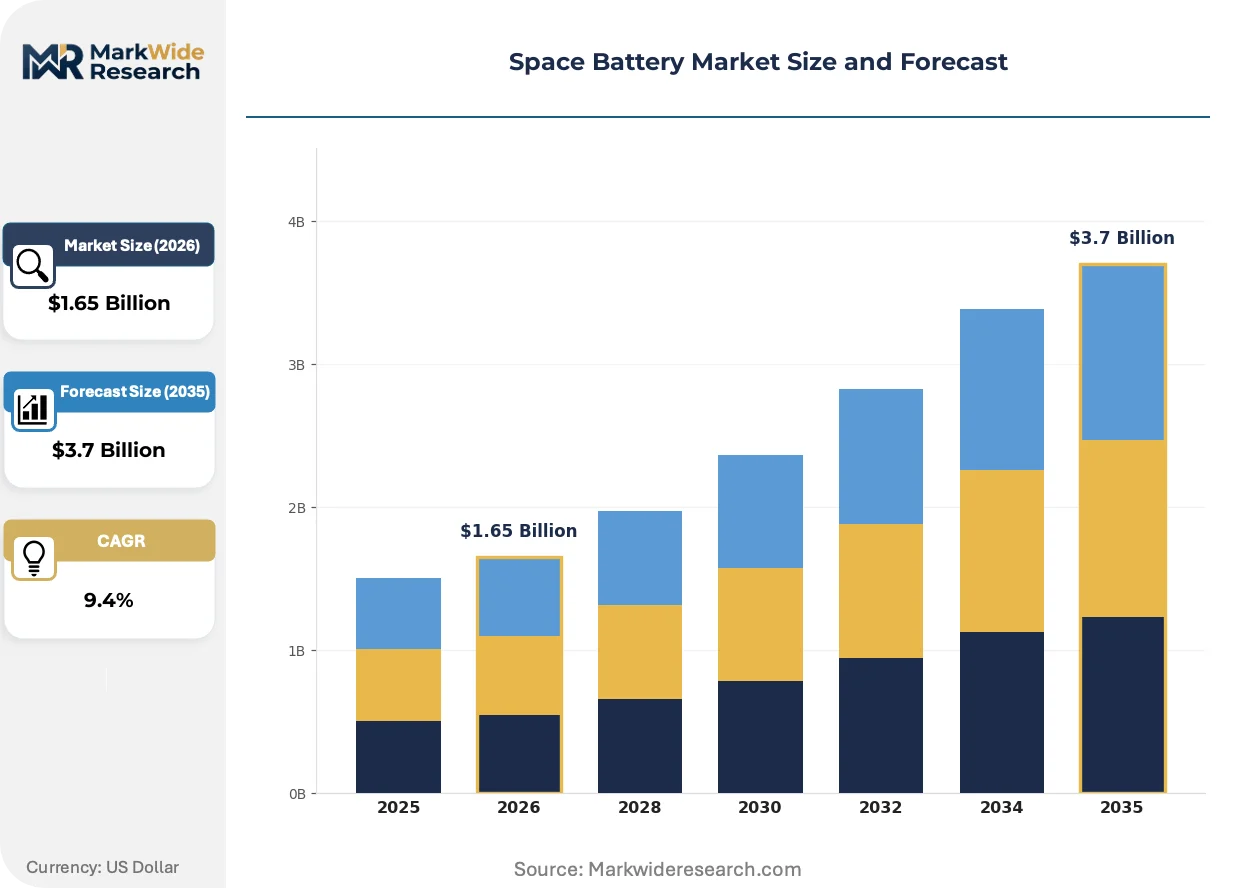
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $3.7 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Battery Chemistry: Lithium-Ion, Nickel-Hydrogen, Silver-Zinc, Lithium-Polymer, Nickel-Cadmium Application: Satellites, Space Probes, Space Stations, Unmanned Aerial Vehicles, Communication Systems Orbital Class: Low Earth Orbit, Medium Earth Orbit, Geostationary Orbit, Highly Elliptical Orbit, Lunar Orbit End User: Government Agencies, Commercial Satellite Operators, Research Institutions, Defense Contractors, Space Exploration Firms |
| Companies Covered | Saft Groupe SA, EaglePicher Technologies, GS Yuasa Corporation, EnerSys, Mitsubishi Electric Corporation, Arotech Corporation, ABSL Space Products, VARTA AG, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Battery Market Strategic Shifts & Innovations
The competitive landscape is being redefined by the dual requirements of commercial volume production and mission-critical reliability. This pressure forces innovation in cell chemistry, manufacturing processes, and business models to serve a diversifying customer base.
Solid-state battery technology, which uses a solid electrolyte instead of a liquid one, offers a pathway to significantly higher energy density and enhanced safety. Commercial LEO constellation operators are aggressively pursuing this technology to reduce satellite mass and extend operational life. This adoption pattern is bifurcating the market between standardized, cost-optimized cells for commercial constellations and bespoke, ultra-reliable cells for government deep-space missions.
International guidelines on space debris mitigation, including those from the Inter-Agency Space Debris Coordination Committee (IADC), are influencing battery design. These regulations compel satellite operators to ensure their spacecraft can be de-orbited at the end of life. The Low Earth Orbit segment is most affected, as battery systems must now retain sufficient charge for a final de-orbit maneuver, adding mass and complexity to the power subsystem.
A transition toward acquiring power performance guarantees, rather than just battery hardware, is altering procurement dynamics. This approach shifts the long-term performance and reliability risk from the satellite operator to the battery manufacturer, disrupting the traditional component-sales model. The trend is most visible within the highly competitive commercial satellite sectors in the United States and Europe, where operational uptime is a critical financial metric.
Space Battery Market Segmentation
The space battery market segments along critical dimensions, reflecting the diverse technical requirements and operational environments of various space missions. Understanding these distinctions helps stakeholders navigate the complex interplay of performance, cost, and qualification standards. Each segment presents unique challenges and opportunities for battery manufacturers and system integrators.
Battery Chemistry:
Space agencies impose strict material and performance standards, directly influencing battery chemistry selection for mission profiles. These regulations mandate extensive testing for radiation hardness and thermal cycling, impacting design and material choices.
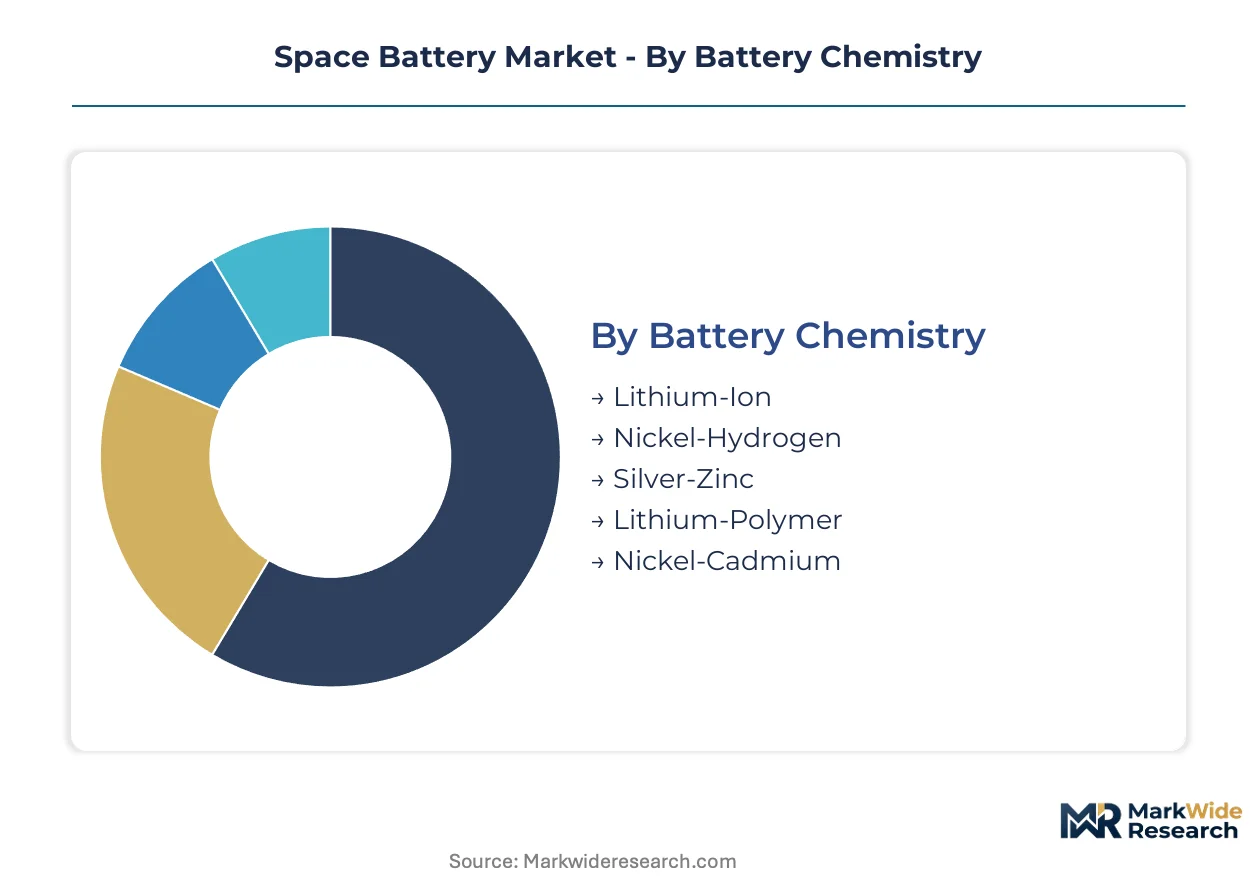
- Lithium-Ion:This chemistry utilizes lithium compounds for energy storage, offering high energy density and cycle life. Demand concentrates heavily in new LEO constellation deployments, driven by the need for lightweight and efficient power solutions.
- Nickel-Hydrogen:These batteries employ nickel hydroxide and hydrogen gas, known for their exceptional reliability and long operational lifespan in geostationary orbits. Government agencies like NASA and the European Space Agency prioritize this chemistry for critical, long-duration deep space missions.
- Silver-Zinc:This chemistry provides high power density for short-duration, high-current applications such as launch vehicle power.
- Lithium-Polymer:Lithium-polymer batteries offer flexible form factors and moderate energy density for smaller satellite platforms.
- Nickel-Cadmium:Nickel-cadmium cells provide robust performance in extreme temperatures for legacy satellite systems.
Established volume favors Nickel-Hydrogen; emerging adoption favors Lithium-Ion.
Application:
The sheer volume of planned deployments dictates battery requirements across various space applications. Each application demands specific power profiles and environmental resilience from its battery systems.
- Satellites:These platforms require batteries to power subsystems during eclipse periods and manage peak power demands. Commercial satellite operators drive demand for high-volume, standardized battery modules for global internet constellations.
- Space Probes:Interplanetary missions demand extremely reliable, long-life power systems capable of enduring harsh radiation environments and extreme temperature swings. Government space exploration programs, particularly from NASA, fund specialized battery development for these applications.
- Space Stations:Orbital outposts like the International Space Station utilize robust battery systems for continuous power supply and life support.
- Unmanned Aerial Vehicles:High-altitude pseudo-satellites often employ battery technology for extended endurance flights in near-space environments.
- Communication Systems:Ground-based communication infrastructure sometimes uses space-grade battery technology for extreme reliability in critical applications.
Satellites represent the largest segment, while space probes demand the most specialized power solutions.
Orbital Class:
Different orbital classes impose distinct cost and performance trade-offs for battery systems. These variations in altitude, radiation, and eclipse durations directly influence battery design and qualification processes.
- Low Earth Orbit:LEO platforms operate at altitudes typically below 2,000 km, experiencing frequent charge/discharge cycles and high radiation exposure. Commercial operators are aggressively deploying large constellations in LEO, driving demand for cost-effective, high-cycle-life batteries.
- Geostationary Orbit:GEO satellites, positioned at approximately 35,786 km, require batteries for long eclipse periods and multi-decade operational lifespans. Traditional government and commercial telecom operators prioritize extreme reliability and long-term performance in GEO.
- Medium Earth Orbit:MEO satellites utilize batteries for navigation and communication services, requiring robust performance over several years.
- Highly Elliptical Orbit:HEO missions, often for communications in polar regions, demand batteries capable of handling varying thermal loads.
- Lunar Orbit:Future lunar missions require specialized batteries for extreme temperature swings and extended operational cycles.
Low Earth Orbit is experiencing the most dynamic expansion, while Geostationary Orbit maintains a demand for proven, long-duration solutions.
End User:
The diverse customer base for space batteries influences procurement strategies and technical specifications. Each end user type has distinct mission objectives and budgetary considerations impacting battery selection.
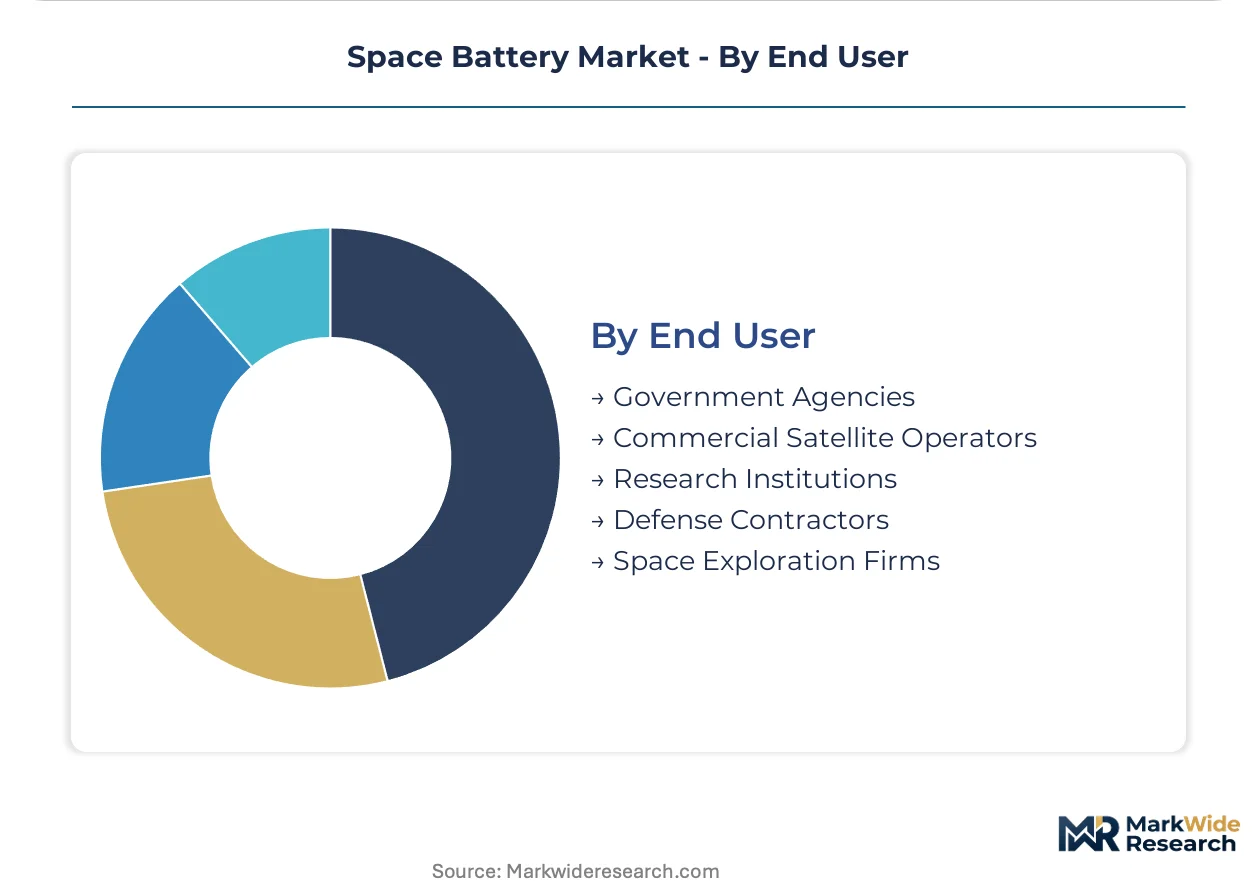
- Commercial Satellite Operators:These entities procure batteries for large-scale constellations providing services like global internet and Earth observation. Their focus is on cost-efficiency, manufacturability, and standardized modules to support rapid deployment.
- Government Agencies:Agencies like NASA and the European Space Agency demand batteries for scientific missions, deep space exploration, and national security assets. Procurement emphasizes extreme reliability, radiation hardness, and long operational lifespans for critical programs.
- Research Institutions:Academic and scientific organizations utilize batteries for experimental payloads and CubeSat development.
- Defense Contractors:These firms integrate space batteries into classified satellite systems and military space applications.
- Space Exploration Firms:Private ventures focused on lunar or Martian missions require advanced, high-performance battery solutions.
Commercial satellite operators are now the largest procurers, with government agencies continuing to drive innovation in specialized battery technologies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The demand for space batteries varies significantly by region, with commercial operators in some areas exhibiting high price sensitivity for LEO constellations. Conversely, government agencies in other regions prioritize extreme reliability and long-term performance over cost for critical missions. This distinction shapes regional investment and technology development across the market.
United States
United States demand for space batteries stems from its robust commercial satellite industry and extensive government exploration programs. NASA's stringent product qualification standards mandate extensive testing for radiation hardness. California's aerospace corridor and Florida's Space Coast concentrate development efforts for advanced power solutions.
Germany
German battery manufacturers support European Space Agency programs and deep space missions, requiring highly reliable, long-life power systems. ESA regulations mandate rigorous thermal cycling and radiation hardness testing for all components. The Munich region and Bremen serve as key centers for aerospace battery research and manufacturing.
France
French demand for space batteries is driven by both national space programs and a strong commercial satellite manufacturing base. The French space agency, CNES, influences battery design through its specific material and performance standards. Toulouse, a major European aerospace hub, hosts significant battery development and integration activities.
Japan
Japanese space battery demand arises from JAXA's scientific missions and the country's advanced communication satellite industry. JAXA standards for reliability and performance guide battery material selection and qualification processes. The Tokyo metropolitan area and Nagoya region house key manufacturers and research institutions for space power systems.
India
India's growing space program, led by ISRO, creates new demand for both specialized and cost-effective battery solutions. ISRO's focus on indigenous development drives specific procurement requirements and qualification protocols. Bengaluru, often called India's 'Space City', is a central hub for space battery research and manufacturing.
Space Battery Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the space battery market. The market exhibits a tiered structure, with established manufacturers focusing on high-reliability, performance-driven solutions for government missions. A separate segment prioritizes cost-efficiency and manufacturability for the high-volume commercial LEO constellation market. This bifurcation influences product development cycles and supply chain configurations. Strategic partnerships between cell manufacturers and system integrators represent a common competitive move to address diverse customer needs.
Within the high-reliability, long-duration mission segment, Saft Groupe SA exemplifies a heritage player leveraging extensive experience in high-reliability cell production. EaglePicher Technologies occupies a position specializing in custom power solutions for defense and critical space applications. Meanwhile, GS Yuasa Corporation represents a manufacturer that differentiates with lithium-ion technologies developed for both automotive and aerospace sectors, bridging different market demands. These companies anchor various segments of the market, reflecting the diverse technical requirements.
| Leading Market Players |
|---|
| Saft Groupe SA |
| EaglePicher Technologies |
| GS Yuasa Corporation |
| EnerSys |
| Mitsubishi Electric Corporation |
| Arotech Corporation |
| ABSL Space Products |
| VARTA AG |
| Toshiba Corporation |
| Others |
Cost & Logistics Intelligence
High-volume manufacturing scale for commercial LEO constellations drives efficiency gains, creating lower price floors for standardized battery modules. This scale simultaneously concentrates supply chains around cost-optimized production hubs.
Pricing Analysis
Performance guarantee contracts represent a significant after-sales revenue tier, shifting long-term reliability risk to manufacturers. The market utilizes a hybrid pricing model, combining project-based bids for specialized deep space missions with long-term contract-based arrangements for commercial constellations. Price differentiation stems from radiation hardness certification levels and guaranteed operational lifespan. Pricing softness intensifies within the commercial LEO segment due to high-volume demand for cost-optimized solutions; commercial satellite operators exhibit the highest price sensitivity.
Supply Chain Analysis
Extended lead times and strategic inventory holding characterize the space battery supply chain due to stringent qualification processes. Supply concentration for high-purity electrochemical materials like lithium and cobalt centers on China and South Korea. Key raw material dependencies include space-grade lithium, cobalt, and radiation-hardened electronic components. Geopolitical supply risks for these critical materials represent a significant structural vulnerability, with direct sales to satellite prime contractors forming the dominant distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The space battery market requires a robust substitution defense, as incumbents must navigate the threat of alternative power sources like advanced radioisotope thermoelectric generators for deep space missions. This imperative drives strategic decisions across the value chain.
For Market Incumbents: Fortify core competencies in radiation-hardened cell design and long-duration mission qualification to counter emerging solid-state battery entrants. Pursue strategic acquisitions of specialized component manufacturers to secure critical supply chains. Invest heavily in advanced material science R&D to extend operational lifespans, mitigating the threat of alternative power technologies. This vertical integration into key component production is a critical lever.
For New Entrants and Emerging Players: Rapid certification pathways, such as those for CubeSat components, offer a low-barrier entry point into the market. Target the underserved small satellite and high-altitude pseudo-satellite platforms with modular, cost-effective lithium-polymer solutions. Focus on developing standardized battery modules for the burgeoning LEO constellation market, leveraging efficient manufacturing processes. A direct-to-integrator sales model emphasizing rapid prototyping and qualification can accelerate market penetration.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized battery manufacturers with proven flight heritage and strong intellectual property in solid-state chemistries. Long-term viability, over a five to ten-year window, hinges on the ability to scale production for commercial LEO while maintaining deep space mission reliability. Target acquisition archetypes include agile developers of next-generation solid-state battery cells and vertically integrated component suppliers. The signal to watch is the successful, large-scale deployment of solid-state batteries in commercial LEO constellations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for LEO Modules | Scaling production for standardized battery modules addresses high-volume demand from commercial satellite operators. |
| Advanced Solid-State R&D | Investing in solid-state chemistries enables higher energy density and extended operational lifespans for deep space probes. |
| Radiation Hardness Certification | Achieving stringent radiation hardness standards ensures market access for critical government agency programs. |
| Vertical Integration into Materials | Securing captive supply of high-purity lithium and cobalt mitigates geopolitical supply risks. |
| Partnerships with System Integrators | Collaborating with satellite system integrators facilitates optimized power subsystem design and faster market entry. |
Research Approach
Initial hypotheses were tested against primary input from satellite manufacturers, space agency procurement leads, battery R&D directors, and commercial constellation operators. This input was refined through iterative analysis and combined with comprehensive secondary validation. Secondary data sources included NASA technical reports, ESA mission documentation, industry association publications, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Variance decomposition techniques were applied to analyze market drivers and restraints, isolating their impact on overall market growth across the analysis window. The market was segmented by battery chemistry, application, orbital class, and end user type. Compound annual growth rates were derived from historical trends and projected future demand scenarios. Forecast inputs included planned satellite launches and advancements in solid-state battery development.
Decision-makers should treat outputs as directional under the base assumptions of stable geopolitical conditions and continued commercial space investment; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions, acknowledging potential shifts in regulatory standards or critical material supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Space
UK Space Propulsion System Market
Space
Space Radar Market
Space
Space Mobile Service Market
Space
Europe Space Electronics Market
Space
China Space Propulsion System Market
Space
Electrically Powered Spacecraft Propulsion Market
Space
Space Wheel Market
Space
Space Management Solutions Market
Space
North America Spacesuit Market
Space
Mexico Space Electronics Market
Space
Spain Space Electronics Market
Space
Space Ground Station Equipment Market
Space
Space Ground System Market
Space
Africa Space Propulsion System Market
Space
US Reusable Launch Vehicle Market
Space
Spacecraft Market