
 Fixed-Wing VTOL UAV Market | 2026-2036
Fixed-Wing VTOL UAV Market Size, Share, and Industry Trends Forecast 2026-2036
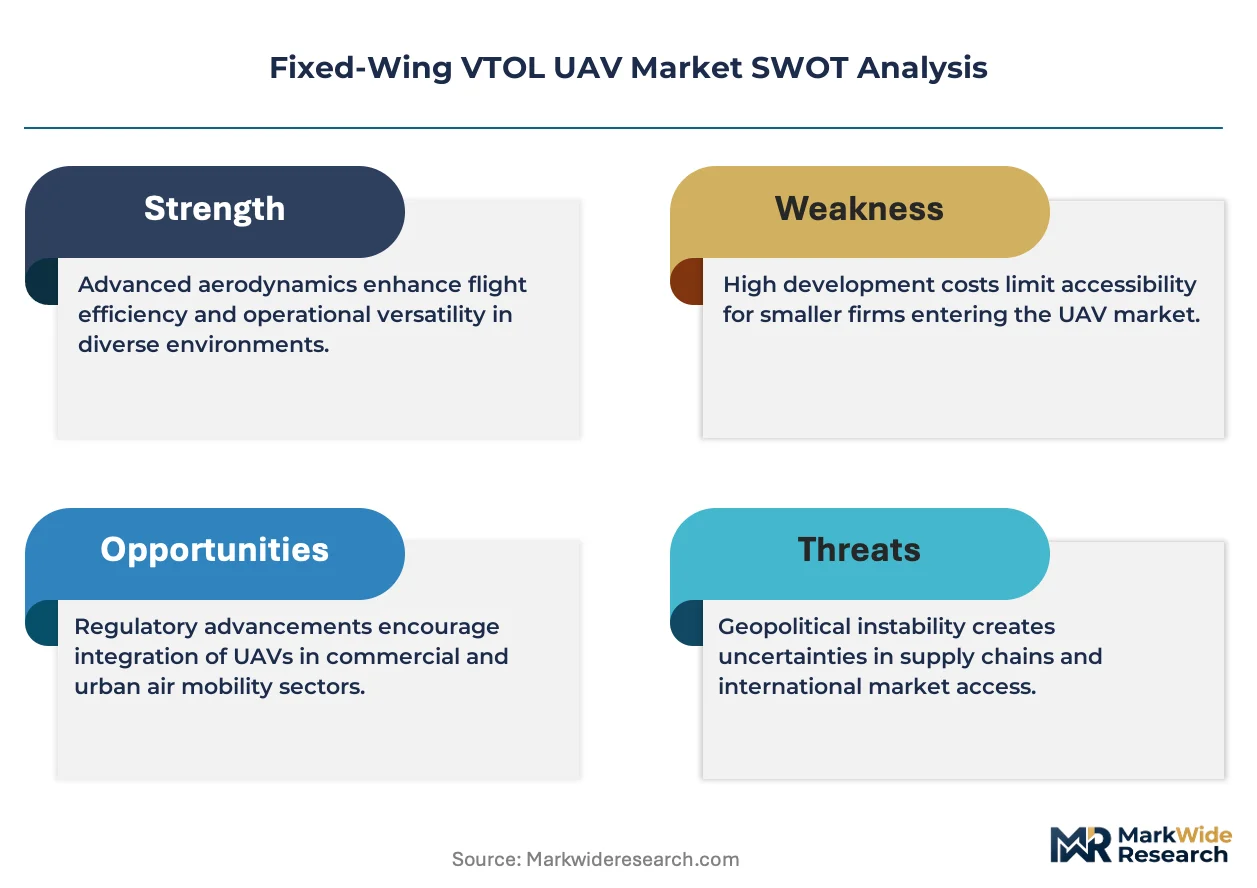
Fixed-Wing VTOL UAV Market Analysis
Hybrid electric propulsion architecture is reconfiguring how fixed-wing VTOL UAV manufacturers balance endurance with vertical lift capability. General Atomics leverages its legacy in remotely piloted aircraft systems to anchor defense contracts requiring extended range and payload flexibility. Quantum-Systems GmbH specializes in electric VTOL platforms for commercial mapping and surveillance applications across European airspace.
A fixed-wing VTOL UAV combines the horizontal cruise efficiency of conventional aircraft with thrust-vectoring or lift-plus-cruise systems enabling vertical takeoff and landing without runway dependency. These platforms typically achieve endurance of four to twelve hours with wingspans ranging from two to eight meters, serving missions where runway access is constrained or mission profiles demand rapid redeployment. Hybrid VTOL configurations currently dominate defense procurement budgets due to their fuel-electric range extension, while electric VTOL variants lead commercial adoption in environmental monitoring where acoustic signature and emissions restrictions apply. Turbine engine technology sustains the heaviest payload segments including signals intelligence and maritime patrol, though electric motor architectures are displacing gasoline engines in logistics trials.
The FAA governs commercial BVLOS operations in the United States under Part 107 waivers and emerging type certification pathways, while EASA's drone regulations in Europe mandate specific design and operational standards for VTOL platforms in certified airspace. Military procurement in NATO countries follows STANAG interoperability standards that shape sensor integration and communication protocols. Stakeholders must monitor evolving type certification requirements as regulators distinguish between autonomous and remotely piloted VTOL systems.
Market Dynamics
Battery energy density improvements above 300 Wh/kg are collapsing the endurance gap between hybrid-electric and turbine-powered VTOL platforms, forcing procurement agencies to rebalance fleet acquisition criteria toward electric architectures.
Growth Catalysts
- BVLOS Regulatory Pathways:The FAA's Part 107 waiver expansion and EASA's drone regulation amendments are unlocking commercial inspection missions over critical infrastructure.
- Distributed Electric Propulsion:Redundant motor configurations reduce single-point-of-failure risks, enabling certification for flights over populated areas previously restricted to manned aviation.
- NATO STANAG Interoperability:Standardized communication protocols allow Danish, Polish, and Norwegian defense agencies to pool sensor assets across joint reconnaissance operations.
Market Restraints
- Lithium-Nickel-Cobalt Supply Concentration:Cathode material processing in the Democratic Republic of Congo and Indonesia creates geopolitical exposure for battery-dependent electric VTOL programs.
- Airspace Integration Friction:EASA's certified-category type certification timelines extend 18-24 months, freezing platform variants before operational deployment.
- Weather Ceiling Limitations:Electric propulsion power degradation in sub-zero conditions restricts Arctic patrol applications where turbine endurance remains mandatory.
Strategic Opportunities
- Urban Air Mobility Corridors:Singapore's Marina Bay and Dubai's Silicon Oasis are designating dedicated low-altitude highways for cargo-carrying VTOL logistics trials.
- Carbon Border Adjustment Alignment:The EU Green Deal's emissions accounting rules favor battery-electric platforms over gasoline-hybrid alternatives for public-sector tenders.
- AI-Driven Autonomy Stacks:Convergence of computer vision and edge computing enables single-operator control of multiple aircraft, collapsing crew-to-aircraft ratios.
Industry Challenges
- Airworthiness Certification Backlogs:FAA type certification queues for novel VTOL configurations delay revenue recognition by 12-18 months beyond engineering completion.
- Systems Integration Complexity:Defense customers demand STANAG-compliant datalinks that conflict with commercial C-band spectrum allocations, forcing dual-radio architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fixed-Wing VTOL UAV Market |
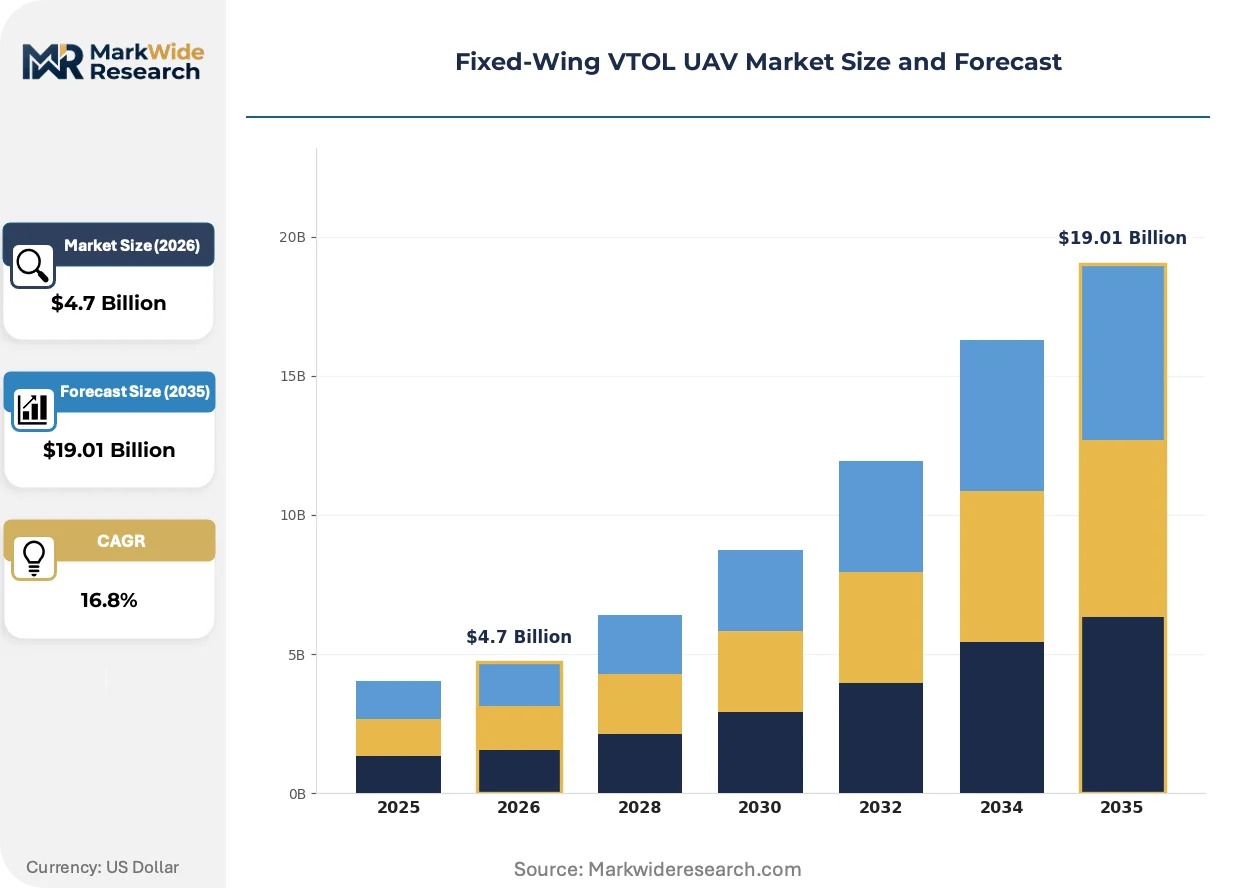
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $19.01 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hybrid VTOL, Conventional Fixed-Wing, Electric VTOL, Multi-Rotor Technology: Pusher Propeller, Turbine Engine, Electric Motor, Gasoline Engine End User: Agriculture, Surveillance, Logistics, Defense Application: Mapping, Search & Rescue, Delivery, Environmental Monitoring |
| Companies Covered | General Atomics, Northrop Grumman Corporation, Lockheed Martin Corporation, AeroVironment, Inc., Textron Systems, Israel Aerospace Industries Ltd., Alti UAS, UKRSPECSYSTEMS, Quantum-Systems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fixed-Wing VTOL UAV Market Emerging Trajectories
Solid-state battery chemistry and hydrogen fuel cell prototyping are compressing the performance frontier between experimental and deployable propulsion systems. Platform developers now face compressed technology refresh cycles.
Silicon-anode lithium-ion configurations are collapsing the mass-penalty tradeoff that previously forced endurance-versus-payload compromises. Maritime patrol operators in Norway and Japan are retrofitting existing airframes with higher-density packs, extending station time without wing extensions. The result collapses the cost-per-flight-hour advantage that turbine systems held above 500 nautical mile ranges.
EASA's Specific Operations Risk Assessment framework is compressing certification timelines for predefined mission profiles. Commercial survey operators in Germany and France now access certified airspace through operational declarations rather than full type certification. The shift collapses entry barriers for mapping and agricultural monitoring segments previously gated by regulatory uncertainty.
Defense procurement agencies are unbundling sensor packages from airframe contracts, forcing integrators to compete on platform performance alone. The US Department of Defense now acquires VTOL airframes through indefinite-delivery vehicles while sourcing ISR payloads through separate software-defined radio competitions. This bifurcation concentrates margin pressure on hardware manufacturers while elevating software and payload specialists.
Fixed-Wing VTOL UAV Market Segmentation
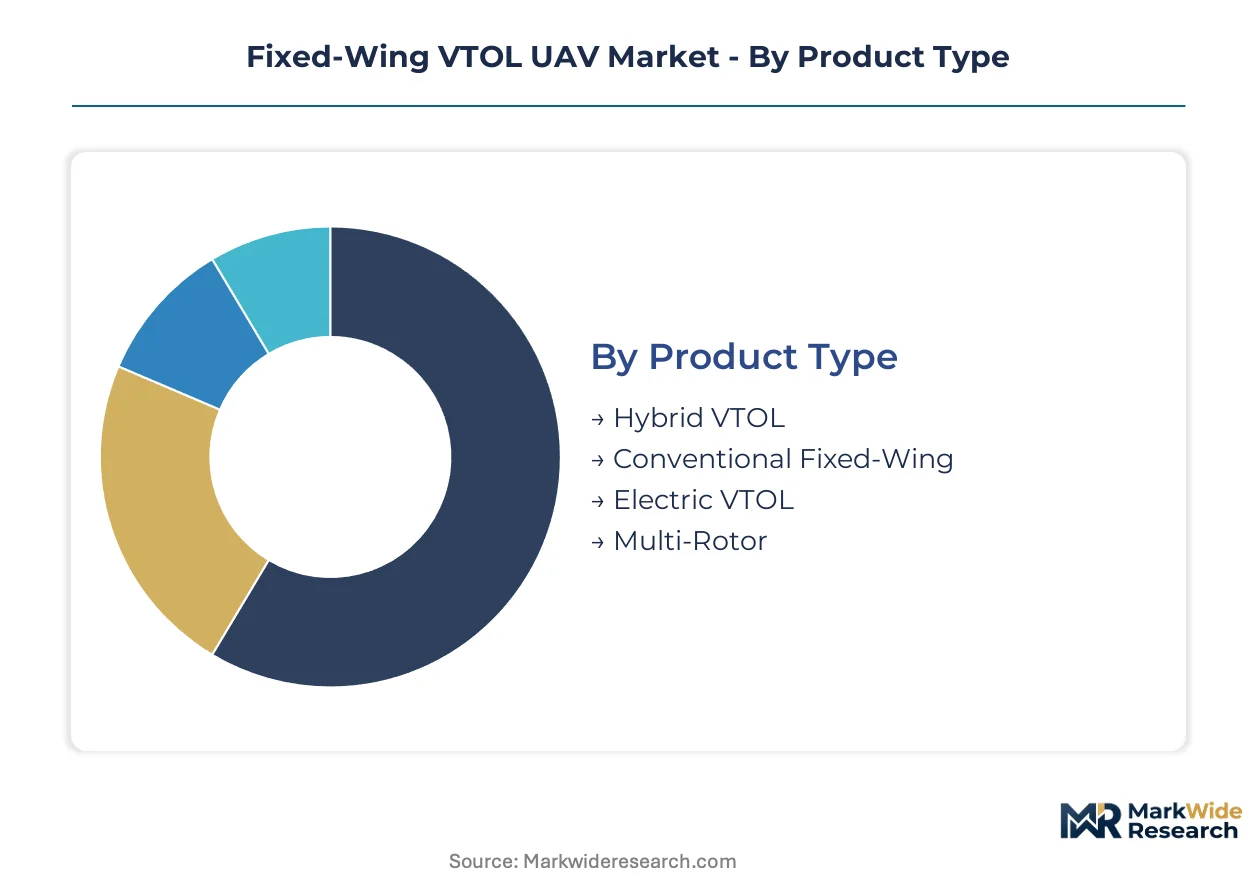
Fixed-wing VTOL UAV procurement splits across propulsion architectures, mission profiles, and regulatory operating categories. Understanding these divisions clarifies why defense agencies favor hybrid systems while commercial operators migrate toward electric platforms.
Product Type:
Propulsion architecture determines endurance ceiling, acoustic signature, and airspace access permissions across operating environments.
- Hybrid VTOL:Combines turbine or gasoline range extension with electric vertical lift, delivering six-to-twelve-hour endurance for signals intelligence and maritime patrol missions. NATO procurement budgets concentrate here due to fuel-electric flexibility in contested logistics environments.
- Electric VTOL:Distributed motor architectures with lithium-ion packs enable sub-55-pound operations under FAA Part 107 waivers without type certification. Environmental monitoring contracts in Germany and France specify electric platforms to meet EU Green Deal emissions accounting requirements.
- Conventional Fixed-Wing:Runway-dependent platforms with superior aerodynamic efficiency for long-range cargo routes where vertical landing capability is unnecessary.
- Multi-Rotor:Pure rotary-wing systems dominate last-mile delivery trials below ten-kilogram payloads in Singapore's Marina Bay corridor and Dubai's Silicon Oasis logistics zones.
Hybrid VTOL holds installed capacity. Electric VTOL is rotating up the share rankings.
Technology:
Powerplant selection locks in maintenance intervals, fuel logistics, and cold-weather operational envelopes.
- Electric Motor:Brushless DC configurations with redundant winding sets reduce single-point-of-failure risks for flights over populated areas. Norway and Japan are retrofitting maritime patrol airframes with silicon-anode lithium-ion packs to extend station time without structural modifications.
- Turbine Engine:Micro-turbines sustain heavy payload segments including synthetic aperture radar and electronic warfare packages where power-to-weight ratios exceed electric alternatives. Arctic defense applications remain turbine-dependent due to battery degradation below minus-twenty Celsius.
- Pusher Propeller:Rear-mounted propulsion optimized for cruise efficiency in mapping missions requiring minimal acoustic interference.
- Gasoline Engine:Two-stroke and four-stroke internal combustion systems persist in commercial survey operations where refueling infrastructure exists and emissions restrictions are absent.
Turbine engine configurations anchor heavy-payload defense contracts. Electric motor architectures are climbing fastest in commercial certification pathways.
End User:
Customer type dictates payload specifications, datalink security requirements, and procurement cycle timelines.
- Defense:STANAG-compliant communication protocols and software-defined radio integration dominate NATO member state requirements. The US Department of Defense now separates airframe acquisition from ISR payload sourcing through indefinite-delivery vehicles.
- Surveillance:Border patrol and critical infrastructure protection operators prioritize BVLOS waiver compliance over endurance maximization.
- Agriculture:Precision crop monitoring in France and Germany leverages EASA's Specific Operations Risk Assessment framework for accelerated airspace access.
- Logistics:Cargo-carrying trials in Singapore and Dubai are establishing dedicated low-altitude corridors for medical supply and e-commerce delivery.
Defense commands procurement volume. Logistics is gaining share fastest in pilot program allocations.
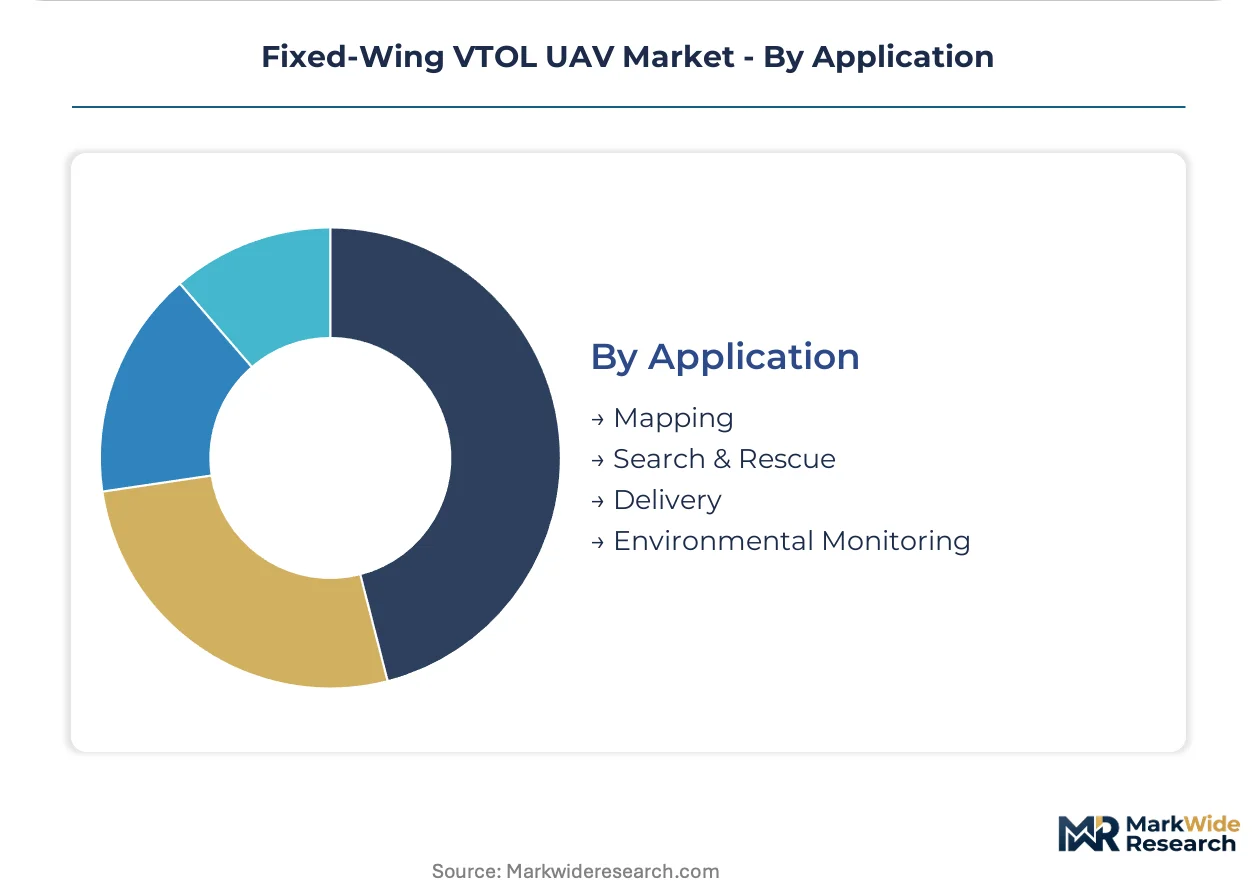
Application:
Mission profile determines sensor integration, flight planning software, and regulatory approval pathways.
- Mapping:Photogrammetry and LiDAR survey missions require gimbal-stabilized payloads with centimeter-level GPS correction. German and French operators access certified airspace through operational declarations rather than full type certification under EASA's evolving framework.
- Environmental Monitoring:Wildfire detection and emissions verification missions prioritize low acoustic signature and zero direct emissions. EU public-sector tenders increasingly specify battery-electric platforms to align with carbon border adjustment mechanisms.
- Search & Rescue:Thermal imaging and drop-capable payloads for maritime and alpine emergency response.
- Delivery:Package transport applications face airworthiness certification backlogs of twelve-to-eighteen months beyond engineering completion in FAA jurisdictions.
Mapping holds established operational scale. Environmental monitoring is expanding most quickly in regulatory alignment with EU decarbonization mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export electric VTOL platforms to French and Dutch survey operators under streamlined EASA certification pathways. Israeli defense contractors supply hybrid systems to NATO procurement agencies seeking STANAG-compliant reconnaissance assets.
United States
The Department of Defense and homeland security agencies dominate procurement volume for intelligence and reconnaissance missions. FAA Part 107 waivers and emerging BVLOS regulatory pathways unlock commercial inspection operations over critical infrastructure. Defense contractors in California and Virginia anchor production clusters serving federal indefinite-delivery vehicle contracts.
Germany
Commercial mapping operators drive demand for electric VTOL platforms with centimeter-level GPS correction capabilities. EASA's Specific Operations Risk Assessment framework accelerates airspace access through operational declarations rather than full type certification. Bavaria-based manufacturers specialize in distributed electric propulsion architectures for environmental monitoring contracts.
Israel
Defense export programs sustain hybrid VTOL production for maritime patrol and signals intelligence applications. The national defense establishment mandates STANAG interoperability for NATO-aligned foreign military sales. Tel Aviv-area engineering clusters focus on software-defined radio integration and autonomous mission systems.
Norway
Maritime patrol operators retrofit existing airframes with silicon-anode lithium-ion packs to extend station time over North Sea infrastructure. Cold-weather battery degradation below minus-twenty Celsius sustains turbine dependency for Arctic applications. Stavanger-based operators collaborate with German platform developers on hybrid-electric endurance trials.
Singapore
Urban air mobility corridor designations in Marina Bay drive cargo-carrying VTOL logistics trials for medical supply delivery. The national aviation regulator collaborates with EASA on type certification reciprocity for European-imported platforms. Local engineering services clusters support multinational platform operators establishing Asia-Pacific maintenance hubs.
Fixed-Wing VTOL UAV Market Vendor Landscape
Channel-controlling players compete with product-specialist players across defense procurement and commercial certification pathways. The market structure concentrates around tier-one defense contractors with indefinite-delivery vehicle relationships and tier-two electric platform specialists with accelerated EASA approvals. Three archetypes dominate: legacy remotely piloted aircraft systems integrators, distributed electric propulsion pure-plays, and hybrid propulsion defense specialists. Competitive moves center on unbundling sensor packages from airframe contracts and establishing maintenance partnerships in Asia-Pacific logistics corridors.
Among defense-heritage integrators, General Atomics and Lockheed Martin Corporation occupy positions anchored by federal procurement relationships, while Quantum-Systems GmbH exemplifies the electric-specialist archetype serving European commercial mapping operators. These three represent distinct competitive vectors: turbine-hybrid endurance platforms, multi-mission software-defined architectures, and battery-electric certification-first strategies.
| Leading Market Players |
|---|
| General Atomics |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| AeroVironment, Inc. |
| Textron Systems |
| Israel Aerospace Industries Ltd. |
| Alti UAS |
| UKRSPECSYSTEMS |
| Quantum-Systems GmbH |
| Others |
Supply Flow & Price Mechanics
Stuttgart's distributed electric propulsion manufacturing cluster shapes downstream pricing power through captive motor winding capacity and silicon-anode lithium-ion pack integration. Defense procurement agencies absorb hybrid VTOL premiums while commercial operators face cost compression from battery chemistry commoditization.
Pricing Analysis
Next-generation solid-state battery configurations command substantial premiums over silicon-anode lithium-ion systems, while prior-generation gasoline-hybrid platforms face accelerating price erosion. Three-tier pricing structure across STANAG-certified defense, EASA-commercial, and experimental research tiers reflects certification burden differentiation. Pricing pressure stems from unbundled sensor contracts forcing airframe-only competition. Defense agencies exhibit lowest price sensitivity; agricultural survey operators in France and Germany show highest elasticity to hardware costs.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn's aerospace division, Jabil's defense electronics unit, and specialized German EMS providers serving Bavarian platform developers. Lithium-nickel-cobalt cathode processing draws from Indonesian refining capacity and DRC mining operations, while rare-earth permanent magnets for brushless motors rest on Chinese separation facilities. Single-source vulnerability in solid-state electrolyte precursors threatens next-generation battery roadmaps. Distribution runs through federal indefinite-delivery vehicles for defense and direct OEM relationships for commercial mapping operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fixed-wing VTOL UAV economics increasingly hinge on predictive maintenance subscriptions and flight-hour service contracts expanding faster than airframe unit sales. Software-defined payload updates and BVLOS operator training packages represent recurring revenue layers outpacing hardware margins.
For Market Incumbents: Build regulatory certification moats through accelerated EASA Specific Operations Risk Assessment pre-approvals and FAA BVLOS waiver aggregation. Lock in defense relationships via STANAG-compliant datalink integration that emerging entrants cannot replicate without 18-24 month certification timelines. Add captive battery pack assembly in Norway to secure Arctic operator contracts where cold-weather performance requirements filter out modular competitors. For New Entrants and Emerging Players: Build out urban air mobility logistics corridors in Singapore and Dubai where corridor-specific operational declarations bypass full type certification barriers. Agricultural monitoring in Germany offers the most penetrable entry point through EASA's operational declaration pathway. Lead with carbon-accounting compliance as the go-to-market wedge for EU public-sector tenders under Green Deal procurement rules. For Investors and Strategic Acquirers: Long-term, this sits as a vertical integration play because battery chemistry control and airspace certification reciprocity determine sustainable margin capture. Target electric platform specialists with accelerated EASA approvals and established German-French distribution. Watch FAA Part 108 final rule publication as the signal separating investable commercial operators from stranded waiver-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Acceleration | Compresses 18-24 month FAA timelines through operational declaration pathways in EASA jurisdictions. |
| Backward Integration into Battery Packs | Captures silicon-anode lithium-ion cost compression and secures supply for Arctic defense contracts. |
| Sensor-Unbundled Platform Sales | Aligns with DoD indefinite-delivery vehicle structures separating airframe from ISR payload procurement. |
| Urban Corridor Operational Declarations | Unlocks Singapore Marina Bay and Dubai Silicon Oasis cargo trials without full type certification. |
| Predictive Maintenance Platform Launch | Converts hardware sales into recurring flight-hour revenue with higher lifetime customer value. |
Methodological Framework
Initial hypotheses were tested against primary input from VTOL platform engineering directors, defense procurement officers at NATO member agencies, EASA certification consultants, and commercial survey fleet operators and refined through secondary validation. Primary fieldwork drew from FAA Part 107 waiver holders, German agricultural monitoring contractors, and Singapore urban air mobility corridor planners. Secondary sources encompassed STANAG interoperability documentation, EASA drone regulation amendment filings, US DoD indefinite-delivery vehicle award notices, and customs records for lithium-ion pack trade flows. Bottom-up platform shipment estimates were triangulated against top-down defense budget appropriations and commercial operator fleet expansion plans.
Demand-supply balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, mission profile category, regulatory operating category, and end-user procurement structure. CAGRs were derived from installed base evolution and replacement cycle analysis rather than extrapolated growth rates. Forecast inputs incorporated battery energy density improvement curves, EASA certification timeline compression assumptions, and NATO defense spending trajectory indicators.
Stress conditions across lithium-cobalt supply disruption scenarios, FAA BVLOS rulemaking delays, and Arctic temperature operational envelope failures were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory reciprocity between EASA and FAA jurisdictions, solid-state battery commercialization timelines, and defense procurement unbundling persistence. Quarterly review of EASA operational declaration approval volumes and DoD IDV award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Multirotor Drones Market
UAV
Global Drone Software Market
UAV
Drone Identification System Market
UAV
North America Fuel Cell UAV Market
UAV
Industrial Drones Market
UAV
Global Inspection Drones Market
UAV
Inspection Drones in Confined Space Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Portable Drone Market
UAV
Drone Flight Controller System Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Drone Delivery Services Market
UAV
Europe Tethered Drone Market
UAV
Latin America Small UAV Market
UAV
GCC Drones Market