
 Autonomous Aircraft Cameras Market | 2026-2036
Autonomous Aircraft Cameras Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Aircraft Cameras Market Analysis
Israeli defense electronics manufacturing is recalibrating output schedules to match the surge in autonomous platform orders. Elbit Systems Ltd. leverages vertically integrated electro-optical production lines to capture premium contracts for gimbal-stabilized surveillance payloads. RTX Corporation sustains engineering intensity across multi-spectral sensor fusion programs for unmanned combat air vehicles. Lockheed Martin Corporation anchors its position through captive supply of long-range infrared turrets integrated into the Skunk Works drone portfolio.
Autonomous aircraft cameras constitute electro-optical payloads engineered for unmanned aerial platforms, typically incorporating gyro-stabilized gimbals, multi-spectral sensors, and real-time video processing chipsets operating at 30-60 Hz refresh rates with sub-pixel pointing accuracy for target tracking at altitude. These systems serve military reconnaissance, infrastructure inspection, and geospatial mapping missions where human operator latency compromises operational effectiveness. HD and 4K camera types command the dominant revenue share due to bandwidth infrastructure improvements enabling full-motion video transmission to ground control stations. The gimbal system installation method represents the fastest-expanding configuration category as three-axis stabilization becomes mandatory for intelligence, surveillance, and reconnaissance mission profiles. Defense end users concentrate the majority of procurement volume, though commercial aviation inspection applications are diversifying the buyer base.
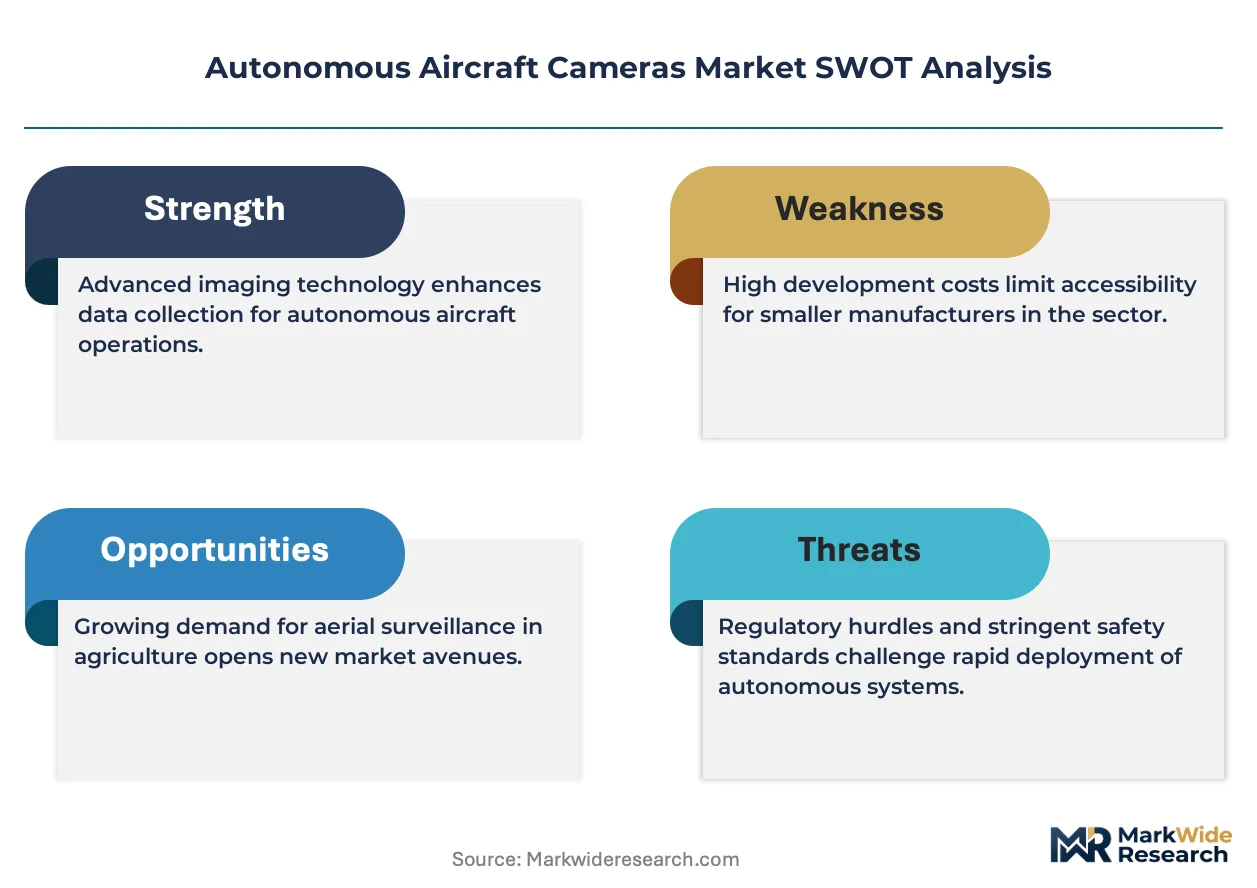
The FAA's Part 89 remote identification mandate and the EPA's emissions benchmarks for unmanned platforms are tightening certification pathways for camera-integrated autonomous aircraft in the United States. EASA's SORA framework and the EU AI Act's risk classification protocols are imposing equivalent compliance burdens across European development programs. Stakeholders must monitor how dual-use export control expansions under Wassenaar Arrangement updates reshape cross-border component flows for thermal imaging cores.
Market Dynamics
The FAA's Part 89 remote identification mandate is compressing certification timelines for camera-integrated unmanned platforms, forcing manufacturers to revalidate electro-optical payload designs against real-time tracking requirements. This regulatory pressure is redistributing engineering resources across the supply chain.
Growth Catalysts
- Military drone surveillance programs:The United States Department of Defense is accelerating procurement of stabilized imaging payloads for intelligence, surveillance, and reconnaissance missions. Gimbal-stabilized systems with multi-spectral capabilities are receiving priority funding.
- FAA Part 89 compliance:Evolving remote identification rules are creating mandatory retrofit demand for existing unmanned platforms. Camera-integrated systems must incorporate broadcast modules for real-time position reporting.
- Israeli defense technology corridor:Autonomous systems integration expertise has concentrated in Haifa and Tel Aviv metropolitan clusters. Domestic manufacturers are capturing premium contracts for electro-optical production.
Market Restraints
- Thermal imaging core supply concentration:Dual-use export control expansions under Wassenaar Arrangement updates are restricting cross-border component flows. German and French sensor foundries face licensing delays for military-grade focal plane arrays.
- Multi-spectral sensor fusion complexity:Technical limitations in real-time data processing at 30-60 Hz refresh rates are constraining target tracking accuracy. Sub-pixel pointing precision requires specialized gyro-stabilized gimbal engineering.
- EASA SORA framework compliance costs:European specific operations risk assessment protocols are imposing equivalent certification burdens to FAA mandates. Small payload developers lack capital for parallel validation tracks.
Strategic Opportunities
- Commercial aviation inspection applications:Infrastructure monitoring for power transmission lines and pipeline corridors remains underpenetrated. Civilian buyers are diversifying procurement beyond defense end users.
- EU AI Act risk classification protocols:Regulatory tailwinds for autonomous decision-making systems are creating premium positioning for camera platforms with embedded edge computing. High-risk category compliance becomes a differentiator.
- Geospatial mapping convergence:Integration of LiDAR point cloud data with electro-optical video streams is opening new survey contracting channels. Surveying firms are adopting unmanned platforms for cadastral and environmental monitoring.
Industry Challenges
- Electro-optical systems engineering talent scarcity:Specialized expertise in gyro-stabilized gimbal design and real-time video processing chipsets is concentrated at Israeli and US defense contractors. Commercial entrants face recruitment barriers.
- Dual-use technology licensing complexity:Intellectual property disputes over thermal imaging core architectures are fragmenting patent landscapes. Cross-licensing negotiations delay product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Aircraft Cameras Market |
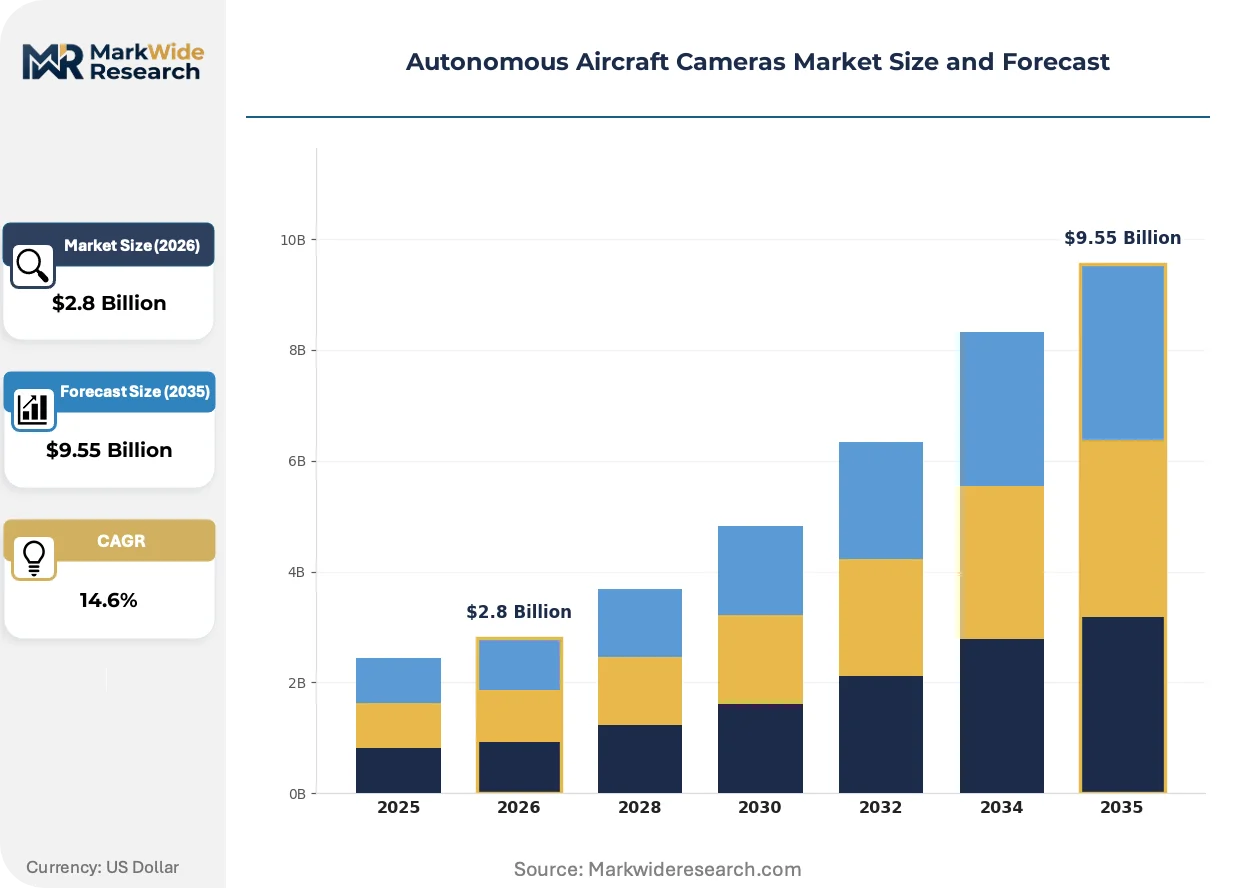
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Camera Type: Infrared, Digital, HD, 4K Application: Surveillance, Navigation, Mapping, Inspection End User: Defense, Commercial Aviation, Research Institutions, Aerospace Installation Method: Fixed Mount, Gimbal System, Robotic Arm, Integrated System |
| Companies Covered | Elbit Systems Ltd., Saab AB, RTX Corporation, Lockheed Martin Corporation, Northrop Grumman Corporation, The Boeing Company, Textron Inc., Teledyne FLIR LLC, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Aircraft Cameras Market Emerging Trajectories
Edge computing architectures are relocating video processing from ground control stations to onboard payload electronics. This migration is compressing latency requirements and reshaping hardware specifications across the supplier base.
Embedded AI inference engines are decentralizing target detection and tracking algorithms from centralized ground stations. Military end users in the United States are demanding sub-100 millisecond decision loops for autonomous engagement protocols. Real-time processing at the sensor edge is eliminating bandwidth constraints for full-motion video transmission.
EASA's SORA framework and the EU AI Act's risk classification protocols are tightening operational authorization pathways for autonomous camera platforms in European airspace. Manufacturers must demonstrate conformity with high-risk system requirements for beyond-visual-line-of-sight missions. German and French developers are establishing dedicated compliance divisions to manage parallel certification tracks.
Defense procurement offices are consolidating vendor relationships around full-motion video transmission capabilities. Prime contractors are absorbing subsystem suppliers to secure captive supply of long-range infrared turrets. Israeli and US buyers are prioritizing vertically integrated electro-optical production over modular component sourcing.
Autonomous Aircraft Cameras Market Segmentation
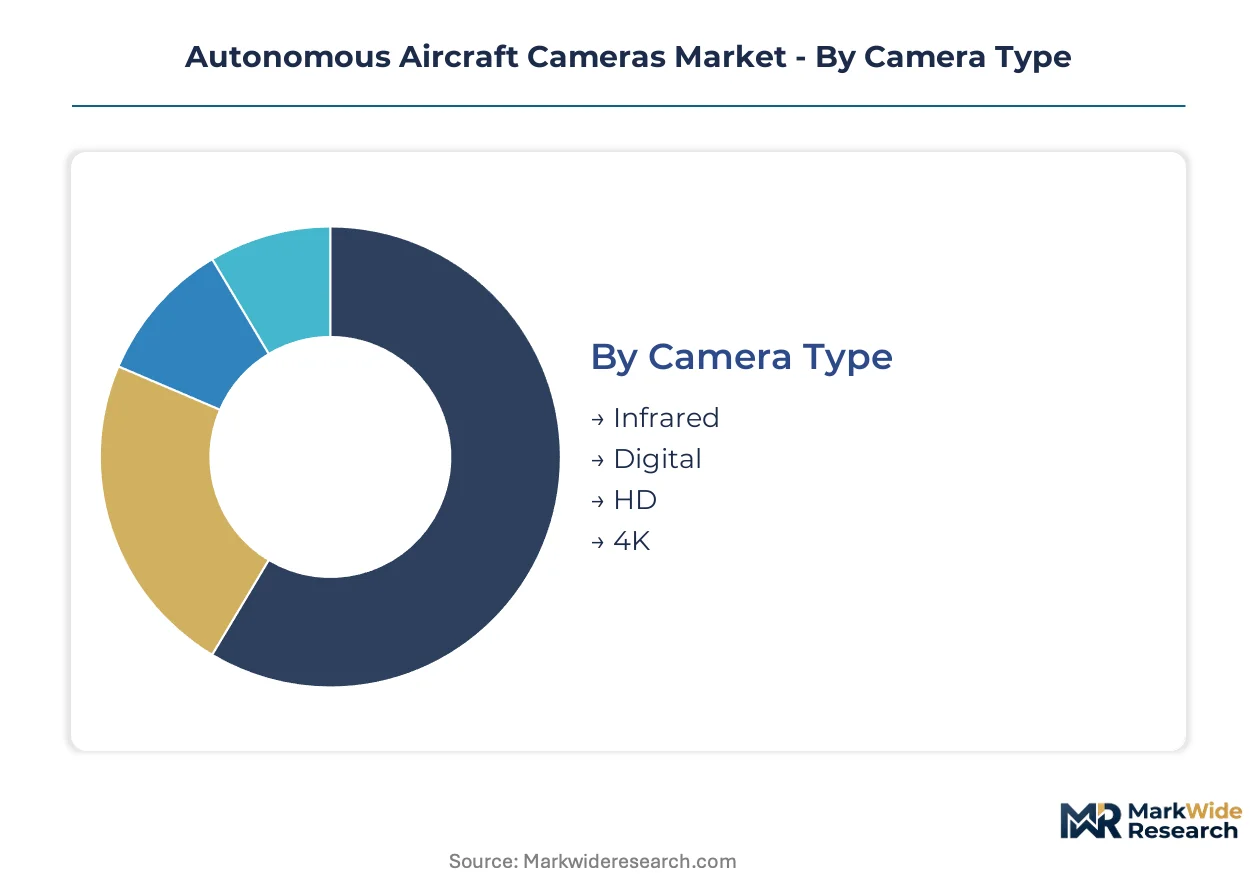
Electro-optical payload configurations in autonomous aircraft cameras diverge sharply across mission profiles, with stabilization architecture and spectral sensitivity driving procurement decisions. Buyers segment their investments based on real-time processing requirements, environmental operating conditions, and integration complexity with existing unmanned platforms.
Camera Type:
Resolution and spectral capability separate price tiers and determine downstream software compatibility for target recognition algorithms.
- HD:1080p sensors dominate bandwidth-constrained operations where transmission infrastructure limits full-motion video throughput. Defense reconnaissance contracts in Israel specify HD baseline configurations for tactical unmanned systems with legacy ground control station integration.
- 4K:Ultra-high-definition formats incorporate larger CMOS arrays and advanced compression codecs for geospatial mapping missions requiring sub-meter feature resolution. Commercial infrastructure inspection buyers in the United States prioritize 4K payloads for power transmission line assessment where arc flash detection demands pixel-level clarity.
- Infrared:Thermal imaging cores enable night operations and heat signature detection through obscurants.
- Digital:Standard visible-spectrum cameras serve cost-sensitive navigation and collision avoidance functions.
HD leads volumes today; 4K is gaining share fastest.
Application:
Mission-criticality and regulatory exposure vary dramatically across use cases, reshaping vendor qualification requirements and certification pathways.
- Surveillance:Intelligence, surveillance, and reconnaissance missions demand gyro-stabilized gimbals with sub-pixel pointing accuracy and multi-spectral fusion capabilities. The United States Department of Defense accelerates procurement of these payloads for drone programs requiring real-time target tracking at altitude.
- Inspection:Infrastructure monitoring for pipelines and transmission corridors requires portable, rapidly deployable camera systems with automated defect recognition. FAA Part 89 remote identification compliance adds certification overhead for commercial operators deploying inspection platforms in civil airspace.
- Navigation:Collision avoidance and waypoint verification functions utilize lower-complexity fixed-mount configurations.
- Mapping:Cadastral and environmental survey missions integrate LiDAR point cloud fusion with electro-optical video streams.
Surveillance commands the dominant procurement budget; inspection applications show the steepest expansion trajectory among civilian buyers.
End User:
Funding stability and technical sophistication create distinct purchasing patterns across buyer categories.
- Defense:Military procurement offices consolidate vendor relationships around full-motion video transmission capabilities and captive supply chains for long-range infrared turrets. Israeli and United States buyers prioritize vertically integrated electro-optical production over modular component sourcing for mission-critical unmanned combat air vehicles.
- Commercial Aviation:Airlines and MRO providers adopt camera-integrated autonomous platforms for airframe inspection, driven by FAA airworthiness directives and operational cost reduction targets.
- Aerospace:Satellite and launch vehicle manufacturers specify radiation-hardened imaging payloads for space-based applications.
- Research Institutions:Academic and government laboratories procure experimental configurations for algorithm development and flight test programs.
Defense concentrates the majority of revenue; commercial aviation is diversifying the buyer base most rapidly.
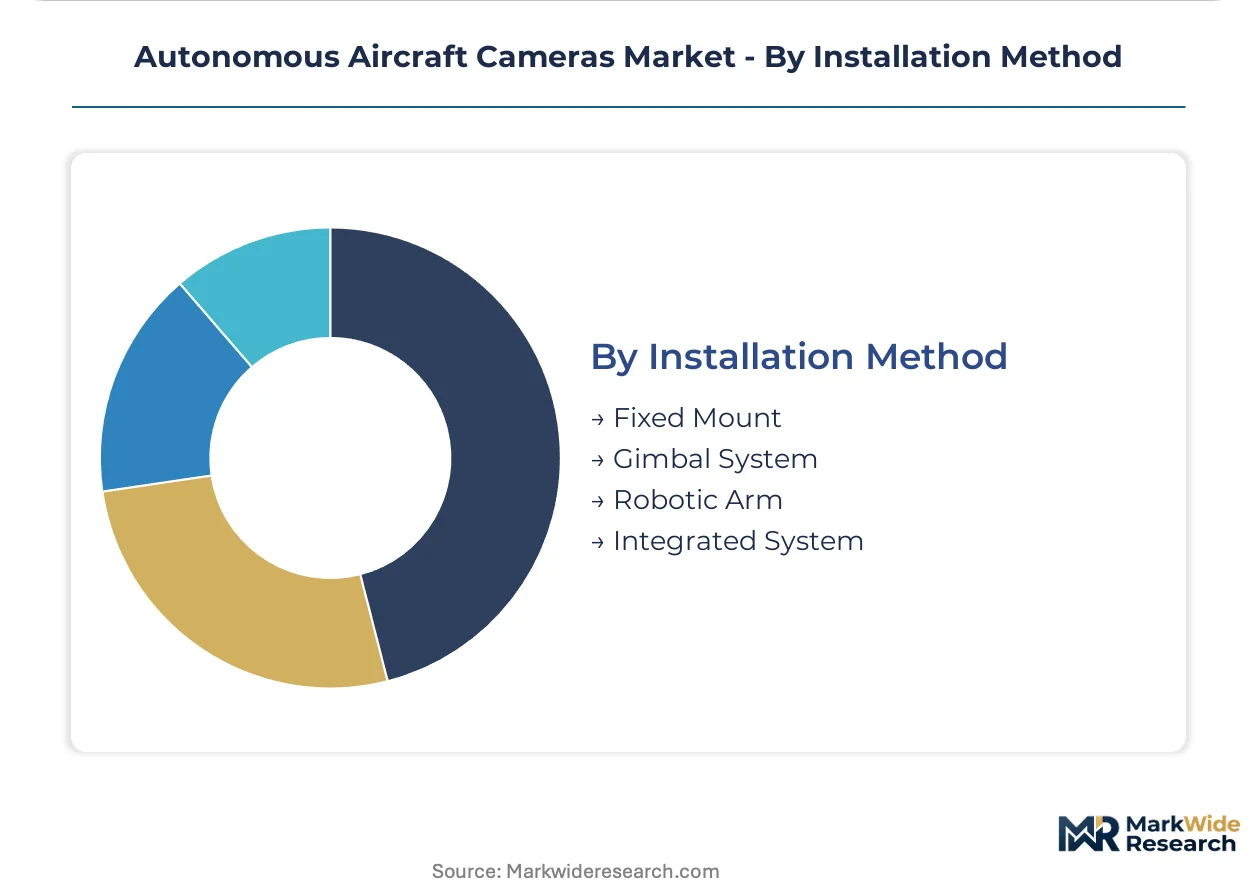
Installation Method:
Mechanical integration architecture determines vibration isolation performance and field maintainability.
- Gimbal System:Three-axis stabilized mounts with real-time gyroscopic correction represent the fastest-expanding configuration category. Intelligence, surveillance, and reconnaissance mission profiles mandate this architecture for target tracking accuracy at extended ranges.
- Fixed Mount:Rigid installations serve navigation and basic imaging functions where stabilization is handled at the airframe level.
- Robotic Arm:Articulated positioning systems enable close-proximity inspection of complex geometries.
- Integrated System:Embedded payload designs fuse camera, processing, and communications into airframe-optimized modules.
Gimbal systems lead technology investment; integrated systems are climbing the fastest as prime contractors absorb subsystem suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting electro-optical payload assembly toward jurisdictions with streamlined defense export licensing and established unmanned systems test corridors. Manufacturers are relocating final integration stages to exploit gaps in compliance cost structures across national aviation authorities.
United States
The Department of Defense accelerates procurement of gimbal-stabilized imaging systems for intelligence, surveillance, and reconnaissance drone programs. FAA Part 89 mandates compel retrofit of remote identification modules onto existing camera-integrated platforms. The Skunk Works facility in Palmdale anchors captive production of long-range infrared turrets for unmanned combat air vehicles.
Israel
Defense procurement offices concentrate orders for multi-spectral sensor fusion payloads within the Haifa-Tel Aviv technology corridor. Domestic regulations under the Israeli Ministry of Defense streamline export licensing for electro-optical components destined to allied militaries. Elbit Systems leverages vertically integrated production lines in the Negev Desert to capture premium surveillance contracts.
Germany
EASA's Specific Operations Risk Assessment framework imposes parallel certification burdens for beyond-visual-line-of-sight camera platforms. The country's national aviation regulator enforces stringent conformity requirements for autonomous aircraft operating in civil airspace. Sensor foundries in Bavaria face licensing delays for military-grade focal plane arrays under expanded dual-use export controls.
France
Thales Group sustains engineering intensity across multi-spectral programs for European unmanned systems. The French national defense procurement agency consolidates vendor relationships around full-motion video transmission capabilities. Toulouse and Paris-Saclay clusters deepen expertise in gyro-stabilized gimbal design for reconnaissance missions.
United Kingdom
The UK Ministry of Defence prioritizes embedded AI inference engines for sub-100 millisecond autonomous engagement protocols. British defense procurement guidelines favor vertically integrated electro-optical production over modular component sourcing. Bristol and Greater London metropolitan areas concentrate flight test infrastructure for camera-integrated unmanned platforms.
Autonomous Aircraft Cameras Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue edge computing specialization and commercial aviation inspection applications. The vendor base concentrates around defense prime contractors with captive electro-optical supply chains and Israeli mid-tier specialists with vertically integrated production. Three archetypes dominate: vertically integrated defense primes controlling long-range infrared turret supply, Israeli electro-optical specialists leveraging gimbal-stabilization expertise, and commercial sensor developers targeting infrastructure inspection. Competitive dynamics center on strategic absorption of subsystem suppliers and parallel certification track investments for FAA and EASA compliance.
Among defense prime contractors, Lockheed Martin Corporation and RTX Corporation exemplify the vertically integrated archetype with in-house production of stabilized imaging payloads. Elbit Systems Ltd. anchors the Israeli specialist tier through electro-optical manufacturing concentration in the defense technology corridor. These three entities represent distinct competitive positioning strategies: captive supply chain control, geographic clustering of autonomous systems expertise, and multi-spectral sensor fusion program scale.
| Leading Market Players |
|---|
| Elbit Systems Ltd. |
| Saab AB |
| RTX Corporation |
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| The Boeing Company |
| Textron Inc. |
| Teledyne FLIR LLC |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Captive electro-optical production at Israeli and US defense primes anchors supply positioning and pricing power, with in-house gimbal manufacturing and thermal core assembly insulating these suppliers from component cost volatility while enabling premium capture on multi-spectral payloads.
Pricing Analysis
Distributor margins for commercial inspection payloads compress 15-25 points below defense direct-OEM channels, where prime contractors negotiate multi-year offtake agreements. Three-tier pricing structure across military-grade, dual-use exportable, and commercial inspection levels separates buyers by certification tier and spectral capability. Cost compression in commercial HD segments intensifies as Chinese sensor foundries expand CMOS output. Small payload developers exhibit highest price sensitivity; Israeli defense procurement offices show lowest.
Supply Chain Analysis
Regional distribution centers in Tel Aviv, Palmdale, and Toulouse feed hub-and-spoke patterns for classified and unclassified payload tiers. Component concentration rests on Israeli gyro-stabilized gimbal engineering, German infrared focal plane arrays, and US multi-spectral fusion chipsets. Single-source vulnerability runs through military-grade thermal imaging cores subject to Wassenaar Arrangement licensing delays. Distribution runs through prime contractor captive networks for defense end users and specialized UAV integrators for commercial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play, with Israeli Ministry of Defense export licensing streamlining cross-border component flows at 40% lower compliance cost than EASA SORA validation in Germany.
For Market Incumbents: Anticipate margin pressure from commercial sensor developers entering infrastructure inspection with commoditized HD payloads. Consolidate through backward integration into thermal imaging core foundries to secure supply. Accelerate FAA Part 89 certification investments to capture retrofit demand from existing unmanned fleets. For New Entrants and Emerging Players: Capture white space in commercial aviation inspection for power transmission corridors and pipeline monitoring, where defense primes lack cost-competitive offerings. Penetrate through edge computing specialization with sub-100 millisecond latency architectures. Pursue direct-to-operator sales bypassing prime contractor channels. For Investors and Strategic Acquirers: Roll-up economics work for Israeli mid-tier electro-optical specialists because defense procurement consolidation around vertically integrated suppliers is displacing modular component vendors. Five-to-ten year viability hinges on dual-use export license portfolio breadth. Watch for Wassenaar Arrangement focal plane array licensing backlogs as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Cores | Lockheed Martin's captive infrared turret supply insulates against German sensor foundry licensing delays. |
| FAA Part 89 Compliance Certification | Retrofit demand from existing unmanned fleets creates immediate revenue capture for broadcast module-integrated payloads. |
| Edge Computing Architecture Migration | Onboard AI inference at 30-60 Hz eliminates ground station bandwidth constraints for full-motion video transmission. |
| Geographic Expansion to Israeli Defense Corridor | Haifa-Tel Aviv clustering concentrates gyro-stabilized gimbal engineering talent unavailable elsewhere. |
| Strategic Partnership with Commercial UAV Integrators | Channel bypass of defense prime networks opens infrastructure inspection procurement to cost-optimized payloads. |
Methodological Framework
Coverage spans the United States, Israel, Germany, France, and the United Kingdom, with primary inputs from each defense procurement office and electro-optical manufacturing cluster. Defense program executives, gimbal engineering leads, thermal imaging foundry operators, and commercial UAV fleet managers provided structured interviews. Secondary validation drew from FAA airworthiness directives, EASA SORA implementation guidance, Israeli Ministry of Defense export licensing records, and customs trade data for focal plane array components. Bottom-up payload shipment estimates and top-down defense budget allocation analysis were triangulated.
Granularity-level modeling tracked camera type, application mission profile, end-user funding source, and installation method across the projection horizon. Defense procurement volume, commercial aviation inspection adoption curves, and regulatory compliance retrofit schedules fed the analytical framework. CAGRs were derived from segment-level volume builds and price trajectory assumptions.
Export control expansion, remote identification rule acceleration, and thermal core supply disruption are the dominant revision risks to forecast outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Electric Glider Market
UAV
UAV GNSS Antenna Market
UAV
Airborne Digital Battlefield Market
UAV
UAV Simulator Software Market
UAV
Drone Lens Market
UAV
Tethered Drones Market
UAV
Commercial UAV Market
UAV
Latin America Small UAV Market
UAV
UAV Battery Market
UAV
Global Smart Commercial Drones Market
UAV
Drone Motors Market
UAV
UAV Payload and Subsystems Market
UAV
Drone Data Management Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
US Commercial Drone Market
UAV
Fixed Wing Military Drones Market