
 Maritime Surveillance and Intervention Market | 2026-2036
Maritime Surveillance and Intervention Market Size, Share, and Industry Trends Forecast 2026-2036
Maritime Surveillance and Intervention Market Intelligence
Multi-sensor data fusion capability is bifurcating the market between legacy single-source systems and advanced integrated platforms. Thales Group leverages its extensive portfolio in radar and satellite systems to offer comprehensive command-and-control solutions for naval defense forces. Saab AB specializes in advanced electronic warfare and signature management technologies, differentiating its offerings for high-threat environments. Kongsberg Gruppen ASA occupies a leading position in the unmanned surface vehicle and autonomous underwater systems segment.
Maritime surveillance and intervention is the integrated use of sensors, platforms, and command systems to monitor sea-lanes and coastal areas. These systems fuse data from Synthetic Aperture Radar (SAR) with Automatic Identification System (AIS) transponders to create a common operating picture. Satellite imaging and electro-optical/infrared sensors represent the fastest-growing technology categories, displacing older radar-only solutions. Illegal fishing detection and border control applications command the largest share of government investment.
The United Nations Convention on the Law of the Sea (UNCLOS) provides the legal framework that necessitates national surveillance of Exclusive Economic Zones (EEZs). National bodies like the US Coast Guard and the European Maritime Safety Agency (EMSA) enforce vessel safety and environmental regulations, mandating specific monitoring capabilities. Stakeholder decisions will center on balancing the high cost of persistent surveillance assets against the operational benefits of AI-driven autonomous threat detection.
Market Dynamics
The convergence of unmanned platforms with AI-driven data analytics is the central structural force shaping the market. This integration shifts maritime surveillance from a reactive, asset-intensive activity to a predictive, information-centric capability for operators like national Coast Guards.
Growth Catalysts
- UNCLOS Enforcement:The United Nations Convention on the Law of the Sea (UNCLOS) provides the legal impetus for nations to monitor and control their Exclusive Economic Zones (EEZs), directly driving government investment in surveillance systems.
- Satellite Constellation Proliferation:The expansion of commercial Synthetic Aperture Radar (SAR) satellite constellations offers more frequent and affordable wide-area maritime monitoring, complementing traditional patrol aircraft and vessels.
- IUU Fishing Countermeasures:Demand from national fisheries agencies to combat illegal, unreported, and unregulated (IUU) fishing is a primary catalyst for deploying integrated AIS and radar monitoring solutions along coastal borders.
Market Restraints
- High Capital Expenditure:The significant upfront cost of persistent surveillance platforms, particularly high-altitude long-endurance (HALE) drones and naval patrol vessels, limits acquisition volume for many national maritime security agencies.
- Data Transmission Bandwidth:In remote oceanic areas, limited satellite communication bandwidth constrains the ability to transmit high-fidelity, real-time sensor data from unmanned systems back to onshore command centers.
- Sovereignty and Data Sharing:Geopolitical tensions and national security concerns create complex legal hurdles for cross-border data sharing, impeding the formation of a unified operating picture in contested regions like the South China Sea.
Strategic Opportunities
- Offshore Infrastructure Security:The expansion of offshore wind farms and other renewable energy installations creates a new application segment for surveillance systems dedicated to protecting critical energy infrastructure from sabotage or accidents.
- Acoustic and Imagery Fusion:Integrating underwater acoustic sensor data from sonobuoys or autonomous underwater vehicles with satellite imagery presents an opportunity to develop more effective anti-submarine warfare (ASW) detection capabilities.
- Southeast Asian Coastal Modernization:Underpenetration of advanced surveillance technology in several Southeast Asian nations offers significant growth potential as they upgrade capabilities to counter piracy, smuggling, and illegal fishing.
Industry Challenges
- Legacy System Integration:A primary operational hurdle is the difficulty of integrating new AI-powered analytical tools and sensor feeds with the decades-old, proprietary command and control systems used by many naval and coast guard forces.
- Maritime Domain Talent Gap:The market faces a shortage of personnel who possess a dual expertise in both advanced data science and the specific operational complexities of the maritime environment, hindering effective system utilization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Maritime Surveillance and Intervention Market |
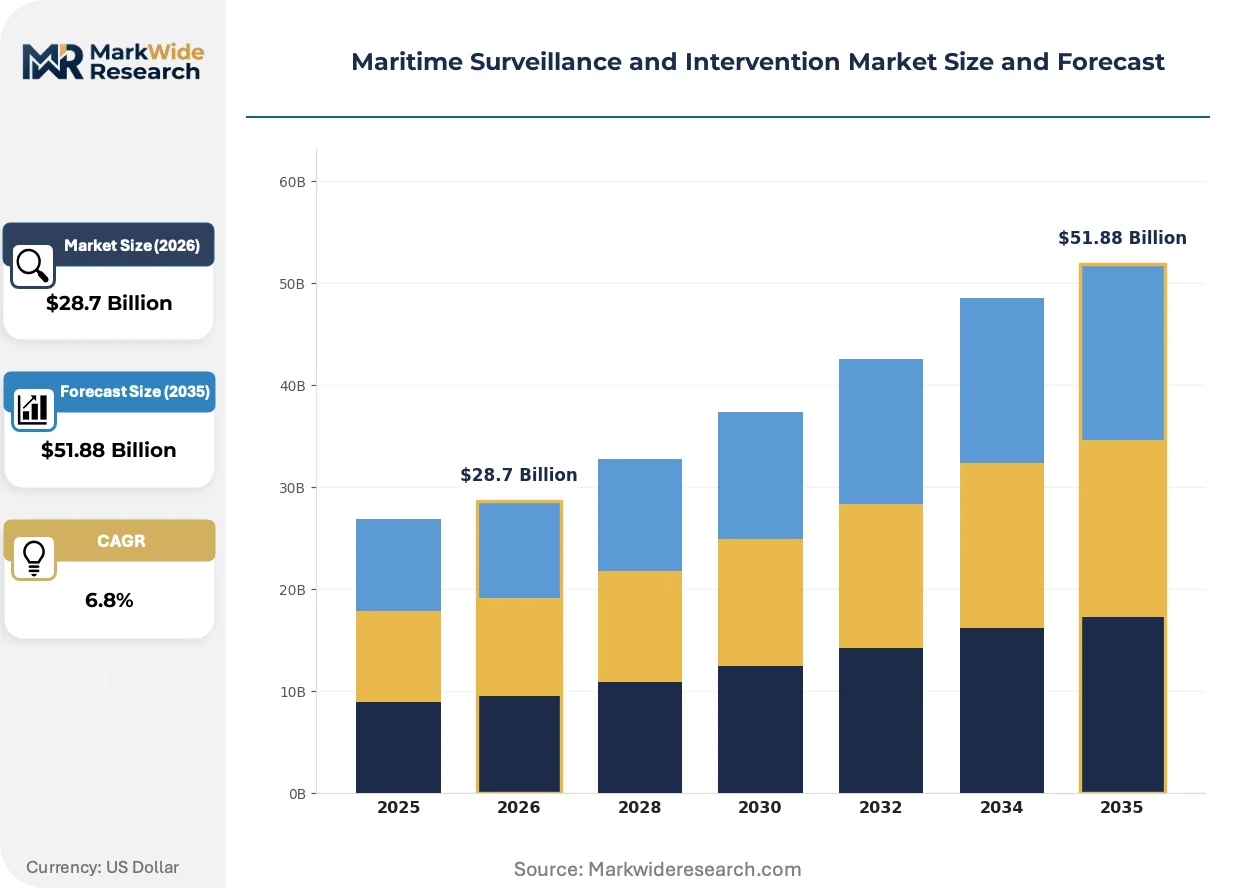
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Patrol Vessels, Unmanned Surface Vehicles, Helicopters, Satellite Systems, Fixed-wing Aircraft Technology: Radar, Sonar, AIS, Electro-Optical/Infrared Sensors, Satellite Imaging Application: Illegal Fishing Detection, Piracy Prevention, Environmental Monitoring, Border Control End User: Coast Guards, Maritime Security Agencies, Port Authorities, Naval Defense Forces |
| Companies Covered | Elbit Systems Ltd., Indra Sistemas, S.A., Saab AB, L3Harris Technologies, Inc., Dassault Aviation SA, Raytheon Technologies Corporation, Kongsberg Gruppen ASA, BAE Systems, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Maritime Surveillance and Intervention Market Strategic Shifts & Innovations
The fundamental shift from platform-centric to data-centric operations defines the current market evolution. This new paradigm prioritizes information superiority and autonomous decision-making over the mere physical presence of assets at sea, changing how navies and coast guards approach their mission.
Electro-optical/infrared (EO/IR) sensor payloads provide high-resolution, multi-spectral imaging critical for positive vessel identification day or night. These systems see rapid adoption by coast guards for deployment on smaller unmanned surface vehicles (USVs). The technology is miniaturizing, allowing sophisticated multi-sensor turrets to be fitted onto platforms previously too small to carry effective surveillance payloads.
Mandates from the International Maritime Organization (IMO) on vessel tracking, such as the Long-Range Identification and Tracking (LRIT) system, establish a digital surveillance baseline. This creates a legal foundation for national authorities to enforce compliance within their territorial waters. Coastal states in regions like West Africa are most affected, using these regulations to justify investment in AIS and radar networks to combat piracy.
A shift from outright capital purchase of surveillance assets to "data-as-a-service" models is gaining traction. This disrupts the traditional procurement cycle where government agencies owned and operated all hardware, with commercial satellite operators now offering subscription-based monitoring. This trend is most visible for environmental monitoring by agencies like the European Maritime Safety Agency (EMSA), which leverages commercial data services.
Maritime Surveillance and Intervention Market Segmentation
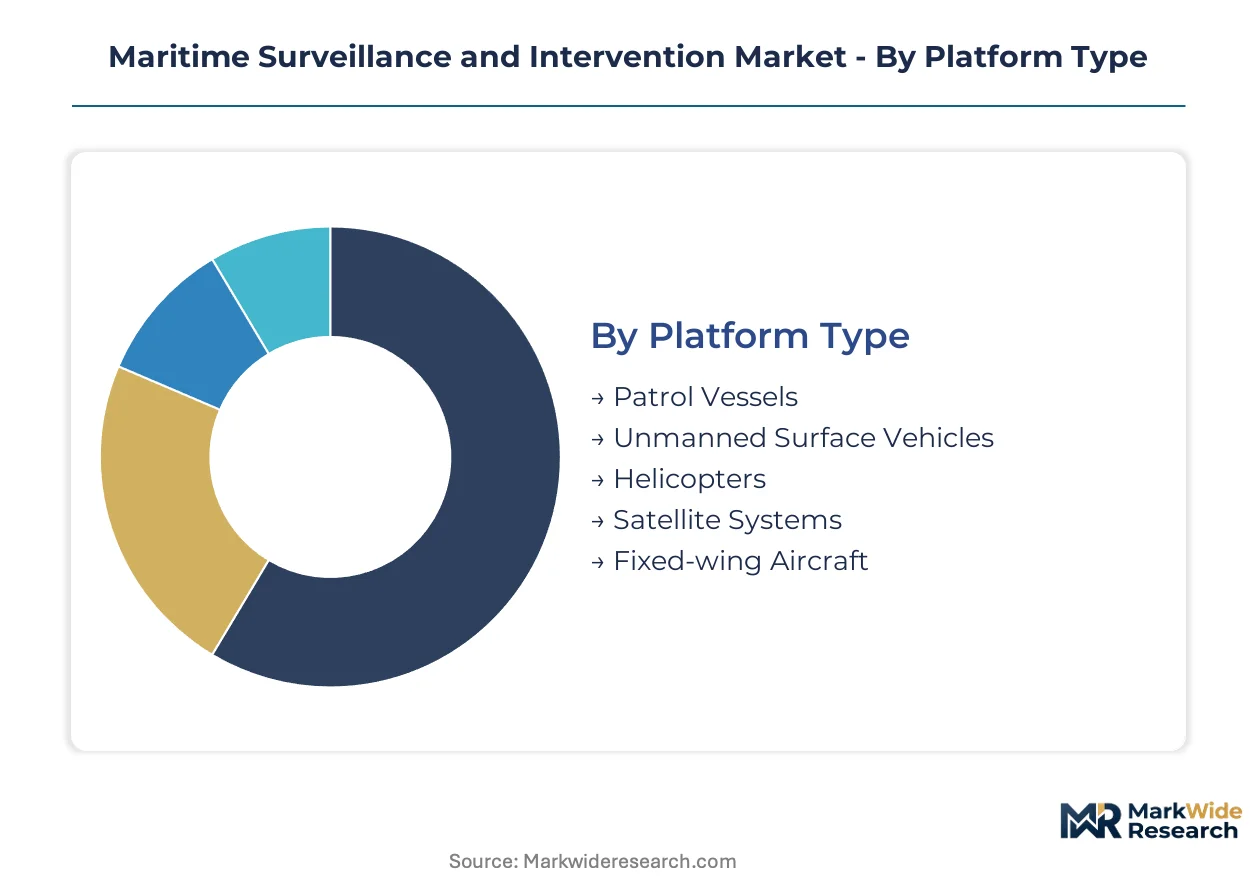
Understanding the segmentation of the Maritime Surveillance and Intervention Market is crucial for stakeholders to effectively address the diverse threats across global oceans and coastal areas.
This market requires tailored solutions that account for varying operational environments, technological capabilities, and end-user mandates, optimizing resource allocation for national security and economic interests.
Platform Type:
The deployment of maritime surveillance platforms varies significantly across national jurisdictions, with some nations prioritizing domestic coastal defense assets while others invest in long-range capabilities for international waters.
- Patrol Vessels:These robust ships form the backbone of national maritime security, providing persistent presence and interdiction capabilities. Demand for new patrol vessels is high in Southeast Asian nations like Vietnam and the Philippines, which are upgrading their naval fleets to counter piracy and illegal fishing.
- Unmanned Surface Vehicles (USVs):USVs are autonomous or remotely operated vessels equipped with various sensors for persistent, cost-effective monitoring. Their adoption is accelerating in the US Coast Guard for extended surveillance missions in remote Exclusive Economic Zones.
- Helicopters:Rotary-wing aircraft offer rapid response and aerial observation capabilities, often deployed from larger vessels or shore bases by forces such as the Japanese Coast Guard.
- Satellite Systems:These space-based assets provide wide-area, persistent monitoring across global oceans, increasingly critical for remote sensing by agencies like the European Maritime Safety Agency.
- Fixed-wing Aircraft:Maritime patrol aircraft conduct long-range surveillance and reconnaissance missions, particularly over vast oceanic areas for countries like Australia.
Patrol Vessels holds the largest share; momentum sits with Unmanned Surface Vehicles.
Technology:
The technological landscape for maritime surveillance demonstrates a clear bifurcation between mature, cost-effective solutions and advanced, higher-investment systems offering superior data fidelity.
- Radar:Radar systems provide all-weather, day-night detection of surface targets, crucial for vessel tracking and collision avoidance. Integration with other sensors is driving upgrades in radar systems for naval defense forces in Germany and the United Kingdom.
- Electro-Optical/Infrared Sensors (EO/IR):EO/IR sensors deliver high-resolution visual and thermal imaging, essential for positive vessel identification and covert operations. Their miniaturization is enabling wider deployment on smaller unmanned platforms for border control in India.
- AIS (Automatic Identification System):AIS transponders broadcast vessel identity and movement data, forming a fundamental layer for tracking commercial shipping across global sea-lanes.
- Sonar:Sonar technology detects underwater objects and submarines, critical for anti-submarine warfare and seabed mapping by navies like the US Navy.
- Satellite Imaging:Space-based imagery provides broad-area surveillance, complementing airborne and surface assets for environmental monitoring and illegal fishing detection.
Radar technology dominates the installed base, while Electro-Optical/Infrared Sensors are expanding most quickly.
Application:
Different maritime applications drive varied investment priorities, with government agencies focusing on core security mandates and environmental protection initiatives.
- Illegal Fishing Detection:This application uses integrated sensor data to identify and track vessels engaged in unauthorized fishing activities within Exclusive Economic Zones. Governments in coastal African nations like Ghana and Senegal are heavily investing in these systems to protect marine resources.
- Border Control:Border control applications involve monitoring coastal areas and maritime boundaries to prevent illicit trafficking, smuggling, and unauthorized entry. The US Coast Guard prioritizes this application for securing its extensive maritime borders.
- Piracy Prevention:Surveillance systems contribute to deterring and responding to piracy incidents, particularly in high-risk shipping lanes off the coast of Somalia.
- Environmental Monitoring:These systems track pollution, oil spills, and marine life, supporting regulatory enforcement by agencies like the European Maritime Safety Agency.
Illegal Fishing Detection represents the largest segment, with Border Control gaining significant traction.
End User:
The end-user landscape reflects distinct operational requirements and procurement processes, influencing the specialization of surveillance solutions.
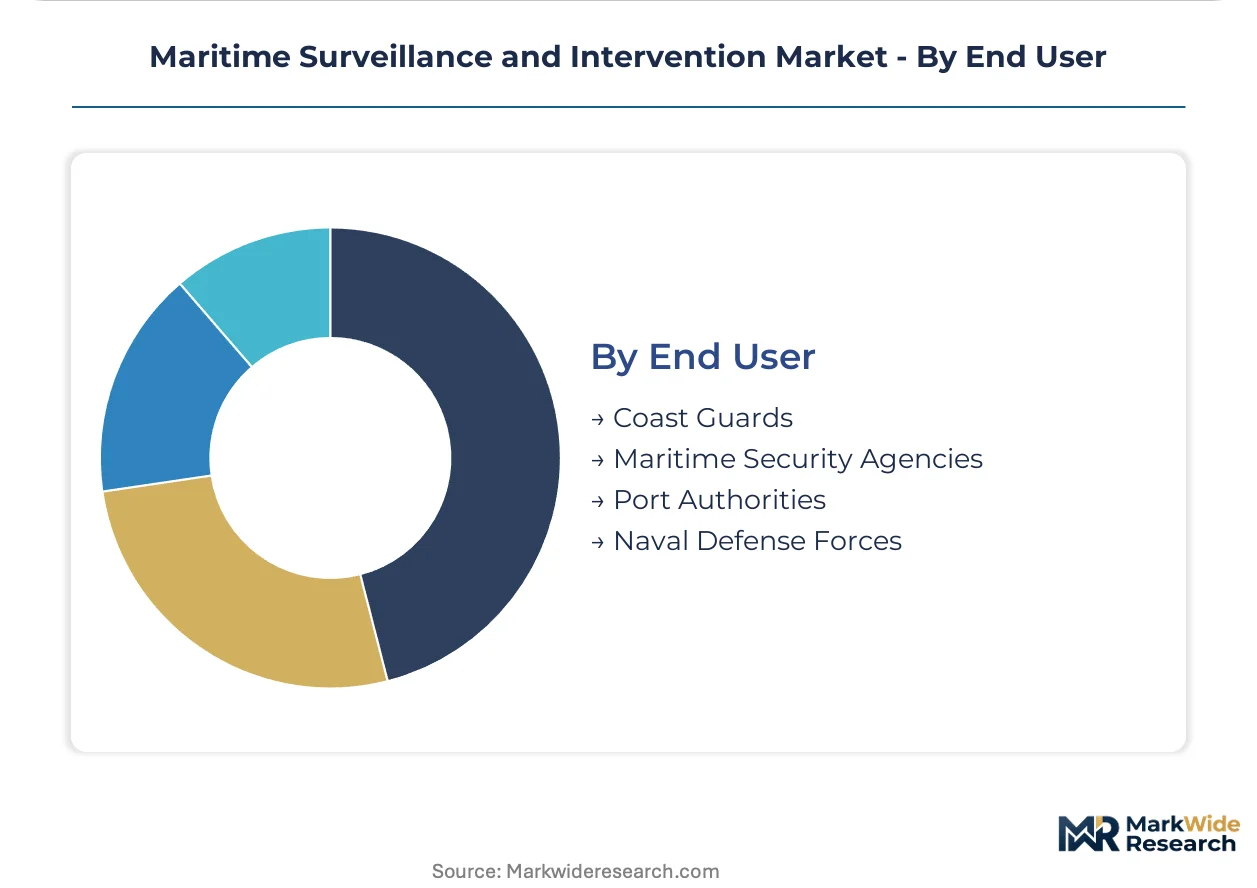
- Coast Guards:National Coast Guards require comprehensive surveillance capabilities for search and rescue, law enforcement, and environmental protection within national waters. The US Coast Guard is a major procurer of advanced multi-sensor platforms.
- Naval Defense Forces:Naval forces deploy sophisticated surveillance systems for strategic intelligence, anti-submarine warfare, and fleet protection in contested maritime environments. The French Navy integrates advanced command-and-control solutions for global operations.
- Maritime Security Agencies:These agencies focus on port security, critical infrastructure protection, and vessel traffic management in major hubs like Singapore.
- Port Authorities:Port authorities utilize surveillance for safe navigation, berth management, and security within port limits, as seen in the Port of Rotterdam.
Coast Guards hold the majority of procurement, while Naval Defense Forces show strong growth in advanced system acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The development and manufacturing of advanced maritime surveillance and intervention systems largely concentrates in nations with established defense industries. These countries possess the technological infrastructure and expertise for sophisticated sensor and platform integration. This concentration influences global market availability and innovation cycles.
United States
The United States drives demand for advanced maritime surveillance through extensive border control and persistent monitoring of its vast Exclusive Economic Zones. The US Coast Guard actively procures multi-sensor platforms to enforce vessel safety and environmental regulations. Major defense contractors in San Diego develop integrated command-and-control solutions for naval operations.
France
French naval defense forces require sophisticated surveillance for global operations and securing strategic maritime interests. The French Navy integrates advanced command-and-control solutions, emphasizing multi-sensor data fusion. Defense technology hubs in Brest concentrate expertise in radar and satellite systems for naval applications.
United Kingdom
British naval modernization programs and North Sea infrastructure security needs sustain demand for advanced maritime surveillance systems. The UK Ministry of Defence collaborates on NATO maritime security protocols, driving interoperability. Major defense centers like Portsmouth focus on developing integrated radar and electronic warfare technologies.
Sweden
Swedish defense priorities include comprehensive Baltic Sea monitoring and advanced electronic warfare capabilities. Saab AB specializes in sophisticated electronic warfare and signature management technologies for high-threat environments. Research and development centers in Linköping advance autonomous underwater and surface vehicle integration.
Singapore
Singapore's strategic location drives significant investment in port security and vessel traffic management systems. Maritime Security Agencies enforce stringent critical infrastructure protection and anti-piracy measures within its waters. The Port of Singapore serves as a key hub for deploying integrated surveillance and intervention technologies.
Maritime Surveillance and Intervention Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the maritime surveillance market. This market exhibits a tiered structure, with established defense contractors offering integrated platforms and specialized firms providing niche sensor or software solutions. Strategic archetypes include large-scale system integrators, specialized technology providers, and emerging AI analytics firms. Companies are pursuing strategic partnerships and portfolio diversification to enhance their offerings.
Specialists in integrated defense solutions and unmanned systems anchor significant market segments. Thales Group, a French multinational, exemplifies comprehensive command-and-control solutions by leveraging its extensive radar and satellite portfolio. Kongsberg Gruppen ASA, a Norwegian company, occupies a leading position in the unmanned surface vehicle and autonomous underwater systems segment. Saab AB, a Swedish defense and security company, differentiates its offerings through advanced electronic warfare and signature management technologies for high-threat environments. These players represent distinct approaches to meeting diverse maritime security needs.
| Leading Market Players |
|---|
| Elbit Systems Ltd. |
| Indra Sistemas, S.A. |
| Saab AB |
| L3Harris Technologies, Inc. |
| Dassault Aviation SA |
| Raytheon Technologies Corporation |
| Kongsberg Gruppen ASA |
| BAE Systems |
| Thales Group |
| Others |
Cost & Logistics Intelligence
Project-based contracting, common for large-scale surveillance system deployments, locks in both supply access and price visibility for national defense entities. This structure mitigates the volatility associated with individual component procurement and ensures long-term operational support.
Pricing Analysis
The United Nations Convention on the Law of the Sea (UNCLOS) dictates the pricing tier structure for surveillance systems, emphasizing compliance with international maritime law. Pricing for advanced platforms like Unmanned Surface Vehicles (USVs) follows a project-based model, incorporating extensive customization. Performance-based differentiation, tied to sensor resolution and data fusion capabilities, drives premium pricing. Pricing pressure stems from the increasing availability of commercial satellite data services, particularly for environmental monitoring applications. National Coast Guards and naval forces prioritize operational reliability, making them less price-sensitive than smaller maritime security agencies.
Supply Chain Analysis
Strategic-stockpile preferences characterize the maritime surveillance supply chain, ensuring readiness for rapid system deployments and maintenance. Supply concentration for specialized sensors and platforms centers in the United States, France, and Sweden. Key raw material dependencies include rare earth elements for advanced electronic warfare systems and specialized composites for unmanned vehicle hulls. Single-source vulnerability for high-fidelity electro-optical/infrared sensors represents a significant supply chain risk. Distribution runs through a network of defense contractors and system integrators, who often manage complex multi-vendor solutions for end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a substitution defense, as commercial data-as-a-service models increasingly threaten traditional hardware procurement for surveillance. Incumbents must adapt to evolving procurement patterns.
For Market Incumbents: Compound existing capabilities in multi-sensor data fusion to maintain a technological edge against emerging AI-driven analytics firms. Invest in developing modular, open-architecture platforms that integrate with legacy systems, addressing the industry challenge of system integration. Control the full lifecycle of surveillance data, from collection to analysis, by deepening expertise in data science, countering the maritime domain talent gap.
For New Entrants and Emerging Players: Anchor in niche application segments, such as offshore infrastructure security or acoustic-imagery fusion for anti-submarine warfare. Target underpenetrated Southeast Asian coastal modernization efforts by offering cost-effective, AI-powered autonomous threat detection solutions. A compelling go-to-market angle involves providing "data-as-a-service" models, disrupting traditional capital expenditure procurement cycles for agencies like the European Maritime Safety Agency.
For Investors and Strategic Acquirers: Specialized technology providers with strong intellectual property in AI-driven data analytics and miniaturized sensor payloads represent attractive acquisition targets. The long-term viability of this market hinges on persistent geopolitical tensions and the increasing demand for Exclusive Economic Zone (EEZ) enforcement. A signal to watch is the adoption rate of commercial satellite data by national Coast Guards, indicating a shift in procurement priorities.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-driven autonomous threat detection | Enhances operational efficiency and reduces human resource dependency for maritime security agencies. |
| Expand "data-as-a-service" offerings | Disrupts traditional procurement by providing flexible, subscription-based access to surveillance intelligence. |
| Invest in miniaturized EO/IR sensor technology | Enables wider deployment on smaller unmanned platforms, increasing monitoring flexibility and cost-effectiveness. |
| Form strategic partnerships for system integration | Addresses the complex challenge of integrating new technologies with existing legacy command-and-control systems. |
| Target coastal modernization in Southeast Asia | Captures significant growth potential in nations upgrading capabilities against piracy and illegal fishing. |
Research Approach
The analysis maps platform types, technologies, applications, and end-users, each validated through interviews with naval defense executives, coast guard commanders, and maritime security agency officials. Secondary data from United Nations Convention on the Law of the Sea (UNCLOS) reports, International Maritime Organization (IMO) mandates, and national defense procurement documents informed the market landscape. This approach combined bottom-up and top-down triangulation for comprehensive market sizing.
Outputs were consistently checked against external benchmarks, ensuring the analytical framework's robustness across the analysis window. The model segmented the market by platform type, technology, application, end-user, and regional demand dynamics. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected future investment cycles. Key forecast inputs included national defense budgets for maritime security and the proliferation rates of commercial satellite constellations.
Decision-makers should treat outputs as directional under current geopolitical stability and technological development assumptions; material deviation would warrant model refresh. Forecasts reflect assumptions documented through extensive primary and secondary research. Revision becomes warranted when major regulatory shifts or significant technological breakthroughs cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Military Surveillance
Global Airborne Warning and Control System Market
Military Surveillance
Global Radar Market
Military Surveillance
Electronically Scanned Array Radar Market
Military Surveillance
Hydrographic Survey Equipment Market
Military Surveillance
Global Signals Intelligence (SIGINT) Market
Military Surveillance
Manportable Radar Market
Military Surveillance
Military Electro-Optics/Infrared (EO/IR) Systems Market
Military Surveillance
Airborne Target Acquisition Systems Market
Military Surveillance
Military Manportable Surveillance Radar Market
Military Surveillance
North America Passive Radar Market
Military Surveillance
Global Military Thermal Imaging Market
Military Surveillance
Long Range Radar Systems Market
Military Surveillance
Defense Geospatial Market
Military Surveillance
Mmwave Radar Market
Military Surveillance
Global Airborne Surveillance Market
Military Surveillance
Tactical Scope Market