
 Military Unmanned Aerial Vehicles Market | 2026-2036
Military Unmanned Aerial Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
Military Unmanned Aerial Vehicles Market Outlook
Multi-source avionics procurement is rebalancing toward in-house sensor integration as prime contractors seek supply chain resilience. General Atomics Aeronautical Systems leverages captive production of electro-optical payloads to protect margin pools. Northrop Grumman Corporation anchors its position through classified programs in high-altitude long-endurance segments. Lockheed Martin Corporation dominates hypersonic-adjacent UAV research with Skunk Works-derived manufacturing protocols.
Military unmanned aerial vehicles are fixed-wing, multi-rotor, or hybrid aircraft operating without onboard human pilots, typically spanning wingspans from two meters to forty meters and achieving endurance profiles from ninety minutes to forty-two hours for intelligence collection or strike missions. Fixed-wing platforms sustain the largest revenue share due to fuel-efficient loiter capacity over contested theaters. Multi-rotor systems are displacing manned alternatives in urban close-quarters reconnaissance where vertical takeoff constraints dominate. Payload capacity segmentation shows heavyweight signal-intelligence configurations carrying synthetic aperture radars generate the steepest margin premiums.
The FAA imposes Certificate of Authorization requirements for military UAV transit through domestic air corridors, while the EASA F-Gas Regulation constrains thermal management refrigerants in European-deployed systems. Israel's CAAI and Turkey's DGCA enforce sovereign data-localization standards that block foreign telemetry architectures from national security missions. Stakeholders must monitor divergence between NATO STANAG interoperability mandates and bilateral host-nation flight restrictions when positioning fleet modernization investments.
Market Dynamics
Defense procurement offices are forcing prime contractors to absorb sensor integration costs previously passed through to subsystem vendors, compressing margin structures and triggering captive production investments across the supply tier.
Growth Catalysts
- NATO STANAG interoperability mandates:Allied defense ministries are synchronizing datalink protocols and command interfaces, creating pooled procurement volumes that reward compliant platform architectures.
- Synthetic aperture radar miniaturization:Advances in gallium nitride semiconductor packaging are shrinking SWaP-C footprints for signal-intelligence payloads, opening tactical-class airframes to missions previously requiring strategic platforms.
- Turkey:The Undersecretariat for Defence Industries is accelerating domestic production quotas through offset requirements that localize avionics sourcing and flight-control software development.
Market Restraints
- Export control fragmentation:The US International Traffic in Arms Regulations and the EU Dual-Use Regulation impose divergent licensing timelines for encrypted communications modules, delaying fleet deliveries.
- Specialized foundry concentration:Radiation-hardened processor fabrication relies on a single qualified facility in the United States, creating single-point vulnerability for mission-computer supply.
- Propulsion thermal limits:Heavy-fuel engines for shipboard compatibility sacrifice power-to-weight ratios against aviation gasoline alternatives, constraining payload-range tradeoffs for naval rotary-wing systems.
Strategic Opportunities
- Urban counter-UAS integration:Municipal police forces in Germany and France are establishing dedicated unmanned systems units requiring military-grade hardware with civilian airworthiness certification.
- Artificial intelligence-enabled sensor fusion:Convergence of edge-computing accelerators with multi-spectral imaging arrays enables real-time target recognition without ground-station bandwidth dependency.
- India:The Ministry of Defence's negative import list and strategic partnership model are channeling foreign OEMs toward joint ventures with Bharat Electronics and Hindustan Aeronautics for domestic assembly.
Industry Challenges
- Airworthiness certification timelines:The FAA's Certificate of Authorization process for beyond-line-of-sight operations averages fourteen months, compressing operational readiness windows for urgent procurement.
- Secure software workforce scarcity:Qualified engineers with both DO-178C safety-critical certification experience and classified security clearances command premium compensation that strains program budgets.
- Legacy datalink interoperability:Fielded ground control stations from the 2000s operate on proprietary waveforms that resist integration with modern IP-based network architectures without expensive retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Unmanned Aerial Vehicles Market |
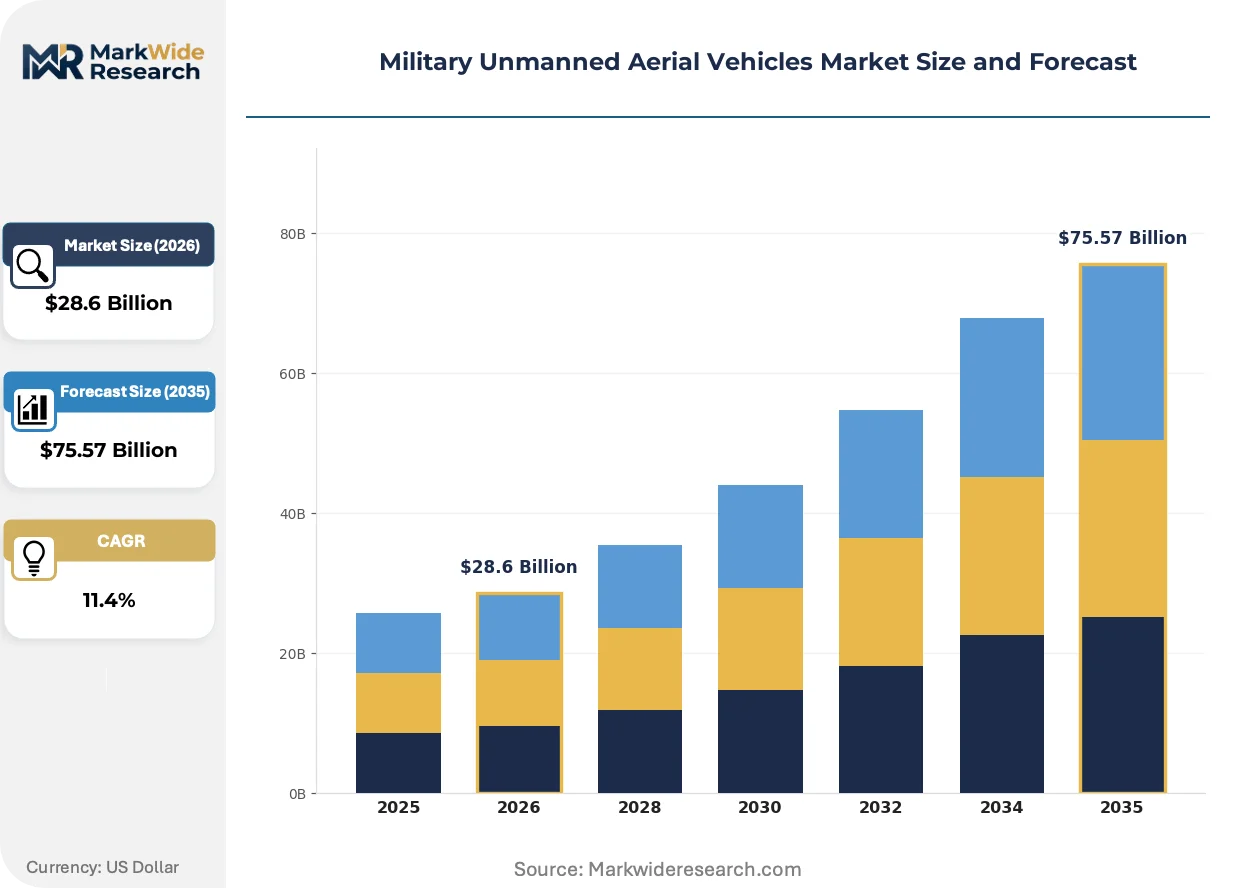
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Single-Rotor Payload Capacity: Lightweight, Medium, Heavyweight, Super Heavy Application: Surveillance, Reconnaissance, Combat, Cargo Transport Control Mode: Remote Control, Autonomous, Semi-Autonomous, Manual |
| Companies Covered | General Atomics Aeronautical Systems, Northrop Grumman Corporation, Lockheed Martin Corporation, AeroVironment, Israel Aerospace Industries, Elbit Systems, BAE Systems, Textron, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Unmanned Aerial Vehicles Market Strategic Shifts
Active electronically scanned array technology is migrating from strategic platforms to tactical airframes, while sovereign data-localization requirements are fragmenting telemetry architectures across national boundaries.
Multi-domain command-and-control software is consolidating previously stovepiped air, maritime, and ground unmanned systems under unified tasking authorities. The US Air Force's Advanced Battle Management System and the British Army's Land Environment Air Picture Provision program are both mandating common operating picture interfaces. This consolidation is compressing vendor-specific ecosystem advantages and rewarding modular, open-architecture platform designs.
The EASA F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in thermal management systems for European-deployed platforms, forcing redesigns of avionics cooling loops. Manufacturers are responding with pumped two-phase cooling alternatives that eliminate refrigerant dependency. High-altitude long-endurance segments face the steepest redesign burden due to extended thermal soak periods at stratospheric altitudes.
Defense ministries are unbundling platform procurement from through-life support contracts, creating separate competitions for maintenance, repair, and overhaul services. The British Ministry of Defence's Defence Equipment Plan and Australia's Sovereign Industrial Capability Priorities both emphasize domestic sustainment workforce development. Australia anchors this shift most visibly, with the RAAF's MQ-28 Ghost Bat program structuring separate vendor selections for production and in-country deep maintenance.
Military Unmanned Aerial Vehicles Market Segmentation
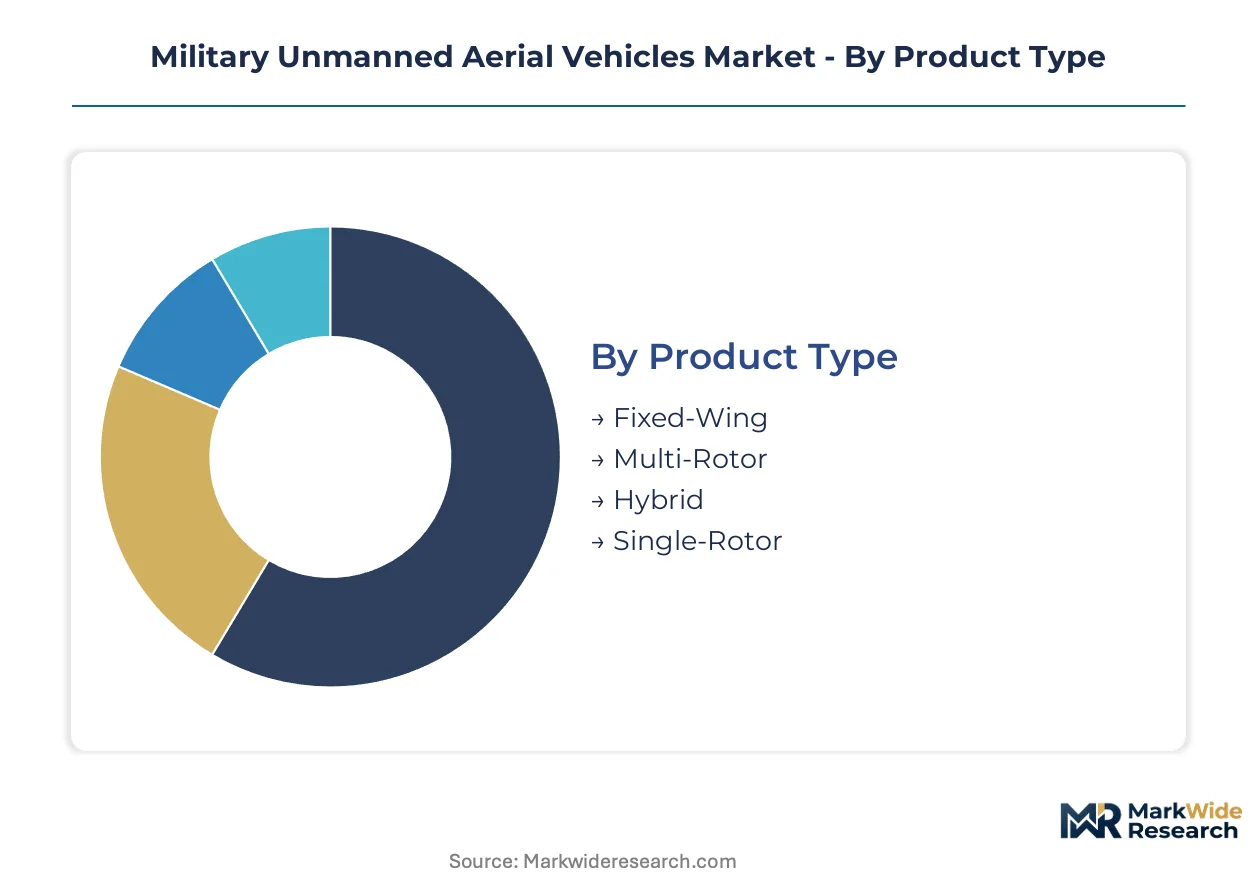
Military UAV procurement splits sharply between high-volume tactical platforms and low-volume strategic systems with divergent margin structures. Platform architecture determines operational ceiling, endurance, and sensor payload integration complexity. Control mode selection increasingly shapes through-life software certification costs and operator training pipelines.
Product Type:
Fixed-wing platforms command premium unit economics against rotary alternatives, while multi-rotor systems dominate procurement volume in urban warfare applications.
- Fixed-Wing:Fuel-efficient airframes with wingspans exceeding twenty meters sustain forty-plus hour endurance for strategic ISR over contested theaters. Demand concentrates in the United States and Israel where long-range strike-integrated reconnaissance missions require extended loiter capacity combined with heavy synthetic aperture radar payloads.
- Multi-Rotor:Vertical takeoff capability enables deployment from confined urban terrain without prepared runways. Procurement accelerates in Turkey's border security operations and German municipal counter-UAS units where building-dense environments constrain fixed-wing operations.
- Hybrid:Tilt-rotor configurations merge runway independence with transit efficiency for shipboard deployment.
- Single-Rotor:Conventional helicopter architectures persist in naval mine-countermeasure missions requiring precision hover.
Today's leader: Fixed-Wing. Tomorrow's challenger: Multi-Rotor.
Payload Capacity:
Weight class segmentation tracks directly with signal-intelligence mission sophistication and thermal management system requirements.
- Heavyweight:Synthetic aperture radar and signals intelligence suites exceeding five hundred kilograms demand reinforced airframes and dedicated power generation. The British Army's Watchkeeper program and French Thales Patroller deployments anchor demand in European NATO states combined with sovereign datalink encryption mandates.
- Lightweight:Electro-optical and infrared sensors under fifty kilograms enable squad-level deployment from backpack-transportable airframes. Israeli Defense Forces and Ukrainian territorial defense units drive procurement where man-portable launch and acoustic signature suppression dominate operational requirements.
- Medium:Multi-spectral targeting pods bridge tactical and strategic mission profiles.
- Super Heavy:Hypersonic testbed and loyal wingman configurations carry external stores exceeding one metric ton.
Heavyweight configurations extract steepest margin premiums; Lightweight segments are expanding most quickly in asymmetric warfare procurement.
Application:
Mission type determines sensor fusion complexity and airworthiness certification pathway divergence between civil and military regulators.
- Surveillance:Persistent wide-area motion imagery requires stabilized gimbal systems and beyond-line-of-sight datalinks for border monitoring. India's Ministry of Defence deploys Israeli-derived platforms along the Line of Actual Control combined with domestic assembly requirements under strategic partnership frameworks.
- Combat:Strike-integrated platforms with weapon release authority demand man-in-the-loop verification architectures and collateral damage estimation algorithms. Turkish operations in Syria and Libya demonstrate autonomous target recognition limitations combined with NATO interoperability constraints.
- Reconnaissance:Deep-penetration missions prioritize low-observable signatures and electronic warfare self-protection.
- Cargo Transport:Tactical resupply to forward operating bases drives heavy-lift rotary development.
Surveillance missions absorb largest procurement volume; Combat applications face steepest regulatory friction.
Control Mode:
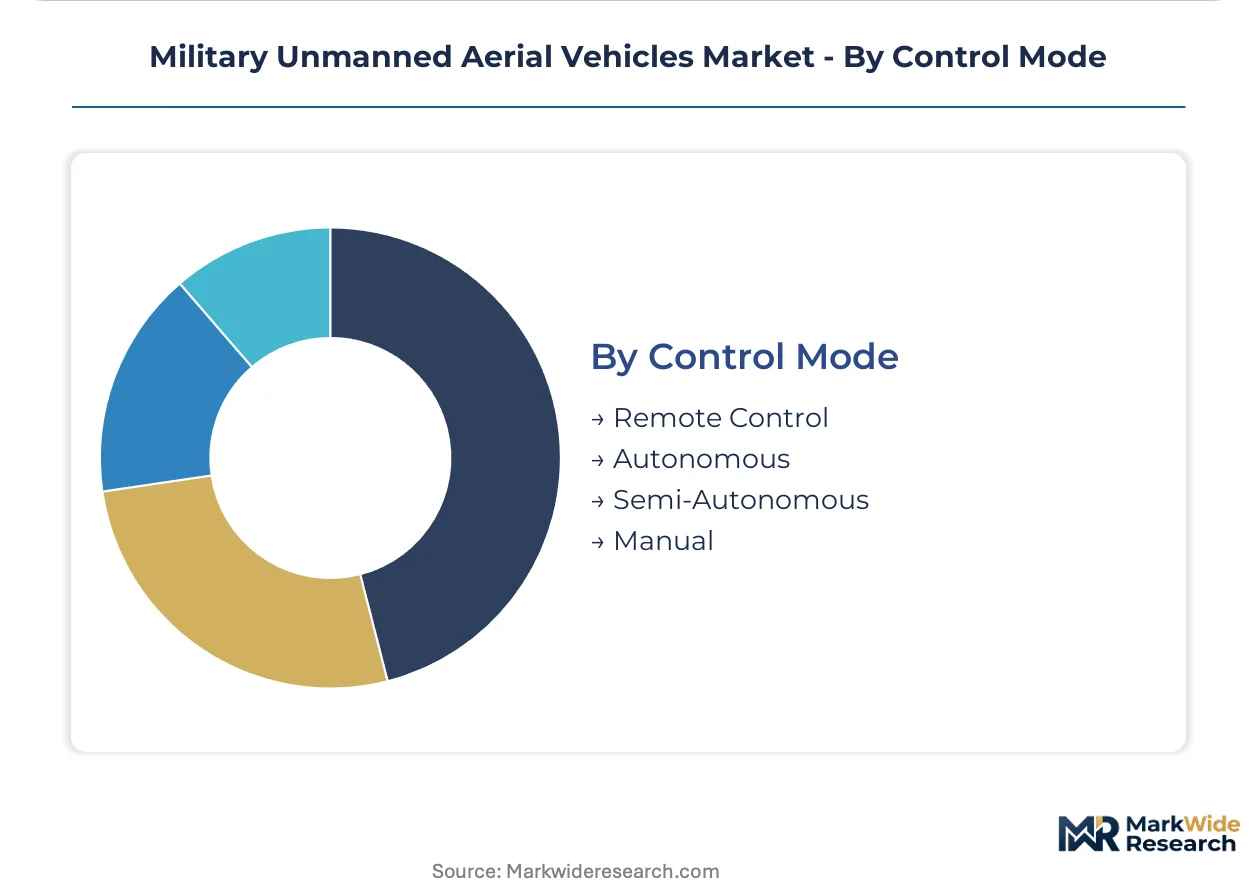
Autonomy level selection constrains software certification scope and cyber-attack surface exposure across fleet architectures.
- Autonomous:Pre-programmed waypoint navigation with obstacle avoidance eliminates continuous radio frequency emissions vulnerable to electronic warfare detection. Australian MQ-28 Ghost Bat and US Navy MQ-25 Stingray programs anchor development combined with artificial intelligence-enabled sensor fusion investments.
- Remote Control:Direct radio link operation persists in close-quarters urban reconnaissance where GPS denial threatens autonomous navigation integrity. Israeli tactical units and French Gendarmerie procurement emphasize jam-resistant directional datalinks combined with minimal latency requirements.
- Semi-Autonomous:Supervised autonomy with human abort authority balances mission flexibility with rules-of-engagement compliance.
- Manual:Stick-and-throttle control survives in training and contested electromagnetic spectrum environments.
Semi-Autonomous modes dominate current procurement; Fully Autonomous architectures are gaining share fastest in denied-area penetration missions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement offices exploit regulatory-arbitrage gaps between jurisdictions with streamlined military airworthiness pathways and those burdened by dual-use export controls. Production investment migrates toward countries offering sovereign data-localization waivers and accelerated flight certification timelines.
United States
The Pentagon's Replicator initiative accelerates procurement of attritable autonomous systems for Indo-Pacific theater operations. The FAA Certificate of Authorization process constrains domestic training flights, pushing operational testing toward restricted military airspace in Nevada and Arizona. General Atomics maintains captive electro-optical production lines in Poway, California to insulate margins from subcontractor pass-through costs.
Israel
The Israeli Defense Forces sustain operational tempo in Gaza and Lebanon border zones, consuming tactical-class rotary platforms at rates exceeding replacement schedules. The Civil Aviation Authority of Israel enforces sovereign telemetry encryption standards that block foreign ground-control architectures from national security missions. Elbit Systems and Israel Aerospace Industries cluster production around Haifa's defense corridor, leveraging cleared workforce pools with signals-intelligence specialization.
Turkey
The Undersecretariat for Defence Industries enforces domestic production quotas through offset requirements that localize flight-control software development and avionics sourcing. Baykar and Turkish Aerospace Industries concentrate manufacturing in Ankara and Istanbul, feeding sustained operational demand from Syria and Libya theaters. The Directorate General of Civil Aviation maintains bilateral friction with NATO STANAG interoperability mandates over sovereign datalink protocols.
United Kingdom
The British Army's Watchkeeper program anchors European demand for heavyweight synthetic aperture radar configurations with sovereign encryption modules. The Ministry of Defence's Defence Equipment Plan unbundles platform procurement from through-life support contracts, creating separate competitions for domestic sustainment workforce development. BAE Systems positions production around Warton and Samlesbury aerodromes, capturing classified high-altitude long-endurance development contracts.
Australia
The Royal Australian Air Force's MQ-28 Ghost Bat program structures separate vendor selections for production and in-country deep maintenance, mandating sovereign industrial capability development. The Defence Strategic Review prioritizes autonomous collaborative platforms for contested airspace penetration in hypothetical Taiwan scenarios. Boeing Australia anchors development in Brisbane with Queensland government co-investment in advanced manufacturing facilities.
Military Unmanned Aerial Vehicles Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue loyal wingman and attritable systems architectures outside traditional prime contractor ecosystems. The vendor base stratifies between integrated platform-sensor houses and subsystem specialists dependent on prime contractor sourcing decisions. Two archetypes dominate: captive vertical integrators protecting margin pools through in-house payload production, and modular open-architecture platforms designed for rapid subsystem swap. Competitive intensity concentrates on M&A activity targeting cleared workforce acquisition and strategic partnerships securing host-nation offset compliance.
Among US-based integrated primes, General Atomics Aeronautical Systems, Northrop Grumman Corporation, and Lockheed Martin Corporation exemplify contrasting strategic postures. General Atomics represents the captive integration archetype through controlled electro-optical supply chains. Northrop Grumman occupies a position anchored in classified high-altitude long-endurance segments with restricted competitive access. Lockheed Martin exemplifies hypersonic-adjacent research positioning through Skunk Works-derived manufacturing protocols. Each sits within distinct margin pools shaped by program security classification levels and sovereign data-localization compliance requirements.
| Leading Market Players |
|---|
| General Atomics Aeronautical Systems |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| AeroVironment |
| Israel Aerospace Industries |
| Elbit Systems |
| BAE Systems |
| Textron |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
The EASA F-Gas Regulation and its hydrofluorocarbon phase-down mandates gate both qualified thermal-management suppliers and premium-tier pricing access for European-deployed military UAV platforms, compressing margins for non-compliant producers while rewarding redesign investments with pricing power.
Pricing Analysis
Input-cost pass-through from gallium nitride semiconductor packaging and radiation-hardened processor fabrication flows unevenly across tiered pricing structures. Premium-mid-economy pricing differentiation separates sovereign-encryption-compliant platforms from standard NATO STANAG configurations, with certification-grade and volume-scale as primary price drivers. Pricing pressure stems from defense procurement offices forcing prime contractors to absorb sensor integration costs previously passed to subsystem vendors. Tactical-class rotary platforms face the steepest price sensitivity due to attritable procurement models, while strategic high-altitude long-endurance systems retain inelastic demand.
Supply Chain Analysis
Reverse-logistics flows for thermal management system refurbishment and mission-computer remanufacturing concentrate in the United States, Israel, and Turkey where sovereign data-localization requirements mandate domestic deep maintenance. The supply chain draws from specialized gallium nitride foundries, heavy-fuel engine producers, and synthetic aperture radar component houses. Single-source vulnerability in radiation-hardened processor fabrication at a single qualified US facility creates structural supply risk. Distribution runs through prime contractor captive production networks and offset-mandated joint ventures in host nations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The military UAV market functions as a geographic-arbitrage play where accelerated FAA Certificate of Authorization timelines in restricted military airspace contrast with fourteen-month averages for beyond-line-of-sight operations, rewarding production positioning near Nevada and Arizona test corridors.
For Market Incumbents: Lock in cleared workforce pools with DO-178C safety-critical certification and classified security clearances before compensation premiums escalate further. Absorb sensor integration costs through backward integration into electro-optical payload production, protecting margin pools against procurement office cost-shifting. Counter emerging modular open-architecture entrants by anchoring proprietary datalink ecosystems. For New Entrants and Emerging Players: The premium-economy price-point gap in tactical-class rotary platforms offers white-space entry for attritable systems with civilian airworthiness dual-certification. Municipal counter-UAS units in Germany and France present the most penetrable segment given military-grade hardware requirements with civilian regulator pathways. Pursue sovereign offset partnerships with Turkey's Undersecretariat for Defence Industries or India's Ministry of Defence to bypass prime contractor gatekeeping. For Investors and Strategic Acquirers: Roll-up economics work for modular avionics subsystem specialists because defense ministry unbundling of platform procurement from through-life support contracts fragments vendor ecosystems and rewards consolidated maintenance, repair, and overhaul capabilities. Target cleared workforce acquisition in signals-intelligence specialization clusters around Haifa or Ankara. Monitor FAA and EASA airworthiness certification timeline divergence as an inflection indicator for production geography shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Electro-Optical Production | General Atomics' Poway facility insulates margins from subcontractor pass-through cost compression. |
| Sovereign Data-Localization Compliance | Israel's CAAI encryption standards block foreign telemetry architectures from national security missions. |
| Modular Open-Architecture Design | BAE Systems' Warton positioning captures classified high-altitude long-endurance development contracts. |
| Offset-Mandated Joint Ventures | Turkey's Undersecretariat for Defence Industries localizes flight-control software through Baykar production quotas. |
| Dual Civil-Military Certification | Boeing Australia's Brisbane facility serves RAAF MQ-28 Ghost Bat with Queensland government co-investment. |
Study Parameters
Coverage spans the United States, Israel, Turkey, the United Kingdom, and Australia, with primary inputs from each combining interviews with defense procurement officers, prime contractor program managers, subsystem vendor executives, and regulatory affairs specialists with secondary validation. Secondary sources include FAA Certificate of Authorization filings, EASA F-Gas Regulation compliance disclosures, NATO STANAG documentation, and defense ministry budget appropriations. Bottom-up platform delivery tracking and top-down defense expenditure analysis provide triangulation.
Rate-of-change decomposition separates volume growth from mix-shift effects across fixed-wing, multi-rotor, and hybrid platform architectures over the projection horizon. Segmentation dimensions modeled include payload capacity tier, control mode autonomy level, application mission type, and regional regulatory cluster. CAGRs derive from defense budget trajectory analysis and procurement schedule acceleration factors. Industry-specific inputs encompass synthetic aperture radar miniaturization curves and sovereign data-localization mandate adoption timelines.
Caveats apply where export control fragmentation between US ITAR and EU Dual-Use Regulation timelines, specialized foundry concentration risk, or propulsion thermal limit breakthroughs could materially shift the outlook. Practitioners should monitor FAA-EASA airworthiness certification divergence and NATO STANAG interoperability friction with bilateral host-nation restrictions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Drone Sensor Market
UAV
Unmanned Combat Aerial Vehicle Market
UAV
Global Drone Data Services Market
UAV
Europe Tethered Drone Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Europe Tactical UAV Market
UAV
Ultra-Long Endurance Drone Market
UAV
Commercial UAV Market
UAV
Drone Inspection Service Market
UAV
Global Aerial Survey Services Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
UAV Simulator Market
UAV
Drone Delivery Services Market
UAV
GCC Drone Pilot Training Market
UAV
Short-Range Delivery Drone Market
UAV
Multirotor Drones Market