
 Small UAV Market | 2026-2036
Small UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Small UAV Market Outlook
China's Guangdong manufacturing corridor is tilting global supply toward Asia-Pacific production density. DJI leverages captive component ecosystems and in-house semiconductor design to sustain cost leadership across consumer and enterprise tiers. AeroVironment anchors defense and tactical segments through hardened platform specifications and Pentagon procurement channels. Skydio differentiates via autonomous navigation stacks that dominate complex obstacle-dense environments for public safety and infrastructure inspection.
Small UAVs are uncrewed aerial vehicles with maximum takeoff weights below 25 kilograms, typically employing electric propulsion, composite airframes, and multi-rotor or fixed-wing configurations for tasks spanning reconnaissance, payload delivery, and geospatial data capture. Rotary-wing platforms occupy the highest volume share due to vertical takeoff flexibility and mechanical simplicity, while fixed-wing systems extend endurance for agricultural mapping and corridor surveillance where runway independence matters less. Hybrid architectures are gaining traction in delivery trials where payload range requirements exceed pure multi-rotor capability.
The FAA Remote ID rule and EASA open-category framework are bifurcating product development roadmaps, with manufacturers engineering dual-compliance architectures for transatlantic market access. China's CAAC and MIIT coordinate airspace classification and radio equipment certification, creating layered approval barriers for foreign entrants. India's DGCA drone rules and BIS quality mandates are accelerating local assembly requirements. Stakeholders must monitor evolving beyond-visual-line-of-sight waivers and detect-and-avoid mandates, as these regulatory thresholds will determine which platform architectures achieve scalable deployment.
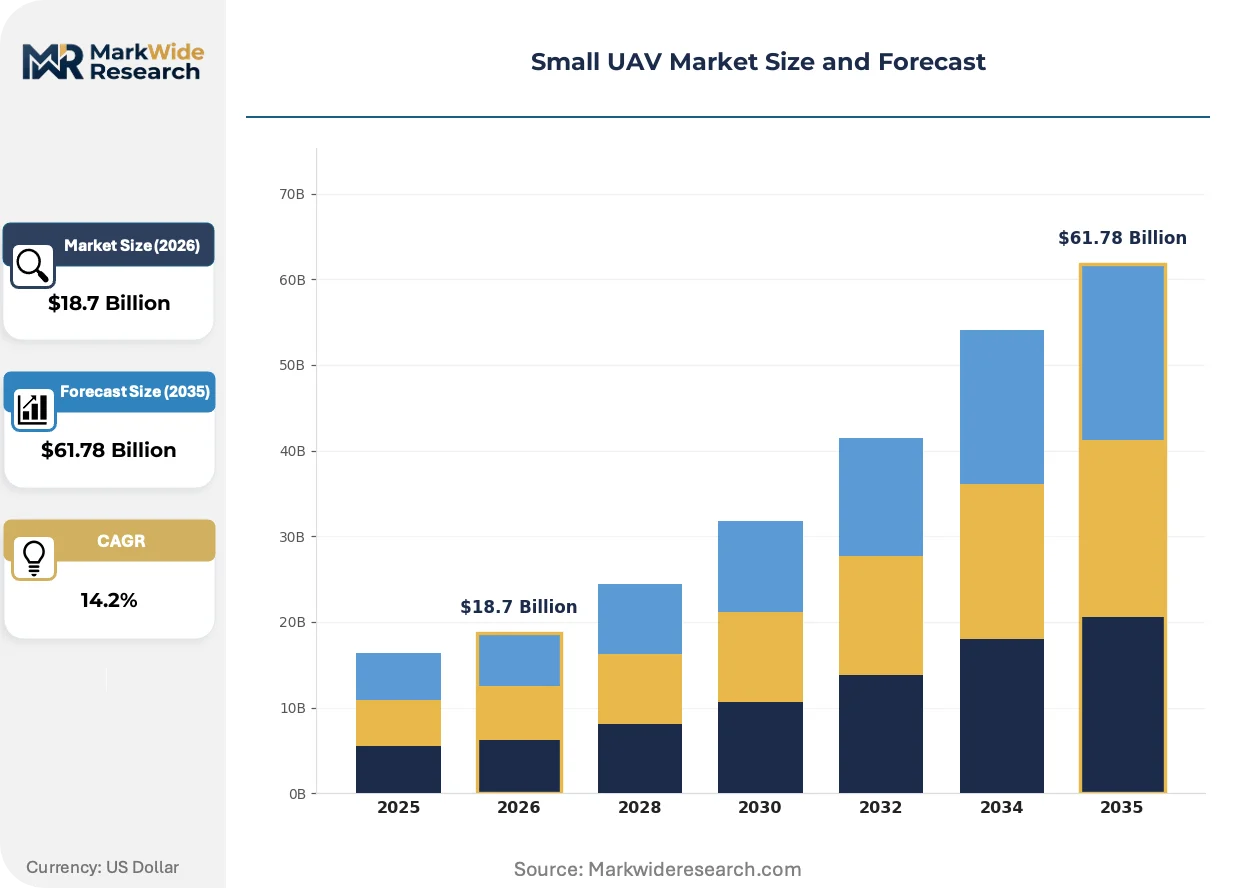
Market Dynamics
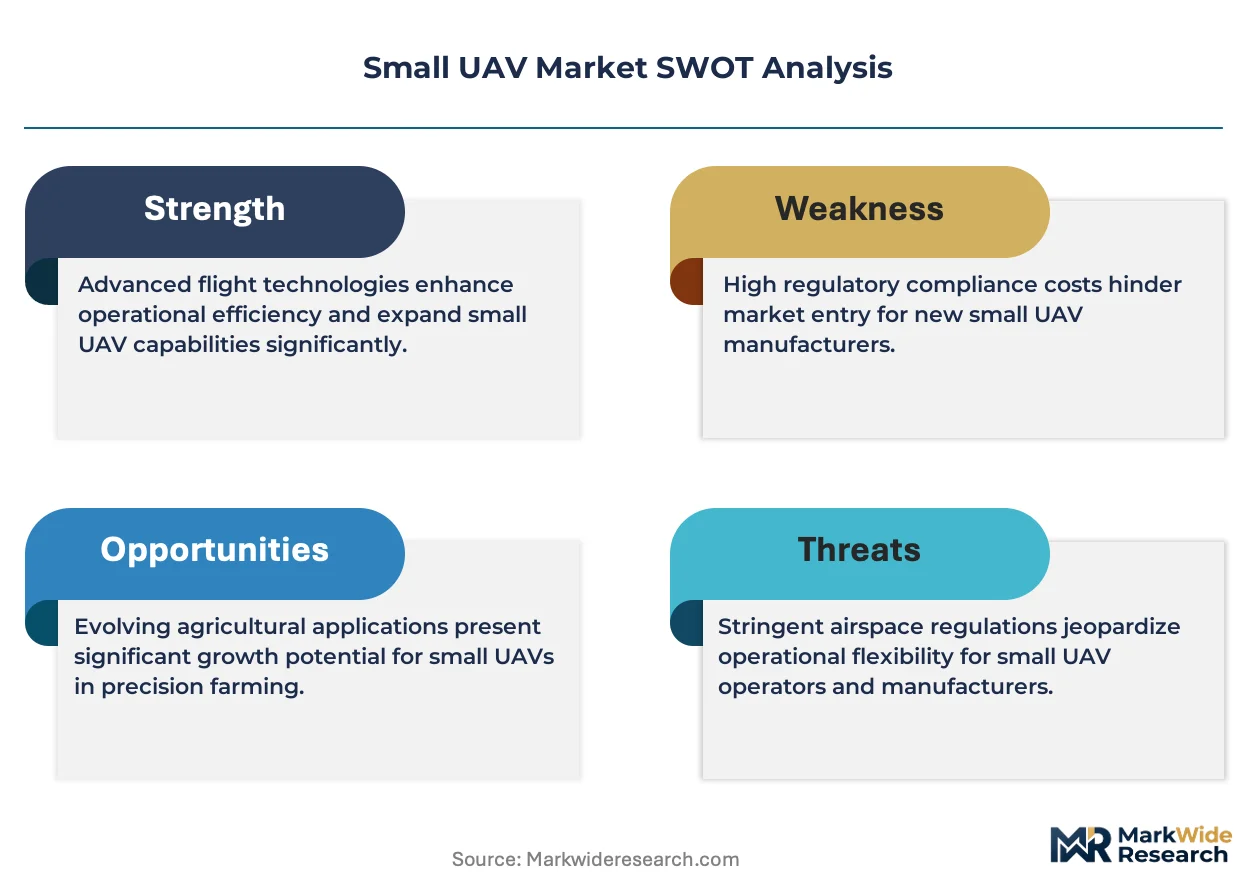
Small UAV procurement is bifurcating between consumer-grade volume and enterprise-grade compliance, with FAA Remote ID and EASA open-category frameworks forcing dual-architecture engineering investments that compress margins for non-vertically integrated assemblers.
Growth Catalysts
- Beyond-Visual-Line-of-Sight waivers:FAA Part 107 waiver expansions for agricultural and infrastructure inspection operators in the United States are unlocking revenue models previously restricted to military channels.
- Carbon fiber composite airframes:Automated fiber placement and resin transfer molding are slashing airframe weight by thirty percent while maintaining crash tolerance for rotary-wing platforms.
- Guangdong component ecosystem density:Proximity to MEMS foundries, brushless motor winding facilities, and lithium-polymer cell packagers is compressing procurement lead times for Shenzhen-based original equipment manufacturers.
Market Restraints
- Lithium-polymer cell price volatility:Cobalt and nickel supply concentration in the Democratic Republic of Congo and Indonesia is injecting input cost uncertainty into battery pack economics.
- Radio frequency module certification fragmentation:Divergent ISM band allocations between the FCC, ETSI, and MIIT regimes are forcing redundant hardware variants for transatlantic market access.
- Detect-and-avoid technical thresholds:Current radar and optical fusion systems fail to satisfy EASA's specific category requirements for autonomous urban operations below one hundred twenty meters.
Strategic Opportunities
- Indian DGCA type certification pathway:The 2021 drone rules and subsequent PLI scheme incentives are creating first-mover advantages for local assembly investments in Telangana and Karnataka.
- Cellular network command-and-control:5G network slicing and C-V2X integration are enabling real-time kinematic positioning without dedicated ground control stations.
- Swarming coordination algorithms:Distributed consensus protocols and mesh networking stacks are opening coordinated payload delivery for disaster response and agricultural spraying at scale.
Industry Challenges
- Flight control firmware certification timelines:DO-178C and equivalent software assurance standards for autonomous navigation stacks are extending development cycles by fourteen to eighteen months.
- Supply chain reconfiguration friction:Shifting final assembly from Guangdong to Vietnam or Mexico to satisfy BIS and USMCA content rules is disrupting established quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small UAV Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Nano Application: Agriculture, Surveillance, Delivery, Aerial Photography End User: Government, Commercial, Research, Education Technology: GPS, LiDAR, Camera Systems, Autonomous Navigation |
| Companies Covered | Parrot, XAG, DJI, JOUAV, Autel Robotics, Skydio, Insitu, Draganfly, AeroVironment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small UAV Market Strategic Shifts
Autonomous navigation stacks and edge-compute inference engines are compressing the functional gap between piloted and uncrewed platforms, while regulatory frameworks race to codify airworthiness standards for machine-decision systems.
Neural network-based obstacle detection fused with stereo vision depth estimation is rendering obsolete manual pilot proficiency requirements for complex infrastructure inspection missions. Public safety agencies in Germany and Australia are mandating these autonomy stacks for bridge and tower assessments. The shift is compressing training budgets while expanding addressable operator pools.
EASA's specific category framework and the FAA's Remote ID rule are forcing hardware retrofits that bifurcate product roadmaps. Manufacturers must engineer dual-transponder architectures for European and American market access. Agricultural spraying platforms face the steepest compliance costs due to fleet size and retrofit labor intensity.
Leasing and drone-as-a-service models are displacing capital expenditure procurement for seasonal agricultural operators. Brazilian soybean cooperatives and Australian cotton growers now prioritize operational expenditure structures with embedded maintenance and liability coverage. This preference shift favors vertically integrated platform-as-a-service providers over hardware-only vendors.
Small UAV Market Segmentation
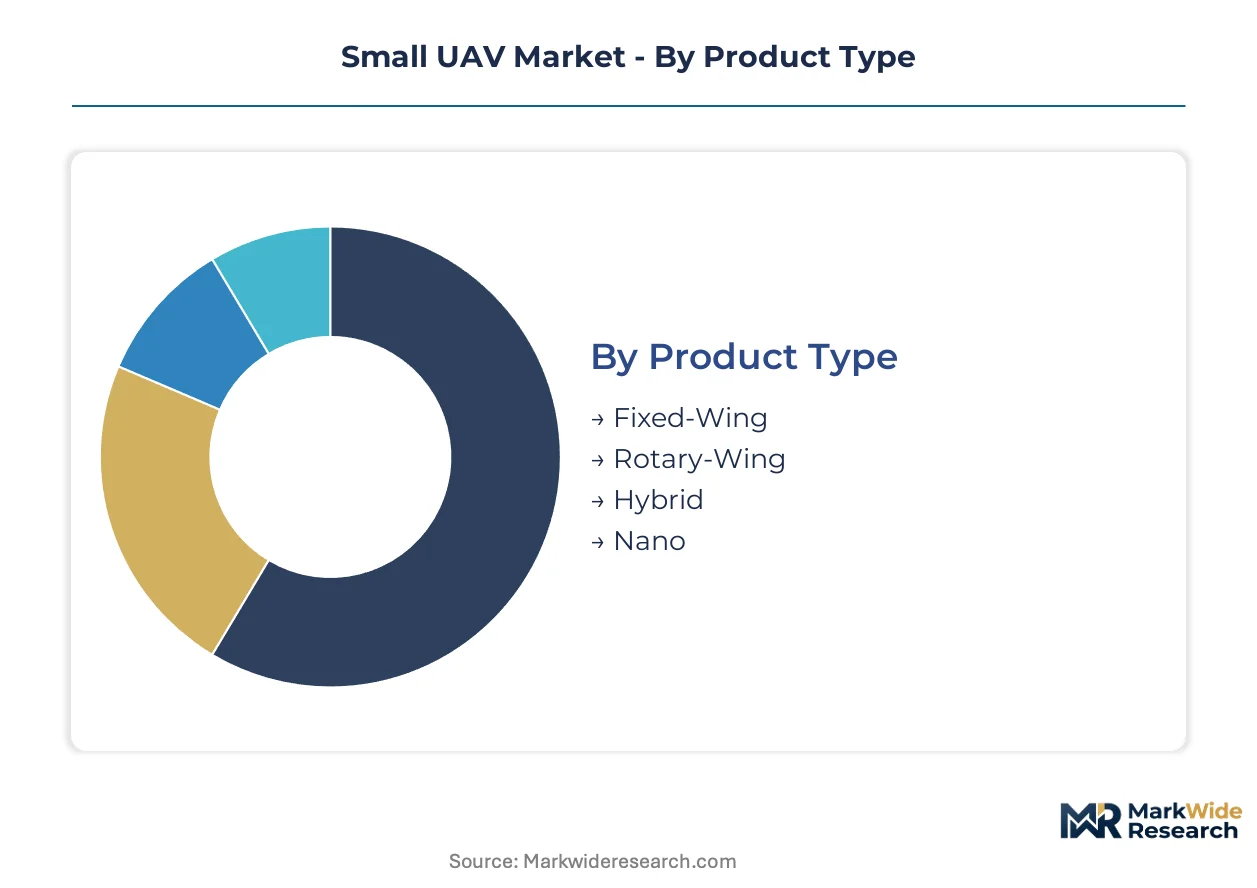
Segmentation in small UAV markets exposes divergent service intensity requirements across product architectures and use cases. Rotary-wing platforms demand frequent propulsion system maintenance, while fixed-wing systems concentrate lifecycle costs in airframe inspections. Application-driven segments reveal stark contrasts between seasonal agricultural deployment and continuous surveillance operations.
Product Type:
After-sales-service intensity varies dramatically across propulsion architectures, with multi-rotor systems requiring motor replacement every 200-400 flight hours versus fixed-wing airframes demanding structural integrity assessments at comparable intervals.
- Fixed-Wing:Composite airframes with pusher or tractor propeller configurations maximize endurance for corridor surveillance and agricultural mapping missions. Brazilian soybean cooperatives and Australian pastoral operators favor these platforms for thousand-hectare survey blocks where runway access exists.
- Rotary-Wing:Multi-rotor and single-rotor helicopters dominate procurement volumes through vertical takeoff flexibility and mechanical simplicity. Guangdong manufacturers exploit captive motor and ESC ecosystems to compress lead times for enterprise fleet orders in infrastructure inspection and public safety.
- Hybrid:Tilt-rotor and tail-sitter architectures combine VTOL convenience with fixed-wing cruise efficiency for delivery trials exceeding pure multi-rotor range envelopes.
- Nano:Sub-250 gram platforms evade registration thresholds in FAA and EASA frameworks, concentrating demand in consumer recreation and tactical military reconnaissance.
By volume, Rotary-Wing leads. By growth pace, Hybrid is gaining share fastest as logistics operators validate beyond-visual-line-of-sight delivery economics.
Application:
Cost tier differentiation separates capital-intensive precision agriculture systems from operational-expenditure surveillance contracts where sensor refresh cycles dominate lifetime economics.
- Agriculture:Variable-rate spraying and multispectral crop monitoring command premium platform specifications with chemical-resistant airframes and RTK-GPS guidance. Brazilian cotton growers and Indian sugarcane cooperatives drive fleet procurement through seasonal leasing structures.
- Surveillance:Border patrol, critical infrastructure monitoring, and event security require encrypted datalinks and thermal sensor payloads. German police forces and Australian emergency services mandate autonomous navigation stacks for reduced operator certification burdens.
- Delivery:Medical supply and last-mile parcel trials concentrate in controlled airspace corridors with cellular command-and-control integration.
- Aerial Photography:Cinematography and real estate marketing sustain consumer-tier volumes through content creator demand and social media distribution economics.
Agriculture captures the highest equipment revenue per unit. Surveillance shows the steepest expansion trajectory as public safety agencies consolidate vendor relationships.
End User:
Customer type determines procurement modality, with government tenders favoring hardened specifications and extended warranty terms versus commercial operators prioritizing operational flexibility.
- Government:Defense, homeland security, and environmental agencies require ITAR-compliant supply chains and airworthiness certification under military standards. Pentagon procurement channels favor AeroVironment and Shield AI platforms for tactical reconnaissance.
- Commercial:Agricultural service providers, infrastructure inspectors, and logistics operators drive enterprise volume through drone-as-a-service models that transfer capital risk to platform-as-a-service vendors.
- Research:Universities and atmospheric science institutes demand payload flexibility and open flight control architectures for algorithm development.
- Education:Flight training academies and STEM programs concentrate demand in sub-$500 trainer platforms with simulator integration.
Government contracts carry the longest sales cycles. Commercial adoption is climbing the fastest as leasing structures reduce barrier to entry.
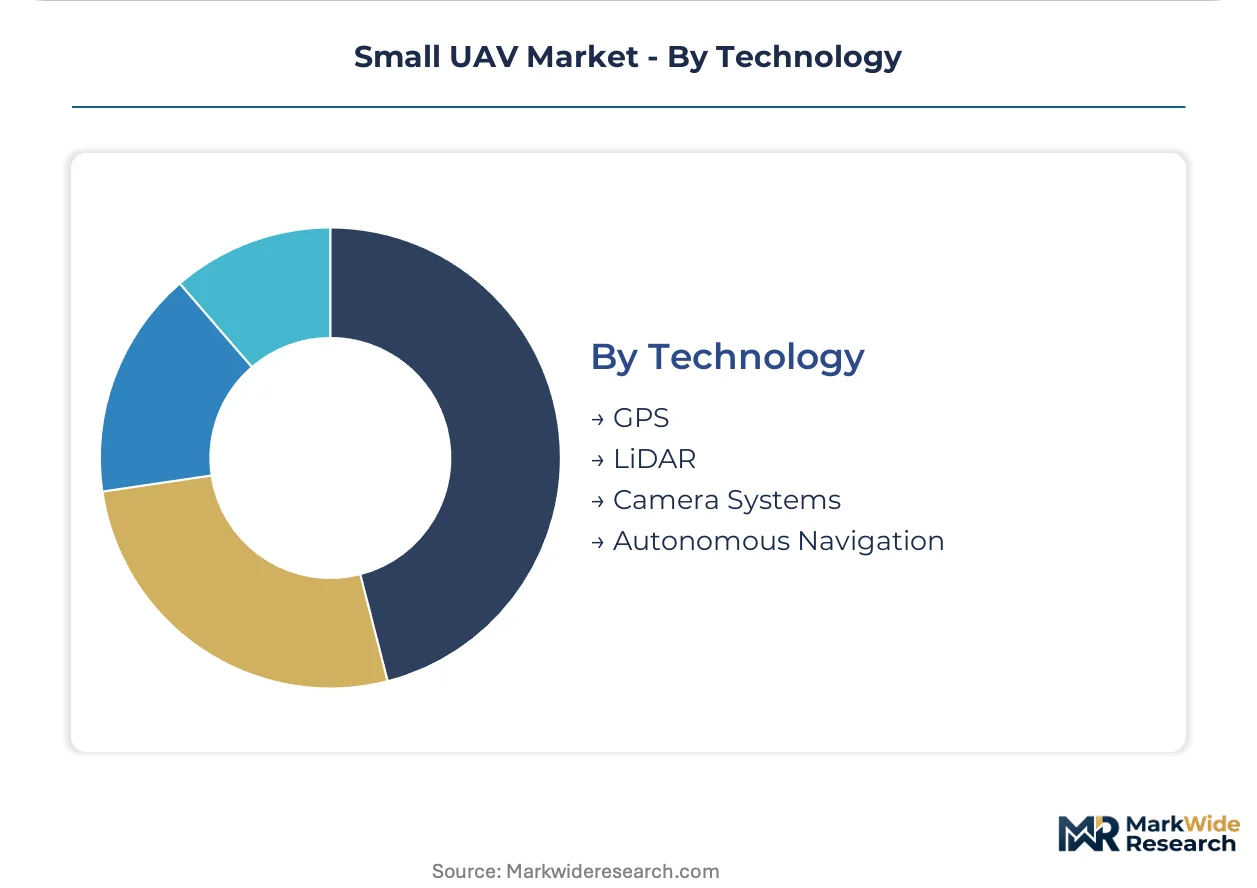
Technology:
Supply concentration in sensor and navigation componentry shapes competitive differentiation, with in-house algorithm development separating premium tiers from commodity assemblers.
- GPS:Multi-constellation receivers integrating GPS, GLONASS, BeiDou, and Galileo signals enable centimeter-level positioning with RTK base station networks. Agricultural spraying in Brazil and surveying in India depend on this precision for autonomous flight path execution.
- LiDAR:Solid-state and mechanical scanning systems generate point clouds for forestry inventory, power line clearance assessment, and construction progress monitoring. Surveying contractors in Germany and Australia mandate these payloads for regulatory compliance in infrastructure documentation.
- Camera Systems:Gimbal-stabilized EO/IR sensors span consumer-grade 4K through military-specified cooled thermal imagers.
- Autonomous Navigation:Neural network obstacle detection and simultaneous localization and mapping enable operations in GPS-denied environments.
Camera Systems dominate unit shipments. Autonomous Navigation represents the fastest-growing technology investment as operators seek reduced certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: Brazilian agricultural operators prioritize spraying payload capacity, while German public safety agencies mandate autonomous navigation certification, and Indian service providers favor leasing structures over capital acquisition.
United States
Agricultural spraying and infrastructure inspection drive fleet procurement, with commercial operators seeking FAA Part 107 waivers for beyond-visual-line-of-sight missions. The FAA Remote ID mandate forces hardware retrofits across existing rotary-wing fleets. California's Central Valley and Texas cotton belts concentrate demand for chemical-resistant platforms with RTK-GPS guidance.
China
Guangdong province anchors manufacturing density through captive component ecosystems spanning MEMS foundries and lithium-polymer cell packagers. The CAAC and MIIT coordinate airspace classification with layered approval barriers for foreign entrants. Shenzhen-based original equipment manufacturers exploit proximity to brushless motor winding facilities for compressed lead times on enterprise orders.
Germany
Public safety agencies mandate neural network-based obstacle detection for bridge and tower assessments, reducing operator certification burdens. EASA's specific category framework drives dual-transponder engineering investments for European market access. Bavarian police forces and infrastructure inspectors consolidate vendor relationships around hardened platform specifications.
Brazil
Soybean cooperatives and cotton growers drive seasonal fleet procurement through operational expenditure structures with embedded maintenance coverage. ANVISA chemical handling regulations intersect with DGAC airspace rules for agricultural spraying operations. São Paulo state concentrates service provider density for thousand-hectare survey blocks.
India
The DGCA drone rules and PLI scheme incentives accelerate local assembly requirements in Telangana and Karnataka. Sugarcane cooperatives and cotton growers prioritize leasing models that transfer capital risk to platform-as-a-service vendors. BIS quality mandates create compliance barriers for imported hardware while favoring domestic fabrication.
Small UAV Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around vertically integrated hardware manufacturers with captive component ecosystems, mid-scale specialists with autonomous navigation differentiation, and defense-focused vendors with Pentagon procurement channels. Consolidation pressure operates through M&A activity targeting navigation software stacks and geographic expansion into Indian assembly jurisdictions.
Within the vertically integrated tier, DJI and Autel Robotics exemplify scale-driven positions anchored in Guangdong manufacturing corridors. Skydio occupies a specialist position emphasizing autonomous navigation for obstacle-dense environments. AeroVironment represents the defense-contractor archetype with hardened platform specifications and federal procurement access.
| Leading Market Players |
|---|
| Parrot |
| XAG |
| DJI |
| JOUAV |
| Autel Robotics |
| Skydio |
| Insitu |
| Draganfly |
| AeroVironment |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's component ecosystem density compresses procurement costs for rotary-wing platforms while amplifying pricing power for vertically integrated original equipment manufacturers serving enterprise fleet operators across agricultural and public safety segments.
Pricing Analysis
Guangdong-to-Brazil price spreads exceed thirty percent for equivalent payload-capable platforms due to tariff layering and ANVISA certification costs. Three-tier pricing structure across premium, standard, and economy levels separates RTK-GPS equipped spraying systems from basic surveying units and consumer recreation hardware. Cost compression in the mid-tier is intensifying because Brazilian cooperatives now demand operational expenditure structures with embedded maintenance. Agricultural service providers exhibit the highest price sensitivity, while defense procurement channels show minimal elasticity.
Supply Chain Analysis
ITAR and EAR export controls restrict brushless motor winding equipment and flight control firmware flows to Chinese manufacturers, forcing redundant engineering investments. Component sourcing draws from China, South Korea, and Japan for MEMS sensors, lithium-polymer cells, and composite prepregs. Single-source vulnerability concentrates in cobalt refining capacity for battery cathodes. Distribution runs through Shenzhen-based original equipment manufacturers to regional assembly partners in Vietnam and Mexico for USMCA compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flight control firmware certification under DO-178C standards represents the scarcest technical capability, separating platform-as-a-service vendors from commodity hardware assemblers unable to satisfy autonomous navigation airworthiness requirements.
For Market Incumbents: Build regulatory certification moats by accelerating DO-178C compliance timelines for autonomous navigation stacks before EASA detect-and-avoid mandates harden. Capture brushless motor winding capacity in Vietnam to preempt USMCA content rule disruptions. Consolidate vendor relationships with Brazilian agricultural cooperatives through embedded leasing structures that transfer retrofit liability. For New Entrants and Emerging Players: Indian state-level assembly incentives in Telangana and Karnataka offer the most penetrable geographic entry point, with PLI scheme subsidies offsetting BIS quality mandate compliance costs. Target sugarcane cooperative leasing demand with cellular command-and-control integration that bypasses dedicated ground station investments. Pursue drone-as-a-service partnerships with existing agrochemical distributors rather than direct hardware sales. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because airspace classification divergence between FAA, EASA, and CAAC regimes creates persistent compliance fragmentation that favors multi-certification platform vendors. Acquisition targets should exhibit captive navigation algorithm development and existing waiver pathways for beyond-visual-line-of-sight operations. Monitor FAA Part 107 waiver expansion velocity as the signal for scalable agricultural deployment economics.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Stack Certification | DO-178C compliance unlocks EASA specific category access for urban operations below 120 meters. |
| Cellular Network Command-and-Control Integration | 5G network slicing enables real-time kinematic positioning without ground control station infrastructure. |
| Geographic Assembly Footprint Expansion | Vietnam and Mexico final assembly satisfies USMCA content rules and BIS quality mandates. |
| Platform-as-a-Service Model Development | Operational expenditure structures transfer capital risk to vendors for seasonal agricultural operators. |
| Swarming Coordination Algorithm Investment | Distributed consensus protocols enable coordinated payload delivery for disaster response at scale. |
Study Parameters
Operator-level perspectives from agricultural fleet managers, public safety procurement officers, infrastructure inspection contractors, and flight control firmware engineers anchored the qualitative base. Primary interviews combined with secondary validation from FAA waiver databases, EASA certification filings, ANVISA chemical handling regulations, and DGCA drone rule amendments. Bottom-up platform shipment estimates triangulated against top-down addressable market sizing across rotary-wing, fixed-wing, and hybrid architectures.
Scenario-bracketing framed demand projections across conservative, baseline, and expansion cases over the projection horizon. Segmentation dimensions modeled include propulsion architecture, application vertical, end-user procurement modality, and technology tier. CAGRs derived from fitted growth curves anchored to disclosed fleet procurement volumes and seasonal deployment patterns. Forecast inputs incorporated lithium-polymer cell price volatility indices and regulatory waiver approval velocity.
Practitioners should monitor FAA detect-and-avoid rulemaking timelines and EASA specific category enforcement thresholds for early signals of platform architecture obsolescence. Forecasts reflect assumptions regarding continued cobalt supply concentration and cellular network slicing deployment pace. Material shifts in export control regime stringency or beyond-visual-line-of-sight waiver denial rates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Drone Inspection and Monitoring Market
UAV
Europe Tactical UAV Market
UAV
Europe Commercial Drones Market
UAV
Short-Range Delivery Drone Market
UAV
Latin America Small UAV Market
UAV
Global Drone Services Market
UAV
Europe Small UAV Market
UAV
UAV Battery Market
UAV
Delivery Drones Market
UAV
North America Small UAV Market
UAV
Anti-Drone Technology Market
UAV
Rc Helicopter Market
UAV
Global Aerial Imaging Market
UAV
Drone Motors Market
UAV
Drone Leasing Market
UAV
Tethered Drones Market