
 Anti-Drone Market | 2026-2036
Anti-Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Drone Market Analysis
Platform licensing revenue is fragmenting across hardware manufacturers, software integrators, and service operators as counter-UAS procurement models shift from capital purchase to subscription-based threat monitoring. RTX leverages its radar heritage to anchor long-range detection contracts with defense agencies. Lockheed Martin Corporation sustains vertical integration across command-and-control layers, while DroneShield differentiates through portable, expeditionary jamming systems tailored for mobile security teams.
An anti-drone system comprises integrated detection, tracking, and neutralization technologies designed to identify, classify, and defeat unauthorized unmanned aerial vehicles, typically operating across radio frequency, electro-optical, infrared, and acoustic sensor modalities with engagement ranges from hundreds of meters to several kilometers depending on platform configuration. Jamming systems currently occupy the largest product type segment due to their non-destructive engagement profile and lower collateral risk in populated environments, while laser systems represent the fastest-expanding category as directed-energy lethality matures and per-shot operating costs decline below kinetic alternatives. The military end user segment dominates absolute spending, though commercial adoption is accelerating at airports, critical infrastructure sites, and large-scale event venues where regulatory mandates now require demonstrable counter-UAS capabilities.
The FAA and Department of Defense shape domestic demand through airspace restriction protocols and procurement certification requirements, while European operators navigate EASA counter-UAS guidance and national defense procurement frameworks that increasingly mandate interoperability standards. ISO and IEC technical committees are developing performance benchmarks for detection accuracy and false-alarm rates that will condition market access across allied defense markets. Stakeholders must monitor how regulatory fragmentation between civilian aviation security and military operational authorities reshapes product development roadmaps and partnership strategies.
Market Dynamics
Defense procurement is pivoting from standalone counter-UAS hardware to layered, software-defined detection architectures that integrate multiple sensor modalities under unified command interfaces.
Growth Catalysts
- Asymmetric Threat Proliferation:State and non-state actors deploy low-cost drones for reconnaissance and payload delivery, compelling military end users to accelerate layered defense procurement.
- FAA Airspace Security Mandates:The Federal Aviation Administration requires demonstrable counter-UAS capabilities at critical infrastructure sites and commercial airports, expanding addressable demand beyond military budgets.
- Directed-Energy Maturation:Solid-state laser and high-power microwave systems achieve operational reliability thresholds, enabling non-kinetic engagement with lower per-intercept cost profiles than missile-based alternatives.
Market Restraints
- Radio Frequency Spectrum Fragmentation:Counter-UAS jamming systems face constrained operating bands due to civilian telecommunications allocation, limiting effective neutralization range in urban environments.
- Dual-Use Export Controls:International Traffic in Arms Regulations and Wassenaar Arrangement restrictions complicate cross-border sales of detection and defeat technologies to allied nations.
- False-Positive Interference Liability:Electromagnetic jamming risks disrupting legitimate aviation and emergency communications, creating operational hesitation among commercial adopters at airports and stadiums.
Strategic Opportunities
- Critical Infrastructure Protection:Power generation facilities and oil refineries face emerging regulatory requirements for perimeter drone detection, opening commercial verticals with recurring service revenue potential.
- AI-Driven Classification:Machine learning integration with radar and electro-optical sensors enables autonomous threat identification, reducing operator burden and enabling scaled deployment across distributed sites.
- European Defense Procurement Harmonization:EASA counter-UAS guidance and NATO interoperability standards create consolidated demand pools for modular, exportable system architectures.
Industry Challenges
- Swarm Coordination Complexity:Simultaneous tracking and prioritization of multiple incoming drones exceeds current automation thresholds, requiring human-in-the-loop protocols that limit response speed.
- Legacy System Integration Friction:New counter-UAS platforms must interface with existing air defense command networks using incompatible data protocols, extending deployment timelines and customization costs.
- Electromagnetic Environmental Effects Certification:Demonstrating safe operation alongside civilian aviation and medical devices requires extensive testing cycles that delay fielding approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Drone Market |
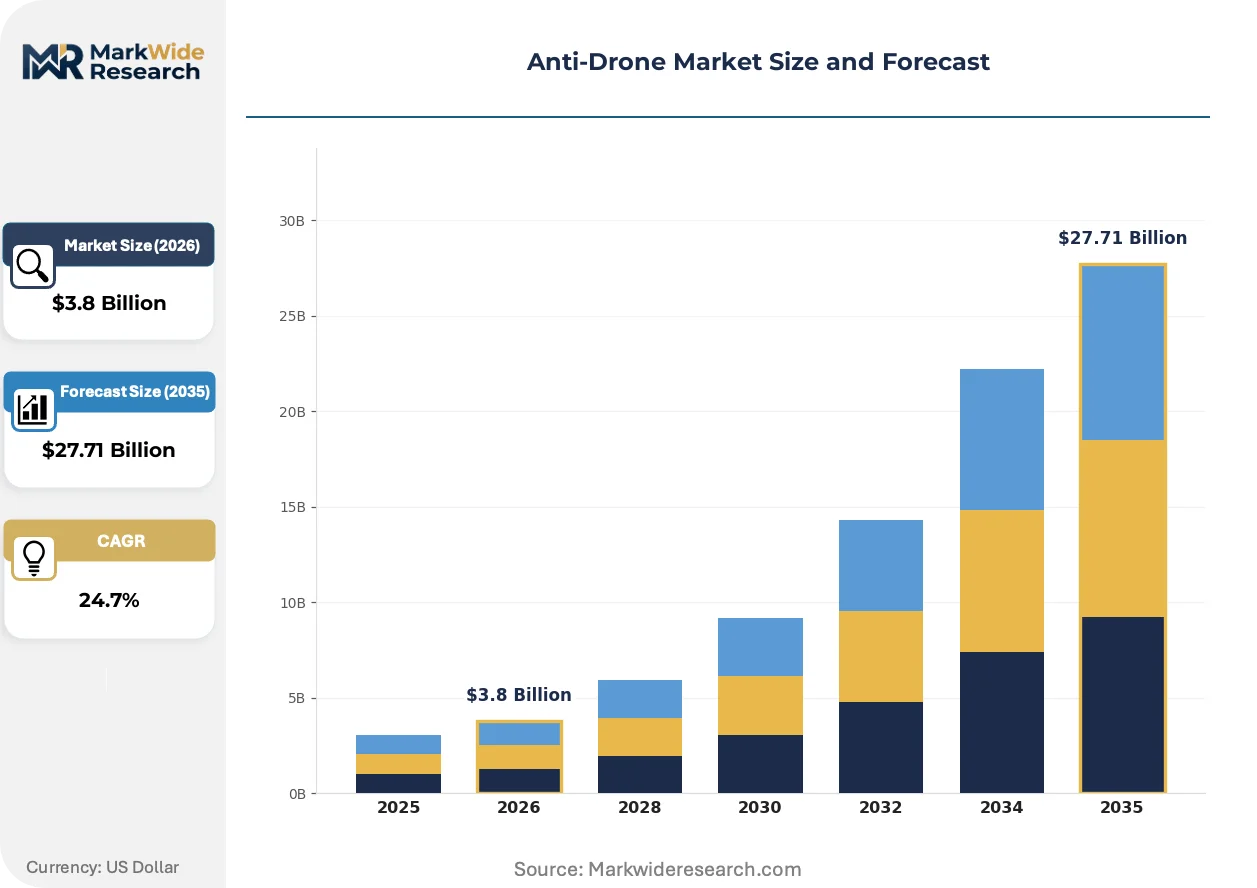
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.71 Billion |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Systems, Jamming Systems, Kinetic Systems, Net Systems End User: Military, Law Enforcement, Civilian, Commercial Technology: Radio Frequency, Electro-Optical, Infrared, Acoustic Application: Security, Defense, Surveillance, Border Control |
| Companies Covered | RTX, Lockheed Martin Corporation, Rafael Advanced Defense Systems, Israel Aerospace Industries, Thales, Leonardo S.p.A., DroneShield, Dedrone, Saab, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Drone Market Emerging Trajectories
Sensor fusion architectures and autonomous engagement protocols are compressing the detection-to-defeat timeline while reducing operator dependency in contested electromagnetic environments.
Passive radio frequency sensing is rendering obsolete active radar-dependent detection systems for clandestine military applications. Special operations units and forward-deployed expeditionary forces prioritize signature-minimal sensors that emit no detectable energy. This shift compresses procurement toward software-defined radio platforms with rapid threat-library updates.
ISO and IEC technical committees are finalizing performance benchmarks for detection accuracy and false-alarm rates that will condition market access across allied defense markets. Manufacturers must redesign sensor fusion algorithms to meet standardized testing protocols. European and Asia-Pacific procurement frameworks increasingly mandate certified interoperability, forcing architectural concessions from vertically integrated suppliers.
Defense agencies are consolidating counter-UAS procurement under multi-year enterprise agreements that bundle hardware, software licenses, and threat-intelligence subscriptions. Traditional capital purchase models lose share to performance-based service contracts where vendors retain system ownership. This restructuring concentrates buying power with prime contractors capable of delivering end-to-end managed detection services across dispersed installations.
Anti-Drone Market Segmentation
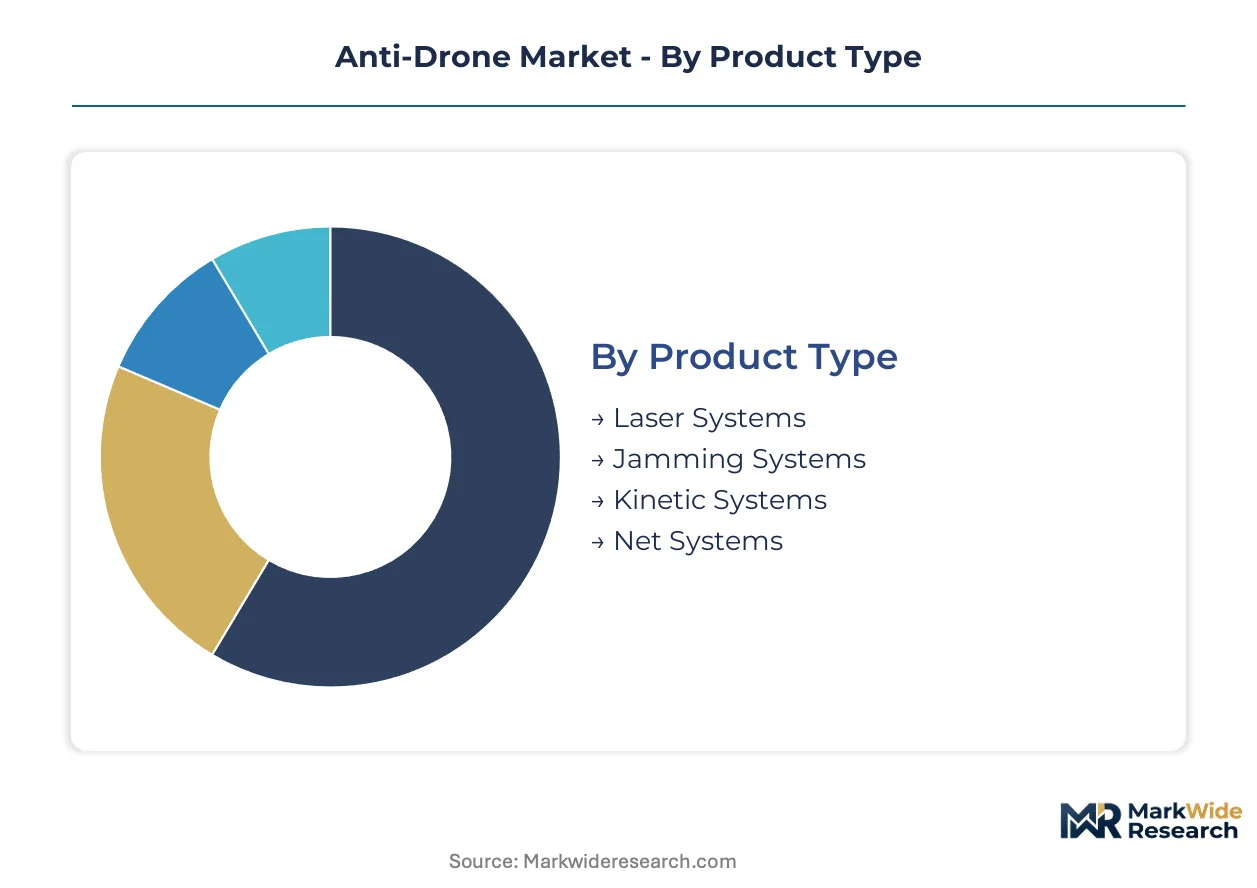
Anti-drone procurement patterns diverge sharply across operational contexts, with military buyers prioritizing detection range and civilian operators emphasizing collateral safety. Understanding these segment boundaries clarifies where technology investments concentrate and which performance specifications command premium pricing.
Product Type:
After-sales service intensity varies dramatically by product type, with directed-energy platforms requiring specialized technician deployment and jamming systems demanding continuous threat-library updates.
- Jamming Systems:Radio frequency and GPS signal disruption platforms dominate current procurement volumes due to their non-destructive engagement profile. Military end users in the United States favor these systems for base perimeter defense where kinetic alternatives risk collateral damage.
- Laser Systems:Solid-state directed-energy weapons achieve precision targeting with negligible per-shot cost once capital investment is recovered. Demand concentrates at fixed-site critical infrastructure installations where engagement rules permit destructive neutralization.
- Kinetic Systems:Projectile-based interceptors including missiles and specialized ammunition retain niche applications against hardened targets.
- Net Systems:Physical capture mechanisms using launched or drone-borne netting suit urban environments with strict electromagnetic emission restrictions.
By volume, Jamming Systems leads. By growth pace, Laser Systems is ahead.
End User:
Cost tier stratification separates military procurement with multi-million-dollar system architectures from commercial buyers seeking portable, expeditionary units under constrained budgets.
- Military:Defense agencies procure layered detection architectures integrating multiple sensor modalities under unified command interfaces. Spending concentrates on forward-operating base protection and convoy security applications.
- Commercial:Airport operators and critical infrastructure managers drive fastest adoption acceleration as FAA mandates tighten. These buyers prioritize false-positive minimization over maximum detection range.
- Law Enforcement:Police and security agencies require man-portable systems for event protection and tactical operations.
- Civilian:Private security firms and high-net-worth individuals represent emerging demand for residential and corporate estate protection.
Military segments anchor absolute spending. Commercial segments are expanding most quickly.
Technology:
Application environment dictates sensor modality selection, with contested electromagnetic environments favoring passive detection and clear-weather fixed sites enabling active radar augmentation.
- Radio Frequency:Passive signal detection and direction-finding systems emit no detectable energy, rendering them essential for clandestine military operations. Software-defined radio platforms enable rapid threat-signature updates without hardware replacement.
- Electro-Optical:Visual spectrum cameras combined with machine vision algorithms provide positive identification capabilities that RF sensors cannot match. Demand concentrates at border control installations requiring target classification before engagement authorization.
- Infrared:Thermal detection extends operational capability through darkness and obscurants.
- Acoustic:Sound signature recognition offers low-cost supplementary detection for short-range applications.
Radio Frequency holds the largest installed base. Electro-Optical is gaining share fastest.
Application:
Customer type differentiation separates sovereign defense procurement with classified performance requirements from commercial security buyers governed by civilian aviation regulations.
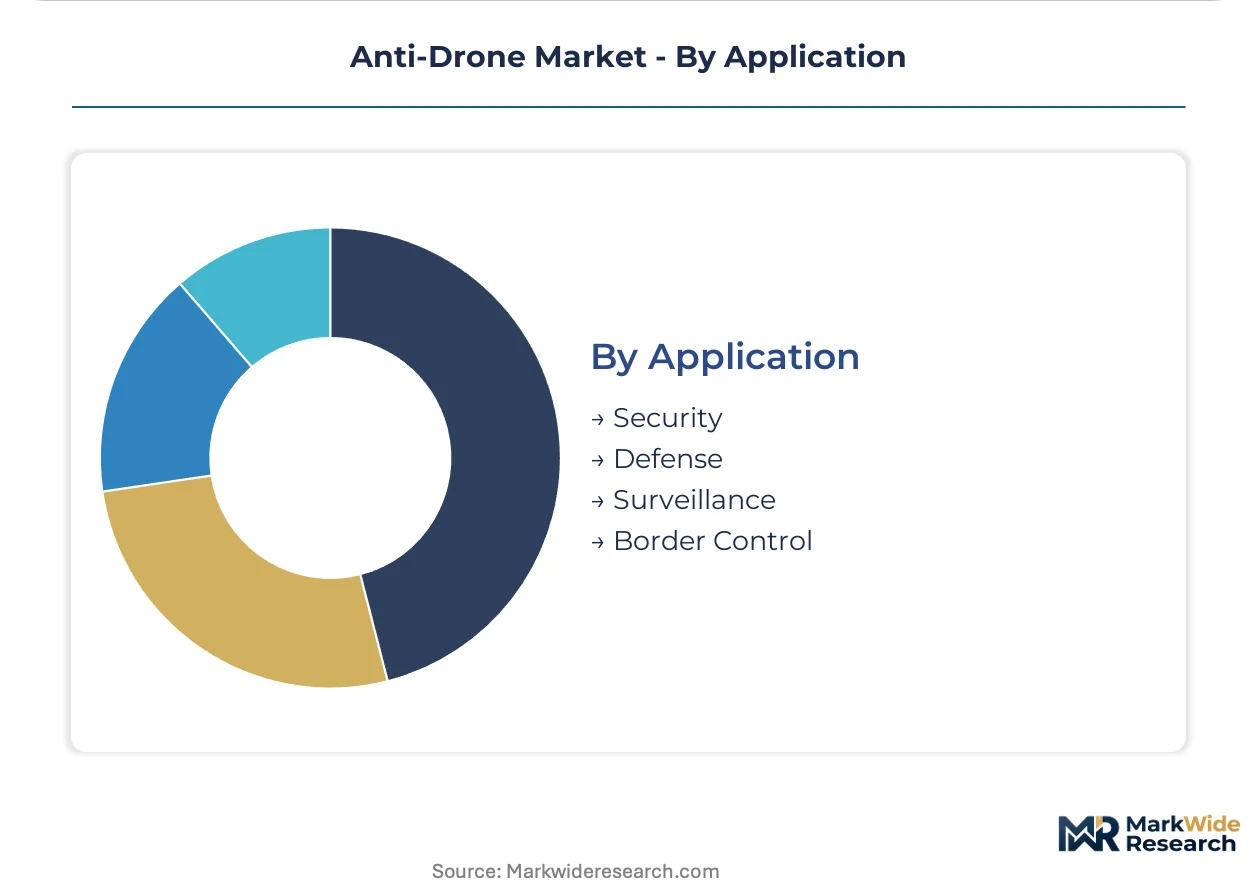
- Defense:Military operational requirements prioritize detection range, track accuracy, and engagement speed against maneuvering threats. Procurement runs through classified acquisition channels with extended testing protocols.
- Security:Commercial venue protection at stadiums and corporate campuses emphasizes rapid deployment and operator training simplicity. FAA coordination requirements shape system selection.
- Surveillance:Intelligence and reconnaissance support applications demand persistent wide-area coverage.
- Border Control:National boundary protection integrates counter-UAS with existing radar and camera networks.
Defense applications command highest unit pricing. Security applications show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement elasticity varies sharply across geographies. United States buyers absorb premium pricing for layered architectures, while emerging markets prioritize portable, expeditionary units under constrained budgets.
United States
The Department of Defense drives demand through multi-year enterprise agreements bundling hardware, software licenses, and threat-intelligence subscriptions. FAA airspace security mandates at commercial airports and critical infrastructure sites expand addressable demand beyond military budgets. RTX anchors long-range detection contracts from its radar heritage base, while DroneShield supplies portable jamming systems for mobile security teams.
Israel
Rafael Advanced Defense Systems and Israel Aerospace Industries concentrate directed-energy and kinetic interceptor development for sovereign defense and export markets. The country's national defense procurement framework prioritizes interoperability with NATO and allied systems. Tel Aviv-area defense clusters advance solid-state laser maturation for precision targeting with negligible per-shot costs.
United Kingdom
Airport operators and critical infrastructure managers accelerate adoption as regulatory mandates tighten around demonstrable counter-UAS capabilities. The Civil Aviation Authority coordinates with Ministry of Defence on civilian-military airspace integration protocols. London and Southeast England clusters focus on false-positive minimization technologies for populated environments.
Germany
EASA counter-UAS guidance and national defense procurement frameworks mandate modular, exportable system architectures. The country's engineering base emphasizes electromagnetic environmental effects certification for safe operation alongside civilian aviation. Bavaria and Baden-Württemberg industrial regions develop sensor fusion algorithms meeting ISO and IEC standardized testing protocols.
France
Thales and Leonardo S.p.A. compete for NATO interoperability contracts requiring certified multi-sensor detection platforms. The country's national defense procurement agency consolidates spending under performance-based service contracts where vendors retain system ownership. Paris and Île-de-France defense electronics clusters integrate passive radio frequency sensing for clandestine military applications.
Anti-Drone Market Vendor Landscape
Capability concentration sits with specialized directed-energy and software-defined radio developers; scale advantage sits with diversified aerospace primes with existing defense procurement relationships. The market structures around three tiers: vertically integrated primes delivering end-to-end managed detection services, mid-cap specialists in portable expeditionary systems, and emerging players in AI-driven classification software. Consolidation pressure intensifies as multi-year enterprise agreements concentrate buying power. Strategic moves center on M&A to acquire software-defined radio platforms and strategic partnerships to meet NATO interoperability certification requirements.
Within the prime contractor tier, RTX and Lockheed Martin Corporation occupy positions anchored by radar heritage and vertical integration across command-and-control layers. DroneShield exemplifies the mid-cap specialist archetype, representing portable, expeditionary jamming system developers tailored for mobile security teams. These three entities illustrate the competitive spectrum from scale-driven layered architectures to agile, threat-library-dependent platforms.
| Leading Market Players |
|---|
| RTX |
| Lockheed Martin Corporation |
| Rafael Advanced Defense Systems |
| Israel Aerospace Industries |
| Thales |
| Leonardo S.p.A. |
| DroneShield |
| Dedrone |
| Saab |
| Others |
Supply Flow & Price Mechanics
Undercapacity in solid-state laser component fabrication is compressing lead times for directed-energy platforms and elevating supplier pricing power against prime contractors. This utilization squeeze propagates through procurement tiers, forcing defense agencies toward performance-based service contracts that transfer capital risk to vendors.
Pricing Analysis
Extended service and threat-intelligence subscription tiers now drive lifetime value capture across counter-UAS deployments. Three-tier pricing structure across expeditionary, fixed-site, and enterprise-managed levels separates portable jamming units from integrated detection architectures and full-service perimeter defense. Price differentiation rests on ISO/IEC certification status and FAA airspace coordination approval tiers. Cost compression in expeditionary hardware intensifies as DroneShield and mid-cap specialists compete for mobile security team contracts. Commercial airport operators exhibit highest price sensitivity due to budget constraints, while Department of Defense multi-year enterprise agreements absorb premium pricing for layered architectures.
Supply Chain Analysis
Extended payment terms from prime contractors to radio frequency component suppliers have become standard practice, stretching working capital requirements down-tier. Gallium nitride semiconductors draw from United States, Japan, and South Korea fabrication facilities. Specialized optical coatings for laser systems sources from Germany and Israel. Software-defined radio processors hinges on Taiwan and South Korea foundry capacity. Single-source vulnerability in gallium nitride substrates poses structural risk given export control restrictions. Distribution runs through defense procurement channels with classified acquisition protocols and commercial security integrators serving FAA-mandated infrastructure sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent counter-UAS suppliers face substitution defense against AI-native classification software entrants that could displace hardware-centric detection architectures.
For Market Incumbents: Entrench through captive supply of software-defined radio platforms and backward integration into gallium nitride semiconductor sourcing. Lockheed Martin Corporation and RTX must accelerate NATO interoperability certification investment to forestall modular system challengers. Threat-intelligence subscription bundling creates switching costs against pure-play software entrants. For New Entrants and Emerging Players: Mid-market critical infrastructure in Germany and France represents the most penetrable entry point, where EASA counter-UAS guidance mandates create compliance-driven demand without prime contractor lock-in. AI-driven classification modules for existing electro-optical installations offer lowest-friction go-to-market path, bypassing hardware certification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined detection layers, enabling asset-light scaling for pure-play entrants. Long-term viability favors acquisition targets with certified interoperability and recurring threat-intelligence revenue streams. Watch for FAA mandate expansion beyond airports into power generation facilities as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Acquisition | Captures passive detection capability essential for clandestine military operations without radar signature. |
| NATO Interoperability Certification Investment | Unlocks EASA-aligned procurement frameworks across Germany, France, and United Kingdom defense budgets. |
| Threat-Intelligence Subscription Bundling | Converts capital purchase relationships into recurring revenue with higher lifetime value per installation. |
| Directed-Energy Manufacturing Scale-Up | Reduces per-shot operating costs below kinetic alternatives for fixed-site critical infrastructure protection. |
| AI-Driven Classification Module Development | Enables autonomous threat identification reducing operator burden across distributed commercial sites. |
Methodological Framework
A standing panel of counter-UAS program executives, FAA airspace security officers, defense procurement managers, and critical infrastructure security directors provided ongoing calibration across the study period. Primary interviews with RTX radar division strategists, DroneShield product leads, and Israeli Aerospace Industries directed-energy engineers combined with secondary validation from Department of Defense budget justification documents, FAA reauthorization filings, EASA counter-UAS guidance publications, and NATO standardization office protocols. Bottom-up unit deployment tracking and top-down defense budget allocation analysis enabled triangulation across estimation approaches.
Scenario-bracketing around FAA mandate timing, Wassenaar Arrangement export control evolution, and directed-energy reliability maturation bounded the projection range. Segmentation dimensions modeled encompass product type, end user archetype, sensor modality technology, and application context across defense, security, surveillance, and border control. CAGRs derived from deployment pipeline analysis and procurement contract velocity. Forecast inputs incorporated electromagnetic environmental effects certification timelines and swarm coordination automation thresholds.
Macroeconomic conditions sit as an overlay; deviation in defense budget sequestration, gallium nitride supply availability, or civilian aviation frequency allocation disputes would shift the trajectory. Forecasts incorporate documented assumptions regarding FAA regulatory expansion pace and ISO/IEC benchmark finalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
UAV Drones Market
UAV
Passenger Drones Market
UAV
Drone Tracking Antenna Market
UAV
UAV Simulator Market
UAV
Drone Defense System Market
UAV
Global VTOL UAV Market
UAV
Global Smartphone Controlled Drone Market
UAV
Global Multirotor UAV Market
UAV
Global Renewable Drones Market
UAV
UAV Simulator Software Market
UAV
GCC Drones Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Europe Tactical UAV Market
UAV
North America Fuel Cell UAV Market
UAV
Drone Payload Market
UAV
Electric Unmanned Aerial Vehicle Market