
 Global Multirotor UAV Market | 2026-2036
Global Multirotor UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Global Multirotor UAV Market Foresight
Modular payload architecture is decoupling airframe sales from sensor and software bundles, giving buyers flexibility to configure mission-specific packages without full system replacement. SZ DJI Technology Co., Ltd. dominates consumer and prosumer tiers through vertical integration across flight controllers, cameras, and ground-station software. Northrop Grumman Corporation anchors defense-grade multirotor programs with hardened communications and extended endurance platforms. Skydio specializes in autonomous navigation stacks that leverage computer vision for obstacle avoidance in GPS-denied environments.
A multirotor UAV is an unmanned aerial vehicle lifted and propelled by multiple fixed-pitch rotors, typically employing brushless DC motors with electronic speed controllers to manage thrust differential for attitude and position control, with quadcopter configurations representing the dominant architecture due to mechanical simplicity and control-system maturity. The primary commercial purpose spans remote sensing, aerial imaging, and autonomous payload delivery across civilian and military domains. Quadcopter platforms occupy the highest volume tier as cost curves and supply chain scale favor four-rotor designs for mainstream agriculture and inspection work. Lidar-equipped systems are capturing expanding margin pools as infrastructure inspection and surveying applications demand centimeter-level accuracy. Thermal imaging integration is accelerating within public safety and emergency responder end-user segments where night operations and hotspot detection drive procurement specifications.
The FAA enforces Remote ID compliance for all multirotor UAVs operating in United States airspace, creating a hardware retrofit cycle and certification burden that favors established manufacturers with regulatory affairs capacity. EASA's drone regulation framework across European Union member states mandates specific product categories and operational limitations that shape design priorities for vendors targeting that market. China's CAAC coordinates with MIIT on low-altitude economy policies that streamline flight approvals in designated zones, concentrating domestic demand around Shenzhen and Beijing manufacturing clusters. Stakeholders must monitor evolving beyond-visual-line-of-sight rulemakings across these three jurisdictions to anticipate where operational scalability and competitive positioning will crystallize first.
Market Dynamics
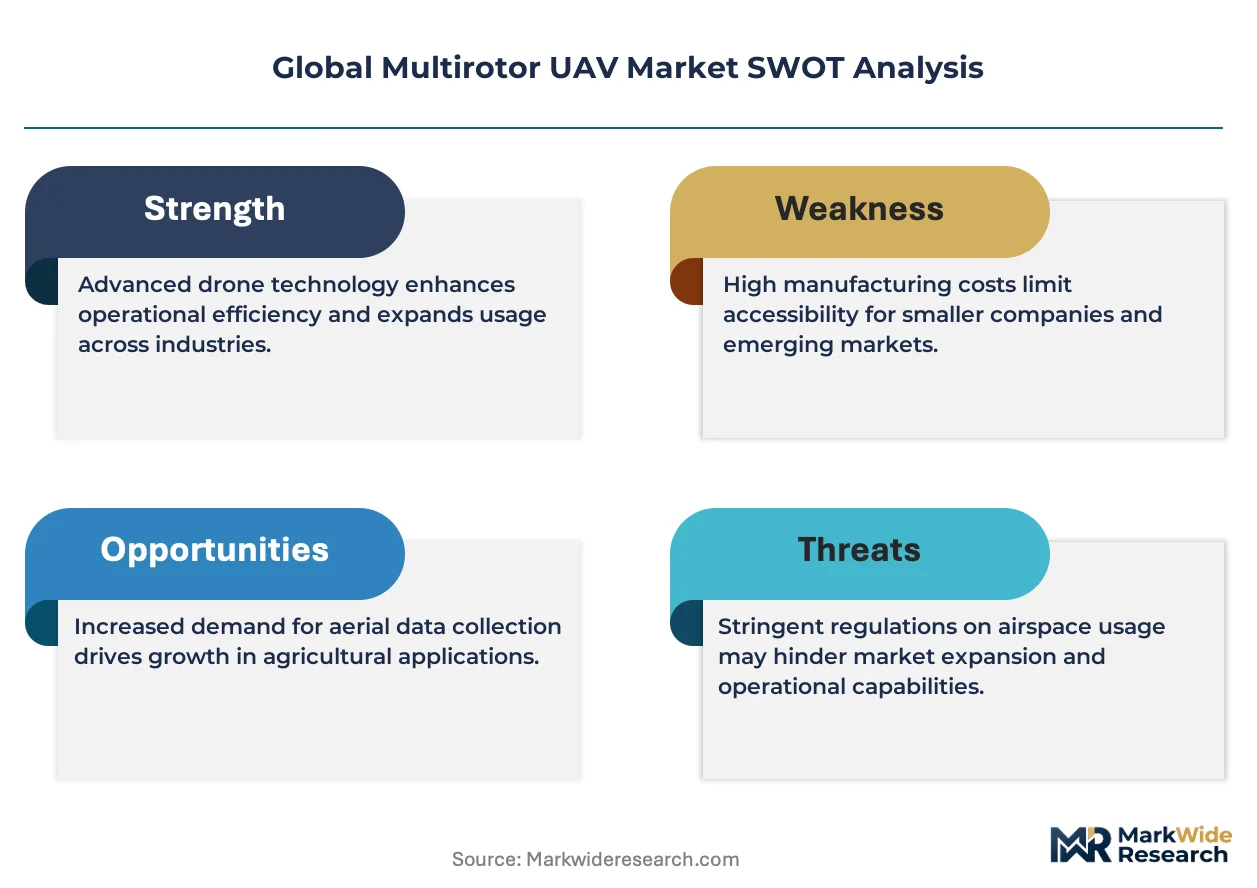
Beyond-visual-line-of-sight rulemaking across the United States, European Union, and China is compressing development timelines and forcing manufacturers to front-load certification investments before revenue scales.
Growth Catalysts
- FAA Remote ID mandate:Hardware retrofit requirements across the United States fleet base are generating replacement demand and pulling forward upgrade cycles for compliant flight controllers and broadcast modules.
- Precision agriculture:Crop health monitoring deployments by farming cooperatives are expanding sensor-integrated multirotor procurement in Brazil, Australia, and the United States Corn Belt.
- Brushless DC motor efficiency gains:Power-to-weight improvements are extending endurance thresholds for commercial inspection missions without battery chemistry breakthroughs.
Market Restraints
- Lithium-ion cell supply concentration:Cathode material processing and cell manufacturing cluster in China's Fujian and Hunan provinces, exposing non-Chinese assemblers to export control and tariff volatility.
- EU AI Act compliance burden:Conformity assessment procedures for autonomous navigation systems are extending time-to-market for computer vision-dependent platforms by twelve to eighteen months.
- Fixed-wing VTOL substitution:Hybrid lift-and-cruise configurations are capturing long-range infrastructure inspection contracts where endurance requirements exceed multirotor mechanical limits.
Strategic Opportunities
- India's low-altitude economy zones:The Directorate General of Civil Aviation is designating corridors in Karnataka and Telangana for commercial drone operations with streamlined flight approvals.
- Lidar-thermal sensor fusion:Converging point-cloud accuracy with radiometric hotspot detection is opening emergency responder specifications previously served by separate platform purchases.
- Subscription-based fleet management:Ground-station software vendors are piloting per-flight-hour pricing models that decouple hardware ownership from operational capability for seasonal agricultural users.
Industry Challenges
- Embedded systems engineering scarcity:Flight control firmware development requires rare combinations of control theory expertise and real-time operating system experience, constraining product roadmap velocity.
- Type certification timeline compression:EASA's Specific category operational authorization demands are forcing smaller manufacturers to outsource quality management system documentation at margin-eroding cost.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Multirotor UAV Market |
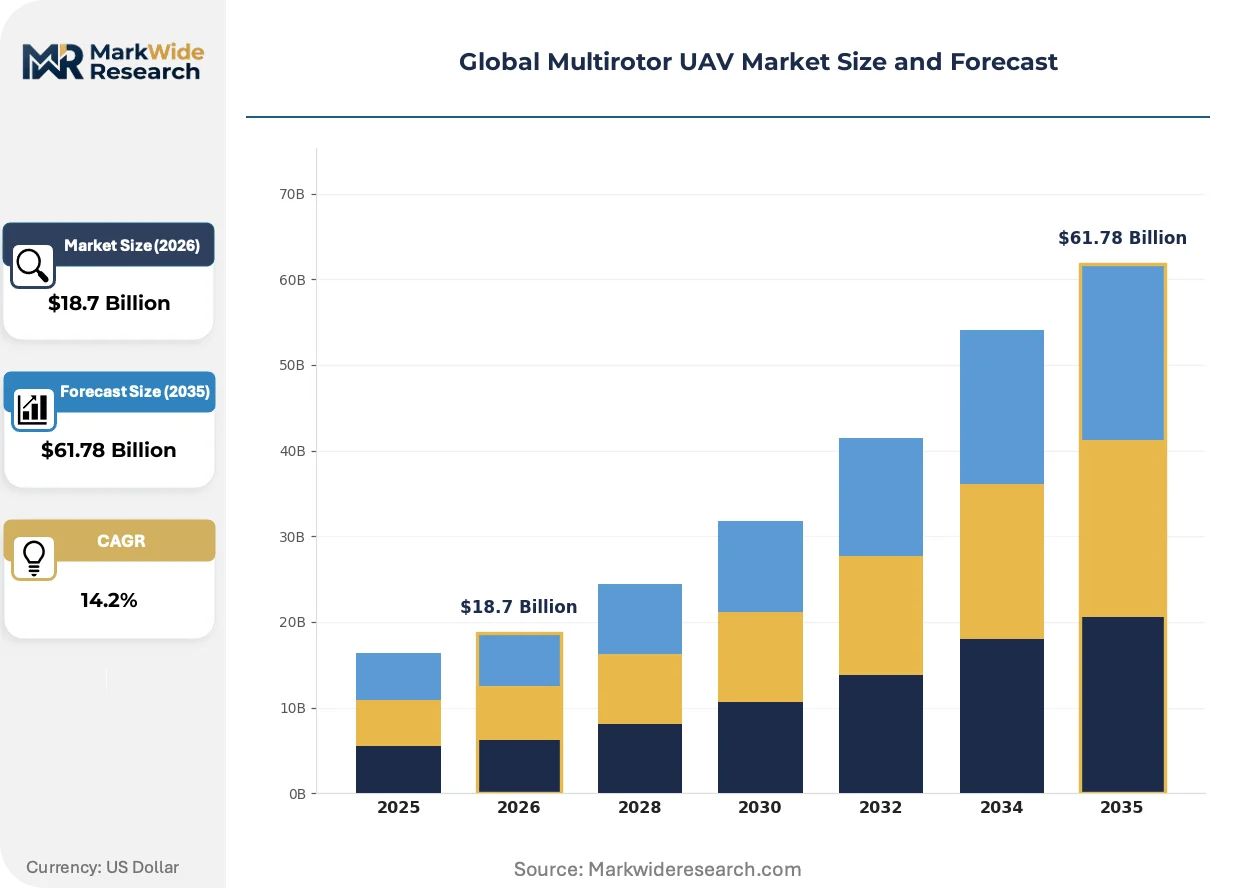
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quadcopter, Hexacopter, Octocopter, Tricopter, Y6, Coaxial Technology: GPS Navigation, Lidar, Thermal Imaging, Optical Flow, Infrared, Ultrasonic Sensors Application: Agricultural Surveillance, Infrastructure Inspection, Film Production, Public Safety, Environmental Monitoring, Scientific Research End User: Precision Farming Firms, Construction Contractors, Cinematographers, Emergency Responders, Environmental Scientists, Research Institutions |
| Companies Covered | SZ DJI Technology Co., Ltd., Northrop Grumman Corporation, Lockheed Martin Corporation, Israel Aerospace Industries Ltd., AeroVironment Inc., Parrot Drone SAS, Autel Robotics, Elbit Systems Ltd., Skydio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Multirotor UAV Market Shifts & Advancements
Autonomous navigation stacks and modular payload architectures are redistributing value capture from airframe manufacturers toward software and sensor suppliers.
Computer vision-based obstacle avoidance is consolidating around edge-processing architectures that eliminate dependency on cloud connectivity and GPS constellations. Public safety agencies in Germany and Japan are specifying these capabilities for urban search-and-rescue contracts. The technology is consolidating procurement decisions around navigation software vendors rather than airframe brands.
EASA's drone regulation framework is mandating operational risk assessments that differentiate between open, specific, and certified categories. Manufacturers targeting European Union member states must embed geofencing and remote identification at the firmware level. Agricultural spraying platforms face the steepest compliance burden due to payload toxicity and population density exposure calculations.
Equipment-as-a-service contracting is displacing outright purchase for seasonal inspection fleets in North American utilities. Drone service providers are retaining airframe ownership while selling data deliverables to transmission line operators. The model is most advanced in Texas and California where investor-owned utilities face wildfire liability exposure driving inspection frequency requirements.
Global Multirotor UAV Market Segmentation
Multirotor UAV procurement patterns diverge sharply across mission profiles, with payload requirements and endurance specifications driving configuration choices more than airframe cost alone. Buyers in precision agriculture prioritize sensor integration flexibility, while defense and public safety agencies emphasize navigation redundancy and hardened communications.
Product Type:
Cost tier and mechanical complexity separate buyers seeking entry-level platforms from those demanding heavy-lift or fault-tolerant architectures.
- Quadcopter:Four-rotor configurations dominate commercial volumes through mechanical simplicity and mature flight control firmware. Agricultural cooperatives in Brazil and the United States Corn Belt are standardizing procurement around quadcopter platforms for crop health monitoring, constrained by battery chemistry limits on flight endurance.
- Hexacopter:Six-rotor designs provide motor-out redundancy for infrastructure inspection missions over populated areas. German transmission line operators specify hexacopter platforms for wildfire liability mitigation programs, where single-motor failure tolerance justifies the 40% airframe cost premium.
- Octocopter:Heavy-lift capacity serves cinematography and industrial sensor payloads exceeding ten kilograms.
- Tricopter:Three-rotor mechanics reduce parts count for budget-constrained academic research programs.
- Y6:Tilt-rotor yaw control eliminates servo complexity in compact inspection drones.
- Coaxial:Stacked contra-rotating propellers shrink footprint for indoor navigation and confined-space emergency response.
Quadcopter platforms lead volumes today; hexacopter configurations are gaining share fastest in regulated commercial applications.
Technology:
Mission accuracy requirements determine sensor stack composition, with GPS-denied navigation capabilities commanding procurement premiums in defense and urban environments.
- GPS Navigation:Satellite-dependent positioning remains the default for open-field agricultural operations across Australia and the United States. FAA Remote ID mandates are embedding GPS receivers as mandatory hardware for United States airspace compliance, pulling forward replacement cycles for legacy flight controllers.
- Lidar:Light detection and ranging systems generate centimeter-accurate point clouds for infrastructure surveying and volumetric measurement. Chinese mining operators in Shanxi Province are deploying lidar-equipped multirotors for stockpile inventory management, where traditional ground-based surveying incurs safety and labor cost penalties.
- Thermal Imaging:Radiometric sensors detect heat signatures for night operations and electrical fault identification.
- Optical Flow:Ground-facing cameras enable position hold without GPS for indoor navigation.
- Infrared:Non-thermal IR sensors support vegetation health analysis in precision viticulture.
- Ultrasonic Sensors:Proximity detection assists low-altitude obstacle avoidance in warehouse automation trials.
GPS navigation leads volumes today; lidar integration is expanding most quickly in infrastructure and mining applications.
Application:
Regulatory authorization timelines and data deliverable standards shape competitive positioning across vertical markets, with seasonal demand patterns in agriculture contrasting against year-round inspection contracts.
- Agricultural Surveillance:Multi-spectral imaging for crop health assessment drives the highest unit volumes in commercial multirotor deployment. Australian cotton growers in Queensland are expanding fleet sizes to weekly monitoring frequencies, replacing satellite imagery latency with on-demand data acquisition.
- Infrastructure Inspection:Transmission line, pipeline, and bridge assessment commands premium pricing for beyond-visual-line-of-sight certified platforms. Japanese utilities in Tohoku region specify autonomous navigation stacks for post-earthquake structural damage surveys, where GPS-denied environments demand computer vision-based positioning.
- Film Production:Cinematography demands stabilized gimbal platforms for broadcast and streaming content capture.
- Public Safety:Search-and-rescue and firefighting operations require thermal-equipped night-flight capabilities.
- Environmental Monitoring:Conservation programs track wildlife and habitat change with acoustic and visual sensors.
- Scientific Research:Atmospheric sampling and glacial survey missions utilize custom payload configurations.
Agricultural surveillance leads volumes today; infrastructure inspection is climbing the fastest as utility liability frameworks tighten.
End User:
Procurement sophistication varies from seasonal rental models in farming to capital-intensive fleet ownership in energy infrastructure, with software integration requirements diverging accordingly.
- Precision Farming Firms:Cooperative and corporate farming operations purchase sensor-integrated platforms for variable-rate input management. Large-scale operations in Germany's Brandenburg state are consolidating vendor relationships around ground-station software compatibility, reducing operational friction across mixed fleets.
- Construction Contractors:Earthwork volume verification and progress documentation drive adoption in civil engineering. Indian infrastructure developers in Karnataka are piloting drone-as-a-service contracts to avoid capital expenditure on seasonal survey requirements.
- Cinematographers:Independent and studio production units prioritize gimbal stabilization and camera payload flexibility.
- Emergency Responders:Fire departments and police units specify thermal imaging and autonomous navigation for night operations.
- Environmental Scientists:Research programs demand open payload architectures for custom sensor integration.
- Research Institutions:Academic users balance cost constraints against experimental flexibility requirements.
Precision farming firms lead volumes today; construction contractors are expanding procurement most quickly in emerging low-altitude economy corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multirotor UAV manufacturing scaled first through Shenzhen's electronics ecosystem before diversifying across defense corridors in the United States and precision engineering clusters in Germany.
China
Domestic demand concentrates around agricultural spraying and infrastructure inspection missions. The Civil Aviation Administration of China coordinates with MIIT on low-altitude economy policies that streamline flight approvals in designated zones. Shenzhen and Beijing manufacturing clusters anchor production capacity for flight controllers, brushless motors, and lithium-polymer battery packs.
United States
Defense procurement and precision agriculture drive platform requirements across military and commercial segments. The FAA enforces Remote ID compliance for all multirotor UAVs operating in national airspace, creating hardware retrofit cycles that favor established manufacturers. Texas and California utilities deploy inspection fleets under investor-owned utility liability frameworks tightening wildfire prevention mandates.
Germany
Transmission line operators and industrial inspection contractors specify redundant motor configurations for missions over populated areas. EASA's drone regulation framework mandates operational risk assessments differentiating open, specific, and certified categories. Bavaria and North Rhine-Westphalia host engineering centers developing autonomous navigation stacks for GPS-denied environments.
India
Infrastructure developers and agricultural cooperatives pilot commercial operations under emerging regulatory clarity. The Directorate General of Civil Aviation designates low-altitude economy corridors in Karnataka and Telangana with streamlined flight approvals. Bangalore and Hyderabad clusters attract component assembly investments serving domestic precision farming and construction survey demand.
Australia
Cotton growers and mining operators deploy multi-spectral and lidar-equipped platforms for crop monitoring and stockpile measurement. The Civil Aviation Safety Authority regulates beyond-visual-line-of-sight operations through certified remote pilot licensing frameworks. Queensland and New South Wales agricultural regions standardize weekly monitoring frequencies replacing satellite imagery latency with on-demand data acquisition.
Global Multirotor UAV Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sensor integration depth and regulatory certification capacity. The vendor base separates into three tiers: vertically integrated platform manufacturers, modular payload specialists, and software-centric autonomy providers. Consolidation pressure concentrates among flight controller firmware developers where embedded systems engineering scarcity constrains roadmap velocity. Dominant competitive moves include strategic partnerships bridging hardware and software stacks and geographic expansion into emerging low-altitude economy corridors.
Within the vertically integrated tier, SZ DJI Technology Co., Ltd. and Northrop Grumman Corporation occupy positions representing divergent market archetypes. SZ DJI Technology Co., Ltd. exemplifies consumer-to-prosumer platform scaling through captive supply chains across flight controllers, cameras, and ground-station software. Northrop Grumman Corporation anchors defense-grade program requirements with hardened communications architectures and extended endurance specifications. Skydio represents the autonomy-software specialist archetype, with computer vision-based obstacle avoidance capabilities consolidating procurement decisions around navigation vendors rather than airframe brands.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Northrop Grumman Corporation |
| Lockheed Martin Corporation |
| Israel Aerospace Industries Ltd. |
| AeroVironment Inc. |
| Parrot Drone SAS |
| Autel Robotics |
| Elbit Systems Ltd. |
| Skydio |
| Others |
Supply & Pricing Matrix
Defense procurement programs and investor-owned utilities anchor the highest-value contract tiers, while precision farming cooperatives drive volume procurement through equipment-as-a-service models that shift ownership risk to fleet operators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates defense-grade platforms with hardened communications from prosumer quadcopters and entry-level academic research units. Price differentiation rests on EASA certification grade and FAA Remote ID compliance status, with compliant flight controllers commanding substantial premiums over retrofit-dependent legacy hardware. Pricing pressure stems from lithium-ion cell cost volatility concentrated in China's cathode processing corridors. Agricultural cooperatives exhibit the sharpest price sensitivity, while defense agencies prioritize mission assurance over unit economics.
Supply Chain Analysis
Brushless DC motor production rests on rare-earth magnet processing in China's Inner Mongolia and Jiangxi provinces, with Japanese and German manufacturers controlling high-precision bearing supply. Lithium-polymer cell assembly clusters in Shenzhen and Dongguan feed global pack integration. Cathode material supply draws from Fujian and Hunan processing facilities, exposing non-Chinese assemblers to export control vulnerability. Distribution runs through Shenzhen component markets for OEM supply, complemented by regional distribution centers in Texas and Bavaria serving defense and industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as procurement specifications harden around beyond-visual-line-of-sight certification and autonomous navigation redundancy.
For Market Incumbents: To counter fixed-wing VTOL substitution in long-range infrastructure inspection, SZ DJI Technology and Northrop Grumman should deepen backward integration into flight controller firmware and hardened communications modules. Certification capacity in EASA's Specific category and FAA type approval pathways represents the critical defensive moat against modular payload specialists eroding airframe margins. For New Entrants and Emerging Players: Capture India's low-altitude economy corridors in Karnataka and Telangana where DGCA flight approval streamlining has outpaced mature market regulatory clarity. Subscription-based fleet management for seasonal agricultural users offers the most penetrable entry vector, with per-flight-hour pricing models decoupling hardware ownership from operational capability. For Investors and Strategic Acquirers: Defense contractors and precision agriculture platform consolidators are the most active acquirers in this space, targeting autonomous navigation software stacks where embedded systems engineering scarcity constrains organic development. Acquisition focus should center on computer vision specialists with GPS-denied positioning capabilities. Watch EASA and FAA beyond-visual-line-of-sight rulemaking acceleration as the primary inflection signal for operational scalability and valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Stack Acquisition | Skydio's computer vision positioning consolidates procurement decisions around software vendors in GPS-denied environments. |
| Modular Payload Architecture Development | Sensor-agnostic airframe designs decouple hardware refresh cycles from mission-specific equipment upgrades for agricultural cooperatives. |
| Regulatory Certification Pre-Investment | EASA Specific category operational authorization demands twelve-to-eighteen-month lead times that favor established quality management systems. |
| Geographic Expansion into Low-Altitude Corridors | DGCA-designated zones in India offer first-mover positioning before mature market saturation hardens competitive barriers. |
| Subscription Fleet Management Pilot | Per-flight-hour ground-station pricing reduces capital friction for seasonal cotton growers in Queensland and Texas. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with flight control firmware engineers, regulatory affairs specialists at EASA and FAA, precision farming cooperative procurement managers, and defense program acquisition officers with secondary validation against CAAC low-altitude economy policy documents, EASA drone regulation framework updates, FAA Remote ID compliance databases, and customs trade data on brushless motor and lithium-polymer battery flows. Bottom-up fleet deployment estimates triangulated against top-down market sizing across the analysis window.
Segment-weighting approaches modeled product type configurations, technology integration levels, application verticals, and end-user procurement sophistication tiers across the projection horizon. CAGRs derived from fitted growth curves incorporating regulatory authorization timeline assumptions, battery chemistry improvement trajectories, and autonomous navigation adoption rates in GPS-denied environments.
Beyond-visual-line-of-sight rulemaking acceleration, lithium-ion supply disruption, and EU AI Act compliance timeline extension are the dominant revision risks to modeled outputs. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Inspection Drones in Confined Space Market
UAV
Asia-Pacific Drone Motor Market
UAV
Autonomous Aircraft Cameras Market
UAV
Drone Telematics Market
UAV
UAV Simulator Market
UAV
Drone Wireless Charging Station Market
UAV
Delivery Drones Market
UAV
Asia Pacific Small UAV Market
UAV
United States Drone Services Market
UAV
Drone Data Management Market
UAV
Drone Leasing Market
UAV
Global Smart Commercial Drones Market
UAV
Micro Drone Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Short-Range Delivery Drone Market
UAV
Middle-East and Africa Drones Market