
 Autonomous Military Weapon Market | 2026-2036
Autonomous Military Weapon Market Size, Share, and Industry Trends Forecast 2026-2036
Autonomous Military Weapon Market Insights
The capability gap between software-defined autonomy stacks and legacy hardware platforms is rotating competitive capital toward algorithm-intensive development. Lockheed Martin leverages its satellite-integrated command infrastructure to dominate high-altitude autonomous systems. Rheinmetall AG anchors European ground-based programs through its tracked unmanned vehicle architectures. Elbit Systems Ltd. specializes in sensor-fusion suites that compress targeting cycles for tactical teams operating in contested electromagnetic environments.
Autonomous military weapons are self-directing combat systems capable of identifying, tracking, and engaging targets through onboard processing without continuous human operator input, typically integrating electro-optical infrared sensors, millimeter-wave radar, and embedded inference engines operating at sub-100-millisecond latency for time-critical engagement decisions. Their primary purpose is to reduce personnel exposure in denied-access environments while accelerating engagement timelines beyond human reaction limits. Unmanned aerial vehicles currently occupy the largest value share due to mature supply chains in turbofan propulsion and beyond-line-of-sight datalinks. Autonomous combat robots represent the fastest-expanding category as urban warfare doctrine shifts toward expendable ground assets for building clearance and perimeter denial. Directed energy weapons sit at the highest margin tier given bespoke power-management subsystems and limited qualified suppliers for solid-state laser gain media.
The United States Department of Defense imposes autonomous weapon review through its Directive 3000.09 requiring human-supervised approval for lethal decisions, while the EU AI Act classifies military autonomous systems outside its scope yet pressures member-state harmonization through export-control alignment. NATO's emerging Responsible Use framework for AI in defense shapes procurement eligibility for cross-border collaborative programs. Stakeholders must monitor whether emerging lethal autonomous weapons protocols at the United Nations Convention on Certain Conventional Weapons harden into binding constraints that reshape permissible system architectures and geographic sales corridors.
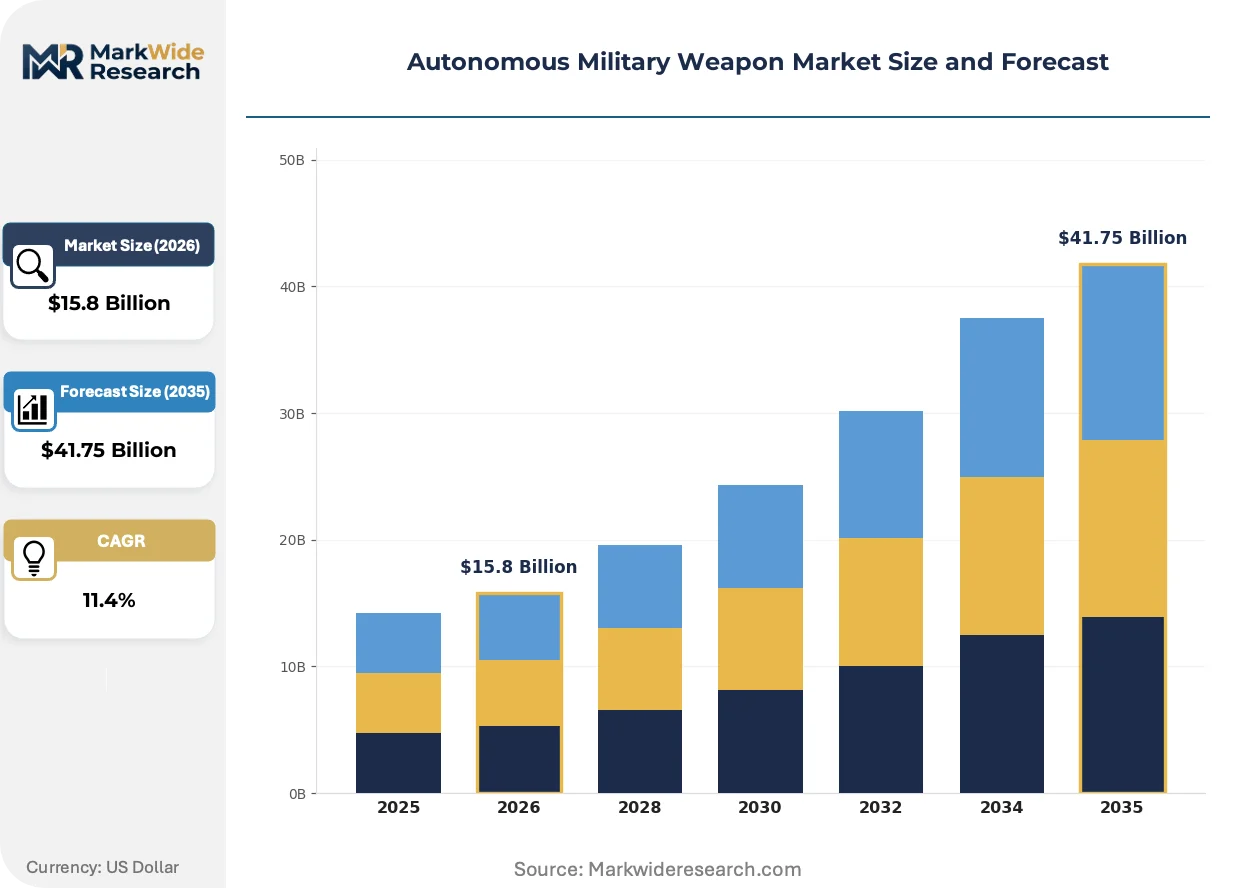
Market Dynamics
The Pentagon's Directive 3000.09 creates a bifurcated procurement landscape where human-supervised lethal systems receive accelerated funding while fully autonomous engagement platforms face extended review cycles, concentrating R&D investment in semi-autonomous architectures with operator-in-the-loop safeguards.
Growth Catalysts
- Urban warfare doctrine:NATO member states prioritize expendable ground assets for building clearance operations, accelerating unmanned vehicle procurement timelines and expanding operational testing budgets.
- EU AI Act alignment pressure:Export-control harmonization across European defense ministries is standardizing certification requirements, reducing cross-border sales friction for compliant system architectures.
- Millimeter-wave radar integration:Sub-100-millisecond target acquisition capabilities are compressing engagement cycles in contested electromagnetic environments, driving sensor-fusion procurement.
Market Restraints
- Solid-state laser gain media scarcity:Directed energy weapon production faces input concentration among limited qualified suppliers, constraining high-margin system scaling.
- Legacy platform integration costs:Software-defined autonomy stacks require extensive hardware modification for fielded vehicle fleets, extending deployment timelines.
- UN CCW protocol uncertainty:Emerging lethal autonomous weapons discussions at the Convention on Certain Conventional Weapons create procurement hesitation pending binding constraint clarity.
Strategic Opportunities
- Perimeter denial applications:Autonomous combat robots for facility protection represent underpenetrated demand within domestic security agencies across Germany and France.
- Beyond-line-of-sight datalink convergence:Satellite-integrated command infrastructure combined with onboard inference engines enables disconnected operations in GPS-denied theaters.
- US unmanned systems budget expansion:Congressional appropriations for autonomous platform development create sustained funding pipelines for compliant contractors.
Industry Challenges
- Embedded systems engineering talent:Sub-100-millisecond latency algorithm development requires specialized skill sets concentrated among defense contractors, constraining workforce scaling.
- Electro-optical infrared certification timelines:Military environmental testing standards for sensor suites extend qualification cycles, delaying platform fielding.
- Interoperability with allied command networks:NATO STANAG compliance for cross-border collaborative programs demands additional software layers, complicating architecture design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autonomous Military Weapon Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $41.75 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unmanned Ground Vehicles, Unmanned Aerial Vehicles, Unmanned Underwater Vehicles, Autonomous Combat Robots, Directed Energy Weapons Technology: Artificial Intelligence, Machine Learning, Sensor Fusion, Computer Vision, Navigation Systems, Robotics Application: Surveillance, Target Acquisition, Reconnaissance, Combat Support, Border Security, Electronic Warfare End User: Defense Forces, Homeland Security, Defense Contractors, Special Operations Units, Tactical Teams |
| Companies Covered | Israel Aerospace Industries Ltd., Lockheed Martin Corporation, BAE Systems plc, Rheinmetall AG, Thales Group, Elbit Systems Ltd., General Dynamics Corporation, Hanwha Aerospace Co., Ltd., Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autonomous Military Weapon Market Trends and Innovations
Autonomous military weapon development is pivoting from hardware-centric platforms toward algorithm-intensive architectures, with competitive advantage migrating to inference engine performance and sensor-fusion sophistication rather than airframe or chassis design.
Onboard processing hardware is miniaturizing. Edge-computing modules for real-time target classification now deploy within tactical unmanned aerial vehicle payload constraints. Special operations units across multiple NATO forces are field-testing these compressed architectures for denied-access reconnaissance missions. This compression is enabling distributed swarming tactics previously impossible under centralized command-and-control datalink dependencies.
EU AI Act high-risk system classifications are reshaping European procurement eligibility. Military autonomous systems sit outside direct regulatory scope, yet export-control alignment pressures member-state harmonization. German and French defense ministries now require algorithmic transparency documentation for cross-border collaborative programs, favoring vendors with established audit trails.
Defense acquisition patterns are fragmenting across operational domains. Traditional platform-centric procurement is yielding to capability-module purchasing where autonomy software licenses separate from hardware delivery. US Special Operations Command exemplifies this shift through standalone algorithm procurement for existing unmanned fleets, with similar patterns emerging in UK Defence Equipment and Support frameworks.
Autonomous Military Weapon Market Segmentation
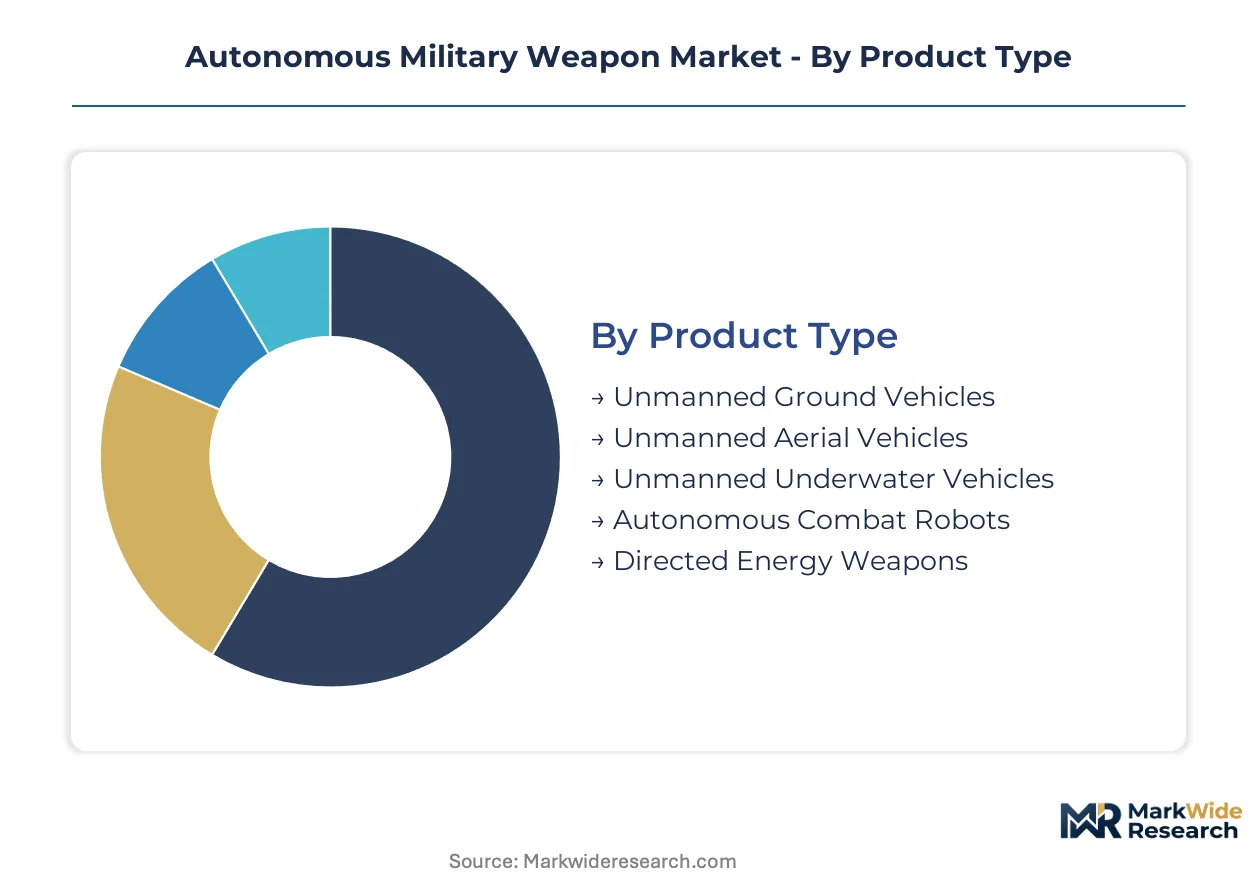
Segmentation in autonomous military weapons reveals where procurement budgets concentrate and where emerging capabilities are displacing legacy platforms. Understanding these divides exposes which technology stacks capture defense ministry attention and which application domains face tightening operational constraints.
Product Type:
Margin pools concentrate in directed energy architectures due to bespoke power-management subsystems and limited qualified suppliers for solid-state laser gain media.
- Unmanned Ground Vehicles:Tracked and wheeled platforms integrate electro-optical infrared sensors with embedded inference engines for terrain navigation. Demand clusters in Germany and France for urban warfare building clearance, driven by NATO doctrine shifts toward expendable ground assets.
- Unmanned Aerial Vehicles:Turbofan and electric propulsion variants dominate current procurement volumes through mature beyond-line-of-sight datalink supply chains. US Pentagon budget allocations sustain the largest operational fleets, though GPS-denied theater requirements are accelerating onboard processing investments.
- Unmanned Underwater Vehicles:Acoustic and magnetic anomaly detection systems patrol harbor perimeters and submarine chokepoints. Naval procurement from US and UK defense ministries favors long-endurance glider architectures.
- Autonomous Combat Robots:Ground platforms with sub-100-millisecond targeting cycles are expanding most quickly as perimeter denial applications multiply across domestic security agencies. Urban warfare doctrine in NATO member states prioritizes these assets for building clearance.
- Directed Energy Weapons:Solid-state and chemical laser systems with specialized thermal management subsystems command premium pricing. Limited supplier concentration for gain media constrains production scaling despite high margins.
Unmanned Aerial Vehicles hold installed capacity. Autonomous Combat Robots are rotating up the share rankings.
Technology:
Development cost tiers separate algorithm-intensive autonomy stacks from hardware-centric sensor platforms, with inference engine performance commanding premium licensing fees.
- Artificial Intelligence:Deep learning architectures for target classification and engagement decision support. EU AI Act alignment pressures are standardizing certification requirements across German and French defense ministries, favoring vendors with algorithmic transparency documentation.
- Machine Learning:Adaptive threat recognition models trained on classified operational datasets. US Special Operations Command procures standalone algorithm licenses for existing unmanned fleets, separating software from hardware delivery.
- Sensor Fusion:Millimeter-wave radar combined with electro-optical infrared compresses targeting cycles in contested electromagnetic environments. Elbit Systems and Rheinmetall anchor this layer through integrated suite architectures.
- Computer Vision:Real-time object detection and tracking algorithms operating at edge-computing latency thresholds. Miniaturization trends enable deployment within tactical payload constraints.
- Navigation Systems:Inertial measurement units and celestial references for GPS-denied positioning. Satellite-integrated command infrastructure from Lockheed Martin dominates high-altitude applications.
- Robotics:Actuation and locomotion subsystems for ground-based platforms. Legacy hardware integration costs extend deployment timelines for fielded vehicle fleet modifications.
Artificial Intelligence captures the steepest expansion trajectory. Robotics maintains foundational infrastructure share.
Application:
Operational maturity varies sharply, with surveillance and reconnaissance commanding established procurement pipelines while electronic warfare faces classified budget fragmentation.
- Surveillance:Persistent wide-area motion imagery and signals intelligence collection. Beyond-line-of-sight datalink convergence enables disconnected operations in contested theaters.
- Target Acquisition:Sub-100-millisecond sensor-to-shooter linkages for time-critical engagements. NATO STANAG compliance demands complicate cross-border collaborative program architectures.
- Reconnaissance:Denied-access penetration missions for special operations units. Edge-computing module compression is enabling distributed swarming tactics.
- Combat Support:Ammunition resupply, casualty evacuation, and communication relay functions. US unmanned systems budget expansion sustains funding pipelines.
- Border Security:Perimeter monitoring and intrusion detection for homeland security agencies. Underpenetrated demand exists in German and French domestic security markets.
- Electronic Warfare:Signal jamming, deception, and spectrum dominance operations. Contested electromagnetic environment requirements drive sensor-fusion procurement.
Surveillance holds mature procurement volume. Electronic Warfare is climbing the fastest in budget priority.
End User:
Customer concentration shapes contract structures, with defense forces demanding full system ownership while special operations units favor modular capability purchasing.
- Defense Forces:National military services operating integrated command-and-control networks. Pentagon Directive 3000.09 imposes human-supervised approval requirements for lethal decisions, bifurcating procurement toward semi-autonomous architectures.
- Homeland Security:Domestic agencies responsible for critical infrastructure protection. Perimeter denial applications for facility protection represent expanding demand in European markets.
- Defense Contractors:Prime and subsystem suppliers integrating autonomy stacks into platform deliveries. Algorithm-intensive development is rotating competitive capital toward software-defined architectures.
- Special Operations Units:Elite forces conducting denied-access reconnaissance and direct action. Field-testing of compressed edge-computing architectures is accelerating miniaturization roadmaps.
- Tactical Teams:Small-unit formations requiring portable autonomous support systems. Sensor-fusion suites compress targeting cycles for operations in contested electromagnetic environments.
Defense Forces anchor procurement volume. Special Operations Units are gaining influence fastest in requirements definition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States defense procurement budgets while European systems face cost compression from export-control harmonization requirements. The United States Department of Defense sustains premium procurement timelines through Congressional unmanned systems appropriations. German and French ministries standardize certification documentation under EU AI Act alignment pressures.
United States
Pentagon budget allocations for unmanned systems exceed peer nation commitments by substantial margins. Directive 3000.09 imposes human-supervised approval requirements that bifurcate procurement toward semi-autonomous architectures. Defense contractors cluster around Washington DC metro, Huntsville Alabama, and San Diego California for proximity to program offices and test ranges.
Germany
Rheinmetall AG anchors tracked unmanned vehicle programs for urban warfare building clearance operations. The Federal Ministry of Defence requires algorithmic transparency documentation for cross-border NATO collaborative programs. Industrial capacity concentrates in Düsseldorf region and Bavaria for ground system integration and sensor-fusion development.
France
Thales Group commands satellite-integrated command infrastructure for high-altitude autonomous systems. DGAC and DGA certification frameworks shape procurement eligibility for export markets. Aerospace and defense engineering clusters in Toulouse and Paris-Saclay corridor drive autonomy software development for tactical applications.
Israel
Israel Aerospace Industries and Elbit Systems anchor electro-optical infrared sensor-fusion suites for contested electromagnetic environments. Israeli Defense Forces field-testing accelerates miniaturization roadmaps for edge-computing modules. Defense technology development concentrates in Haifa and Tel Aviv metro corridors for special operations unit requirements.
South Korea
Hanwha Aerospace Co., Ltd. represents expanding East Asian capacity for autonomous combat robot platforms. Korean Agency for Technology and Standards certification requirements align with NATO STANAG frameworks for export compatibility. Manufacturing and R&D activity clusters in Changwon and Seoul capital region for ground-based unmanned systems.
Autonomous Military Weapon Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where algorithm-intensive developers command premium positioning while hardware fabricators compete on production scale. The vendor base separates into three strategic archetypes: satellite-integrated command infrastructure providers, sensor-fusion suite specialists, and tracked vehicle platform integrators. Dominant competitive moves include strategic partnerships for beyond-line-of-sight datalink convergence and portfolio diversification into perimeter denial applications.
Within the sensor-fusion specialist tier, Elbit Systems Ltd. and Rheinmetall AG exemplify contrasting geographic anchoring for European and Middle Eastern market access. Lockheed Martin Corporation occupies a position representing North American prime contractor scale for high-altitude autonomous systems. These three entities illustrate how competitive positioning separates across algorithm licensing, hardware integration, and command infrastructure domains without overlapping core competencies.
| Leading Market Players |
|---|
| Israel Aerospace Industries Ltd. |
| Lockheed Martin Corporation |
| BAE Systems plc |
| Rheinmetall AG |
| Thales Group |
| Elbit Systems Ltd. |
| General Dynamics Corporation |
| Hanwha Aerospace Co., Ltd. |
| Northrop Grumman Corporation |
| Others |
Pricing and Supply Chain Analysis
EU AI Act high-risk system classifications gate both supplier qualification and price differentiation simultaneously, as algorithmic transparency documentation requirements concentrate procurement eligibility among vendors with established audit trails while compressing margins for non-compliant architectures. Pentagon Directive 3000.09 imposes parallel certification burdens in the United States, creating dual-track pricing where human-supervised systems command premiums over fully autonomous alternatives facing extended review cycles.
Pricing Analysis
Configured-to-order pricing spreads of 40-60% separate standard unmanned aerial vehicle platforms from customized sensor-fusion suites with sub-100-millisecond latency specifications. The dominant structure runs through project-based contracting with milestone payments tied to certification gates, where price differentiation rests on ITAR compliance tier and embedded inference engine performance grade. Cost compression in directed energy weapon tiers is intensifying because solid-state laser gain media scarcity limits qualified supplier pools, while special operations units show lowest price sensitivity due to mission-critical latency requirements.
Supply Chain Analysis
Inbound logistics costs for millimeter-wave radar components face acute pressure from transpacific container availability constraints and Port of Long Beach congestion affecting electro-optical infrared sensor deliveries. Supply concentrates in the United States for satellite-integrated command infrastructure, Germany for tracked vehicle platforms, and Israel for sensor-fusion suites. Raw material dependencies center on gallium arsenide substrates, rare-earth magnet alloys, and solid-state laser gain media crystals. Single-source vulnerability in directed energy gain media suppliers constrains scaling. Distribution runs through prime contractor integration with defense ministry program offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous military weapons represent a service-attach opportunity where algorithm licensing and sustainment contracts expand faster than hardware unit sales, as US Special Operations Command procurement patterns demonstrate through standalone software acquisitions for existing unmanned fleets.
For Market Incumbents: Shield algorithm-intensive revenue streams by deepening backward integration into solid-state laser gain media production and securing exclusive ITAR-compliant foundry capacity. Satellite-integrated command infrastructure providers face margin pressure from emerging sensor-fusion specialists; incumbents should consolidate through selective acquisition of edge-computing module developers with established NATO STANAG compliance documentation. For New Entrants and Emerging Players: Differentiate on algorithmic transparency documentation for EU AI Act alignment, targeting German and French perimeter denial applications for domestic security agencies where incumbent presence remains thin. The most penetrable white-space sits in GPS-denied navigation subsystems for denied-access reconnaissance missions. A direct-to-program-office go-to-market angle bypasses prime contractor gatekeeping. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-defined autonomy stacks as hardware commoditization accelerates, favoring asset-light algorithm licensing models over platform fabrication. Long-term viability over the coming decade hinges on regulatory compliance infrastructure rather than manufacturing scale. Acquisition targets should display established audit trails for cross-border NATO collaborative programs. The signal to monitor is binding constraint emergence from UN Convention on Certain Conventional Weapons protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithm Licensing Separation | US Special Operations Command procurement patterns validate standalone software revenue models decoupled from hardware delivery. |
| ITAR-Compliant Foundry Investment | Domestic gallium arsenide substrate production secures supply chain resilience for millimeter-wave radar integration. |
| NATO STANAG Certification Pre-Positioning | Cross-border collaborative program eligibility requires interoperability software layers that extend development timelines. |
| Perimeter Denial Application Expansion | German and French domestic security agencies represent underpenetrated demand for autonomous combat robot platforms. |
| Directed Energy Supply Consolidation | Limited qualified suppliers for solid-state laser gain media create captive supply opportunities for vertical integration. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with defense procurement officers, autonomy software engineers, sensor-fusion specialists, and program office directors; and secondary validation through Pentagon budget justification documents, EU AI Act regulatory filings, NATO STANAG specification databases, and defense contractor SEC disclosures. Bottom-up triangulation across platform unit economics and top-down reconciliation against national unmanned systems appropriations anchored volume estimates.
Across the analysis window, the analytical framework modeled segmentation dimensions spanning product type, autonomy technology stack, operational application, and end-user archetype with defense ministry procurement tier. CAGRs were derived from historical budget trajectory analysis and policy-documented procurement acceleration signals. Industry-specific forecast inputs included Pentagon Directive 3000.09 implementation timelines and EU AI Act export-control alignment pressures.
Forecasts assume regulatory continuity in US ITAR regimes and EU AI Act implementation; material policy shifts at the UN Convention on Certain Conventional Weapons would require re-modeling. Assumptions reflect documented program office statements and defense ministry budget allocations. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Unmanned Systems
United States ROV Market
Unmanned Systems
Unmanned Surface Vehicle (USV)S Market
Unmanned Systems
Autonomous Drone Station Market
Unmanned Systems
Japan Autonomous Navigation Market
Unmanned Systems
Brazil ROV Market
Unmanned Systems
United States Aerostat Systems Market
Unmanned Systems
North America Hyperloop Technology Market
Unmanned Systems
North America Unmanned Systems Market
Unmanned Systems
Drone Battery System Market
Unmanned Systems
High Altitude Platform Market
Unmanned Systems
Military Robotics Market
Unmanned Systems
Missile Guidance System Market
Unmanned Systems
Asia-Pacific Military Unmanned Vehicles Market
Unmanned Systems
Middle-East and Africa AUV & ROV Market
Unmanned Systems
Remote Weapon Systems Market
Unmanned Systems
Global Military Robotics Autonomous Systems Market