
 Rc Helicopter Market | 2026-2036
Rc Helicopter Market Size, Share, and Industry Trends Forecast 2026-2036
Rc Helicopter Market Analysis
Software-defined flight stabilization is consolidating as the critical service layer in RC helicopter value chains, transforming hardware sales into recurring upgrade cycles. DJI Innovations leverages its proprietary flight control algorithms to lock in user ecosystems across consumer and prosumer tiers. Align Corporation anchors the premium aerobatic segment through precision-machined rotor head assemblies and carbon fiber airframe specialization. Horizon Hobby sustains North American channel dominance through hobby shop distribution networks and proprietary Bind-N-Fly radio protocols.
An RC helicopter is a radio-controlled rotorcraft with a single main rotor and anti-torque tail rotor, typically spanning 150mm to 700mm in rotor diameter, powered by electric brushless motors or nitro-methane combustion engines, designed for recreational flight, competitive aerobatics, or camera payload carriage. Electric technology leads unit volume due to declining lithium polymer cell costs and simplified maintenance profiles, while nitro systems retain a dedicated enthusiast base seeking extended flight duration and mechanical tunability. Full-size electric models capture the fastest growth trajectory as FPV racing leagues and cinematic aerial photography expand, whereas nano segments face margin compression from toy-grade commoditization.
The FAA governs RC helicopter operations under Part 107 and recreational flyer rules in the United States, mandating registration and altitude ceilings that shape product design for American consumers. EASA harmonizes unmanned aircraft certification across EU member states through the EU Drone Regulation framework, creating a unified market access pathway for manufacturers. China's CAAC and MIIT jointly administer GB standards for radio transmission power and frequency allocation, directly impacting transmitter compatibility for export-bound production. Stakeholders must monitor evolving remote identification mandates and geofencing requirements as regulators progressively integrate hobbyist rotorcraft into national airspace management systems.
Market Dynamics
Software-defined flight stabilization is consolidating as the critical service layer in RC helicopter value chains, transforming hardware sales into recurring upgrade cycles and locking manufacturers into algorithm-dependent ecosystems.
Growth Catalysts
- FAA Part 107:Commercial drone licensing in the United States legitimizes professional aerial cinematography, expanding addressable demand for camera-capable rotorcraft beyond hobbyist bases.
- Brushless motor efficiency gains:Neodymium magnet formulations and ESC firmware advances extend flight endurance past twenty minutes, enabling practical FPV racing and inspection missions.
- Shenzhen component clustering:Concentrated lithium polymer cell and carbon fiber airframe manufacturing in Guangdong Province compresses production lead times and input costs for global OEMs.
Market Restraints
- Lithium polymer price volatility:Cobalt and lithium carbonate spot market swings directly impact bill-of-materials stability for electric powertrain suppliers.
- Single-region supply concentration:Overreliance on Dongguan CNC machining houses for precision rotor head assemblies creates vulnerability to localized logistics disruptions or trade policy shifts.
- Nitro engine emissions friction:EASA and EPA tailpipe regulations progressively restrict methanol-fueled combustion systems in urban flying fields, compressing the addressable base for fuel-powered enthusiasts.
Strategic Opportunities
- India hobbyist penetration:Low current RC helicopter ownership rates among India's expanding middle class present first-mover positioning for entry-level electric models priced below premium Western tiers.
- Remote ID mandate preparation:FAA broadcast requirements for unmanned aircraft create aftermarket retrofit demand for transponder modules and firmware upgrades across legacy fleets.
- FPV racing league broadcast rights:Dedicated sports streaming channels monetize competitive rotorcraft events, pulling equipment specifications toward high-visibility, sponsor-friendly aerobatic performance.
Industry Challenges
- Flight controller firmware certification:EASA's Specific Category operational approval demands extensive failure-mode documentation, stretching engineering timelines for smaller developers lacking dedicated compliance staff.
- Geofencing database maintenance:Continuous updates to restricted airspace polygons require persistent server infrastructure and legal liability exposure for manufacturers hosting no-fly zone servers.
- Radio frequency harmonization:Divergent ISM band allocations between Japan's METI, Europe's CEPT, and the FCC force SKU fragmentation or costly multi-protocol transmitter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rc Helicopter Market |
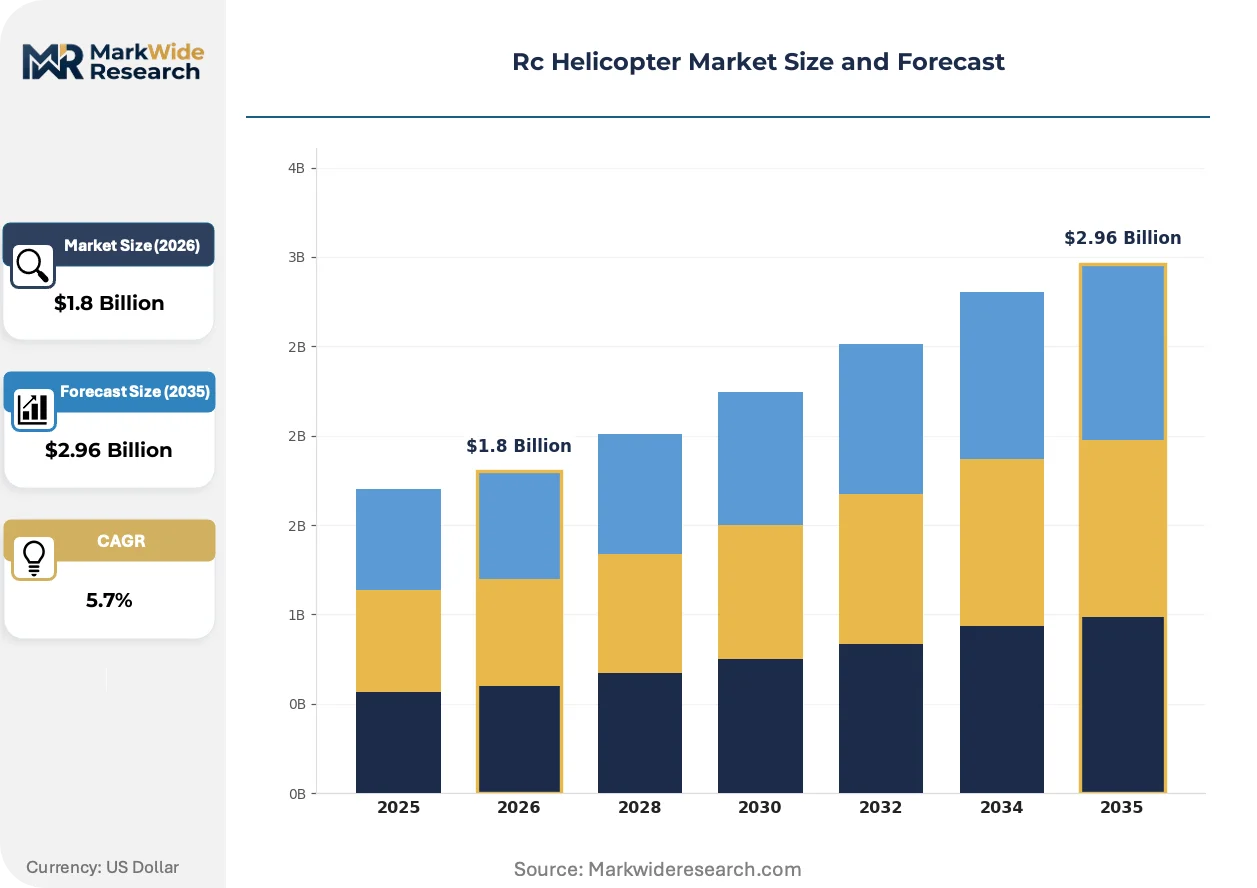
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nano, Mini, Micro, Full-Size Technology: Electric, Nitro, Gas, Hybrid End User: Hobbyists, Professionals, Educational Institutions, Military Application: Racing, Aerial Photography, Surveillance, Training |
| Companies Covered | DJI Innovations, Align Corporation, Horizon Hobby, Syma Toys, Blade, WLtoys, Walkera Technology, Thunder Tiger Corporation, Gaui Model, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rc Helicopter Market Emerging Trajectories
Active stabilization algorithms and embedded machine vision are compressing the skill threshold for piloting complex maneuvers, simultaneously expanding the casual user base and reshaping competitive differentiation toward software rather than mechanical refinement.
Brushless direct-drive motor systems are consolidating as the dominant propulsion architecture across mid-market and premium RC helicopter tiers. Hobbyists migrating from brushed or nitro alternatives demand quieter operation and reduced maintenance intervals. This technology shift is consolidating aftermarket parts demand around standardized ESC form factors and proprietary motor mounting patterns that lock users into manufacturer-specific upgrade ecosystems.
EASA's EU Drone Regulation framework is harmonizing operational certification across twenty-seven member states, replacing fragmented national permits with unified remote pilot competency standards. Manufacturers must now design for a single conformity assessment pathway rather than country-by-country type acceptance. The standard-midrange electric segment faces the steepest compliance cost absorption, as budget producers lack capital to sustain notified body relationships.
Direct-to-consumer channel expansion is fragmenting traditional hobby shop distribution networks that previously controlled product education and post-sale support. Enthusiasts increasingly research specifications through video platforms and purchase through manufacturer websites or marketplace aggregators. This behavioral pivot is most pronounced in North American and Western European markets where brick-and-mortar specialty retail density has declined sharply over the past decade.
Rc Helicopter Market Segmentation
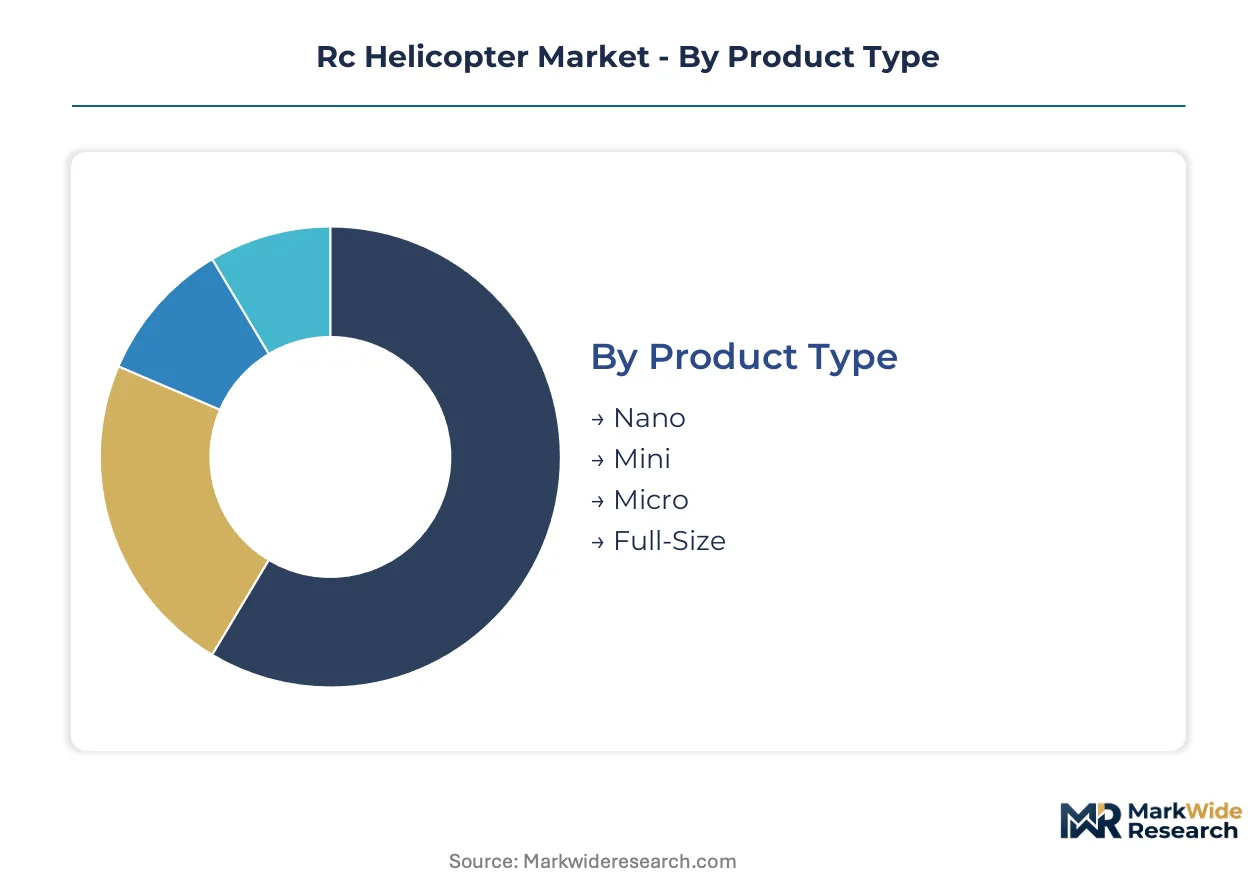
RC helicopter segmentation reveals divergent replacement cycles across size classes and powertrains. Upgrade cadences stretch from months for nano-class toy-grade units to years for precision aerobatic platforms. Understanding these rhythms helps suppliers calibrate inventory and service revenue models.
Product Type:
Upgrade cycles compress toward smaller form factors as component costs drop and durability expectations shift.
- Full-Size:Spanning 450mm to 700mm rotor diameter, these platforms accommodate interchangeable gimbals, telemetry modules, and long-range radio systems. Demand clusters among FPV racing leagues and commercial aerial cinematographers in Germany and the United States, where brushless motor standardization enables incremental powertrain swaps rather than full airframe replacement.
- Mini:250mm to 450mm rotor diameter balances portability with payload capacity for action cameras. Japanese hobbyists and South Korean drone racing clubs drive volume, though lithium polymer cell degradation accelerates replacement purchases relative to larger formats.
- Micro:150mm to 250mm span suits indoor flight and beginner training. Chinese domestic consumption absorbs the majority of production from Shenzhen assembly lines.
- Nano:Sub-150mm designs target impulse retail and toy channels. Margin pressure from commodity electronics limits aftermarket attachment rates.
Volume placements concentrate in Mini; the faster expansion belongs to Full-Size.
Technology:
Powertrain selection locks users into distinct maintenance ecosystems and spare parts procurement patterns.
- Electric:Brushless motor and lithium polymer configurations dominate unit shipments through simplified storage and reduced mechanical complexity. German and French regulatory frameworks favor electric noise profiles for urban flying site access.
- Nitro:Methanol-fueled combustion retains dedicated adherents seeking extended flight duration and mechanical tunability. United States and Japanese enthusiast clubs sustain residual demand despite tightening EPA and local emissions constraints.
- Gas:Gasoline-powered systems scale to heavy-lift applications exceeding ten kilograms payload. Professional agricultural and industrial inspection operators in Australia and Brazil specify these for endurance missions.
- Hybrid:Combined electric-combustion architectures extend range for specialized surveillance and search-rescue configurations. Development concentrates among defense contractors and university research programs.
Commercial momentum gathers behind Electric; Hybrid architectures climb the fastest among emerging powertrain categories.
End User:
Customer type determines purchasing authority, technical support expectations, and fleet standardization pressure.
- Hobbyists:Individual enthusiasts purchasing one to three units annually, prioritizing community reputation and upgrade compatibility. North American and Western European markets show highest per-capita expenditure on premium aerobatic platforms.
- Professionals:Commercial operators requiring FAA Part 107 or EASA Specific Category certification compliance. Aerial photography studios and infrastructure inspection services in the United States and United Kingdom standardize on programmable flight controllers.
- Educational Institutions:University engineering departments and vocational programs acquiring training fleets. South Korean and Chinese technical institutes expand procurement for robotics and mechatronics curricula.
- Military:Defense agencies specifying hardened communications and extended operational envelopes. Procurement runs through national tender processes with multi-year contract horizons.
Unit economics favor Hobbyists for volume; Professionals gain share fastest as commercial licensing frameworks mature.
Application:
Use case dictates performance specifications, durability requirements, and regulatory exposure.
- Aerial Photography:Camera-stabilized platforms with three-axis gimbal integration. Content creators in the United States and United Kingdom upgrade most frequently to access improved sensor formats.
- Racing:Lightweight, high-thrust configurations optimized for gate navigation and broadcast visibility. FPV league expansion in South Korea and Australia pulls equipment specifications toward standardized competition formats.
- Surveillance:Extended-endurance designs with thermal or multispectral payload options. Border security and critical infrastructure operators in India and Brazil specify these for patrol automation.
- Training:Durable, repairable platforms with stability augmentation for novice pilots. Flight schools and hobby club instruction programs in Germany and Japan favor predictable handling characteristics over performance extremes.
Training applications anchor volume deployment; Racing commands the steepest specification escalation trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Dongguan manufacturing clusters supply the majority of global RC helicopter components, while consumption concentrates in Germany, the United States, Japan, and Australia where hobbyist infrastructure and commercial licensing frameworks mature.
United States
FAA Part 107 commercial licensing and recreational flyer rules legitimize professional aerial cinematography, expanding demand for camera-capable rotorcraft. The FAA mandates registration and altitude ceilings that directly shape product design specifications for American consumers. California and Texas host the densest concentrations of FPV racing leagues and aerial photography studios.
Germany
EASA's EU Drone Regulation framework harmonizes operational certification across member states, creating unified market access for manufacturers. German urban flying site access favors electric noise profiles over nitro combustion systems. Bavaria anchors Central European hobbyist club density and precision engineering supply chains for carbon fiber airframe components.
China
CAAC and MIIT jointly administer GB standards for radio transmission power and frequency allocation, impacting transmitter compatibility for export-bound production. Domestic consumption of micro-class helicopters absorbs majority output from Shenzhen assembly lines. Dongguan CNC machining houses concentrate precision rotor head assembly manufacturing for global OEM procurement.
Japan
METI regulates divergent ISM band allocations that force SKU fragmentation for transmitter engineering. Japanese enthusiast clubs sustain residual demand for nitro-fueled systems despite tightening local emissions constraints. Tokyo and Osaka metropolitan areas concentrate hobby shop retail networks and competitive aerobatics tournament infrastructure.
Australia
Extended-endurance gasoline-powered systems scale to heavy-lift agricultural and industrial inspection missions across vast operational territories. The country's national aviation regulator administers unmanned aircraft certification parallel to EASA and FAA frameworks. Queensland and Western Australia host professional operators specifying ten-kilogram-plus payload configurations for patrol automation.
Rc Helicopter Market Vendor Landscape
Top-tier vendors anchor premium aerobatic and professional cinematography tiers, while mid-market specialists and toy-grade commoditized producers fill volume segments below. The vendor base stratifies across three tiers: algorithm-locked ecosystem players, precision hardware fabricators, and contract assembly exporters. Two dominant competitive moves are consolidating: flight controller firmware certification investments to satisfy EASA Specific Category approvals, and direct-to-consumer channel expansion bypassing traditional hobby shop distribution.
Within the algorithm-dependent ecosystem tier, DJI Innovations exemplifies proprietary flight control platform lock-in across consumer and prosumer tiers. Align Corporation and Horizon Hobby occupy positions at the precision-hardware and channel-dominance vectors respectively—Align through specialized rotor head engineering, Horizon Hobby through North American distribution network control and proprietary radio protocol ecosystems.
| Leading Market Players |
|---|
| DJI Innovations |
| Align Corporation |
| Horizon Hobby |
| Syma Toys |
| Blade |
| WLtoys |
| Walkera Technology |
| Thunder Tiger Corporation |
| Gaui Model |
| Others |
Supply Flow & Price Mechanics
EASA remote identification mandates gate qualified supply access and premium-tier pricing power, as manufacturers absorbing firmware certification costs pass compliance premiums through to camera-capable and commercial-grade rotorcraft tiers while budget producers face margin compression.
Pricing Analysis
Margin tightening in the standard-midrange tier reflects EASA Specific Category compliance cost absorption by smaller developers lacking dedicated certification staff. Three-tier pricing structure across premium aerobatic, standard prosumer, and economy toy-grade levels separates Align Corporation's precision-machined rotor head assemblies from DJI's algorithm-locked ecosystems from Shenzhen commodity assemblers. Price differentiation hinges on flight controller firmware certification grade and carbon fiber airframe customization depth. Pricing pressure intensifies in nano-class segments as Dongguan electronics commoditization accelerates replacement cycles. Hobbyist enthusiasts show lowest price sensitivity for aerobatic platforms, while impulse retail channels exhibit highest elasticity.
Supply Chain Analysis
Domestic-content thresholds in India's phased manufacturing program and Brazil's local assembly incentives are reshaping sourcing patterns for lithium polymer cell integration and final airframe assembly. Component manufacturing concentrates in China, South Korea, and Japan. Shenzhen and Dongguan clusters supply carbon fiber airframes, brushless motors, and precision-machined rotor heads. Raw material dependencies rest on neodymium magnet formulations, lithium carbonate feedstock, and methanol-based nitro fuel chemistry. Single-region vulnerability to Dongguan CNC machining house concentration creates tariff exposure and logistics disruption risk. Distribution runs through direct-to-consumer manufacturer websites, hobby shop networks, and marketplace aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless direct-drive motor systems are displacing nitro combustion and brushed alternatives, compressing maintenance ecosystems and spare parts procurement patterns around standardized ESC form factors.
For Market Incumbents: Deepen proprietary flight control algorithm development to lock user ecosystems against DJI's platform dominance, while securing captive supply of precision-machined rotor head assemblies from Dongguan CNC houses to defend against single-source disruption. Invest in EASA Specific Category firmware certification ahead of smaller competitors to capture commercial operator procurement standardization. Reinforce North American channel control through hobby shop education partnerships and Bind-N-Fly radio protocol ecosystems. For New Entrants and Emerging Players: Begin with India's underpenetrated hobbyist base, where expanding middle-class disposable income meets low current RC helicopter ownership rates and limited premium Western brand presence. Target entry-level electric models priced below established tiers through direct-to-consumer video platform marketing. FPV racing league equipment specifications offer a sponsor-visible, standardized entry point for aerobatic performance credibility. For Investors and Strategic Acquirers: FAA broadcast Remote ID mandate enforcement is the leading indicator that aftermarket transponder retrofit demand will consolidate around firmware-upgradeable legacy fleets and certified new platform introductions. Long-term viability favors algorithm-dependent ecosystem players with recurring service revenue over hardware-only fabricators. Acquisition targets should demonstrate EASA conformity assessment relationships and geofencing server infrastructure. Watch for lithium polymer price volatility spikes as margin compression signals.| Strategic Initiative | Industry Significance |
|---|---|
| Flight Controller Firmware Certification | EASA Specific Category approval unlocks commercial operator procurement in Germany and United Kingdom. |
| Backward Integration into Motor Manufacturing | Neodymium magnet supply control insulates against rare earth price volatility from Chinese export policy. |
| Direct-to-Consumer Channel Expansion | Manufacturer website sales bypass declining North American hobby shop retail density. |
| Geofencing Database Infrastructure | Proprietary no-fly zone servers create recurring service revenue and regulatory liability management. |
| FPV Racing League Partnership | Broadcast visibility pulls equipment specifications toward standardized competition formats in South Korea and Australia. |
Methodological Framework
Multi-period observation of brushless motor efficiency gains, lithium polymer cell cost curves, and regulatory framework evolution anchored the trend analysis, supplemented by interviews with RC helicopter OEM product managers, Shenzhen component suppliers, FAA regulatory affairs specialists, German hobby shop owners, and FPV racing league organizers. Secondary validation drew from FAA Part 107 compliance databases, EASA EU Drone Regulation implementation notices, CAAC GB standards filings, and customs trade data for carbon fiber airframe and lithium polymer cell shipments. Bottom-up segment sizing triangulated against top-down market envelope checks.
Segment-weighting across product type, powertrain technology, end user archetype, and application use case drove the analytical framework. CAGRs were derived from fitted growth curves applied to base-year observations, with cross-validation against technology adoption S-cycles and regulatory milestone timing. Industry-specific forecast inputs included brushless motor penetration rates and EASA remote pilot certification volume trajectories across the analysis window.
Underlying measurement precision varies by segment; full-size and mini-class platforms carry tighter precision than nano-class commodity tiers due to manufacturer disclosure granularity. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and raw material price stability. Lithium carbonate spot volatility, Dongguan logistics disruptions, or accelerated nitro engine emissions restrictions could revise trajectory expectations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Fixed Wing Military Drones Market
UAV
North America Fuel Cell UAV Market
UAV
Drone Data Management Market
UAV
Racing Drone Market
UAV
Electric Glider Market
UAV
Counter-UAS Market
UAV
Bubble Drone Market
UAV
Autonomous Underwater Gliders (AUG) Market
UAV
Global Aerial Survey Services Market
UAV
United States Drone Services Market
UAV
Anti-Drone Market
UAV
Military UAV Sensor Market
UAV
Enterprise Drone Management Solutions Market
UAV
Passenger Drones Market
UAV
Tactical UAV Market
UAV
Europe Tactical UAV Market