
 Electric Unmanned Aerial Vehicle Market | 2026-2036
Electric Unmanned Aerial Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Unmanned Aerial Vehicle Market Foresight
FAA Part 107 remote pilot certification is unwinding barriers to commercial entry while elevating operational compliance burdens for new entrants. SZ DJI Technology leverages its Shenzhen manufacturing base to dominate consumer and prosumer multi-rotor segments across North America and Europe. Northrop Grumman Corporation anchors defense-grade fixed-wing electric UAV programs with sustained R&D intensity in autonomous navigation systems. General Atomics Aeronautical Systems competes in the high-endurance hybrid-electric segment with specialized platforms for intelligence, surveillance, and reconnaissance missions.
Electric unmanned aerial vehicles are aircraft propelled by electric powertrains, typically employing lithium-polymer or lithium-ion battery packs delivering energy densities between 150 and 300 watt-hours per kilogram, with flight durations spanning 20 minutes to several hours depending on configuration and payload. Their primary commercial and industrial purpose centers on replacing manned aviation for data collection, physical delivery, and remote sensing tasks where human presence is costly, hazardous, or impractical. Multi-rotor architectures lead in unit volume across delivery services and infrastructure inspection due to vertical takeoff flexibility and lower capital thresholds, while fixed-wing platforms dominate energy sector environmental monitoring missions where range and endurance determine operational economics. Hybrid technology represents the fastest-expanding segment as battery limitations push developers toward combined powertrains that extend flight duration without sacrificing payload capacity.
FAA Part 107 and the EU's U-space regulatory framework under EASA jurisdiction shape airspace access, pilot qualification, and beyond-visual-line-of-sight operational permissions across the United States and European markets. China's CAAC implements distinct certification pathways for urban air mobility and autonomous navigation that accelerate domestic deployment while creating divergent compliance standards for multinational manufacturers. Stakeholders must monitor evolving battery safety standards from IEC and UN 38.3 testing protocols, as thermal runaway incidents in high-density packs threaten certification timelines and insurance underwriting across all major jurisdictions. The decisive strategic variable will be which operators secure type certification for autonomous navigation before regulators finalize dedicated low-altitude traffic management systems.
Market Dynamics
Battery energy density limitations are compressing flight endurance thresholds while hybrid-electric architectures extend mission profiles for commercial operators. This structural tension between pure-electric simplicity and range requirements shapes platform development roadmaps across defense, agriculture, and logistics verticals.
Growth Catalysts
- FAA Part 107 framework:Remote pilot certification requirements in the United States lower entry barriers for commercial operators while standardizing operational protocols across state jurisdictions.
- Precision agriculture mapping:Crop health monitoring via multispectral sensors replaces manned aircraft surveys, cutting per-acre data collection costs for large-scale farming cooperatives.
- Shenzhen manufacturing cluster:Concentrated battery cell and airframe component production in Guangdong Province compresses procurement lead times for global system integrators.
Market Restraints
- Lithium-polymer cell supply:Cathode material price volatility and concentrated refining capacity in Hunan and Sichuan provinces create input cost instability for battery pack assemblers.
- Beyond-visual-line-of-sight restrictions:EASA U-space framework and FAA waiver requirements impose operational ceilings that limit long-range infrastructure inspection contracts.
- Manned aviation substitution:Helicopter services retain cost advantages for heavy-lift cargo and emergency response missions above 50-kilogram payload thresholds.
Strategic Opportunities
- Urban air mobility corridors:CAAC certification pathways for autonomous navigation in Shenzhen and Shanghai accelerate passenger drone deployment ahead of Western regulatory timelines.
- Last-mile pharmaceutical delivery:Cold-chain validated electric UAV networks address rural healthcare access gaps in sub-Saharan African markets with limited road infrastructure.
- Solid-state battery convergence:Silicon-anode and ceramic electrolyte technologies promise 400+ watt-hour-per-kilogram densities that would eliminate hybrid powertrain complexity for medium-range missions.
Industry Challenges
- Autonomous navigation certification:Type approval timelines for detect-and-avoid systems lag hardware development by 18-24 months across FAA and EASA jurisdictions.
- Low-altitude traffic management integration:Legacy radar infrastructure at municipal airports requires software retrofitting to accommodate electric UAV transponder protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Unmanned Aerial Vehicle Market |
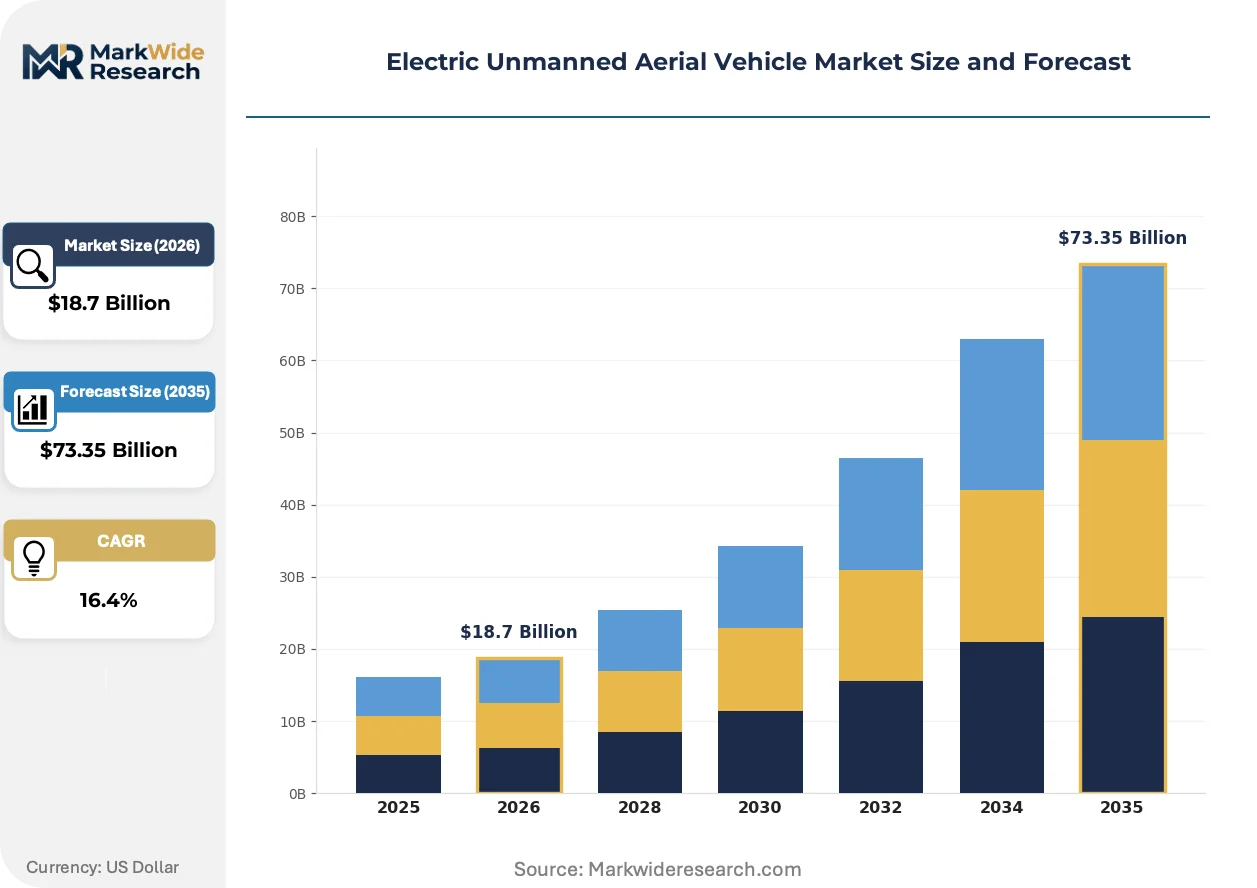
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Tethered Application: Agricultural Surveillance, Infrastructure Inspection, Delivery Services, Environmental Monitoring End User: Agriculture, Energy, Logistics, Public Safety Technology: Battery Electric, Solar Powered, Hybrid Electric, Autonomous Navigation |
| Companies Covered | SZ DJI Technology Co., Ltd., Northrop Grumman Corporation, General Atomics Aeronautical Systems, AeroVironment Inc., Lockheed Martin Corporation, Teledyne FLIR LLC, Parrot, EHang, Israel Aerospace Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Unmanned Aerial Vehicle Market Shifts & Advancements
Powertrain architecture decisions are bifurcating the competitive landscape as operators weigh capital efficiency against mission flexibility. This technical divergence is compressing product life cycles and forcing platform specialization across end-use verticals.
Silicon-carbide power electronics are supplanting traditional silicon MOSFETs in motor controllers for heavy-lift multi-rotor platforms. Agricultural spraying contractors in Brazil and Australia are adopting these systems to reduce thermal losses during high-throttle crop-dusting operations. The shift is enabling 15-20% longer flight durations on equivalent battery capacity, compressing the total-cost-of-ownership gap with combustion alternatives.
EASA's U-space regulatory framework mandates networked identification and geofencing capabilities for operations above 120 meters altitude across European Union member states. Industrial inspection providers must retrofit existing fleets with C2 link redundancy and remote identification broadcast modules to maintain airspace access. German and French energy utilities are prioritizing compliant platforms for offshore wind farm maintenance contracts, accelerating hardware refresh cycles.
Service-based fleet management contracts are displacing direct equipment purchases among North American infrastructure inspection firms. Engineering consultancies now contract flight-hour availability from specialized UAV operators rather than maintaining captive aircraft inventories. This preference shift concentrates capital risk with platform-as-a-service providers and compresses margins for hardware manufacturers dependent on unit sales.
Electric Unmanned Aerial Vehicle Market Segmentation
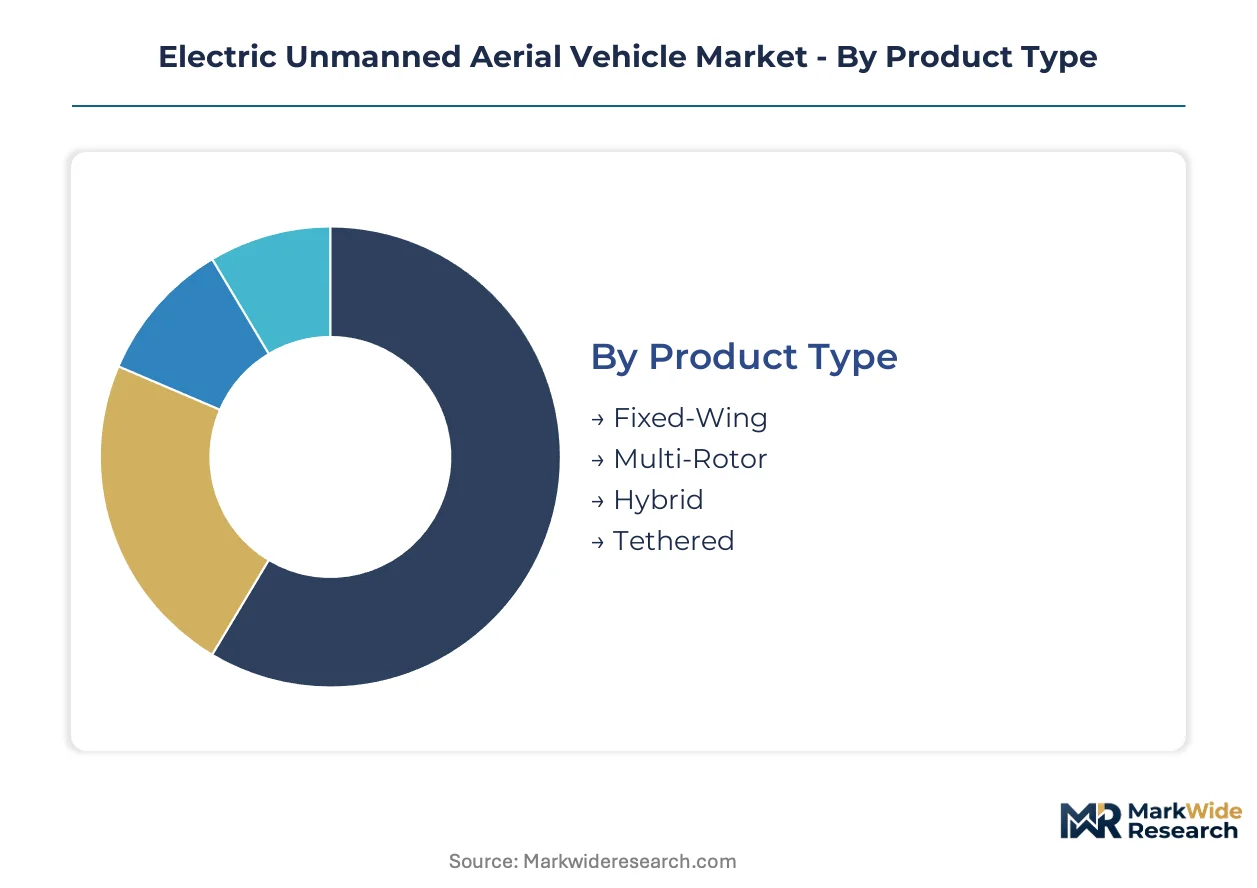
Platform architecture and powertrain choices determine operational economics across defense, agriculture, and logistics verticals. Segment boundaries are blurring as hybrid systems penetrate multi-rotor form factors and autonomous navigation becomes standard across price tiers.
Product Type:
Domestic demand in China and the United States absorbs most fixed-wing and multi-rotor production, while hybrid and tethered systems ship primarily to European energy utilities and Middle Eastern defense contractors.
- Fixed-Wing:Aerodynamic efficiency enables 2-6 hour flight durations with minimal energy consumption per kilometer. Agricultural cooperatives in Brazil and Australia deploy these platforms for thousand-hectare crop surveys where endurance outweighs vertical landing requirements.
- Multi-Rotor:Vertical takeoff capability eliminates runway infrastructure, reducing capital barriers for last-mile logistics operators. Shenzhen manufacturers ship 70% of global multi-rotor volume to North American and European consumer and prosumer segments.
- Hybrid:Combined battery-combustion powertrains extend mission range beyond 500 kilometers for offshore wind inspection contracts in the North Sea.
- Tethered:Continuous ground power supply enables indefinite hover for persistent surveillance at military installations and border monitoring stations.
Multi-rotor commands the established base. The steepest expansion runs through hybrid architectures.
Application:
Cost tier stratification separates commodity data collection from premium autonomous operations requiring detect-and-avoid certification.
- Agricultural Surveillance:Multispectral imaging identifies nitrogen stress, irrigation deficits, and pest infestations at 5-centimeter resolution. Brazilian soybean producers and Australian wheat belt operators are replacing manned Cessna surveys with electric UAV fleets.
- Infrastructure Inspection:High-resolution photogrammetry and thermal imaging detect corrosion, delamination, and conductor hotspots on transmission towers and bridge decks. German energy utilities mandate EASA U-space compliance for offshore wind farm maintenance contracts.
- Delivery Services:Urban air mobility pilots in Shenzhen and Dubai test blood sample and pharmaceutical transport within 10-kilometer radii.
- Environmental Monitoring:Atmospheric sensors and water quality probes track methane emissions and algal blooms in remote extraction and conservation zones.
Infrastructure inspection commands the established base. The steepest expansion trajectory runs through delivery services.
End User:
Customer type determines procurement sophistication, with agriculture and energy favoring fleet purchases while logistics and public safety migrate toward service contracts.
- Agriculture:Large-scale farming cooperatives in the US Midwest and Ukraine Black Earth region operate 50-200 unit fleets for seasonal crop monitoring and variable-rate input application.
- Energy:Transmission operators and renewable developers deploy fixed-wing platforms for corridor mapping and turbine blade inspection across Texas, Scandinavia, and coastal China.
- Logistics:E-commerce platforms and pharmaceutical distributors trial autonomous delivery networks in suburban Dallas and Shanghai Pudong.
- Public Safety:Fire departments and search-and-rescue units in California and Australia acquire thermal-equipped multi-rotor systems for wildfire perimeter mapping and victim location.
Energy commands the established base. Agriculture is gaining share fastest.
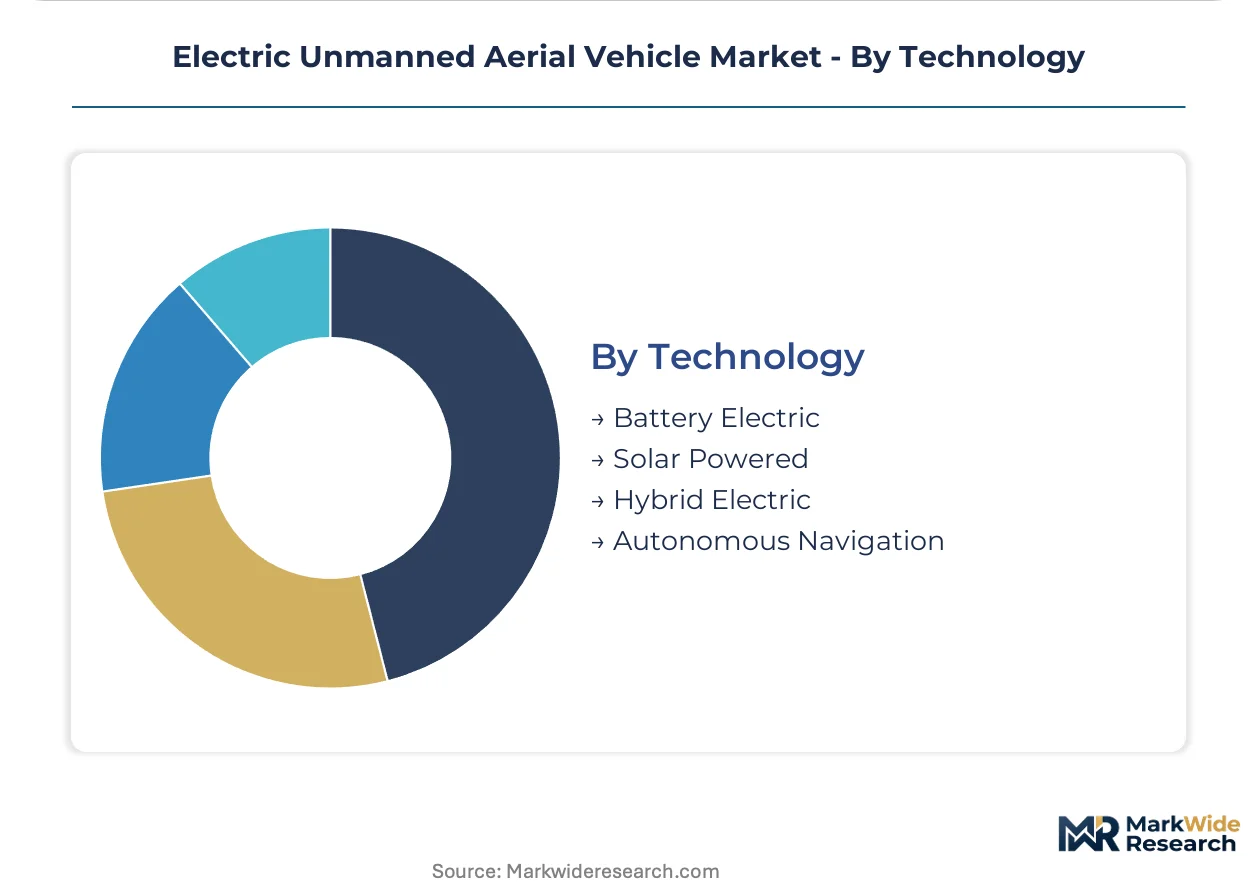
Technology:
Supply concentration in lithium-polymer cell manufacturing shapes cost structures and certification timelines across all powertrain categories.
- Battery Electric:Lithium-polymer and lithium-ion packs at 150-300 watt-hours per kilogram dominate commercial and consumer segments. Cell supply from CATL and BYD facilities in Fujian and Guangdong provinces determines pack pricing for global assemblers.
- Solar Powered:Gallium-arsenide and perovskite cell integration extends endurance for stratospheric pseudo-satellite platforms. Airbus Zephyr and BAE Systems PHASA-35 programs target months-long persistence for military communications relay.
- Hybrid Electric:Range-extender combustion generators address battery density limitations for 100-500 kilometer logistics missions. Regulatory frameworks in the United States and European Union impose distinct noise and emissions standards on hybrid operations.
- Autonomous Navigation:Detect-and-avoid algorithms and GNSS-denied positioning enable beyond-visual-line-of-sight approval. FAA and EASA certification timelines lag hardware readiness by 18-24 months.
Battery electric commands the established base. Autonomous navigation is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement agencies and precision agriculture cooperatives concentrate purchasing power across five national markets. Regulatory divergence between FAA, EASA, and CAAC frameworks fragments certification pathways. Manufacturing scale aggregates in Guangdong Province while application deployment spreads across temperate agricultural zones and urban logistics corridors.
United States
Defense contractors and infrastructure inspection firms drive fixed-wing and multi-rotor procurement. FAA Part 107 remote pilot certification standardizes commercial access while beyond-visual-line-of-sight waivers remain concentrated in Texas and California energy corridors. Dallas-Fort Worth anchors pharmaceutical delivery pilot programs with suburban air mobility trials.
China
Agricultural surveillance fleets and urban air mobility operators absorb domestic production volume. CAAC certification pathways for autonomous navigation accelerate deployment timelines in designated low-altitude zones. Shenzhen manufacturing clusters in Guangdong Province integrate battery cell production with airframe assembly for global export.
Germany
Offshore wind farm operators and transmission utilities mandate EASA U-space compliance for inspection contracts. The country's national aviation regulator enforces networked identification and geofencing above 120 meters altitude. Hamburg and Bremerhaven ports concentrate maritime logistics drone development for North Sea operations.
Brazil
Soybean producers and sugarcane cooperatives replace manned Cessna surveys with electric UAV fleets for thousand-hectare crop mapping. ANAC regulatory frameworks adapt FAA precedents for agricultural exemption categories. São Paulo state anchors precision farming equipment distribution networks serving the Cerrado and Pantanal regions.
Australia
Wheat belt operators and mining surveyors deploy fixed-wing platforms for remote sensing across vast pastoral leases. CASA maintains distinct remote operator certificate requirements aligned with agricultural seasonal demand cycles. Queensland and Western Australia concentrate thermal-equipped multi-rotor acquisition for wildfire perimeter mapping.
Electric Unmanned Aerial Vehicle Market Competitive Landscape
Player mix skews toward vertically integrated hardware manufacturers and defense-tier system integrators. Shenzhen-based producers dominate consumer and prosumer volume segments through concentrated component sourcing. Two strategic archetypes define competitive positioning: scale-driven platform manufacturers leveraging manufacturing cluster proximity, and R&D-intensive defense contractors anchoring autonomous navigation development. Capacity expansion in battery pack assembly and strategic partnerships for detect-and-avoid certification represent dominant competitive moves.
Within the defense-tier segment, Northrop Grumman Corporation and General Atomics Aeronautical Systems occupy positions anchored in sustained government R&D contracting. SZ DJI Technology Co., Ltd. exemplifies the scale-driven archetype through its Shenzhen manufacturing base integration. These three entities represent the structural poles of competitive positioning—defense-grade fixed-wing programs, hybrid-electric endurance platforms, and consumer-prosumer multi-rotor volume—without overlapping segment focus.
| Leading Market Players |
|---|
| SZ DJI Technology Co., Ltd. |
| Northrop Grumman Corporation |
| General Atomics Aeronautical Systems |
| AeroVironment Inc. |
| Lockheed Martin Corporation |
| Teledyne FLIR LLC |
| Parrot |
| EHang |
| Israel Aerospace Industries Ltd. |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day battery pack lead times from Guangdong Province suppliers concentrate pricing power with vertically integrated airframe manufacturers, while spot-market lithium carbonate volatility feeds directly into contract renegotiation clauses for tier-two assemblers.
Pricing Analysis
Cost-plus contracts with quarterly lithium carbonate indexation dominate procurement between battery pack assemblers and agricultural fleet operators. Three-tier pricing structure across FAA-certified, CE-marked, and uncertified equipment tiers separates premium autonomous navigation platforms from standard visual-line-of-sight units and economy-grade consumer imports. Pricing pressure stems from CATL and BYD capacity additions in Fujian province compressing cell margins. Agricultural cooperatives in Brazil and Australia exhibit highest price sensitivity, while defense contractors in the United States and Middle East accept premium positioning for detect-and-avoid certification.
Supply Chain Analysis
Container availability on the Shenzhen-Los Angeles trade lane shapes inbound logistics costs for North American distributors, with port congestion at Long Beach periodically extending delivery windows for multi-rotor platforms. Manufacturing concentrates in China, South Korea, and Japan for lithium-polymer cells, with Germany and the United States hosting final assembly for defense-grade fixed-wing programs. Raw material dependencies span cobalt from the Democratic Republic of Congo, lithium from Chile and Australia, and rare earth magnets from China. Single-source vulnerability in ceramic electrolyte substrates for solid-state prototypes threatens next-generation certification timelines. Distribution runs through direct OEM channels for defense and energy customers, with agricultural and logistics segments served by regional equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of FAA-certified detect-and-avoid engineering talent constrains platform development timelines, amplifying returns for operators securing autonomous navigation approvals ahead of low-altitude traffic management deployment.
For Market Incumbents: Shield market position by securing captive lithium-polymer cell supply through backward integration into cathode material partnerships in Hunan province, while accelerating EASA U-space compliance investments to preempt European infrastructure inspection contract losses to Shenzhen-based competitors. Regulatory fragmentation between FAA, EASA, and CAAC frameworks threatens margin compression for non-compliant legacy fleets. For New Entrants and Emerging Players: Cold-chain pharmaceutical delivery networks in sub-Saharan Africa offer under-served rural healthcare access gaps where road infrastructure constraints create natural demand for electric UAV logistics. Target Kenyan and Nigerian last-mile distribution partnerships with Ministries of Health, leveraging temperature-validated payload compartments as the primary go-to-market differentiator against commodity surveying equipment. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because autonomous navigation certification timelines lag hardware readiness by eighteen-to-twenty-four months across FAA and EASA jurisdictions, creating acquisition windows for detect-and-avoid software specialists ahead of type approval standardization. Monitor CAAC low-altitude corridor designations in Shenzhen and Shanghai as the signal for Western regulatory acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Navigation Certification | Secures beyond-visual-line-of-sight operational permissions ahead of FAA and EASA standardization timelines. |
| Backward Integration into Cell Supply | Captures cathode material cost stability through partnerships with Hunan and Sichuan province refiners. |
| Platform-as-a-Service Transition | Concentrates capital risk with specialized operators while compressing hardware manufacturer margins. |
| EASA U-space Compliance Investment | Maintains airspace access for European offshore wind inspection contracts above 120 meters altitude. |
| Solid-state Battery R&D Partnership | Eliminates hybrid powertrain complexity through silicon-anode and ceramic electrolyte convergence. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with UAV fleet operators, FAA Part 107 certified remote pilots, agricultural cooperative procurement managers, energy utility inspection coordinators, and battery pack assembly engineers; and secondary validation through FAA waiver filings, EASA U-space implementation guidance, CAAC low-altitude corridor designations, customs trade data for lithium-polymer cell shipments, and SEC filings from defense-tier system integrators. Bottom-up unit shipment estimates from Shenzhen manufacturing clusters were triangulated against top-down addressable market calculations for precision agriculture and infrastructure inspection verticals.
Across the projection horizon, the analytical framework modeled platform architecture, powertrain technology, application vertical, and end-user procurement sophistication as primary segmentation dimensions. CAGRs were derived from regression analysis of historical shipment data against regulatory milestone timing and battery energy density improvement curves. Forecast inputs incorporated EASA networked identification mandates, solid-state battery commercialization trajectories, and autonomous navigation certification queue lengths.
Forecasts assume regulatory continuity in FAA Part 107 waiver frameworks, EASA U-space altitude thresholds, and CAAC designated low-altitude zones; material policy shifts in detect-and-avoid approval timelines or battery safety standards would require re-modeling. Recalibration cycles align with material shifts in certification queue lengths, cathode material pricing volatility, and low-altitude traffic management deployment milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Small UAV Market
UAV
Europe Small UAV Market
UAV
Military UAV Sensor Market
UAV
Global Multirotor UAV Market
UAV
Drone-Based Consulting Services Market
UAV
Drone Motors Market
UAV
Drones Market
UAV
Europe Drones Market
UAV
Enterprise Drone Management Solutions Market
UAV
Asia Pacific Small UAV Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Ultra-Long Endurance Drone Market
UAV
Global Target Drone Market
UAV
Global Renewable Drones Market
UAV
Drone-In-A-Box Market
UAV
Middle-East and Africa Small UAV Market