
 Global Target Drone Market | 2026-2036
Global Target Drone Market Size, Share, and Industry Trends Forecast 2026-2036
Global Target Drone Market Outlook
The EU Green Deal is expanding the addressable market for low-emission target drones as European defense ministries embed carbon accounting into procurement criteria. General Atomics Aeronautical Systems leverages its vertical integration across turboprop and jet-powered target platforms to sustain long-term contracts with the US Navy and Marine Corps. Kratos Defense & Security Solutions differentiates through high-subsonic and supersonic aerial target systems that replicate advanced threat profiles for missile defense testing.
A target drone is an unmanned aerial vehicle designed specifically to simulate enemy aircraft, missiles, or swarming threats during weapons testing and combat training, typically constructed from lightweight composites with radar cross-section enhancement and expendable recovery systems. Fixed-wing configurations dominate procurement volumes due to their endurance and speed envelope, while rotary-wing variants capture growing interest for helicopter threat simulation and urban warfare training scenarios. Autonomous technology segments command premium positioning as militaries prioritize reduced operator burden and realistic swarm behaviors.
The US FAA regulates airspace integration for target drone operations through Part 107 waivers and Certificate of Authorization processes, while the EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems deployed in European training ranges. China's MIIT enforces GB standards on radio frequency emissions and flight control architectures for domestically manufactured platforms. Stakeholders must monitor divergence between NATO interoperability standards and national sovereignty requirements for encrypted command links.
Market Dynamics
The Pentagon's Replicator initiative and parallel NATO procurement programs are compressing development cycles for attritable target systems, forcing suppliers to prioritize rapid fielding over multi-year platform refinement cycles.
Growth Catalysts
- Live-fire training mandates:Defense ministries across NATO member states mandate annual live-fire exercises against realistic aerial targets, sustaining replacement demand for expendable systems.
- EU Green Deal procurement criteria:European defense ministries now embed carbon accounting into acquisition frameworks, advantaging electric-propulsion target drone manufacturers.
- Autonomous swarm replication:Militaries require target systems that replicate coordinated threat behaviors, pulling investment toward AI-enabled flight control architectures.
Market Restraints
- Lithium-ion supply concentration:Battery cell production for electric target drones concentrates in East Asian manufacturing clusters, exposing European and North American assemblers to input bottlenecks.
- FAA airspace integration friction:Certificate of Authorization timelines for beyond-visual-line-of-sight operations extend development schedules and constrain rapid deployment capabilities.
- Cross-platform interoperability gaps:Divergent encrypted command-link standards between national defense forces fragment procurement and limit economies of scale.
Strategic Opportunities
- Urban warfare training expansion:Rotary-wing target configurations for helicopter threat simulation remain underdeveloped relative to fixed-wing platforms, opening white space for specialized entrants.
- Recyclable airframe materials:Bio-based composites and thermoplastic recycling processes align with EU circular economy directives while reducing per-unit material costs.
- Dual-use range services:Commercial drone testing facilities in Germany and the United Kingdom seek military-grade target systems for civilian certification programs.
Industry Challenges
- Autonomous systems engineering talent:Shortage of flight control software specialists with military security clearances constrains development velocity for classified programs.
- NATO STANAG compliance timelines:Interoperability certification processes extend 18-24 months, delaying revenue recognition for new platform introductions.
- Legacy radar cross-section calibration:Integration with existing threat simulation databases requires costly re-engineering of signature management subsystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Target Drone Market |
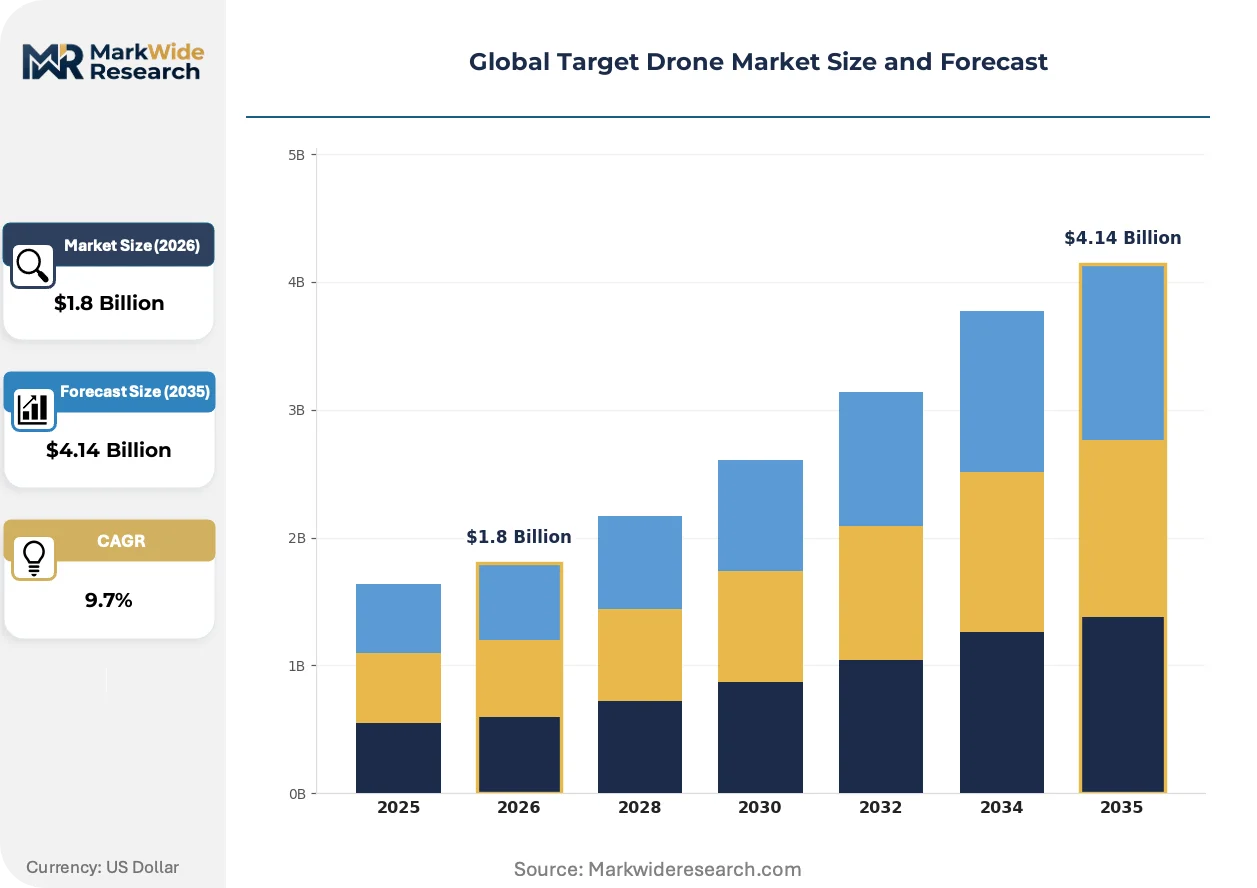
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Rotary-Wing, Hybrid, Supertitan End User: Military, Defense Contractors, Law Enforcement, Aviation Safety Deployment Model: Ground-Based, Airborne, Sea-Based, Mobile Technology: FPV, GPS, Autonomous, Remote-Controlled |
| Companies Covered | General Atomics Aeronautical Systems, Skydio, AeroVironment, JOUAV, Vantage Robotics, Kratos Defense & Security Solutions, Insitu, ChinaMoneypro UAV, Northrop Grumman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Target Drone Market Strategic Shifts
Modular payload architectures are compressing platform development timelines while regulatory pressure on emissions and algorithmic transparency is redirecting R&D investment toward electric propulsion and explainable autonomy systems.
Digital twin-based flight simulation is unifying pre-flight validation with real-time performance monitoring. The US Navy and Marine Corps now mandate virtual mission rehearsal before live-fire exercises, collapsing traditional separation between development and operational testing. This convergence is compressing qualification timelines and enabling iterative hardware refinement without full prototype rebuilds.
The EU AI Act imposes algorithmic transparency requirements on autonomous targeting systems deployed in European training ranges. Manufacturers must now document decision pathways for threat-recognition and evasion behaviors, adding compliance engineering overhead. French and German defense procurement offices have begun requiring AI audit trails as standard contract terms.
Defense buyers are consolidating orders through multi-year framework agreements rather than annual competitive tenders. The Army Futures Command and similar bodies in the United Kingdom and Australia now negotiate five-year supply commitments with pre-qualified vendors, displacing spot purchasing. This concentration favors established suppliers with proven manufacturing scale and security infrastructure.
Global Target Drone Market Segmentation
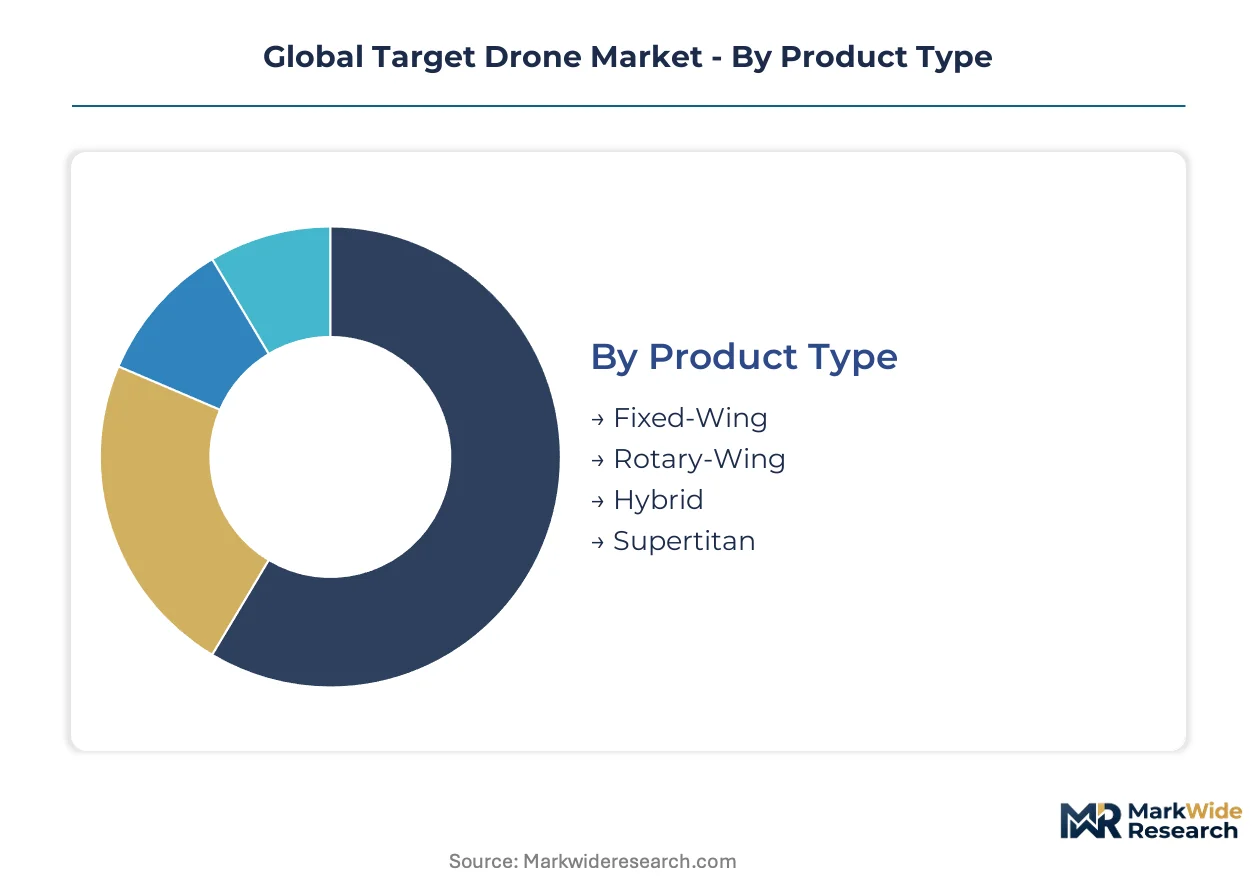
Segmentation in the target drone market reveals distinct procurement patterns across propulsion architectures, operator categories, and control modalities. Supply-side specialization concentrates around fixed-wing and autonomous configurations, while emerging demand pulls investment toward rotary-wing and hybrid platforms.
Product Type:
Manufacturing capacity clusters heavily around fixed-wing configurations, with composite airframe suppliers in the United States and Germany dominating production tooling for high-endurance platforms.
- Fixed-Wing:These platforms utilize carbon-fiber monocoque structures with swept-wing or delta configurations to achieve sustained high-subsonic speeds. The Pentagon's Replicator initiative and parallel NATO live-fire programs concentrate replacement orders here, though lithium-ion cell sourcing from East Asian suppliers creates input bottlenecks for electric variants.
- Rotary-Wing:Helicopter threat simulation demands multi-rotor or single-rotor architectures with collective pitch control. Urban warfare training expansion in the United Kingdom and Australia is pulling procurement toward these systems, where maneuverability in confined airspace outweighs endurance limitations.
- Hybrid:Tilt-rotor or tail-sitter configurations combine vertical takeoff with fixed-wing cruise efficiency. Defense contractors in Israel and South Korea are fielding limited prototypes for shipboard launch scenarios.
- Supertitan:Large-format target systems replicate heavy bomber or transport aircraft radar signatures. The US Navy maintains sole-source contracts for these specialized platforms due to signature calibration complexity.
Fixed-wing configurations absorb the bulk of installed capacity; rotary-wing platforms are expanding most quickly.
End User:
Customer concentration follows defense procurement centralization, with multi-year framework agreements displacing spot purchasing across major NATO ministries.
- Military:National armed forces operate the majority of target drone fleets through dedicated test and evaluation squadrons. The Army Futures Command and United States Marine Corps prioritize attritable systems with rapid fielding cycles over platform longevity.
- Defense Contractors:Prime systems integrators maintain captive target fleets for missile development and validation. Lockheed Martin and Raytheon subsidiaries in the United States operate private airspace corridors that bypass FAA Certificate of Authorization timelines.
- Law Enforcement:Counter-UAS training programs in Germany and France utilize commercial-grade target systems for interceptor drone certification. Procurement volumes remain limited by budget constraints relative to military end users.
- Aviation Safety:Airport authorities and civil aviation regulators deploy bird-strike simulation drones. The United Kingdom's CAA mandates regular testing for wildlife hazard management at major hubs including Heathrow and Gatwick.
Military end users command the dominant share of procurement volume; defense contractors are climbing the fastest as primes internalize testing capabilities.
Deployment Model:
Platform mobility requirements dictate supply chain configuration, with ground-based systems leveraging commercial automotive components while sea-based variants demand marine-grade environmental sealing.
- Ground-Based:Pneumatic or rail launch systems from fixed installations dominate continental training ranges. The US Army's White Sands Missile Range and Germany's Todendorf facility operate permanent launch infrastructure with integrated tracking radar.
- Airborne:Mothership-deployed targets enable beyond-line-of-sight testing without ground station investment. The US Navy's GQM-163 Coyote launches from F/A-18 aircraft for supersonic sea-skimming threat simulation.
- Sea-Based:Vertical launch systems from destroyer decks require salt-spray corrosion resistance and compact stowage. Royal Australian Navy trials in Jervis Bay are validating containerized launch modules.
- Mobile:Truck-mounted or trailer-based systems support expeditionary training. French forces in Djibouti deploy rapid-relocation target systems to avoid predictable launch signatures.
Ground-based deployment retains the largest installed base; sea-based configurations are gaining share fastest as Pacific theater exercises intensify.
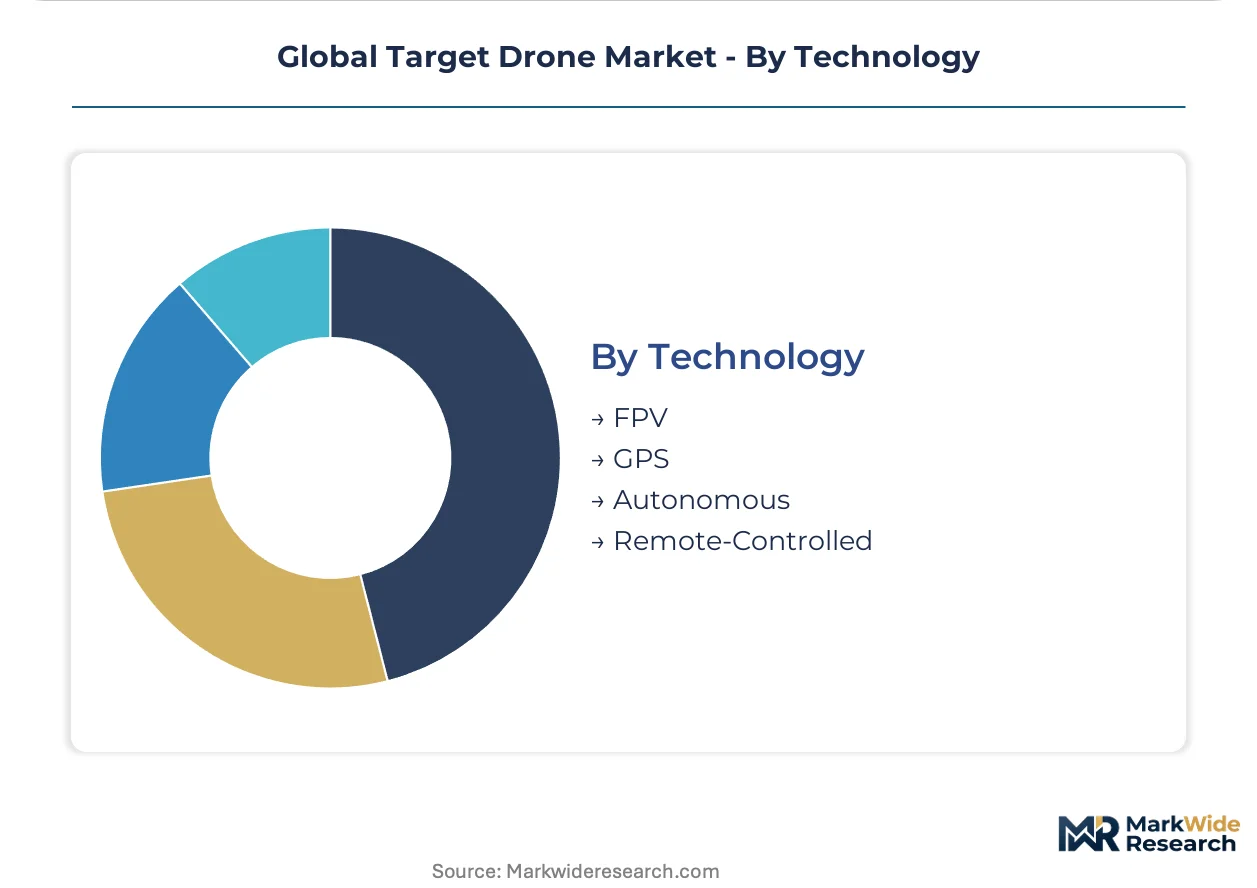
Technology:
Control architecture selection determines regulatory compliance burden, with autonomous systems facing EU AI Act algorithmic transparency requirements that remote-controlled platforms avoid.
- FPV:First-person-view systems immerse operators in real-time video feeds for manual threat replication. The US Marine Corps favors these for low-cost swarm training where individual target behavior customization outweighs automation benefits.
- GPS:Waypoint navigation enables repeatable flight profiles for missile seeker calibration. Pre-programmed routes at the US Navy's Point Mugu Sea Range support standardized threat presentation across test events.
- Autonomous:AI-enabled flight control replicates coordinated evasion behaviors and adaptive threat patterns. French and German procurement offices now require AI audit trails as standard contract terms under EU AI Act implementation.
- Remote-Controlled:Direct radio link operation persists for basic target presentation where electromagnetic spectrum congestion is manageable. Legacy systems at United Kingdom ranges continue operation under grandfathered frequency allocations.
Remote-controlled technology retains the broadest installed base; autonomous systems are expanding most quickly as swarm replication requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors the global target drone ecosystem through its concentration of defense primes and naval aviation test infrastructure. The metropolitan corridor hosts integrated development facilities that span composite airframe fabrication to autonomous flight software validation. This geographic clustering shapes procurement patterns across NATO training ranges and Pacific theater exercises.
United States
The Pentagon's Replicator initiative and Army Futures Command compress development cycles for attritable target systems. The FAA regulates airspace integration through Part 107 waivers and Certificate of Authorization processes that extend deployment timelines. White Sands Missile Range in New Mexico operates permanent launch infrastructure with integrated tracking radar for continental test programs.
Germany
The EU Green Deal embeds carbon accounting into defense procurement frameworks, advantaging electric-propulsion manufacturers. Todendorf facility in Schleswig-Holstein maintains ground-based launch systems for NATO live-fire exercises. Stuttgart's industrial corridor concentrates composite airframe suppliers serving both military and dual-use range services.
United Kingdom
The Civil Aviation Authority mandates bird-strike simulation testing at Heathrow and Gatwick airports, pulling commercial demand toward military-grade target systems. Point Mugu Sea Range protocols influence Royal Navy procurement for maritime threat replication. Salisbury Plain training areas host rotary-wing target exercises for urban warfare preparation.
Australia
Pacific theater exercises intensify demand for sea-based launch configurations from Royal Australian Navy destroyers. Jervis Bay trials validate containerized launch modules for expeditionary deployment. Queensland-based contractors supply rapid-relocation systems to French forces operating in Djibouti through regional logistics hubs.
France
French and German procurement offices require AI audit trails as standard contract terms under EU AI Act implementation. Auvergne-Rhône-Alpes hosts specialists in autonomous swarm replication for missile defense testing. French forces deploy mobile target systems across Sahel operations to avoid predictable launch signatures.
Global Target Drone Market Competitive Environment
The competitive structure tilts toward vertically integrated defense primes with captive airspace corridors. Tiered specialization separates high-subsonic platform specialists from attritable swarm system suppliers. Two archetypes dominate: established aerospace conglomerates with multi-decade Navy contracts, and mid-scale autonomy firms serving Marine Corps rapid-fielding requirements. Competitive moves concentrate on backward integration into lithium-ion cell sourcing and strategic partnerships with composite recyclers.
Among San Diego-based defense contractors, General Atomics Aeronautical Systems and Kratos Defense & Security Solutions exemplify contrasting scale archetypes. General Atomics occupies a position spanning turboprop through jet-powered target platforms. Kratos sits within the high-speed threat replication tier. AeroVironment represents the attritable systems vector with Marine Corps alignment. Insitu anchors the airborne launch configuration segment through naval aviation integration.
| Leading Market Players |
|---|
| General Atomics Aeronautical Systems |
| Skydio |
| AeroVironment |
| JOUAV |
| Vantage Robotics |
| Kratos Defense & Security Solutions |
| Insitu |
| ChinaMoneypro UAV |
| Northrop Grumman |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NATO STANAG-compliant platforms and non-certified commercial systems manifests in both unit economics and sourcing complexity. Premium-tier suppliers command pricing power through captive airspace corridors and multi-year framework agreements, while commodity-grade assemblers face margin compression from lithium-ion cell import dependencies and FAA certification delays.
Pricing Analysis
Value-based pricing anchors on threat-replication fidelity and mission-completion rates rather than hardware costs alone. Three-tier pricing structure across premium, standard, and economy levels separates signature-calibrated systems for missile defense testing from attritable swarm trainers and basic radar-reflector drones. Cost compression in the economy tier is intensifying because East Asian battery suppliers concentrate cell production, forcing North American assemblers to absorb tariff exposure or surrender margin. Defense contractors exhibit the lowest price sensitivity due to captive testing budgets, while law enforcement agencies face hard procurement ceilings that push demand toward refurbished or leased platforms.
Supply Chain Analysis
Domestic-content mandates in the US Buy American Act and EU defense procurement directives are reshaping sourcing patterns for composite airframes and flight control electronics. Manufacturing gravity centers on the United States, Germany, and Israel for carbon-fiber monocoque fabrication, while lithium-ion cell production draws from China, South Korea, and Japan. Critical dependencies span rare-earth magnets for electric motors, gallium nitride semiconductors for radar cross-section management, and thermoplastic resin systems for recyclable airframes. Single-source vulnerability in East Asian battery supply creates exposure to export restriction shocks. Distribution runs through prime contractor integration channels rather than open-market procurement, with the Army Futures Command and NATO procurement offices negotiating direct multi-year offtake agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vertically integrated primes with captive security infrastructure and proven NATO interoperability, as FAA airspace friction and lithium-ion supply concentration force subscale competitors toward exit or acquisition.
For Market Incumbents: To counter autonomous systems engineering talent shortages with military security clearances, General Atomics and Kratos Defense should deepen backward integration into lithium-ion cell sourcing through joint ventures with South Korean suppliers, while accelerating certification investments for EU AI Act algorithmic transparency requirements to preempt framework agreement displacement by European primes. For New Entrants and Emerging Players: A mid-tier pricing gap between $50,000-per-unit attritable swarms and $2 million supersonic threat replicators creates entry space for rotary-wing specialists targeting urban warfare training expansion in the United Kingdom and Australia. The most penetrable segment sits with helicopter threat simulation for confined airspace exercises, where maneuverability requirements outstrip endurance specifications and incumbent fixed-wing tooling offers limited adaptation leverage. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale autonomy firms possessing Marine Corps rapid-fielding relationships and modular payload architectures, given Pentagon Replicator initiative acceleration compressing procurement cycles toward software-iterative suppliers. Acquisition targets should demonstrate proven FAA Part 107 waiver histories and established composite recycling partnerships aligning with EU circular economy directives. The signal to watch is NATO STANAG certification backlog clearance rates as a proxy for revenue recognition velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Supply | Captive lithium-ion sourcing insulates North American assemblers from East Asian export restrictions and tariff exposure. |
| EU AI Act Compliance Certification | Algorithmic audit trail capabilities unlock French and German defense procurement framework agreements. |
| Rotary-Wing Platform Development | Helicopter threat simulation addresses underdeveloped urban warfare training demand in Commonwealth forces. |
| Recyclable Airframe Material Partnerships | Thermoplastic recycling processes align with EU Green Deal circular economy directives while reducing per-unit material costs. |
| Multi-Year Framework Agreement Negotiation | Five-year supply commitments with Army Futures Command displace spot purchasing and lock out emerging competitors. |
Study Parameters
Defense procurement databases, FAA Certificate of Authorization filings, and EU tender documentation formed the secondary backbone, supplemented by primary interviews with flight control software engineers, defense procurement officers at NATO ministries, composite airframe plant managers, and lithium-ion supply chain specialists. Bottom-up triangulation against top-down military budget allocation analysis validated volume estimates across propulsion architectures and control modalities.
Historical trendline analysis of Pentagon Replicator initiative order flows and NATO live-fire exercise frequencies established baseline demand patterns across the projection horizon. The analytical framework modeled segmentation across fixed-wing, rotary-wing, and hybrid configurations; autonomous, GPS, and FPV control technologies; and ground-based, sea-based, and airborne deployment models. CAGRs derived from defense budget growth trajectories and attrition-rate assumptions for expendable target systems, with electric-propulsion adoption curves calibrated against EU Green Deal procurement criteria implementation timelines.
Inputs from defense ministry procurement portals and FAA regulatory filing systems were available through the study window; gaps in classified program expenditure data introduce uncertainty bands around autonomous systems segment sizing. Forecasts reflect assumptions regarding NATO interoperability standardization timelines and lithium-ion supply chain stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Europe Small UAV Market
UAV
Home Security Drone Market
UAV
Counter-UAS Market
UAV
Europe Drone Services Market
UAV
Unmanned Aerial Vehicle Fuel Cell Market
UAV
Global Aerial Imaging Market
UAV
Tethered Drones Market
UAV
Commercial Drone Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Drone Delivery Services Market
UAV
Ultra Micro Drone Market
UAV
Solar-Powered UAV Market
UAV
Nano Drones Market
UAV
Micro Drone Market
UAV
Drone Roof Inspection Market
UAV
Portable Drone Market