
 Europe Small UAV Market | 2026-2036
Europe Small UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Small UAV Market Foresight
A shortage of certified UAV pilots and flight-systems engineers is unwinding delivery timelines for European defense contracts. Airbus leverages its integrated aerospace supply chain to sustain large-scale tactical UAV production. Parrot Drones SAS competes in the nano-drone segment through civilian-grade imaging platforms. Quantum-Systems GmbH specializes in vertical-takeoff hybrid designs that occupy the gap between fixed-wing endurance and rotary-wing flexibility.
Small unmanned aerial vehicles in Europe encompass platforms under 150 kilograms maximum takeoff weight, typically powered by electric motors or small combustion engines with operational ranges below 100 kilometers and endurance under eight hours, designed for intelligence collection, precision agriculture, and critical infrastructure monitoring. Rotary-wing systems dominate the agricultural monitoring application due to hover stability and payload versatility for multispectral sensors. Fixed-wing configurations lead in infrastructure inspection where extended loiter time over linear assets such as pipelines and transmission corridors maximizes coverage per sortie. AI integration represents the fastest-expanding technology segment as obstacle-avoidance algorithms and autonomous navigation reduce operator burden and enable beyond-visual-line-of-sight approvals.
EASA implements EU 2019/947 and the forthcoming U-space regulatory framework to standardize drone operations across member states, while national regulators such as Germany's Luftfahrt-Bundesamt enforce type-certification standards that shape product development roadmaps. CE marking requirements under the EU Machinery Directive constrain market access for non-compliant hardware imports. Stakeholders must monitor the interplay between EASA's operational harmonization and member-state military procurement sovereignty as dual-use classification determines whether civilian or defense acquisition rules apply.
Market Dynamics
EASA's U-space regulatory framework is compressing operational approval timelines while NATO defense procurement accelerates platform standardization across member states. This dual regulatory-military pressure is restructuring supplier hierarchies and certification priorities.
Growth Catalysts
- Beyond-Visual-Line-of-Sight approvals:EASA's operational authorization under EU 2019/947 is unlocking commercial inspection contracts for linear infrastructure operators. Rail and pipeline utilities in Germany and France are expanding fleet procurement.
- Vertical-takeoff hybrid architectures:VTOL designs combining fixed-wing endurance with rotary-wing landing flexibility are capturing agricultural monitoring contracts previously split between two platform categories.
- Dual-use procurement sovereignty:Article 346 TFEU exemptions allow member states to fast-track tactical UAV acquisitions outside standard EU defense procurement rules, accelerating domestic manufacturing scale-up.
Market Restraints
- Lithium-polymer battery supply concentration:Cell production for sub-150kg platforms depends on Asian suppliers, exposing European assemblers to input cost volatility and customs processing delays.
- Type-certification timeline friction:Luftfahrt-Bundesamt's design approval process for autonomous navigation systems extends product launch windows by 18-24 months versus non-certified commercial alternatives.
- Manned aviation substitution ceiling:Regulatory altitude restrictions and airspace segregation requirements limit UAV deployment in dense terminal control areas around Frankfurt, Paris, and London hubs.
Strategic Opportunities
- Poland and Baltic states:Eastern flank NATO members are expanding border surveillance and artillery spotting programs, creating demand for tactical platforms with encrypted datalinks and all-weather optics.
- AI-act compliance services:High-risk system classification under the EU AI Act is generating advisory revenue streams for firms assisting manufacturers with conformity assessment documentation.
- Direct-to-operator digital distribution:Bypassing traditional defense integrators, manufacturers are selling certified platforms through online configurators to municipal emergency services and agricultural cooperatives.
Industry Challenges
- Certified flight-systems engineering scarcity:EASA Part-66 licensed avionics specialists with UAV-specific experience command premium compensation, inflating R&D overhead for mid-tier manufacturers.
- Legacy air traffic management integration:U-space service provider interfaces require software architecture redesigns that delay product roadmaps for platforms targeting controlled airspace operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Small UAV Market |
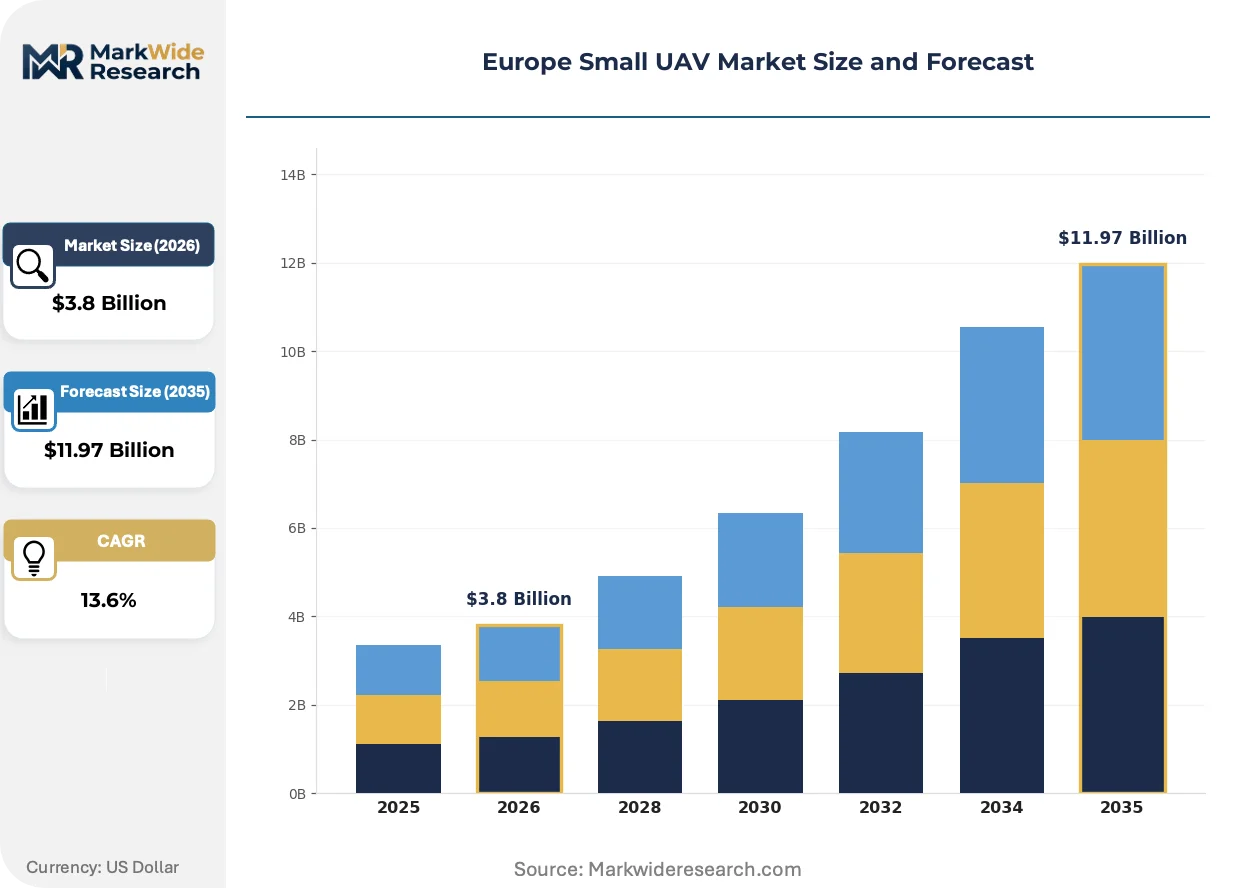
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Wing, Rotary Wing, Hybrid, Nano Drones, Tactical UAVs Technology: Autonomous Navigation, Remote Control, FPV Systems, AI Integration, Obstacle Avoidance Application: Surveillance, Agricultural Monitoring, Infrastructure Inspection, Environmental Research, Search & Rescue End User: Defense Forces, Agricultural Enterprises, Utility Providers, Scientific Institutions |
| Companies Covered | Airbus, BAE Systems, Leonardo S.p.A., Thales, SAAB, Parrot Drones SAS, Microdrones GmbH, Quantum-Systems GmbH, DELAIR SAS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Small UAV Market Shifts & Advancements
Autonomous navigation architectures and regulatory harmonization are compressing the gap between experimental prototypes and certifiable production platforms. Three developments are restructuring competitive positioning.
AI-powered obstacle-avoidance systems with embedded neural inference engines are supplanting rule-based path-planning algorithms in platforms targeting beyond-visual-line-of-sight operations. Agricultural spraying contractors in Spain and Italy are prioritizing these sensor packages to reduce insurance premiums and operator certification burdens. The shift is compressing margins for legacy flight-control suppliers unable to integrate machine-learning stacks.
EU 2019/947 and the forthcoming U-space Implementing Regulation are mandating remote identification and geofencing capabilities as baseline airworthiness requirements. Hardware manufacturers must redesign avionics bays to accommodate broadcast modules and real-time kinematic positioning receivers. Civilian logistics operators in the Netherlands and Denmark are advancing compliance roadmaps faster than defense procurement offices, creating a temporary capability gap.
Platform-as-a-service contracting is displacing capital purchase agreements for infrastructure inspection fleets. Transmission grid operators in Germany and Austria are unbundling hardware ownership from flight-hour guarantees, transferring airframe risk to OEM balance sheets. This preference shift favors vertically integrated manufacturers with captive maintenance networks over component assemblers dependent on third-party service partnerships.
Europe Small UAV Market Segmentation
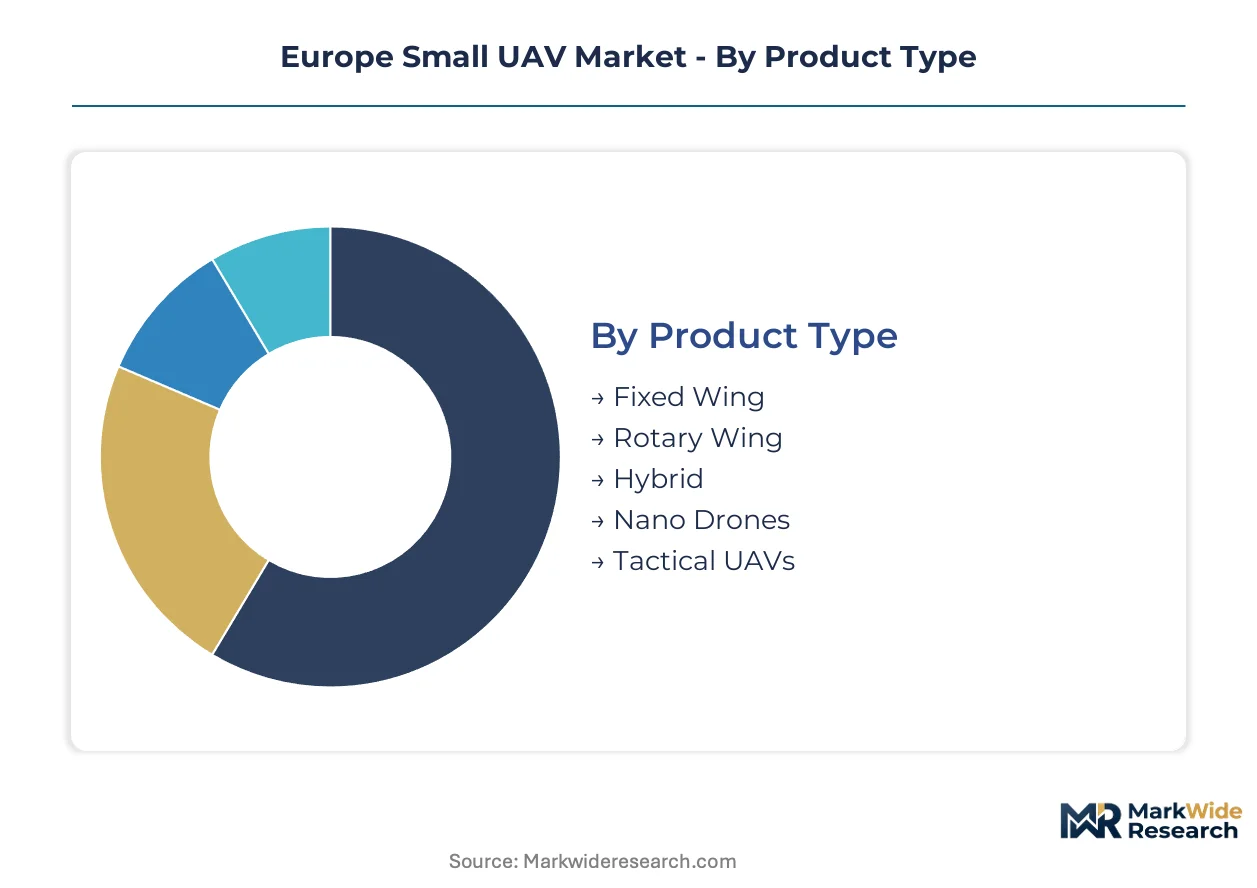
Segmentation in the European small UAV market reveals how procurement sovereignty and regulatory harmonization create divergent commercial pathways. Platform specifications and operational authorizations vary sharply between defense-led member states and civilian-commercial clusters.
Product Type:
German and French manufacturers dominate fixed-wing and tactical exports, while rotary-wing and nano platforms serve more localized agricultural and municipal demand across the region.
- Fixed Wing:Electric and combustion-powered designs with extended loiter capability serve linear infrastructure inspection across German transmission corridors and French pipeline networks. Luftfahrt-Bundesamt type-certification timelines stretch 18-24 months for autonomous variants, compressing margins for non-vertically integrated assemblers.
- Rotary Wing:Multirotor architectures with hover stability carry multispectral sensors for precision agriculture in Spain and Italy. EASA EU 2019/947 operational authorizations for beyond-visual-line-of-sight flights are unlocking fleet procurement from agricultural cooperatives.
- Hybrid:VTOL configurations combining fixed-wing endurance with rotary landing flexibility occupy the gap between endurance and access.
- Nano Drones:Sub-250g platforms evade stringent certification requirements for close-quarters inspection and confined-space operations.
- Tactical UAVs:Article 346 TFEU exemptions allow NATO members to fast-track acquisitions outside standard EU defense procurement rules.
Fixed Wing commands the established base. The steepest expansion runs through Hybrid designs capturing agricultural contracts previously split between two platform categories.
Technology:
Cost tiers separate premium autonomous stacks from commodity remote-control systems, with AI integration commanding R&D premiums that reshape supplier hierarchies.
- Autonomous Navigation:GPS-denied positioning and waypoint autonomy enable beyond-visual-line-of-sight operations under EASA frameworks. Polish and Baltic defense programs prioritize encrypted datalinks and all-weather navigation for artillery spotting missions.
- AI Integration:Embedded neural inference engines for real-time decision-making attract premium positioning from agricultural spraying contractors in Spain and Italy seeking insurance reductions.
- Remote Control:Direct radio-link operation within visual line of sight dominates low-cost municipal and training applications.
- FPV Systems:First-person-view immersion supports precision maneuvering in complex environments for search and rescue units.
- Obstacle Avoidance:Sensor fusion architectures using lidar and computer vision reduce operator burden in cluttered airspace.
Remote Control retains volume leadership in unit terms. AI Integration is climbing the fastest as high-risk system classification under the EU AI Act generates conformity assessment revenue streams.
Application:
Maturity curves diverge: surveillance and infrastructure inspection operate under established regulatory frameworks while environmental research and search and rescue navigate emergent operational approval pathways.
- Surveillance:Border monitoring and perimeter security deployments leverage encrypted datalinks and thermal optics. Eastern flank NATO members in Poland and the Baltic states are expanding programs with all-weather platforms.
- Infrastructure Inspection:Transmission grid and pipeline operators in Germany and Austria are shifting from capital purchase to platform-as-a-service contracts, transferring airframe risk to OEM balance sheets.
- Agricultural Monitoring:Multispectral crop health assessment spreads across Spanish and Italian cooperatives.
- Environmental Research:Atmospheric sampling and wildlife tracking applications face altitude restrictions in dense terminal control areas around Frankfurt and Paris hubs.
- Search & Rescue:Thermal-equipped platforms for missing-person location gain traction with municipal emergency services in the Netherlands and Denmark.
Infrastructure Inspection anchors current revenue. Search & Rescue is gaining share fastest as direct-to-operator digital distribution bypasses traditional defense integrators.
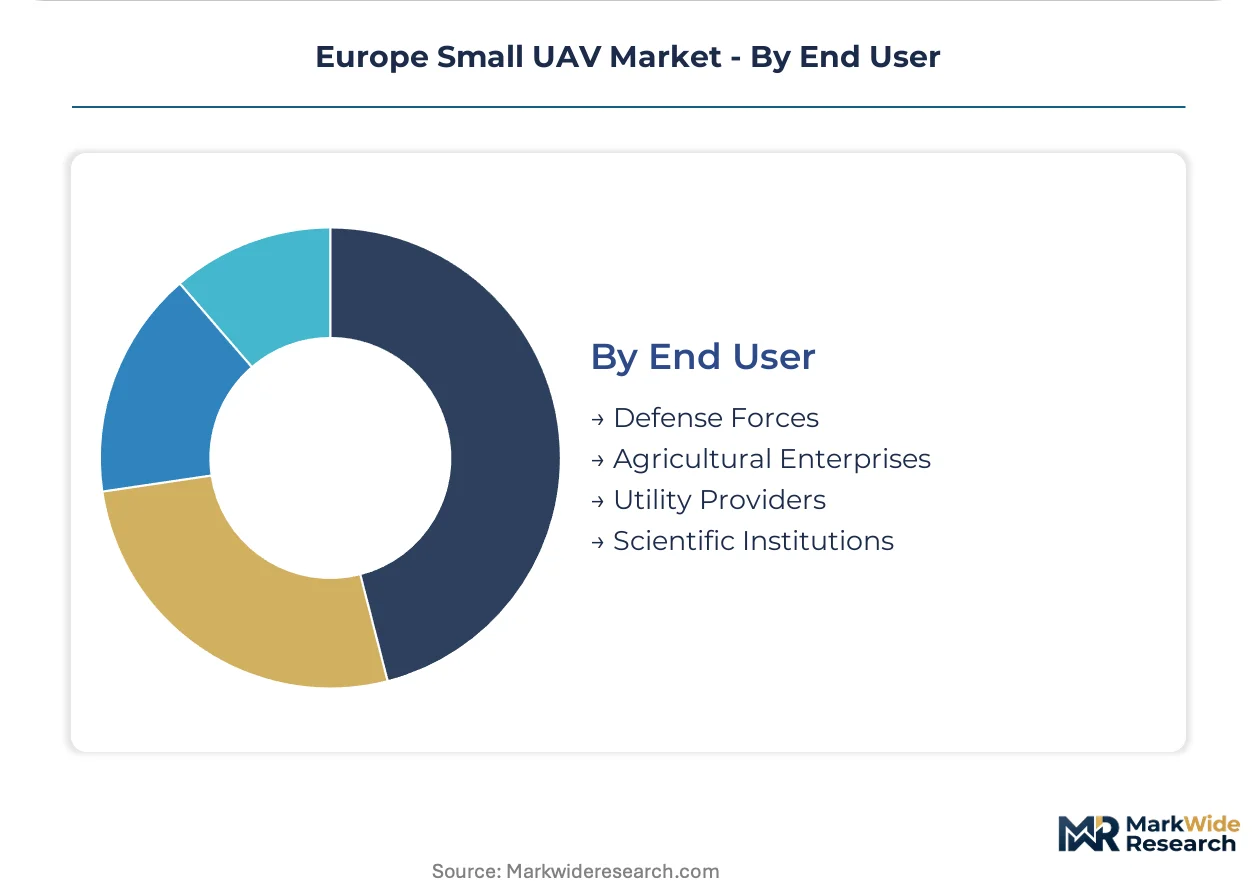
End User:
Customer type determines procurement channel: defense forces route through sovereign acquisition frameworks while agricultural enterprises and utility providers access commercial distribution.
- Defense Forces:NATO standardization pressures and Article 346 TFEU exemptions create dual procurement tracks. German and French domestic manufacturers capture scale advantages through integrated aerospace supply chains.
- Utility Providers:Transmission and pipeline operators in Germany and Austria unbundle hardware ownership from flight-hour guarantees, favoring vertically integrated OEMs with captive maintenance networks.
- Agricultural Enterprises:Cooperatives in Spain and Italy prioritize certified platforms with AI-powered obstacle avoidance to reduce insurance premiums.
- Scientific Institutions:Research programs face extended Luftfahrt-Bundesamt approval timelines for experimental autonomous navigation systems.
Defense Forces represent the revenue concentration. Agricultural Enterprises show the steepest expansion trajectory as EASA operational authorizations unlock commercial inspection contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utility providers deploy fixed-wing platforms for linear infrastructure inspection, while French pipeline operators favor hybrid VTOL architectures. Spanish and Italian agricultural cooperatives concentrate rotary-wing demand for multispectral crop monitoring. Eastern flank defense programs in Poland and the Baltic states drive tactical platform procurement through NATO standardization channels.
Germany
Transmission grid operators in Bavaria and North Rhine-Westphalia unbundle hardware ownership from flight-hour guarantees, transferring airframe risk to OEM balance sheets. Luftfahrt-Bundesamt type-certification timelines stretch 18-24 months for autonomous navigation variants. Industrial UAV manufacturing clusters around Munich and Hamburg serve both domestic defense contracts and export customers across NATO member states.
France
Pipeline utilities in the Île-de-France and Provence-Alpes-Côte d'Azur regions expand fleet procurement for beyond-visual-line-of-sight inspection missions. EASA's operational authorization under EU 2019/947 unlocks commercial contracts previously constrained by cross-border regulatory fragmentation. Paris-based defense integrators leverage Article 346 TFEU exemptions to fast-track tactical acquisitions outside standard EU procurement rules.
Spain
Agricultural spraying contractors in Andalusia and Catalonia prioritize AI-powered obstacle-avoidance sensor packages to reduce insurance premiums and operator certification burdens. CE marking requirements under the EU Machinery Directive constrain market access for non-compliant hardware imports. Barcelona and Madrid host emerging clusters for civilian-grade imaging platform assembly.
Italy
Multispectral crop health assessment spreads across agricultural cooperatives in Emilia-Romagna and Lombardy, driving rotary-wing platform demand. EASA EU 2019/947 operational authorizations unlock fleet procurement from mid-tier agricultural enterprises. Northern Italian manufacturing bases supply subsystems to German and French system integrators.
Poland
Eastern flank NATO members expand border surveillance and artillery spotting programs, creating demand for tactical platforms with encrypted datalinks and all-weather optics. Article 346 TFEU exemptions accelerate domestic manufacturing scale-up outside standard EU defense procurement timelines. Warsaw and Krakow emerging as assembly hubs for NATO-standardized tactical UAV subsystems.
Europe Small UAV Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with aerospace conglomerates controlling defense procurement channels and mid-cap firms capturing civilian-commercial niches. Airbus anchors the integrated tier through captive supply chains and NATO contract relationships. Specialist archetypes include VTOL hybrid designers, nano-drone assemblers, and AI-enabled autonomy stack developers. Competitive moves center on backward integration into battery and sensor supply, plus direct-to-operator digital distribution bypassing traditional defense integrators.
Among Germany-based fabricators, Quantum-Systems GmbH and Microdrones GmbH occupy positions within the VTOL specialist tier, exemplifying vertical-takeoff hybrid architectures that bridge fixed-wing endurance and rotary-wing flexibility. Parrot Drones SAS represents the nano-drone archetype, anchoring civilian-grade imaging platforms for close-quarters inspection. These three firms illustrate how European manufacturers differentiate through regulatory compliance velocity rather than scale-driven cost positioning.
| Leading Market Players |
|---|
| Airbus |
| BAE Systems |
| Leonardo S.p.A. |
| Thales |
| SAAB |
| Parrot Drones SAS |
| Microdrones GmbH |
| Quantum-Systems GmbH |
| DELAIR SAS |
| Others |
Supply & Pricing Matrix
Platform-as-a-service contracting locks in multi-year flight-hour guarantees between German transmission grid operators and OEMs, anchoring price visibility while transferring airframe risk and maintenance burden to manufacturer balance sheets. This structure concentrates procurement leverage among vertically integrated suppliers with captive service networks.
Pricing Analysis
Long-term offtake agreements dominate defense procurement channels, while spot purchasing persists for agricultural and municipal applications. Price differentiation rests on EASA certification grade and Luftfahrt-Bundesamt type-approval status, with autonomous navigation variants commanding substantial premiums over remote-control alternatives. Cost compression in the rotary-wing segment intensifies as Asian battery suppliers capture cell production, squeezing margins for non-vertically integrated European assemblers. Agricultural cooperatives in Spain and Italy exhibit highest price sensitivity, prioritizing CE-marked platforms with basic multispectral capability over premium AI-integrated stacks.
Supply Chain Analysis
China and South Korea anchor lithium-polymer cell production for sub-150kg platforms, while Germany and France concentrate airframe assembly and avionics integration. Critical inputs span high-energy-density battery cells, embedded neural inference processors, and real-time kinematic positioning modules. Single-source vulnerability in Asian cell supply exposes European manufacturers to customs processing delays and input cost volatility. Distribution runs through direct-to-operator digital channels for civilian applications, contrasting with defense procurement through national sovereign acquisition frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
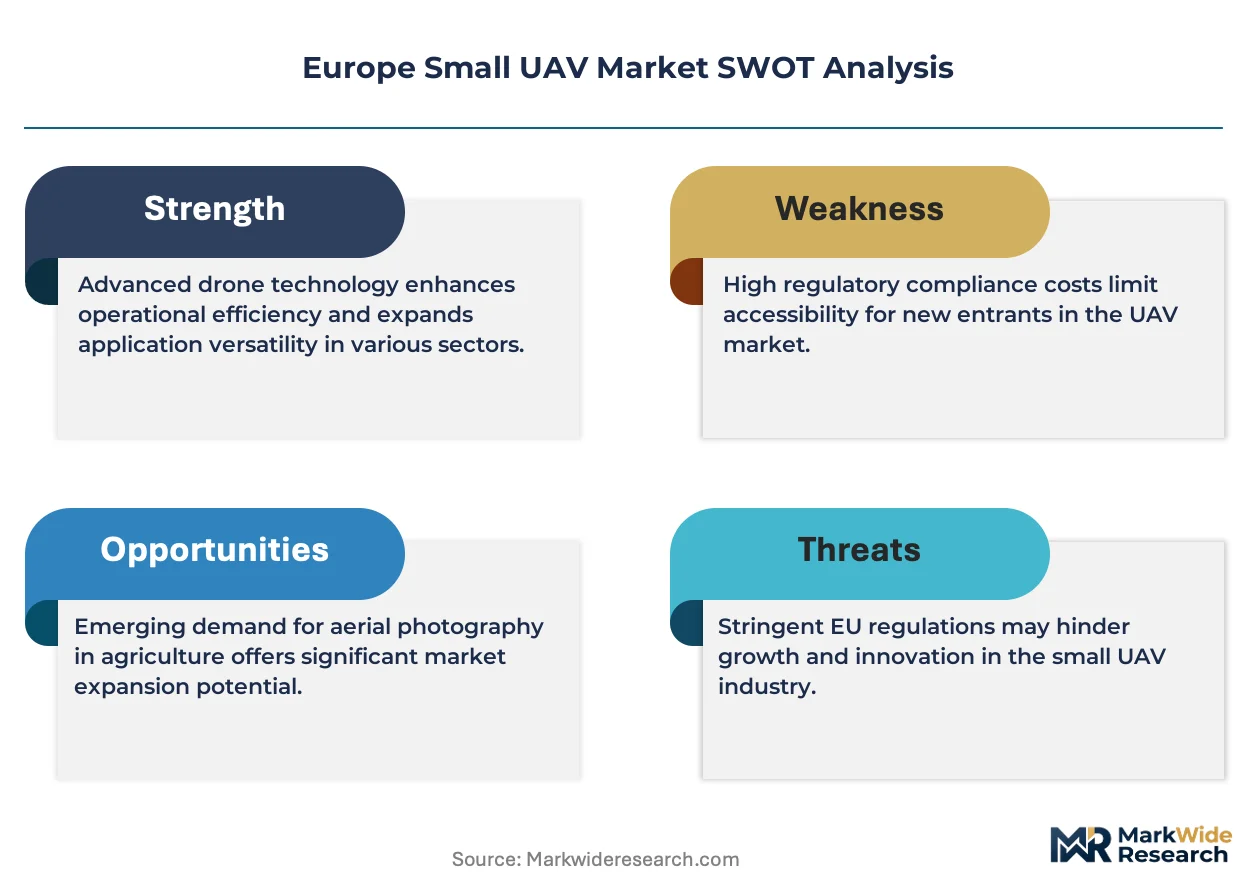
The market rewards firms that control scarce EASA Part-66 licensed avionics talent and Luftfahrt-Bundesamt certification velocity, with capability gaps in autonomous flight-systems engineering constraining scale-up timelines for mid-tier competitors.
For Market Incumbents: Fortify captive maintenance networks in Germany and Austria to capture platform-as-a-service contracts transferring airframe risk from utility buyers. Accelerate backward integration into battery pack assembly to reduce exposure to Asian cell supply volatility. Defensive priority centers on locking in EASA type-certification timelines ahead of U-space regulatory implementation. For New Entrants and Emerging Players: EASA's streamlined operational authorization pathway under EU 2019/947 opens white-space in beyond-visual-line-of-sight agricultural monitoring across Spain and Italy. Municipal emergency services in the Netherlands and Denmark represent the most penetrable end-user segment, with direct digital distribution bypassing traditional defense integrators. Go-to-market focus should target AI-act compliance advisory services for manufacturers navigating high-risk system classification. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated OEMs with captive certification expertise and established Luftfahrt-Bundesamt relationships, positioned for sustained viability through NATO procurement cycles and civilian regulatory harmonization. Acquisition target archetype combines hybrid VTOL design capability with existing EASA operational approvals. Signal to monitor: Polish and Baltic defense budget acceleration for encrypted datalink tactical platforms.| Strategic Initiative | Industry Significance |
|---|---|
| EASA Type-Certification Fast-Track | Luftfahrt-Bundesamt approval velocity determines product launch windows and margin capture. |
| Backward Integration into Battery Assembly | In-house pack production reduces Asian cell supply dependency and customs exposure. |
| Platform-as-a-Service Contracting | Flight-hour guarantees transfer airframe risk and lock in recurring revenue streams. |
| AI-Act Compliance Service Launch | High-risk system classification under EU AI Act generates conformity assessment revenue. |
| Direct-to-Operator Digital Distribution | Online configurators bypass defense integrators for municipal and agricultural procurement. |
Research Methodology
A standing panel of EASA certification specialists, Luftfahrt-Bundesamt design approval officers, defense procurement directors at NATO member ministries, and agricultural cooperative fleet managers provided ongoing calibration across primary interview rounds. Secondary validation drew from EASA regulatory filings, EU 2019/947 implementing regulation texts, national defense budget appropriations documents, and transmission grid operator procurement disclosures. Bottom-up platform shipment estimates triangulated against top-down defense expenditure allocations.
Consistency checks validated volume and value outputs against NATO standardization program announcements, EASA operational authorization issuance rates, and utility sector fleet procurement disclosures. Segmentation modeling spanned product architecture, autonomy technology tier, application mission profile, and end-user procurement channel. CAGRs derived from regression analysis across historical procurement trajectories and projected regulatory milestone impacts, incorporating battery cost curve assumptions and certification timeline elasticity.
Underlying assumptions cover EASA U-space implementation schedules, NATO member defense budget trajectories, and lithium-polymer supply continuity, with deviation risk concentrated in regulatory delay scenarios and geopolitical trade friction. Recalibration cycles align with material shifts in EASA regulatory issuance patterns and NATO procurement authorization timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Drone Delivery Services Market
UAV
Small UAV Market
UAV
US Commercial Drone Market
UAV
Fuel Cell UAV Market
UAV
Middle-East and Africa Drones Market
UAV
Europe Tactical UAV Market
UAV
Delivery Drones Market
UAV
Global Aerial Survey Services Market
UAV
North America Drones Market
UAV
Global Electric Drone Market
UAV
Ultra-Long Endurance Drone Market
UAV
North America Drone Services Market
UAV
FPV Drone Goggles Market
UAV
Drone Leasing Market
UAV
Europe Tethered Drone Market
UAV
Toy Drones Market