
 UAV Payload and Subsystems Market | 2026-2036
UAV Payload and Subsystems Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Payload and Subsystems Market Intelligence
Defense procurement channels are being redrawn as national security agencies direct spending toward indigenous UAV payload manufacturing, a shift that is reshaping supplier relationships across NATO and non-aligned militaries. Lockheed Martin leverages its Skunk Works division to sustain classified payload integration programs for high-altitude platforms. Northrop Grumman anchors its position through advanced radar and electronic warfare payloads for the Global Hawk family. Elbit Systems competes aggressively in European tender processes with its Hermes-series payload packages.
UAV payload and subsystems encompass the mission-critical hardware modules—electro-optical/infrared cameras, synthetic aperture radar, signals intelligence sensors, and associated power and stabilization electronics—mounted aboard unmanned aircraft to execute designated operational tasks, typically operating across spectral bands from visible light to millimeter-wave frequencies with stabilization accuracies below 50 microradians. Camera Systems and Sensors dominate current procurement volumes within Payload Type, while Communication Equipment captures expanding share as beyond-line-of-sight datalink requirements intensify for contested environments. Navigation and Data Processing subsystems concentrate margin pools due to ITAR-controlled algorithmic content and radiation-hardened component sourcing constraints.
FAA Part 107 waivers and EASA drone regulation frameworks govern civilian payload deployment altitudes and beyond-visual-line-of-sight operations, while ITAR and EAR export controls restrict military-grade sensor transfers to approved end-user destinations. The EU AI Act introduces emerging compliance obligations for autonomous targeting and decision-aid algorithms embedded in sensor-fusion subsystems. Stakeholders must monitor evolving frequency allocation battles between commercial 5G networks and military C-band datalink operations as spectrum congestion intensifies.
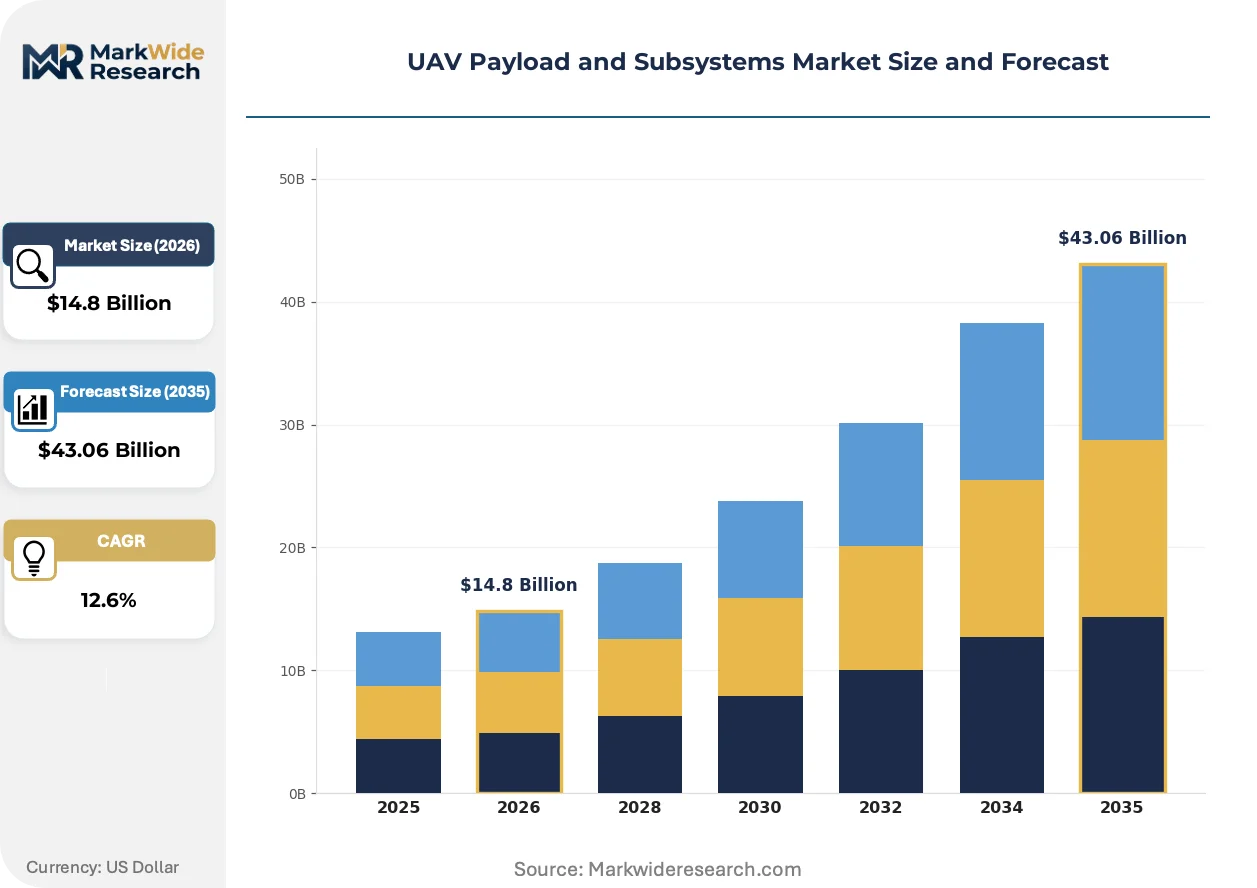
Market Dynamics
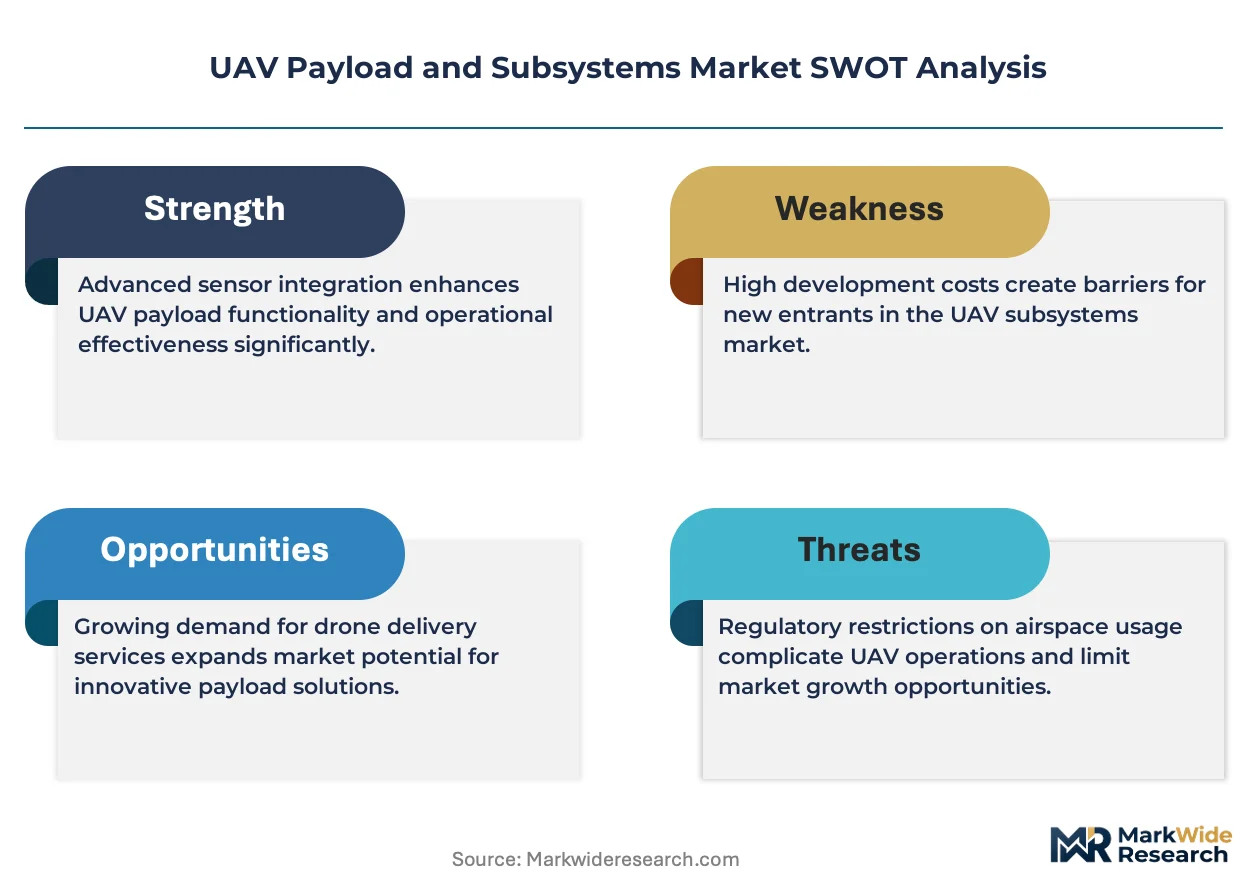
Payload miniaturization is compressing development cycles as defense agencies demand multi-spectral capabilities in reduced form factors, forcing suppliers to consolidate sensor fusion and power management into integrated modules that previously occupied separate airframe stations.
Growth Catalysts
- Beyond-Line-of-Sight Datalink Mandates:Military end-users in contested electromagnetic environments require hardened communication equipment that maintains connectivity through jamming and terrain masking.
- Israel:Domestic manufacturers supply national military programs with electro-optical/infrared packages optimized for desert and urban operational profiles.
- FAA Part 107 Evolution:Expanded waiver categories for night operations and operations over people accelerate civilian payload deployment for infrastructure inspection and emergency response.
Market Restraints
- ITAR-Controlled Algorithm Sourcing:Navigation and data processing subsystems face restricted component availability from approved suppliers, extending lead times for radiation-hardened processors.
- Gallium Arsenide Wafer Concentration:High-frequency radar payload production depends on concentrated substrate supply from East Asian foundries vulnerable to export licensing delays.
- Power Density Limitations:Synthetic aperture radar and signals intelligence payloads exceed thermal dissipation capacity of small rotary-wing platforms below Group 3 weight classes.
Strategic Opportunities
- Turkey:Indigenous UAV programs create captive demand for domestic payload integration capabilities previously supplied through foreign offset agreements.
- Hyperspectral-AI Sensor Fusion:Convergence of push-broom hyperspectral imagers with onboard inference engines enables real-time target classification without ground station dependency.
- EU AI Act Compliance Services:Emerging obligations for autonomous targeting algorithm documentation create advisory revenue streams for subsystem integrators.
Industry Challenges
- Electromagnetic Compatibility Certification:Multi-sensor payload integration requires simultaneous satisfaction of FCC Part 15, MIL-STD-461, and platform-specific airworthiness standards with conflicting test protocols.
- Stabilization Engineer Scarcity:Gimbal design expertise combining inertial navigation, control theory, and aerodynamic loading analysis concentrates in defense-adjacent labor markets with restricted clearance mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Payload and Subsystems Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $43.06 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payload Type: Camera Systems, Sensors, Communication Equipment, Jammers Subsystem Function: Navigation, Stabilization, Power Management, Data Processing Application Sector: Agriculture, Surveying, Defense, Search and Rescue Deployment Model: Civilian, Military, Commercial, Research |
| Companies Covered | Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, Teledyne FLIR LLC, Elbit Systems Ltd., BAE Systems Plc, AeroVironment Inc., Israel Aerospace Industries Ltd., General Atomics Aeronautical Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Payload and Subsystems Market Strategic Shifts & Innovations
Active electronically scanned arrays are migrating from manned platforms to tactical UAVs, compressing radar payload size-weight-power metrics while expanding synthetic aperture resolution capabilities previously reserved for strategic assets.
Solid-state phased array architectures are digitizing beam-forming functions that analog systems performed through mechanical gimbals and waveguide switching. Defense procurement channels in NATO member states are prioritizing these configurations for signals intelligence and ground-moving target indication missions. The technology is digitizing supplier value chains by collapsing discrete component tiers into integrated transmit-receive module assemblies.
EASA drone certification frameworks are mandating design assurance levels for autonomous flight control systems that cascade into payload subsystem documentation requirements. European payload integrators must demonstrate traceability from sensor output to decision algorithm under emerging compliance obligations. Small unmanned aircraft system manufacturers in Germany and France are restructuring supplier qualification protocols to satisfy these expanded audit scopes.
Defense agencies are unbundling sensor procurement from airframe acquisition, creating standalone payload competition for retrofit programs and interoperability mandates. Traditional prime contractors face displacement by specialized subsystem houses with faster development cycles. This pattern concentrates in the United States, where the Air Force Rapid Capabilities Office has established separate contracting vehicles for intelligence-surveillance-reconnaissance payload refresh cycles distinct from platform sustainment funding.
UAV Payload and Subsystems Market Segmentation
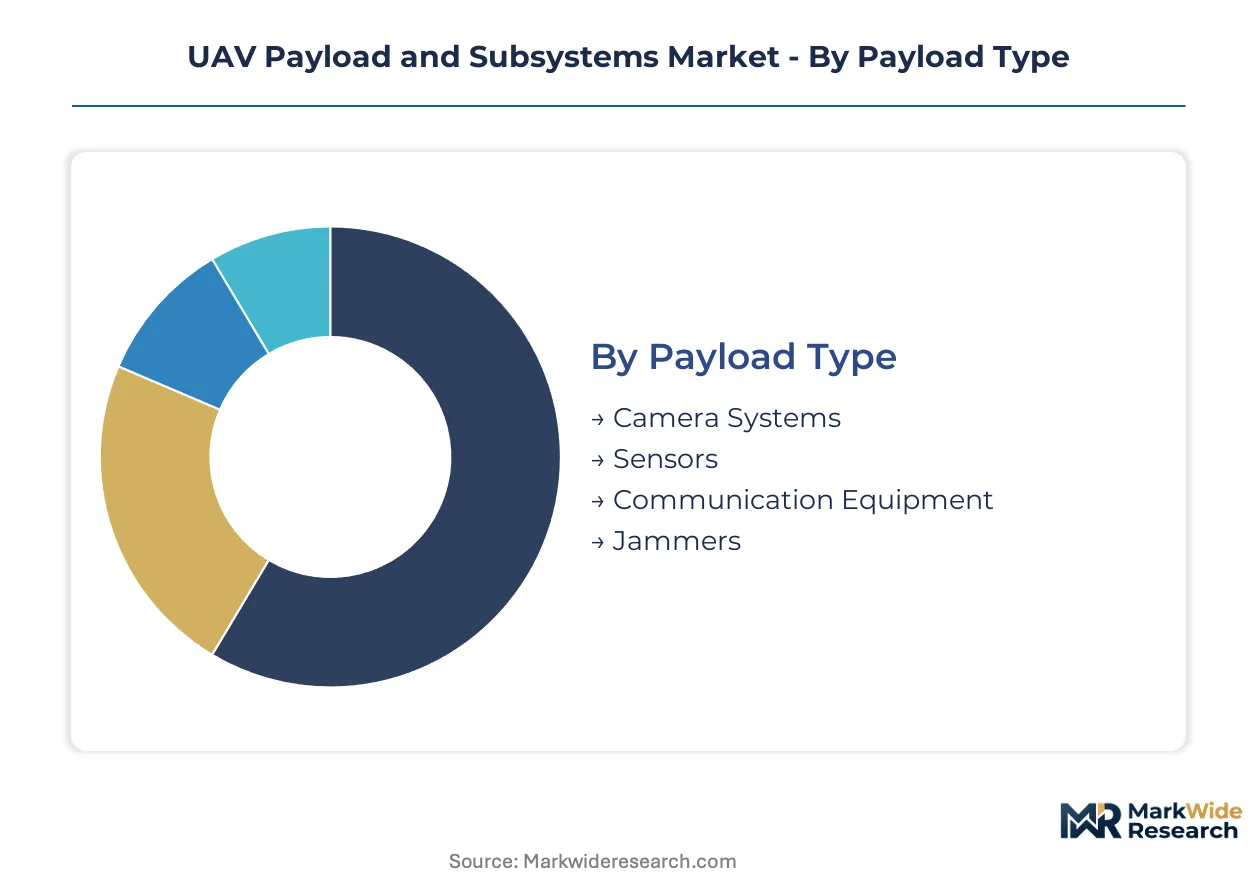
Payload modularity defines competitive positioning in UAV subsystems. Suppliers configure integrated packages across spectral bands and mission profiles to capture procurement cycles in defense and civilian channels.
Payload Type:
Military end-users demand multi-spectral coverage across desert, maritime, and urban operational theaters, while civilian operators prioritize cost-optimized single-band configurations for infrastructure monitoring.
- Camera Systems:Electro-optical and infrared modules integrate stabilized gimbals with sub-50 microradian accuracy. Defense procurement in Israel and Turkey concentrates demand for dual-band packages capable of day-night target acquisition in contested electromagnetic environments.
- Sensors:Synthetic aperture radar and signals intelligence payloads operate across millimeter-wave frequencies with active electronically scanned array architectures. NATO member states drive adoption for ground-moving target indication missions requiring all-weather penetration.
- Communication Equipment:Beyond-line-of-sight datalinks with anti-jam waveforms serve contested spectrum operations.
- Jammers:Electronic warfare payloads deliver electromagnetic denial capabilities for suppression of enemy air defense missions.
Established volume favors Camera Systems; emerging adoption favors Communication Equipment.
Subsystem Function:
Margin concentration tracks ITAR-controlled content and radiation-hardened component sourcing constraints across processor categories.
- Navigation:Inertial measurement units and GPS-denied positioning algorithms enable operations in GPS-contested environments. FAA Part 107 waiver categories for beyond-visual-line-of-sight flight expand civilian demand for redundant navigation architectures in infrastructure inspection applications.
- Stabilization:Gimbal control systems combine inertial navigation with aerodynamic load compensation. Labor scarcity for control-theory engineers with security clearances constrains supplier capacity in the United States defense corridor.
- Power Management:Thermal dissipation systems address power density limitations in Group 3 and smaller rotary-wing platforms.
- Data Processing:Onboard inference engines for real-time target classification reduce ground station dependency.
Navigation captures premium pricing through ITAR restrictions; Data Processing climbs the fastest as autonomous targeting mandates expand.
Application Sector:
Defense procurement channels dominate revenue concentration, while civilian sectors exhibit fragmented demand across specialized use cases.
- Defense:Multi-spectral sensor suites for intelligence-surveillance-reconnaissance missions require hardened packaging for high-altitude long-endurance platforms. The United States Air Force Rapid Capabilities Office maintains separate contracting vehicles for payload refresh cycles distinct from platform sustainment.
- Agriculture:Multispectral cameras for crop health monitoring operate at reduced stabilization tolerances compared to military specifications. FAA Part 107 expanded waiver categories for night operations accelerate deployment for large-scale farm management in the United States Midwest.
- Surveying:LiDAR and photogrammetry payloads serve construction and mining site documentation.
- Search and Rescue:Thermal imaging configurations prioritize detection range over resolution for wilderness and maritime operations.
Defense commands procurement volume; Agriculture shows steepest expansion trajectory as regulatory frameworks mature.
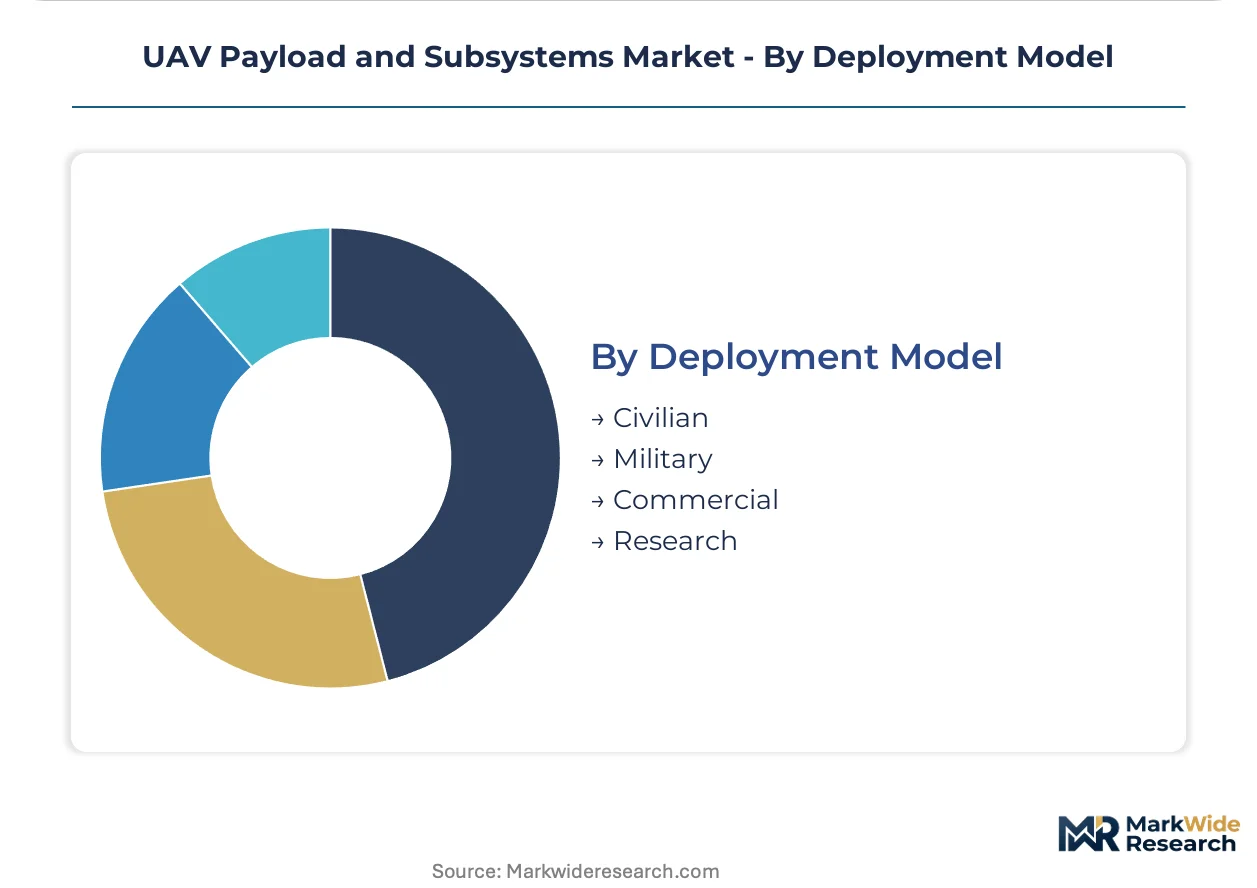
Deployment Model:
Procurement patterns diverge between sovereign defense programs with captive industrial bases and commercial operators sourcing through distributor channels.
- Military:National security agencies direct spending toward indigenous manufacturing capabilities, reshaping supplier relationships across NATO and aligned militaries. Turkey's indigenous UAV programs create captive demand for domestic payload integration previously supplied through foreign offset agreements.
- Civilian:EASA drone certification frameworks mandate design assurance levels that cascade into payload subsystem documentation requirements. European integrators in Germany and France restructure supplier qualification protocols to satisfy expanded audit scopes.
- Commercial:Logistics and delivery operators drive miniaturization requirements for last-mile payload capacity.
- Research:Academic and government laboratory programs test experimental sensor configurations without production scale requirements.
Military deployment anchors supplier revenue; Commercial channels gain share fastest as beyond-line-of-sight regulations harmonize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Red Sea corridor's fiber-optic cable landing stations and Turkey's Straits pipeline network anchor Middle Eastern UAV payload demand, while the Transatlantic data cable systems underpin North Atlantic defense electronics procurement patterns.
United States
The Air Force Rapid Capabilities Office sustains separate contracting vehicles for intelligence-surveillance-reconnaissance payload refresh cycles. FAA Part 107 waiver expansions for night operations and beyond-visual-line-of-sight flight accelerate civilian deployment for infrastructure inspection. Greater Boston's defense corridor concentrates gimbal stabilization engineering talent with security clearance mobility restrictions.
Israel
Domestic manufacturers supply national military programs with electro-optical/infrared packages optimized for desert and urban operational profiles. The country's national security procurement frameworks prioritize indigenous payload integration over foreign offset agreements. Tel Aviv's defense electronics cluster concentrates dual-band camera system development for contested electromagnetic environments.
Turkey
Indigenous UAV programs create captive demand for domestic payload integration capabilities previously supplied through foreign offset agreements. The country's defense procurement agencies direct spending toward sovereign manufacturing capabilities. Ankara's aerospace corridor anchors radar and electronic warfare payload development for tactical platforms.
Germany
EASA drone certification frameworks mandate design assurance levels that cascade into payload subsystem documentation requirements. The EU AI Act introduces compliance obligations for autonomous targeting algorithms embedded in sensor-fusion subsystems. Bavaria's unmanned aircraft system manufacturers restructure supplier qualification protocols to satisfy expanded audit scopes.
United Kingdom
Defense procurement channels prioritize multi-spectral sensor suites for intelligence-surveillance-reconnaissance missions on high-altitude long-endurance platforms. ITAR-controlled algorithm sourcing restrictions constrain navigation and data processing subsystem availability. The Southwest England aerospace cluster concentrates synthetic aperture radar integration for NATO ground-moving target indication missions.
UAV Payload and Subsystems Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream with faster development cycles and narrower certification scopes. The supplier base fragments across defense primes with airframe integration capabilities and subsystem houses with spectral-domain expertise. Three archetypes dominate: sovereign defense contractors with classified program access, commercial sensor houses with civilian regulatory fluency, and dual-use specialists bridging military and industrial inspection markets. Competitive moves concentrate on unbundling sensor procurement from airframe acquisition and consolidating transmit-receive module assemblies into integrated packages.
Within the sovereign defense contractor tier, Lockheed Martin Corporation and Northrop Grumman Corporation exemplify platform-integrated payload development, while Elbit Systems Ltd. occupies a position bridging Israeli national programs and European tender processes. RTX Corporation and BAE Systems Plc represent transatlantic defense electronics houses with radar and electronic warfare payload lineages. Among specialized component suppliers, Teledyne FLIR LLC and Israel Aerospace Industries Ltd. exemplify electro-optical/infrared domain concentration, with AeroVironment Inc. and General Atomics Aeronautical Systems Inc. representing tactical platform specialists with captive payload integration capabilities.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| Northrop Grumman Corporation |
| RTX Corporation |
| Teledyne FLIR LLC |
| Elbit Systems Ltd. |
| BAE Systems Plc |
| AeroVironment Inc. |
| Israel Aerospace Industries Ltd. |
| General Atomics Aeronautical Systems Inc. |
| Others |
Cost & Logistics Intelligence
Greater Boston's defense corridor concentrates gimbal stabilization engineering talent with security clearance mobility restrictions, creating asymmetric pricing power for ITAR-controlled navigation subsystems against commoditized camera modules. This geographic concentration of specialized labor pools enables premium capture in data processing categories while compressing margins in electro-optical hardware facing multi-source competition.
Pricing Analysis
Three-tier pricing structure across ITAR-restricted, EAR-controlled, and unclassified commercial levels dominates procurement contracts. Price differentiation rests on certification grade and volume scale, with defense primes commanding substantial premiums for radiation-hardened processors. Cost compression in commercial camera modules is intensifying because of Asian foundry competition. Agricultural operators exhibit highest price sensitivity; national security agencies demonstrate lowest.
Supply Chain Analysis
Contract manufacturing concentrates with Taiwan Semiconductor Manufacturing Company, Samsung Foundry, and GlobalFoundries holding advanced node capacity for radar processors. Gallium arsenide wafer sourcing draws from East Asian foundries in Taiwan, South Korea, and Japan. Supply chain risk centers on single-source vulnerability for radiation-hardened component qualification. Distribution runs through prime contractor integration channels and specialized subsystem houses with direct defense procurement access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UAV payload and subsystems sit in early-cycle expansion as beyond-line-of-sight regulatory harmonization unlocks civilian deployment at scale previously restricted to military applications.
For Market Incumbents: Insulate classified program access through accelerated security clearance pipelines and captive gimbal engineering capacity in defense-corridor labor markets. Threat from commercial sensor houses with faster development cycles demands consolidation of transmit-receive module assemblies into integrated packages. Priority lever: backward integration into gallium arsenide substrate sourcing to mitigate foundry concentration risk.
For New Entrants and Emerging Players: European agricultural inspection markets present underpenetration for cost-optimized multispectral payloads operating under reduced stabilization tolerances. White-space targets include EU AI Act compliance services for autonomous targeting algorithm documentation and German unmanned aircraft system manufacturer supplier qualification restructuring. Go-to-market angle: EASA certification fluency as competitive wedge against ITAR-constrained incumbents.
For Investors and Strategic Acquirers: Long-term, this sits as a defense-adjacent dual-use play because civilian regulatory maturation creates expansion optionality beyond cyclical military procurement. Acquisition target archetype: specialized subsystem houses with spectral-domain expertise and faster development cycles than platform primes. Signal to watch: FAA Part 107 waiver volume acceleration as inflection indicator for commercial channel scaling.
| Strategic Initiative | Industry Significance |
|---|---|
| Payload Miniaturization Investment | Consolidates multi-spectral capabilities into reduced form factors demanded by Group 3 rotary-wing platforms. |
| ITAR-Controlled Algorithm Development | Captures premium pricing in navigation and data processing through restricted component sourcing constraints. |
| EASA Certification Pathway | Unlocks European civilian deployment as design assurance levels cascade into payload subsystem requirements. |
| Hyperspectral-AI Sensor Fusion | Enables real-time target classification without ground station dependency for contested electromagnetic environments. |
| Gallium Arsenide Supply Agreement | Secures high-frequency radar substrate access from East Asian foundries vulnerable to export licensing delays. |
Research Approach
Cross-validation between primary interviews with defense procurement officers, payload subsystem integrators, gimbal stabilization engineers, and EASA certification consultants and secondary validation through FAA waiver databases, ITAR-controlled component manifests, and EASA design assurance documentation anchors the qualitative findings. Bottom-up triangulation against top-down defense budget allocation analysis ensures segmentation integrity.
Calibration against historical procurement cycle patterns and platform refresh timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include payload type, subsystem function, application sector, deployment model, and spectral band coverage. CAGRs were derived from installed base expansion rates and replacement cycle acceleration. Industry-specific forecast inputs encompass electromagnetic spectrum allocation battles and radiation-hardened processor lead time trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign defense contractors with captive industrial bases would shift outcomes. Quarterly review of FAA Part 107 waiver issuance rates and EASA design assurance approval velocity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
North America Small UAV Market
UAV
Small Drone Market
UAV
Drone Camera Market
UAV
UAV Lidar Market
UAV
UAV GNSS Antenna Market
UAV
Counter Drone System Market
UAV
UAV Simulator Software Market
UAV
Drone-Based Consulting Services Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Drone Defense System Market
UAV
Electric Unmanned Aerial Vehicle Market
UAV
Enterprise Drone Management Solutions Market
UAV
UAV Simulator Market
UAV
North America Fuel Cell UAV Market
UAV
Drone Powered Business Solutions Market
UAV
Airborne Digital Battlefield Market