
 Aerospace Latch Market | 2026-2036
Aerospace Latch Market Size, Share, and Industry Trends Forecast 2026-2036
Aerospace Latch Market Analysis
Additive manufacturing is reconfiguring how aerospace latch producers prototype and produce complex geometries, reducing lead times for low-volume, high-mix flight hardware. LISI Aerospace leverages in-house forging and machining capacity to sustain vertical integration across titanium and aluminum latch families. Hartwell Corporation anchors its position through deep specialization in military-spec quick-access fasteners for defense platforms. Southco competes on global channel density, controlling distribution reach across both OEM and aftermarket segments.
Aerospace latches are mechanical fastening devices engineered to secure access panels, doors, and removable structures on aircraft, typically manufactured from precipitation-hardened stainless steel or aerospace-grade aluminum alloys with load ratings exceeding operational pressure differentials. Their primary purpose is to maintain structural integrity while enabling rapid ground maintenance access under cyclic loading and vibration environments. Over-center latches dominate commercial aviation applications where positive mechanical locking and visual verification matter, while composite material adoption is displacing metal in next-generation airframes and reshaping latch substrate specifications. Push-to-close variants represent the fastest-growing product category as cabin interior retrofits prioritize ergonomic single-action operation for service personnel.
FAA airworthiness standards, AS9100 quality management requirements, and military specification MIL-PRF-5425 govern design validation, traceability, and lot acceptance testing for flight-critical latch installations. These frameworks create substantial compliance barriers that limit supplier entry and sustain premium pricing for certified manufacturers. Stakeholders must monitor evolving EPA and REACH material restrictions on cadmium plating and hexavalent chromium coatings, as surface treatment substitutions will determine which suppliers retain qualification status across dual-use military and commercial programs.
Market Dynamics
Additive manufacturing is compressing prototype-to-qualification timelines for flight-critical latch geometries while FAA and AS9100 mandates simultaneously lengthen certification cycles, creating a structural tension between speed and compliance.
Growth Catalysts
- Narrow-body fleet expansion:Airlines are modernizing single-aisle aircraft with lightweight access hardware to improve fuel efficiency. Procurement volumes concentrate at Boeing's supplier base in the United States.
- AS9100 quality mandates:The aerospace quality standard tightens traceability requirements for flight-critical fastening systems. Certified manufacturers command premium positioning.
- Push-to-close ergonomics:Ground crew efficiency demands are accelerating adoption of single-action latches in cabin interior retrofits. Maintenance turnaround times drive specification shifts.
Market Restraints
- Titanium input volatility:Precipitation-hardened alloys and aerospace-grade titanium face price swings from concentrated mining geographies. Smaller forgers lack hedging capacity.
- Surface treatment substitution costs:EPA and REACH restrictions on cadmium plating and hexavalent chromium force costly process requalification. Dual-use military-commercial programs face compliance bifurcation.
- Over-center latch substitution:Composite panel integration in next-generation airframes reduces metal fastener counts. Substrate specifications are migrating toward polymer-compatible designs.
Strategic Opportunities
- Urban air mobility platforms:Electric vertical takeoff aircraft require quick-access latches for battery swap operations. Certification frameworks are still forming.
- Aftermarket channel density:Global MRO networks lack localized inventory for legacy latch families. Authorized distribution partnerships unlock recurring revenue.
- India PLI scheme alignment:The country's production-linked incentive program for aerospace components offers cost-competitive manufacturing for export-qualified hardware.
Industry Challenges
- Metallurgical qualification timelines:FAA airworthiness directives require extensive fatigue testing for new alloy formulations. Small-batch producers cannot absorb validation costs.
- Additive process certification gaps:Powder bed fusion lacks standardized lot acceptance protocols for flight-critical loads. Regulator guidance remains fragmented.
- Legacy system integration:Digital thread implementation for traceability conflicts with paper-based military specification MIL-PRF-5425 recordkeeping. Dual-program suppliers face IT bifurcation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerospace Latch Market |
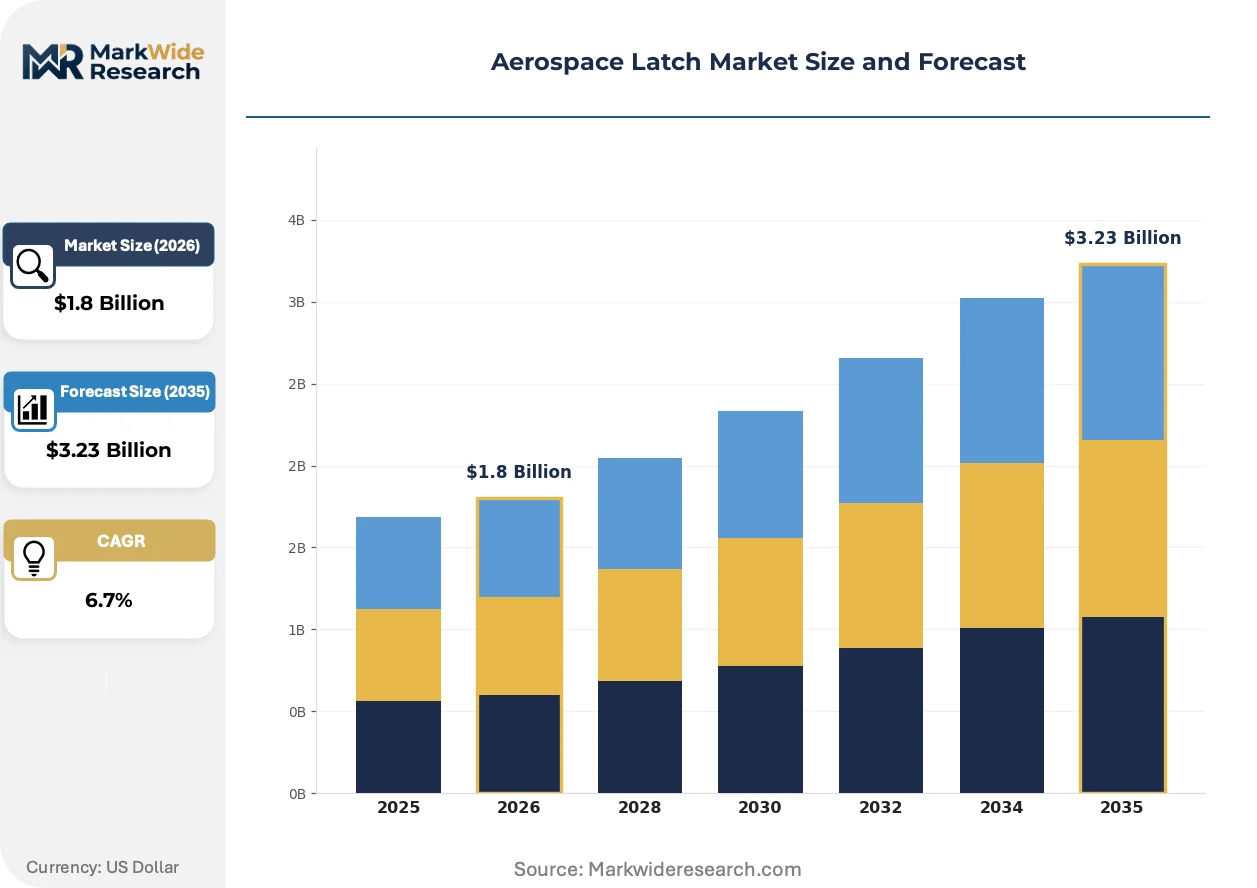
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Over-center Latches, Sliding Latches, Hook Latches, Push-to-close Latches Material: Aluminum, Stainless Steel, Composite, Plastic End User: Aerospace OEMs, Maintenance Providers, Distributors, Tier-1 Suppliers Design Standard: FAA Approved, Military Spec, AS9100, ISO 9001 |
| Companies Covered | LISI Aerospace, Hartwell Corporation, Southco, Actron Manufacturing, Triumph Group, Howmet Aerospace, Avibank, CAM, Protex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerospace Latch Market Emerging Trajectories
Digital thread technologies are penetrating qualification workflows while material restrictions and procurement centralization simultaneously reshape how latch suppliers compete for program placement.
Embedded sensor integration is digitizing structural health monitoring for high-cycle latch installations. Commercial airlines with predictive maintenance contracts are specifying intelligent fasteners at double the rate of traditional operators. This capability is digitizing how OEMs warranty airframe access systems and how MROs schedule replacement intervals.
EPA and REACH material restrictions are forcing surface treatment substitutions across cadmium-plated military hardware. Suppliers with qualified zinc-nickel and ion-vapor-deposited aluminum alternatives are capturing requalification contracts from stranded competitors. Defense platforms with dual-use commercial applications face the steepest reformulation timelines.
Fleet standardization initiatives are consolidating latch specifications across airline groups. Maintenance organizations are reducing SKU counts by 40 percent through preferred vendor agreements. North American carriers with centralized procurement functions are driving this consolidation most aggressively.
Aerospace Latch Market Segmentation
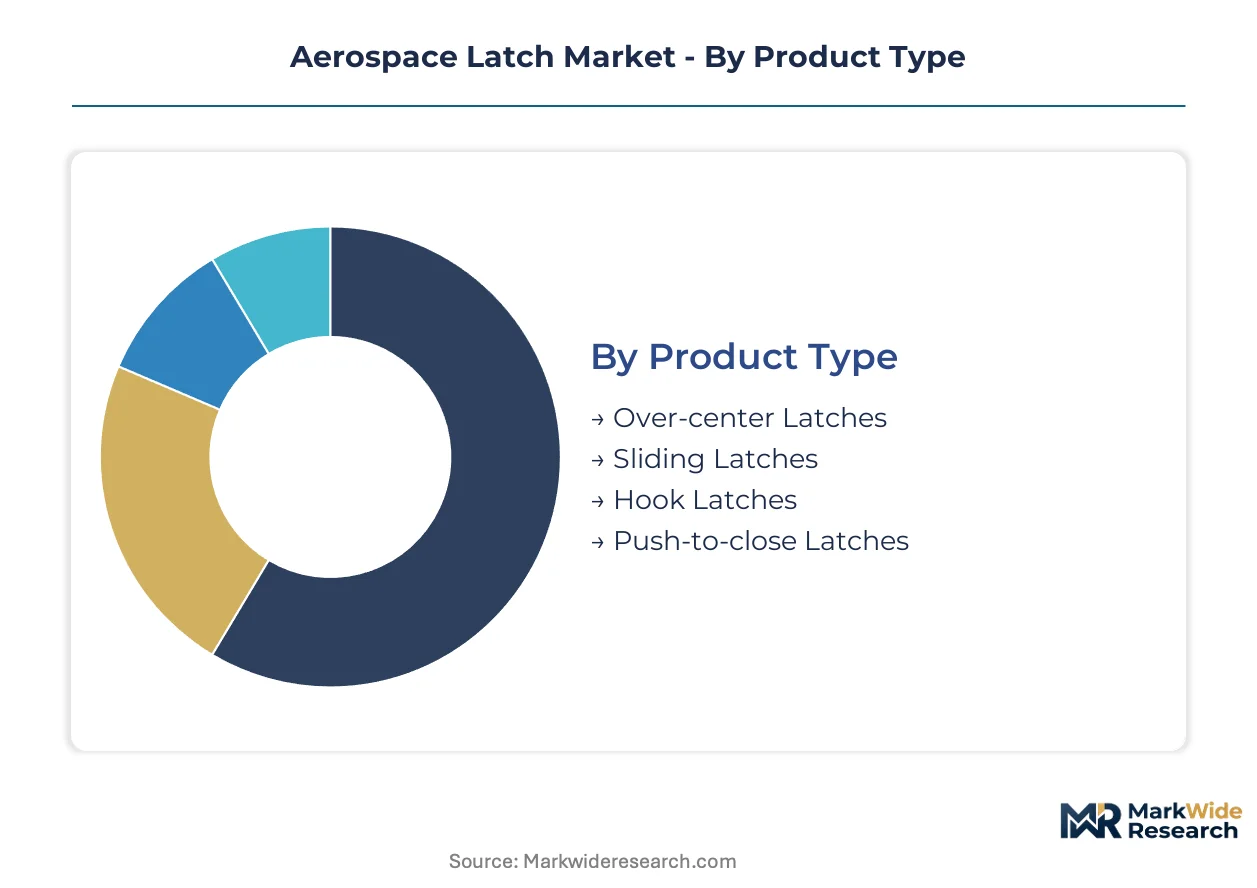
Aerospace latch segmentation reveals how certification tiers, material specifications, and procurement channels fragment a concentrated supplier base. Each dimension carries distinct margin structures and qualification barriers that reshape competitive positioning across commercial and defense programs.
Product Type:
Mature mechanical designs dominate installed bases while ergonomic innovations capture specification shifts in cabin retrofits and next-generation platforms.
- Over-center Latches:Positive mechanical locking with visual verification remains the default for external access panels on narrow-body commercial aircraft. Boeing's supplier base in the United States drives concentrated procurement for these flight-critical installations. Over-center designs handle the majority of throughput; push-to-close variants are the fastest mover on share.
- Push-to-close Latches:Single-action operation reduces ground crew fatigue and maintenance turnaround times. Airlines with centralized procurement functions specify these for cabin interior retrofits at accelerating rates. AS9100-certified manufacturers command premium positioning for ergonomic variants.
- Sliding Latches:Compact envelope suits confined spaces in avionics bays and auxiliary power unit compartments. Military-spec programs retain legacy sliding mechanisms for field-repair compatibility.
- Hook Latches:Simplified geometry serves non-structural applications where load ratings remain below pressure differential thresholds. Aftermarket distributors stock hook variants for non-critical access hardware replacement.
Over-center latches handle the majority of throughput; push-to-close variants are the fastest mover on share.
Material:
Substrate selection tracks airframe evolution, with legacy metal alloys defending structural applications while polymer-compatible designs penetrate composite-intensive platforms.
- Stainless Steel:Precipitation-hardened grades deliver fatigue resistance exceeding one million cycles for flight-critical installations. FAA airworthiness directives mandate extensive lot acceptance testing for stainless formulations, sustaining premium pricing for qualified suppliers.
- Aluminum:Aerospace-grade alloys with anodized surface treatments balance weight reduction against galvanic compatibility. LISI Aerospace leverages in-house forging capacity to control aluminum latch production vertically.
- Composite:Carbon-fiber-reinforced polymers match thermal expansion coefficients with next-generation airframe substrates. Boeing and Airbus programs specify composite-compatible latches for access panels on composite-intensive fuselage sections.
- Plastic:Injection-molded engineering polymers serve interior applications where fire-smoke-toxicity ratings supersede structural load requirements. Cabin retrofit programs drive specification shifts toward color-matched plastic hardware.
Stainless steel commands the highest certification premiums; composite substrates are expanding most quickly as airframe materials migrate.
End User:
Procurement authority fragments across build-phase OEMs, in-service MRO networks, and authorized distribution channels with divergent technical requirements.
- Aerospace OEMs:Boeing and Airbus airframe programs specify flight-critical latches at original equipment build, embedding suppliers for program life cycles. Long-term agreements lock in volume commitments across narrow-body production ramps.
- Tier-1 Suppliers:Spirit AeroSystems and other aerostructures contractors procure latch assemblies for subsystems integration. AS9100 traceability requirements flow down through supplier tiers.
- Maintenance Providers:Global MRO networks source replacement latches through authorized distribution to maintain airworthiness documentation. Southco's channel density positions it for aftermarket capture.
- Distributors:Independent stocking distributors serve legacy aircraft programs where OEM direct procurement has lapsed. Inventory localization determines competitive positioning for AOG support contracts.
OEMs concentrate design authority; maintenance providers represent the fastest-expanding procurement volume as fleet ages deepen.
Design Standard:
Certification tier determines addressable market scope, with flight-critical approvals enabling defense and commercial aerospace participation while quality-only standards restrict suppliers to industrial applications.
- FAA Approved:Part 25 airworthiness certification enables installation on transport-category aircraft. FAA airworthiness directives govern fatigue testing protocols and traceability documentation.
- Military Spec:MIL-PRF-5425 governs quick-access fasteners for defense platforms with dual-use commercial applications. Hartwell Corporation anchors its positioning through military-spec specialization.
- AS9100:Aerospace quality management standard tightens supplier audit frequencies and lot acceptance criteria. AS9100 certification functions as a de facto entry barrier for flight-critical programs.
- ISO 9001:General quality management standard serves non-flight-critical industrial aerospace applications. Lower compliance burden attracts price-competitive suppliers excluded from certified tiers.
FAA and military specifications concentrate premium procurement; AS9100 certification is climbing the fastest as quality mandates tighten across supplier bases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aerospace latch procurement concentrates where airframe OEMs and Tier-1 aerostructures contractors cluster. Boeing's supplier base in the United States generates the dominant share of flight-critical hardware demand, while European and Asian manufacturing hubs expand their certified supplier footprints.
United States
Boeing's narrow-body production ramp in Washington and South Carolina drives concentrated latch procurement from AS9100-certified suppliers. FAA airworthiness directives govern fatigue testing protocols for precipitation-hardened stainless steel formulations. Wichita's dense network of aerostructures contractors sustains pull for quick-access hardware across commercial and defense programs.
France
Airbus final assembly lines in Toulouse and Hamburg-bound supply chains sustain demand for lightweight access hardware on A320 family aircraft. EASA certification requirements align with FAA Part 25 standards for transport-category installations. The country's aerospace valley around Toulouse hosts specialized fastener suppliers serving both OEM and aftermarket channels.
Germany
Premium aerostructures production for Airbus and defense platforms generates specification-grade latch demand. REACH restrictions on cadmium plating and hexavalent chromium force surface treatment substitutions across dual-use military-commercial programs. Bavaria's precision manufacturing cluster around Munich supports high-mix, low-volume flight hardware production.
China
COMAC C919 production expansion and indigenous narrow-body programs build domestic latch qualification capacity. MIIT and CAAC certification frameworks are converging toward international airworthiness standards for structural fasteners. Shanghai's Yangtze River Delta aerospace corridor attracts joint ventures with Western fastener specialists seeking local content compliance.
India
Boeing and Airbus supplier diversification initiatives channel latch procurement toward export-qualified domestic manufacturers. The PLI scheme for aerospace components subsidizes capital investment in forging and machining capacity. Karnataka's Bengaluru-Tumkur aerospace cluster hosts Tier-2 suppliers qualifying for global OEM direct contracts.
Aerospace Latch Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. The vendor base clusters around three strategic positions: vertically integrated forgers with captive metallurgical capacity, distribution-heavy specialists capturing aftermarket volume, and defense-focused contractors with MIL-SPEC qualification depth. Competitive moves concentrate on geographic expansion into emerging aerospace manufacturing corridors and portfolio diversification toward composite-compatible latch families.
Among vertically integrated fabricators, LISI Aerospace exemplifies the forging-to-finish archetype with in-house capacity across titanium and aluminum substrate families. Hartwell Corporation occupies the military-specification specialist position, anchoring defense platform relationships through quick-access fastener expertise. Southco represents the channel-density model, competing on global distribution reach across both OEM specification and aftermarket replacement demand. These three archetypes illustrate how certification depth, manufacturing control, and logistics scale constitute alternative competitive foundations.
| Leading Market Players |
|---|
| LISI Aerospace |
| Hartwell Corporation |
| Southco |
| Actron Manufacturing |
| Triumph Group |
| Howmet Aerospace |
| Avibank |
| CAM |
| Protex |
| Others |
Supply Flow & Price Mechanics
Wichita's dense aerostructures cluster concentrates titanium forging capacity for flight-critical latch assemblies, translating upstream metallurgical control into downstream pricing power for AS9100-certified suppliers serving Boeing's narrow-body programs. This geographic concentration of qualified forgers enables premium capture on precipitation-hardened stainless steel formulations while smaller producers face margin compression from input volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange titanium indexation dominate OEM procurement for narrow-body programs. Three-tier pricing structure across flight-critical certified, AS9100 quality-grade, and industrial-standard tiers separates Boeing-approved suppliers from aftermarket distributors. Cost compression in industrial-grade latches is intensifying because REACH-forced surface treatment substitutions erode margins on legacy military hardware. Tier-1 aerostructures contractors exhibit lowest price sensitivity due to program-locked long-term agreements, while independent MRO distributors face highest sensitivity on non-critical hook latch replacements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for aerospace fastener procurement. Concentrated supply rests on titanium sponge from Japan and Kazakhstan, precipitation-hardened stainless steel from the United States and Germany, and aluminum forgings from France and the United Kingdom. Single-source vulnerability persists in FAA-qualified heat treatment facilities for fatigue-tested latch formulations. Distribution runs through authorized stocking distributors for aftermarket documentation compliance and direct OEM supply agreements for original equipment build.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composite panel substitution in next-generation airframes threatens metal latch incumbents with specification displacement, forcing defensive capability investments in polymer-compatible fastening systems.
For Market Incumbents: Insulate program positions by deepening backward integration into titanium forging capacity and accelerating composite-compatible latch qualification with Boeing and Airbus. Anchor defense against polymer fastener substitution through embedded sensor integration for predictive maintenance contracts. For New Entrants and Emerging Players: Establish a beachhead in urban air mobility battery-swap latch applications where certification frameworks remain open and incumbent qualification advantages are weakest. Target India's PLI-subsidized aerospace corridor for export-qualified manufacturing cost positioning. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated forgers with captive heat treatment and FAA fatigue-testing infrastructure over pure distribution plays. Long-term viability hinges on composite-substrate qualification timelines and additive manufacturing process certification closure. Watch for FAA powder bed fusion lot acceptance protocol finalization as inflection signal for additive-capable target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Composite-Compatible Latch Qualification | Secures specification placement on Boeing 777X and Airbus A350 composite-intensive fuselage sections. |
| Embedded Sensor Integration | Enables predictive maintenance contracts with Delta and United fleet standardization initiatives. |
| India PLI Manufacturing Alignment | Captures cost-competitive export capacity for global OEM direct contract qualification. |
| Additive Manufacturing Process Certification | Compresses prototype-to-qualification timelines for low-volume military-spec quick-access hardware. |
| Aftermarket Channel Density Expansion | Locks in recurring revenue from aging narrow-body fleet MRO replacement demand. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with procurement directors at Tier-1 aerostructures contractors, quality assurance leads at AS9100-certified forgers, and aftermarket distribution managers at global MRO networks; and secondary validation against FAA airworthiness directive filings, EASA certification databases, SEC 10-K disclosures from publicly traded fastener suppliers, and customs trade data for titanium and aerospace aluminum flows. Bottom-up build from program-level latch content and top-down triangulation against OEM production schedules anchored volume estimates.
Forecast inputs span product type evolution, material substrate migration, end-user procurement authority shifts, and design standard certification tier dynamics across the projection horizon. CAGRs derive from segmented growth rate application with cross-segment interaction effects. Industry-specific inputs include Boeing and Airbus narrow-body production ramp schedules, REACH material restriction implementation timelines, and urban air mobility platform development trajectories.
Sensitivities concentrate around FAA additive manufacturing certification protocol finalization, titanium price volatility from concentrated mining geographies, and composite airframe adoption rates that displace metal fastener counts. Forecasts reflect documented assumptions on program-level content per aircraft and fleet age-driven replacement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Impact-Resistant Composite Radome Structures for High-Bandwidth Antennas Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Global Aerospace Pressure Gauge Market
Aircraft and Aerospace Components
Germany Rotor Blade Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Spain Rotor Blade Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Multi-Foil Rotors Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
France Rotor Blade Market
Aircraft and Aerospace Components
Asia-Pacific Aircraft Band Clamps Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aerostructure Equipment Market
Aircraft and Aerospace Components
Enclosure Support Arm Systems Market
Aircraft and Aerospace Components
North America Rotor Blade Market
Aircraft and Aerospace Components
Global Aircraft Windows and Windshields Market