
 Middle East Satellite Imagery Services Market | 2026-2036
Middle East Satellite Imagery Services Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Satellite Imagery Services Market Insights
Project finance partnerships between sovereign wealth vehicles and foreign satellite operators is rewriting competitive access across the Middle East. Maxar Technologies leverages its high-resolution constellation to anchor defense contracts with Gulf military commands. Airbus SE sustains dual-use positioning through its Pleiades Neo capacity serving both European export protocols and regional security frameworks. Bayanat differentiates via its AI-native geospatial platform tailored to Emirati urban masterplans.
Middle East satellite imagery services encompass the acquisition, processing, and distribution of Earth observation data captured by orbital and sub-orbital platforms, typically delivering spatial resolutions from 30 centimeters to 30 meters depending on sensor modality and orbital altitude. These services convert raw multispectral or synthetic aperture radar signals into actionable geospatial products for terrain modeling, change detection, and asset monitoring across commercial and government workflows. Optical imagery dominates current revenue streams due to established defense procurement channels and heritage agricultural yield forecasting programs across the Levant and Gulf. Radar imagery represents the fastest-expanding service category as all-weather, day-night acquisition capability addresses pipeline security and maritime domain awareness gaps in the Arabian Sea and Strait of Hormuz. Data processing and geospatial analysis technology layers command disproportionate margin pools relative to raw imagery licensing, reflecting customer preference for finished intelligence over unprocessed pixels.
The UAE Space Agency and Saudi Communications and Information Technology Commission shape operator licensing, spectrum allocation, and data sovereignty requirements across their respective jurisdictions. Egypt's National Authority for Remote Sensing and Space Sciences complements this framework through Nile Basin monitoring standards that regulate cross-border imagery distribution. Stakeholders must monitor how national space legislation evolves around foreign ownership thresholds and classified imagery handling protocols as sovereign capabilities mature.
Market Dynamics
Sovereign space capability investments across Gulf Cooperation Council states are compressing procurement timelines for foreign satellite operators while mandating domestic data processing infrastructure. This structural force is redrawing competitive access rules and margin capture across the value chain.
Growth Catalysts
- Defense procurement acceleration:Gulf military commands are expanding geospatial intelligence platform budgets under national security frameworks. Saudi Arabia's defense modernization programs specify high-resolution terrain mapping for corridor infrastructure.
- AI-native processing platforms:Machine learning pipelines for automated feature extraction are reducing analyst labor costs. Emirati urban masterplans now require AI-augmented change detection for construction compliance monitoring.
- NEOM giga-project corridor:Linear infrastructure planning across Saudi Arabia's northwest development zone demands sub-meter resolution stereo imagery. This concentration is pulling dedicated satellite capacity allocation from commercial operators.
Market Restraints
- Launch cost volatility:Proton and Soyuz capacity constraints following geopolitical realignment have elevated orbital insertion pricing. Operators dependent on Russian launch services face 40-60% cost escalation for replacement rideshare options.
- Sensor supply concentration:High-resolution optical focal plane arrays concentrate among three European and US component suppliers. Any export control tightening immediately propagates through downstream imagery service pricing.
- Data sovereignty mandates:UAE Space Agency ground segment localization requirements force foreign operators to establish domestic processing facilities. This capital burden filters smaller regional competitors from licensed operator status.
Strategic Opportunities
- Egyptian Nile Basin monitoring:Cross-border water security applications remain underpenetrated despite established regulatory frameworks. The National Authority for Remote Sensing and Space Sciences standards create compliant pathways for regional operators.
- Synthetic aperture radar convergence:All-weather pipeline security monitoring is hybridizing with IoT sensor networks for real-time leak detection. This convergence opens subscription-based monitoring contracts beyond traditional imagery licensing.
- Maritime domain awareness gaps:Strait of Hormuz vessel tracking applications lack sufficient revisit frequency from current commercial constellations. Dedicated microsatellite constellations for AIS-correlated SAR imaging address this white space.
Industry Challenges
- Geospatial analyst talent scarcity:Spectral signature interpretation and stereo compilation expertise concentrates among defense-trained personnel. Commercial operators compete with government security clearance requirements for this limited labor pool.
- Legacy system integration friction:Defense customer geographic information systems operate on classified networks with proprietary data formats. Foreign operators must rebuild processing pipelines for each national security architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Satellite Imagery Services Market |
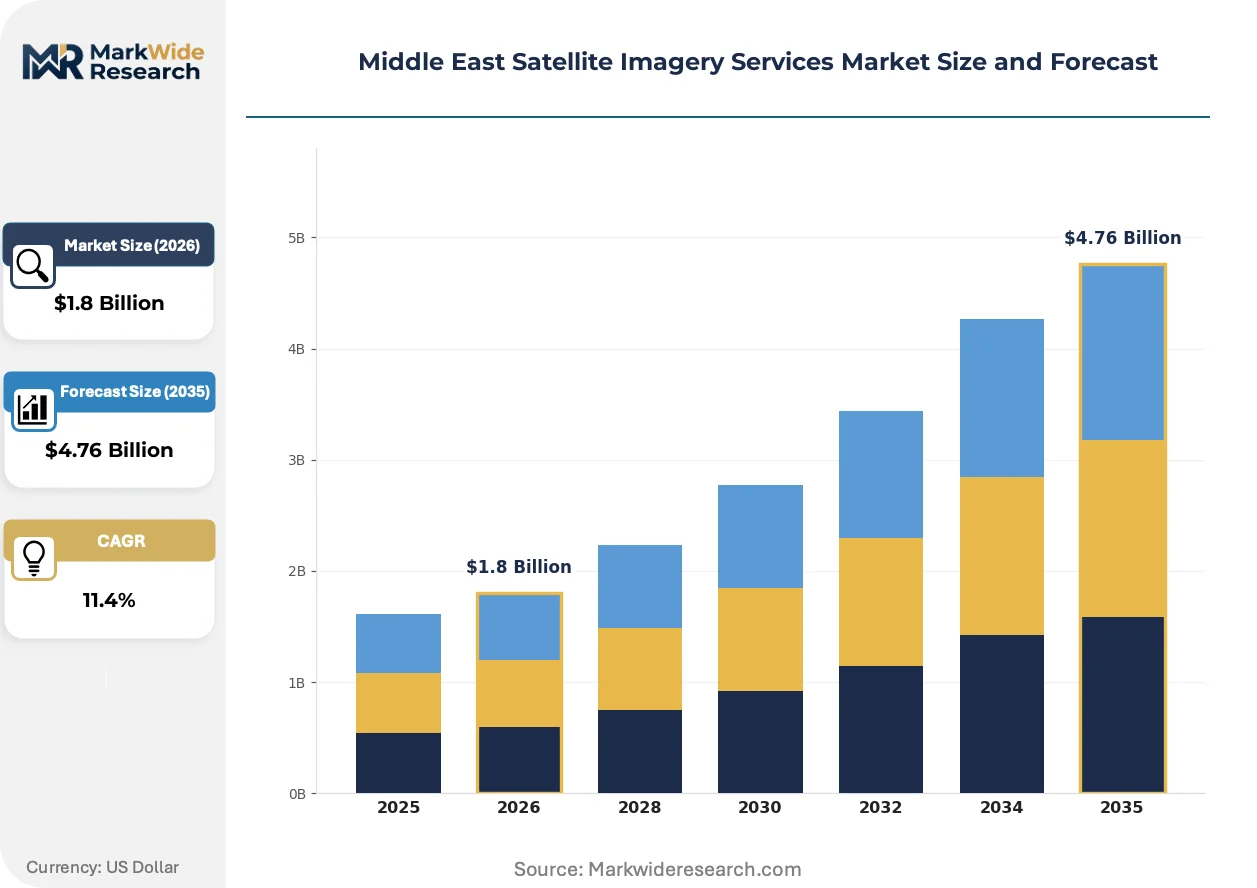
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Optical Imagery, Radar Imagery, Hyperspectral Imagery, LiDAR End User: Agriculture, Defense, Urban Planning, Environmental Monitoring Technology: Satellite-Based, Aerial-Based, Geospatial Analysis, Data Processing Application: Disaster Management, Resource Management, Infrastructure Development, Security Surveillance |
| Companies Covered | SARsat Arabia, Maxar Technologies, Airbus SE, Serco Group plc, Northstar Saudi Arabia, Thales Group, Al Yah Satellite Communications Company PJSC, Bayanat, Space Imaging Middle East, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Satellite Imagery Services Market Trends and Innovations
Multi-sensor fusion architectures are displacing single-modality acquisition contracts across Middle East defense and infrastructure verticals. This shift is compressing pricing power for pure-play optical operators while elevating integrated analytics providers.
Hyperspectral imaging systems are hybridizing with synthetic aperture radar platforms to deliver material identification capabilities through cloud cover. Saudi agricultural ministries are adopting these fused products for groundwater stress monitoring at 30-meter spatial resolution. The structural consequence is collapsing the historical premium for cloud-free optical revisit guarantees.
UAE Space Agency orbital debris mitigation guidelines are mandating end-of-life propulsion systems for all licensed commercial satellites. This regulation is elevating capital requirements for constellation operators while creating maintenance service opportunities for regional ground segment providers. Smaller microsatellite ventures without propulsion budgets are exiting the licensing queue.
Subscription-based analytics contracts are displacing per-scene imagery licensing across Gulf state infrastructure authorities. Saudi giga-project developers now specify guaranteed change detection alerts rather than raw pixel delivery. This behavioral shift concentrates procurement authority with integrated platform vendors and marginalizes pure data resellers.
Middle East Satellite Imagery Services Market Segmentation
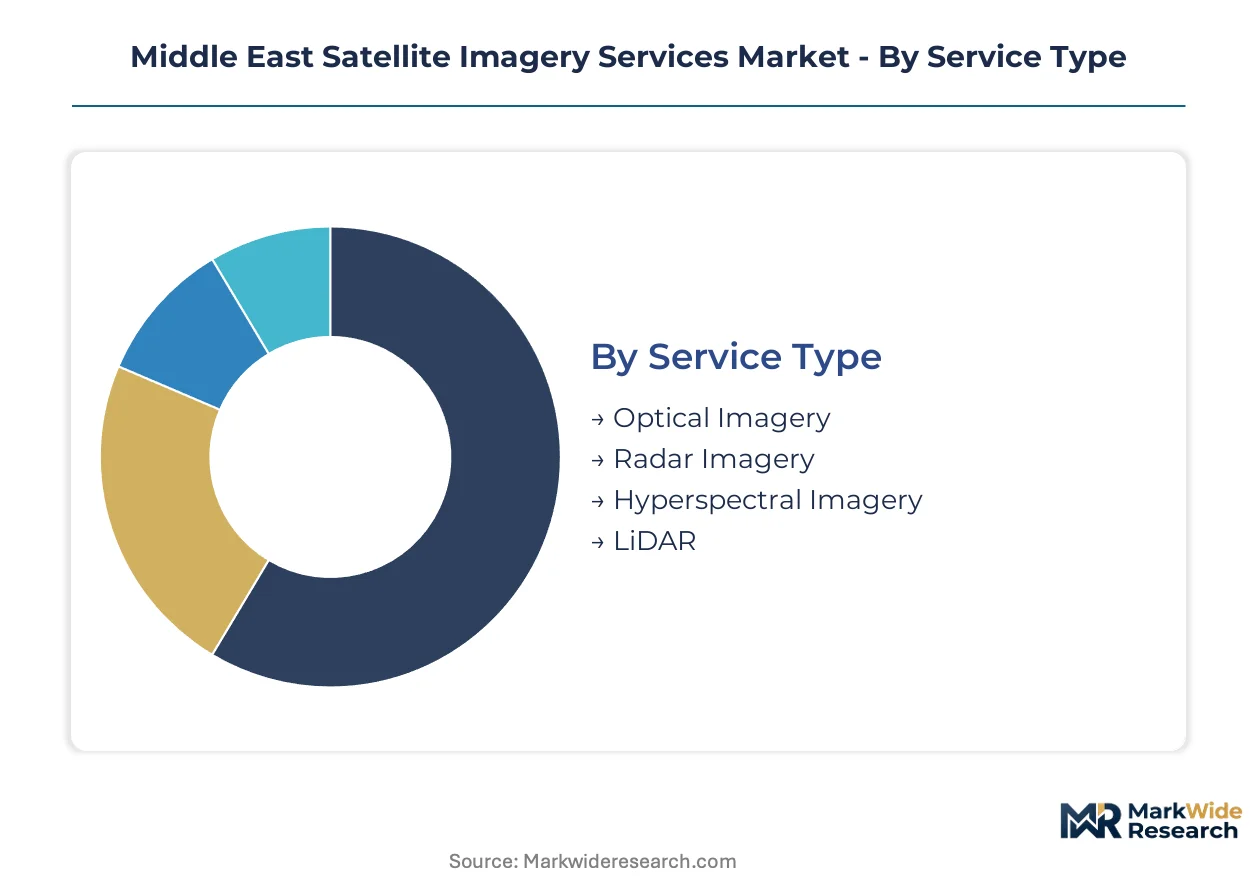
Service differentiation across acquisition modality, end-use vertical, and processing depth determines pricing power and contract duration in Middle East satellite imagery markets. Procurement patterns reveal concentration in defense-grade optical solutions while emerging radar and hyperspectral capabilities reshape competitive positioning.
Service Type:
Maturity varies sharply across acquisition modalities, with optical platforms commanding established procurement channels while newer sensor technologies penetrate specialized use cases.
- Optical Imagery:Multispectral and panchromatic sensors deliver spatial resolutions from 30 centimeters to 5 meters depending on orbital altitude and aperture size. Defense ministries across Saudi Arabia and the UAE anchor procurement through multi-year geospatial intelligence contracts, with NEOM infrastructure planners specifying sub-meter stereo pairs for terrain modeling.
- Radar Imagery:Synthetic aperture radar systems penetrate cloud cover and darkness using active microwave illumination, enabling all-weather pipeline monitoring across the Arabian Peninsula. Maritime security commands in the Strait of Hormuz drive demand for vessel detection and oil spill identification regardless of atmospheric conditions.
- Hyperspectral Imagery:Contiguous narrow spectral bands enable material identification and mineral composition mapping for Saudi agricultural groundwater stress assessment.
- LiDAR:Active laser ranging generates high-density elevation models for UAE urban masterplan flood risk assessment and coastal engineering.
Optical Imagery retains volume leadership; Radar Imagery holds the steepest expansion curve.
End User:
Customer type determines contract structure, with sovereign entities demanding localized processing while commercial developers accept standardized delivery terms.
- Defense:Military geospatial intelligence platforms require classified handling protocols and domestic ground segment infrastructure. Gulf Cooperation Council states mandate foreign operators establish sovereign data processing facilities to satisfy national security frameworks.
- Urban Planning:Masterplan authorities in Dubai and Riyadh specify AI-augmented change detection for construction compliance rather than raw pixel delivery, compressing procurement timelines for integrated analytics vendors.
- Agriculture:Saudi ministries deploy fused hyperspectral-radar products for irrigation optimization across desert reclamation zones.
- Environmental Monitoring:Egyptian Nile Basin water security applications remain underpenetrated despite established regulatory pathways through the National Authority for Remote Sensing and Space Sciences.
Defense commands the largest contract values; Urban Planning demonstrates the most rapid procurement model evolution.
Technology:
Platform altitude and processing depth stratify margin capture, with orbital assets delivering scale and aerial systems addressing precision requirements.
- Satellite-Based:Constellation operators provide systematic global coverage with revisit frequencies from multiple times daily to bi-weekly depending on orbital configuration. UAE Space Agency licensing mandates end-of-life propulsion systems, elevating capital barriers for new entrants.
- Geospatial Analysis:Machine learning pipelines for automated feature extraction and change detection command premium pricing over raw imagery licensing. Subscription-based analytics contracts displace per-scene sales across Gulf infrastructure authorities.
- Aerial-Based:Manned and unmanned aircraft deliver centimeter-resolution photography for localized engineering surveys where orbital timing proves insufficient.
- Data Processing:Cloud-native platforms normalize spectral calibration and orthorectification workflows, reducing analyst labor costs for high-volume production environments.
Satellite-Based platforms dominate addressable market scope; Geospatial Analysis captures the highest margin expansion.
Application:
Use case urgency shapes pricing tolerance, with security-critical applications accepting premium rates while developmental planning operates on extended procurement cycles.
- Security Surveillance:Border monitoring and critical infrastructure protection require guaranteed availability service levels with rapid tasking response. Saudi Aramco pipeline operators specify maximum four-hour delivery windows for anomaly detection alerts.
- Infrastructure Development:Linear corridor planning across NEOM and Red Sea Project zones demands dedicated satellite capacity allocation with guaranteed stereo coverage. Giga-project developers now contract for finished intelligence products rather than unprocessed imagery archives.
- Disaster Management:Flood and seismic event response leverages international charter mechanisms for no-cost emergency acquisition, limiting commercial revenue potential.
- Resource Management:Groundwater and mineral extraction monitoring combines historical trend analysis with real-time extraction compliance verification.
Security Surveillance maintains the highest contract renewal rates; Infrastructure Development shows the strongest volume trajectory from megaproject pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in satellite imagery services tilt toward foreign constellation operators supplying Gulf defense commands, while domestic ground segment providers capture processing value. Sovereign data localization mandates are reversing this flow by mandating in-country infrastructure investment.
Saudi Arabia
Defense modernization programs and NEOM linear infrastructure anchor procurement volumes for high-resolution terrain mapping. The Communications and Information Technology Commission enforces data sovereignty frameworks requiring domestic processing nodes. Riyadh and the northwest development corridor concentrate demand from giga-project developers contracting for finished intelligence products.
United Arab Emirates
Urban masterplan authorities in Dubai and Abu Dhabi specify AI-augmented change detection for construction compliance monitoring. UAE Space Agency licensing mandates end-of-life propulsion systems and ground segment localization for all commercial operators. Dubai's satellite ground station cluster hosts foreign operators establishing sovereign data processing facilities.
Egypt
Nile Basin water security applications remain underpenetrated despite established cross-border monitoring standards. The National Authority for Remote Sensing and Space Sciences regulates imagery distribution across riparian states. Cairo anchors public sector demand for agricultural yield forecasting and flood risk assessment products.
Israel
Maritime domain awareness gaps in the Eastern Mediterranean drive demand for vessel detection and coastal surveillance capabilities. National security frameworks restrict foreign operator access to classified processing contracts. Haifa's defense technology corridor concentrates domestic geospatial intelligence platform development.
Qatar
Critical infrastructure protection for hydrocarbon export facilities requires guaranteed availability service levels with rapid tasking response. The national communications regulator shapes spectrum allocation for commercial satellite operators. Doha's energy sector procurement specifies all-weather radar monitoring for pipeline security.
Middle East Satellite Imagery Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying focal plane arrays and propulsion systems. Market structure tilts toward consolidated foreign operators with heritage defense contracts, while domestic licensing requirements filter smaller regional competitors. Three archetypes dominate: constellation operators with global coverage, AI-native analytics platforms, and sovereign ground segment providers. Competitive moves concentrate on strategic partnerships with sovereign wealth vehicles and capacity reservation agreements for giga-project corridors.
Among foreign constellation operators, Maxar Technologies and Airbus SE exemplify the defense-contractor archetype, leveraging high-resolution optical capacity to anchor multi-year geospatial intelligence agreements with Gulf military commands. Bayanat occupies a distinct position as an AI-native platform provider tailored to Emirati urban masterplan requirements.
| Leading Market Players |
|---|
| SARsat Arabia |
| Maxar Technologies |
| Airbus SE |
| Serco Group plc |
| Northstar Saudi Arabia |
| Thales Group |
| Al Yah Satellite Communications Company PJSC |
| Bayanat |
| Space Imaging Middle East |
| Others |
Pricing and Supply Chain Analysis
European focal plane array manufacturers in France and Germany anchor upstream component supply, concentrating margin capture with downstream operators that control AI-native processing layers and subscription-based analytics delivery. Defense procurement offices in Riyadh and Abu Dhabi absorb cost escalation through multi-year geospatial intelligence contracts, while commercial infrastructure developers face sharper price sensitivity for raw imagery licensing.
Pricing Analysis
Defense ministry buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Premium tiers attach AI-augmented change detection and guaranteed tasking response to high-resolution optical capacity; standard tiers deliver processed archives without analyst support; economy tiers offer unprocessed pixels with delayed delivery windows. Price differentiation rests on sensor resolution grade and domestic ground segment certification status. Cost compression in economy-tier raw licensing is intensifying because sovereign data localization mandates force foreign operators to fund domestic processing facilities. Commercial giga-project developers exhibit the highest price sensitivity, while Gulf military commands accept premium rates for classified handling protocols.
Supply Chain Analysis
Tariff exposure between European component suppliers and Gulf assembly facilities dominates supply chain risk assessment for satellite imagery services. High-resolution optical focal plane arrays concentrate in France, Germany, and the United States; synthetic aperture radar subsystems draw from Italian and Israeli specialist manufacturers; launch services rest on French Guiana and emerging Indian capacity. Raw material dependencies include germanium substrates for infrared sensors, gallium arsenide for radar transmitters, and specialized aluminum-lithium alloys for satellite bus structures. Single-source vulnerability persists for sub-meter resolution optical sensors subject to export control tightening. Distribution runs through sovereign-licensed ground stations in Dubai, Riyadh, and Cairo before final analytics delivery to defense and infrastructure end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based geospatial analytics contracts are expanding faster than raw imagery hardware licensing, creating a service-attach opportunity where recurring revenue layers command margin premiums over transactional pixel sales.
For Market Incumbents: Pre-empt margin compression in pure-play optical licensing by securing exclusive capacity reservation agreements for Saudi giga-project corridors. Anchor defensive positioning through backward integration into AI-native processing pipelines that automated feature extraction demands. The threat of domestic sovereign constellation launches by UAE and Saudi space agencies accelerates timeline pressure for foreign operators to deepen local partnership structures. For New Entrants and Emerging Players: Egyptian Nile Basin water security applications represent the most penetrable geographic white space despite established regulatory pathways through the National Authority for Remote Sensing and Space Sciences. Maritime domain awareness gaps in the Strait of Hormuz offer a second entry vector where dedicated microsatellite constellations address insufficient revisit frequency from incumbent operators. A compliance-first go-to-market angle leveraging existing cross-border monitoring standards accelerates licensing velocity versus direct competition with entrenched defense contractors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed geospatial analytics platforms that have scaled AI processing layers but lack sovereign ground segment infrastructure in Gulf markets. Long-term viability over a five-to-ten-year window favors operators with dual-use positioning across European export protocols and regional security frameworks. The acquisition target archetype combines machine learning pipelines with established UAE Space Agency licensing status. Watch for inflection signals in Saudi Communications and Information Technology Commission enforcement patterns around foreign ownership thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Platform Integration | Machine learning pipelines for automated feature extraction reduce analyst labor costs at Bayanat and comparable operators. |
| Sovereign Ground Segment Expansion | Domestic processing facilities in Dubai satisfy UAE Space Agency data localization mandates for foreign constellation operators. |
| Capacity Reservation Agreements | Dedicated satellite allocation for NEOM linear infrastructure planning secures multi-year revenue visibility against spot-market volatility. |
| Hyperspectral-Radar Fusion Development | Hybrid sensor architectures address Saudi agricultural ministry groundwater monitoring requirements through cloud-penetrating material identification. |
| Maritime Microsatellite Constellation Deployment | Strait of Hormuz vessel tracking applications leverage AIS-correlated SAR imaging to close revisit frequency gaps in commercial coverage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with defense geospatial intelligence officers, commercial satellite constellation program managers, UAE Space Agency regulatory affairs leads, and Saudi giga-project infrastructure planners. Secondary validation drew from operator licensing disclosures to the UAE Space Agency and Saudi Communications and Information Technology Commission, customs records for focal plane array imports, and SEC filings from publicly traded constellation operators. Bottom-up demand aggregation across defense, urban planning, and agriculture verticals was triangulated against top-down market sizing from satellite capacity supply estimates.
Calibration across the projection horizon employed scenario-weighted CAGRs reflecting defense procurement acceleration versus launch cost volatility risks. Segmentation dimensions modeled include acquisition modality, end-use vertical, processing depth, and national regulatory jurisdiction. CAGRs were derived from fitted growth curves anchored to documented capacity expansion timelines and sovereign investment program announcements. Industry-specific forecast inputs incorporated orbital debris mitigation compliance costs and AI processing platform adoption curves observed in Emirati urban masterplan procurement.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sovereign-backed domestic constellation operators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Satellite
VSAT Maritime Satellite Communication Market
Satellite
Medium and Large Satellite Market
Satellite
Satellite Transponder Market
Satellite
China Satellite Connectivity Market
Satellite
Eastern Europe and North Africa Satellite Communication Market
Satellite
Reconnaissance Satellite Market
Satellite
Military Satellite Market
Satellite
Brazil Satellite Imagery Services Market
Satellite
Satellite Communication Subsystem Market
Satellite
Satellite Gateway Market
Satellite
North America Satellite Manufacturing Market
Satellite
Nano and Microsatellite Market
Satellite
China Satellite Communication Market
Satellite
Asia-Pacific Satellite Connectivity Market
Satellite
Satellite Signal Meter Market
Satellite
LEO and GEO Satellite Market