
 Drone Wireless Charging Station Market | 2026-2036
Drone Wireless Charging Station Market Size, Share, and Industry Trends Forecast 2026-2036
Drone Wireless Charging Station Market Insights
IEC 62368-1 safety certification for wireless power transfer is reorganizing competitive entry in the drone charging sector. WiBotic leverages its early certification pathway to anchor North American supply relationships for defense and industrial clients. Heisha Technology dominates Asia-Pacific manufacturing scale through Shenzhen-based production facilities that sustain cost advantages in resonant charging hardware.
A drone wireless charging station transfers electrical energy to unmanned aerial vehicles without physical contact, typically operating at frequencies between 6.78 MHz and 13.56 MHz for resonant inductive systems and achieving 85-93% end-to-end efficiency in optimized configurations. Its primary purpose is eliminating manual battery swap labor and enabling continuous autonomous operations for commercial and military drone fleets. Resonant charging occupies the largest installed base due to its tolerance for coil misalignment during landing, while laser charging represents the fastest-growing category despite atmospheric attenuation constraints because it offers the highest power density for extended-range applications. Deployment through autonomous platforms concentrates margin pools where integrated perception and precision landing systems command premium pricing from logistics providers and utility inspectors.
FAA Part 107 remote identification requirements and EU drone regulation framework standards from EASA jointly shape product design by mandating traceable operational infrastructure for beyond-visual-line-of-sight missions. IEC electromagnetic compatibility standards further gate market access by specifying emission limits that charging stations must satisfy during concurrent data-link operations. Stakeholders must monitor evolving frequency allocation rulings from national regulators and decide whether to architect multi-standard hardware or specialize in single-territory certification pathways.
Market Dynamics
FAA Part 107 remote ID mandates are compressing deployment timelines for certified charging infrastructure across commercial drone operations. Defense procurement of autonomous fleet systems is simultaneously pulling capital toward hardened, interoperable station architectures.
Growth Catalysts
- Defense Autonomous Fleet Procurement:Military operators across the United States, United Kingdom, and Australia are mandating wireless charging compatibility for next-generation UAV tenders, creating locked-in demand for IEC 62368-1 certified hardware.
- Precision Agriculture Automation:Automated crop monitoring corridors in the American Midwest require continuous drone uptime that only resonant inductive systems can deliver without manual battery swap labor.
- EU Drone Regulation Framework:EASA standards for beyond-visual-line-of-sight missions are forcing operators toward traceable charging infrastructure that satisfies electromagnetic compatibility requirements for concurrent data-link operations.
Market Restraints
- Copper and Ferrite Input Volatility:Resonant coil assemblies depend on ferrite core supplies concentrated in Chinese processing facilities, exposing hardware margins to raw material price swings and export control friction.
- Atmospheric Attenuation Limits:Laser charging systems face fundamental physics constraints in humid or dusty environments, restricting deployable geography for the highest power-density category.
- Frequency Allocation Uncertainty:National regulators in Germany, Japan, and South Korea maintain divergent rulings on 6.78 MHz versus 13.56 MHz operational bands, fragmenting hardware certification pathways and delaying multi-territory product launches.
Strategic Opportunities
- Utility Inspection Scale Deployment:Power grid operators in Texas, California, and Florida are piloting autonomous drone nests with integrated wireless charging for continuous transmission line monitoring, opening recurring service revenue streams.
- Resonant-Laser Hybrid Architectures:Convergence of near-field inductive landing pads with directed-energy topping-off systems enables tiered power delivery that matches mission duration to energy transfer mode.
- Indian PLI Scheme Alignment:Domestic manufacturing incentives for electronics hardware are attracting resonant charging assembly investments to serve South Asian agricultural and surveillance demand without import duty exposure.
Industry Challenges
- RF Engineering Talent Scarcity:Optimized coil design for 85-93% end-to-end efficiency requires specialized expertise in magnetic resonance physics that outpaces current university pipeline output.
- IEC 62368-1 Certification Timelines:Safety validation for wireless power transfer systems averages 14-18 months, compressing product refresh cycles and freezing engineering resources on legacy platform maintenance.
- Legacy Fleet Retrofit Complexity:Existing commercial UAVs lack standardized power reception coils, forcing charging station vendors to maintain multi-protocol hardware or abandon installed base capture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drone Wireless Charging Station Market |
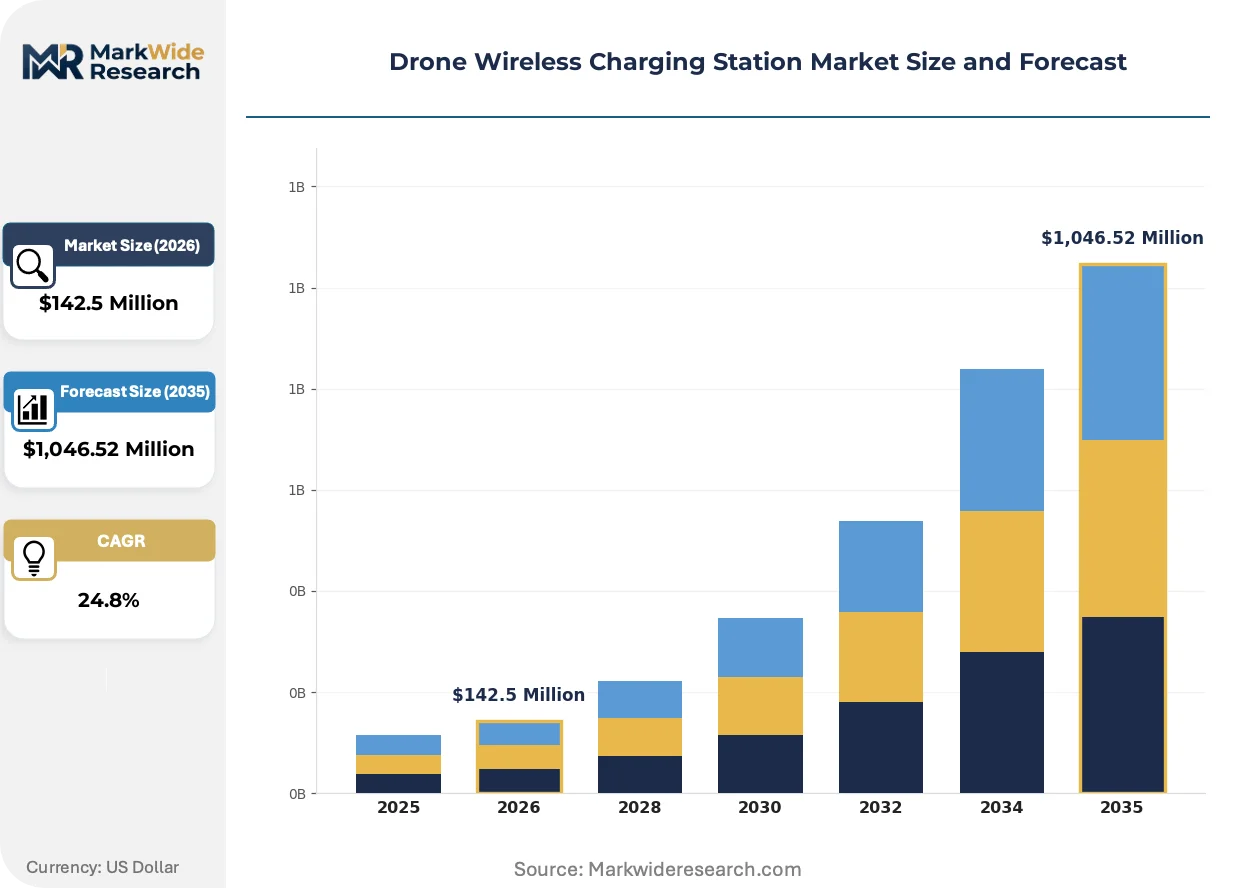
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $1,046.52 Million |
| CAGR (2026 – 2036) | 24.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inductive Charging, Resonant Charging, Radio Frequency Charging, Laser Charging, Capacitive Charging Application: Surveillance, Delivery, Agriculture Monitoring, Infrastructure Inspection, Environmental Research Deployment: Fixed Station, Mobile Unit, Integrated Drone Docking, Portable Setup, Autonomous Platform End User: Defense Sector, Logistics Providers, Precision Farming Operators, Utility Inspectors, Scientific Institutions |
| Companies Covered | WiBotic, Heisha Technology, Skycharge, DJI, Witricity, Skysense, PowerUp Technologies, H3 Dynamics, Airobotics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drone Wireless Charging Station Market Trends and Innovations
Active frequency tuning algorithms and solid-state RF amplification are compressing system footprints while extending operational range. These advances are reshaping competitive positioning around software-defined power delivery rather than pure hardware scale.
Resonant inductive systems with dynamic impedance matching are displacing fixed-frequency architectures in precision agriculture deployments. Mid-scale farming cooperatives in Nebraska and Iowa are adopting these platforms to eliminate landing tolerance requirements. The technology is displacing manual battery swap labor as the dominant operational cost line in autonomous crop monitoring workflows.
EASA drone regulation framework standards for beyond-visual-line-of-sight operations are mandating traceable ground infrastructure with electromagnetic emission documentation. Industrial operators in Germany and France must now certify charging stations for concurrent data-link interference immunity. Logistics providers are responding by pre-qualifying only IEC-compliant hardware in fleet procurement specifications.
Power-as-a-service contracting is replacing capital equipment purchases for utility inspection fleets. Texas and Florida grid operators now lease charging infrastructure with uptime guarantees rather than owning depreciating assets. This shift concentrates vendor risk on reliability engineering while unlocking balance-sheet efficiency for drone fleet operators.
Drone Wireless Charging Station Market Segmentation
Wireless charging architectures for drone fleets fragment across power transfer physics, mission profiles, and infrastructure mobility. Each segmentation dimension carries distinct certification burdens and margin structures that reshape vendor competitive positioning.
Product Type:
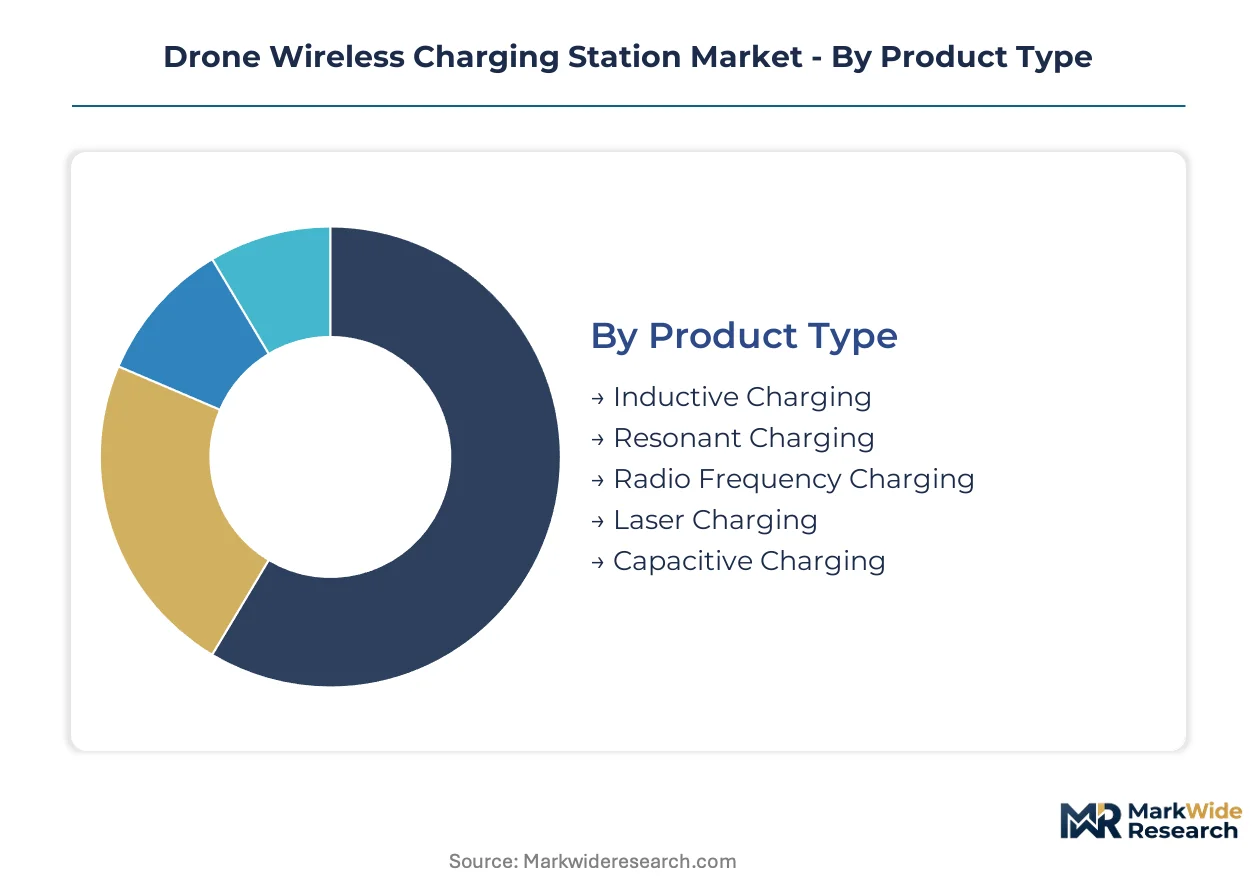
Resonant charging systems face intensifying substitution pressure from laser-based alternatives in extended-range defense applications, while inductive platforms confront margin compression from simpler capacitive designs in low-power consumer segments.
- Inductive Charging:Near-field electromagnetic coupling operates at tightly controlled coil alignment tolerances below 5 millimeters. Demand concentrates in indoor logistics facilities across Germany and Japan where precision landing infrastructure eliminates misalignment risk.
- Resonant Charging:Magnetic resonance systems tolerate coil displacement up to several centimeters through frequency-matched LC circuits. American Midwest precision farming corridors anchor demand where automated crop monitoring requires continuous drone uptime without manual battery swap labor.
- Radio Frequency Charging:Far-field power beaming at 2.4 GHz or 5.8 GHz bands enables mid-air charging for extended surveillance orbits. Regulatory fragmentation across FCC, ETSI, and ARIB emission limits constrains multi-territory deployment.
- Laser Charging:Directed-energy systems deliver the highest power density for military beyond-visual-line-of-sight missions. Atmospheric attenuation in humid climates restricts addressable geography despite defense procurement pull.
- Capacitive Charging:Electric field coupling through paired conductive plates suits small-form-factor commercial drones with sub-100-watt power requirements. Cost advantages in Asian manufacturing clusters sustain penetration in price-sensitive consumer segments.
Resonant charging retains volume leadership; laser charging holds the steepest expansion curve.
Application:
Cost tier differentiation separates capital-intensive infrastructure inspection deployments from recurring-revenue surveillance contracts, with agriculture monitoring occupying a mid-tier equipment ownership model.
- Surveillance:Continuous perimeter monitoring for defense installations and critical infrastructure demands 99.9% uptime guarantees. Power-as-a-service contracting in Texas and Florida concentrates vendor risk on reliability engineering while unlocking balance-sheet efficiency for fleet operators.
- Delivery:Last-mile logistics networks in urban corridors require rapid turnaround charging at distributed nodes. FAA Part 107 remote ID mandates compress deployment timelines for certified charging infrastructure across commercial drone operations.
- Agriculture Monitoring:Automated crop scouting workflows in Nebraska and Iowa displace manual battery swap labor as the dominant operational cost line. Resonant systems with dynamic impedance matching eliminate landing tolerance requirements for cooperative farming operations.
- Infrastructure Inspection:Power grid operators in California pilot autonomous drone nests with integrated wireless charging for continuous transmission line monitoring. Recurring service revenue streams replace capital equipment purchases.
- Environmental Research:Scientific institutions deploy portable charging architectures for remote ecosystem monitoring in protected wilderness areas. Limited grid access privileges energy-harvesting hybrid systems over pure wireless transfer.
Infrastructure inspection commands premium pricing; delivery networks are expanding most quickly.
Deployment:
Customer type stratification distinguishes defense procurement of hardened autonomous platforms from logistics providers seeking flexible mobile units with rapid redeployment capability.
- Fixed Station:Permanent installations at distribution centers and military bases anchor high-utilization fleet operations. EASA electromagnetic compatibility standards mandate traceable ground infrastructure with emission documentation for beyond-visual-line-of-sight missions.
- Mobile Unit:Trailer-mounted or vehicle-integrated systems enable forward operating base resupply and emergency response scenarios. Australian defense tenders specify interoperable architectures for expeditionary UAV support.
- Integrated Drone Docking:Combined landing, charging, and data offload stations command premium pricing from utility inspectors and logistics providers. Perception and precision landing systems integrate at the enclosure level.
- Portable Setup:Rapidly deployable charging pads suit scientific fieldwork and temporary event security. Weight constraints favor capacitive and radio frequency architectures over resonant coil assemblies.
- Autonomous Platform:Self-positioning charging stations with robotic alignment systems serve fully unmanned operations. Software-defined power delivery with active frequency tuning algorithms compresses system footprints while extending operational range.
Fixed stations retain volume leadership; autonomous platforms are gaining share fastest.
End User:
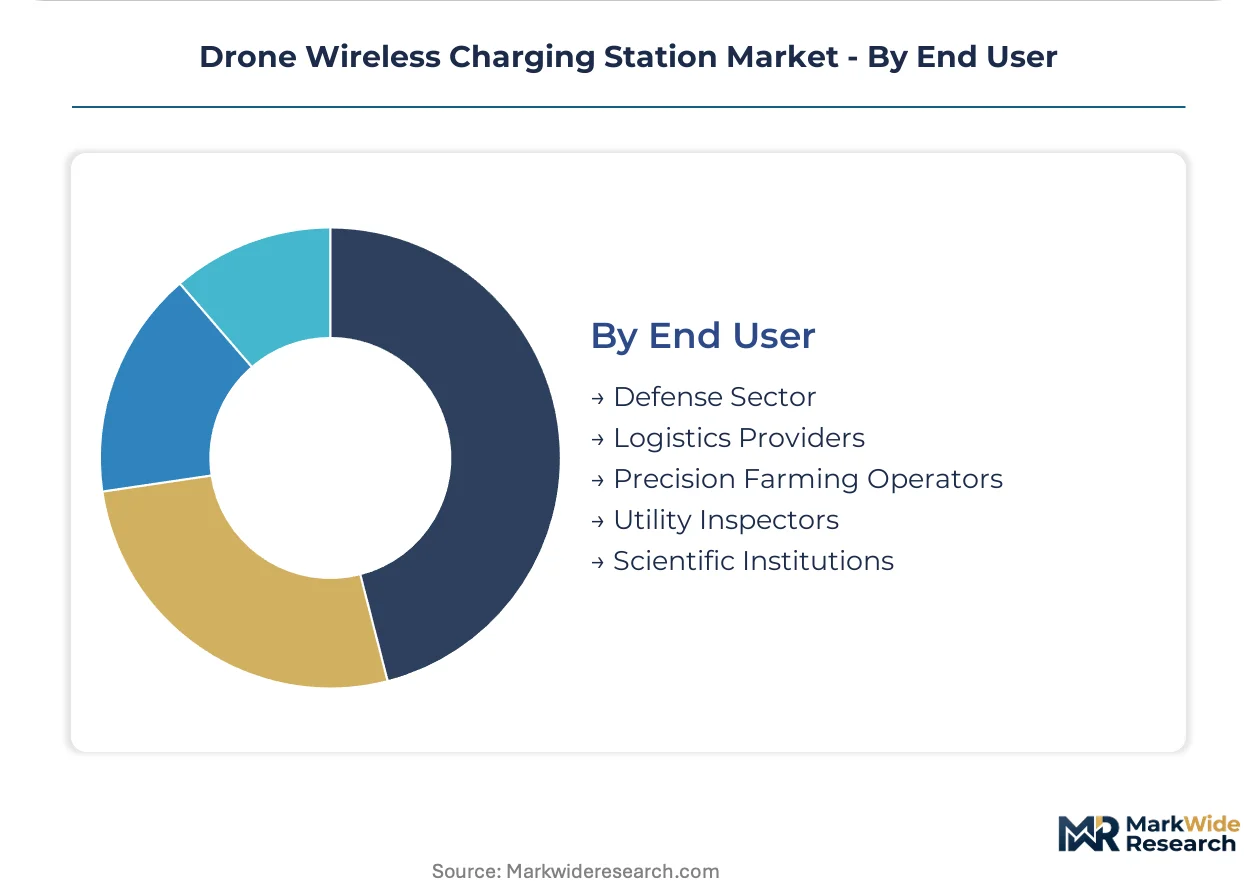
Supply concentration in resonant coil manufacturing shapes margin distribution across end-user segments, with defense sector procurement pulling capital toward hardened architectures and precision farming operators driving cost-down pressure.
- Defense Sector:Military operators across the United States, United Kingdom, and Australia mandate wireless charging compatibility for next-generation UAV tenders. IEC 62368-1 certification creates locked-in demand for safety-validated hardware.
- Logistics Providers:E-commerce fulfillment networks prioritize rapid turnaround and minimal human intervention. Three-tier pricing structure across premium, standard, and economy levels matches certification grade to mission criticality.
- Precision Farming Operators:Midwest agricultural cooperatives adopt resonant inductive platforms to eliminate manual battery swap labor. Ferrite core supply concentration in Chinese processing facilities exposes hardware margins to raw material price swings.
- Utility Inspectors:Power grid operators in Texas, California, and Florida lease charging infrastructure with uptime guarantees rather than owning depreciating assets. Balance-sheet efficiency unlocks fleet scaling without capital constraint.
- Scientific Institutions:Research organizations prioritize portability and electromagnetic compatibility with sensitive instrumentation. Funding cycles favor lower-capital portable setups over integrated docking investments.
Defense sector retains volume leadership; utility inspectors hold the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The American Midwest's automated crop monitoring corridors and the Pearl River Delta's electronics manufacturing clusters anchor regional demand concentration for resonant charging hardware.
United States
Defense procurement of autonomous UAV fleets and FAA Part 107 remote ID mandates drive certified charging infrastructure deployment. The FAA mandates traceable ground infrastructure for beyond-visual-line-of-sight missions. Nebraska and Iowa farming cooperatives adopt resonant inductive platforms to eliminate manual battery swap labor in automated crop scouting workflows.
China
Shenzhen-based production facilities sustain cost advantages in resonant charging hardware manufacturing for Asia-Pacific supply. MIIT frequency allocation rulings on 6.78 MHz versus 13.56 MHz operational bands shape hardware certification pathways. The Yangtze River Delta concentrates ferrite core processing facilities that expose margins to raw material price swings.
Germany
EASA electromagnetic compatibility standards mandate traceable charging infrastructure with emission documentation for industrial drone operations. The KBA coordinates with federal regulators on frequency allocation for concurrent data-link operations. Bavaria's precision manufacturing clusters pilot IEC 62368-1 certified hardware for logistics and utility inspection applications.
Australia
Defense tenders specify interoperable wireless charging architectures for expeditionary UAV support in forward operating scenarios. The TGA framework influences electromagnetic compatibility documentation for scientific fieldwork deployments. Queensland's power grid operators pilot autonomous drone nests with integrated charging for continuous transmission line monitoring.
India
The PLI scheme for electronics hardware attracts resonant charging assembly investments to serve South Asian agricultural demand without import duty exposure. BIS safety standards gate market access for wireless power transfer systems in commercial deployments. Maharashtra's precision farming corridors adopt automated crop monitoring requiring continuous drone uptime.
Drone Wireless Charging Station Market Competitive Landscape
Listed leaders compete with private specialists across certification pathways and defense procurement channels. The vendor base organizes around early certification achievers, Asia-Pacific manufacturing scale players, and integrated platform developers. Three archetypes dominate: IEC-certified safety validators, cost-optimized resonant hardware fabricators, and autonomous docking system integrators. Competitive moves concentrate on strategic partnerships with defense contractors and capacity expansion into Indian PLI-aligned manufacturing.
Within the certification-led tier, WiBotic anchors North American supply relationships through early IEC 62368-1 pathway completion. Heisha Technology exemplifies Asia-Pacific manufacturing scale advantages through Shenzhen-based production facilities. Skycharge occupies a position among European specialists addressing EASA electromagnetic compatibility requirements for beyond-visual-line-of-sight missions.
| Leading Market Players |
|---|
| WiBotic |
| Heisha Technology |
| Skycharge |
| DJI |
| Witricity |
| Skysense |
| PowerUp Technologies |
| H3 Dynamics |
| Airobotics |
| Others |
Pricing and Supply Chain Analysis
Solid-state RF amplification replacing discrete component architectures is redrawing procurement geography toward semiconductor fabrication clusters while compressing hardware bill-of-materials costs. This substitution simultaneously weakens ferrite core pricing power in Chinese processing facilities and elevates gallium nitride foundry margins in Taiwan and South Korea.
Pricing Analysis
Certification level under IEC 62368-1 safety standards creates the primary spread between hardware tiers. Pricing stratifies across premium certified, standard compliant, and economy non-certified levels with defense procurement absorbing the top tier and agricultural cooperatives clustering in the middle. Cost compression in the economy tier is intensifying because capacitive charging alternatives from Shenzhen manufacturers undercut resonant coil assemblies on unit economics. Logistics providers exhibit the highest price sensitivity due to thin last-mile margins, while defense operators prioritize interoperability over acquisition cost.
Supply Chain Analysis
Strategic stockpiling of ferrite cores and copper litz wire now dominates inventory strategy as raw material volatility outpaces just-in-time efficiency gains. Manufacturing concentrates in China, Taiwan, and Germany with resonant coil assemblies drawing from Yangtze River Delta ferrite processing and Bavarian precision winding operations. Single-source vulnerability sits with Chinese rare earth magnet supplies for high-efficiency transmitter designs. Distribution runs through defense procurement channels, agricultural equipment dealers, and direct OEM integration contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hardware vendors should treat power-as-a-service contracting as the primary service-attach opportunity, since uptime guarantee subscriptions expand recurring revenue faster than charging station unit sales. This shift concentrates vendor risk on reliability engineering while unlocking customer balance-sheet efficiency.
For Market Incumbents: Shield installed base relationships against laser charging substitution in extended-range defense applications by accelerating IEC 62368-1 certification for hybrid resonant-laser architectures. Deepen backward integration into gallium nitride semiconductor sourcing to secure RF amplification supply against Taiwan foundry allocation constraints. Prioritize capacity addition in Indian PLI-aligned manufacturing to serve South Asian agricultural demand without import duty exposure. For New Entrants and Emerging Players: Certification fast-track through EASA electromagnetic compatibility pre-qualification opens white-space access in German and French industrial drone operations. Target utility inspection segments in Texas and Florida where power-as-a-service contracting lowers customer switching costs and accelerates fleet penetration. Pursue go-to-market partnerships with agricultural equipment cooperatives in Nebraska and Iowa to bypass entrenched dealer networks. For Investors and Strategic Acquirers: FAA Part 107 remote ID mandate enforcement reshapes the acquisition landscape by locking in demand for traceable charging infrastructure and freezing out uncertified hardware vendors. Five-to-ten year viability favors vendors with software-defined power delivery capabilities over pure hardware fabricators. Target acquisition archetypes include autonomous docking system integrators with perception and precision landing IP. Watch for frequency allocation rulings from Germany, Japan, and South Korea as the signal to monitor for multi-territory product launch viability.| Strategic Initiative | Industry Significance |
|---|---|
| IEC 62368-1 Certification Fast-Track | Defense procurement tenders in the United States, United Kingdom, and Australia now mandate this safety validation for wireless charging compatibility. |
| Indian PLI Manufacturing Alignment | Domestic assembly investments avoid import duty exposure while serving Maharashtra's precision farming corridors. |
| Resonant-Laser Hybrid Architecture Development | Convergence enables tiered power delivery matching mission duration to energy transfer mode for extended-range applications. |
| Power-as-a-Service Contracting Launch | Texas and Florida grid operators now lease infrastructure with uptime guarantees rather than owning depreciating assets. |
| Gallium Nitride Semiconductor Integration | Solid-state RF amplification compresses system footprints while extending operational range for software-defined power delivery. |
Research Methodology
A spread of perspectives from defense procurement officers, agricultural cooperative managers, utility fleet operators, RF engineering specialists, and charging station OEM executives converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FAA regulatory filings, EASA electromagnetic compatibility documentation, SEC equipment manufacturer disclosures, and customs trade data for ferrite core and copper litz wire imports. Bottom-up unit economics triangulated against top-down addressable fleet sizing across precision agriculture, defense, and utility inspection verticals.
Segmentation dimensions modeled include power transfer physics, deployment mobility, end-user procurement archetype, and regional regulatory framework across the analysis window. CAGRs derived from installed base penetration curves and replacement cycle assumptions for autonomous drone fleet infrastructure. Industry-specific forecast inputs incorporated ferrite core price elasticity and defense budget authorization trajectories for UAV systems.
Decision-makers should treat outputs as directional under assumptions of sustained FAA and EASA regulatory enforcement, stable rare earth magnet supply from Chinese processing facilities, and continued gallium nitride foundry capacity expansion in Taiwan; material deviation would warrant model refresh. Revision becomes warranted when frequency allocation rulings in Germany, Japan, or South Korea cross thresholds that fragment hardware certification pathways.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Passenger Drones Market
UAV
Drone Telematics Market
UAV
Auto-Follow Drone Market
UAV
Global Drone Software Market
UAV
Consumer Drone Market
UAV
Utility Drone Market
UAV
Industrial Drones Market
UAV
Fuel Cell UAV Market
UAV
Europe Small UAV Market
UAV
Middle-East and Africa Small UAV Market
UAV
UAV Payload Market
UAV
North America Small UAV Market
UAV
Aerial Smart Weapons Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
Fixed Wing Military Drones Market
UAV
Drone Payload Market