
 UAV Lidar Market | 2026-2036
UAV Lidar Market Size, Share, and Industry Trends Forecast 2026-2036
UAV Lidar Market Outlook
Premium solid-state lidar arrays is decoupling from commodity mechanical spinning units on the basis of pulse repetition rate, thermal stability, and SWaP constraints. RIEGL Laser Measurement Systems GmbH leverages its Austrian engineering heritage to dominate long-range waveform digitization for mining and infrastructure clients. Velodyne Lidar, Inc. competes through high-volume manufacturing scale and automotive-adjacent cost curves that extend into UAV payload economics. YellowScan specializes in fully integrated survey-grade systems that occupy the compact-aircraft niche where pilot training and deployment speed determine contract awards.
UAV lidar denotes airborne laser scanning systems mounted on unmanned aerial vehicles, typically emitting near-infrared pulses at rates exceeding 100 kHz to generate dense point clouds with sub-decimeter vertical accuracy for topographic mapping, vegetation analysis, and asset inspection. Solid-state lidar leads product type evolution by eliminating mechanical wear components, while hybrid architectures capture margin pools in applications requiring multi-spectral fusion. Infrastructure and mining drive application growth as tunnel monitoring and stockpile volumetrics demand repeatability that passive photogrammetry cannot match. Surveying firms anchor end-user demand, though environmental agencies represent the fastest-expanding procurement channel as carbon accounting protocols tighten.
The FAA's Part 107 and evolving beyond-visual-line-of-sight waivers shape US market access timelines, while EASA's drone regulation framework in Europe imposes specific type-certification burdens on sensor payloads above certain kinetic energy thresholds. ISO 21384-3 for unmanned aircraft systems and ASPRS lidar data quality standards further constrain product design and service deliverables. Stakeholders must monitor regulatory divergence between permissive experimental frameworks and restrictive certified-equipment mandates, as this tension will determine which technology architectures achieve cross-border deployability without costly requalification cycles.
Market Dynamics
The UAV lidar sector pivots on the tension between solid-state photonic integration and legacy mechanical architectures, as pulse repetition rates above 400 kHz redefine survey economics and thermal management becomes the binding constraint on payload miniaturization.
Growth Catalysts
- FAA Part 107 waivers:Beyond-visual-line-of-sight permissions for commercial operators compress deployment timelines for linear infrastructure inspection contracts.
- Carbon accounting protocols:Environmental agencies mandate repeatability standards that photogrammetry cannot satisfy, accelerating procurement of waveform-digitizing sensors.
- Stockpile volumetrics:Mining operations in Brazil's Carajás basin require weekly repeat surveys, creating recurring revenue pools for integrated system providers.
Market Restraints
- InGaAs detector costs:Near-infrared sensor substrates face price volatility tied to gallium refining capacity concentrated in Chinese smelters.
- EASA type-certification burdens:Kinetic energy thresholds above 25 kg impose redundant testing cycles on multi-spectral payload configurations.
- Photogrammetry substitution:Structure-from-motion software advances threaten low-altitude vegetation mapping applications where absolute accuracy requirements relax.
Strategic Opportunities
- Indonesian archipelago mapping:Maritime logistics corridors lack current topographic baselines, creating first-mover advantages for bathymetric-capable units.
- EU Green Deal restoration mandates:Rewilding project monitoring requires multi-temporal canopy analysis, opening procurement channels outside traditional surveying firms.
- Edge-computing convergence:Onboard point-cloud preprocessing with NVIDIA Jetson modules reduces ground-station bandwidth requirements for remote deployments.
Industry Challenges
- Geomatics talent scarcity:Universities produce insufficient waveform analysis specialists to support service-provider expansion.
- ISO 21384-3 compliance timelines:Unmanned aircraft system documentation requirements extend product development cycles by 8-14 months.
- Legacy CAD integration:Survey-grade point clouds require format translation layers that fracture workflow automation for civil engineering clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAV Lidar Market |
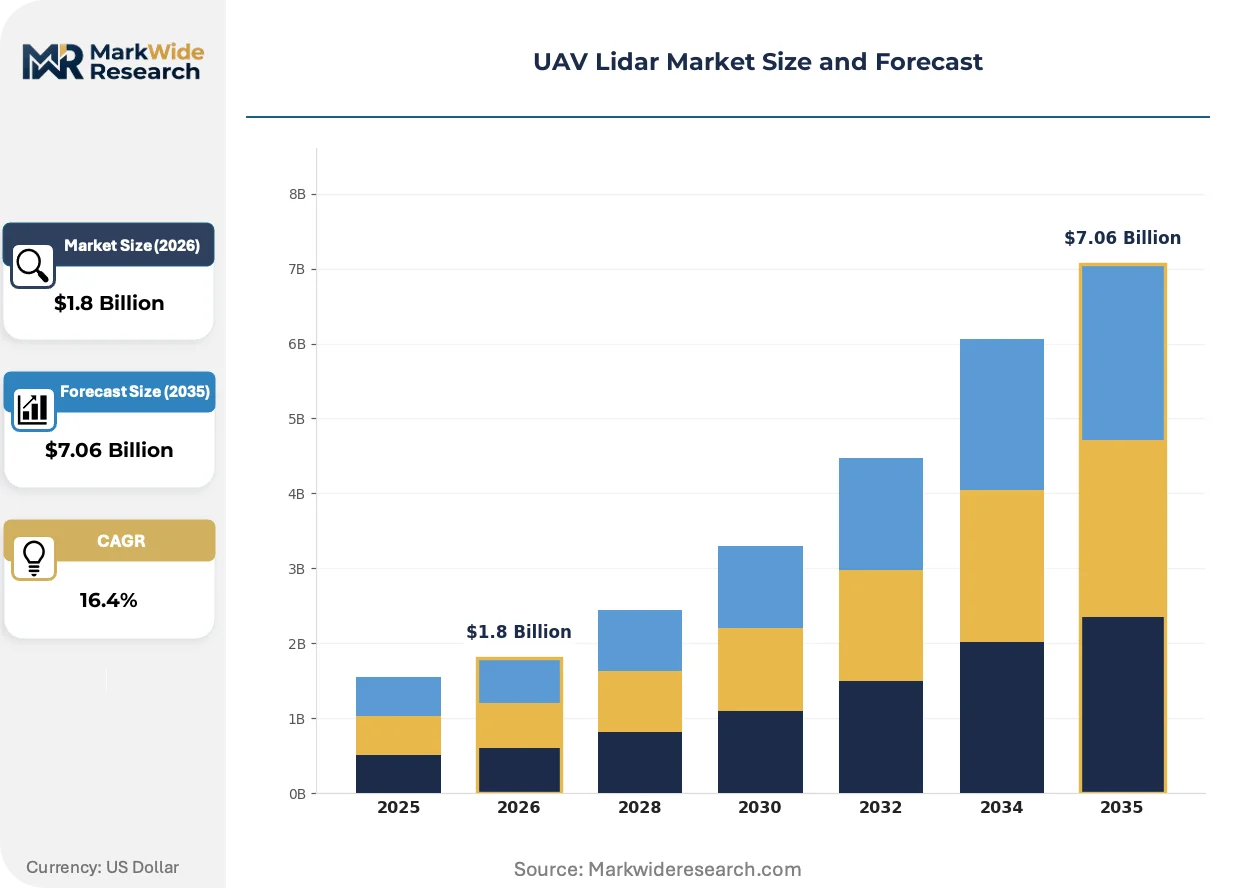
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
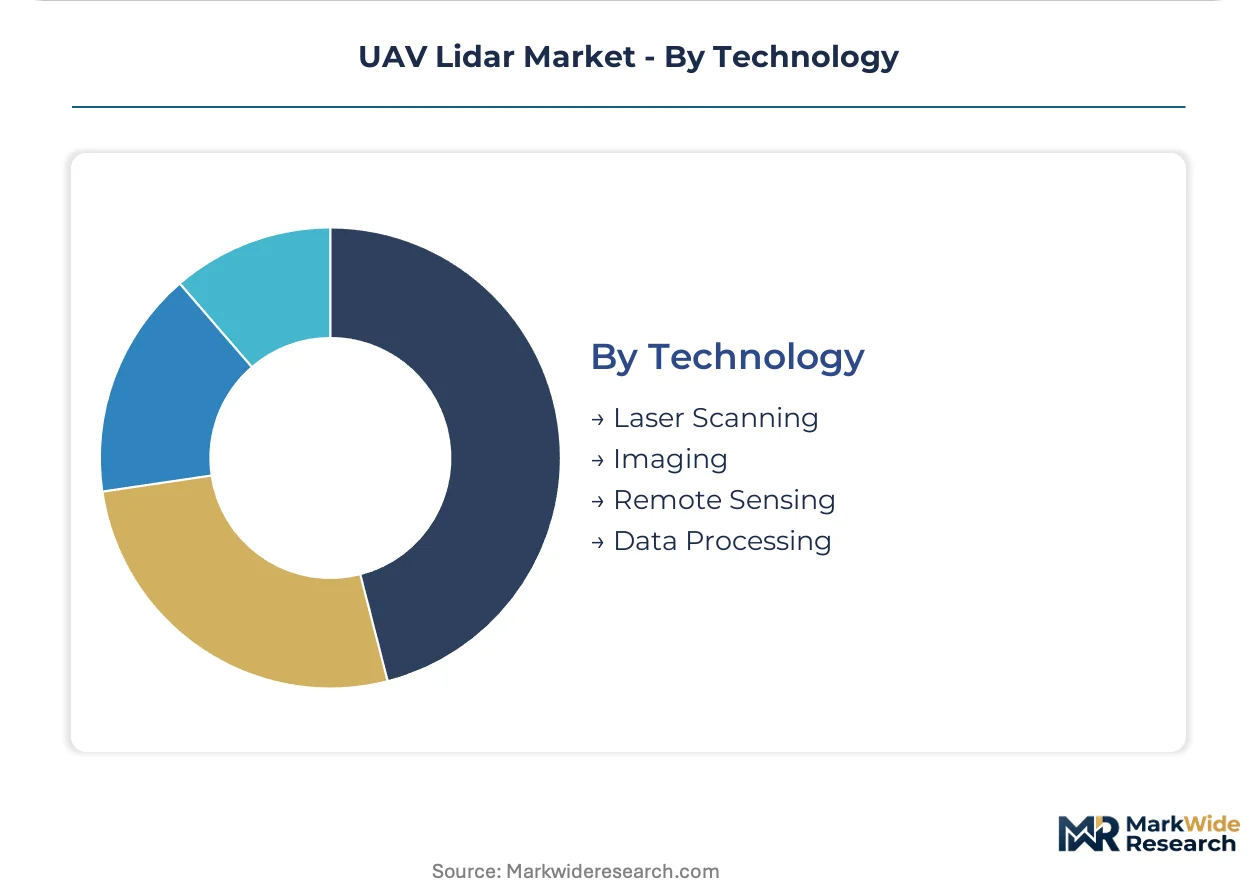
| Segmentation | Product Type: Active Lidar, Passive Lidar, Hybrid Lidar, Solid-State Lidar Application: Agriculture, Forestry, Mining, Infrastructure End User: Surveying Firms, Environmental Agencies, Construction Companies, Emergency Services Technology: Laser Scanning, Imaging, Remote Sensing, Data Processing |
| Companies Covered | Velodyne Lidar, Inc., RIEGL Laser Measurement Systems GmbH, Teledyne Optech, Phoenix LiDAR Systems, YellowScan, Leica Geosystems AG, GeoCue Group, SICK AG, Microdrones, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAV Lidar Market Strategic Shifts
Waveform-digitizing solid-state arrays are compressing mechanical spinning units into niche applications, while regulatory fragmentation between permissive experimental frameworks and certified-equipment mandates forces architecture bets.
MEMS-based beam steering is overtaking motorized gimbal assemblies in the sub-2kg payload segment. Forestry contractors in the Pacific Northwest adopt these units for canopy penetration surveys where vibration tolerance determines data quality. The shift compresses maintenance schedules from 500-hour intervals to 10,000-hour lifecycles, reshaping total-cost-of-ownership calculations for fleet operators.
EASA's drone regulation framework imposes specific electromagnetic compatibility testing on payloads above 25 kg kinetic energy, creating bifurcated product roadmaps. Manufacturers serving European markets must maintain parallel certification tracks, diverting engineering resources from performance optimization. Survey-grade system providers respond by capping airframe masses below threshold limits through carbon-fiber structural redesigns.
Service contracts now unbundle hardware ownership from data deliverables. Mining conglomerates in Western Australia lease point-cloud subscriptions rather than capitalizing sensor assets, transferring obsolescence risk to vendors. This model concentrates procurement authority with corporate geospatial departments and marginalizes independent surveying partnerships that previously intermediated equipment selection.
UAV Lidar Market Segmentation
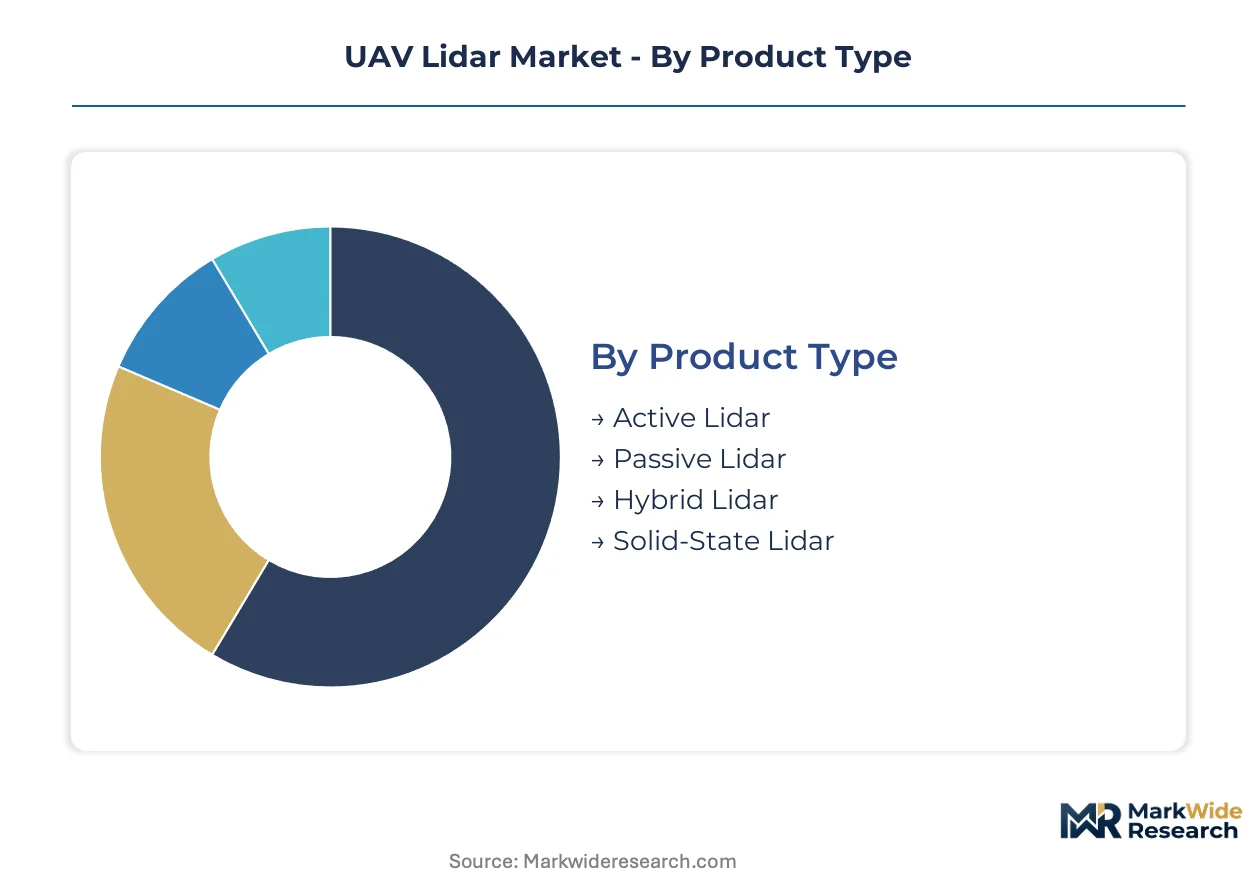
UAV lidar segmentation reveals how capital allocation, technical performance requirements, and procurement authority distribute across the value chain. Equipment buyers face distinct trade-offs between upfront sensor investment and operational flexibility depending on mission profile and regulatory environment.
Product Type:
Capital intensity varies sharply across photonic architectures, with mechanical beam-steering systems demanding precision manufacturing infrastructure while solid-state platforms require semiconductor foundry partnerships.
- Solid-State Lidar:Eliminates mechanical wear components through MEMS or optical phased array steering. Mining operations in Western Australia prioritize these units for 10,000-hour maintenance intervals that compress total ownership costs across fleet deployments.
- Hybrid Lidar:Combines mechanical scanning with solid-state elements to enable multi-spectral fusion. Environmental agencies in Germany procure these configurations for EU Green Deal restoration monitoring where canopy penetration and spectral discrimination must coexist.
- Active Lidar:Emits dedicated laser pulses rather than relying on ambient illumination. Infrastructure inspectors favor these systems for tunnel surveys where lighting conditions are unpredictable.
- Passive Lidar:Detects reflected energy without active emission. Academic researchers deploy these units where eye-safety regulations restrict laser power output.
Solid-state configurations absorb the bulk of installed capacity; hybrid architectures are expanding most quickly as procurement specifications harden around multi-spectral deliverables.
Application:
Revenue concentration tracks extractive industry capital expenditure cycles, with mining and infrastructure commanding premium pricing for survey-grade accuracy while agriculture operates on compressed margins.
- Mining:Weekly stockpile volumetrics and pit progression monitoring require sub-decimeter repeatability. Operations in Brazil's Carajás basin generate recurring revenue pools through subscription-based point-cloud deliverables rather than equipment ownership.
- Infrastructure:Linear asset inspection of bridges, railways, and transmission corridors demands beyond-visual-line-of-sight operational waivers. FAA Part 107 permissions in the United States compress deployment timelines for corridor mapping contracts.
- Agriculture:Precision farming operations in Brazil accelerate sensor deployments for variable-rate input management. Photogrammetry substitution pressures limit pricing power in vegetation height mapping applications.
- Forestry:Canopy penetration surveys in the Pacific Northwest adopt MEMS-based units where vibration tolerance determines data quality. Carbon accounting protocols mandate repeatability standards that passive methods cannot satisfy.
Infrastructure commands the largest share of procurement value; mining applications are climbing the fastest as subscription models displace capital expenditure.
End User:
Procurement authority is concentrating with corporate geospatial departments that lease data subscriptions, marginalizing independent surveying partnerships that previously intermediated equipment selection.
- Surveying Firms:Traditional intermediaries with established client relationships and waveform analysis expertise. Talent scarcity across geomatics programs constrains service-provider expansion.
- Environmental Agencies:Fastest-expanding procurement channel as carbon accounting protocols tighten. EU Green Deal restoration mandates in Europe open multi-temporal canopy analysis contracts outside traditional surveying channels.
- Construction Companies:Earthwork verification and as-built documentation drive adoption. Legacy CAD integration challenges fracture workflow automation for civil engineering deliverables.
- Emergency Services:Post-disaster rapid mapping and search-and-rescue operations. Edge-computing convergence with NVIDIA Jetson modules reduces ground-station bandwidth requirements for remote deployments.
Surveying firms retain the deepest installed base; environmental agencies are gaining share fastest as regulatory mandates proliferate.
Technology:
Performance differentiation concentrates in pulse generation and detection subsystems, with waveform digitization commanding premium positioning against basic time-of-flight architectures.
- Laser Scanning:Core range-finding capability emitting near-infrared pulses above 100 kHz. Long-range waveform digitization dominates mining and infrastructure client specifications.
- Data Processing:Onboard point-cloud preprocessing and ground-station analytics. Bandwidth constraints in remote deployments elevate the competitive importance of edge-computing integration.
- Imaging:Co-registered photogrammetric capture for RGB texture mapping. Structure-from-motion software advances threaten low-altitude applications where absolute accuracy requirements relax.
- Remote Sensing:Integration with multispectral and thermal payloads. EASA electromagnetic compatibility testing above 25 kg kinetic energy imposes bifurcated product roadmaps for European market access.
Laser scanning underpins the majority of deployed systems; data processing capabilities are expanding most quickly as bandwidth economics reshape remote deployment architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European UAV lidar engineering, with Bavaria's precision manufacturing corridor hosting RIEGL and SICK headquarters that feed geospatial instrumentation clusters across the continent.
United States
Beyond-visual-line-of-sight infrastructure contracts accelerate sensor procurement for linear corridor mapping. FAA Part 107 waivers compress deployment timelines for transmission line and railway inspectors. Phoenix LiDAR Systems occupies the Southwest corridor where mining conglomerates lease point-cloud subscriptions rather than capitalizing hardware assets.
Germany
EU Green Deal restoration mandates drive environmental agency procurement for multi-temporal canopy analysis. EASA electromagnetic compatibility testing above 25 kg kinetic energy forces carbon-fiber structural redesigns to cap airframe masses below threshold limits. The Stuttgart engineering belt concentrates hybrid lidar development where spectral discrimination requirements harden.
Brazil
Precision agriculture operations in Mato Grosso accelerate variable-rate input management deployments. ANVISA eye-safety regulations constrain laser power output for pasture monitoring applications. The Carajás basin mining complex generates recurring weekly stockpile volumetric surveys that favor subscription-based service models over equipment ownership.
China
Dual carbon goals tighten carbon accounting protocols that photogrammetry cannot satisfy, accelerating waveform-digitizing sensor procurement. MIIT unmanned aircraft system standards impose documentation requirements that extend product development cycles. The Yangtze River Delta hosts solid-state photonic integration foundries that supply MEMS-based beam steering subsystems.
Australia
Western Australian mining conglomerates transfer obsolescence risk to vendors through leased data deliverables. The country's national aviation regulator maintains permissive experimental frameworks that contrast with European certified-equipment mandates. Perth anchors bathymetric-capable unit development for Indonesian archipelago mapping contracts.
UAV Lidar Market Competitive Environment
Capital-heavy producers compete with asset-light designers across divergent technology roadmaps. The vendor base separates between semiconductor foundry-dependent solid-state platforms and precision mechanical assembly operations. Austrian engineering heritage anchors long-range waveform digitization archetypes, while automotive-adjacent scale players leverage high-volume manufacturing curves. Dominant competitive moves include strategic partnerships with carbon-fiber airframe fabricators and geographic expansion into Indonesian maritime logistics corridors.
Within the survey-grade integrated systems tier, YellowScan exemplifies compact-aircraft specialization where pilot training and deployment speed determine contract awards. RIEGL Laser Measurement Systems GmbH anchors the European precision manufacturing archetype. Velodyne Lidar, Inc. occupies the scale-driven position where automotive cost curves extend into UAV payload economics.
| Leading Market Players |
|---|
| Velodyne Lidar, Inc. |
| RIEGL Laser Measurement Systems GmbH |
| Teledyne Optech |
| Phoenix LiDAR Systems |
| YellowScan |
| Leica Geosystems AG |
| GeoCue Group |
| SICK AG |
| Microdrones |
| Others |
Value Chain & Pricing Dynamics
Captive photonic foundry partnerships in the Yangtze River Delta anchor both component supply security and pricing power for solid-state lidar arrays. Austrian and German precision manufacturers defend waveform-digitization premiums through in-house pulse-generation subsystems that commodity assemblers cannot replicate.
Pricing Analysis
Uptime-guaranteed subscription contracts dominate mining and infrastructure procurement, with Western Australian conglomerates leasing point-cloud deliverables rather than capitalizing hardware. Three-tier pricing structure across survey-grade, professional-grade, and entry-level systems separates RIEGL's long-range waveform units from Velodyne's automotive-adjacent payloads and YellowScan's compact-aircraft integrations. Cost compression in the sub-2kg MEMS segment is intensifying because photogrammetry software advances threaten vegetation-mapping applications. Independent surveying firms exhibit the highest price sensitivity as corporate geospatial departments concentrate procurement authority.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining and agriculture buyer demand, while distributor networks serve fragmented surveying firm procurement. InGaAs detector substrates draw from Chinese gallium refining capacity, Austrian precision optics manufacturing, and Taiwanese semiconductor packaging. Carbon-fiber airframe components rest on Japanese Toray supply and German SGL Carbon output. Single-source vulnerability concentrates in rare-earth refining for laser pump diodes. Distribution runs through Phoenix LiDAR Systems in the US Southwest, SICK's German engineering corridor, and Microdrones' European service partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS-based beam steering is displacing motorized gimbal assemblies across the sub-2kg payload segment, compressing maintenance intervals from 500 hours to 10,000 hours and rewriting total-cost-of-ownership calculations for fleet operators.
For Market Incumbents: Hedge against photogrammetry substitution by deepening waveform-digitization capabilities that structure-from-motion software cannot replicate. Secure captive supply of InGaAs detector substrates through long-term offtake agreements with Chinese gallium refiners. Invest in FAA Part 107 waiver facilitation services that compress deployment timelines for infrastructure clients and lock in subscription renewal rates. For New Entrants and Emerging Players: Capture the Indonesian archipelago mapping white space where maritime logistics corridors lack current topographic baselines and bathymetric-capable units command first-mover premiums. Target EU Green Deal restoration monitoring contracts in Eastern European rewilding corridors where environmental agencies bypass traditional surveying firm intermediaries. Lead with edge-computing integration using NVIDIA Jetson modules that reduce bandwidth requirements for remote deployments. For Investors and Strategic Acquirers: Exit pathways concentrate in semiconductor foundry-dependent solid-state platforms with automotive-adjacent scale potential. Long-term viability favors vendors with waveform-analysis talent pipelines and carbon-fiber structural design capabilities that cap airframe masses below EASA kinetic energy thresholds. Watch for inflection when FAA beyond-visual-line-of-sight waivers standardize rather than require case-by-case approval.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Beam Steering Integration | Eliminates mechanical wear components, extending maintenance intervals to 10,000 hours for forestry contractors. |
| Carbon-Fiber Structural Redesign | Caps airframe masses below EASA 25 kg kinetic energy thresholds, preserving European market access. |
| Edge-Computing Convergence | NVIDIA Jetson onboard preprocessing reduces ground-station bandwidth requirements for Australian mining leases. |
| Waveform-Digitization Investment | RIEGL's Austrian engineering heritage defends premium positioning against photogrammetry substitution threats. |
| Subscription Service Model | Western Australian mining conglomerates transfer obsolescence risk to vendors through leased point-cloud deliverables. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this UAV lidar market assessment. Primary interviews with geomatics program directors, mining geospatial procurement leads, FAA certification consultants, and environmental agency remote sensing specialists combined with secondary validation from ASPRS lidar quality standards documentation, EASA drone regulation frameworks, and ISO 21384-3 unmanned aircraft system specifications. Bottom-up sensor shipment tallies and top-down mining infrastructure capex allocations underwent rigorous triangulation.
Data-stream reconciliation across product type, application, end user, and technology segmentation dimensions generated volume and value outputs over the projection horizon. Pulse repetition rate adoption curves, thermal management payload constraints, and subscription service penetration rates informed CAGR derivation. Solid-state versus mechanical architecture transition velocities and carbon accounting protocol enforcement timelines served as industry-specific forecast inputs.
The model holds under stable FAA Part 107 waiver processing timelines and continued EASA electromagnetic compatibility testing harmonization; deviation in InGaAs detector supply disruptions or photogrammetry software accuracy breakthroughs would shift deployment economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Micro Drone Market
UAV
GCC Drone Pilot Training Market
UAV
Drone Leasing Market
UAV
Global Target Drone Market
UAV
UAV Simulator Market
UAV
Airborne Digital Battlefield Market
UAV
Consumer Drone Market
UAV
Fuel Cell UAV Market
UAV
Global Drone Analytics Market
UAV
UAV Battery Market
UAV
Industrial Drones Market
UAV
Tactical UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Military UAV Sensor Market
UAV
Global Stratospheric UAV Payload Technology Market
UAV
Small UAV Market