
 Tactical UAV Market | 2026-2036
Tactical UAV Market Size, Share, and Industry Trends Forecast 2026-2036
Tactical UAV Market Intelligence
Turkey is narrowing the gap between indigenous output and Western supply through accelerated airframe and avionics investment. General Atomics leverages its vertical integration across propulsion and sensor payloads to sustain long-term program contracts with the US Department of Defense. Elbit Systems anchors its position in autonomous navigation suites, while Baykar Tech competes aggressively on cost-engineered combat platforms for Middle Eastern and Asian buyers.
A tactical UAV is an unmanned aerial system weighing typically under 600 kilograms, designed for battlefield reconnaissance, target acquisition, and limited strike missions at ranges up to 300 kilometers, operating at altitudes below 18,000 feet with endurance cycles of 8 to 24 hours. The primary purpose is to deliver real-time intelligence and precision engagement without risking crewed aircraft. Combat UAVs occupy the highest margin pool due to integrated weapons stations and sovereign-content requirements, while tactical reconnaissance UAVs lead absolute volume through modular sensor swap-outs demanded by military end users. AI-powered systems represent the fastest-growing technology segment as autonomy reduces operator burden and enables swarm coordination.
The FAA governs domestic airspace integration through Part 107 and emerging beyond-visual-line-of-sight waivers, while NATO STANAG standards shape interoperability requirements for coalition operations. Turkey's national aviation authority applies military-type certification aligned with EU Green Deal decarbonization benchmarks for future propulsion transitions. Stakeholders must monitor how sovereign data-localization mandates and export-control tightening affect cross-border sensor and software supply chains.
Market Dynamics
Autonomous navigation architectures are compressing operator-to-platform ratios and redefining procurement economics across NATO-aligned defense ministries.
Growth Catalysts
- BVLOS Regulatory Expansion:The FAA's evolving beyond-visual-line-of-sight waiver framework in the United States is unlocking extended-range missions for reconnaissance and logistics applications.
- Swarm Coordination Algorithms:AI-enabled distributed control systems are reducing single-point-of-failure vulnerabilities while multiplying strike density per sortie.
- Turkish Manufacturing Scale:Baykar Tech and domestic suppliers in Turkey are expanding airframe output for export-oriented combat programs across Middle Eastern and Asian buyer networks.
Market Restraints
- Sensor Export Controls:ITAR and multilateral regime restrictions are fragmenting cross-border electro-optical and radar payload supply chains.
- Lithium-Ion Cell Concentration:Battery chemistry supply for extended endurance platforms depends on concentrated East Asian cell manufacturing.
- Spectrum Allocation Friction:Military C-band and commercial 5G interference disputes are complicating frequency licensing for datalink-dependent operations.
Strategic Opportunities
- Sub-Saharan Border Surveillance:Unpenetrated demand for persistent reconnaissance exists across Sahel and Horn of Africa security partnerships.
- Hybrid-Electric Propulsion:EU Green Deal decarbonization benchmarks are creating certification pathways for reduced-signature endurance platforms.
- Modular Payload Architectures:Rapid sensor swap-out standards are enabling multi-mission flexibility without dedicated airframe procurement.
Industry Challenges
- Autonomy Software Talent Scarcity:Machine learning engineers with defense clearance eligibility remain concentrated in limited geographic clusters.
- STANAG Interoperability Timelines:NATO standardization cycles lag platform refresh rates, forcing national customization that fragments fleet commonality.
- Legacy C2 System Integration:Ground control station retrofit requirements are extending deployment schedules for mixed-generation operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tactical UAV Market |
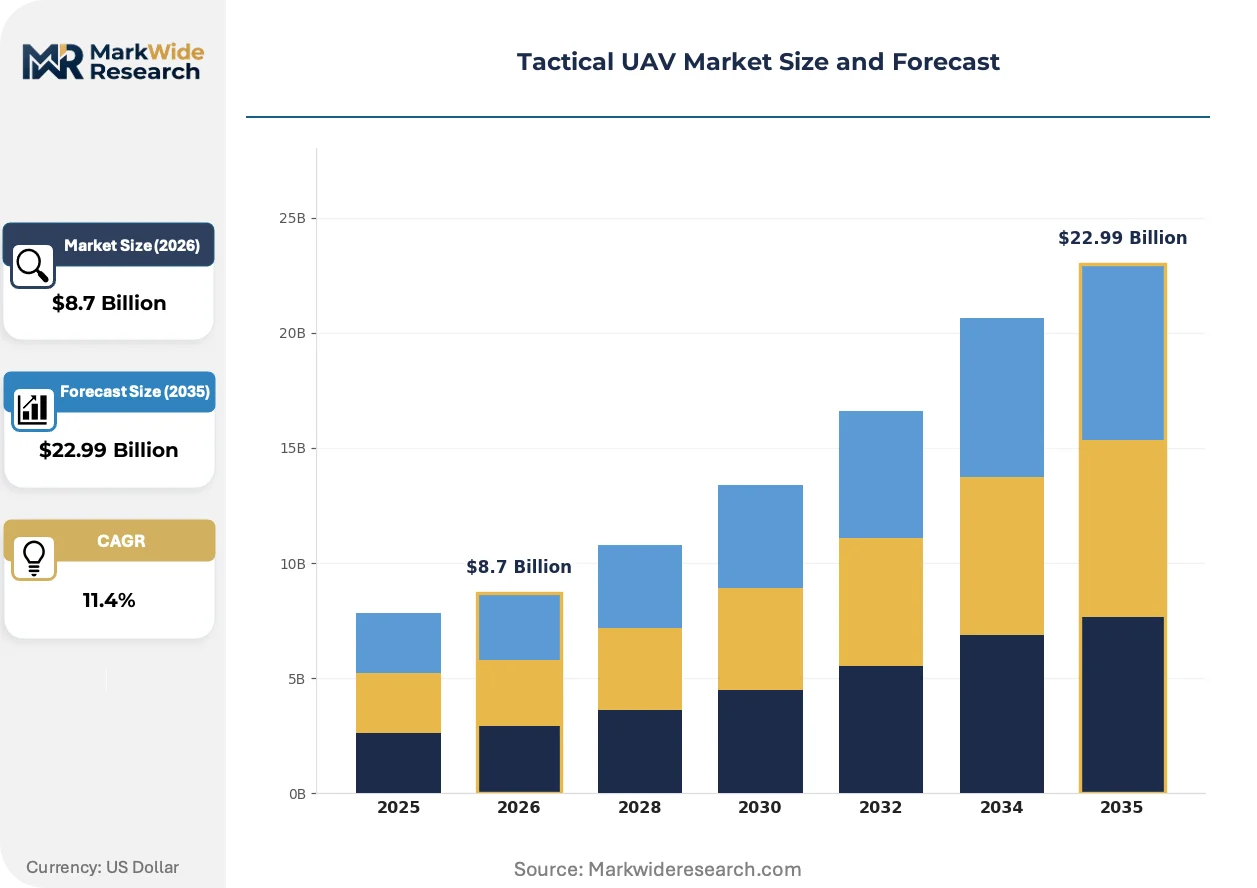
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini UAVs, Micro UAVs, Tactical Reconnaissance UAVs, Combat UAVs End User: Military, Defense Contractors, Law Enforcement, Emergency Services Technology: Autonomous Navigation, AI-Powered Systems, Remote Control, Sensor Integration Application: Surveillance, Reconnaissance, Border Patrol, Disaster Management |
| Companies Covered | General Atomics, Northrop Grumman, Lockheed Martin, Elbit Systems, Israel Aerospace Industries, AeroVironment, Textron, BAE Systems, Baykar Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tactical UAV Market Strategic Shifts & Innovations
Edge computing architectures and sovereign data mandates are rewiring how intelligence is processed, stored, and transmitted across tactical networks.
AI-powered mission planning is migrating from ground-based servers to onboard inference engines. Defense procurement offices in Australia and South Korea are mandating reduced bandwidth dependence for contested electromagnetic environments. This compression of decision latency is displacing traditional manned-unmanned teaming hierarchies.
EU AI Act risk classification frameworks are forcing transparency requirements on autonomous target recognition algorithms. European defense contractors must now document training data provenance and decision audit trails for lethal autonomous systems. Combat UAV programs with significant European content are responding by segregating human-in-the-loop kill chains from navigation autonomy.
Defense ministries are consolidating vendor relationships around full-lifecycle service bundles rather than discrete platform acquisitions. Turkish and Israeli suppliers are capturing multi-year availability contracts that embed training, spares, and software updates. This preference shift is most visible in Middle Eastern buyer markets where operational readiness guarantees outweigh unit procurement cost.
Tactical UAV Market Segmentation
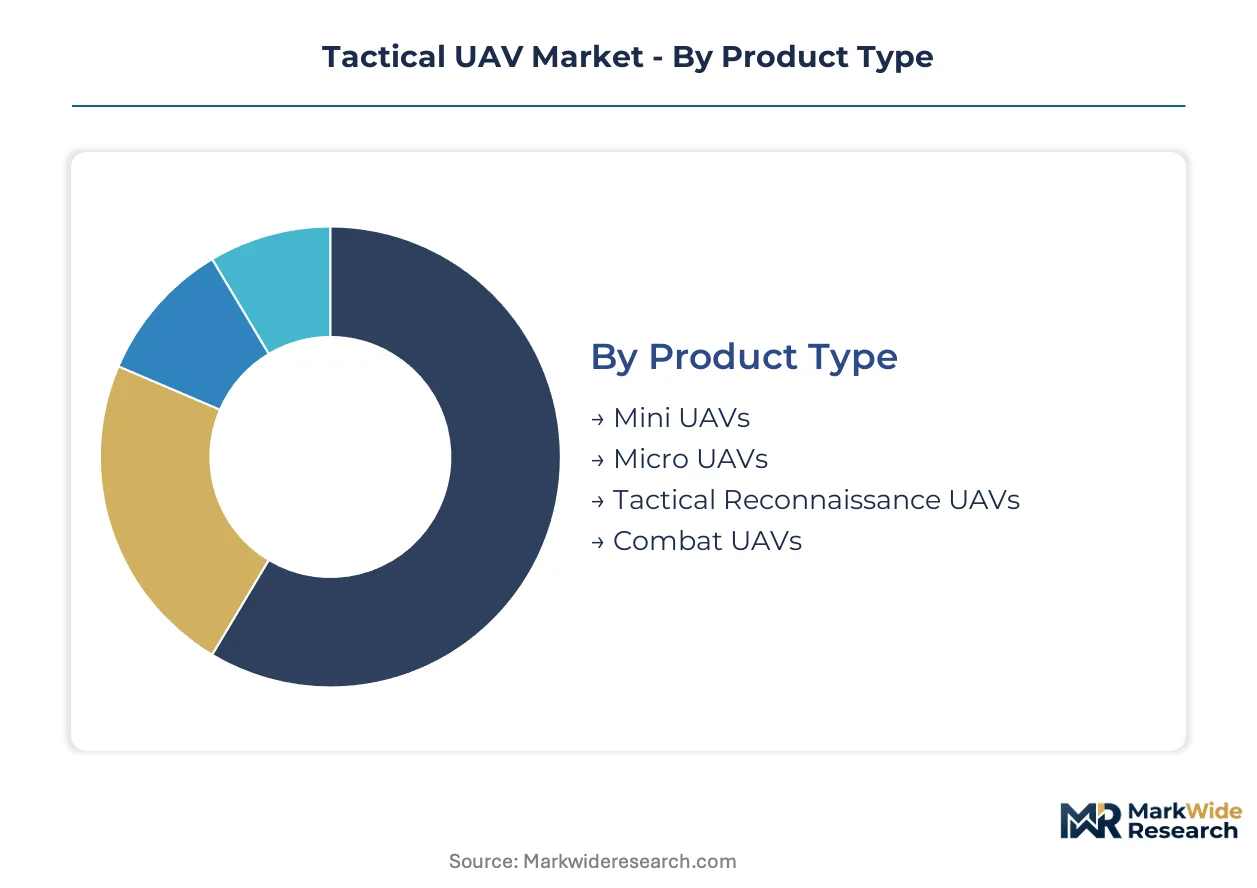
Tactical UAV procurement divides across mission profile, operator sophistication, and technology readiness. Understanding these fault lines reveals where margin concentrates and where volume expansion meets regulatory friction.
Product Type:
Platform weight and armament capability segment the market into distinct cost tiers with divergent certification pathways.
- Combat UAVs:Armed platforms integrate weapons stations and hardened datalinks for precision strike missions. Turkish defense exports to Middle Eastern operators concentrate here, driven by sovereign-content mandates and multi-year availability contracts that bundle training and spares.
- Tactical Reconnaissance UAVs:Modular sensor architectures dominate this tier, with NATO STANAG standards enabling rapid payload swap-outs across coalition fleets. Australian and South Korean procurement offices prioritize reduced bandwidth dependence for contested electromagnetic environments.
- Mini UAVs:Hand-launched systems serve dismounted infantry with 30-90 minute endurance cycles; urban warfare applications in Eastern European security partnerships expand deployment.
- Micro UAVs:Sub-2-kilogram platforms penetrate indoor structures; SWAT teams and hostage rescue units drive demand for acoustic signature suppression.
Combat UAVs hold installed capacity. Tactical Reconnaissance UAVs are rotating up the share rankings.
End User:
Customer type determines procurement authority, operational tempo, and sensitivity to sovereign data localization requirements.
- Military:National defense ministries command the largest program budgets, with FAA BVLOS waivers and NATO interoperability standards shaping acquisition specifications. US Department of Defense contracts emphasize vertical integration across propulsion and sensor payloads.
- Defense Contractors:Prime systems integrators subcontract airframe and avionics production, with Turkish and Israeli suppliers capturing multi-year service bundles that embed software updates.
- Law Enforcement:Police departments face stricter FAA Part 107 altitude and airspace restrictions, limiting deployment to line-of-sight operations over populated areas.
- Emergency Services:Fire departments and search-and-rescue units prioritize rapid deployment kits with thermal imaging for wildfire and flood response.
Military commands program scale. Defense Contractors are rotating up the share rankings.
Technology:
Autonomy level and processing architecture define competitive differentiation and export control exposure.
- AI-Powered Systems:Onboard inference engines compress decision latency for swarm coordination and contested electromagnetic operations. EU AI Act transparency requirements now mandate training data provenance documentation for European content programs.
- Autonomous Navigation:GPS-denied positioning and obstacle avoidance reduce operator-to-platform ratios, with Elbit Systems anchoring market position in suite integration.
- Sensor Integration:Multi-spectral electro-optical and synthetic aperture radar fusion demands ITAR-compliant supply chains that fragment across US and non-US payload vendors.
- Remote Control:Legacy manual override retains human-in-the-loop kill chain segregation for lethal autonomous systems under emerging regulatory frameworks.
Autonomous Navigation holds installed capacity. AI-Powered Systems are climbing the fastest.
Application:
Mission purpose dictates endurance requirements, sensor payload, and rules of engagement complexity.
- Surveillance:Persistent area monitoring over extended durations requires hybrid-electric propulsion to meet EU Green Deal decarbonization benchmarks for reduced acoustic and thermal signatures.
- Reconnaissance:Deep-target acquisition missions prioritize range and altitude performance, with Sub-Saharan border security partnerships in the Sahel and Horn of Africa representing unpenetrated demand.
- Border Patrol:Coastal and land frontier monitoring integrates radar and automatic identification system correlation, with spectrum allocation friction between military C-band and commercial 5G complicating licensing.
- Disaster Management:Rapid infrastructure assessment post-hurricane or earthquake leverages modular payload swap-outs for communications relay and supply drop coordination.
Surveillance holds installed capacity. Reconnaissance is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense ministries deploy tactical UAVs differently across geographies. NATO members prioritize STANAG interoperability for coalition operations. Middle Eastern buyers favor sovereign-content bundles with multi-year service contracts. Asian procurement offices emphasize reduced bandwidth dependence for contested electromagnetic environments.
United States
The US Department of Defense commands the largest program budgets through prime systems integrators. FAA Part 107 and emerging BVLOS waivers reshape operational certification for extended-range missions. San Diego hosts General Atomics and other defense contractors leveraging vertical integration across propulsion and sensor payloads.
Turkey
Baykar Tech and domestic suppliers scale airframe output for export-oriented combat programs across Middle Eastern and Asian networks. The national aviation authority applies military-type certification aligned with EU Green Deal decarbonization benchmarks. Ankara and Istanbul anchor manufacturing clusters expanding sovereign production capacity.
Israel
Israel Aerospace Industries and Elbit Systems anchor positions in autonomous navigation suites and hardened datalink technologies. The national defense establishment drives procurement prioritizing human-in-the-loop kill chain segregation. Tel Aviv and Haifa concentrate R&D talent for AI-powered mission planning systems.
Germany
Bundeswehr procurement emphasizes NATO STANAG interoperability and EU AI Act transparency requirements for autonomous target recognition. The KBA and federal defense procurement office coordinate certification timelines. Bavaria and Baden-Württemberg host systems integrators navigating fragmented payload supply chains.
Australia
The Australian Defence Force mandates reduced bandwidth dependence for contested electromagnetic environments in Indo-Pacific operations. The TGA and defense procurement office coordinate sovereign data-localization requirements. Adelaide and Canberra anchor development clusters for modular sensor architectures and rapid payload swap-outs.
Tactical UAV Market Key Industry Players
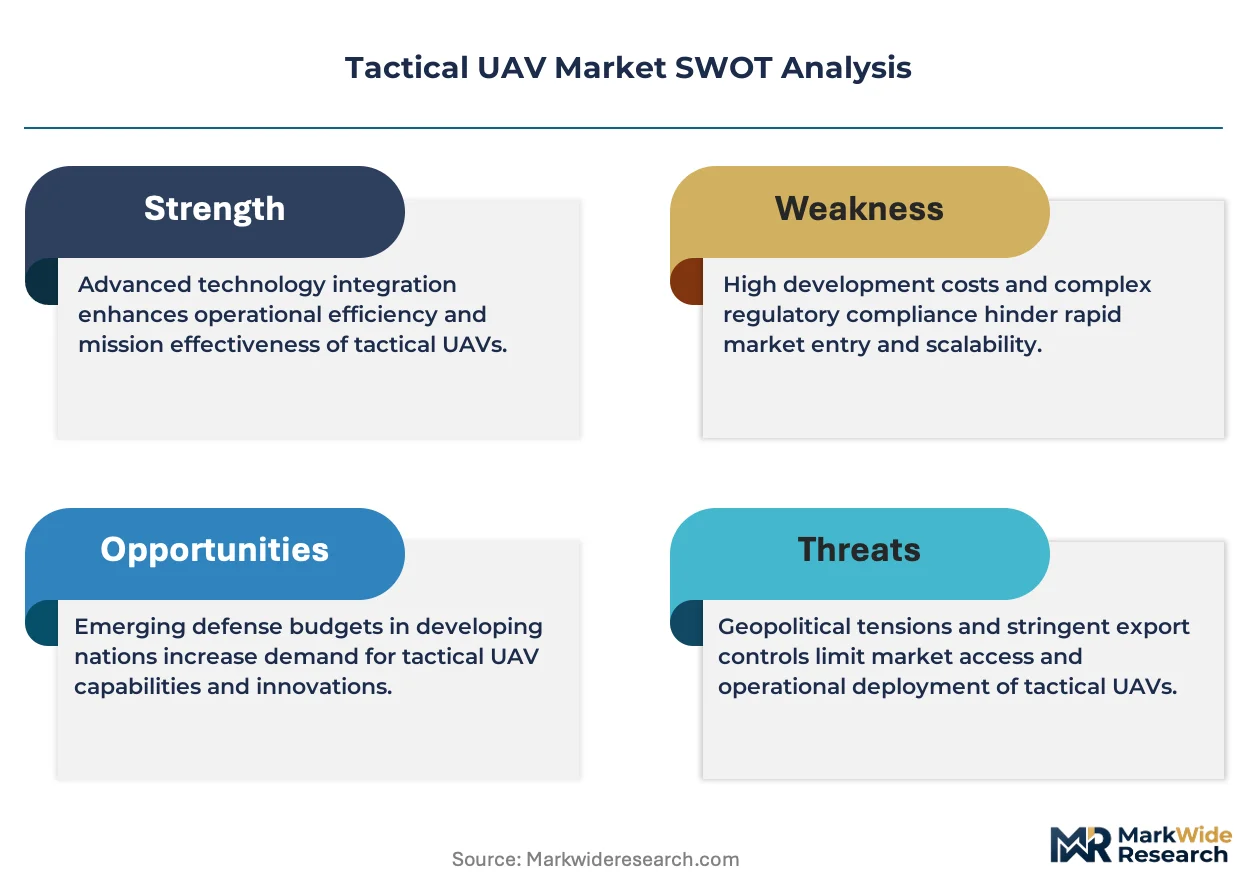
Capability concentration sits with one tier; scale advantage sits with another. The vendor base organizes around three strategic archetypes: full-lifecycle service bundlers, vertically integrated platform specialists, and modular subsystem suppliers. Consolidation pressure favors multi-year availability contracts over discrete platform sales. Dominant competitive moves include geographic expansion into underpenetrated Middle Eastern and Asian buyer networks, and backward integration into captive propulsion and sensor supply.
Among US-based defense primes, General Atomics and Northrop Grumman exemplify vertically integrated platform specialists. Elbit Systems occupies a position within the autonomous navigation tier. Baykar Tech represents the scale-driven export-oriented combat platform archetype.
| Leading Market Players |
|---|
| General Atomics |
| Northrop Grumman |
| Lockheed Martin |
| Elbit Systems |
| Israel Aerospace Industries |
| AeroVironment |
| Textron |
| BAE Systems |
| Baykar Tech |
| Others |
Cost & Logistics Intelligence
East Asian lithium-ion cell manufacturing concentration feeds directly into endurance platform margin pools, with battery chemistry costs determining competitive positioning across extended-range tactical UAV tiers.
Pricing Analysis
Long-term availability contracts dominate procurement structures, bundling airframe acquisition with multi-year training, spares, and software update commitments. Three-tier pricing structure across premium, standard, and economy levels separates NATO STANAG-certified platforms from sovereign-content combat systems and cost-engineered export alternatives. Cost compression in Middle Eastern buyer networks is intensifying because Turkish suppliers compete aggressively on bundled service economics. Defense contractors exhibit lowest price sensitivity due to lifecycle value guarantees, while law enforcement agencies face strictest budget constraints under FAA Part 107 operational limitations.
Supply Chain Analysis
Lithium carbonate and cobalt hydroxide feedstock sourcing draws from concentrated Chilean, Australian, and Indonesian mining operations. Semiconductor foundry capacity for flight control processors rests on Taiwanese and South Korean fabrication networks, with ITAR-compliant electro-optical sensor supply fragmenting across US and Israeli vendors. Single-source vulnerability in gallium arsenide radar substrate supply threatens payload integration timelines. Distribution runs through prime systems integrators with captive maintenance infrastructure rather than open component markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manned-unmanned teaming hierarchies face substitution pressure from fully autonomous swarm architectures, forcing incumbents to defend platform relevance through autonomy software differentiation.
For Market Incumbents: Build data-sovereignty moats through sovereign-cloud ground control station architectures that comply with EU AI Act transparency mandates and emerging data-localization requirements. Capture multi-year availability contracts embedding software update subscriptions to lock out Turkish cost competitors. Autonomy software talent scarcity in cleared engineering pools threatens program execution timelines; in-house production of edge inference engines secures supply chain control over mission-critical processing. For New Entrants and Emerging Players: Establish a beachhead in Sub-Saharan border surveillance partnerships where persistent reconnaissance demand remains unpenetrated and incumbent presence is minimal. Target Sahel and Horn of Africa security cooperation frameworks with rapid-deployment mini UAV kits featuring thermal imaging for wildfire and flood response. Go-to-market leverage centers on modular payload architectures enabling multi-mission flexibility without dedicated airframe procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-powered systems development as EU AI Act documentation requirements and training data provenance audits add compliance overhead. Acquisition targets should exhibit captive autonomy navigation suite development and existing FAA BVLOS waiver portfolios. The signal to watch is STANAG standardization timeline acceleration, which would compress national customization premiums and favor interoperable platform architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propulsion Systems | General Atomics leverages in-house turbine production to secure long-term US Department of Defense program contracts. |
| BVLOS Certification Pathway Investment | FAA waiver portfolio accumulation unlocks extended-range reconnaissance missions for logistics applications. |
| Autonomy Software Acquisition | Machine learning engineering talent concentration in Tel Aviv and Haifa anchors competitive positioning in GPS-denied navigation. |
| Multi-Year Service Bundle Expansion | Turkish suppliers capture Middle Eastern buyer preference through operational readiness guarantees exceeding unit procurement economics. |
| Hybrid-Electric Propulsion Certification | EU Green Deal alignment creates decarbonization-compliant pathways for reduced-signature endurance platforms. |
Research Approach
Findings reconcile primary fieldwork against secondary review of defense procurement databases, FAA regulatory filings, NATO standardization documents, and customs trade records. Program managers at prime systems integrators, autonomy software engineers with security clearance, defense ministry acquisition officers, and electro-optical sensor procurement leads contributed structured interviews. Bottom-up platform shipment tallies and top-down defense budget allocation analysis were cross-validated through triangulation.
Forecast inputs include mission profile segmentation, operator sophistication tiers, and technology readiness levels across the projection horizon. Product type, end user category, autonomy architecture, and geographic procurement authority were modeled as segmentation dimensions. CAGRs were derived from installed base growth rates and replacement cycle compression. Industry-specific inputs encompass FAA BVLOS waiver issuance velocity and Turkish export license approval timelines.
Stress conditions across lithium supply disruption, STANAG standardization delays, and C-band spectrum reallocation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding defense budget continuity and regulatory pathway stability. Cross-checking against national defense procurement disclosure databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Aerial Survey Services Market
UAV
Drone Data Management Market
UAV
Solar Powered Drones Market
UAV
Drone Defense System Market
UAV
Middle-East and Africa Small UAV Market
UAV
UAV Navigation Systems Market
UAV
Asia-Pacific Tethered Drone Market
UAV
Anti-Drone Technology Market
UAV
Europe Small UAV Market
UAV
UAV Sense-And-Avoid Systems Market
UAV
Europe Drones Market
UAV
UAV Lidar Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Asia Pacific Small UAV Market
UAV
Small UAV Market
UAV
UAV Battery Market