
 Global Drone Autopilots Market | 2026-2036
Global Drone Autopilots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drone Autopilots Market Analysis
The capability gap between integrated flight-stack vendors and modular autopilot suppliers is collapsing as software-defined architectures commoditize core stabilization algorithms. DJI Innovations leverages captive semiconductor sourcing to sustain margin compression resistance across consumer and enterprise tiers. Skydio specializes in computer-vision-first navigation for confined-space defense applications, while Autel Robotics competes through FCC-certified platforms positioned for North American commercial deployment.
Drone autopilots comprise embedded flight-control systems integrating inertial measurement units, GPS receivers, and real-time kinematic correction modules to execute autonomous waypoint navigation, attitude stabilization, and failsafe recovery without human intervention. These systems process sensor fusion outputs at sub-100-millisecond loop rates to maintain controlled flight across fixed-wing, multirotor, and hybrid vertical-takeoff configurations. Computer vision segments command premium positioning where optical-flow and visual-inertial odometry replace GPS-denied navigation, while agriculture applications anchor volume demand through spray-drone and crop-scouting deployment at scale. Mapping applications differentiate on Lidar payload integration density, with defense end users driving infrared sensor configurations for thermal surveillance missions.
The FAA's Part 107 framework and EASA's Specific Category regulations under EU drone regulation shape airworthiness certification burdens that determine market access timelines for autopilot-integrated platforms. China's CAAC coordinates with MIIT on low-altitude economy zoning that accelerates commercial route approval in designated urban air mobility corridors. Stakeholders must monitor evolving detect-and-avoid mandates across jurisdictions, as regulatory harmonization failure would fragment autopilot software validation requirements and multiply type-certification costs for cross-border platform deployment.
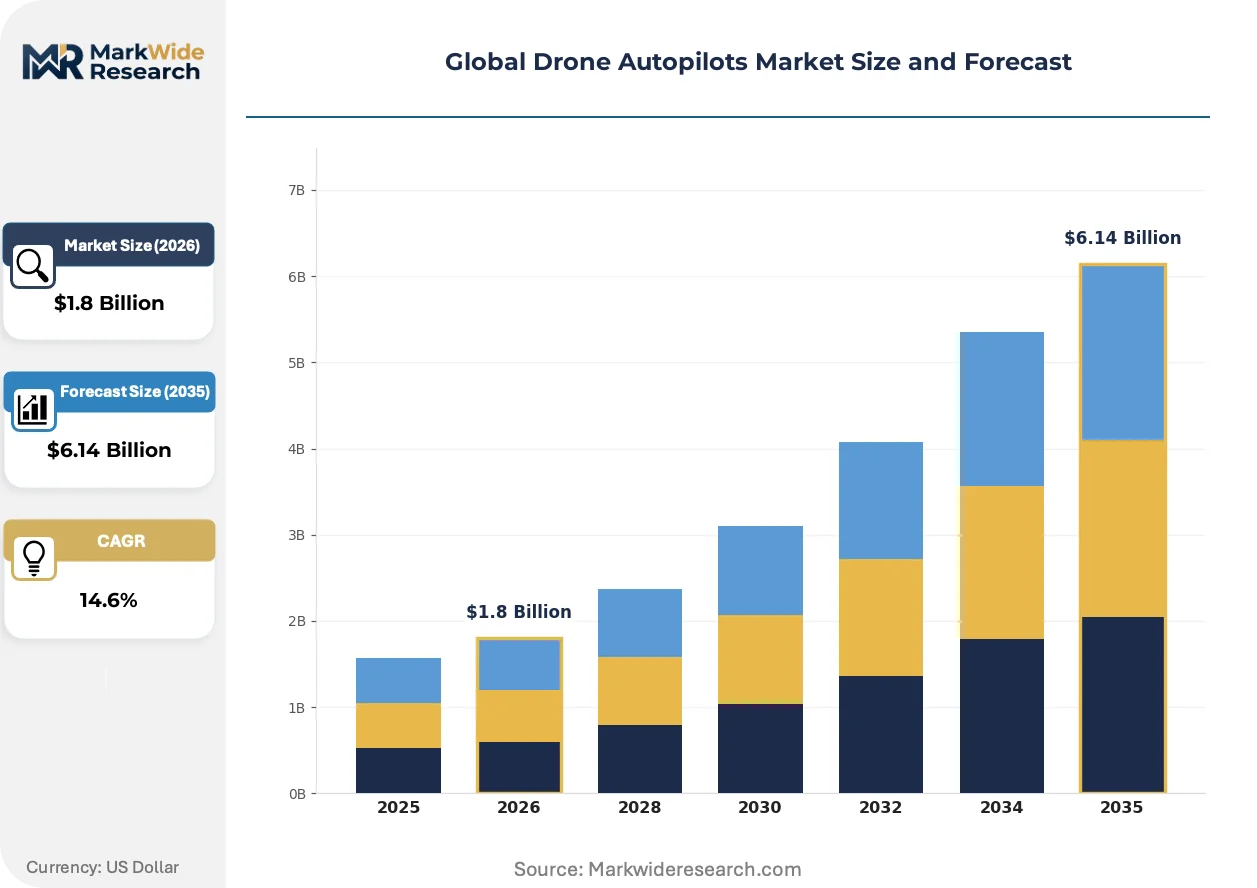
Market Dynamics
Software-defined flight architectures are collapsing the historical separation between integrated flight-stack vendors and modular autopilot suppliers, compressing margins for hardware-centric suppliers while rewarding firmware-agnostic platform providers.
Growth Catalysts
- Brazilian precision agriculture expansion:Autonomous crop-monitoring flight operations are scaling across Mato Grosso and São Paulo states, generating sustained autopilot module demand for spray-drone and multispectral imaging deployments.
- FAA Part 107 framework expansion:Beyond-visual-line-of-sight certification pathways are unlocking commercial route density for last-mile logistics and infrastructure inspection applications.
- Real-time kinematic correction:Centimeter-accurate GPS augmentation is enabling automated takeoff and landing in GPS-challenged environments, expanding addressable use cases for survey and construction monitoring.
Market Restraints
- Semiconductor supply concentration:Captive chip sourcing from Shenzhen's hardware ecosystem creates single-point vulnerability for non-integrated autopilot vendors lacking MIIT-backed supply relationships.
- Detect-and-avoid validation costs:EASA's Specific Category airworthiness requirements impose redundant sensor-suite mandates that inflate per-unit certification expenditure for cross-border platform deployment.
- Optical-flow algorithm commoditization:Open-source visual-inertial odometry libraries are eroding premium pricing for computer-vision navigation modules in consumer-tier applications.
Strategic Opportunities
- Urban air mobility corridors:CAAC-MIIT low-altitude economy zoning in designated Chinese metropolitan zones is accelerating commercial route approval timelines for autonomous passenger and cargo platforms.
- Lidar payload integration density:Mapping applications are demanding higher-resolution point-cloud generation, creating upgrade cycles for autopilot modules with expanded payload power and data-throughput capacity.
- Defense thermal surveillance:Infrared sensor configuration requirements for military end users are opening specialized procurement channels with extended contract durations and restricted vendor pools.
Industry Challenges
- Sub-100-millisecond control-loop engineering:Sensor fusion latency requirements demand scarce embedded systems talent capable of real-time kernel optimization across heterogeneous processor architectures.
- Type-certification timeline fragmentation:Regulatory harmonization failure between FAA, EASA, and CAAC validation protocols is multiplying software verification costs for multi-jurisdictional platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drone Autopilots Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Computer Vision, GPS Navigation, Lidar, Infrared Sensors Application: Agriculture, Surveillance, Delivery, Mapping End User: Aerospace, Defense, Civil, Entertainment Size: Small, Medium, Large, Commercial |
| Companies Covered | JOUAV, Autel Robotics, DJI Innovations, EHang, Parrot, Skydio, Yuneec, ACSL Inc, XAG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drone Autopilots Market Emerging Trajectories
Edge-computing migration and neural-network inference acceleration are redefining autopilot processing architectures, shifting computational load from ground stations to airborne units while enabling GPS-denied navigation in contested electromagnetic environments.
Multi-core ARM-based system-on-chip architectures are miniaturizing flight-control processing into sub-5-gram form factors. Defense contractors and confined-space inspection operators are adopting these modules for swarm-coordination and tunnel-navigation applications. Component density compression is enabling dual-redundant autopilot configurations in consumer-tier price brackets previously restricted to commercial platforms.
EASA's AI Act conformity assessment requirements for autonomous decision-making systems are imposing algorithmic transparency mandates on computer-vision navigation suppliers. Manufacturers must now document training-data provenance and inference-logic auditability for type-certification eligibility. European commercial operators are prioritizing FCC-certified platforms with pre-validated EASA technical documentation to compress approval timelines.
Buyer preference is consolidating around firmware-agnostic hardware platforms that permit third-party flight-stack installation. Agricultural cooperatives in Brazil and survey contractors in Australia are rejecting locked-ecosystem autopilots in favor of modular units supporting PX4 and ArduPilot open-source architectures. This unbundling of hardware from software is compressing vendor switching costs and fragmenting supplier concentration in price-sensitive volume segments.
Global Drone Autopilots Market Segmentation
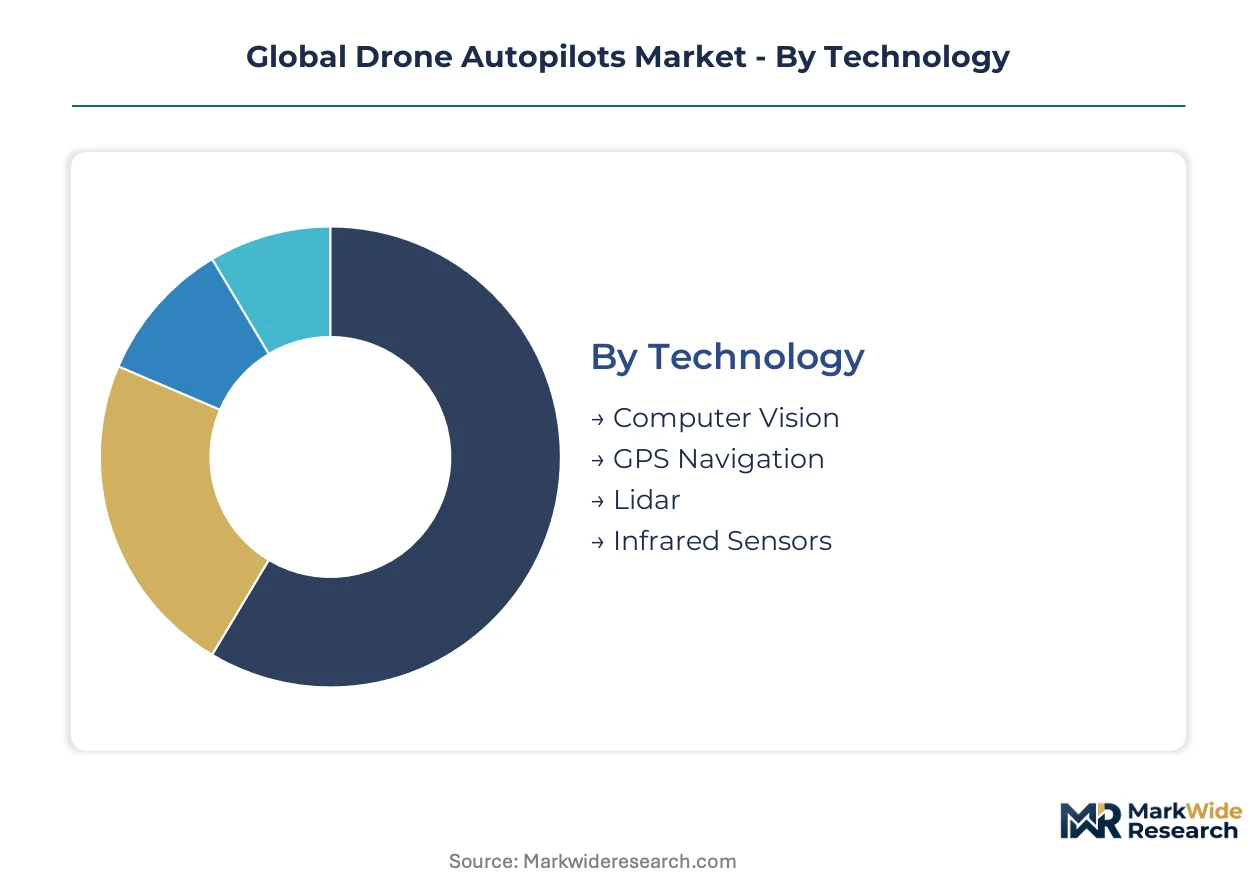
Drone autopilot segmentation reveals how regulatory frameworks fragment certification requirements across technology tiers, while application-specific performance thresholds determine module specification and procurement patterns.
Technology:
FAA Part 107 and EASA's Specific Category impose divergent sensor-redundancy mandates that reshape technology-tier economics.
- Computer Vision:Optical-flow and visual-inertial odometry algorithms process terrain features for GPS-denied navigation in confined spaces. EASA's AI Act conformity assessments now demand training-data provenance documentation, compressing margins for European-bound suppliers.
- GPS Navigation:Real-time kinematic correction modules deliver centimeter-accurate positioning for automated takeoff and landing sequences. Brazilian precision agriculture operators in Mato Grosso deploy these systems for spray-drone corridor tracking across expansive soy and corn operations.
- Lidar:Point-cloud generation for high-resolution mapping demands expanded payload power capacity.
- Infrared Sensors:Thermal surveillance configurations serve defense procurement channels with extended contract durations.
Established volume favors GPS Navigation; emerging adoption favors Computer Vision.
Application:
Customer procurement patterns concentrate in firmware-agnostic platforms that permit third-party flight-stack installation.
- Agriculture:Spray-drone and multispectral imaging deployments anchor volume demand, with Brazilian cooperatives rejecting locked-ecosystem autopilots for modular PX4-compatible units. Crop-scouting automation in São Paulo state drives sustained module replacement cycles.
- Surveillance:Infrastructure inspection and perimeter monitoring require sub-100-millisecond control-loop latency for stable footage capture. China's CAAC low-altitude economy zoning accelerates commercial route approval for urban corridor operations.
- Delivery:Last-mile logistics platforms demand beyond-visual-line-of-sight certification compliance.
- Mapping:Survey contractors in Australia prioritize Lidar payload integration density for construction monitoring.
Margin concentration sits with Surveillance; steepest expansion trajectory belongs to Delivery.
End User:
Defense procurement operates through restricted vendor pools with specialized thermal configuration requirements.
- Aerospace:Urban air mobility platforms require type-certification across FAA, EASA, and CAAC jurisdictions, multiplying software validation costs. Shenzhen's hardware ecosystem feeds component supply for passenger drone autopilot assembly.
- Defense:Infrared sensor configurations and swarm-coordination capabilities command premium positioning with extended contract durations. Confined-space tunnel navigation drives adoption of sub-5-gram multi-core ARM system-on-chip modules.
- Civil:Commercial operators prioritize FCC-certified platforms with pre-validated EASA technical documentation.
- Entertainment:Consumer-tier cinematography demands dual-redundant configurations at compressed price points.
Contract duration favors Defense; volume scale favors Civil.
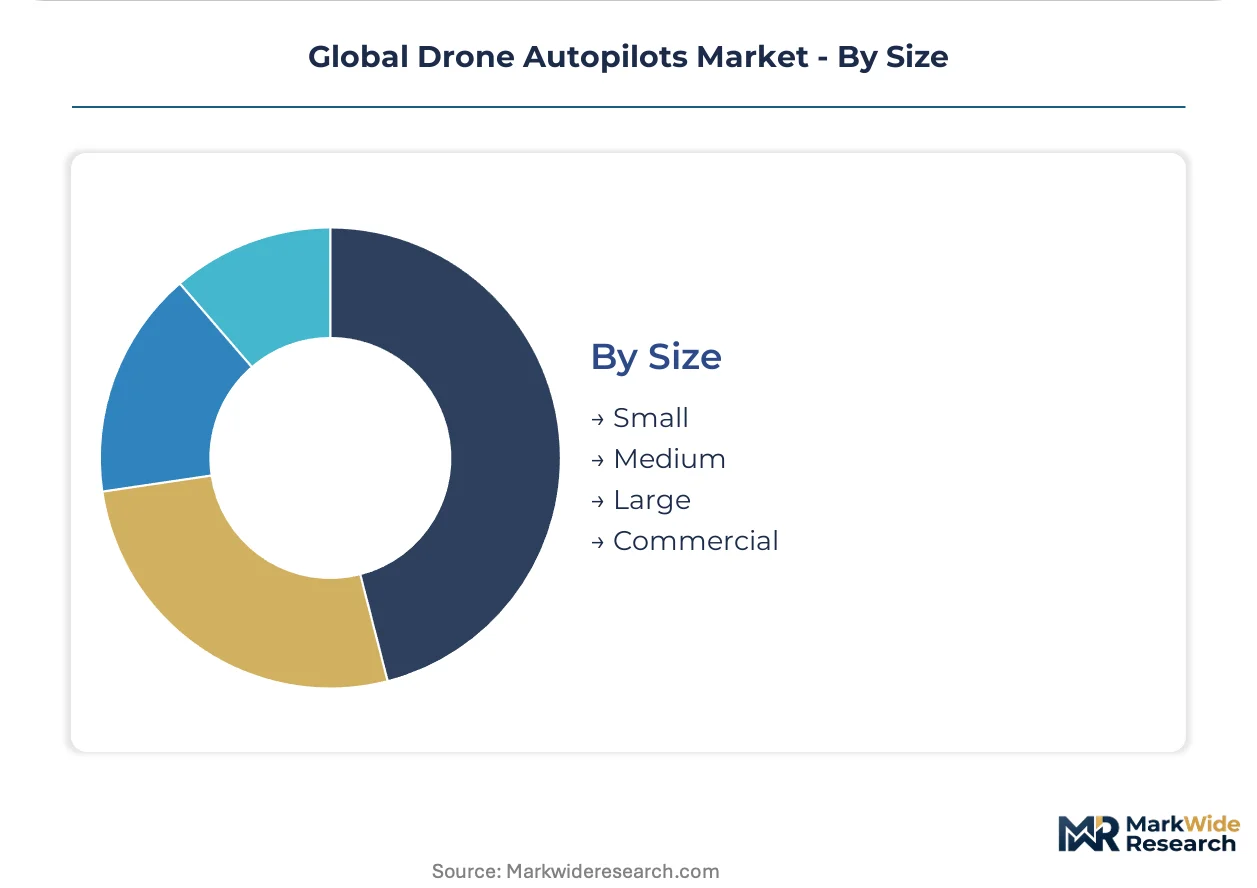
Size:
Component density compression enables capability migration across traditional tier boundaries.
- Small:Sub-5-gram form factors enable swarm-coordination and tunnel-navigation applications previously restricted to larger platforms. Defense contractors adopt these modules for contested electromagnetic environment operations.
- Medium:Agricultural spray-drones in Brazil's Mato Grosso state concentrate procurement in this tier, balancing payload capacity with cost sensitivity. Multirotor configurations dominate for crop-monitoring missions.
- Large:Fixed-wing platforms for long-range mapping require expanded power and data-throughput capacity.
- Commercial:Firmware-agnostic hardware supporting ArduPilot architectures fragments supplier concentration.
Technology transfer favors Small; procurement volume favors Medium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Shenzhen's hardware ecosystem while certification arbitrage favors North American platform vendors. Brazilian agricultural operators absorb margin compression through volume procurement of modular autopilot units. European compliance costs fragment supplier profitability across EASA jurisdiction boundaries.
United States
Last-mile logistics operators and infrastructure inspection contractors drive module procurement at scale. FAA Part 107 beyond-visual-line-of-sight expansions compress commercial certification timelines for cross-state route deployment. Silicon Valley flight-stack developers and Boston-area autonomy researchers anchor software-defined architecture migration.
China
Urban air mobility corridor approvals and agricultural spray-drone fleet renewals concentrate demand in Guangdong province. CAAC-MIIT low-altitude economy zoning accelerates commercial route validation in designated metropolitan airspace. Shenzhen's component ecosystem feeds captive semiconductor sourcing for autopilot module assembly at compressed cost structures.
Brazil
Mato Grosso soy cooperatives and São Paulo crop-scouting deployers generate sustained autopilot replacement cycles for spray-drone applications. ANVISA coordination with civil aviation regulators streamlines agricultural UAV type-certification pathways. Campinas hardware integrators and Piracicaba agtech clusters specialize in PX4-compatible modular unit distribution.
Germany
Industrial inspection contractors and mapping surveyors prioritize EASA pre-validated platform procurement. EU AI Act conformity assessments impose algorithmic transparency mandates on computer-vision navigation suppliers. Munich autonomy engineering centers and Stuttgart aerospace clusters drive detect-and-avoid sensor fusion development.
Australia
Mining corridor survey operators and construction monitoring contractors demand centimeter-accurate RTK correction modules. CASA beyond-visual-line-of-sight framework expansions unlock remote infrastructure inspection route density. Brisbane hardware distributors and Perth mining-technology integrators specialize in ArduPilot-compatible ruggedized autopilot deployment.
Global Drone Autopilots Market Vendor Landscape
Concentration sits with integrated flight-stack vendors possessing captive semiconductor sourcing relationships. Tier fragmentation emerges between firmware-agnostic modular suppliers and locked-ecosystem platform providers. Three archetypes dominate: Shenzhen-based hardware-integrated stack vendors, North American computer-vision specialists, and European certification-focused system integrators. Competitive moves center on strategic partnerships with agricultural fleet operators and technology licensing for defense procurement channels.
Within the integrated-stack tier, DJI Innovations and EHang exemplify hardware-captive sourcing strategies that resist margin compression across consumer and enterprise tiers. Skydio occupies a position among computer-vision-first navigation specialists targeting confined-space defense applications. Autel Robotics sits within the certification-focused archetype, leveraging FCC-validated platforms for North American commercial deployment acceleration.
| Leading Market Players |
|---|
| JOUAV |
| Autel Robotics |
| DJI Innovations |
| EHang |
| Parrot |
| Skydio |
| Yuneec |
| ACSL Inc |
| XAG |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts between Guangdong-based semiconductor foundries and integrated flight-stack vendors lock in component access while freezing price visibility across multi-year procurement cycles. This contract structure insulates captive-sourcing incumbents from spot-market volatility while exposing modular autopilot suppliers to margin compression when silicon wafer allocations tighten.
Pricing Analysis
The customization-premium spread separates configured-to-order autopilot modules with EASA pre-validated documentation from standard-tier units shipping with open-source firmware compatibility. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and payload integration density as primary differentiation drivers. Price erosion runs through the economy tier as PX4-compatible hardware commoditizes, while premium positioning holds firm for defense-grade thermal configurations. Agricultural cooperatives in Brazil exhibit highest price sensitivity, whereas urban air mobility operators in China absorb premium pricing for CAAC-fast-tracked certification bundles.
Supply Chain Analysis
Just-in-time inventory strategies dominate among North American commercial drone assemblers, while Chinese integrated-stack vendors maintain strategic stockpiles of MIIT-prioritized semiconductor wafers. Supply concentration centers on China for system-on-chip fabrication, South Korea for memory components, and Taiwan for gyroscope MEMS sensors. Raw material dependencies span silicon wafers, rare-earth magnets for motor control, and high-grade aluminum for thermal management housings. Single-source vulnerability from Shenzhen's hardware ecosystem creates exposure for non-integrated vendors lacking MIIT-backed allocation priority. Distribution runs through direct OEM relationships for volume tiers and specialized agtech distributors for modular units in Brazil and Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among agricultural fleet operators and defense procurement offices, fragmenting vendor pricing leverage as volume procurement consolidates under fewer contract signatures.
For Market Incumbents: Consolidate backward integration into semiconductor sourcing through MIIT-allied foundry partnerships to defend against margin compression from open-source firmware commoditization. Lock in multi-year offtake agreements with Mato Grosso soy cooperatives before Brazilian agtech distributors fragment channel control. Priority investment in EASA technical documentation pre-validation compresses approval timelines for European-bound platforms. For New Entrants and Emerging Players: Lead with firmware-agnostic hardware architectures targeting Australian mining survey contractors currently locked out by DJI's closed ecosystem. The most penetrable white space sits in ArduPilot-compatible ruggedized modules for CASA-certified beyond-visual-line-of-sight operations. Go-to-market acceleration through Brisbane hardware distributors with established Perth mining-technology relationships bypasses direct OEM sales cycle length. For Investors and Strategic Acquirers: Capital is best deployed toward computer-vision navigation specialists possessing EASA AI Act conformity assessment documentation and defense-cleared engineering teams. Long-term viability across the projection horizon favors acquisition targets with dual-use technology credentials spanning civil certification and restricted military procurement channels. The signal to watch is CAAC low-altitude economy corridor expansion velocity as inflection indicator for urban air mobility autopilot demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Validation Investment | EASA technical documentation bundling compresses European market entry timelines for FCC-certified platforms. |
| Firmware-Agnostic Hardware Launch | PX4 and ArduPilot compatibility fragments supplier concentration among price-sensitive agricultural volume segments. |
| Defense Thermal Configuration Development | Infrared sensor integration opens restricted procurement channels with extended contract durations and premium pricing. |
| Urban Air Mobility Partnership | CAAC corridor approval alignment accelerates commercial route validation for autonomous passenger platforms. |
| Real-Time Kinematic Module Integration | Centimeter-accurate GPS augmentation expands addressable use cases for survey and construction monitoring applications. |
Methodological Framework
Operator-level perspectives from flight-control engineering leads at integrated-stack vendors, procurement managers at Brazilian agricultural cooperatives, certification specialists at EASA-notified bodies, and defense program officers at thermal surveillance contractors anchored the qualitative base. Secondary validation drew from FAA Part 107 regulatory filings, CAAC low-altitude economy zoning announcements, EASA AI Act conformity assessment guidance documents, and customs trade data for autopilot module component flows. Bottom-up segmentation modeling triangulated against top-down market sizing from semiconductor consumption patterns and OEM production forecasts.
Sensitivity analysis tested forecast robustness across regulatory harmonization scenarios, semiconductor allocation priority shifts, and defense procurement budget trajectories throughout the projection horizon. Segmentation dimensions spanned technology tier, application vertical, end-user category, and platform size class, with additional modeling of certification pathway complexity across FAA, EASA, and CAAC jurisdictions. CAGRs were derived from regression analysis of historical module shipment volumes against explanatory variables including agricultural fleet renewal cycles and urban air mobility corridor approvals. Industry-specific inputs incorporated RTK correction module adoption curves and Lidar payload power capacity upgrade frequencies.
The analysis sits within stated boundaries; outcomes outside sustained CAAC-MIIT low-altitude economy policy support or abrupt EASA detect-and-avoid mandate acceleration would require recalibration. Forecasts reflect documented assumptions regarding semiconductor supply normalization and defense thermal surveillance procurement continuity. Revision becomes warranted when regulatory harmonization failure between FAA, EASA, and CAAC crosses thresholds that fragment software validation requirements beyond modeled cost multipliers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Portable Drone Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
Global Multirotor UAV Market
UAV
North America Tactical UAV Market
UAV
Global Drone Data Services Market
UAV
North America Small UAV Market
UAV
Europe Tethered Drone Market
UAV
Middle-East and Africa Drones Market
UAV
Stratospheric Flying Drone Market
UAV
Racing Drone Market
UAV
Drone Camera Market
UAV
Inspection Drones in Confined Space Market
UAV
Fixed-Wing VTOL UAV Market
UAV
Global Drone Services Market
UAV
Drone Flight Controller System Market
UAV
Global Drone Sensor Market