
 Solar Photovoltaic Glass Market | 2026-2036
Solar Photovoltaic Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Photovoltaic Glass Market Intelligence
A divergence in capital intensity between integrated manufacturers and specialty finishers is rotating the competitive landscape. Xinyi Solar Holdings Ltd. leverages its immense scale in float glass production to control costs for utility-scale projects. In contrast, Saint-Gobain differentiates through advanced anti-reflective coatings and specialized glass solutions for building-integrated photovoltaics. Borosil Renewables focuses on tempered low-iron solar glass, serving specific regional and niche application demands.
Solar photovoltaic glass is an ultra-clear, low-iron material engineered for maximum light transmittance, typically exceeding 91%. Its primary function is to encapsulate and protect delicate photovoltaic cells from environmental factors while ensuring optimal solar energy absorption. Anti-reflective glass is becoming a standard for performance, commanding a price premium over basic tempered glass. While utility-scale solar farms constitute the largest application segment, bifacial technology is creating new demand for highly transparent rear-side glass.
National energy policies, including China's dual carbon goals and the US Inflation Reduction Act (IRA), directly incentivize domestic solar manufacturing. Concurrently, standards like the EU's RoHS directive and CE marking govern material composition and product safety for market access. Manufacturers must decide whether to compete on volume for utility projects or specialize in high-performance glass for building-integrated PV.
Market Dynamics
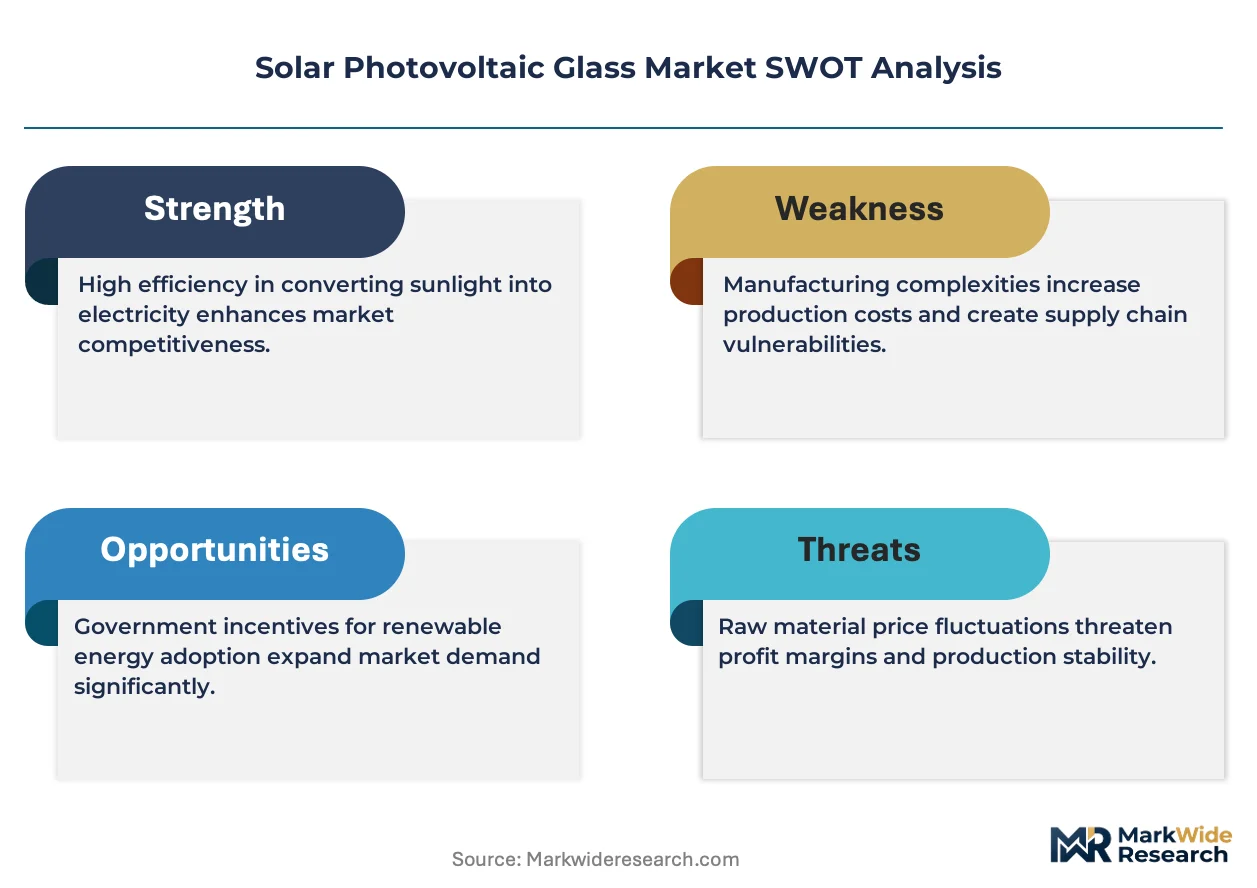
The central dynamic in the solar photovoltaic glass market is the divergence between high-volume, cost-driven production for utility-scale applications and the development of high-performance, specialized glass for premium segments like building-integrated photovoltaics (BIPV).
Growth Catalysts
- National Energy Policies:China's dual carbon goals and the US Inflation Reduction Act (IRA) are creating sustained, large-scale demand by mandating renewable energy targets and incentivizing domestic solar component manufacturing.
- Bifacial Technology Adoption:The increasing use of bifacial solar panels, which generate power from both sides, creates a distinct need for highly transparent and durable rear-side glass, expanding the total glass volume per module.
- Building-Integrated PV (BIPV):Architectural demand for aesthetically integrated solar solutions in facades, windows, and roofing is driving innovation in colored, textured, and semi-transparent solar glass, opening a high-margin application segment.
Market Restraints
- Raw Material Volatility:The price and availability of high-purity, low-iron silica sand, the primary raw material for ultra-clear solar glass, are subject to significant fluctuation and supply constraints, impacting manufacturer cost structures.
- Supply Chain Concentration:An overwhelming concentration of primary float glass production capacity within China creates geopolitical risks and logistical vulnerabilities for solar panel manufacturers in other regions.
- Substitution from Polymer Films:In certain niche and flexible PV applications, advanced polymer-based backsheets and frontsheets present a lower-weight and potentially lower-cost alternative, posing a substitution threat to glass.
Strategic Opportunities
- Agrivoltaics Glass:Developing specialized glass that optimizes light transmission for specific crop types while generating electricity offers a significant opportunity in the emerging agrivoltaics sector, where land use is dual-purpose.
- Geographic Diversification:Government incentives in India, such as the Production Linked Incentive (PLI) scheme, create a major opportunity for establishing new, localized solar glass manufacturing to serve its rapidly growing domestic market.
- Integrated Self-Cleaning Surfaces:Incorporating permanent hydrophobic or photocatalytic coatings directly into the glass manufacturing process offers a path to differentiate products by reducing soiling losses and maintenance costs for asset owners.
Industry Challenges
- High Capital Expenditure:The construction of new float glass production lines requires immense upfront capital investment and long lead times, creating a high barrier to entry and limiting the supply response to demand surges.
- End-of-Life Recycling:Developing scalable and economically viable processes for separating and recycling solar glass from end-of-life PV modules remains a significant operational challenge for the industry's long-term sustainability.
- Bifacial Standardization:A lack of universally accepted standards for measuring and certifying the performance and durability of rear-side glass in bifacial modules creates uncertainty for project developers and financiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Photovoltaic Glass Market |
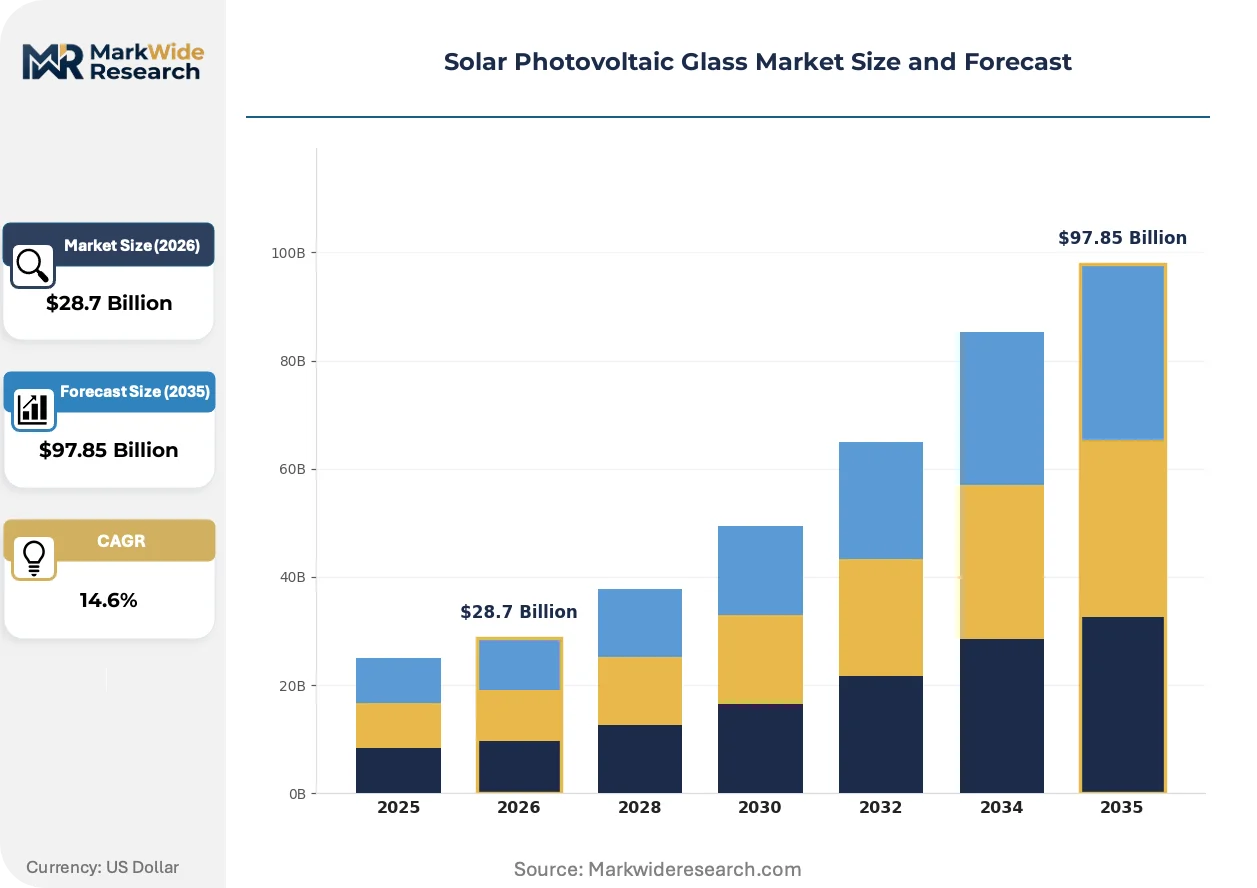
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $97.85 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Heat Strengthened Glass, Anti-reflective Glass, Low-Iron Glass Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial, Concentrated PV Application: Building Integrated, Utility-scale Solar Farms, Residential Rooftop, Commercial Solar Panels, Off-grid Systems End User: Energy Developers, Rooftop Installers, Commercial Enterprises, Government Agencies, Research Institutions |
| Companies Covered | Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd, IRICO Group New Energy Co., Ltd., AGC Inc., Saint-Gobain, CSG Holding Co. Ltd., Borosil Renewables, NSG Pilkington, Dongguan CSG Solar Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Photovoltaic Glass Market Strategic Shifts & Innovations
Material science advancements are enabling higher energy conversion efficiencies, while parallel policy shifts are reshaping supply chain geography. This dual evolution forces manufacturers to compete on both technical performance and strategic alignment with national industrial policies.
Anti-reflective (AR) coated glass is a specialized product featuring a nanometer-scale surface layer that reduces light reflection and maximizes transmittance. Utility-scale solar project developers are rapidly adopting AR-coated glass to boost the energy yield and financial returns of their assets. Consequently, AR-coated glass is supplanting basic tempered glass as the new performance standard in large-scale solar deployments.
The US Inflation Reduction Act (IRA) provides significant tax credits for domestic production of solar components, directly impacting manufacturing decisions. This policy is stimulating investment in new solar glass production facilities within the United States to reduce reliance on imported materials. The utility-scale segment is most affected, as developers seek to maximize IRA benefits by sourcing components from a revitalized domestic supply chain.
A notable shift in purchasing behavior involves buyers prioritizing lifecycle performance and bankability over minimal upfront cost. This change disrupts traditional spot-market procurement, favoring manufacturers who can provide extensive degradation warranties and third-party validated performance data. This trend is most pronounced in North American and European project finance, where investors and lenders scrutinize long-term asset risk.
Solar Photovoltaic Glass Market Segmentation
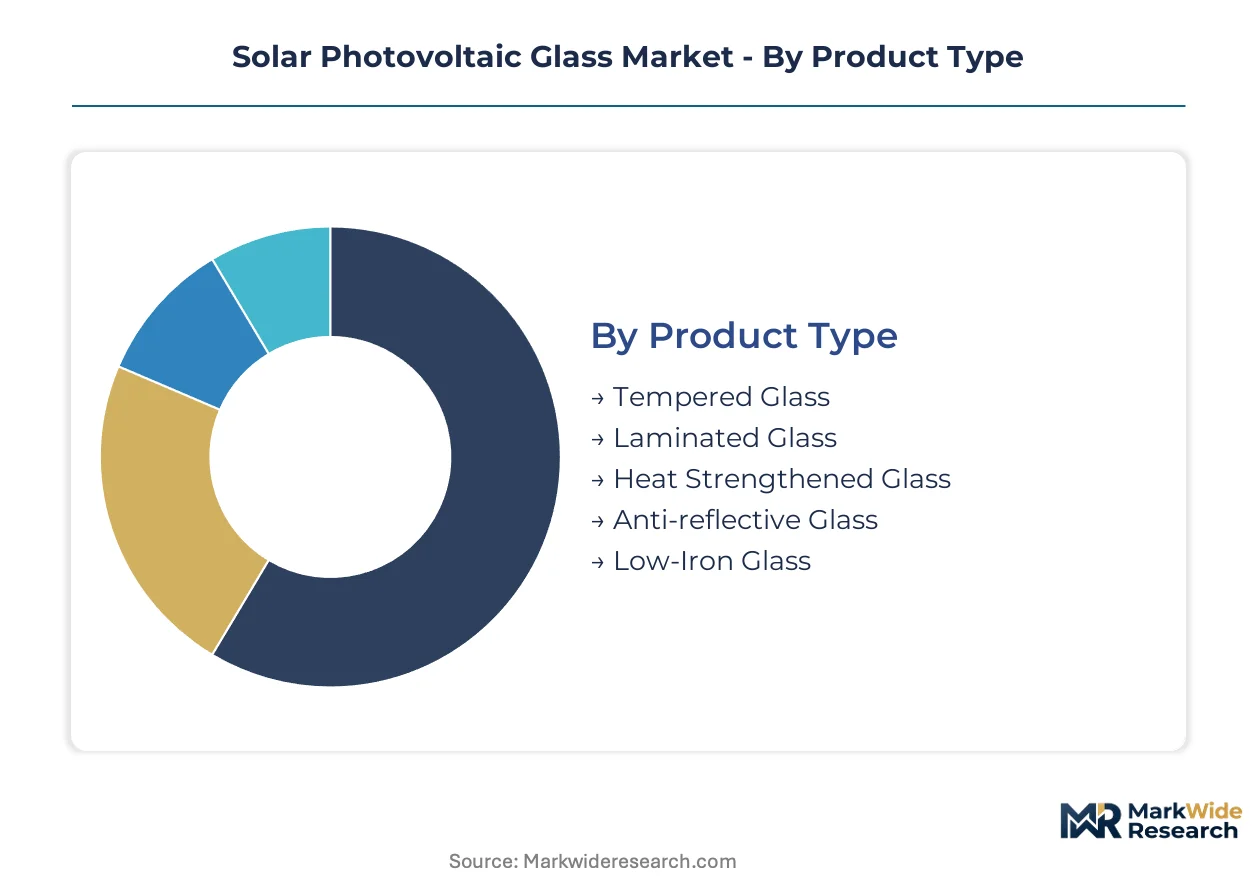
The solar photovoltaic glass market segmentation reveals distinct value propositions and competitive battlegrounds for manufacturers. Understanding these segments helps companies align production capabilities with evolving demand patterns and regulatory incentives. Each category reflects different technical requirements and market dynamics.
Product Type:
Margin pools within product type segmentation heavily concentrate in advanced performance solutions like anti-reflective coatings and specialized low-iron formulations.
- Anti-reflective Glass:This specialized product features a nanometer-scale surface layer that reduces light reflection, maximizing light transmittance to photovoltaic cells. Utility-scale solar farm developers in the United States and China increasingly adopt AR-coated glass to boost energy yield and project financial returns.
- Tempered Glass:This glass undergoes a controlled thermal or chemical treatment to increase its strength and safety, making it resistant to impact and temperature fluctuations. Borosil Renewables focuses on tempered low-iron solar glass, serving specific regional demands in India and niche application requirements.
- Laminated Glass:Comprising two or more glass layers bonded with an interlayer, laminated glass offers enhanced durability and safety against breakage.
- Heat Strengthened Glass:Subjected to a heating and cooling process, this glass offers increased mechanical strength and thermal shock resistance compared to annealed glass.
- Low-Iron Glass:Engineered with minimal iron content, this ultra-clear glass maximizes light transmission for optimal solar energy absorption.
Tempered Glass holds installed capacity. Anti-reflective Glass is rotating up the share rankings.
Technology:
Cost efficiency and energy conversion rates differentiate technology segments, with newer innovations commanding premium pricing in specialized applications.
- Bifacial:Bifacial technology allows solar panels to generate electricity from both their front and rear sides, requiring highly transparent and durable glass for the backsheet. The increasing use of bifacial solar panels in utility-scale projects expands the total glass volume per module in regions like Europe.
- Monocrystalline:Characterized by high efficiency and a uniform appearance, monocrystalline technology utilizes single-crystal silicon cells. Global demand for high-performance modules often drives the use of monocrystalline cells in residential and commercial installations.
- Polycrystalline:Consisting of multiple silicon crystals, polycrystalline panels offer a cost-effective alternative with good efficiency for various solar applications.
- Thin Film:This technology uses thin layers of photovoltaic material, allowing for flexible and lightweight solar panels suitable for specialized architectural integration.
- Concentrated PV:CPV systems use lenses or mirrors to focus sunlight onto small, high-efficiency solar cells, requiring specialized glass components for optical performance.
Monocrystalline technology maintains a broad market presence. Bifacial technology is expanding most quickly due to performance advantages.
Application:
Volume concentration dictates the market dynamics within application segments, with utility-scale projects consuming the largest share of solar glass.
- Utility-scale Solar Farms:These large-scale installations generate electricity for power grids, demanding vast quantities of standardized, high-performance solar glass. Expanded deployment in China and the United States drives significant glass demand for utility-scale projects.
- Building Integrated:BIPV integrates solar technology directly into building elements like facades, windows, and roofing, requiring aesthetically customized and specialized glass solutions. Architectural demand for seamless integration in European cities fuels innovation in colored and semi-transparent solar glass.
- Residential Rooftop:Solar panels installed on residential homes primarily aim for energy self-sufficiency and reduced electricity bills.
- Commercial Solar Panels:These systems are deployed on commercial buildings or properties to offset energy consumption and achieve sustainability goals.
- Off-grid Systems:Providing electricity to remote locations without access to the main power grid, off-grid systems require robust and reliable solar glass solutions.
Utility-scale Solar Farms command the largest volume. Building Integrated applications are gaining share fastest in niche markets.
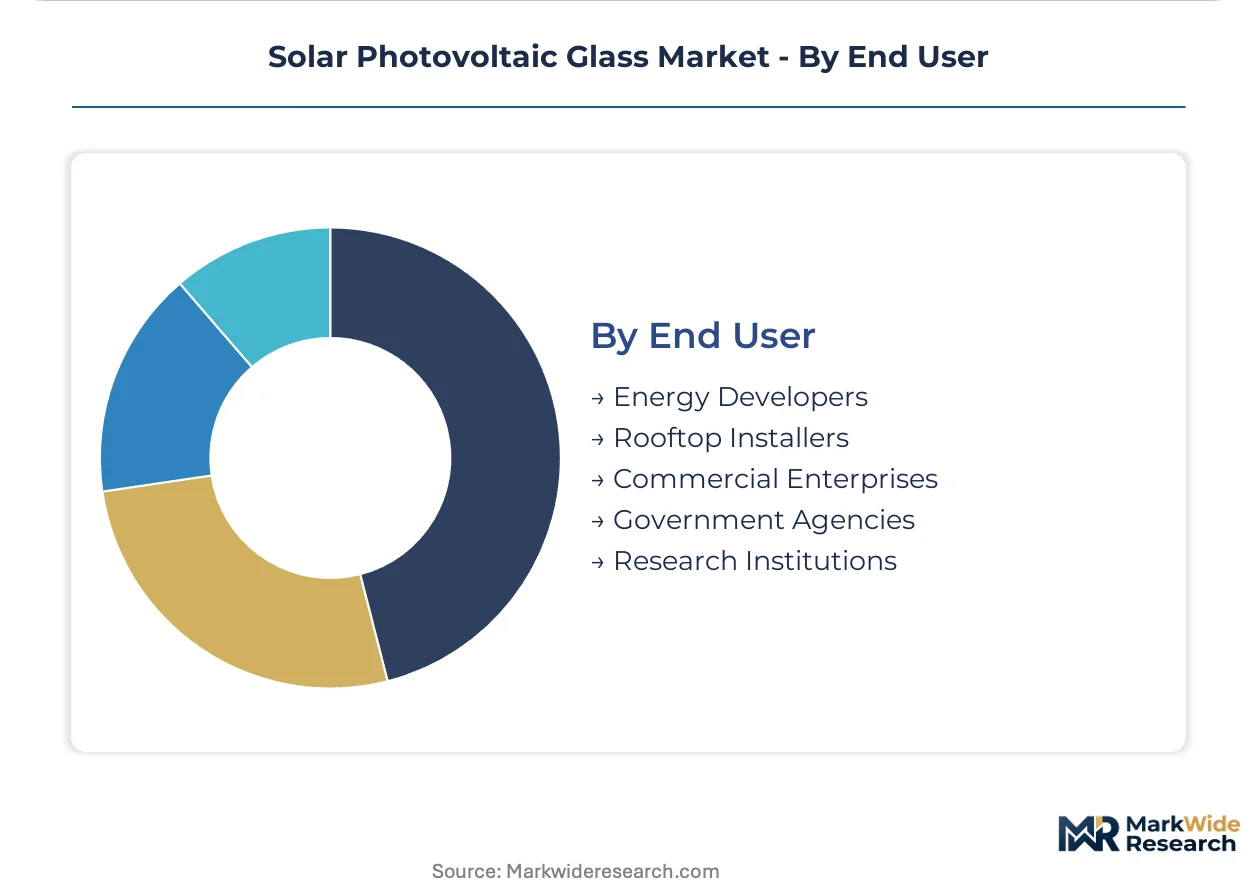
End User:
Customer type influences procurement strategies and product specifications, with energy developers focusing on scale and long-term performance.
- Energy Developers:These entities plan, finance, and construct large-scale solar power plants, prioritizing cost-effective, high-performance glass with long-term warranties. Energy developers in India are actively seeking localized solar glass manufacturing to support ambitious project pipelines.
- Commercial Enterprises:Businesses installing solar solutions on their premises seek durable, efficient panels to reduce operational costs and meet corporate sustainability targets. Commercial enterprises in Germany often prioritize certified, high-quality solar glass for their installations.
- Rooftop Installers:Companies specializing in installing solar panels on residential and small commercial rooftops require reliable and easy-to-handle glass products.
- Government Agencies:These entities may procure solar glass for public infrastructure projects or to support national renewable energy initiatives.
- Research Institutions:Academic and private research bodies utilize specialized solar glass for testing new technologies and improving photovoltaic efficiency.
Energy Developers drive substantial procurement volume. Commercial Enterprises show a steepest expansion trajectory in their solar adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for solar photovoltaic glass exhibits varying elasticity across regions. Utility-scale projects in some areas prioritize cost-efficiency, while others emphasize specialized performance for high-value applications. This distinction shapes regional market dynamics and investment patterns for manufacturers.
China
China's vast utility-scale solar farm deployments drive immense demand for photovoltaic glass. The nation's dual carbon goals and national manufacturing policies strongly incentivize domestic production. The Yangtze River Delta region concentrates significant float glass production capacity, supporting global supply chains.
United States
Utility-scale projects and emerging domestic solar manufacturing initiatives generate substantial demand in the United States. The US Inflation Reduction Act (IRA) provides significant tax credits for local component production. New solar glass production facilities are emerging in the Southeast US to reduce reliance on imported materials.
India
India's rapidly expanding domestic market and ambitious solar project pipelines create a strong demand for photovoltaic glass. The Production Linked Incentive (PLI) scheme incentivizes localized manufacturing of solar components. Gujarat is becoming a hub for new solar glass production, aiming to serve national energy developers.
Germany
European architectural demand for building-integrated photovoltaics and commercial solar installations drives specialized glass solutions in Germany. The EU's RoHS directive and CE marking govern material composition for market access. Bavaria focuses on advanced glass solutions, supporting high-efficiency BIPV projects across the region.
Japan
Japanese demand for high-performance monocrystalline modules and specialized architectural integration requires advanced solar glass. METI policies encourage innovation in renewable energy technologies and component manufacturing. The Kansai region hosts significant research institutions focusing on PV efficiency and material science advancements.
Solar Photovoltaic Glass Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the solar photovoltaic glass market. The industry structure exhibits a clear bifurcation between high-volume integrated manufacturers and specialized finishers. Large-scale float glass producers leverage immense scale for cost control, while niche providers focus on advanced anti-reflective coatings and specialized solutions. These distinct approaches define competitive positioning. Companies primarily engage in capacity expansion and strategic partnerships to secure raw material access and broaden market reach.
At the scale-driven end of the market, Xinyi Solar Holdings Ltd. exemplifies the integrated manufacturer archetype. This Hong Kong-based company leverages its immense float glass production to control costs for utility-scale projects. In contrast, Saint-Gobain, a French multinational corporation, represents the advanced specialty glass segment, differentiating through anti-reflective coatings and building-integrated photovoltaics solutions. India's Borosil Renewables focuses on tempered low-iron solar glass, serving specific regional and niche application demands. These players collectively illustrate the market's divergent strategies, from high-volume standardized products to premium, customized offerings.
| Leading Market Players |
|---|
| Xinyi Solar Holdings Ltd. |
| Flat Glass Group Co., Ltd |
| IRICO Group New Energy Co., Ltd. |
| AGC Inc. |
| Saint-Gobain |
| CSG Holding Co. Ltd. |
| Borosil Renewables |
| NSG Pilkington |
| Dongguan CSG Solar Glass Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Extended lead times for new float glass capacity directly influence supply chain shape and pricing power for solar photovoltaic glass. This capital-intensive industry requires significant upfront investment, creating barriers to entry and affecting the responsiveness of supply to demand surges.
Pricing Analysis
Long-term performance warranties drive initial pricing for solar photovoltaic glass, emphasizing lifecycle value over minimal upfront cost. The dominant pricing model is project-based and contract-driven, particularly for utility-scale deployments. Price differentiation stems from advanced anti-reflective coatings and specialized low-iron formulations, alongside certification levels like CE marking. Pricing pressure stems from high-volume utility-scale projects seeking cost efficiency, while raw material volatility can exert upward pressure. Utility-scale developers exhibit the most price sensitivity, prioritizing cost-effectiveness, whereas BIPV applications value aesthetic integration and specialized performance.
Supply Chain Analysis
Strategic stockpiles of high-purity low-iron silica sand are often preferred by manufacturers to mitigate raw material volatility. The supply chain for primary float glass production concentrates overwhelmingly in China, creating geopolitical risks and logistical vulnerabilities. Key raw material dependencies include high-purity low-iron silica sand and specialized chemicals for coatings. Supply chain risk primarily involves commodity price volatility for critical inputs and potential single-source vulnerabilities. Distribution typically runs through direct contracts with solar module manufacturers and EPC contractors for large projects, alongside specialized channels for BIPV solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar photovoltaic glass market faces a capability scarcity in specialized production processes, particularly for advanced coatings and integrated solutions.
For Market Incumbents:
Consolidate market share by expanding production capacity in strategically important regions like India and the United States, leveraging government incentives such as the PLI scheme and the IRA. Invest in backward integration into silica sand mining to mitigate raw material volatility and secure supply. Develop next-generation self-cleaning and anti-reflective coatings to counter substitution from polymer films and enhance product differentiation. Establish long-term supply agreements with major utility-scale developers to ensure consistent demand.
For New Entrants and Emerging Players:
Anchor in niche, high-margin segments such as agrivoltaics glass or specialized BIPV solutions. Focus on performance differentiation through innovative material science, targeting aesthetic integration and unique functionalities for architectural applications. The most penetrable segment involves specialized glass for building facades and advanced agrivoltaics projects. A compelling go-to-market angle involves offering complete, certified solutions that simplify integration for architects and agricultural developers.
For Investors and Strategic Acquirers:
Carve-out targets emerge from diversified glass manufacturers seeking to divest non-core solar assets or from specialized coating technology firms. The long-term viability of this market hinges on its role in the global energy transition and sustainability goals. Focus on acquiring specialized finishers with proprietary advanced coating intellectual property or regional manufacturers with strong alignment to local energy policies. The signal to watch is the widespread adoption of new recycling technologies for end-of-life solar glass modules.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in New Geographies | New float glass lines in India or the US reduce regional supply chain risks. |
| Advanced Coatings R&D | Enhances anti-reflective properties and integrates self-cleaning surfaces for higher energy yields. |
| Raw Material Security Agreements | Securing long-term contracts for low-iron silica sand mitigates supply volatility. |
| BIPV Product Development | Creates specialized glass solutions for architectural integration in urban environments. |
| Recycling Infrastructure Investment | Develops scalable processes for end-of-life solar glass, addressing industry sustainability challenges. |
Research Approach
A standing panel of float glass production engineers, solar module manufacturers, utility-scale project developers, and BIPV architects provided ongoing calibration. This analysis combines insights from primary interviews with extensive secondary validation from national energy agency reports, company annual reports, and material science journals. Data triangulation through bottom-up and top-down approaches ensured comprehensive market sizing and forecasting.
Forecast outputs were consistently checked against external benchmarks and industry consensus to ensure accuracy across the analysis window. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user, and regional policy frameworks. CAGRs were derived from a synthesis of historical trends and projected market drivers, incorporating industry-specific inputs such as renewable energy targets and raw material price forecasts.
Material uncertainties — geopolitical shifts, raw material supply shocks, or policy reversals — sit outside the modeled envelope, reflecting inherent market complexities. Forecasts reflect assumptions regarding technological advancements and market dynamics. Revision becomes warranted when these external factors cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Vegetable Dryer Market
Solar Power Systems
Solar Concentrator Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Global Photovoltaic Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
United Kingdom Solar Power Market
Solar Power Systems
UV Solar Simulators Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
China Distributed Solar Power Generation Market
Solar Power Systems
Solar Panel Cleaning Equipment Market
Solar Power Systems
Utility Scale PV Inverter Market
Solar Power Systems
Global Micro Solar Inverter Market