
 Single Axis Solar PV Tracker Market | 2026-2036
Single Axis Solar PV Tracker Market Size, Share, and Industry Trends Forecast 2026-2036
Single Axis Solar PV Tracker Market Analysis
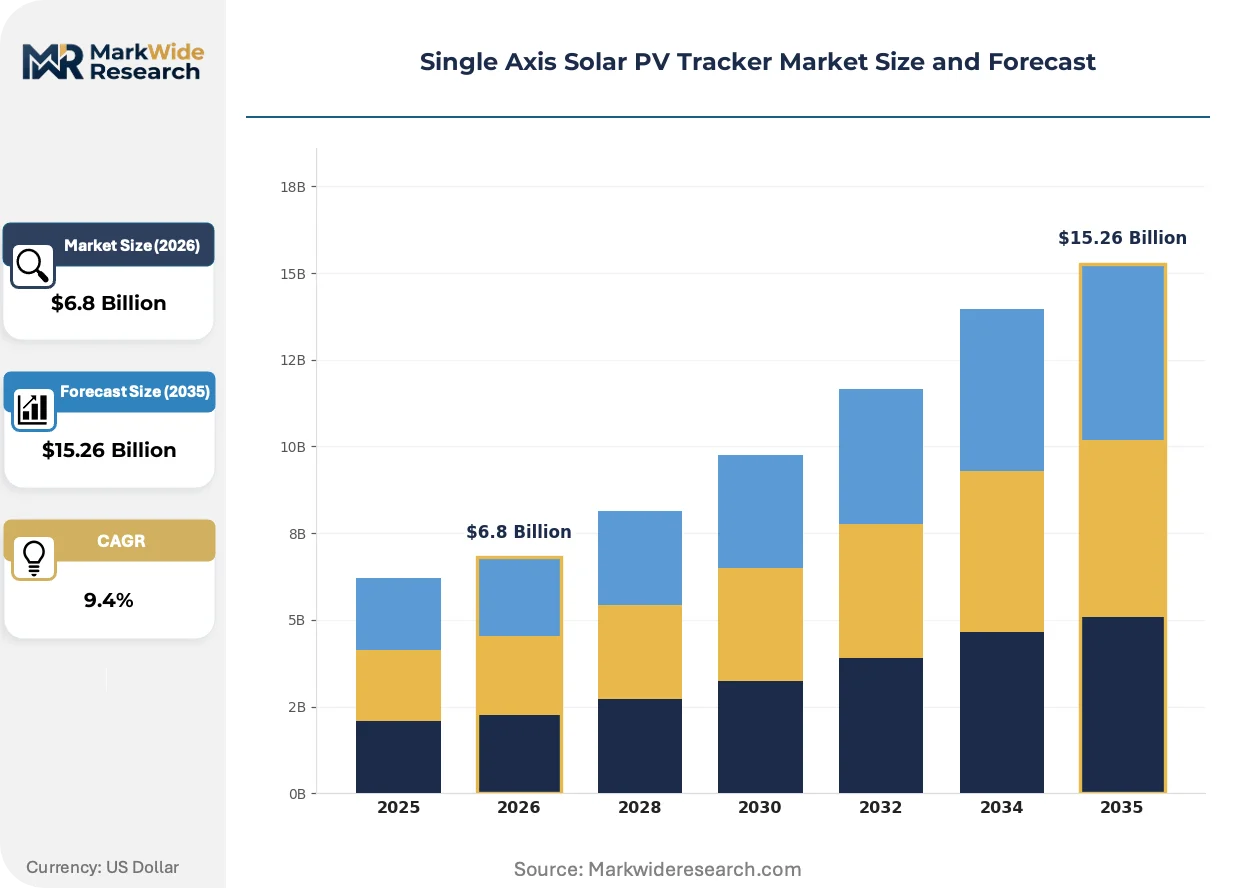
The EU Green Deal is expanding the addressable market for tracker-equipped solar farms across member states with binding renewable targets. Nextracker leverages its steel supply partnerships to control input costs across project pipelines. Array Technologies anchors its competitive position through domestic manufacturing capacity in the southwestern United States. Soltec Power Holdings dominates European project development with terrain-adaptive tracker designs.
A single axis solar PV tracker rotates photovoltaic modules along one axis to follow the sun's daily path, typically increasing energy yield by 20-25% over fixed-tilt systems through east-west tracking. The ground-mounted segment leads installation volumes due to scale economies in utility procurement, while bifacial tracker configurations represent the fastest-growing product category as dual-sided module adoption accelerates. Independent power producers drive end-user demand through long-term power purchase agreements that reward generation optimization.
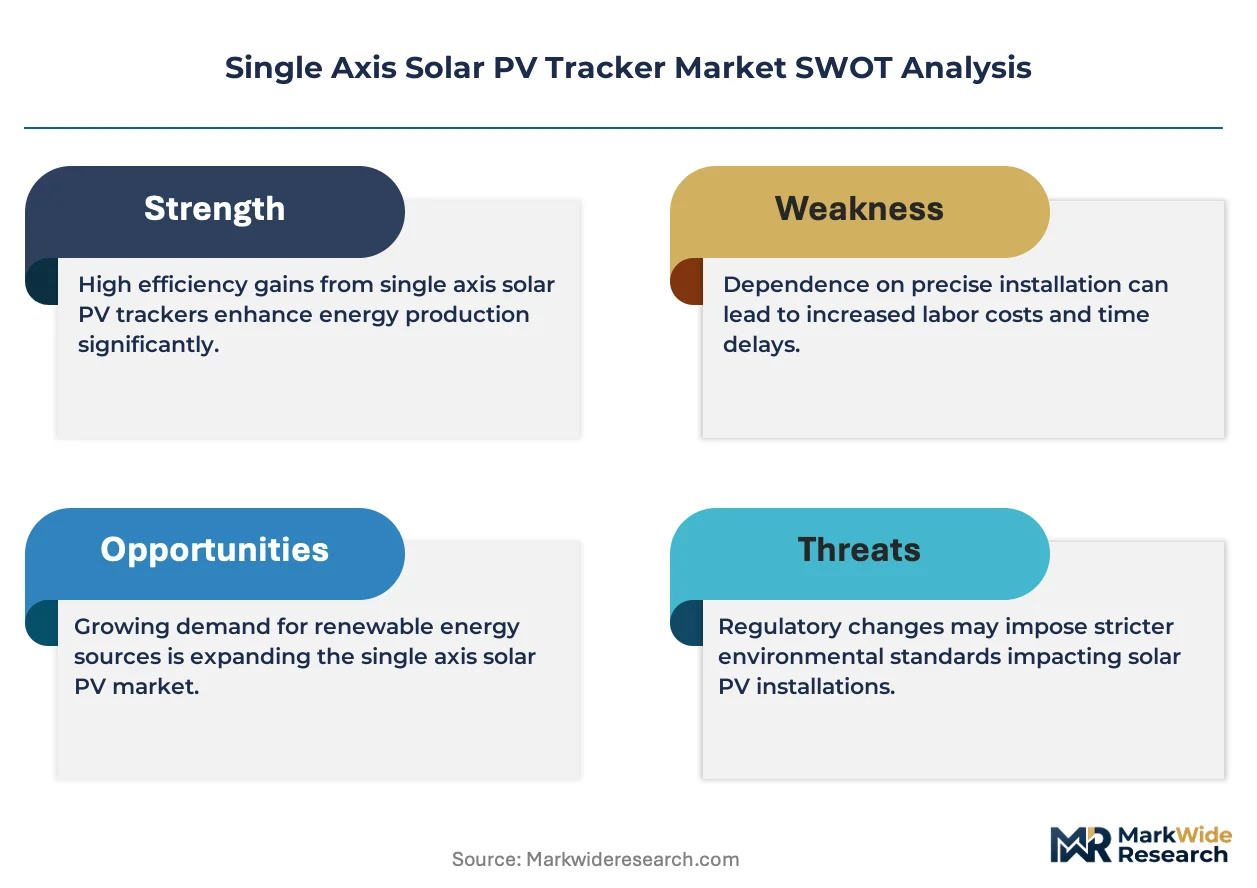
The US Inflation Reduction Act and EU F-Gas Regulation collectively reshape component sourcing requirements and carbon accounting standards for tracker manufacturers. India's BIS certification mandates and China's GB standards for structural steel further fragment compliance obligations across supply chains. Stakeholders must monitor evolving domestic content thresholds and anti-dumping proceedings that could reroute module and steel procurement strategies.
Market Dynamics
The bifacial module transition is compressing tracker design cycles as manufacturers race to optimize rear-side irradiance capture and structural load margins simultaneously.
Growth Catalysts
- US IRA Manufacturing Credits:Domestic content bonuses accelerate steel torque tube and drive assembly localization, tightening project cost structures for utility-scale developers.
- EU Green Deal Binding Targets:Member state renewable mandates expand addressable acreage for tracker-equipped solar farms, particularly in Spain and Italy where irradiance profiles favor single-axis deployment.
- India PLI Scheme:Production-linked incentives for solar module manufacturing cascade downstream into tracker demand as domestic module supply stabilizes project pipelines.
Market Restraints
- Steel Price Volatility:Hot-rolled coil fluctuations directly compress tracker margin structures, with galvanized structural tubing representing 35-40% of bill-of-materials costs.
- Supply Concentration Risk:Drive motor and controller assembly concentrates among a narrow supplier base in China, exposing procurement timelines to GB standards compliance delays and shipping bottlenecks.
- Soil Variability Constraints:Poor geotechnical conditions in saturated clay or high-wind coastal zones impose foundation cost premiums that erode tracker yield advantages over fixed-tilt alternatives.
Strategic Opportunities
- Australian Utility Pipeline:The country's 82% renewable electricity target by 2030 opens greenfield tracker deployment in Queensland and New South Wales solar zones.
- Agrivoltaics Convergence:Elevated tracker configurations enabling dual-use agriculture access premium land lease rates and carbon credit stacking revenue streams.
- Brazil Distributed Generation:Net metering expansion for commercial and industrial rooftops creates demand for compact single-axis systems optimized for sub-5MW installations.
Industry Challenges
- Structural Engineer Scarcity:Specialized geotechnical and wind-loading expertise for tracker foundation design bottlenecks project engineering capacity, extending pre-construction timelines.
- Multi-Jurisdiction Certification:UL 3703, IEC 62817, and country-specific structural approvals fragment product qualification pathways, delaying new market entry.
- Legacy SCADA Integration:Proprietary tracker control protocols complicate fleet-wide monitoring integration for independent power producers managing mixed-vendor solar assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Axis Solar PV Tracker Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground-mounted, Rooftop, Bifacial, Fixed Tilt End User: Utilities, Independent Power Producers, Commercial, Residential Technology: Hybrid, Single Axis, Dual Axis, Active Installation: Onshore, Offshore, Integrated, Standalone |
| Companies Covered | Soltec Power Holdings, Canadian Solar, Nextracker, GameChange Solar, Valmont Industries, Array Technologies, PV Hardware, First Solar, Arctech Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Axis Solar PV Tracker Market Emerging Trajectories
Control intelligence and module technology are converging to redefine performance optimization, while procurement structures compress supplier selection cycles and reward integrated system offerings.
Artificial intelligence-enabled backtracking algorithms is rewriting yield optimization by dynamically adjusting tracker angles to minimize inter-row shading during low-sun-angle periods. Independent power producers with multi-gigawatt portfolios deploy these systems fastest, compressing the performance gap between premium and standard tracker offerings while raising baseline software expectations across procurement evaluations.
The EU F-Gas Regulation's phasedown of hydrofluorocarbon refrigerants indirectly reshapes tracker manufacturing by accelerating electric drive motor adoption over hydraulic alternatives. Industrial consequences include supply chain requalification for actuator suppliers and redesign of terrain-following systems. European project developers now specify all-electric tracker architectures to preempt carbon accounting scrutiny under CSRD disclosure requirements.
Utility procurement teams increasingly bundle tracker supply with module and inverter sourcing under single-engineering-procurement-construction contracts, displacing component-level competitive bidding. This consolidation favors vertically integrated suppliers capable of warranting full system performance. The shift is most visible in southwestern United States utility-scale auctions where developers prioritize bankability and schedule certainty over lowest-component pricing.
Single Axis Solar PV Tracker Market Segmentation
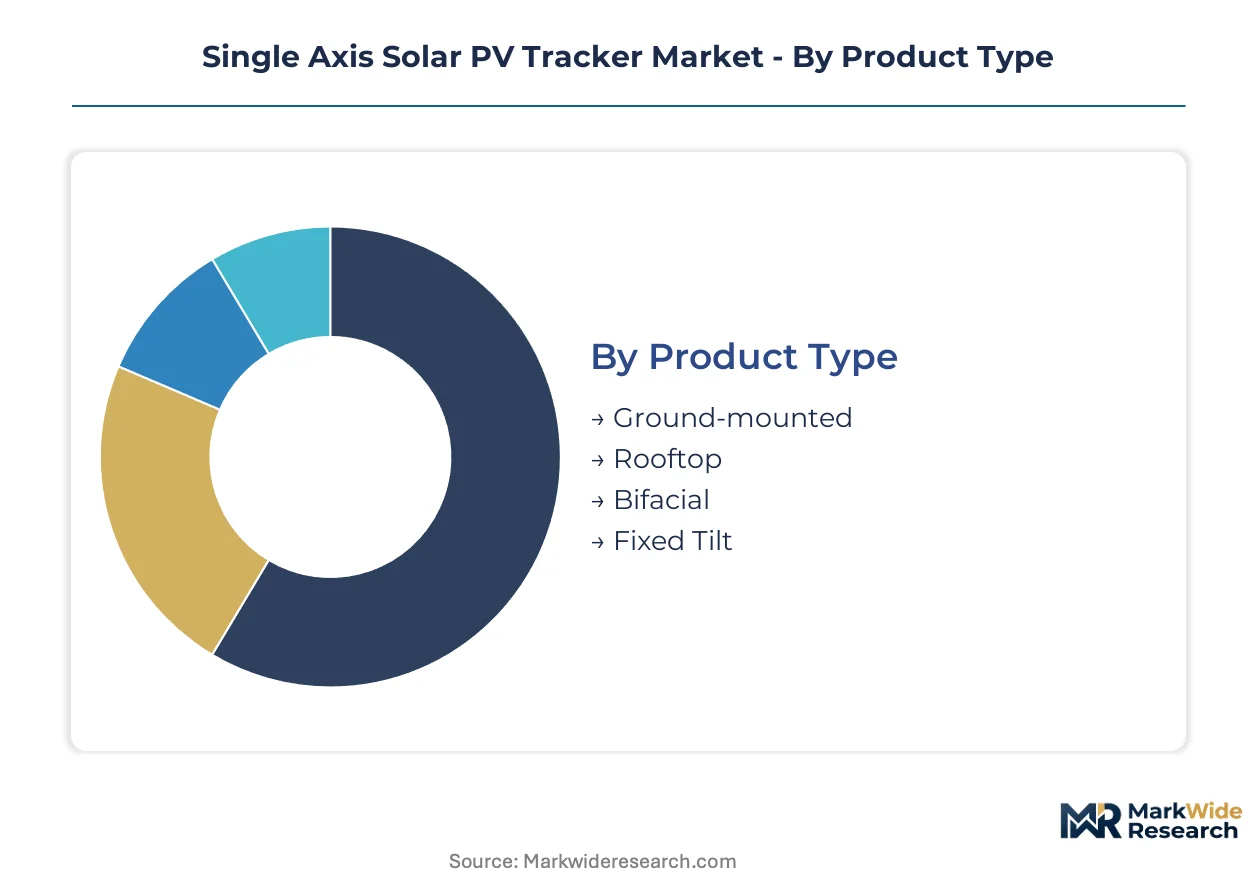
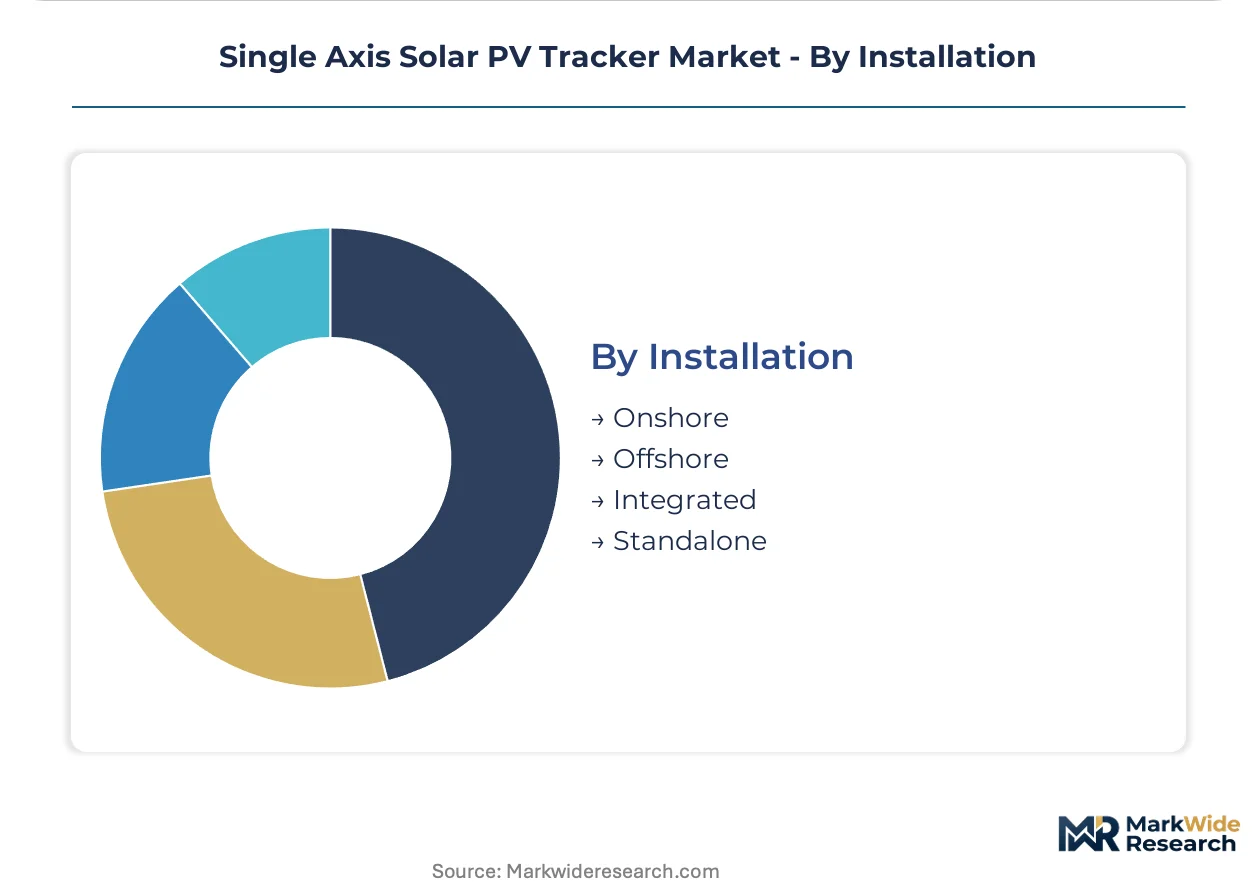
Tracker configuration choices cascade through project economics, with mounting architecture and module compatibility determining yield optimization potential and foundation cost structures. Procurement teams weight bifacial gain capture against structural load margins when specifying system designs for specific irradiance profiles and soil conditions.
Product Type:
Mounting architecture defines the structural envelope and terrain adaptability of tracker deployments.
- Ground-mounted:Steel torque tube assemblies anchored to driven piles or ground screws dominate utility-scale procurement. Southwestern United States solar zones concentrate demand where flat terrain and high irradiance maximize row density and energy density per acre.
- Bifacial:Elevated tracker configurations with increased ground clearance capture rear-side irradiance on dual-sided modules. Array Technologies and Nextracker optimize structural margins for bifacial load cases as dual-sided module adoption accelerates in Iberian Peninsula and Australian project pipelines.
- Rooftop:Compact single-axis systems with distributed drive architectures serve commercial and industrial building applications where structural loading constraints limit tracker size.
- Fixed Tilt:Stationary racking retains cost advantage in saturated clay or high-wind coastal zones where geotechnical premiums erode tracker yield benefits.
Ground-mounted configurations lead on scale; bifacial designs lead on momentum.
End User:
Customer procurement structures shape warranty requirements and performance guarantee terms.
- Utilities:Vertically integrated power companies deploy trackers across regulated renewable portfolios. Duke Energy and Southern California Edison specify bankable suppliers with domestic manufacturing capacity to satisfy IRA domestic content thresholds.
- Independent Power Producers:Project developers finance tracker-equipped solar farms through long-term power purchase agreements. IPPs prioritize generation optimization software and fleet-wide SCADA integration capabilities in vendor selection.
- Commercial:C&I offtakers under net metering regimes balance tracker premium against demand charge reduction and sustainability disclosure requirements.
- Residential:Single-axis systems remain rare in rooftop applications due to structural complexity and permitting friction relative to fixed-tilt alternatives.
Utilities anchor procurement volume; independent power producers drive technology specification intensity.
Technology:
Tracking mechanism architecture determines precision, maintenance burden, and terrain following capability.
- Single Axis:East-west rotation along one horizontal axis captures 20-25% yield gain over fixed-tilt systems. Horizontal single-axis trackers dominate utility-scale deployment due to structural simplicity and wind load management.
- Hybrid:Combined mechanical and electronic control systems optimize tracking precision across variable terrain. Soltec Power Holdings deploys terrain-adaptive hybrid architectures in European projects with undulating topography.
- Dual Axis:Azimuth and elevation tracking maximizes direct normal irradiance capture. Dual-axis systems concentrate in concentrated solar power hybrid applications and high-latitude installations where solar path variability justifies mechanical complexity.
- Active:Sensor-driven real-time positioning responds to diffuse light conditions and cloud edge effects. Active control systems integrate with satellite weather feeds and site-specific irradiance modeling for predictive positioning.
Single-axis configurations dominate installed base; hybrid systems are climbing the fastest on terrain adaptability requirements.
Installation:
Project delivery structure determines supply chain integration depth and commissioning risk allocation.
- Onshore:Terrestrial tracker deployment on private or leased land represents the overwhelming majority of installation activity. Foundation design adapts to geotechnical variability across clay, sand, and rock substrates.
- Standalone:Tracker supply as discrete equipment package under separate procurement from modules and inverters. Standalone contracting retains flexibility for developers with established EPC relationships and module sourcing strategies.
- Integrated:Bundled tracker-module-inverter procurement under single engineering-procurement-construction contract. Integrated contracting accelerates in southwestern United States utility auctions where schedule certainty outweighs component-level price optimization.
- Offshore:Floating tracker platforms for marine solar applications remain experimental with limited commercial deployment.
Onshore installations anchor project volume; integrated delivery models gain share fastest on bankability requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-axis solar tracker manufacturing originated in the southwestern United States during the 2000s utility-scale solar boom. Production subsequently dispersed across steel-producing regions with favorable logistics for torque tube fabrication and module integration.
United States
Utility-scale procurement dominates tracker demand through independent power producers financing multi-gigawatt projects. The IRA manufacturing credits tighten domestic content requirements for steel torque tubes and drive assemblies. Nextracker and Array Technologies anchor production in Arizona and New Mexico manufacturing corridors serving California and Texas solar zones.
Spain
Iberian Peninsula irradiance profiles favor single-axis deployment across Castilla-La Mancha and Extremadura solar parks. EU Green Deal binding targets accelerate member state renewable procurement timelines. Soltec Power Holdings maintains engineering and assembly operations in Murcia, supplying terrain-adaptive trackers to Italian and French project pipelines.
China
Domestic module oversupply cascades into tracker demand as state-owned utilities expand northwestern desert solar bases. GB standards for structural steel and NMPA-equivalent quality certifications fragment export compliance pathways. Zhejiang and Jiangsu provinces concentrate drive motor and controller manufacturing for global supply.
Australia
Queensland and New South Wales solar zones drive tracker procurement toward the country's 82% renewable electricity target. The national Clean Energy Regulator's carbon credit mechanisms reward generation optimization technologies. Local EPCs increasingly specify bifacial tracker configurations for high-irradiance inland projects.
India
Gujarat and Rajasthan solar parks anchor tracker deployment under national renewable purchase obligations. BIS certification mandates for structural components delay import timelines and favor domestic fabrication partnerships. PLI scheme module manufacturing expansion stabilizes downstream tracker demand through integrated project pipelines.
Single Axis Solar PV Tracker Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the tracker value chain. The market structures around three tiers: integrated steel fabricators with captive torque tube supply, specialized tracker engineering houses, and diversified solar module manufacturers extending into mounting systems. Strategic moves concentrate on backward integration into steel processing and forward integration into software-enabled performance optimization.
Among US-based fabricators, Nextracker and Array Technologies exemplify the integrated engineering archetype with domestic manufacturing footprints. Soltec Power Holdings occupies a position representing European terrain-adaptive specialization. Canadian Solar and First Solar anchor the module-origin diversification pattern, extending from cell manufacturing into tracker supply bundling.
| Leading Market Players |
|---|
| Soltec Power Holdings |
| Canadian Solar |
| Nextracker |
| GameChange Solar |
| Valmont Industries |
| Array Technologies |
| PV Hardware |
| First Solar |
| Arctech Solar |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up tracker specialists have consolidated domestic steel fabrication capacity, tightening supply discipline and compressing procurement timelines for utility-scale developers seeking IRA-compliant domestic content bonuses. This ownership concentration amplifies pricing power over galvanized torque tube supply while exposing project pipelines to margin pressure when hot-rolled coil benchmarks spike.
Pricing Analysis
Project-based contract pricing with volume-scaled discounts dominates procurement structures, separating premium tier suppliers with integrated steel mills from standard tier fabricators sourcing externally. Price differentiation hinges on UL 3703 certification tier and domestic manufacturing footprint qualifying for IRA credits. Cost compression in standard tier offerings is intensifying because Chinese drive motor imports face GB standards compliance delays. Independent power producers with multi-gigawatt portfolios exhibit lowest price sensitivity, prioritizing bankability and schedule certainty over component-level optimization.
Supply Chain Analysis
Freight cost differentials between ocean and rail corridors reshape sourcing economics for steel torque tubes, favoring southwestern United States manufacturing clusters serving California and Texas solar zones. Geographic supply concentration centers on China for drive motors and controllers, the United States for galvanized structural tubing, and Spain for terrain-adaptive system engineering. Raw material dependencies draw from hot-rolled steel coil, rare-earth permanent magnets, and aluminum extrusions. Single-source vulnerability in Chinese motor controller firmware exposes procurement timelines to shipping bottlenecks. Distribution runs through engineering-procurement-construction contractors bundling tracker supply with module and inverter sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The single axis solar PV tracker market functions as a regulatory compounder, with the US Inflation Reduction Act's domestic content thresholds and the EU Green Deal's binding renewable mandates collectively expanding addressable project pipelines faster than underlying component costs decline.
For Market Incumbents: Lock in captive steel supply through backward integration into galvanizing facilities or long-term offtake agreements with domestic mills, defending margin position against emerging Chinese tracker entrants leveraging module oversupply for bundling discounts. Prioritize certification investment in IEC 62817 and country-specific structural approvals to bottleneck new market entry. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer white-space access for compact single-axis systems optimized for distributed generation markets in Brazil and Australia, bypassing incumbent EPC relationships. Target agrivoltaics configurations enabling dual-use agriculture as the most penetrable application segment, deploying terrain-following hybrid architectures where Soltec holds limited presence. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light tracker engineering houses without captive steel capacity, offering acquisition exposure to software-enabled performance optimization and AI backtracking algorithms. Watch for inflection when steel price volatility triggers consolidation among second-tier fabricators unable to hedge input costs.| Strategic Initiative | Industry Significance |
|---|---|
| Steel Torque Tube Localization | Captive galvanizing capacity secures IRA domestic content bonuses for utility-scale pipelines. |
| AI-Enabled Backtracking Deployment | Machine learning algorithms compress yield gaps between premium and standard tracker offerings. |
| Agrivoltaics Configuration Development | Elevated tracker architectures unlock premium land lease rates and carbon credit stacking. |
| Multi-Jurisdiction Certification Investment | UL 3703 and IEC 62817 approvals bottleneck competitor entry in EU and US markets. |
| Integrated EPC Bundling Capability | Single-contract tracker-module-inverter supply accelerates procurement in southwestern US auctions. |
Methodological Framework
Bottom-up utility and independent power producer procurement modeling reconciled against top-down steel fabrication capacity tracking forms the analytical core, combining primary interviews with EPC contractors, utility planning officers, IPP project developers, and tracker manufacturer sales executives with secondary validation from EIA project databases, FERC interconnection queues, IEA renewable deployment reports, and customs trade records for steel torque tube imports.
Input-output matrices map tracker deployment volumes against module procurement timelines, steel price indices, and regulatory incentive phase-ins across the modeling period. Segmentation dimensions include mounting architecture, end-user procurement structure, tracking mechanism technology, and project delivery model. CAGRs derive from regression analysis of historical deployment data against policy incentive trajectories and steel cost forecasting, incorporating bifacial module adoption curves and domestic content threshold compliance rates as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for dual-axis or active sensor-driven tracking would alter the outlook if cost curves steepen unexpectedly. Forecasts reflect assumptions about IRA credit continuity, EU member state renewable procurement enforcement, and Chinese export financing availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Organic Solar Cells Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
South America Solar PV Inverters Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
Bangladesh Solar Energy Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
North America Concentrated Solar Power (CSP) Market
Solar Power Systems
Global Solar Microinverter Market