
 Floating Solar Panels Market | 2026-2036
Floating Solar Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Floating Solar Panels Market Analysis
Chinese module manufacturers are rebalancing capacity toward floating-specific production lines as water-body deployment gains scale. LONGi Solar dominates n-type bifacial supply for humid environments, leveraging anti-corrosion frame designs. Ciel & Terre International anchors floating structure engineering, sustaining proprietary HDPE pontoon patents across European and Asian installations. JA Solar Technology Co. Ltd. competes on cost-optimized monofacial modules for utility-scale reservoir farms.
Floating solar panels consist of photovoltaic arrays mounted on buoyant platforms that rest on calm water surfaces, typically using high-density polyethylene pontoons with aluminum or composite framing rated for decades of UV and moisture exposure; these systems generate electricity while reducing water evaporation and algae growth in host reservoirs. Photovoltaic panels remain the dominant product category, though bifacial modules are capturing margin pools by harvesting reflected light from water surfaces. Utilities represent the most concentrated end-user segment, with permanent installations locking in twenty-plus-year power purchase agreements that underpin project finance structures.
Japan's METI maintains feed-in tariff frameworks that specifically incentivize floating solar on agricultural reservoirs, while China's MEE enforces environmental impact assessments for water-body energy projects. The EU Green Deal and F-Gas Regulation indirectly shape floating solar demand by restricting conventional cooling-dependent thermal generation near water resources. Stakeholders must monitor evolving anchoring standards and mooring load certifications as projects migrate from sheltered inland waters to coastal and offshore exposure zones.
Market Dynamics
Water-body scarcity for ground-mounted arrays is pushing utilities toward reservoir-based photovoltaic deployment, while corrosion-resistant framing and dynamic mooring engineering now determine project bankability more than module efficiency metrics.
Growth Catalysts
- Japan's Agricultural Reservoir Tariff:METI maintains feed-in tariff premiums specifically for floating solar on irrigation ponds, creating dedicated procurement channels for domestic utilities.
- Evaporation Suppression Co-Benefits:Water utilities in drought-prone regions now recognize floating arrays as dual-use infrastructure that reduces reservoir losses while generating power.
- HDPE Pontoon Durability Gains:Advances in high-density polyethylene UV stabilization have extended platform service life, lowering lifecycle cost assumptions for long-term power purchase agreements.
Market Restraints
- Anchoring System Cost Volatility:Steel and synthetic mooring line prices fluctuate with marine-grade alloy markets, compressing EPC margins on large reservoir projects.
- Coastal Certification Gaps:IEC standards for offshore exposure remain under development, delaying insurance underwriting for saltwater-adjacent installations.
- Ground-Mount Competition:Desert solar farms in Australia and the Middle East offer lower levelized costs, diverting some utility procurement away from floating alternatives.
Strategic Opportunities
- India's Dam-Top Pilot Pipeline:State electricity boards are evaluating floating arrays on hydroelectric reservoirs to hybridize existing grid infrastructure without land acquisition.
- Bifacial-Water Surface Convergence:Modules capturing reflected light from water surfaces unlock yield premiums that justify higher structural costs in premium electricity markets.
- EU Green Deal Cooling Restrictions:F-Gas Regulation limits thermal plant siting near water bodies, creating regulatory space for floating photovoltaic replacement capacity.
Industry Challenges
- Marine Engineering Talent Scarcity:Project developers struggle to recruit mooring designers with combined hydrodynamic and electrical system expertise.
- Multi-Stakeholder Permitting Complexity:Reservoir projects require coordination between water resource agencies, grid operators, and environmental regulators, extending development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floating Solar Panels Market |
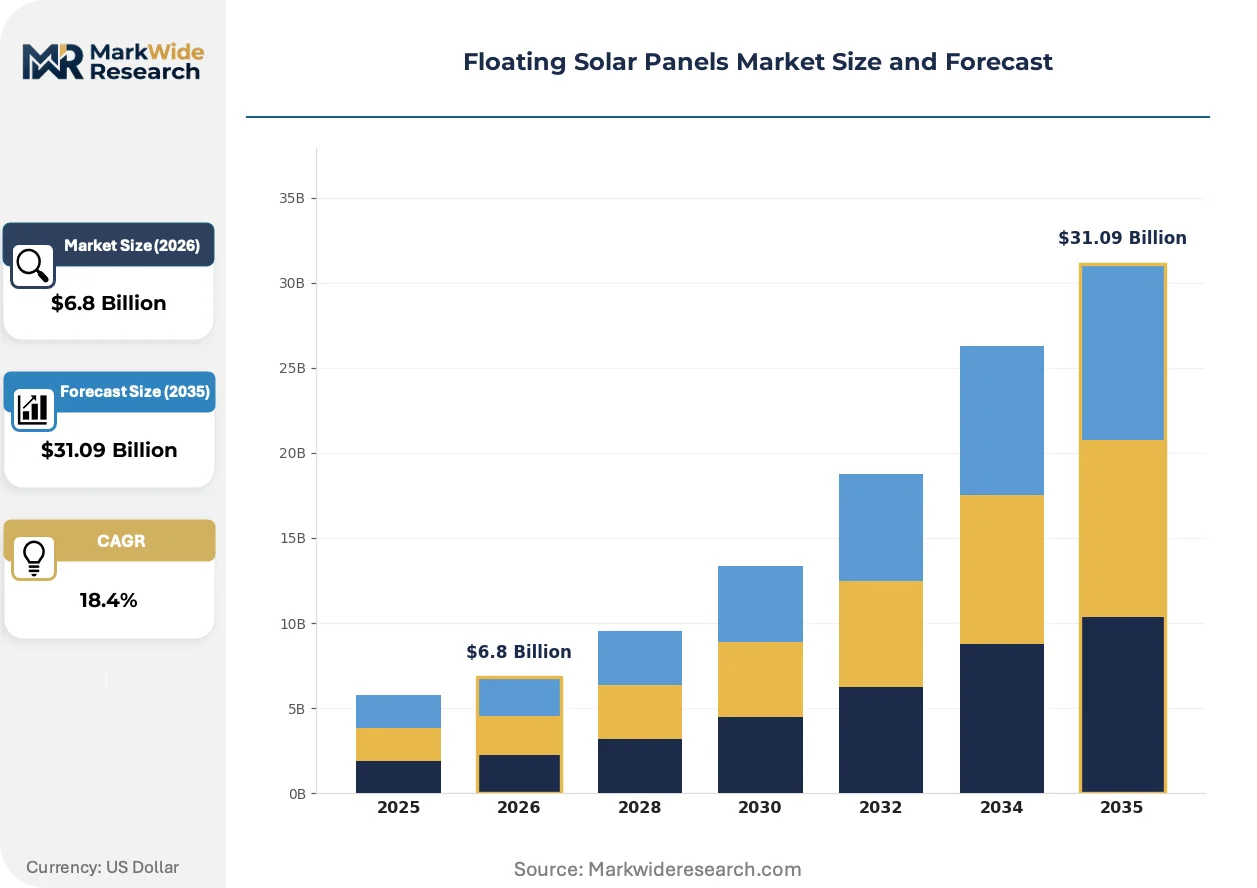
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Bifacial Modules, Thin-Film Solar, Concentrated Solar Power Application: Power Generation, Water Treatment, Aquaculture, Carbon Sequestration End User: Utilities, Commercial Installations, Residential Users, Research Institutions Installation Type: Permanent Installations, Temporary Setups, Pilot Projects, Large-Scale Farms |
| Companies Covered | Ciel & Terre International, KYOCERA Corporation, Trina Solar, JA Solar Technology Co. Ltd., LONGi Solar, Hanwha Group, Canadian Solar Inc., Vikram Solar Limited, Sharp Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floating Solar Panels Market Emerging Trajectories
Module manufacturers and structural engineers are converging on integrated platform-electrical systems that reduce onsite assembly labor, while regulatory bodies race to codify standards for harsher marine environments.
Corrosion-resistant composite framing is expanding into humid coastal markets as the default structural choice for salt-laden environments. Taiwanese and Vietnamese utilities now specify glass-fiber reinforced platforms for typhoon-exposed reservoirs. This material shift is compressing aluminum framing's historical dominance in temperate climates and enabling project finance in previously restricted exposure zones.
China's MEE now mandates environmental impact assessments for all water-body energy projects, including floating solar arrays on artificial reservoirs. The regulation requires hydrodynamic modeling of mooring loads and aquatic ecosystem disruption analysis. Domestic developers are responding by front-loading marine biology consultancy costs into early-stage feasibility studies.
Utility procurement departments now unbundle structural engineering from module supply, creating separate RFP tracks for pontoon platforms and photovoltaic arrays. European power generators pioneered this split-contracting model to optimize supplier selection, and Southeast Asian state utilities are adopting similar practices. This fragmentation is most visible in Thailand's EGAT reservoir program, where platform and module contracts now carry independent performance guarantees.
Floating Solar Panels Market Segmentation
Floating solar deployment spans divergent certification pathways, with reservoir-based installations requiring water-resource agency approvals while coastal arrays trigger marine engineering standards. Product selection and installation scale directly determine which regulatory frameworks apply, shaping procurement timelines and project bankability across end-user categories.
Product Type:
Certification burden varies sharply by cell technology, with bifacial modules requiring additional IEC 61215-1:2021 testing for rear-side performance claims while thin-film arrays face distinct UL 1703 fire safety protocols.
- Photovoltaic Panels:Monocrystalline and polycrystalline silicon arrays dominate procurement volumes, with standard IEC 61215 certification satisfying most reservoir project requirements. Chinese module suppliers anchor manufacturing capacity for humid-environment specifications, particularly for Southeast Asian utility tenders.
- Bifacial Modules:Double-sided cells capture reflected irradiance from water surfaces, delivering yield premiums that justify structural cost premiums in Japan's METI-subsidized agricultural reservoir programs. Additional rear-side testing extends certification timelines by 4-6 weeks.
- Thin-Film Solar:Cadmium-telluride and CIGS technologies occupy niche coastal markets requiring flexible substrate compatibility.
- Concentrated Solar Power:Thermal trough systems remain experimental for floating deployment, with no commercial installations exceeding pilot scale.
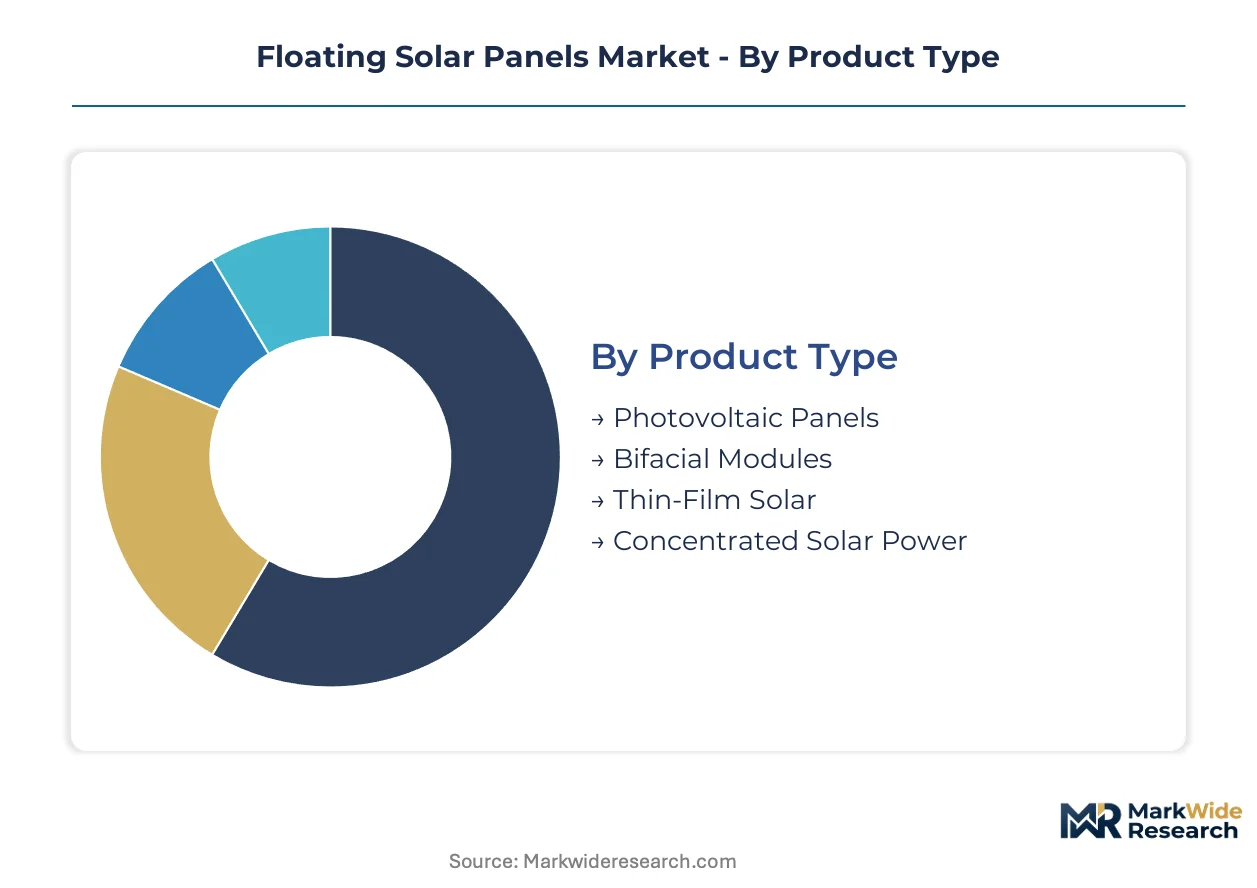
Photovoltaic Panels sits at the top of the volume ranking, with Bifacial Modules climbing the fastest.
Application:
Cost tier stratification separates mature power generation applications from emerging dual-use configurations, with aquaculture co-location commanding structural premiums for platform load-bearing modifications.
- Power Generation:Utility-scale electricity delivery under 20-25 year power purchase agreements represents the commercial core, with procurement concentrated among Southeast Asian state electricity boards and Japanese regional utilities. Project finance structures prioritize proven revenue streams over speculative co-benefits.
- Water Treatment:Floating arrays powering desalination and wastewater facilities gain traction in Middle Eastern markets facing land-body scarcity. Energy-water nexus frameworks from Saudi Arabia's national water utility are standardizing technical specifications.
- Aquaculture:Integrated fish farming platforms require modified pontoon spacing and feed-system accommodation.
- Carbon Sequestration:Algae cultivation and direct air capture integrations remain pre-commercial, with no standardized performance metrics established.
Power Generation captures the dominant revenue share, while Water Treatment applications are expanding most quickly in arid-climate markets.
End User:
Customer type determines contract structure complexity, with utilities demanding bankable performance guarantees while research institutions accept technology-risk exposure for demonstration access.
- Utilities:State and investor-owned power generators anchor procurement volume through competitive tenders specifying dual-axis tracking compatibility and 25-year degradation warranties. Thailand's EGAT and Vietnam's EVN have issued consecutive annual RFPs since reservoir pilot validations completed.
- Commercial Installations:Industrial off-takers and corporate power purchase agreement buyers seek smaller-scale deployments on privately held water bodies, with shorter contract tenors reflecting balance-sheet constraints.
- Residential Users:Private pond and small reservoir installations remain negligible outside Japan's agricultural landholder segment.
- Research Institutions:Universities and national laboratories operate demonstration platforms for mooring-load and biofouling studies.
Utilities dominate absolute installation capacity, with Commercial Installations gaining share fastest among distributed energy adopters.
Installation Type:
Project maturity stage dictates engineering standard applicability, with permanent installations requiring full IEC 62817 tracker certification while pilot projects operate under provisional waivers.
- Permanent Installations:Fixed 20-plus-year asset configurations with concrete-anchored mooring systems and integrated electrical infrastructure. Japanese irrigation pond arrays and Thailand's Sirindhorn Dam installation exemplify this category's bankability requirements.
- Temporary Setups:Seasonal or event-power deployments using rapid-assembly floating platforms with shore-tethered electrical connections.
- Pilot Projects:Technology validation platforms typically under 2MW capacity, prevalent in India's dam-top hybridization studies and Singapore's reservoir testing program.
- Large-Scale Farms:Multi-hundred-megawatt configurations requiring segmented construction phasing and staged grid interconnection.
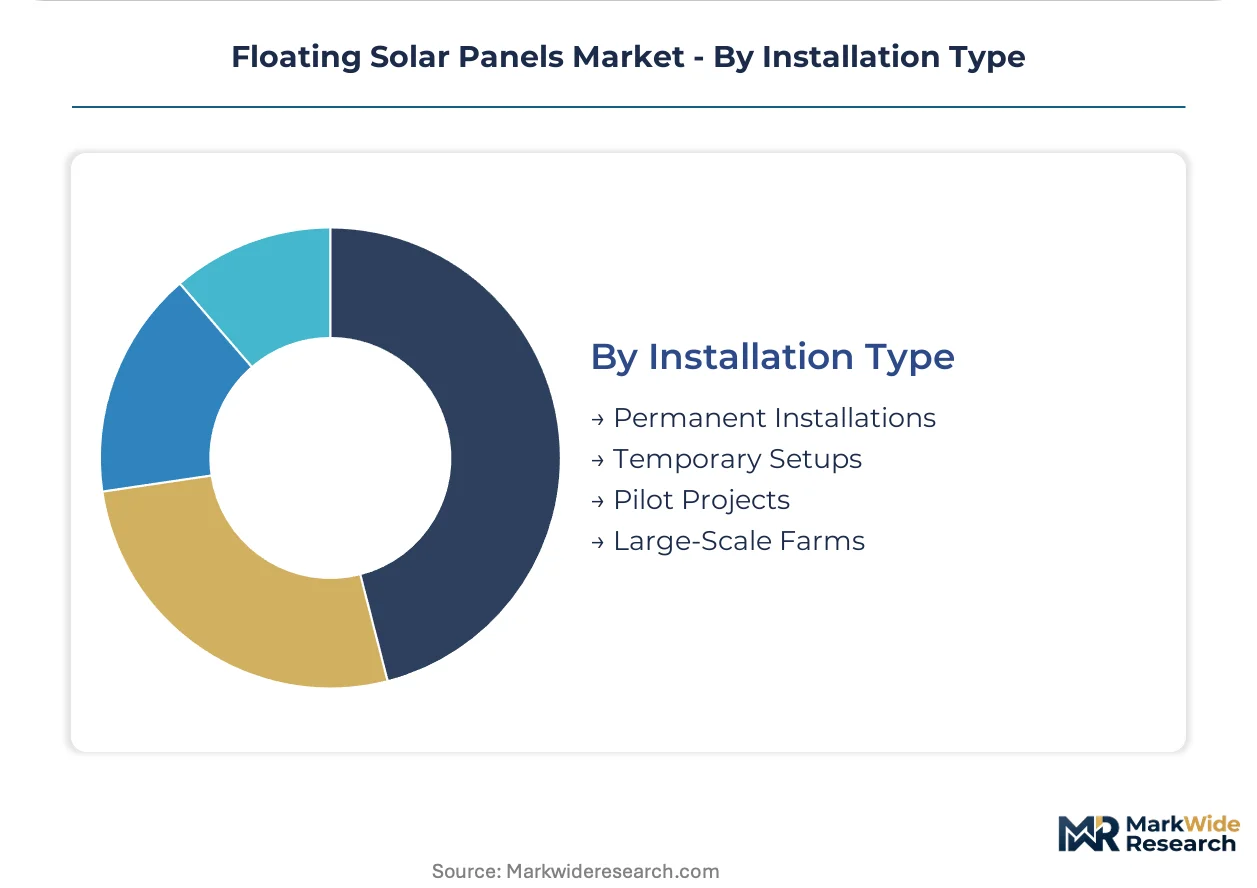
Permanent Installations lead deployment volume, with Large-Scale Farms showing the steepest expansion trajectory as reservoir availability concentrates in utility portfolios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting floating solar deployment toward jurisdictions with streamlined water-use permitting and established feed-in tariff mechanisms, compressing development timelines in markets with mature environmental assessment frameworks.
China
Domestic module manufacturers are rebalancing capacity toward floating-specific production lines as reservoir deployment gains scale. The Ministry of Ecology and Environment mandates environmental impact assessments for all water-body energy projects, requiring hydrodynamic modeling of mooring loads. The Yangtze River Delta anchors manufacturing clusters for HDPE pontoon systems serving Southeast Asian export markets.
Japan
Regional utilities concentrate procurement on agricultural reservoir installations backed by METI feed-in tariff premiums specifically incentivizing floating photovoltaic systems. The Ministry of Economy, Trade and Industry maintains dedicated procurement channels for irrigation pond deployments. Kansai's Osaka Prefecture hosts validation platforms for typhoon-resistant mooring engineering.
Thailand
State electricity boards issue consecutive annual RFPs for reservoir-based power generation following Sirindhorn Dam pilot validations. The Electricity Generating Authority of Thailand unbundles structural engineering from module supply, creating separate contract tracks for pontoon platforms. Central Plains irrigation districts concentrate feasibility studies for evaporation suppression co-benefits.
India
Dam-top hybridization studies on hydroelectric reservoirs are expanding without land acquisition constraints. The Central Electricity Authority evaluates floating arrays for grid infrastructure hybridization. Maharashtra's state electricity board pilots segmented construction phasing for multi-hundred-megawatt configurations on existing water bodies.
Vietnam
Typhoon-exposed reservoirs drive specification shifts toward glass-fiber reinforced platforms for salt-laden environments. State utility EVN adopts European split-contracting models for platform and module procurement. Mekong Delta provinces concentrate early-stage feasibility studies integrating marine biology consultancy costs.
Floating Solar Panels Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue coastal certification and offshore exposure capabilities. The vendor base stratifies across integrated module-platform suppliers, specialized structural engineers, and regional EPC contractors. Three archetypes dominate: Chinese manufacturers with captive module capacity, European engineering houses with proprietary pontoon IP, and Asian utilities with captive project development arms. Competitive moves concentrate on capacity rebalancing toward humid-environment specifications and technology licensing for mooring system standardization.
Within the integrated manufacturing tier, LONGi Solar and JA Solar Technology Co. Ltd. exemplify divergent positioning strategies for reservoir deployment. Ciel & Terre International occupies a distinct engineering-specialist position, anchoring proprietary HDPE pontoon deployment across European and Asian installations. These three entities represent the structural fault lines between module-centric and platform-centric value capture models.
| Leading Market Players |
|---|
| Ciel & Terre International |
| KYOCERA Corporation |
| Trina Solar |
| JA Solar Technology Co. Ltd. |
| LONGi Solar |
| Hanwha Group |
| Canadian Solar Inc. |
| Vikram Solar Limited |
| Sharp Corporation |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed utilities with captive project development arms anchor procurement volume across Southeast Asia, compressing supplier margins through competitive tendering while simultaneously locking in long-term offtake structures that stabilize revenue visibility for EPC contractors willing to absorb upfront engineering risk.
Pricing Analysis
Direct-to-utility contracting discounts dominate the channel structure, with module suppliers bypassing distribution layers to capture margin pools otherwise lost to intermediaries. Three-tier pricing structure across premium, standard, and economy levels separates bifacial modules with IEC 61215-1:2021 rear-side certification from monofacial baseline products and thin-film coastal alternatives. Cost compression in standard-tier monofacial supply is intensifying because Chinese manufacturers are rebalancing capacity toward floating-specific humid-environment specifications. State electricity boards in Thailand and Vietnam exhibit the highest price sensitivity, while Japanese regional utilities purchasing under METI agricultural reservoir tariffs accept structural cost premiums for typhoon-resistant mooring systems.
Supply Chain Analysis
Marine freight costs for HDPE pontoon systems from China's Yangtze River Delta manufacturing clusters to Southeast Asian project sites represent a material landed cost component, particularly for Vietnam's Mekong Delta and Thailand's Central Plains installations. Manufacturing concentration centers on China for module assembly, South Korea for glass-fiber reinforced platform composites, and France for proprietary mooring engineering IP. Raw material dependencies include high-density polyethylene resin, marine-grade aluminum alloy, and UV-stabilization additives. Single-source vulnerability in HDPE pontoon patent licensing from European engineering houses creates supply chain risk for Asian EPC contractors. Distribution runs through utility-led competitive tenders with unbundled platform and module procurement tracks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Floating solar deployment functions as a geographic-arbitrage play where developers exploit the gap between Japan's METI feed-in tariff premiums and China's lower manufacturing input costs, capturing spread returns while navigating divergent environmental assessment standards.
For Market Incumbents: Lock in long-term HDPE resin supply agreements and captive mooring engineering capacity before marine-grade polymer markets tighten. Defensive consolidation through backward integration into pontoon manufacturing insulates against European patent-holder pricing power. Certification investment in IEC 62817 tracker standards for permanent installations creates switching costs that emerging EPC contractors cannot immediately replicate. Threat substitution from desert solar farms in Australia and the Middle East intensifies procurement competition for utility-scale contracts. For New Entrants and Emerging Players: Enter via India's dam-top hybridization pilot pipeline, where state electricity boards evaluate floating arrays without land acquisition constraints and procurement protocols remain less codified than Japan's agricultural reservoir channels. White-space targets include water treatment applications in Saudi Arabia's energy-water nexus and aquaculture co-location platforms requiring modified load-bearing specifications. Go-to-market positioning as marine biology consultancy-integrated developers addresses China's MEE environmental impact assessment mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among regional EPC contractors with established utility relationships but lacking proprietary platform technology. Long-term viability framing favors developers with demonstrated project finance track records across multiple reservoir typologies rather than single-market specialists. Acquisition target archetype: Asian contractors with split-contracting experience and marine engineering talent pipelines. Signal to watch: finalization of IEC offshore exposure standards enabling insurance underwriting for saltwater-adjacent installations.| Strategic Initiative | Industry Significance |
|---|---|
| HDPE Pontoon Capacity Expansion | Chinese manufacturers rebalancing lines toward floating-specific production capture Southeast Asian utility procurement growth. |
| Bifacial Module Certification Investment | Rear-side IEC 61215-1:2021 testing unlocks METI tariff premiums for Japanese agricultural reservoir deployments. |
| Marine Engineering Talent Acquisition | Combined hydrodynamic and electrical expertise scarcity determines project bankability in coastal exposure zones. |
| Split-Contracting Model Adoption | European unbundling of platform and module procurement optimizes supplier selection for Thailand's EGAT program. |
| Environmental Impact Assessment Front-Loading | Early-stage marine biology consultancy integration satisfies China's MEE mandates for water-body energy projects. |
Methodological Framework
Multiple input streams — structured interviews with utility planning officers and EPC project developers, regulatory filing analysis from China's MEE and Japan's METI, and customs data tracking HDPE pontoon trade flows — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged reservoir developers, marine engineering specialists, module procurement leads at state electricity boards, and environmental assessment consultants across Southeast Asian markets. Secondary validation drew from FERC-style grid interconnection filings, IEA renewable energy deployment databases, IEC standard development records, and project finance documentation from utility-scale installations. Cross-referencing installation capacity claims against power purchase agreement registries identified reporting discrepancies requiring analyst adjustment.
Data-stream reconciliation anchored volume projections to segmented modeling across cell technology tiers, installation type maturity stages, and regional regulatory framework clusters. The analytical framework weighted bifacial module yield premiums, permanent installation bankability requirements, and pilot project waiver availability throughout the forecast period. CAGRs were derived from utility procurement pipeline analysis and manufacturing capacity rebalancing announcements. Industry-specific forecast inputs included METI tariff schedule stability assumptions and IEC offshore certification timeline expectations.
Inputs from utility procurement officers and marine engineering contractors were available through the study window; gaps in early-stage project development databases and proprietary mooring load modeling introduce uncertainty bands around coastal exposure zone deployment timelines. Forecasts reflect documented assumptions regarding regulatory schedule adherence and resin supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Graphene Solar Cell Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Solar PV Backsheet Market
Solar Power Systems
Photovoltaic (PV) Materials Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Bifacial Solar Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
US Solar Market