
 Utility Scale PV Inverter Market | 2026-2036
Utility Scale PV Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Scale PV Inverter Market Analysis
Independent power producers are unwinding the historical dominance of vertically integrated utilities in inverter procurement for new solar capacity. Sungrow Power Supply leverages its manufacturing scale to anchor supply contracts across Asia-Pacific and Middle Eastern project pipelines. Huawei Technologies differentiates through string inverter architectures that compete with traditional central inverter bids on levelized cost metrics. SMA Solar Technology sustains its position in European and North American markets through grid-forming capabilities and service density.
A utility scale PV inverter converts direct current from megawatt-class photovoltaic arrays into grid-compliant alternating current at voltages typically ranging from 480 V to 35 kV, with power ratings from 500 kW to 8 MW and efficiency targets exceeding 98.5 percent. String inverters now dominate new ground-mounted installations below 100 MW due to modular redundancy and lower balance-of-system costs, while central inverters retain share in desert megaprojects where economies of scale offset single-point failure risks. Battery storage integration represents the fastest-expanding technology segment as developers pair inverters with four-hour lithium-ion configurations to capture capacity market revenues.
IEC 61727 and IEEE 1547 standards shape product design by mandating low-voltage ride-through, frequency-watt control, and harmonic distortion limits that filter non-compliant suppliers from tender eligibility. Grid-tied systems face additional scrutiny from national regulators including China's National Energy Administration, India's Central Electricity Authority, and Germany's Federal Network Agency as each jurisdiction tightens connection codes. Stakeholders must monitor evolving interconnection rules and storage co-location mandates to align inverter roadmaps with procurement specifications.
Market Dynamics
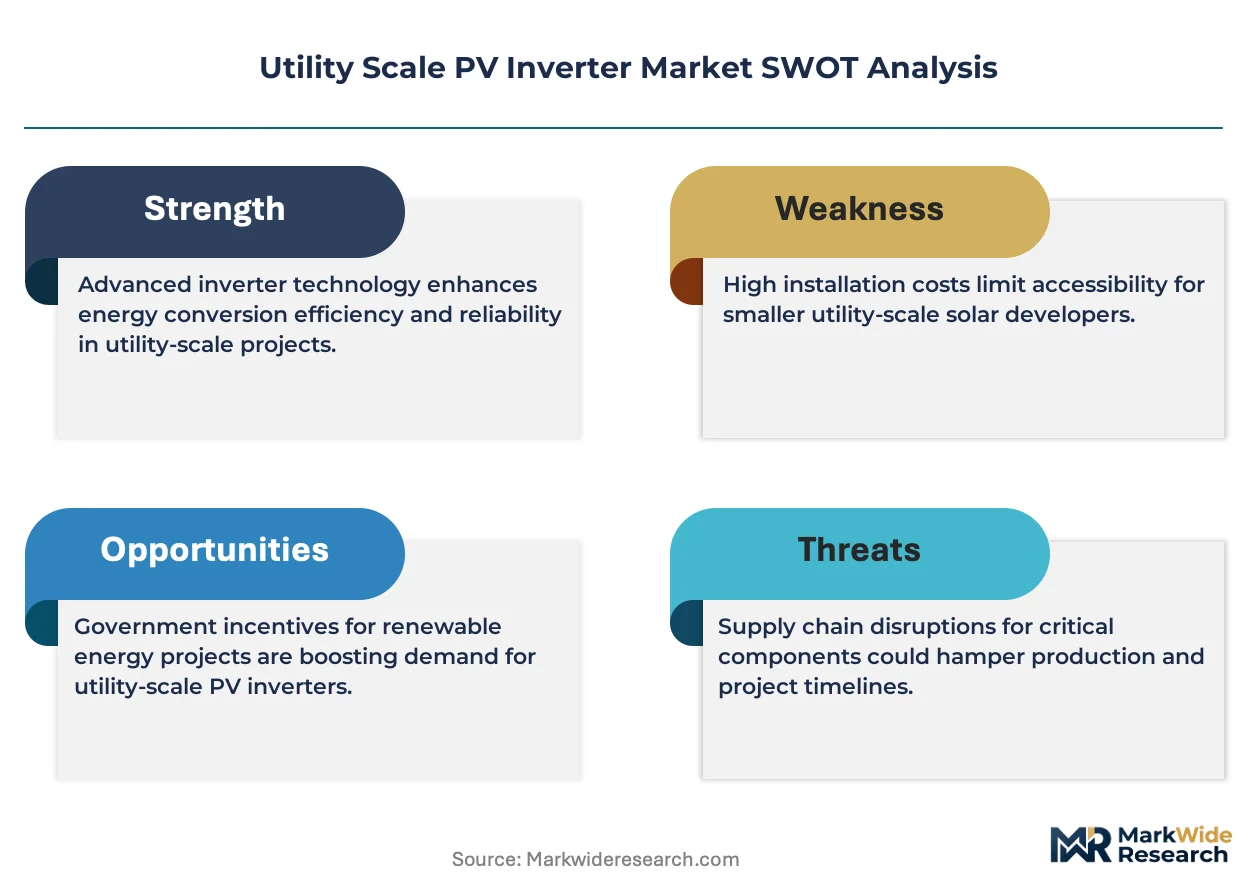
Grid code harmonization under IEEE 1547 and IEC 61727 is forcing inverter manufacturers to redesign power electronics for reactive power capability and fault ride-through functions, compressing product development cycles and disqualifying legacy architectures from tender eligibility.
Growth Catalysts
- Multi-gigawatt solar programs:China, India, and the United States are deploying centralized procurement frameworks that aggregate demand for string and central inverter volumes.
- Battery storage co-location mandates:Grid operators in California and Germany now require four-hour lithium-ion pairing, expanding inverter specification scope.
- IEC 61727 compliance thresholds:Low-voltage ride-through and frequency-watt control mandates are filtering non-compliant suppliers from project finance eligibility.
Market Restraints
- IGBT and silicon carbide supply concentration:Power semiconductor fabrication concentrates in East Asian foundries, exposing inverter OEMs to input cost volatility and allocation constraints.
- Central inverter single-point failure risk:Desert megaprojects exceeding 500 MW face downtime exposure that string architectures mitigate through modular redundancy.
- Utility interconnection queue delays:FERC Order 2023 implementation timelines vary by regional transmission organization, stretching project commissioning schedules.
Strategic Opportunities
- Saudi Arabia's renewable energy procurement:The Kingdom's National Renewable Energy Program is tendering utility-scale solar at scale without incumbent inverter supplier relationships.
- Grid-forming capability premium:Inverters with black-start and synthetic inertia functions command specification preference in islanded and weak-grid applications.
- String inverter channel expansion:EPC contractors are adopting modular architectures for ground-mounted installations below 100 MW, displacing traditional central inverter bids.
Industry Challenges
- Power electronics engineering talent scarcity:Grid-tied inverter design requires specialized expertise in electromagnetic compatibility and thermal management that outpaces university pipeline output.
- Multi-jurisdiction certification timelines:Separate testing protocols for China's GB standards, India's CEA regulations, and Germany's VDE-AR-N 4120 extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Scale PV Inverter Market |
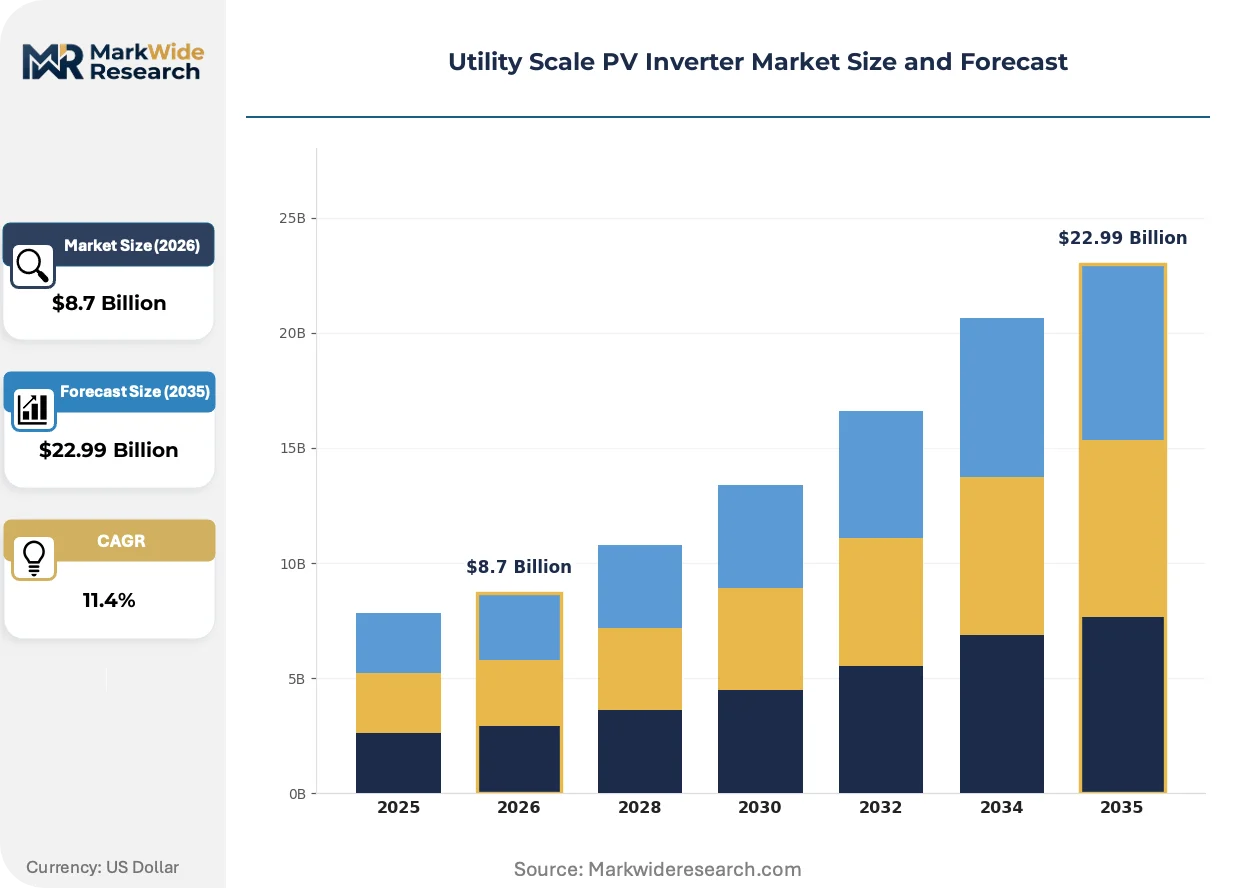
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Central Inverters, Microinverters, Hybrid Inverters Technology: Thermal Management, Grid-Tied Systems, Battery Storage Integration, Monitoring Solutions End User: Utility Providers, Independent Power Producers, Commercial Developers, Energy Cooperatives Installation: Ground Mounted, Rooftop, Carport, Floating Systems |
| Companies Covered | Sineng Electric, Ginlong Technologies, Sungrow Power Supply, SolarEdge Technologies, TMEIC, Huawei Technologies, Power Electronics, FIMER, SMA Solar Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Scale PV Inverter Market Emerging Trajectories
Inverter architectures are diverging between modular string systems and consolidated central blocks, with each path optimizing for different balance-of-system trade-offs and grid service requirements.
Silicon carbide power semiconductors are bifurcating inverter efficiency trajectories. These wide-bandgap devices enable switching frequencies above 50 kHz, shrinking magnetic component mass. Independent power producers in Texas and Australia are specifying SiC-based string inverters for distributed solar-plus-storage configurations. The technology is bifurcating supplier tiers, separating OEMs with captive module sourcing from those dependent on merchant power semiconductor markets.
Europe's F-Gas Regulation is phasing down sulfur hexafluoride use in switchgear integrated with inverter substations. Manufacturers must redesign medium-voltage connection enclosures with vacuum interruption or clean air insulation. Central inverter suppliers serving German and Spanish utility-scale projects are accelerating SF6-free product roadmaps to maintain tender eligibility under tightening environmental product declarations.
Asset owners are unbundling inverter service contracts from EPC wrap agreements. Large solar park operators in India and Brazil now procure multi-year operations and maintenance separately, creating direct vendor relationships with SMA Solar Technology and Sungrow Power Supply service arms. This shift concentrates aftermarket revenue with OEMs possessing regional technician density and spare part warehousing.
Utility Scale PV Inverter Market Segmentation
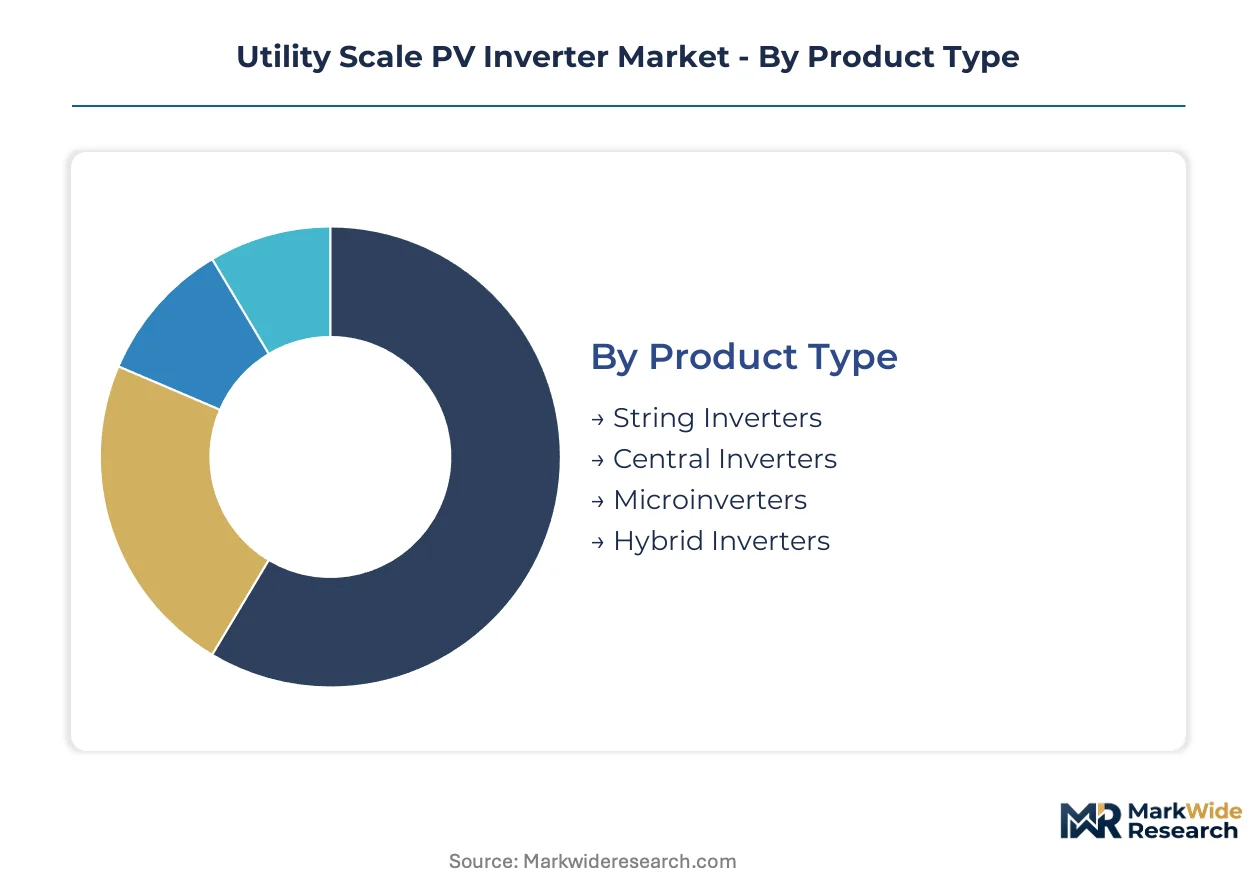
Product architecture choices in utility-scale solar determine balance-of-system costs, grid service capabilities, and project finance eligibility. Procurement patterns diverge sharply across installation scales and regulatory environments, forcing inverter suppliers to maintain parallel technology roadmaps.
Product Type:
String architectures face intensifying substitution pressure from hybrid systems that bundle storage conversion, while central inverter blocks confront redundancy disadvantages in modular procurement frameworks.
- String Inverters:Distributed power electronics operating at 1,500 V DC with individual MPPT channels per string. Demand concentrates in Indian and Brazilian solar parks below 100 MW where EPC contractors prioritize modular redundancy and reduced DC cabling costs.
- Central Inverters:Consolidated conversion blocks rated 2.5 MW to 8 MW with integrated medium-voltage transformers. Saudi Arabian and Australian desert megaprojects specify these for economies of scale despite single-point failure exposure.
- Microinverters:Module-level power electronics with per-panel MPPT optimization.
- Hybrid Inverters:Bidirectional conversion hardware enabling DC-coupled battery storage integration.
Central inverters retain volume leadership in desert utility-scale deployments; hybrid inverters hold the steepest expansion curve as storage mandates proliferate.
Technology:
Cost tier differentiation separates premium thermal management and grid-forming capabilities from baseline commodity specifications.
- Thermal Management:Active cooling systems with liquid-cooled IGBT modules sustaining full-load operation above 50°C ambient. Texas and Arizona developers specify these for derating avoidance in extreme climates.
- Grid-Tied Systems:Standard utility-interactive inverters without storage conversion capability. Emerging market procurement in Vietnam and South Africa favors these for pure-play solar economics.
- Battery Storage Integration:Four-hour lithium-ion pairing with unified power conversion systems. California's CPUC mandates and Germany's market premium schemes accelerate specification.
- Monitoring Solutions:Cloud-connected diagnostics with predictive maintenance algorithms.
Thermal management commands premium pricing in high-temperature geographies; battery storage integration is expanding most quickly through regulatory mandate.
End User:
Customer type determines procurement sophistication, with independent power producers driving technical specification intensity.
- Utility Providers:Vertically integrated electricity distributors with captive engineering resources. State-owned entities in China and India aggregate demand through centralized tender frameworks.
- Independent Power Producers:Non-utility developers financing projects through power purchase agreements. IPPs in Chile and Mexico specify string inverters with 25-year service contracts to optimize LCOE.
- Commercial Developers:Corporate offtake aggregators procuring behind-the-meter capacity.
- Energy Cooperatives:Community-owned generation entities with limited technical staffing.
Utility providers anchor procurement volume through sovereign-backed programs; independent power producers are gaining share fastest through merchant and corporate PPA expansion.
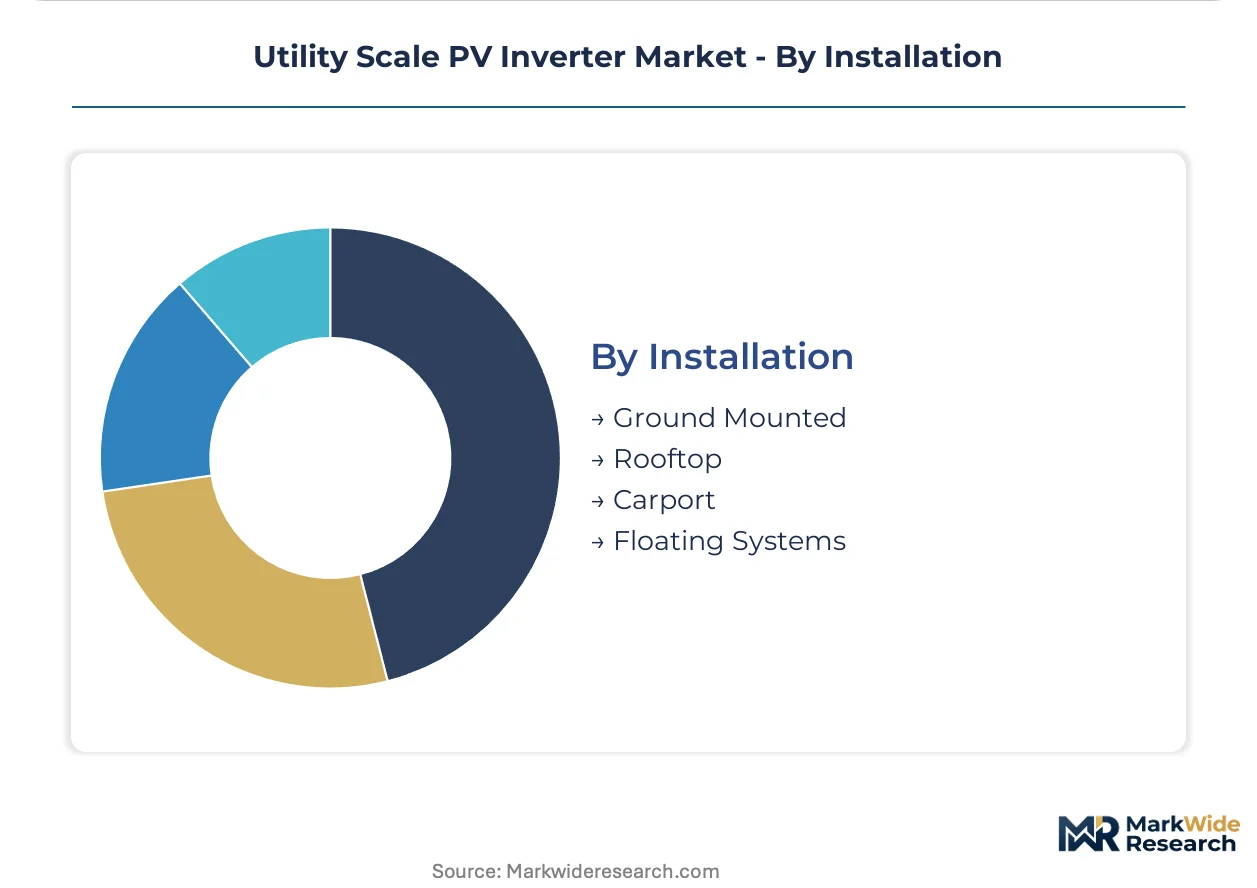
Installation:
Application environment dictates enclosure ratings, cooling architecture, and balance-of-system integration requirements.
- Ground Mounted:Fixed-tilt and tracking array configurations on graded terrain. Indian Rajasthan and Saudi Arabian Al-Jouf projects dominate procurement with string and central inverter splits by scale threshold.
- Rooftop:Elevated structures on commercial and industrial buildings with weight constraints. Distributed generation programs in Brazil and Turkey specify lightweight string inverter solutions.
- Carport:Solar canopy structures over parking facilities with dual-use revenue streams.
- Floating Systems:Pontoon-mounted arrays on reservoirs and coastal lagoons. Southeast Asian hydropower reservoir projects in Vietnam and Thailand drive corrosion-resistant inverter demand.
Ground mounted retains absolute volume leadership; floating systems are climbing the fastest as land constraints intensify in densely populated regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power semiconductor fabrication concentrates in East Asian foundries, yet inverter procurement clusters in jurisdictions with aggressive renewable deployment mandates and grid modernization programs. China, India, the United States, Germany, and Saudi Arabia anchor demand through divergent regulatory frameworks and project development scales.
China
Multi-gigawatt solar parks in Inner Mongolia and Qinghai drive string and central inverter volumes through state-backed procurement frameworks. The National Energy Administration enforces GB standards compliance and dual carbon goals that accelerate grid-forming inverter specifications. Sungrow Power Supply anchors manufacturing scale in Hefei while supplying utility-scale projects across the Belt and Road corridor.
India
Rajasthan and Gujarat solar parks above 500 MW specify central inverters for desert megaprojects while sub-100 MW installations favor string architectures for modularity. The Central Electricity Authority mandates CEA technical standards for low-voltage ride-through and reactive power capability that filter non-compliant suppliers from tender eligibility. IPPs in Karnataka and Maharashtra procure 25-year service contracts to optimize LCOE metrics.
United States
Texas and Arizona developers specify liquid-cooled inverters for derating avoidance in extreme climates, while California's CPUC mandates four-hour lithium-ion pairing that expands hybrid inverter specifications. FERC Order 2023 implementation timelines vary by regional transmission organization, stretching interconnection queues and commissioning schedules. ERCOT and CAISO market designs reward grid-forming capabilities with capacity market premiums.
Germany
The Federal Network Agency enforces VDE-AR-N 4120 grid codes and F-Gas Regulation phase-downs that force SF6-free switchgear redesigns in medium-voltage substations. SMA Solar Technology sustains service density across Bavarian and North Rhine-Westphalian project pipelines through regional technician networks. The EU Green Deal accelerates storage co-location mandates that hybrid inverters capture.
Saudi Arabia
The National Renewable Energy Program tenders utility-scale solar at scale without incumbent supplier relationships, creating entry opportunities for string and central inverter OEMs. Al-Jouf and Tabuk desert megaprojects exceed 500 MW and specify central inverter blocks for economies of scale despite single-point failure exposure. ACWA Power and other developers prioritize IEC 61727 compliance for project finance eligibility through multilateral lending institutions.
Utility Scale PV Inverter Market Vendor Landscape
Concentration sits with diversified power electronics conglomerates and specialized solar inverter OEMs that span technology architectures and geographic markets. The vendor base separates into three tiers: captive semiconductor fabricators with in-house module sourcing, merchant-component assemblers dependent on foundry allocation, and service-intensive specialists competing on regional technician density. Strategic moves center on backward integration into power semiconductor supply and geographic expansion into tender-heavy Middle Eastern and Latin American markets.
Within the diversified technology tier, Huawei Technologies and Sungrow Power Supply exemplify scale-driven positioning across Asia-Pacific and Middle Eastern project pipelines. SMA Solar Technology occupies a specialist position anchored in European and North American service density. These three represent divergent competitive vectors: manufacturing scale, modular architecture innovation, and aftermarket service concentration.
| Leading Market Players |
|---|
| Sineng Electric |
| Ginlong Technologies |
| Sungrow Power Supply |
| SolarEdge Technologies |
| TMEIC |
| Huawei Technologies |
| Power Electronics |
| FIMER |
| SMA Solar Technology |
| Others |
Supply Flow & Price Mechanics
GB standards compliance gates both supplier qualification and price differentiation in China's utility-scale solar procurement, compressing margins for non-compliant OEMs while rewarding grid-forming premium tiers. This regulatory threshold simultaneously filters tender eligibility and stratifies pricing power across inverter manufacturers.
Pricing Analysis
IEC 61727 and IEEE 1547 dictate the pricing tier structure by mandating low-voltage ride-through and frequency-watt control as baseline qualifiers. Three-tier pricing separates grid-forming premium inverters with black-start capability from standard utility-tied units and economy-tier legacy architectures. Cost compression in the economy tier is intensifying because merchant-component assemblers lack captive silicon carbide sourcing. Independent power producers exhibit the highest price sensitivity, while vertically integrated utilities prioritize service density over unit cost.
Supply Chain Analysis
China and Taiwan anchor IGBT and silicon carbide wafer fabrication, feeding power semiconductor demand across inverter OEM tiers. Inverter assembly draws from East Asian foundries for wide-bandgap devices, copper magnet wire from Chinese smelters, and aluminum enclosures from domestic extruders. Single-source vulnerability concentrates in 1500V DC-rated silicon carbide modules, where two foundries control merchant supply. Distribution runs through EPC contractor procurement channels with multi-year framework agreements, bypassing spot markets for utility-scale volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide power semiconductor adoption represents a technological inflection that will bifurcate inverter supplier tiers within this high-growth disruption, separating captive-sourcing OEMs from merchant-dependent assemblers.
For Market Incumbents: Secure backward integration into silicon carbide module fabrication to offset foundry allocation constraints and defend margin position against Chinese manufacturing scale. Prioritize grid-forming certification investments for ERCOT and CAISO capacity market premiums, while consolidating regional service technician density in India and Brazil to capture unbundled O&M contracts. For New Entrants and Emerging Players: Anchor in Saudi Arabia's National Renewable Energy Program tender pipeline, where incumbent supplier relationships remain unformed and ACWA Power procurement favors IEC 61727 compliance over brand legacy. Target hybrid inverter architectures for California and German storage co-location mandates, leveraging bidirectional conversion as a specification wedge against pure-play solar incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized power electronics divisions and stranded inverter product lines lacking storage integration roadmaps. Long-term viability favors OEMs with captive semiconductor sourcing and regional service networks. The signal to watch is FERC Order 2023 implementation velocity, which will accelerate or delay utility-scale commissioning schedules and working capital cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Sourcing | Captive wafer supply from Chinese foundries insulates margins against merchant allocation constraints. |
| Grid-Forming Certification | ERCOT and CAISO capacity premiums reward black-start and synthetic inertia capabilities in weak-grid applications. |
| Hybrid Inverter Development | Four-hour lithium-ion pairing mandates in California and Germany expand addressable specification scope. |
| Regional Service Network Buildout | Technician density in Rajasthan and Al-Jouf captures unbundled O&M contracts from IPP asset owners. |
| SF6-Free Switchgear Redesign | F-Gas Regulation compliance maintains tender eligibility in German and Spanish utility-scale procurement. |
Methodological Framework
Initial hypotheses were tested against primary input from IPP project developers, EPC procurement directors, grid interconnection engineers, and inverter OEM product managers, and refined through secondary validation against FERC filings, IEA renewable deployment databases, CEA technical standards documentation, and project finance term sheets. Bottom-up unit economics from individual solar park developments were triangulated with top-down national installation targets across China, India, and the United States.
Variance decomposition across product architecture, storage integration intensity, and regional grid code stringency shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include inverter type, cooling technology, battery coupling configuration, and end-user procurement sophistication. CAGRs were derived from capacity-weighted average selling price trajectories and installation volume buildouts, with silicon carbide adoption curves and interconnection queue clearance rates as industry-specific forecast inputs.
Underlying assumptions cover sustained multi-gigawatt solar program execution, stable power semiconductor foundry allocation, and FERC Order 2023 implementation timelines, with deviation risk concentrated in tariff exposure for East Asian component imports and utility interconnection queue delays. Recalibration cycles align with material shifts in grid code harmonization progress and storage mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
Saudi Arabia Solar PV Module Market
Solar Power Systems
Sweden Solar Energy Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Solar Fuel Market
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Australia Solar Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar PV Carport Market
Solar Power Systems
Europe Solar Concentrator Market
Solar Power Systems
Greece Renewable Energy Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Spain Rooftop Solar Market