
 Solar Module Racking Market | 2026-2036
Solar Module Racking Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Module Racking Market Insights
Utility-scale solar deployment is realigning racking procurement toward high-load, terrain-adaptive systems. Clenergy leverages its Asia-Pacific manufacturing footprint to serve utility tenders across Southeast Asia. K2 Systems anchors its position through specialized rooftop mounting solutions for commercial installations. Schletter competes on engineering depth in tracking systems for large ground-mount arrays.
Solar module racking encompasses the structural support assemblies that secure photovoltaic panels at optimal tilt and azimuth, typically fabricated from extruded aluminum sections, cold-formed steel channels, or hot-dip galvanized profiles with specified yield strengths and corrosion ratings. These systems transfer wind, snow, and seismic loads into foundations while enabling electrical grounding and thermal expansion accommodation across the array field. Fixed racking retains dominant installed volume due to lower capital intensity and reduced maintenance exposure, though tracking systems capture expanding share in high-irradiance zones where energy yield premiums justify mechanical complexity. Steel and galvanized steel materials sustain cost-sensitive utility procurement, while aluminum profiles command premium residential and commercial segments where weight constraints and corrosion resistance shape specification. Ground mount installations occupy the largest addressable base, with community solar configurations emerging as a discrete channel with distinct interconnection and land-use permitting profiles.
FERC interconnection standards and state-level renewable portfolio obligations in the US shape utility-scale deployment timelines and racking specification intensity. IEC 62817 for solar trackers and EU CE marking under the Construction Products Regulation establish mechanical safety and durability benchmarks for market access across Europe. Stakeholders must monitor evolving wind-load design codes and emerging circularity requirements for end-of-life material recovery as procurement criteria harden.
Market Dynamics
Utility-scale procurement is compressing supplier margins while demanding higher structural load ratings and terrain-adaptive engineering, forcing racking manufacturers to absorb foundation cost volatility and accelerate certification cycles.
Growth Catalysts
- India's PLI scheme for solar manufacturing:Domestic content mandates under the Production Linked Incentive program are accelerating localized racking fabrication capacity to serve national solar park tenders.
- EU Green Deal construction standards:Updated CE marking requirements under the Construction Products Regulation are mandating enhanced corrosion ratings and circularity documentation for market access.
- Single-axis tracking technology:Energy yield premiums in high-irradiance zones are pulling procurement toward mechanical tracking systems despite higher capital intensity.
Market Restraints
- Aluminum price volatility:Extruded aluminum sections face input cost swings that compress margin buffers for premium residential and commercial segments.
- Foundation labor concentration:Pile-driving and geotechnical preparation capabilities concentrate in specialized regional contractors, creating scheduling bottlenecks for utility-scale deployment.
- IEC 62817 certification timelines:Extended testing protocols for solar tracker mechanical safety delay product commercialization and tender participation.
Strategic Opportunities
- Agrivoltaics integration:Dual-use solar installations combining module racking with agricultural operations are opening specification channels requiring elevated mounting heights and adjustable tilt.
- Community solar configurations:Distributed generation programs in multiple US states are creating discrete interconnection and land-use permitting profiles with specialized racking needs.
- End-of-life material recovery mandates:Emerging circularity requirements under EU waste frameworks are creating first-mover advantages for suppliers with closed-loop aluminum and steel reclamation systems.
Industry Challenges
- Geotechnical engineering talent scarcity:Specialized foundation design expertise for terrain-adaptive systems remains concentrated among limited consulting pools, extending project development timelines.
- Multi-standard compliance complexity:Simultaneous adherence to FERC interconnection standards, IEC structural benchmarks, and evolving wind-load design codes fragments engineering resources.
- Tracker mechanical integration risk:Single-axis and dual-axis systems face warranty exposure from bearing wear, motor failure, and control system synchronization errors in harsh climate zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Module Racking Market |
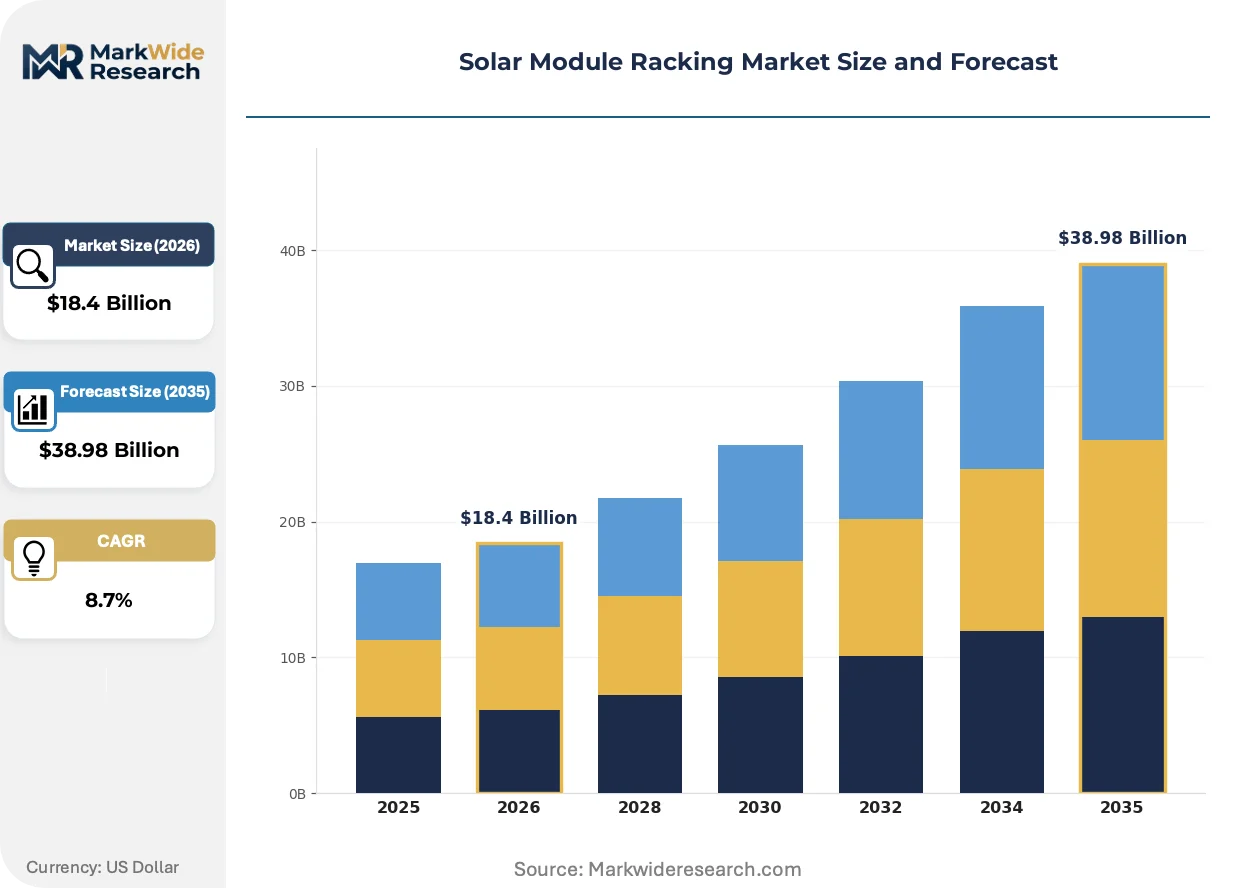
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $38.98 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Racking, Adjustable Racking, Tracking Systems, Ground Mount Material: Aluminum, Steel, Galvanized Steel, Polymeric Installation Type: On-grid, Off-grid, Hybrid, Community Solar End User: Residential, Commercial, Industrial, Utility |
| Companies Covered | Clenergy, K2 Systems, Schletter, JZNEE, RBI Solar, Unirac, Esdec, Mounting Systems, DPW Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Module Racking Market Trends and Innovations
Structural design philosophy is pivoting from standardized fixed-tilt arrays toward adaptive systems that accommodate irregular terrain and dual-use land applications without custom engineering for each site.
High-strength cold-formed steel channel sections are consolidating as the dominant material choice for cost-sensitive utility procurement. EPC contractors in India and the United States are specifying galvanized steel profiles with 50 ksi minimum yield strength for ground-mount arrays. This material shift is compressing aluminum's addressable share in the utility segment while enabling longer span distances between foundation points.
EU CE marking under the Construction Products Regulation is tightening mechanical safety and durability benchmarks for solar racking market access. Manufacturers must now submit extended corrosion testing documentation and structural calculation packages to notified bodies. Large ground-mount arrays in Germany and Spain face heightened scrutiny of wind-load design assumptions and foundation pull-out resistance verification.
Buyers are unbundling racking supply from turnkey EPC contracts to capture direct procurement savings and accelerate installation scheduling. Utility developers in India and community solar sponsors in Minnesota are issuing separate tenders for structural support assemblies independent of module and inverter packages. This pattern fragments traditional supplier relationships and exposes racking manufacturers to direct price competition and extended warranty negotiations.
Solar Module Racking Market Segmentation
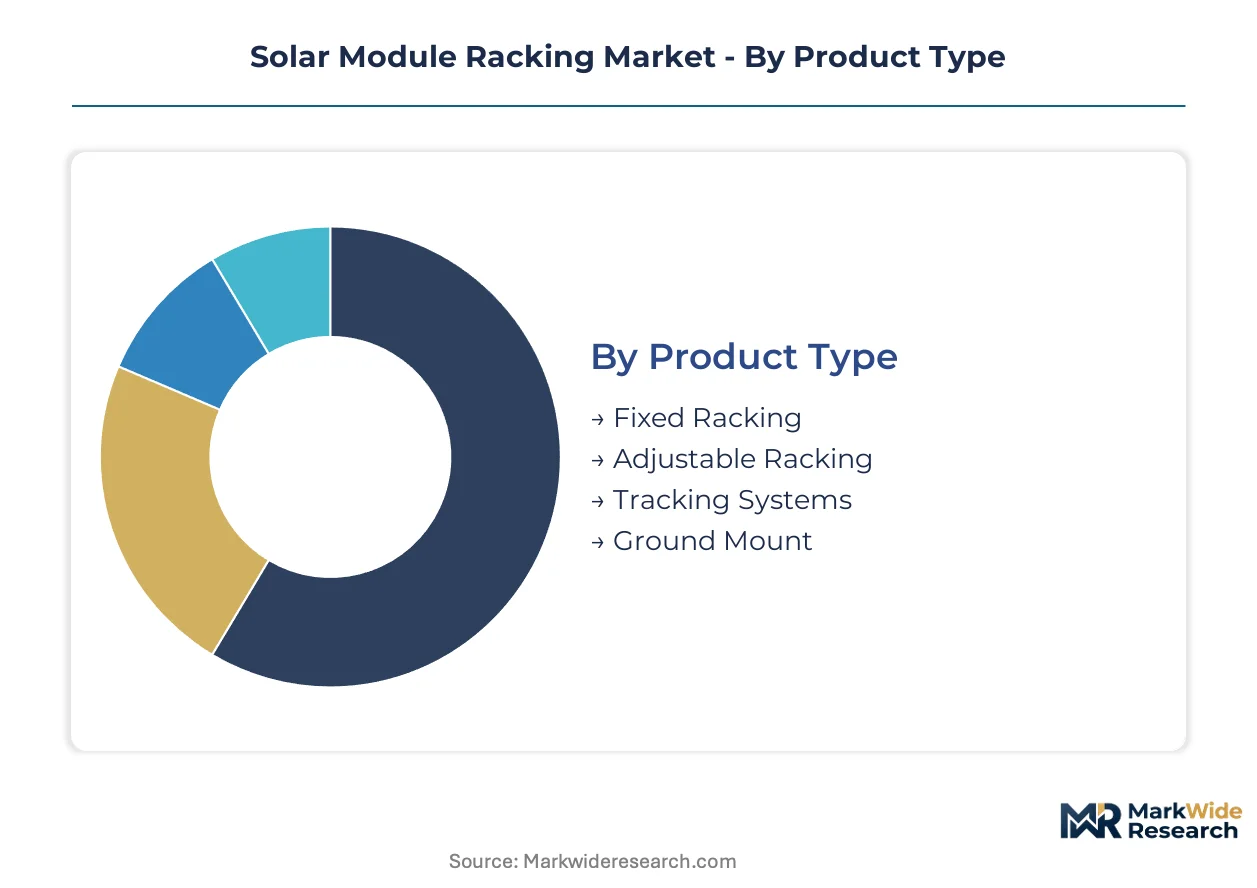
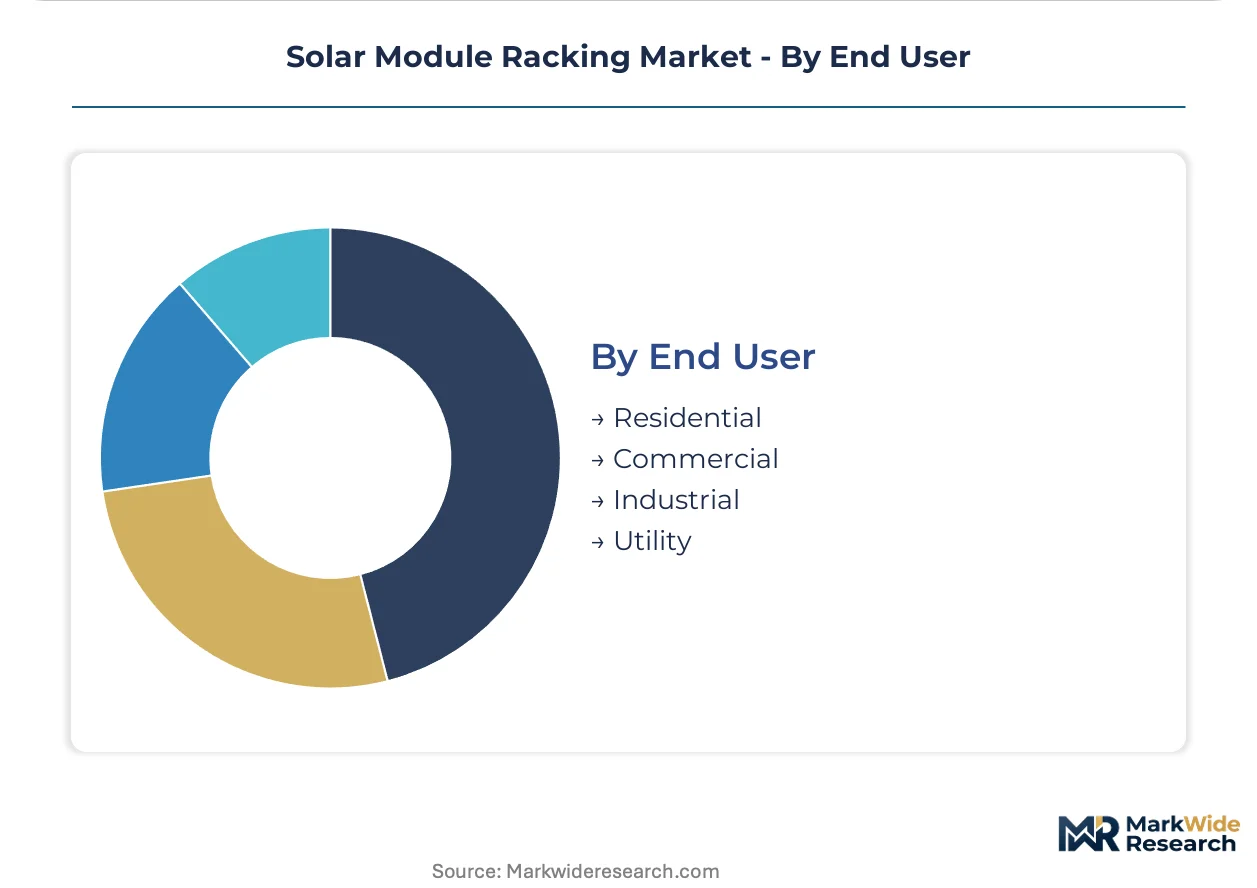
Solar module racking segmentation reveals how certification intensity, material cost exposure, and installation scale reshape procurement patterns across distinct buyer profiles. Structural load ratings and foundation engineering requirements fragment specification standards between residential rooftops and utility-scale arrays.
Product Type:
IEC 62817 certification mandates apply selectively across product categories, with tracking systems facing the most extensive mechanical safety testing protocols while fixed racking navigates simpler structural compliance pathways.
- Fixed Racking:Stationary tilt-angle assemblies fabricated from extruded aluminum or steel channels dominate installed volume due to minimal moving parts and reduced maintenance exposure. Procurement concentrates in India and the United States where utility-scale tenders prioritize capital efficiency over energy yield optimization, though terrain-adaptive engineering now extends standard product lines.
- Tracking Systems:Single-axis and dual-axis mechanical assemblies rotate modules to track solar azimuth, capturing energy yield premiums in high-irradiance zones. Demand clusters in Spain and the southwestern United States where FERC interconnection standards and state renewable portfolio obligations justify higher capital intensity through enhanced capacity factors.
- Adjustable Racking:Seasonal tilt-modification systems occupy a narrow niche between fixed and tracking solutions.
- Ground Mount:Foundation-anchored arrays for open-terrain deployment represent the default configuration for utility-scale procurement.
Leading the category by volume: Fixed Racking. Growing fastest: Tracking Systems.
Material:
Raw material cost tiers stratify supplier margins and end-use accessibility, with aluminum commanding premium positioning against steel's utility-scale dominance.
- Steel:Cold-formed and hot-rolled carbon steel profiles with specified yield strengths anchor cost-sensitive utility procurement, enabling longer foundation spans and reduced pile density. Specification intensity concentrates in Indian national solar park tenders and United States utility-scale EPC contracts where galvanized coatings address corrosion exposure.
- Aluminum:Extruded 6061-T6 and 6005-T5 alloy sections deliver weight advantages and corrosion resistance for residential and commercial rooftops where structural loading constraints limit steel deployment. European CE marking requirements under the Construction Products Regulation intensify documentation burdens for aluminum suppliers serving German and Spanish markets.
- Galvanized Steel:Hot-dip zinc-coated profiles bridge cost and durability requirements for ground-mount installations.
- Polymeric:Composite and thermoplastic structural elements occupy emerging niches in corrosive coastal environments.
Steel captures the largest volume share. Aluminum maintains the steepest expansion trajectory in premium segments.
Installation Type:
Interconnection complexity and regulatory jurisdiction fragment procurement patterns across grid-tied and standalone configurations.
- On-grid:Utility-interconnected arrays dominate capacity deployment, with racking specification tied to FERC standards in the United States and national grid codes in India. Commercial and industrial rooftops in Germany and Spain drive aluminum-intensive procurement under EU Green Deal construction standards.
- Community Solar:Shared-generation configurations in Minnesota, New York, and Colorado create discrete permitting profiles requiring specialized land-use racking solutions. Subscription-based models accelerate deployment timelines compared to behind-the-meter commercial installations.
- Off-grid:Standalone systems for remote electrification prioritize modularity and simplified foundation requirements.
- Hybrid:Grid-tied arrays with battery storage integration demand enhanced structural loading for energy storage equipment mounting.
On-grid installations lead by installed capacity. Community Solar configurations are gaining share fastest among distributed generation channels.
End User:
Buyer scale and technical sophistication reshape specification intensity, warranty negotiation leverage, and supplier relationship structures.
- Utility:Gigawatt-scale developers unbundle racking from turnkey EPC contracts to capture direct procurement savings, compressing supplier margins while demanding extended structural warranties and terrain-adaptive engineering. Tender participation in India and the United States requires demonstrated compliance with evolving wind-load design codes.
- Commercial:Mid-scale rooftop and carport installations balance aluminum weight constraints against steel cost advantages, with K2 Systems and Schletter competing through specialized engineering packages for flat-roof membrane compatibility.
- Residential:Single-home installations prioritize rapid permitting and aesthetic integration over structural optimization.
- Industrial:Large rooftop and brownfield deployments combine scale economies with complex structural engineering requirements.
Utility end users command the largest volume. Commercial segment shows the fastest specification sophistication gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Asia-Pacific manufacturing hubs while consumption clusters in high-irradiance zones across India, the United States, and southern Europe. This geographic split creates freight cost exposure for European and North American developers sourcing structural assemblies. Procurement localization mandates are gradually rebalancing this equation.
United States
Utility-scale deployment in Texas and California drives demand for high-load steel racking systems. FERC interconnection standards shape project timelines and structural specification intensity. Arizona and Nevada solar clusters absorb growing volumes of single-axis tracking hardware to maximize capacity factors in desert irradiance conditions.
India
National solar park tenders in Rajasthan and Gujarat are accelerating localized fabrication capacity under PLI scheme incentives. CEA grid connectivity regulations mandate specific structural documentation for utility-scale arrays. Tamil Nadu and Karnataka manufacturing corridors are attracting steel processing investments to serve domestic content requirements.
Germany
Commercial rooftop installations in Bavaria and North Rhine-Westphalia sustain premium aluminum racking demand. EU Green Deal construction standards and CE marking under the Construction Products Regulation intensify corrosion testing documentation. Brandenburg and Saxony-Anhalt are emerging as agrivoltaics testing grounds requiring elevated mounting structures.
Spain
Extremadura and Andalusia solar clusters favor tracking systems to capture energy yield premiums in high-irradiance zones. IEC 62817 certification requirements filter supplier participation in large ground-mount tenders. Castilla-La Mancha is developing specialized permitting frameworks for dual-use agricultural solar configurations.
Australia
Queensland and New South Wales utility pipelines specify terrain-adaptive systems for irregular topography. Grid connection standards under AEMO jurisdiction influence structural load calculations and foundation design. Victoria is piloting community solar programs with discrete racking procurement profiles separate from utility-scale channels.
Solar Module Racking Market Competitive Landscape
Top-tier vendors anchor utility-scale procurement, while mid-tier specialists capture commercial rooftop and distributed generation niches. The vendor base stratifies across three tiers: integrated steel fabricators serving cost-sensitive tenders, aluminum extrusion specialists targeting premium residential segments, and tracking system engineers competing on yield optimization. Strategic moves concentrate on backward integration into steel processing and geographic expansion through regional licensing arrangements.
Within the Asia-Pacific manufacturing tier, Clenergy and JZNEE represent the scale-driven archetype serving utility tenders across Southeast Asia and India. Schletter and K2 Systems exemplify engineering-depth positioning, with the former anchoring tracking system specifications and the latter occupying specialized commercial rooftop solutions. These four names illustrate how competitive positioning fragments across material specialization, installation type focus, and regional manufacturing footprint.
| Leading Market Players |
|---|
| Clenergy |
| K2 Systems |
| Schletter |
| JZNEE |
| RBI Solar |
| Unirac |
| Esdec |
| Mounting Systems |
| DPW Solar |
| Others |
Pricing and Supply Chain Analysis
Captive steel processing in India and Vietnam anchors both supply security and pricing leverage for utility-scale racking manufacturers serving national solar park tenders. This backward integration insulates integrated fabricators from raw material volatility while compressing margins for aluminum-dependent specialists in premium residential segments.
Pricing Analysis
Short-lead-time premiums command pricing separation from spot inventory channels in the solar racking sector. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with IEC 62817-certified tracking systems capturing brand premiums over uncertified fixed-rack alternatives. Cost compression in the steel-intensive utility tier is intensifying because Indian PLI scheme beneficiaries are absorbing foundation cost volatility to secure tender awards. Utility developers exhibit the highest price sensitivity, while commercial rooftop installers prioritize membrane compatibility and rapid permitting over per-watt procurement savings.
Supply Chain Analysis
Single-source vulnerability sits with Chinese aluminum extrusion capacity serving European residential and commercial segments. Manufacturing gravity centers on India, Vietnam, and China for structural steel processing and aluminum profile fabrication, with raw material inputs drawing from Australian iron ore, Indonesian nickel for galvanized coatings, and Chinese primary aluminum. Tariff exposure on Chinese aluminum sections fragments engineering resources for European suppliers seeking alternative sourcing. Distribution runs through EPC contractor networks in utility-scale channels and specialized solar distributors in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around integrated steel fabricators with captive processing capabilities, as aluminum price volatility and certification burden force pure-play extrusion specialists toward acquisition or exit.
For Market Incumbents: Anticipate foundation labor scarcity extending project timelines by securing exclusive pile-driving contractor partnerships in Rajasthan and Gujarat solar corridors. Deepen backward integration into hot-dip galvanizing capacity to capture margin from corrosion-rated steel demand under EU CE marking requirements. Prioritize terrain-adaptive engineering R&D to defend position against emerging tracker specialists capturing yield-premium procurement in Spain and the southwestern United States. For New Entrants and Emerging Players: Agrivoltaics-compatible elevated mounting systems offer a technology-first wedge into underserved dual-use agricultural solar configurations in Germany and Australia. Target community solar permitting expertise in Minnesota and Colorado as the most penetrable white-space channel, where subscription-based models accelerate deployment timelines compared to utility-scale tender participation. Pursue direct racking supply relationships with IPP developers unbundling from turnkey EPC contracts as the primary go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier steel fabricators with demonstrated PLI scheme compliance and established utility tender relationships. Long-term viability favors suppliers with closed-loop aluminum reclamation systems positioned for EU circularity mandates. Watch IEC 62817 certification backlog duration as the signal for tracker market entry timing and competitive intensity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Processing | Captive galvanizing capacity secures margin control for Indian utility tender participation under PLI incentives. |
| Agrivoltaics Engineering Development | Elevated mounting structures open dual-use land access in Germany's Brandenburg agricultural testing zones. |
| IEC 62817 Certification Investment | Mechanical safety testing compliance filters supplier participation in Spanish Extremadura tracking tenders. |
| Community Solar Channel Partnership | Direct procurement relationships with Minnesota developers bypass traditional EPC bundling structures. |
| Circular Aluminum Reclamation Buildout | Closed-loop recovery systems anticipate EU waste framework mandates for end-of-life material documentation. |
Research Methodology
Multi-period observation of tender award patterns, certification timelines, and raw material cost indices anchored the trend analysis, supplemented by interviews with EPC procurement directors, solar park development officers, racking manufacturer sales leads, and geotechnical engineering consultants. Secondary validation drew from FERC interconnection filings, CEA grid connectivity regulations, EU Construction Products Regulation documentation, and Indian PLI scheme beneficiary disclosures. Bottom-up project pipeline tracking and top-down manufacturing capacity assessments were triangulated to reconcile volume estimates.
Input-output matrices modeled deployment across product type, material grade, installation scale, and regulatory framework clusters throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific forecast inputs included solar irradiance zone yield premiums for tracking system penetration and domestic content mandate compliance rates for localized fabrication capacity buildout.
Several conditions sit outside the modeled scope, including unannounced regulatory revisions to wind-load design codes and unscheduled aluminum tariff adjustments. Forecasts reflect documented assumptions about PLI scheme continuation and IEC certification protocol stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
United States Solar Microinverter Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Flat Plate Solar Collector Market
Solar Power Systems
Industrial Solar Water Heaters Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Rooftop Solar PV Market
Solar Power Systems
Single Axis Solar PV Tracker Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
High-Efficiency Solar Modules Market