
 China Distributed Solar Power Generation Market | 2026-2036
China Distributed Solar Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
China Distributed Solar Power Generation Market Outlook
Multi-source procurement of photovoltaic modules is hardening as developers diversify supply beyond legacy single-source contracts. LONGi Green Energy Technology Co., Ltd. anchors high-efficiency monocrystalline wafer output through captive silicon production. JinkoSolar Holding Co., Ltd. leverages vertically integrated cell-to-module capacity to sustain cost discipline across distributed project bids. Trina Solar Co., Ltd competes on 210mm large-format module architecture optimized for commercial rooftop density.
China distributed solar power generation encompasses decentralized photovoltaic systems typically below 50 MW capacity, installed at or near consumption points with voltage levels ranging from 220V to 35kV, converting sunlight through silicon-based cells into grid-synchronous alternating current for on-site use or net-export. These systems serve industrial and commercial load centers seeking electricity cost reduction, peak shaving, and carbon compliance without transmission-scale infrastructure. Rooftop systems dominate current deployment volume due to mature installation protocols and minimal land-use friction across dense manufacturing zones. Battery storage attachment rates are accelerating fastest among installation types as time-of-use tariff spreads and grid stability requirements reshape project economics. Agricultural applications within the application dimension occupy an emerging margin pool where agrivoltaic dual-use policies unlock rural land access previously restricted under farmland preservation rules.
MIIT governs solar manufacturing standards through GB certification mandates that filter module efficiency thresholds for grid-connected distributed projects. NMPA-aligned technical supervision ensures inverter and battery storage safety compliance under evolving electrochemical energy storage regulations. MEE enforces dual carbon trajectory reporting that compels industrial end users to document renewable electricity share in provincial environmental audits. Stakeholders must track how county-level grid absorption capacity constraints and interconnection queue reforms reshape project viability timelines across China's fragmented distribution network.
Market Dynamics
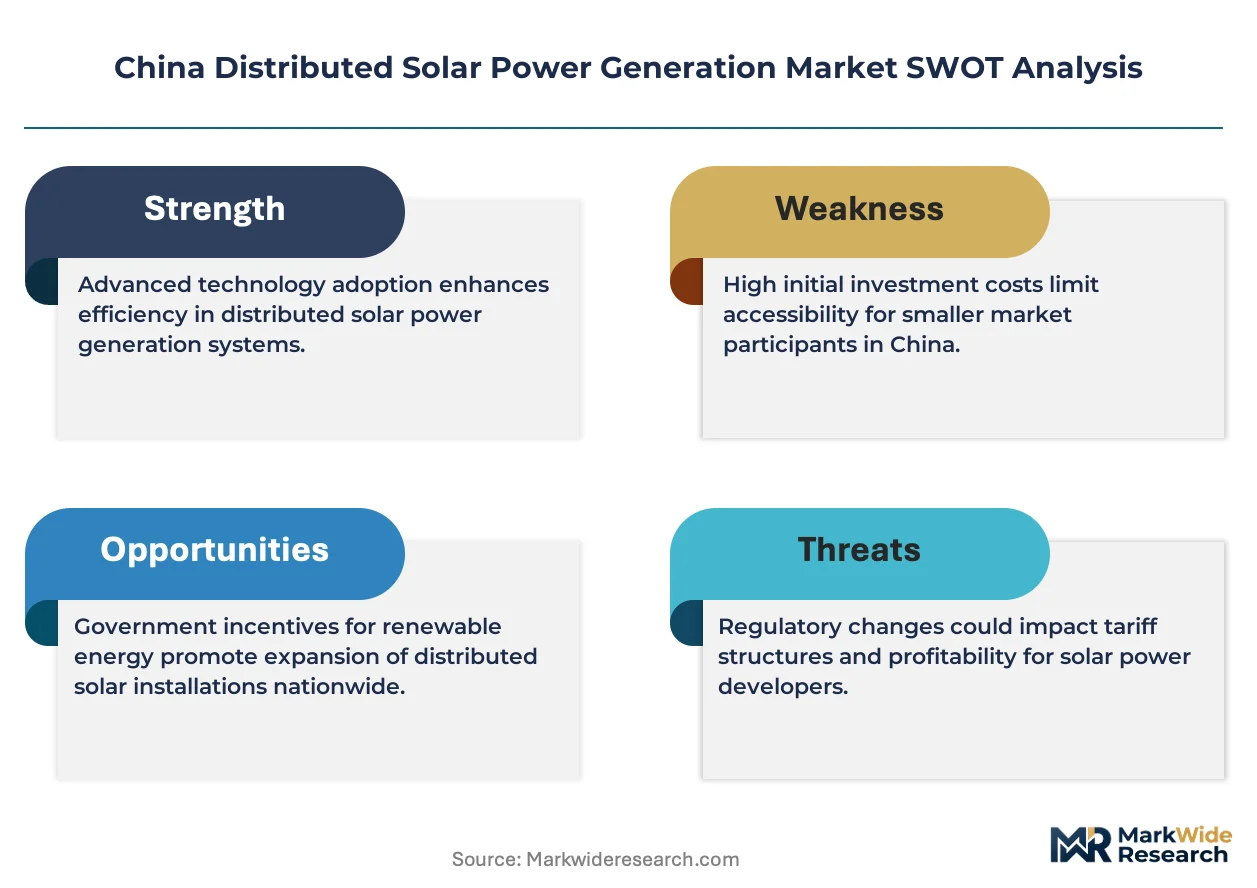
Grid parity mechanisms and county-level absorption capacity constraints are reshaping project economics across China's fragmented distribution network, forcing developers to prioritize interconnection-ready sites over raw irradiance metrics.
Growth Catalysts
- Dual carbon trajectory reporting:MEE mandates compel industrial facilities in Jiangsu and Zhejiang to document renewable electricity share, converting compliance pressure into procurement pull for rooftop systems.
- Net metering policies:Provincial structures in Shandong channel investment toward manufacturing clusters by enabling on-site consumption credits that improve project IRR without external subsidies.
- Agrivoltaic dual-use frameworks:Rural land access rules are unlocking previously restricted farmland for agricultural applications, expanding addressable surface area beyond industrial rooftops.
Market Restraints
- Polysilicon input volatility:Captive silicon production concentrates among legacy suppliers, exposing non-integrated developers to margin compression when metallurgical-grade feedstock prices spike.
- County-level grid absorption limits:Eastern coastal distribution networks face interconnection queue bottlenecks that extend project viability timelines beyond developer capital lockup tolerances.
- Electrochemical storage safety compliance:NMPA-aligned technical supervision for battery attachment creates certification friction that delays revenue recognition for hybrid installations.
Strategic Opportunities
- Central and western province penetration:Manufacturing relocation to inland provinces under China's industrial transfer policy is creating untapped rooftop inventory outside saturated coastal markets.
- Time-of-use tariff arbitrage:Peak shaving economics are accelerating battery storage attachment rates among commercial zones seeking demand charge reduction.
- GB certification threshold elevation:MIIT efficiency mandates are filtering substandard module supply, creating margin expansion for certified high-efficiency monocrystalline wafer output.
Industry Challenges
- Electrical engineering talent scarcity:Distributed project scaling has outpaced vocational training pipeline for grid-synchronous inverter commissioning and 35kV interconnection design.
- Legacy meter infrastructure incompatibility:Bidirectional net metering requires utility-side hardware upgrades that fragment deployment timelines across provincial grid operators with varying capex cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Distributed Solar Power Generation Market |
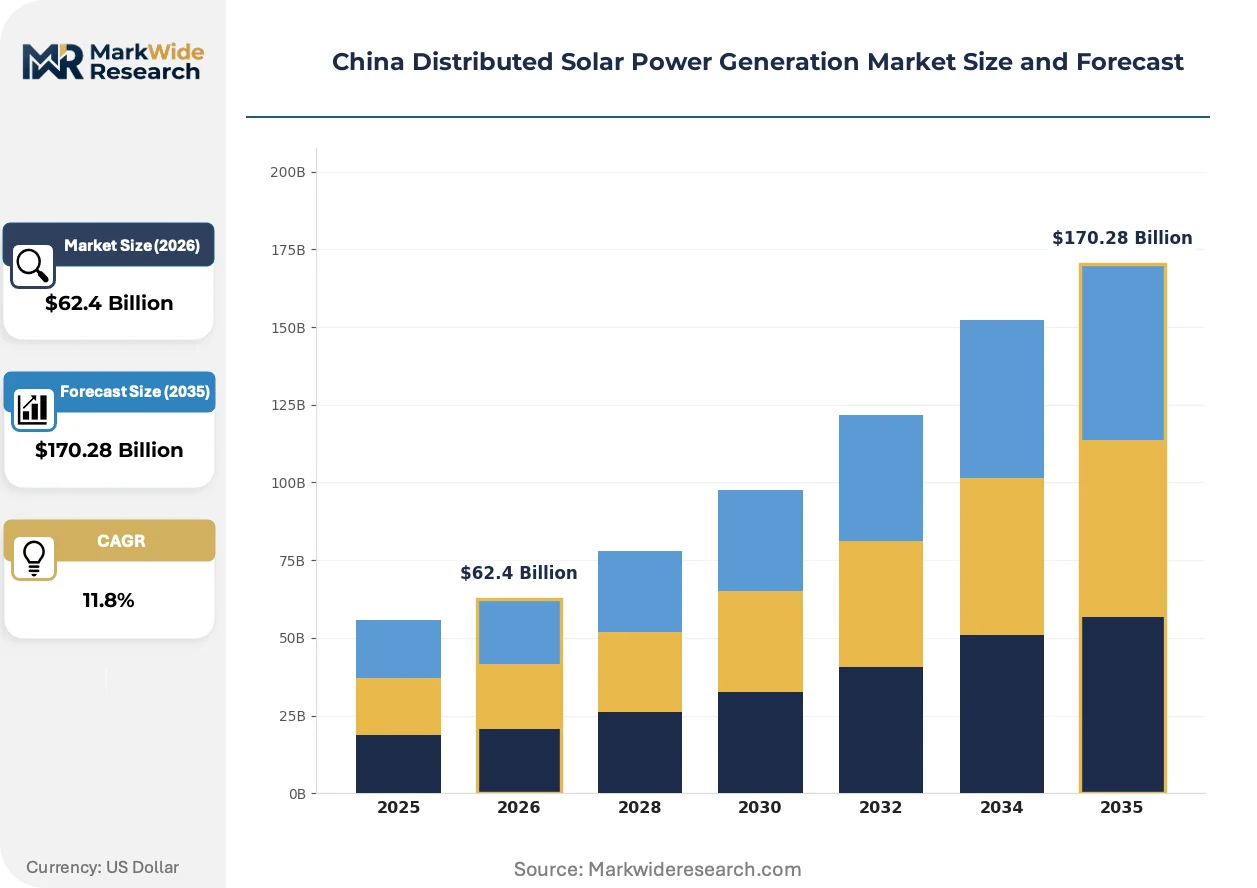
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $170.28 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar Panels, Inverters, Battery Storage, Monitoring Systems Application: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop Systems, Ground-mounted Systems, Building-integrated Systems, Off-grid Systems End User: Homeowners, Businesses, Farms, Educational Institutions |
| Companies Covered | JA Solar Holdings Co., Ltd., CSUNPOWER Technology (Nanjing) Co., Ltd, JinkoSolar Holding Co., Ltd., Astronergy (Chint New Energy Technology), Wuxi Suntech Power Co., Ltd., Trina Solar Co. Ltd, Tongwei Solar, Shanghai Aiko Solar Energy Co., Ltd., LONGi Green Energy Technology Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Distributed Solar Power Generation Market Strategic Shifts
Technology convergence and procurement model evolution are compressing installation cycles while regulatory tightening around carbon disclosure is embedding solar generation into industrial facility valuation metrics.
Smart inverter systems with integrated power electronics are automating voltage regulation and reactive power compensation for commercial rooftops. Food processing and cold storage facilities in Guangdong are adopting these systems fastest due to refrigeration load sensitivity. This automation is compressing O&M headcount requirements and enabling remote fault detection that reduces truck-roll frequency for distributed asset operators.
MIIT's evolving GB certification mandates are elevating module efficiency thresholds for grid-connected distributed projects. Manufacturers must now recalibrate cell-to-module processes to maintain bid eligibility under tightened technical specifications. Industrial end-users in Shandong and Jiangsu are responding by embedding efficiency guarantees into EPC contracts, transferring compliance risk to installers.
Buyer concentration among state-owned manufacturing conglomerates is consolidating procurement authority previously dispersed across facility managers. Direct OEM relationships are displacing regional distributor networks for module and inverter supply in the steel and cement sectors. This pattern is most visible in Hebei province where provincial SOE restructuring has centralized energy procurement decisions for subsidiary plant networks.
China Distributed Solar Power Generation Market Segmentation
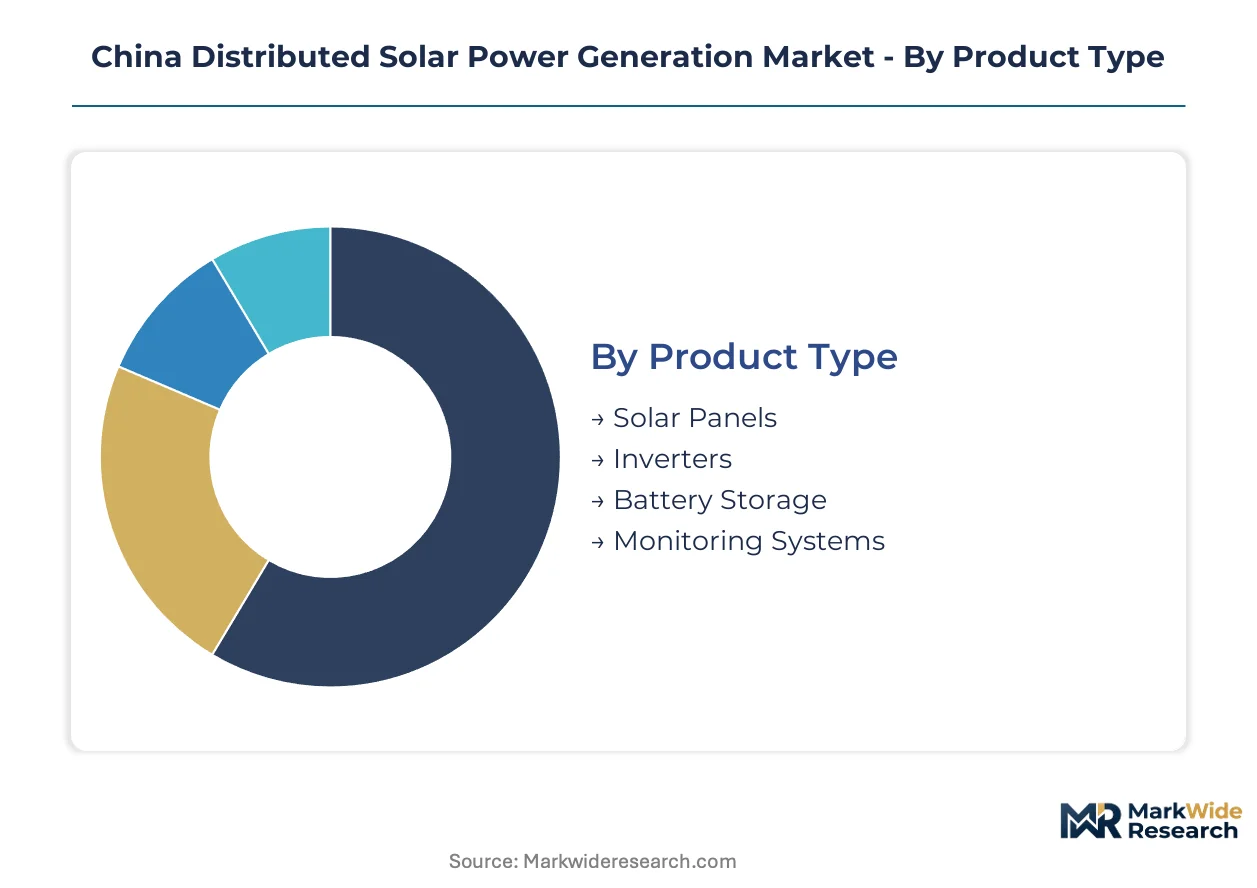
Segmentation in China's distributed solar market reveals how procurement priorities diverge across hardware categories, use cases, and customer economics. Understanding these divisions exposes where margin concentrates and which technology combinations unlock project bankability under provincial regulatory frameworks.
Product Type:
Standardization dominates solar panels and inverters, while battery storage and monitoring systems demand heavier customization for site-specific load profiles and grid interconnection requirements.
- Solar Panels:Silicon-based photovoltaic cells convert sunlight to direct current electricity, with monocrystalline architectures commanding premium positioning in Jiangsu and Zhejiang manufacturing clusters where efficiency guarantees anchor EPC contract terms.
- Inverters:Power electronics convert DC output to grid-synchronous alternating current at 220V to 35kV levels, with smart systems automating voltage regulation for Guangdong food processing facilities facing refrigeration load sensitivity.
- Battery Storage:Electrochemical systems enable peak shaving and time-of-use arbitrage; NMPA-aligned technical supervision creates certification friction that delays revenue recognition for hybrid installations.
- Monitoring Systems:Remote fault detection platforms reduce truck-roll frequency for distributed asset operators managing fragmented portfolios across county-level grid boundaries.
Most installed capacity flows through Solar Panels. Expansion is steepest in Battery Storage.
Application:
Volume concentration tilts toward industrial and commercial loads where electricity cost reduction drives procurement, while agricultural applications unlock restricted land access under dual-use policy frameworks.
- Industrial:Manufacturing facilities in Shandong deploy rooftop systems to document renewable electricity share for MEE environmental audits under dual carbon trajectory mandates.
- Commercial:Retail and office properties leverage net metering credits to improve project IRR without external subsidies, with provincial structures in Zhejiang channeling investment toward dense commercial zones.
- Residential:Homeowner adoption concentrates in eastern coastal provinces where grid parity mechanisms and mature installation protocols reduce deployment friction.
- Agricultural:Agrivoltaic dual-use policies unlock rural land access previously restricted under farmland preservation rules, expanding addressable surface area beyond industrial rooftops.
Industrial applications absorb the majority of current deployment. Agricultural installations are climbing the fastest as county-level land access reforms take hold.
Installation Type:
Maturity gradients separate rooftop protocols from emerging building-integrated and off-grid architectures, with ground-mounted systems facing land-use friction that constrains scaling outside western provinces.
- Rooftop Systems:Mature installation protocols dominate deployment volume across dense manufacturing zones, minimizing land-use friction while serving on-site consumption needs for industrial and commercial load centers.
- Ground-mounted Systems:Distributed arrays below 50 MW capacity face absorption constraints in eastern coastal distribution networks, pushing development toward central and western provinces under industrial transfer policy.
- Building-integrated Systems:Photovoltaic elements embedded in building envelopes serve aesthetic and structural functions, with technical standards evolving under MIIT GB certification mandates.
- Off-grid Systems:Standalone installations serve remote loads without utility interconnection, requiring battery attachment to maintain supply continuity outside grid-synchronous operation.
Rooftop Systems carry the dominant share of installed base. Building-integrated configurations are gaining share fastest as urban density constraints intensify.
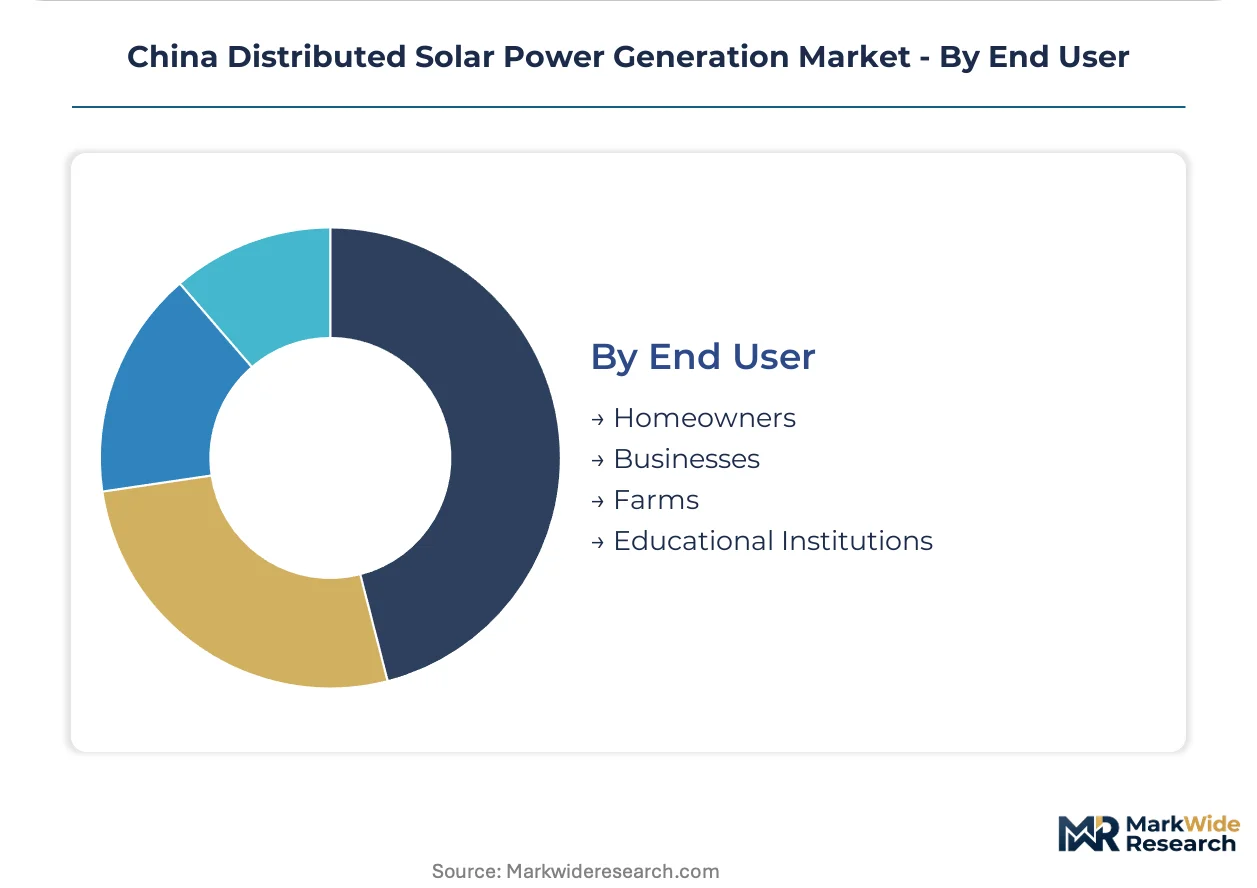
End User:
Procurement authority consolidation distinguishes state-owned manufacturing conglomerates from fragmented homeowner decision-making, with educational institutions occupying a mid-tier position on standardization and customization.
- Businesses:State-owned manufacturing conglomerates in Hebei province have centralized energy procurement decisions for subsidiary plant networks, displacing regional distributor networks with direct OEM relationships.
- Homeowners:Fragmented residential demand relies on regional installer networks and provincial net metering structures to aggregate project pipelines across county-level jurisdictions.
- Farms:Agricultural end-users access dual-use land frameworks that unlock previously restricted farmland, with rural credit facilities and county-level grid absorption limits shaping project viability timelines.
- Educational Institutions:Schools and universities combine rooftop availability with public procurement protocols, creating standardized bidding environments that filter substandard module supply under elevated GB certification thresholds.
Businesses account for the largest share of procurement volume. Farms are expanding most quickly as agrivoltaic policy implementation accelerates across interior provinces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu, Zhejiang, and Shandong provinces anchor China's distributed solar deployment through manufacturing cluster density and provincial net metering frameworks that accelerate rooftop adoption under dual carbon compliance mandates.
Jiangsu Province
Automotive and electronics manufacturing facilities in Suzhou and Wuxi drive rooftop procurement to offset electricity costs and meet MEE environmental audit requirements. Provincial feed-in tariff structures enable on-site consumption credits that improve project returns without external subsidies. Nanjing and Changzhou industrial zones concentrate the strongest installation pipelines as grid parity mechanisms mature.
Zhejiang Province
Textile and chemical processing plants in Ningbo and Hangzhou deploy distributed systems to document renewable electricity share for dual carbon trajectory reporting. Net metering policies channel investment toward dense commercial zones where peak shaving economics accelerate battery storage attachment rates. Wenzhou manufacturing clusters exhibit the fastest adoption velocity among private industrial enterprises.
Shandong Province
Steel and cement sector facilities in Jinan and Qingdao centralize energy procurement decisions under provincial SOE restructuring that displaces regional distributor networks. County-level grid absorption constraints reshape project viability timelines, forcing developers to prioritize interconnection-ready sites. Weifang and Yantai industrial corridors concentrate ground-mounted distributed arrays below 50 MW capacity.
Guangdong Province
Food processing and cold storage facilities in Shenzhen and Dongguan adopt smart inverter systems with integrated power electronics to manage refrigeration load sensitivity. MIIT GB certification mandates elevate module efficiency thresholds, filtering substandard supply from bid eligibility. Foshan and Zhuhai manufacturing zones lead building-integrated photovoltaic deployment as urban density constraints intensify.
Sichuan-Chongqing Region
Electronics manufacturing relocation under China's industrial transfer policy creates untapped rooftop inventory outside saturated coastal markets. Western province distribution networks face lower absorption constraints, compressing interconnection queue timelines. Chengdu and Chongqing metropolitan areas anchor emerging project pipelines as manufacturing gravity shifts inland.
China Distributed Solar Power Generation Market Competitive Environment
Global majors compete with regional champions across module efficiency tiers and captive silicon supply strategies. The vendor base stratifies between vertically integrated wafer-to-module producers and cell-to-module specialists competing on format architecture and certification compliance. Three archetypes dominate: integrated polysilicon-to-module producers controlling upstream feedstock, large-format module architects optimizing commercial rooftop density, and high-efficiency monocrystalline specialists anchoring premium EPC contract terms. Capacity expansion and direct OEM relationship cultivation represent the dominant competitive moves as procurement authority consolidates among state-owned manufacturing conglomerates.
Within the integrated production tier, LONGi Green Energy Technology Co., Ltd. and Tongwei Solar exemplify archetypes combining captive silicon supply with high-efficiency cell output. JinkoSolar Holding Co., Ltd. occupies a position between scale-driven module architecture and vertically integrated cost discipline. These three entities represent how procurement model evolution and GB certification compliance are compressing installation cycles while embedding solar generation into industrial facility valuation metrics.
| Leading Market Players |
|---|
| JA Solar Holdings Co., Ltd. |
| CSUNPOWER Technology (Nanjing) Co., Ltd |
| JinkoSolar Holding Co., Ltd. |
| Astronergy (Chint New Energy Technology) |
| Wuxi Suntech Power Co., Ltd. |
| Trina Solar Co. Ltd |
| Tongwei Solar |
| Shanghai Aiko Solar Energy Co., Ltd. |
| LONGi Green Energy Technology Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Metallurgical-grade silicon price indices cascade through China's distributed solar supply chain, compressing margins for non-integrated developers while concentrating pricing power among polysilicon-to-module producers with captive upstream supply. This input-cost architecture stratifies module procurement into efficiency-certified tiers that filter bid eligibility under MIIT's evolving GB mandates.
Pricing Analysis
Input-cost pass-through from polysilicon feedstock dominates module pricing dynamics, with efficiency-certified monocrystalline architectures commanding premium positioning against standard-tier multicrystalline alternatives. Price differentiation hinges on GB certification tier and volume scale, with provincial SOE procurement consolidating around direct OEM relationships that bypass distributor markups. Pricing pressure intensifies in the standard tier as polysilicon volatility exposes non-integrated assemblers to margin compression. State-owned manufacturing conglomerates exhibit lowest price sensitivity due to dual carbon compliance mandates, while fragmented residential demand remains most exposed to module cost fluctuations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from consolidated state-owned manufacturing conglomerates, displacing regional distributor networks that previously served fragmented facility-level procurement. Geographic supply concentration centers on China for wafer and cell production, with polysilicon feedstock drawing from domestic metallurgical-grade silicon smelters and limited Mongolian concentrate imports. Raw material dependencies include high-purity silicon metal, silver paste for cell metallization, and aluminum frames for module assembly. Single-source vulnerability in captive polysilicon supply chains exposes non-integrated developers to input cost spikes when metallurgical-grade benchmarks rise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's distributed solar market operates as a regulatory compounder where MEE dual carbon trajectory reporting mandates convert compliance pressure into sustained procurement pull across industrial manufacturing clusters.
For Market Incumbents: To counter procurement authority consolidation among state-owned manufacturing conglomerates, anchor defensive positioning through backward integration into captive polysilicon supply and GB certification threshold elevation that filters substandard module competition. Deepen channel control via direct OEM relationships with Hebei province's restructured SOE networks, while expanding cell-to-module capacity in Jiangsu and Zhejiang to sustain cost discipline across distributed project bids. For New Entrants and Emerging Players: County-level installer partnerships offer the most penetrable entry vector for bypassing saturated coastal markets and accessing central-western province manufacturing relocation corridors. Target Sichuan-Chongqing electronics manufacturing clusters where industrial transfer policy creates untapped rooftop inventory outside interconnection-constrained eastern networks. Lead with agrivoltaic dual-use land access frameworks that unlock previously restricted farmland for agricultural application deployments. For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists combining captive silicon supply with high-efficiency monocrystalline output and direct OEM channel penetration. Long-term viability over the projection horizon favors producers with backward integration into metallurgical-grade feedstock and MIIT GB certification compliance. Watch county-level grid absorption capacity expansion timelines as the primary inflection indicator for project pipeline velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polysilicon | Captive silicon supply insulates margin structures from metallurgical-grade price volatility. |
| GB Certification Threshold Elevation | MIIT efficiency mandates filter substandard module supply from grid-connected bid eligibility. |
| Direct OEM Relationship Cultivation | Hebei SOE restructuring centralizes procurement authority for subsidiary plant network access. |
| Agrivoltaic Dual-Use Land Access | Rural land policy reforms unlock previously restricted farmland for distributed array deployment. |
| Smart Inverter Platform Integration | Automated voltage regulation reduces O&M headcount for Guangdong refrigeration load facilities. |
Study Parameters
Bottom-up industrial facility modeling reconciled against top-down module supply tracking forms the analytical core of this study. Primary interviews with EPC contractors, county-level grid operators, SOE energy procurement directors, and MIIT certification auditors combined with secondary validation from NMPA electrochemical storage filings, provincial environmental audit disclosures, and customs module export records. Top-down triangulation against polysilicon production databases and inverter manufacturing registries ensures supply-side coverage matches demand-side facility pipeline tracking.
Input-output matrices map module efficiency tiers to end-use application segments across the projection horizon. Segmentation dimensions modeled include product type, application category, installation architecture, and end-user procurement authority structure. CAGRs derive from facility-level adoption velocity curves weighted against county-level grid absorption constraints and interconnection queue reforms. Forecast inputs incorporate time-of-use tariff spread evolution and battery storage attachment rate trajectories for commercial peak shaving economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polysilicon price volatility, county-level absorption capacity expansion delays, and MIIT GB certification mandate evolution. Forecasts reflect documented assumptions around dual carbon policy enforcement continuity and industrial transfer policy manufacturing relocation velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Vacuum Receiver Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
France Distributed Solar Power Generation Market
Solar Power Systems
Solar Power Meters Market
Solar Power Systems
Solar Flower Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
Global Photovoltaic Glass Market
Solar Power Systems
Chile Renewable Energy Market
Solar Power Systems
Solar Panel Laminator Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Solar Kiosk Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Saudi Arabia Solar Energy Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market