
 Global Photovoltaic Market | 2026-2036
Global Photovoltaic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photovoltaic Market Intelligence
The channel between component manufacturers and utility-scale project developers is narrowing as supply chains consolidate. First Solar Inc. leverages its unique Cadmium Telluride (CdTe) thin-film technology to secure a distinct market position, especially in the United States. LONGi Green Energy Technology Co. Ltd. dominates the monocrystalline silicon wafer and module space through massive manufacturing scale. Canadian Solar Inc. competes by offering a diversified portfolio of modules and integrated project development services.
Photovoltaic technology involves the direct conversion of sunlight into electricity using semiconductor materials. These systems are built from cells, often made of silicon doped to create a p-n junction, which exhibit the photovoltaic effect when exposed to photons. Monocrystalline silicon products command the market due to higher efficiency ratings, while the utility-scale application represents the largest volume segment. Thin-film technologies, including Cadmium Telluride, maintain a niche in specific environments and large-scale deployments where cost per watt is critical.
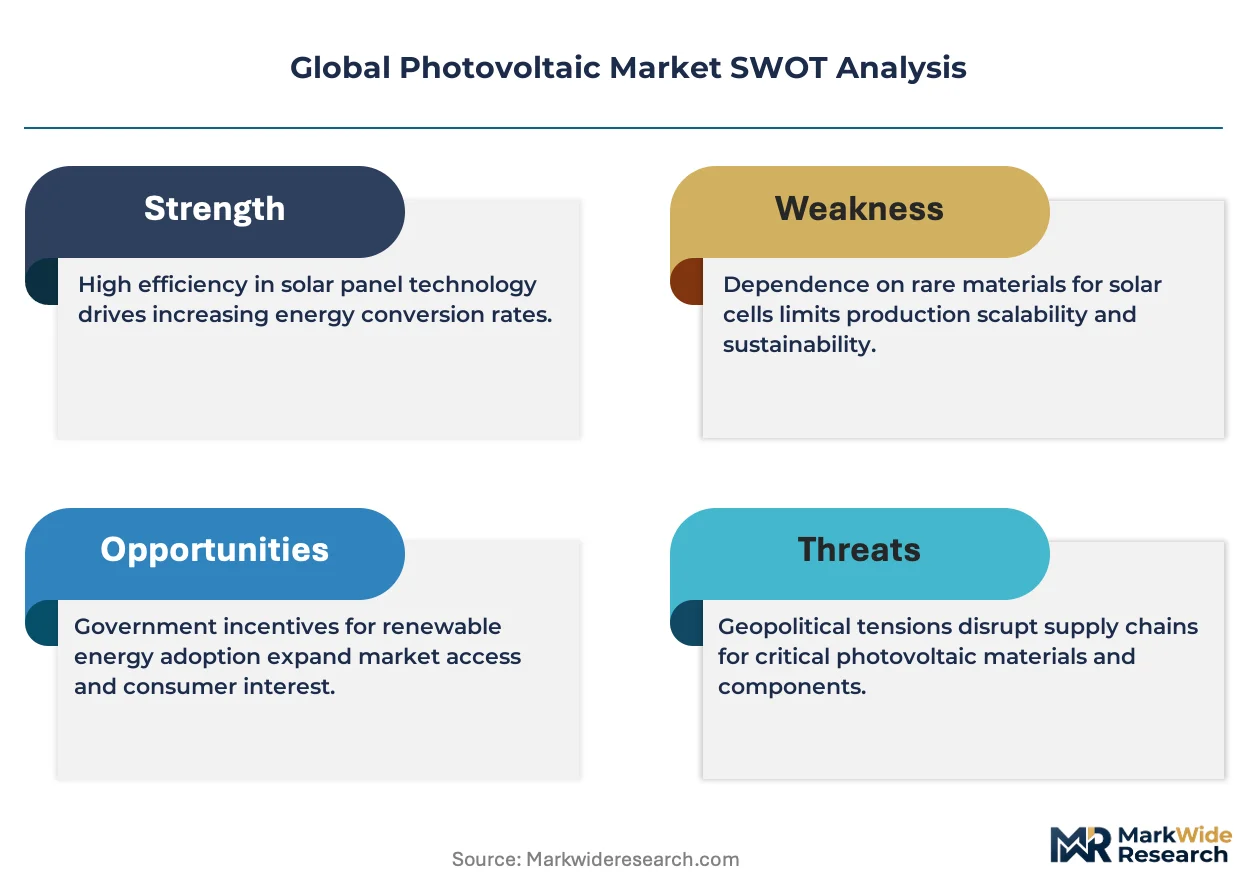
Governmental policies are central to market dynamics, with examples including the US Inflation Reduction Act (IRA), the EU Green Deal, and China's dual carbon goals. These frameworks influence manufacturing incentives, import tariffs, and deployment targets, directly shaping regional competitiveness and supply chain strategies. Stakeholders must now decide whether to onshore production to mitigate geopolitical risks or continue relying on highly concentrated Asian supply chains.
Market Dynamics
The central dynamic shaping the photovoltaic market is the strategic friction between policy-driven efforts to onshore manufacturing, exemplified by the US IRA, and the industry's deep-rooted reliance on China's highly concentrated and cost-efficient supply chain.
Growth Catalysts
- EU Green Deal Framework:This policy accelerates solar deployment through ambitious renewable energy targets and mandates, directly stimulating demand for photovoltaic installations across member states.
- Perovskite Technology Advancements:Innovations in perovskite solar cells promise higher conversion efficiencies and lower material costs, attracting significant research and development investment to overcome current stability issues.
- Utility-Scale Application Growth:The expansion of large-scale solar farms, driven by cost-competitiveness with fossil fuels, represents the largest volume segment for module consumption.
Market Restraints
- Polysilicon Price Volatility:As a primary raw material for silicon wafers, fluctuations in polysilicon pricing directly impact module manufacturing costs and create margin pressure for producers.
- Geopolitical Supply Risk:Extreme concentration of wafer, cell, and module manufacturing in China exposes the global supply chain to significant disruption from trade policy or regional lockdowns.
- Land Availability:Utility-scale solar projects require vast tracts of land, creating conflicts with agriculture and conservation, which can delay or block development.
Strategic Opportunities
- Building-Integrated Photovoltaics (BIPV):The integration of solar technology into building materials like glass and facades opens a new market for aesthetic and functional power generation in urban environments.
- New Market Development in Africa:Countries with high solar irradiance and underdeveloped grid infrastructure represent a significant opportunity for off-grid and utility-scale solar projects to meet energy demand.
- US Manufacturing Incentives:The Inflation Reduction Act provides substantial tax credits for domestic manufacturing of photovoltaic components, creating a business case for establishing production in the United States.
Industry Challenges
- Onshoring Execution Complexity:Relocating capital-intensive manufacturing from Asia to North America or Europe involves immense investment, long lead times, and developing a new skilled labor force.
- Grid Modernization Needs:Integrating large volumes of intermittent solar power into aging electrical grids requires significant upgrades to transmission infrastructure and energy storage systems to ensure stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photovoltaic Market |
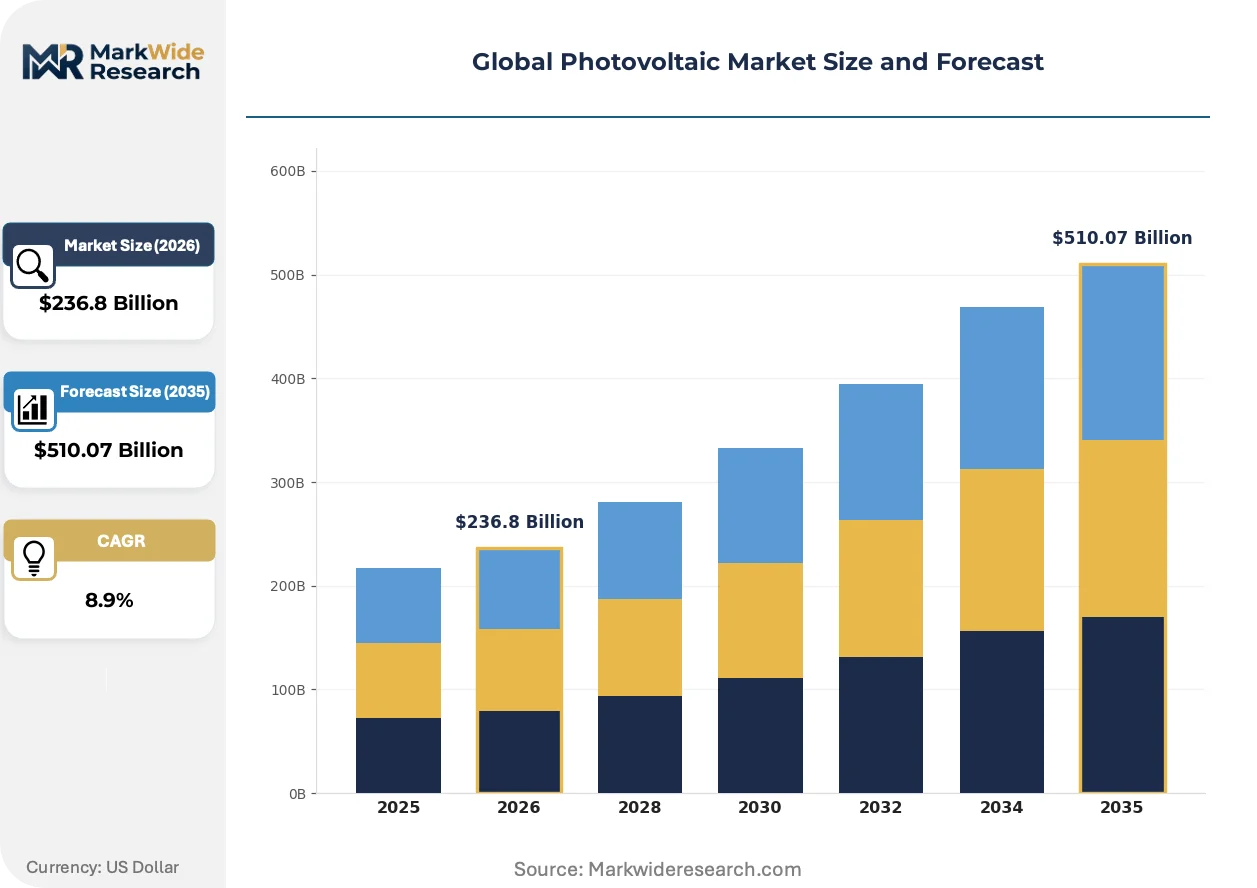
| Market Size in 2026 | $236.8 Billion |
| Market Size in 2035 | $510.07 Billion |
| CAGR (2026 – 2036) | 8.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial, Concentrated PV Technology: Silicon-Based, Cadmium Telluride, Copper Indium Gallium Selenide, Perovskite, Organic Photovoltaics Application: Residential, Commercial, Utility-Scale, Agricultural, Remote Power Supply End User: Energy Providers, Telecom Operators, Transportation Sector, Retail Chains, Public Infrastructure |
| Companies Covered | LONGi Green Energy Technology Co. Ltd, Trina Solar Co. Ltd, JinkoSolar Holding Co. Ltd, JA Solar Technology Co. Ltd, Tongwei Solar, First Solar Inc., Hanwha Q CELLS, Canadian Solar Inc., Astronergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photovoltaic Market Strategic Shifts & Innovations
Technological evolution and policy mandates are jointly pushing the photovoltaic industry toward higher conversion efficiencies and more resilient supply chain configurations. This shift prioritizes performance gains and de-risking procurement from geographically concentrated sources.
Perovskite-on-silicon tandem cells are engineered to capture a broader spectrum of light, surpassing the theoretical efficiency limits of conventional silicon-only cells. Premium residential and utility-scale developers are closely monitoring commercialization progress. The market for high-performance modules is migrating from single-junction silicon architectures toward these complex, multi-junction cell structures to maximize energy yield.
China’s dual carbon goals establish a national strategic directive for transitioning its energy system toward renewables. This policy framework sustains immense domestic demand for new solar installations, underpinning the scale of its manufacturing base. Consequently, Chinese producers of wafers, cells, and modules reinforce their global cost leadership and export competitiveness.
A notable shift in purchasing behavior involves utility-scale developers engaging in direct, multi-year supply agreements with module producers. This disintermediates traditional distribution channels and gives large buyers more control over technology roadmaps and price security. This trend is most visible in the United States and Australia, where project pipelines are large enough to support such direct partnerships.
Global Photovoltaic Market Segmentation
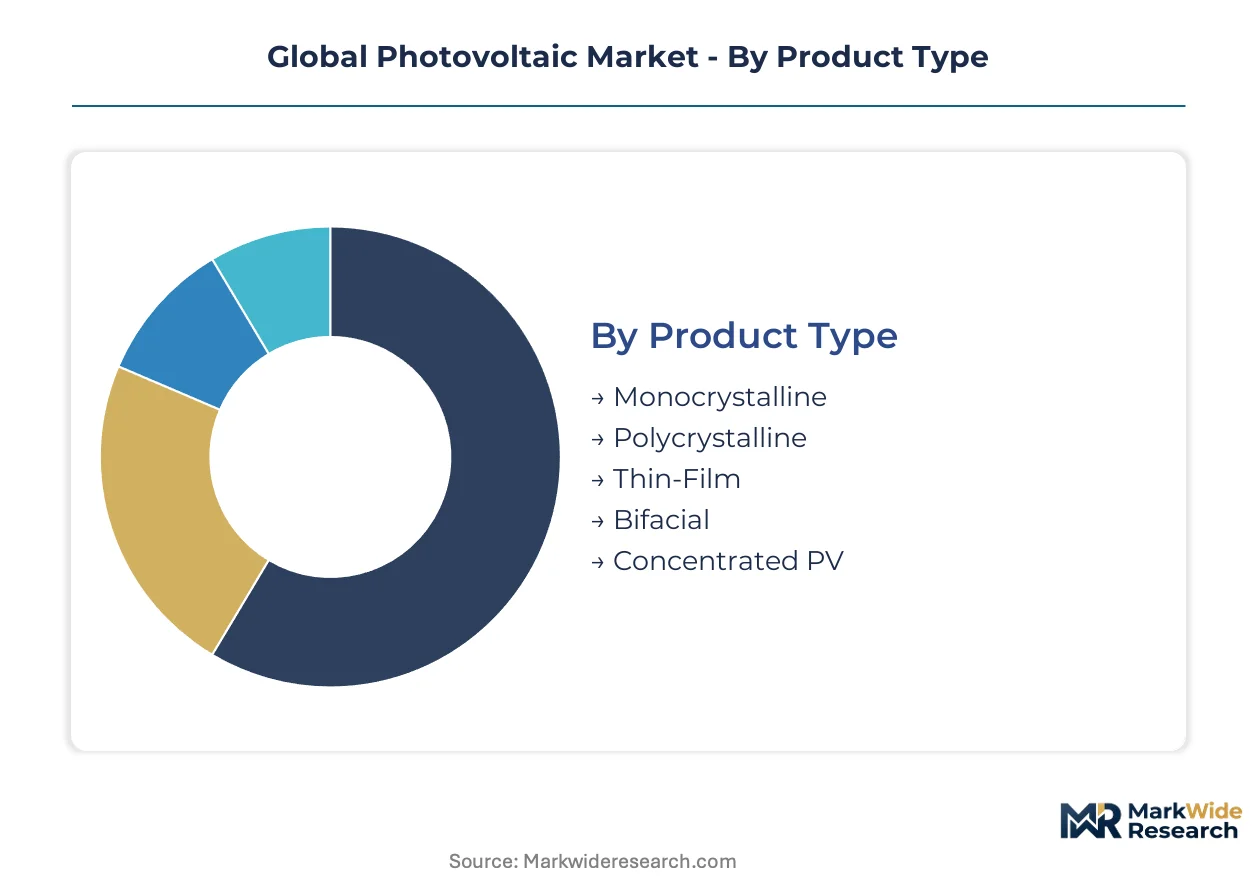
Understanding the Global Photovoltaic Market through segmentation clarifies the distinct technological preferences, application landscapes, and end-user demands shaping its evolution. This granular view enables stakeholders to pinpoint specific growth vectors and strategic opportunities within the broader energy transition.
Product Type:
The product type segmentation highlights the maturity spectrum of photovoltaic offerings, ranging from established silicon-based modules to emerging specialized designs.
- Monocrystalline:These modules feature a single, continuous crystal structure, providing high efficiency and a uniform appearance. Utility-scale projects in China drive demand due to superior energy yield and long-term performance.
- Thin-Film:Fabricated by depositing thin layers of photovoltaic material onto various substrates, these technologies often offer flexibility and lower manufacturing costs per watt. Large-scale deployments in the United States benefit from lower balance-of-system costs and performance in diffuse light conditions.
- Polycrystalline:Composed of multiple silicon crystals, these modules are a cost-effective alternative to monocrystalline, with slightly lower efficiency.
- Bifacial:Designed to capture sunlight from both the front and rear sides, bifacial modules increase overall energy generation, especially in high albedo environments.
- Concentrated PV:This technology uses lenses or mirrors to focus sunlight onto small, high-efficiency solar cells, primarily for utility-scale applications in high direct normal irradiance regions.
Monocrystalline modules handle the majority of throughput; Bifacial modules are the fastest mover on share.
Technology:
Technology segmentation reveals distinct supply chain concentrations, with silicon-based solutions dominating global production and specialized materials carving out niche markets.
- Silicon-Based:This category encompasses both monocrystalline and polycrystalline technologies, utilizing silicon wafers for photon-to-electron conversion. Utility-scale and residential installations globally depend on this established technology for reliable power output.
- Perovskite:Composed of hybrid organic-inorganic lead or tin halide-based materials, perovskite cells promise higher conversion efficiencies and lower material costs. Research and development in Japan and Europe focus on overcoming stability challenges for future commercialization.
- Cadmium Telluride:A thin-film semiconductor technology, Cadmium Telluride is cost-effective for large-scale projects and performs well in hot, humid climates.
- Copper Indium Gallium Selenide:This flexible thin-film technology offers high efficiency and is suitable for various applications, including building-integrated photovoltaics.
- Organic Photovoltaics:Utilizing carbon-based materials, organic photovoltaics offer flexibility, transparency, and lightweight properties for niche applications like consumer electronics and smart windows.
Silicon-Based technology maintains its market lead; Perovskite technology exhibits the steepest expansion trajectory.
Application:
Application segmentation clarifies the volume drivers across different deployment scales, from individual household systems to vast energy generation facilities.
- Utility-Scale:These are large ground-mounted or floating solar arrays designed to generate electricity for the grid, often spanning hundreds of acres. Energy providers in the United States and China prioritize these projects for grid decarbonization targets.
- Residential:Comprising rooftop installations on single-family homes or multi-dwelling units, residential solar provides distributed generation for homeowners. Homeowners in Germany and Australia seek energy independence and reduced electricity bills.
- Commercial:This segment includes rooftop or ground-mounted systems for businesses, industrial facilities, and public buildings, aiming to reduce operational costs and carbon footprints.
- Agricultural:Solar solutions in agriculture power irrigation systems, greenhouse climate control, and remote farm equipment, enhancing energy self-sufficiency.
- Remote Power Supply:Off-grid solar systems provide electricity to isolated communities, telecommunication towers, and industrial sites lacking grid connectivity.
Utility-Scale applications command the largest market share; Agricultural applications are gaining share fastest.
End User:
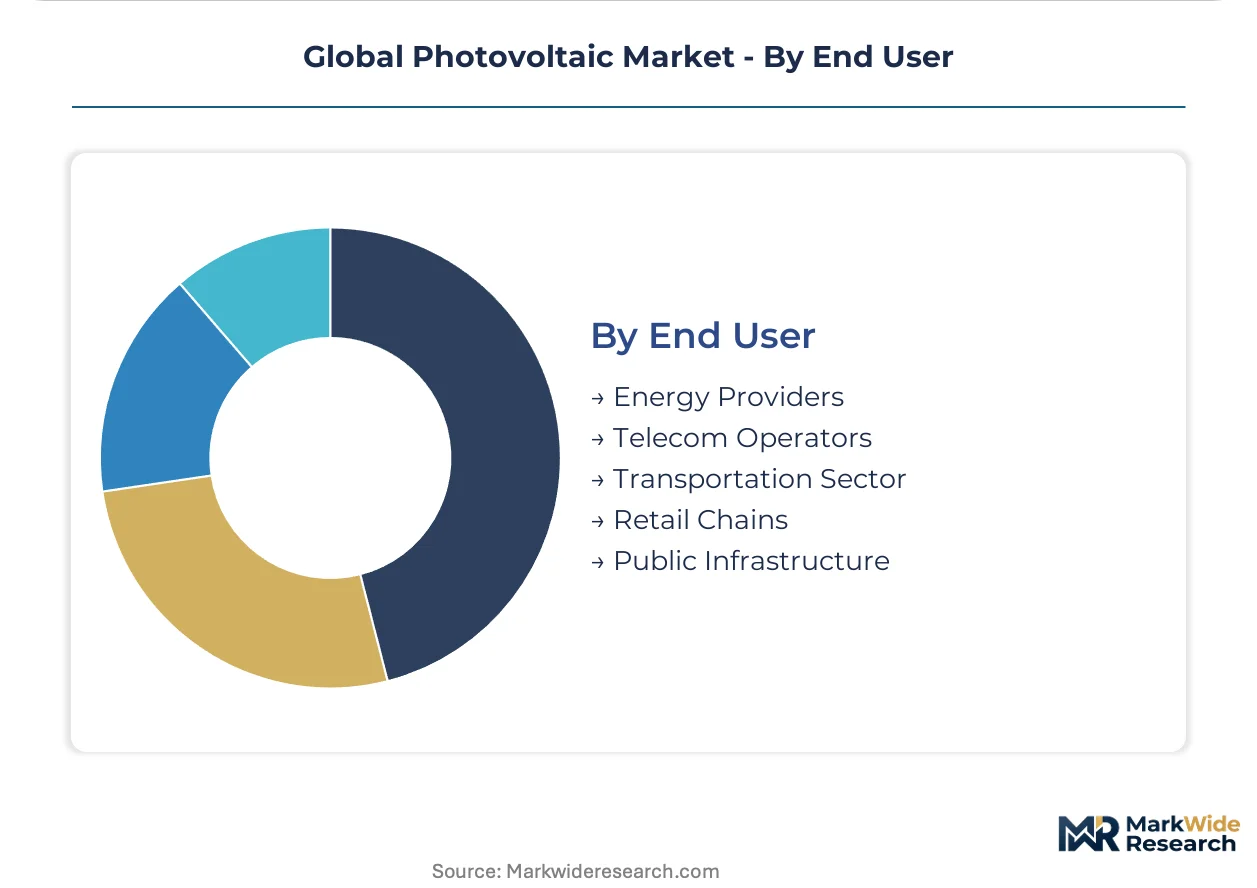
End-user segmentation differentiates customer types based on their primary operational needs and scale of energy consumption.
- Energy Providers:These entities, including utilities and independent power producers, integrate solar power into national grids, requiring large-scale generation and storage solutions. Utilities in India and Brazil invest in solar to meet growing electricity demand and renewable portfolio standards.
- Public Infrastructure:This segment involves government-led projects to power public buildings, streetlights, and transportation systems. Municipalities in France and Canada deploy solar for sustainability goals and reduced public utility costs.
- Telecom Operators:Solar power ensures reliable operation of remote cell towers, data centers, and network infrastructure, particularly in areas with unreliable grid access.
- Transportation Sector:Photovoltaic systems are increasingly used in electric vehicle charging stations, public transit facilities, and specialized vehicles.
- Retail Chains:Businesses in the retail sector deploy solar on store rooftops and distribution centers to power operations and enhance corporate sustainability profiles.
Energy Providers represent the dominant purchasing segment; Telecom Operators are expanding most quickly in their adoption of photovoltaic solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global electricity grid infrastructure underwrites diverse photovoltaic market developments across key geographies. Specific national policies and technological advancements drive installation rates and manufacturing investments. Utility-scale projects and distributed generation characterize regional growth patterns.
China
Massive domestic demand for solar power fuels its manufacturing base and technology leadership. China's dual carbon goals provide a strategic directive for renewable energy expansion and sustained investment. The Yangtze River Delta region continues to anchor vast production capacities for silicon wafers and modules, supporting global supply.
United States
Energy independence and decarbonization targets stimulate significant solar deployment across various scales. The US Inflation Reduction Act (IRA) offers substantial tax credits for domestic photovoltaic manufacturing and project development. Arizona and Texas are seeing increased investment in utility-scale solar farms, driven by federal incentives.
Germany
High residential and commercial solar adoption aims for greater energy autonomy and reduced carbon emissions. The EU Green Deal framework accelerates solar deployment through ambitious renewable energy targets and mandates. Bavaria and Baden-Württemberg lead in distributed generation installations, supported by strong local incentives.
India
Rapidly growing electricity demand drives large-scale solar projects and infrastructure development. India's PLI scheme incentivizes domestic manufacturing of solar cells and modules, reducing import reliance. Rajasthan and Gujarat are developing major solar parks to meet national energy needs and achieve renewable targets.
Australia
Abundant solar irradiance supports high rooftop solar penetration and utility-scale developments. The Australian Renewable Energy Agency (ARENA) funds innovative solar projects and research into new technologies. Queensland and New South Wales lead in both residential and utility-scale solar deployments, leveraging natural resources.
Global Photovoltaic Market Key Industry Players
On the supply side, the industry is highly concentrated, particularly in core manufacturing segments like wafers and cells. The market structure features vertically integrated giants, specialized component manufacturers focusing on niche technologies, and project developers. These archetypes often compete through aggressive capacity expansion and strategic partnerships to secure market share. Companies are increasingly focused on de-risking supply chains and enhancing technological differentiation to maintain competitiveness.
Scale-driven manufacturers, often based in Asia, anchor the high-volume segments of the market. LONGi Green Energy Technology Co. Ltd. exemplifies this approach, dominating monocrystalline silicon wafer and module production through massive scale. First Solar Inc., a US-based company, occupies a distinct position by leveraging its unique Cadmium Telluride thin-film technology, especially in the North American utility-scale sector. Canadian Solar Inc. represents a diversified player, offering a broad portfolio of modules alongside integrated project development services. These companies collectively shape global supply dynamics.
| Leading Market Players |
|---|
| LONGi Green Energy Technology Co. Ltd |
| Trina Solar Co. Ltd |
| JinkoSolar Holding Co. Ltd |
| JA Solar Technology Co. Ltd |
| Tongwei Solar |
| First Solar Inc. |
| Hanwha Q CELLS |
| Canadian Solar Inc. |
| Astronergy |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta region's immense production capacity for silicon wafers and modules directly influences global photovoltaic pricing power for downstream buyers. This concentration creates both cost efficiencies and potential vulnerabilities for international markets.
Pricing Analysis
Volume-discount tiering structures dominate procurement for large-scale photovoltaic projects, reflecting the commodity nature of standard modules. Price differentiation stems primarily from module efficiency ratings and specific technology types, such as Cadmium Telluride versus monocrystalline silicon. Pricing softness runs through the market, driven by persistent polysilicon price volatility and intense competition among Asian manufacturers. Utility-scale developers exhibit the highest price sensitivity due to project financing requirements, while residential homeowners prioritize long-term energy independence over marginal cost savings.
Supply Chain Analysis
Export-control regimes, particularly those influenced by US-China trade tensions, increasingly limit the free flow of photovoltaic components and raw materials. The global supply chain concentrates heavily in China, which supplies the majority of silicon wafers, cells, and modules. Raw material dependencies include polysilicon for silicon-based modules and specialized materials for thin-film technologies. Geopolitical supply risk remains a significant structural concern due to extreme manufacturing concentration. Downstream distribution runs through direct, multi-year supply agreements for utility-scale projects and traditional channels for residential and commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a cyclical recovery, primarily driven by aggressive global decarbonization targets and supportive policy frameworks like the EU Green Deal.
For Market Incumbents: Pre-empt competitive threats by investing in advanced manufacturing capabilities within key growth regions, such as the United States, leveraging incentives like the IRA. Secure long-term supply agreements for critical raw materials like polysilicon to mitigate price volatility and ensure production continuity. Develop next-generation perovskite-on-silicon tandem cells through focused R&D to maintain technology leadership against emerging players and enhance module efficiency.
For New Entrants and Emerging Players: Building-integrated photovoltaics (BIPV) in urban environments represent a growing niche for aesthetic and functional power generation. Off-grid solutions in African countries with high solar irradiance offer significant demand for reliable energy. Focus on integrated energy solutions for remote power supply or specialized BIPV applications, offering comprehensive design and installation services as a go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as an infrastructure development play because global energy transition mandates require massive solar capacity additions. Target specialized component manufacturers developing perovskite technology or project developers with strong utility-scale pipelines in incentivized geographies. Practitioners should monitor sustained policy support for renewables as a key inflection indicator for continued market expansion and investment viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in US/EU | Mitigates geopolitical supply risk and leverages IRA incentives for domestic manufacturing. |
| Perovskite R&D Investment | Targets higher conversion efficiencies and lower material costs for future module generations. |
| Multi-year Supply Agreements | Secures price stability and technology roadmaps for large utility-scale developers. |
| BIPV Product Development | Unlocks new market opportunities for aesthetic solar integration in urban areas. |
| Grid Modernization Advocacy | Supports integration of large solar volumes, ensuring grid stability for energy providers. |
Research Approach
A spread of perspectives from utility-scale project developers, module manufacturing executives, government policy advisors, and raw material suppliers converged on the working assumptions. This analysis integrates insights from primary interviews with industry stakeholders, validated against extensive secondary research. Secondary sources include International Energy Agency (IEA) reports, national energy statistics from EIA, trade association publications, and corporate financial filings, all triangulated using bottom-up and top-down approaches.
Demand-supply-balance modeling forms the core of the forecast framework, projecting market evolution across the analysis window. This approach systematically evaluates market size and growth, segmenting by product type, technology, application, end-user, and regional policy frameworks. Compound annual growth rates are derived from historical data analysis and projected market dynamics, incorporating key industry-specific inputs such as polysilicon pricing trends and national renewable energy deployment targets.
Practitioners should monitor shifts in geopolitical trade policies, accelerated perovskite technology commercialization, and grid infrastructure development pace for early signals of market revision. Forecasts inherently reflect assumptions documented at the time of publication regarding these critical factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
France Solar Energy Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
Solar Crimp Set Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
Solar PV Mounting Systems Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
GCC Solar Photovoltaic (PV) Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
US Residential Solar PV Market