
 Solar Concentrator Market | 2026-2036
Solar Concentrator Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Concentrator Market Outlook
Aftermarket service revenue for heliostat cleaning and mirror refurbishment is fragmenting across regional service networks rather than concentrating with original equipment providers. Abengoa Solar leverages its integrated project development model to capture recurring maintenance contracts across Spanish and Middle Eastern installations. SunPower Corporation anchors the high-efficiency photovoltaic concentrator segment through its differentiated gallium arsenide cell architecture. Suncore Photovoltaic Technology Co. Ltd. competes primarily on manufacturing scale, sustaining cost advantages in utility-scale dish Stirling deployments.
Solar concentrators are optical-thermal systems that employ mirrors or lenses to focus direct normal irradiance onto a small receiver area, achieving concentration ratios from 10x to over 1,000x depending on geometry and tracking precision; parabolic trough systems predominate in commercial operation due to mature single-axis tracking and proven heat transfer fluid integration with steam Rankine cycles. Parabolic trough technology occupies the largest installed base globally, though solar tower configurations with molten salt storage are recording the fastest capacity additions because their higher operating temperatures enable extended dispatch. Fresnel lens concentrators sustain niche traction in process heat applications below 300°C where linear geometry reduces structural steel requirements. Dish Stirling systems remain technically compelling for off-grid installations but face margin pressure from photovoltaic cost declines.
The US Federal Energy Regulatory Commission shapes market access through interconnection queue reform, while the EU F-Gas Regulation constrains heat transfer fluid selections for European trough installations. India's Central Electricity Authority mandates renewable purchase obligations that channel state-discom procurement toward solar thermal hybrids. Saudi Arabia's national renewable energy program and Morocco's MASEN procurement framework direct developer attention toward dispatchable concentrated solar power with integrated storage rather than intermittent photovoltaic alternatives.
Market Dynamics
The solar concentrator market is being fundamentally restructured by the shift toward dispatchable renewable generation, where molten salt storage integration transforms intermittent solar thermal output into schedulable baseload capacity prized by grid operators.
Growth Catalysts
- Saudi Arabia's National Renewable Energy Program:Procurement frameworks explicitly favor concentrated solar power with integrated storage, directing developer capital toward molten salt tower configurations over photovoltaic alternatives.
- Process heat decarbonization:Industrial facilities below 300°C are adopting linear Fresnel concentrators to displace natural gas in food processing and textile manufacturing.
- EU F-Gas Regulation phase-down:Heat transfer fluid restrictions on synthetic refrigerants are accelerating synthetic oil and molten salt adoption in European trough installations.
Market Restraints
- Silver and aluminum input volatility:Mirror substrate and reflective coating costs fluctuate with precious metals markets, compressing project margins during construction windows.
- Heliostat manufacturing concentration:Precision tracking drive assemblies rely on a limited supplier base in Germany and Spain, creating bottleneck risk for tower project timelines.
- Photovoltaic cost compression:Utility-scale silicon module pricing below $0.20 per watt displaces concentrator economics in non-dispatchable applications.
Strategic Opportunities
- Green hydrogen integration:Concentrator-generated steam is hybridizing with electrolyzer arrays in Morocco and Chile to produce export-oriented ammonia and synthetic fuels.
- India's CEA renewable purchase obligations:State discom procurement mandates channel capacity additions toward solar thermal hybrids with existing coal plant co-location.
- Aftermarket service unbundling:Regional mirror cleaning and receiver refurbishment networks are capturing recurring revenue streams previously held by original equipment providers.
Industry Challenges
- Receiver tube fabrication skill scarcity:Vacuum envelope sealing and selective coating deposition require specialized technician training that outpaces vocational program output.
- Interconnection queue reform complexity:FERC Order 2023 compliance timelines for transmission study standardization are extending project development cycles in US markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Concentrator Market |
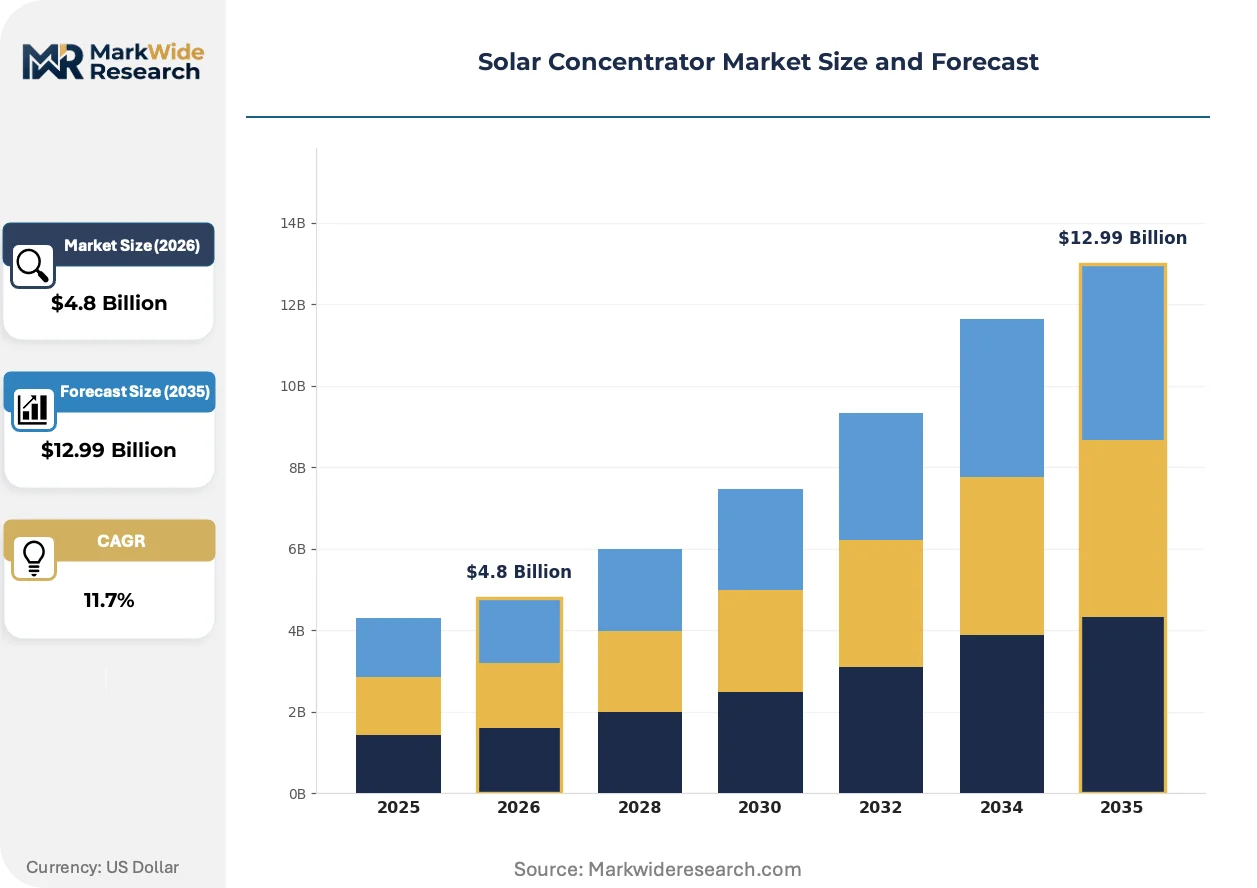
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Parabolic Trough, Solar Tower, Fresnel Lens, Dish Stirling Application: Power Generation, Desalination, Process Heat, Industrial Heating End User: Utilities, Commercial Buildings, Residential, Agriculture Installation Type: On-grid, Off-grid, Building-integrated, Ground-mounted |
| Companies Covered | SunPower Corporation, Suncore Photovoltaic Technology Co. Ltd., Solar Junction Corporation, Semprius Inc., Zytech Solar Pvt. Ltd., Abengoa Solar, Amonix, Inc., Isofoton S.A., BrightSource Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Concentrator Market Strategic Shifts
Concentrator technology is diverging along two paths: higher-temperature tower systems chasing industrial process heat and power block efficiency, while linear geometries optimize for cost-sensitive thermal applications below 400°C.
Advanced receiver designs incorporating solid particle and supercritical carbon dioxide heat transfer are hybridizing with conventional steam Rankine cycles, enabling tower operators to access both established turbine supply chains and next-generation efficiency gains. Saudi Aramco and ACWA Power are piloting these configurations in Neom. The technology is hybridizing project finance structures, blending development bank debt with corporate offtake agreements.
The EU F-Gas Regulation's hydrofluorocarbon phase-down is constraining heat transfer fluid selections for European trough installations, forcing operators toward synthetic thermal oils with lower vapor pressure but reduced maximum operating temperatures. Spanish and Italian developers are responding by accelerating molten salt direct receiver development to bypass organic fluid limitations entirely. Southern European project pipelines are prioritizing tower configurations as a result.
Industrial offtakers are unbundling engineering-procurement-construction contracts from long-term operations and maintenance agreements, fragmenting vendor relationships that previously ran twenty-five years. Chemical and mining sector buyers in Chile and South Africa are driving this disaggregation, seeking competitive bidding on mirror washing, tracking calibration, and receiver replacement cycles. This restructuring is most visible in Atacama Desert installations where dust accumulation rates demand specialized regional service expertise.
Solar Concentrator Market Segmentation
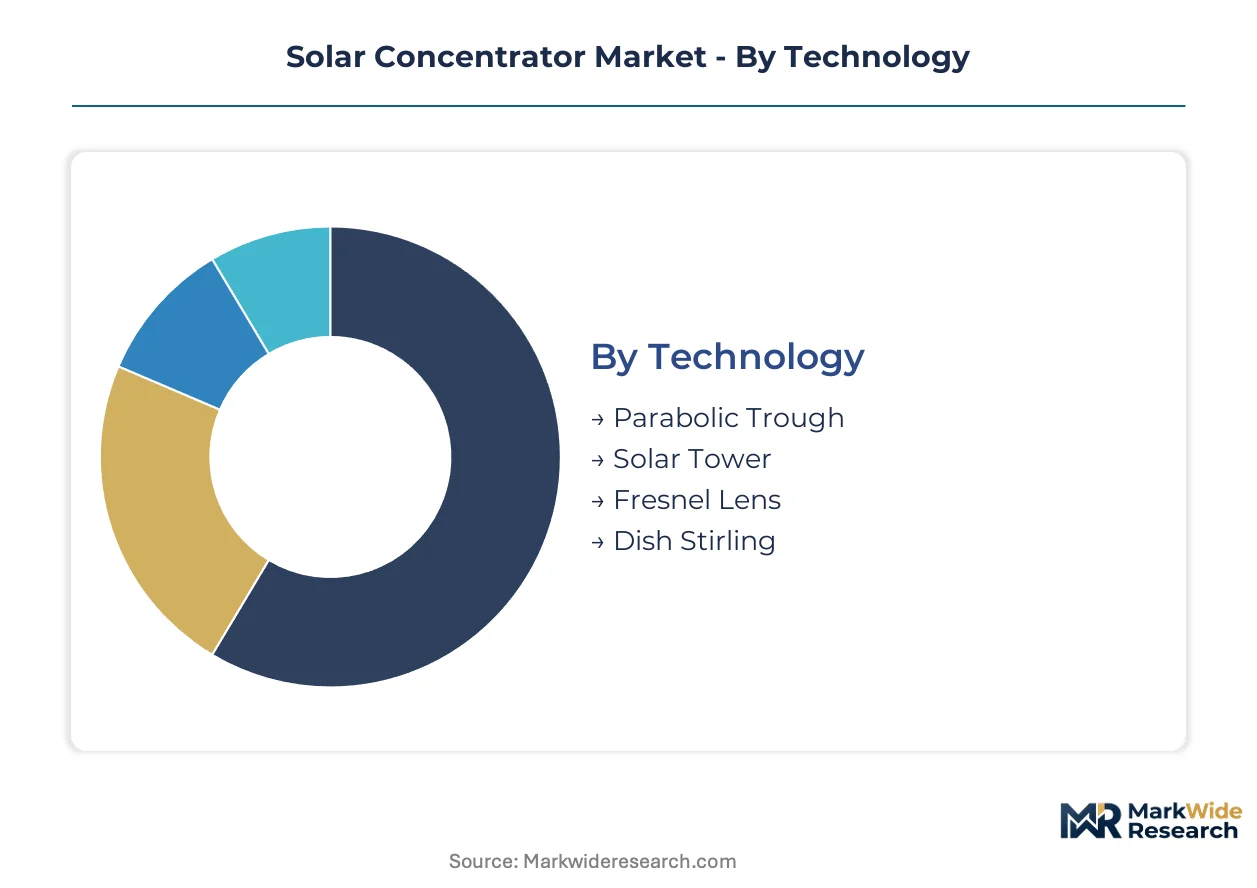
Technology choices in solar concentrators lock in decades of operational characteristics, from heat transfer fluid compatibility to dispatchability profiles. Application segmentation reveals where molten salt storage economics outrun photovoltaic alternatives. End user and installation type splits expose divergent financing structures and regulatory pathways across deployment contexts.
Technology:
Cost tier differentiation across concentrator geometries determines project bankability and offtake contract structures.
- Parabolic Trough:Single-axis tracking systems using synthetic oil or molten salt heat transfer fluids achieve concentration ratios near 80x. Mature supply chains in Spain and the United States sustain deployment volumes for utility-scale steam Rankine integration. Trough configurations command the largest installed base globally due to proven operational track records and standardized receiver tube manufacturing.
- Solar Tower:Dual-axis heliostat fields concentrate irradiance onto central receivers, enabling operating temperatures above 565°C with molten salt storage. Saudi Arabia's Neom project and Morocco's MASEN pipeline anchor demand for dispatchable tower configurations with 15-hour storage duration. The steepest capacity additions are running through tower systems as developers chase higher thermodynamic efficiency and schedulable output.
- Fresnel Lens:Fixed receiver tubes with tracking mirror arrays reduce structural steel requirements by 30% versus trough equivalents, optimizing for process heat applications below 300°C.
- Dish Stirling:Parabolic dish concentrators with Stirling engine receivers achieve the highest solar-to-electric conversion efficiency but face margin compression from silicon photovoltaic cost declines in distributed applications.
Parabolic trough commands the established base. The steepest expansion runs through solar tower.
Application:
Application segmentation tracks where thermal storage integration transforms intermittent solar harvest into firm capacity valued by grid operators and industrial offtakers.
- Power Generation:Utility-scale concentrated solar power plants with molten salt storage deliver dispatchable electricity to national grids and merchant markets. ACWA Power's procurement pipeline in Saudi Arabia and MASEN's Noor Ouarzazate complex in Morocco exemplify developer preference for tower-based power generation with integrated storage over photovoltaic alternatives.
- Process Heat:Linear Fresnel systems supplying thermal energy below 300°C displace natural gas in food processing, textile manufacturing, and chemical production. The EU F-Gas Regulation's hydrofluorocarbon phase-down is accelerating synthetic oil and molten salt adoption in European process heat installations.
- Desalination:Multi-effect distillation plants paired with concentrator-generated steam address water scarcity in the Middle East and North Africa.
- Industrial Heating:High-temperature tower systems supply heat for cement, steel, and mining operations above 400°C.
Power generation captures the dominant revenue share. The most rapid demand acceleration is appearing in process heat decarbonization.
End User:
Customer type determines project scale, financing structures, and regulatory compliance burdens across deployment scenarios.
- Utilities:State-owned and independent power producers procure multi-hundred-megawatt installations with 25-year power purchase agreements. Saudi Arabia's National Renewable Energy Program and India's Central Electricity Authority renewable purchase obligations channel utility capital toward dispatchable solar thermal with storage integration.
- Commercial Buildings:District cooling and heating networks in the Middle East adopt linear concentrators for absorption chiller integration. Dubai and Abu Dhabi building codes increasingly mandate renewable thermal contributions for large commercial developments.
- Residential:Distributed rooftop concentrators remain niche due to tracking complexity and maintenance requirements.
- Agriculture:Greenhouse heating and crop drying applications in Spain and Italy employ small-scale Fresnel arrays.
Utilities anchor the capital deployment. Commercial buildings are gaining share fastest as district energy mandates spread.
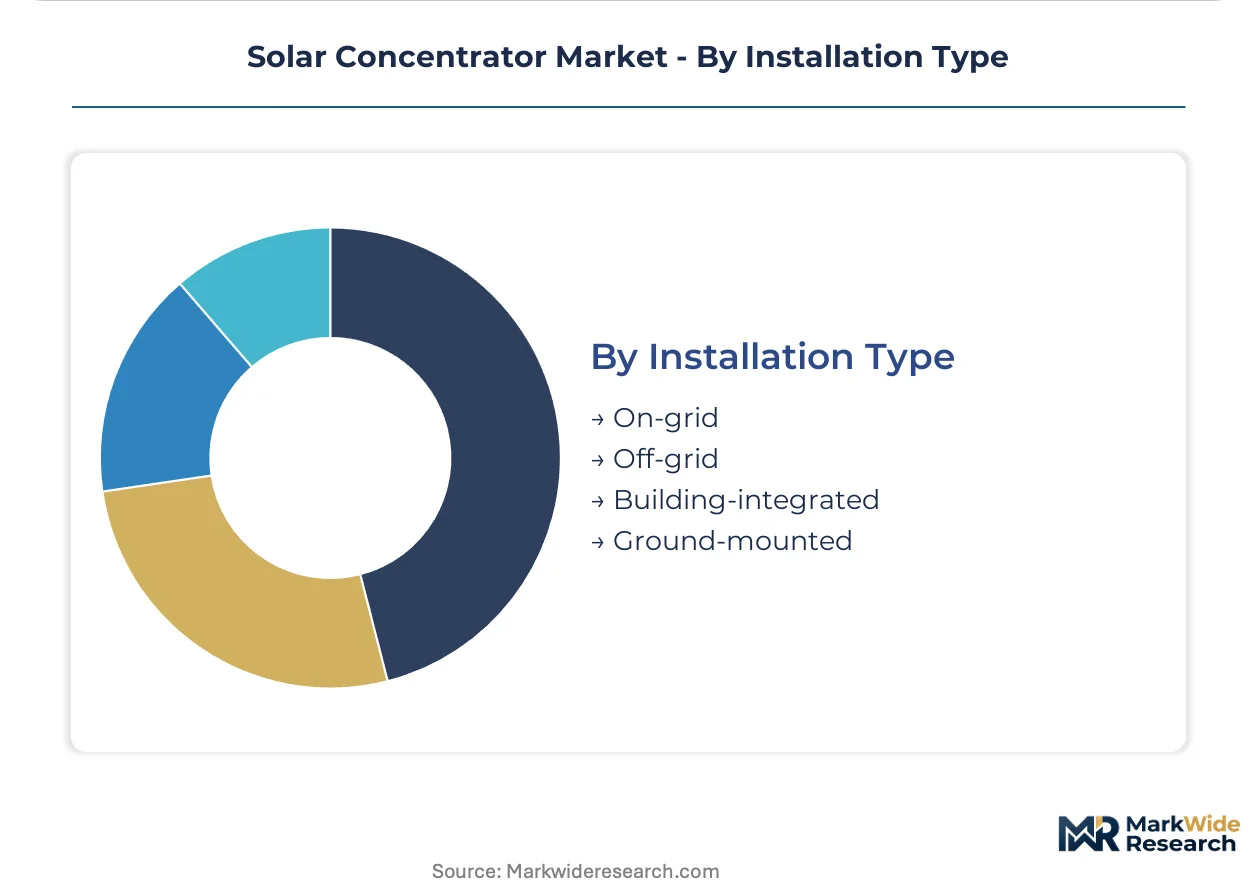
Installation Type:
Grid connection status and mounting configuration dictate interconnection queue positioning, land use permitting, and balance-of-system costs.
- On-grid:Transmission-connected installations access wholesale electricity markets and capacity payment mechanisms. FERC interconnection queue reform in the United States and EU network codes shape project development timelines for on-grid concentrator deployments.
- Off-grid:Remote mining and industrial facilities in Chile's Atacama Desert and South African platinum belts deploy dish Stirling and small tower systems where transmission extension is uneconomical.
- Ground-mounted:Utility-scale heliostat and trough fields occupy desert and arid land with high direct normal irradiance.
- Building-integrated:Rooftop and facade-mounted concentrators serve niche architectural applications with limited commercial traction.
Ground-mounted configurations hold the dominant installed capacity. Off-grid installations are expanding most quickly in remote industrial corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Saudi Arabia and Morocco exhibit low price elasticity, prioritizing dispatchability and storage integration over upfront capital minimization. Indian and Chilean procurement shows higher sensitivity, where solar thermal hybrids must compete against plummeting photovoltaic tariffs. European demand sits between these poles, with industrial process heat applications accepting moderate premiums for decarbonization compliance.
Saudi Arabia
ACWA Power's procurement pipeline and the King Abdulaziz City for Science and Technology anchor domestic deployment of molten salt tower configurations. The National Renewable Energy Program explicitly favors concentrated solar power with integrated storage, directing developer capital away from photovoltaic alternatives. The NEOM project in the northwest region is piloting advanced receiver designs incorporating solid particle heat transfer.
Morocco
MASEN's Noor Ouarzazate complex exemplifies developer preference for dispatchable tower-based power generation with extended storage duration. The country's procurement framework channels international development finance toward schedulable renewable capacity. The Ouarzazate solar cluster in the Drâa-Tafilalet region hosts the world's largest concentrated solar power complex with molten salt storage integration.
United States
FERC Order 2023 compliance timelines for transmission study standardization are extending project development cycles for on-grid concentrator deployments. The Federal Energy Regulatory Commission shapes market access through interconnection queue reform, while southwestern states with high direct normal irradiance attract tower project proposals. California's Imperial Valley and Nevada's Crescent Dunes region concentrate operational installations and pilot demonstrations.
India
The Central Electricity Authority mandates renewable purchase obligations that channel state-discom procurement toward solar thermal hybrids with existing coal plant co-location. State-owned power producers face regulatory pressure to procure dispatchable renewable capacity, creating a protected market segment for concentrator technology. Rajasthan and Gujarat host the majority of project pipelines, with industrial corridors in these states driving hybrid configuration adoption.
Chile
Remote mining facilities in the Atacama Desert deploy dish Stirling and small tower systems where transmission extension is uneconomical, accepting premium pricing for energy security. Chemical and mining sector buyers are unbundling engineering-procurement-construction contracts from long-term operations agreements, fragmenting vendor relationships. The Atacama Desert installations concentrate demand for specialized regional mirror cleaning and tracking calibration services due to extreme dust accumulation rates.
Solar Concentrator Market Competitive Environment
Capability concentration sits with integrated project developers possessing proprietary receiver technology; scale advantage sits with manufacturing specialists serving utility-scale deployments. The market structures around a tiered vendor base where technology licensors, engineering-procurement-construction contractors, and component fabricators occupy distinct profit pools. Two strategic archetypes dominate: vertically integrated developers capturing recurring maintenance contracts, and pure-play manufacturers competing on heliostat or trough component cost curves. Competitive moves center on backward integration into receiver tube fabrication and geographic expansion into Middle Eastern and North African project pipelines.
Among Spain-based integrated developers, Abengoa Solar exemplifies the project development archetype with recurring maintenance contract capture. SunPower Corporation and Suncore Photovoltaic Technology Co. Ltd. occupy positions on the technology differentiation vector, representing contrasting approaches to concentrator cell architecture and manufacturing scale respectively. These three anchors illustrate how competitive positioning splits between integrated service providers and specialized component suppliers across distinct regional markets.
| Leading Market Players |
|---|
| SunPower Corporation |
| Suncore Photovoltaic Technology Co. Ltd. |
| Solar Junction Corporation |
| Semprius Inc. |
| Zytech Solar Pvt. Ltd. |
| Abengoa Solar |
| Amonix, Inc. |
| Isofoton S.A. |
| BrightSource Energy |
| Others |
Value Chain & Pricing Dynamics
The Red Sea corridor freight cost dynamics concentrate supply chain leverage with German and Spanish heliostat drive assembly manufacturers, feeding downstream price differentiation between integrated tower developers and component-only trough suppliers serving Middle Eastern and North African project pipelines.
Pricing Analysis
Aftermarket service contracts for heliostat cleaning and receiver refurbishment drive lifetime value capture, with recurring revenue streams unbundling from original equipment providers to regional specialists. Three-tier pricing structure across premium molten salt tower configurations, standard parabolic trough installations, and economy Fresnel process heat systems reflects concentration ratio performance and storage duration. Cost compression in photovoltaic modules is forcing concentrator developers toward dispatchability premiums and industrial offtake contracts. Utility-scale power purchasers in Saudi Arabia and Morocco show lowest price sensitivity, prioritizing schedulable capacity, while Indian state discoms and Chilean mining operators exhibit highest sensitivity to upfront capital minimization.
Supply Chain Analysis
Silver nitrate and aluminum ingot feedstock sourcing draws from Mexican mining operations, Chinese smelting capacity, and German precision coating deposition equipment. Mirror substrate fabrication rests on Japanese float glass technology and Spanish selective coating application lines. Supply chain risk centers on single-source vulnerability for vacuum receiver tube sealing equipment from Italian specialists. Distribution runs through engineering-procurement-construction contractors with captive installation crews in Saudi Arabia, Morocco, and the southwestern United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation accelerates as industrial offtakers unbundle twenty-five-year vendor relationships, creating specialized niches for regional mirror cleaning networks and receiver refurbishment specialists across high-dust environments.
For Market Incumbents: Build captive maintenance contract moats by acquiring regional service providers in the Atacama Desert and Rajasthan industrial corridors before photovoltaic cost compression displaces non-dispatchable concentrator applications. Secure backward integration into receiver tube selective coating deposition to bypass Italian equipment bottlenecks. Anchor procurement relationships with ACWA Power and MASEN through integrated storage offerings that silicon modules cannot replicate. For New Entrants and Emerging Players: Build out process heat decarbonization specialization in European food processing and textile manufacturing below 300°C, where Fresnel geometry cost advantages outrun photovoltaic thermal hybrid economics. Target India's Central Electricity Authority renewable purchase obligation compliance segment with coal plant co-location configurations. Lead with engineering-procurement-construction unbundling to capture operations and maintenance contracts previously held by integrated developers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors component specialists with manufacturing scale over pure-play project developers exposed to interconnection queue delays. Concentrator technology exhibits viable long-term demand anchored in dispatchability premiums and industrial process heat applications where storage integration creates irreplaceable value. Watch FERC Order 2023 compliance timelines and EU F-Gas Regulation enforcement intensity as inflection signals for North American and European deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Molten Salt Storage Integration | Transforms intermittent output into schedulable baseload capacity prized by Saudi Arabia's National Renewable Energy Program. |
| Regional Service Network Acquisition | Captures recurring mirror cleaning revenue in Atacama Desert installations with extreme dust accumulation rates. |
| Receiver Tube Fabrication Backward Integration | Bypasses Italian vacuum envelope sealing equipment bottlenecks constraining tower project timelines. |
| Process Heat Decarbonization Specialization | Displaces natural gas in European food processing installations constrained by EU F-Gas Regulation phase-down. |
| Green Hydrogen Electrolyzer Hybridization | Links concentrator-generated steam to ammonia export projects in Morocco and Chile. |
Study Parameters
Desk research of FERC interconnection queue filings, IEA technology roadmaps, and MASEN procurement documentation preceded structured interviews with utility planning officers, concentrated solar power project developers, EPC contractors, and aftermarket service network operators. Secondary validation drew from EIA generation capacity databases, EU F-Gas Regulation impact assessments, and customs records of heliostat drive assembly trade flows. Bottom-up project pipeline aggregation was cross-checked against top-down national renewable energy program targets to establish analytical triangulation.
Fixed assumptions across the projection horizon held direct normal irradiance resource availability, molten salt storage cost curves, and photovoltaic module pricing trajectories at central-case values while varying interconnection queue reform implementation speed, EU F-Gas Regulation enforcement intensity, and industrial offtake contract unbundling rates. Segmentation modeling tracked technology geometry, application temperature tier, end-user type, and grid connection status. CAGRs were derived from capacity addition run-rates through project finance commitment tracking and development bank disbursement patterns.
Stress conditions across silver and aluminum input volatility, heliostat manufacturing concentration, and FERC Order 2023 compliance timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding dispatchability premium persistence and industrial process heat regulatory compliance trajectories. Cross-checking against IEA renewable energy auction result databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Full-Cell Solar Module Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Solar Appliances Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Solar Rooftop Sales Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
India Rooftop Solar Market
Solar Power Systems
Parabolic Solar Cookers Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market