
 Global Photovoltaic Glass Market | 2026-2036
Global Photovoltaic Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Global Photovoltaic Glass Market Outlook
Project finance and green bond structures is tilting competitive dynamics toward capital-intensive manufacturers with balance sheet depth. Xinyi Solar Holdings Ltd. leverages integrated float-glass-to-module supply chains across Southeast Asian production bases. Flat Glass Group Co., Ltd anchors domestic capacity expansion through captive raw material sourcing. Saint-Gobain differentiates via European technical glass heritage adapted to photovoltaic transmission specifications.
Photovoltaic glass is a soda-lime silica glass engineered with iron content below 0.05% to maximize solar transmittance above 91%, produced through float-line processes with online chemical vapor deposition of anti-reflective coatings. Its primary purpose is to protect semiconductor junctions while minimizing photon loss in crystalline silicon and thin-film modules. Anti-reflective coated glass leads product type margins due to coating equipment intensity and performance premiums for bifacial applications. Thin-film technology segments compete on weight advantages in building integrated photovoltaics where structural load limits constrain conventional glass thickness. Bifacial technology segments sustain the fastest expansion as rear-side gain requirements push manufacturers toward double-sided coated, high-transmission substrates.
FDA, EPA, and OSHA frameworks govern occupational exposure limits in US manufacturing facilities producing photovoltaic glass, while REACH and RoHS constrain heavy metal content in European-imported coatings. China's GB standards and dual carbon goals enforce energy consumption caps on float glass furnaces, directly constraining capacity additions. India's BIS certification mandates mechanical load testing for imported solar glass under its renewable energy procurement rules. Stakeholders must monitor how carbon border adjustment mechanisms reshape cost competitiveness between Chinese float-glass exporters and regional manufacturing investments.
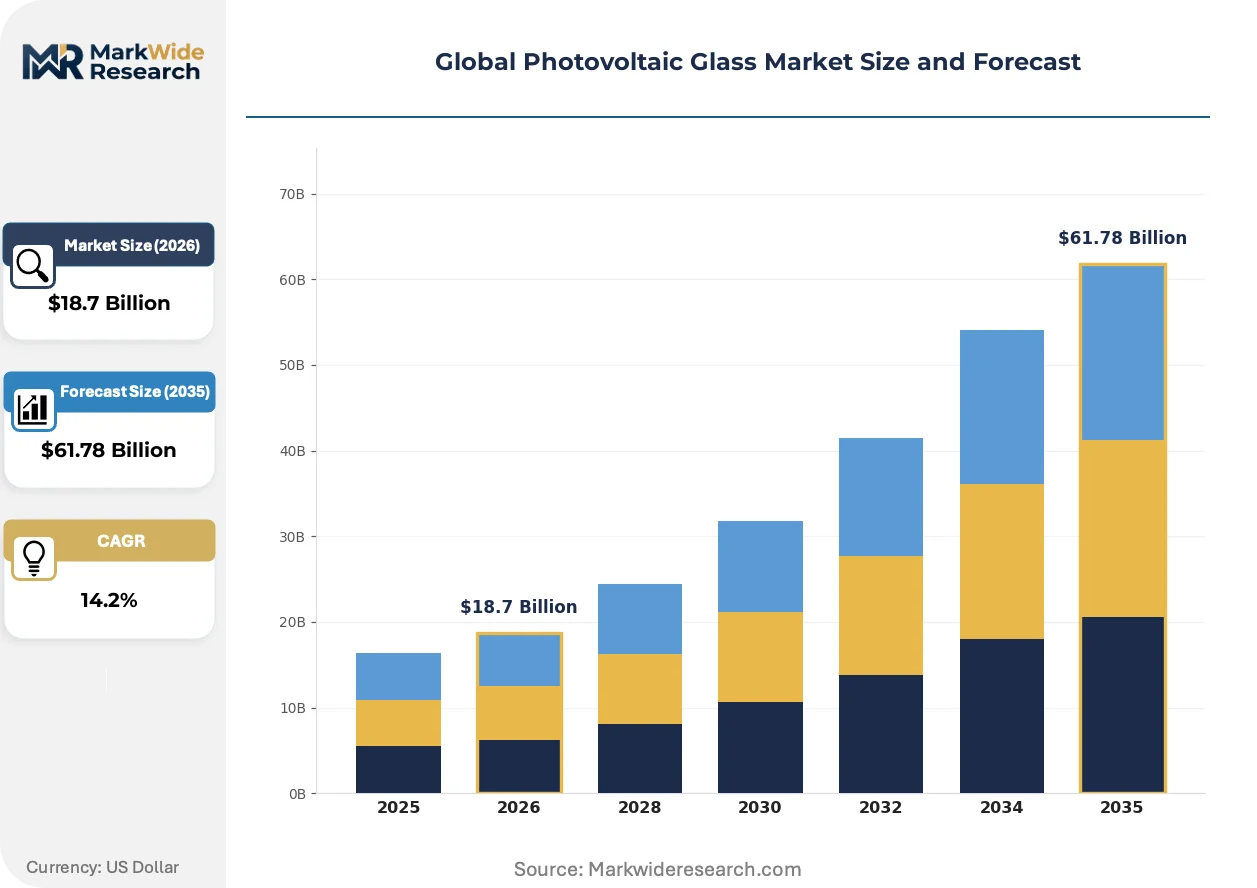
Market Dynamics
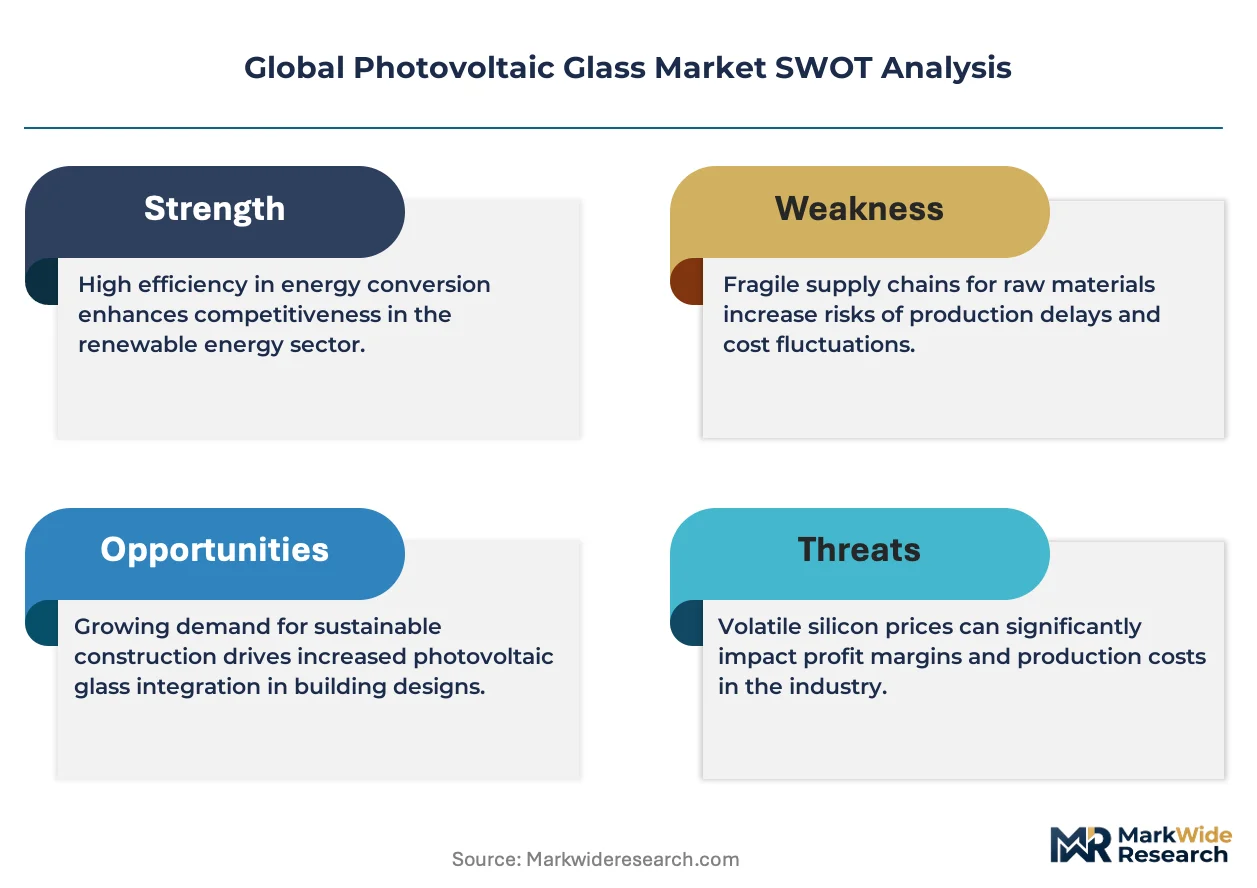
Bifacial module architecture is compressing supply chains toward specialized high-transmission substrates, while China's dual carbon goals constrain float-glass furnace expansions and concentrate procurement power among integrated manufacturers with captive coating capabilities.
Growth Catalysts
- Feed-in tariff tightening in India:Utility-scale solar developers accelerate procurement of anti-reflective coated glass as renewable purchase obligations harden procurement specifications.
- Bifacial rear-side gain requirements:N-type cell production lines demand double-sided coated substrates with iron content below 0.05%, pulling capacity toward specialized float-line retrofits.
- Carbon border adjustment mechanisms:European importers face escalating compliance costs on Chinese float-glass, redirecting investment toward Southeast Asian manufacturing bases with lower embodied carbon profiles.
Market Restraints
- High-purity silica sand concentration:Premium low-iron feedstock deposits cluster in specific coastal regions, exposing margins to bulk shipping rate volatility and geological depletion curves.
- Float-glass furnace energy intensity:Natural gas and electricity account for majority of production cost, with China's GB standards enforcing consumption caps that freeze capacity additions.
- Thin-film weight advantage in BIPV:Cadmium telluride and CIGS technologies compete on structural load limits where conventional glass thickness exceeds building code tolerances.
Strategic Opportunities
- Saudi Arabia's renewable procurement pipeline:Giga-scale solar installations under Vision 2030 create demand for high-transmission glass with desert abrasion resistance specifications.
- Building-integrated photovoltaics in urban cores:Façade-integrated modules require curved and patterned glass variants that command coating equipment premiums.
- Green bond structures:Project finance vehicles favor manufacturers with verified Scope 3 emissions data, advantaging integrated float-glass-to-module supply chains.
Industry Challenges
- CVD coating technician scarcity:Online chemical vapor deposition requires specialized furnace operators with semiconductor process experience, constraining coating line ramp speeds.
- BIS mechanical load certification timelines:India's mandatory testing for imported solar glass extends procurement cycles by four to six months, disrupting just-in-sequence module assembly.
- Intellectual property fragmentation in AR coating chemistries:Sol-gel and plasma-enhanced deposition patents span multiple holders, complicating licensing for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Photovoltaic Glass Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Reflective Coated Glass, Tempered Glass, Backsheet Glass, Laminated Glass End User: Residential Installations, Commercial Installations, Utility Scale Projects, Solar Farms Application: Building Integrated Photovoltaics, Solar Panels, Concentrated Solar Power, Off-Grid Systems Technology: C-Si Technology, Thin-Film Technology, Bifacial Technology, Multi-Junction Technology |
| Companies Covered | Xinyi Solar Holdings Ltd., Flat Glass Group Co., Ltd, IRICO Group New Energy Co., Ltd., AGC Inc., Saint-Gobain, CSG Holding Co. Ltd., NSG Pilkington, Borosil Renewables, Taiwan Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Photovoltaic Glass Market Strategic Shifts
Coating chemistry and deposition methods are diverging sharply as bifacial modules demand rear-side performance parity with front-side transmission, while furnace decarbonization pressures force process innovation.
Anti-reflective coating technology is migrating from single-layer sol-gel formulations toward multi-layer nanostructured surfaces. European module assemblers now specify double-sided coatings with hydrophobic top layers for soiling resistance. This migration from legacy coating architectures is compressing equipment supplier margins while concentrating procurement among furnace operators with in-house CVD capabilities.
China's dual carbon goals enforce hard energy consumption caps on float-glass furnace operations. GB standards now mandate specific thermal efficiency thresholds that block conventional natural gas furnace expansions. Domestic manufacturers respond by piloting hydrogen-blended combustion and electric melting technologies, though these remain capital-intensive at commercial scale.
Utility procurement committees now embed lifecycle carbon accounting into glass supplier scorecards. Developers in the Middle East and India weight embodied emissions alongside unit pricing, displacing spot-market purchasing with multi-year offtake agreements tied to verified Scope 3 data. This behavioral shift is most visible in Saudi Arabia's renewable energy project authority auctions, where sustainability-linked financing terms favor low-carbon glass sourcing.
Global Photovoltaic Glass Market Segmentation
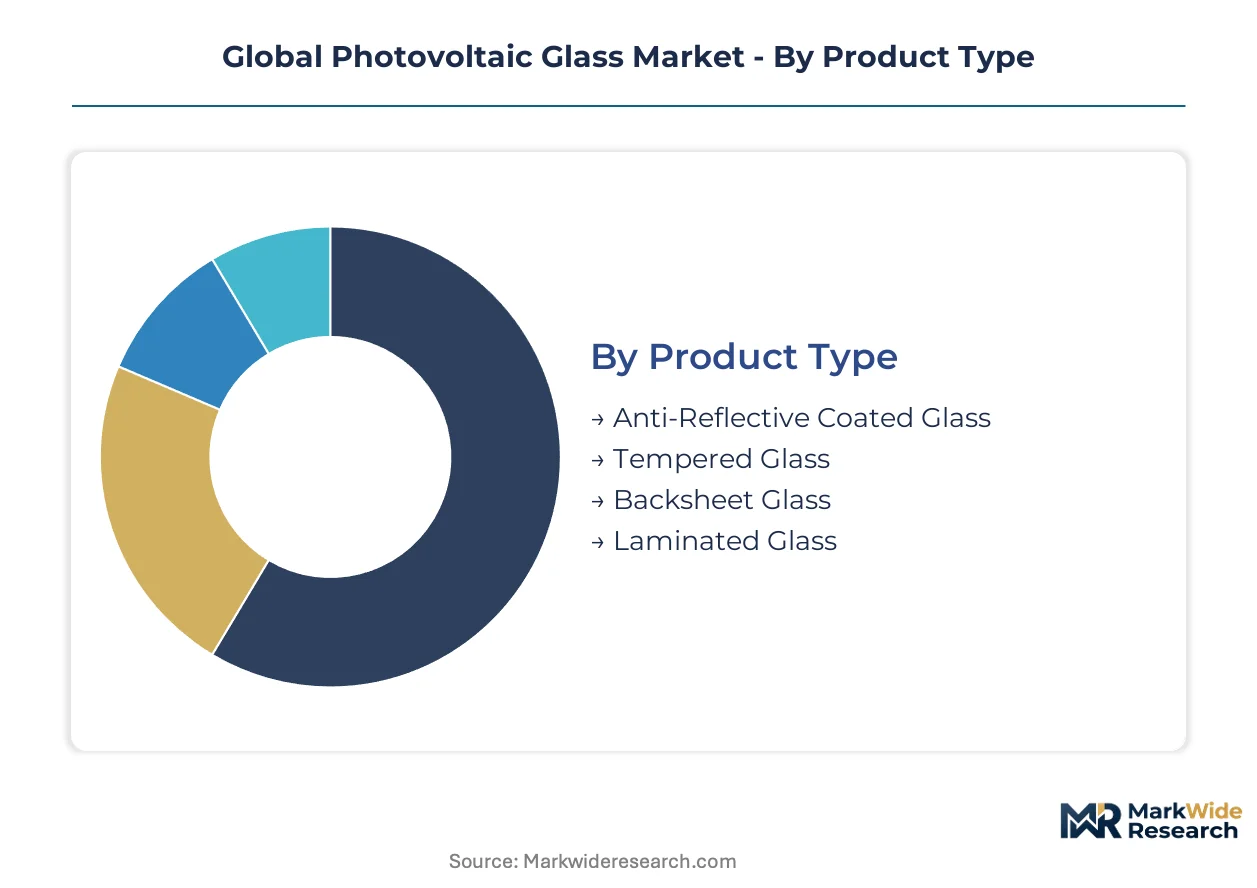
Photovoltaic glass segmentation reveals how coating chemistry, installation scale, and cell architecture pull demand toward specialized substrate specifications. Manufacturers configure float-line investments differently depending on which segment combination commands procurement priority in a given geography.
Product Type:
Mature float-glass processes dominate commodity segments while emerging coating technologies concentrate margins in performance tiers.
- Anti-Reflective Coated Glass:Multi-layer nanostructured surfaces deposited via online chemical vapor deposition push solar transmittance above 91% for crystalline silicon modules. Utility-scale developers in India specify hydrophobic top layers for soiling resistance under renewable purchase obligations. N-type cell production lines in China's manufacturing clusters demand iron content below 0.05% to maximize photon capture.
- Tempered Glass:Thermal strengthening creates surface compression layers that withstand mechanical load testing under India's BIS certification mandates. Residential installations in Germany and distributed commercial rooftops across Japan specify tempered variants for hail impact resistance.
- Backsheet Glass:Protective rear-side substrates for frameless module designs compete with polymer alternatives on weight and thermal expansion coefficients.
- Laminated Glass:Interlayer bonding with polyvinyl butyral addresses safety fragmentation requirements in building-integrated applications across urban cores.
Anti-reflective coated glass retains volume leadership; laminated glass holds the steepest expansion curve in façade-integrated segments.
End User:
Customer scale determines coating specification intensity and procurement contract structures.
- Residential Installations:Distributed rooftop systems in Australia and the Netherlands prioritize tempered glass with standardized dimensions for installer efficiency.
- Commercial Installations:Corporate power purchase agreements in the United States and South Korea specify verified Scope 3 emissions data for glass suppliers under green bond covenants.
- Utility Scale Projects:Giga-scale developments in Saudi Arabia under Vision 2030 demand high-transmission substrates with desert abrasion resistance specifications. Procurement committees embed lifecycle carbon accounting into supplier scorecards alongside unit pricing.
- Solar Farms:Agrivoltaic dual-use installations in France and Italy require patterned glass variants that balance light transmission with crop photosynthesis requirements.
Utility scale projects command the largest procurement volumes; solar farms gain share fastest in European agricultural land-use frameworks.
Application:
Structural integration requirements split demand between conventional module protection and architectural load-bearing functions.
- Building Integrated Photovoltaics:Curved and patterned glass variants for façade integration command coating equipment premiums in Singapore and Dubai commercial towers. Thin-film technologies compete on weight advantages where conventional glass thickness exceeds building code tolerances.
- Solar Panels:Standard crystalline silicon module assembly concentrates demand for anti-reflective coated float glass in Vietnam and Malaysia production bases.
- Concentrated Solar Power:High-temperature mirror substrates for parabolic trough systems in Morocco and Chile require specialized thermal shock resistance specifications.
- Off-Grid Systems:Rural electrification programs in Nigeria and Indonesia specify tempered glass durability for remote maintenance constraints.
Solar panels retain volume leadership; building integrated photovoltaics climbs the fastest as urban density tightens rooftop availability.
Technology:
Cell architecture evolution determines substrate transmission specifications and coating deposition methods.
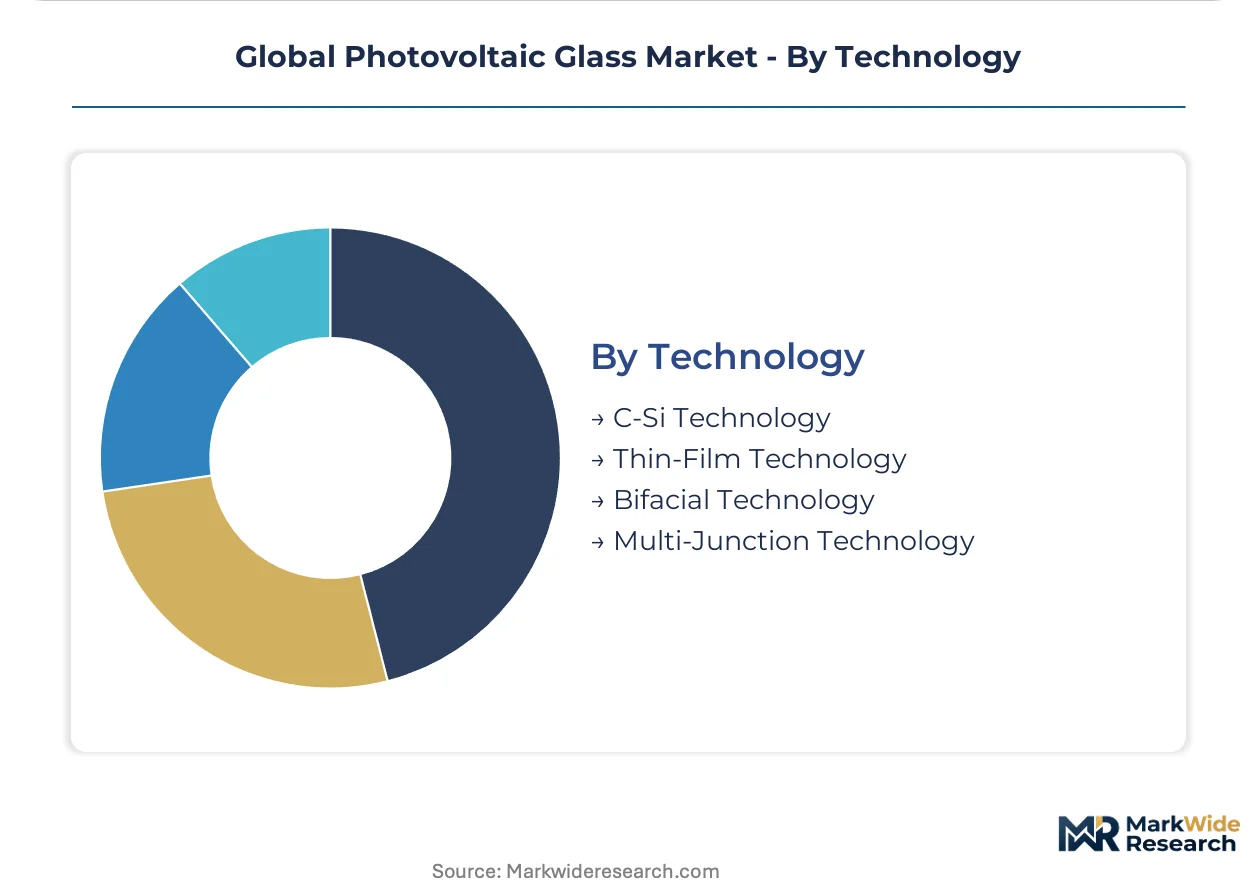
- C-Si Technology:Monocrystalline and polycrystalline silicon cells dominate module assembly in India and Brazil, pulling demand toward standardized high-transmission glass dimensions.
- Thin-Film Technology:Cadmium telluride and CIGS deposition on lightweight substrates addresses structural load limits in German and Austrian building retrofits.
- Bifacial Technology:Double-sided cell architectures demand rear-side coated substrates with performance parity to front-side transmission. N-type production lines in China's manufacturing clusters require specialized float-line retrofits for double-sided chemical vapor deposition.
- Multi-Junction Technology:III-V semiconductor stacks for space and concentrated applications in the United States and Japan specify ultra-high transmission substrates with minimal iron content.
C-Si technology retains volume leadership; bifacial technology represents the fastest-growing trajectory as rear-side gain requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed-in tariff tightening and renewable purchase obligations across multiple jurisdictions are redirecting procurement flows toward specialized high-transmission substrates. China's dual carbon goals constrain float-glass furnace expansions while India's BIS certification mandates reshape import timelines. Middle Eastern giga-scale developments under sovereign wealth-backed programs are embedding lifecycle carbon requirements into supplier selection.
China
N-type cell production lines in Jiangsu and Zhejiang manufacturing clusters demand iron content below 0.05% for bifacial modules. GB standards enforce hard energy consumption caps on float-glass furnaces, blocking conventional natural gas expansions. Xinyi Solar Holdings Ltd. anchors integrated float-glass-to-module supply chains across Southeast Asian production bases with captive coating capabilities.
India
Utility-scale solar developers accelerate procurement of anti-reflective coated glass as renewable purchase obligations harden under CEA mandates. BIS certification requires four-to-six month mechanical load testing timelines for imported solar glass, disrupting just-in-sequence module assembly. Gujarat and Rajasthan host domestic manufacturing investments seeking to bypass certification bottlenecks.
Saudi Arabia
Giga-scale solar installations under Vision 2030 create demand for high-transmission glass with desert abrasion resistance specifications. The renewable energy project authority embeds sustainability-linked financing terms favoring low-carbon glass sourcing. NEOM Northwest anchors planned manufacturing capacity targeting regional procurement committees.
Germany
Building-integrated photovoltaics in urban cores require curved and patterned glass variants commanding coating equipment premiums. REACH and RoHS constrain heavy metal content in imported coatings while EU Green Deal carbon border adjustments reshape cost competitiveness. Bavaria and Baden-Württemberg concentrate façade-integrated module development for commercial retrofits.
United States
Corporate power purchase agreements specify verified Scope 3 emissions data for glass suppliers under green bond covenants. FDA, EPA, and OSHA frameworks govern occupational exposure limits in domestic manufacturing facilities. Texas and California utility procurement committees embed lifecycle carbon accounting into supplier scorecards alongside unit pricing.
Global Photovoltaic Glass Market Competitive Environment
Channel-controlling players compete with product-specialist players across a market consolidating around integrated supply chain capabilities. Float-glass manufacturers with captive coating operations command procurement preference as bifacial rear-side gain requirements harden substrate specifications. Three archetypes dominate: integrated float-glass-to-module suppliers, specialized coating technology licensors, and regional distributors with technical service depth. Capacity expansion and strategic partnerships represent the dominant competitive moves as furnace decarbonization pressures force process innovation.
Within the integrated supply tier, Xinyi Solar Holdings Ltd. and Flat Glass Group Co., Ltd exemplify manufacturers leveraging Southeast Asian production bases and domestic capacity expansion respectively. Saint-Gobain occupies a position reflecting European technical glass heritage adapted to photovoltaic transmission specifications. These three anchors illustrate how geographic origin and corporate structure map to divergent strategic postures in a market tilting toward capital-intensive manufacturers with balance sheet depth.
| Leading Market Players |
|---|
| Xinyi Solar Holdings Ltd. |
| Flat Glass Group Co., Ltd |
| IRICO Group New Energy Co., Ltd. |
| AGC Inc. |
| Saint-Gobain |
| CSG Holding Co. Ltd. |
| NSG Pilkington |
| Borosil Renewables |
| Taiwan Glass |
| Others |
Value Chain & Pricing Dynamics
Float-glass furnace undercapacity across China's Jiangsu and Zhejiang clusters is compressing supplier margins while amplifying pricing power for integrated manufacturers with captive coating capabilities. GB standards enforcing hard energy consumption caps have frozen conventional natural gas expansions, forcing procurement committees toward multi-year offtake agreements with verified Scope 3 data.
Pricing Analysis
Certification level creates the primary spread across procurement tiers, with BIS mechanical load certification for Indian imports commanding premiums over standard tempered variants. Three-tier pricing structure across premium, standard, and economy levels reflects iron content purity, coating deposition method, and hydrophobic top-layer specifications. Cost compression in economy-tier float glass is intensifying because China's dual carbon goals constrain furnace expansions and concentrate supply among integrated players. Utility-scale developers in Saudi Arabia and India demonstrate lowest price sensitivity, embedding lifecycle carbon accounting into supplier scorecards alongside unit pricing.
Supply Chain Analysis
Export-control regimes on semiconductor manufacturing equipment have redirected coating technology flows, constraining CVD equipment availability for new market entrants. Geographic supply concentrates in China, Vietnam, and Malaysia, where integrated float-glass-to-module supply chains anchor Southeast Asian production bases. Raw material dependencies center on high-purity silica sand from specific coastal deposits, low-iron soda ash, and specialty chemical precursors for anti-reflective coatings. Single-source vulnerability in CVD coating technician expertise constrains coating line ramp speeds. Distribution runs through module assembly clusters in India, the Middle East, and European building-integrated photovoltaic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bifacial module architecture disruption, amplified by N-type cell production scaling and carbon border adjustment mechanisms, is compressing competitive timelines for substrate suppliers. This technological-regulatory inflection favors capital-intensive manufacturers with balance sheet depth and captive coating capabilities.
For Market Incumbents: Pre-empt coating chemistry obsolescence by accelerating in-house CVD capability expansion across Southeast Asian production bases. Secure captive low-iron silica sand offtake agreements before geological depletion curves tighten feedstock availability. Defend against thin-film weight advantages in building-integrated photovoltaics by piloting patterned glass variants for façade integration.
For New Entrants and Emerging Players: Establish a beachhead in India's utility-scale procurement pipeline, where BIS certification timelines create four-to-six month bottlenecks for imported glass and domestic manufacturing investments bypass disruption. Target agrivoltaic solar farm segments in France and Italy requiring specialized patterned glass variants that balance light transmission with crop photosynthesis. Lead with verified Scope 3 emissions data to access green bond-structured project finance.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated float-glass-to-module suppliers with Southeast Asian manufacturing footprints and captive coating capabilities. Long-term viability across the projection horizon hinges on furnace decarbonization technology readiness and hydrogen-blended combustion pilot scale-up. Watch for bifacial rear-side gain requirements hardening from performance preference to procurement mandate as the signal to force portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Float-Glass Furnace Decarbonization | GB standards in China enforce hydrogen-blended combustion pilots that block conventional natural gas expansions. |
| Captive Coating Capability Expansion | In-house CVD operations command procurement preference as bifacial rear-side gain requirements harden specifications. |
| Low-Iron Silica Sand offtake Agreements | Premium coastal feedstock deposits face geological depletion curves that threaten margin stability. |
| Multi-Year offtake Agreement Structuring | Utility procurement committees in Saudi Arabia and India embed lifecycle carbon accounting alongside unit pricing. |
| Building-Integrated Photovoltaic Glass Development | Curved and patterned variants for Singapore and Dubai commercial towers command coating equipment premiums. |
Study Parameters
The analysis maps anti-reflective coated glass, tempered glass, backsheet glass, and laminated glass sub-sectors, each validated through float-line operations managers, module assembly procurement leads, utility-scale project developers, and CVD coating equipment specialists. Primary interviews with these stakeholders combined with secondary validation from SEC filings of listed glass manufacturers, customs and trade data on silica sand imports, GB standards documentation, and BIS certification timelines. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Assumptions held fixed include China's dual carbon enforcement trajectory, India's renewable purchase obligation hardening, and bifacial module penetration curves. The projection horizon spans product type, end user scale, application architecture, and technology segments. CAGRs derived from weighted capacity expansion announcements, furnace energy intensity improvements, and coating technology substitution rates. Industry-specific inputs incorporated float-glass furnace thermal efficiency thresholds and chemical vapor deposition equipment lead times.
Macroeconomic conditions sit as an overlay; deviation in natural gas pricing, bulk shipping rates, or green bond issuance volumes would shift the trajectory. Forecasts reflect these documented assumptions. Material shifts in carbon border adjustment mechanism implementation timelines or hydrogen-blended combustion technology commercialization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Solar PV Tracker Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Slovakia Solar Energy Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar Power Manager Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Solar Cell (Photovoltaic) Module Market
Solar Power Systems
Flexible Parylene-Based Solar Cells Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Solar Photovoltaics Wafer Market