
 United Kingdom Solar Power Market | 2026-2036
United Kingdom Solar Power Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Solar Power Market Analytics
Perovskite-silicon tandem cell research is recalibrating module efficiency benchmarks across the United Kingdom solar supply chain. Lightsource bp Renewable Energy Investments Ltd leverages its domestic development pipeline to anchor utility-scale deployment in southern England. SSE Renewables sustains competitive positioning through integrated grid infrastructure control. Octopus Energy Generation differentiates via agile residential aggregation platforms that optimize behind-the-meter economics.
United Kingdom solar power encompasses photovoltaic energy conversion systems, thermal collectors, power electronics, and electrochemical storage devices engineered to transform incident solar radiation into usable electricity or heat, with crystalline silicon modules typically achieving 20-22% conversion efficiency under standard test conditions. The technology serves grid-connected generation, self-consumption optimization, and rural electrification across residential, commercial, and utility contexts. Photovoltaic Panels and Solar Batteries capture expanding margin pools as developers prioritize dispatchable renewable capacity. Rooftop installations compete with Ground-mounted arrays for capital allocation, with urban density constraints favoring elevated and building-integrated configurations in Greater London and Birmingham corridors.
Ofgem administers grid connection queues and capacity market rules that directly determine project timelines and revenue stack composition for United Kingdom solar developers. The Contracts for Difference scheme administered by the Low Carbon Contracts Company establishes strike price floors that de-risk utility-scale investment decisions. MCS certification requirements govern residential system eligibility for export tariff schemes. Stakeholders must monitor queue reform implementation and locational pricing signals as network constraints intensify in high-penetration zones.
Market Dynamics
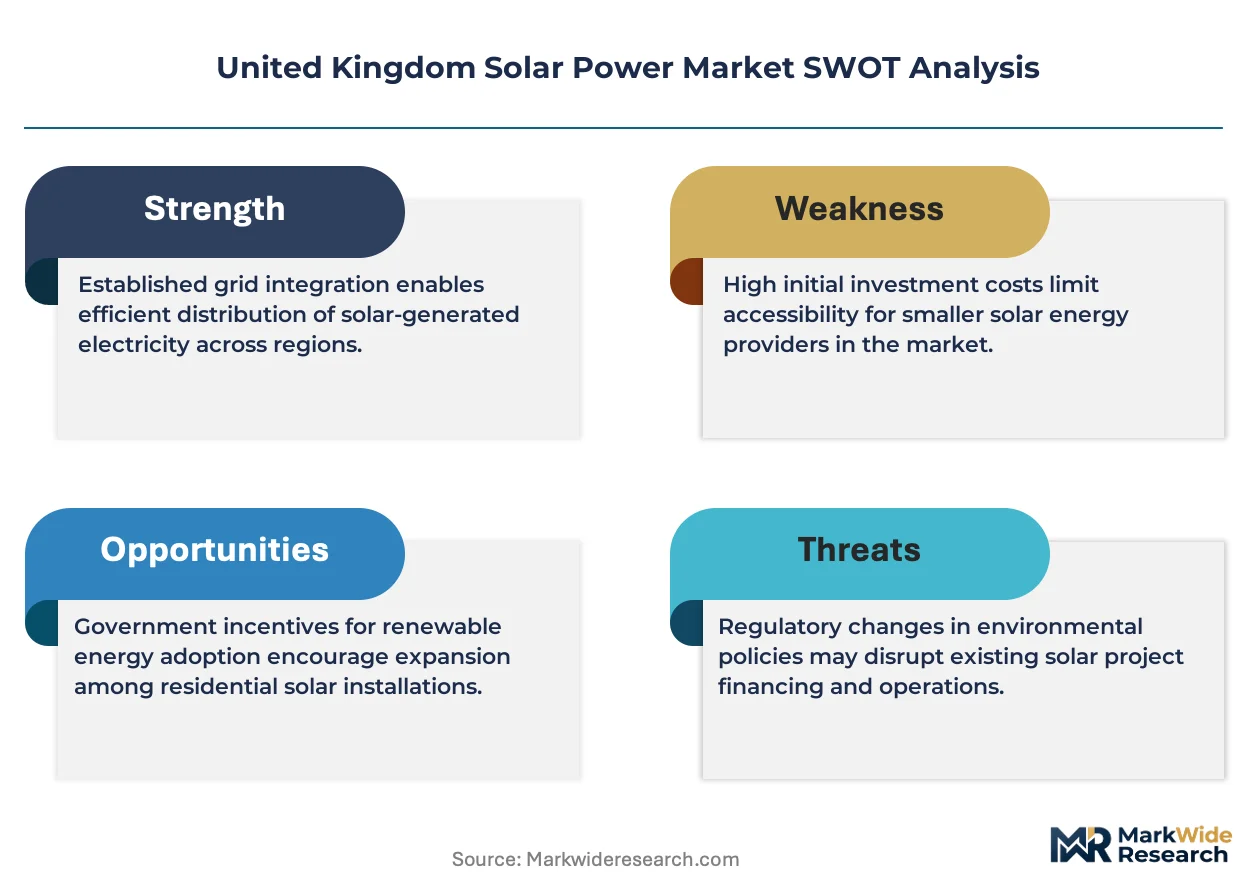
The Contracts for Difference scheme administered by the Low Carbon Contracts Company is compressing project risk premiums and redirecting capital toward utility-scale solar farms in southern England and the Scottish Highlands.
Growth Catalysts
- Contracts for Difference scheme:The Low Carbon Contracts Company establishes strike price floors that de-risk utility-scale investment decisions and accelerate procurement timelines for developers.
- Perovskite-silicon tandem cells:Laboratory breakthroughs in conversion efficiency are recalibrating module performance benchmarks across domestic supply chains.
- Scottish Highlands clusters:Grid connection reforms and land availability are concentrating utility-scale deployment in northern Scotland's renewable energy zones.
Market Restraints
- Polysilicon input volatility:Price swings in refined silicon feedstock compress module manufacturer margins and destabilize project cost forecasting.
- Ofgem grid connection queues:Administrative bottlenecks in network access applications extend project development timelines by 18-36 months.
- Land use competition:Agricultural land preservation policies in England's southern counties restrict available sites for ground-mounted arrays.
Strategic Opportunities
- Building-integrated photovoltaics:Urban density constraints in Greater London and Birmingham corridors favor elevated and facade-mounted configurations.
- Behind-the-meter aggregation:Residential battery storage coupled with rooftop solar enables demand response participation in capacity markets.
- MCS certification expansion:Streamlined accreditation for emerging module technologies opens export tariff eligibility to next-generation systems.
Industry Challenges
- Electrical engineering skill scarcity:Qualified technicians for grid-tied inverter commissioning and battery integration remain undersupplied relative to deployment targets.
- Locational pricing signal complexity:Network constraint charges in high-penetration zones require sophisticated revenue optimization that many developers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Solar Power Market |
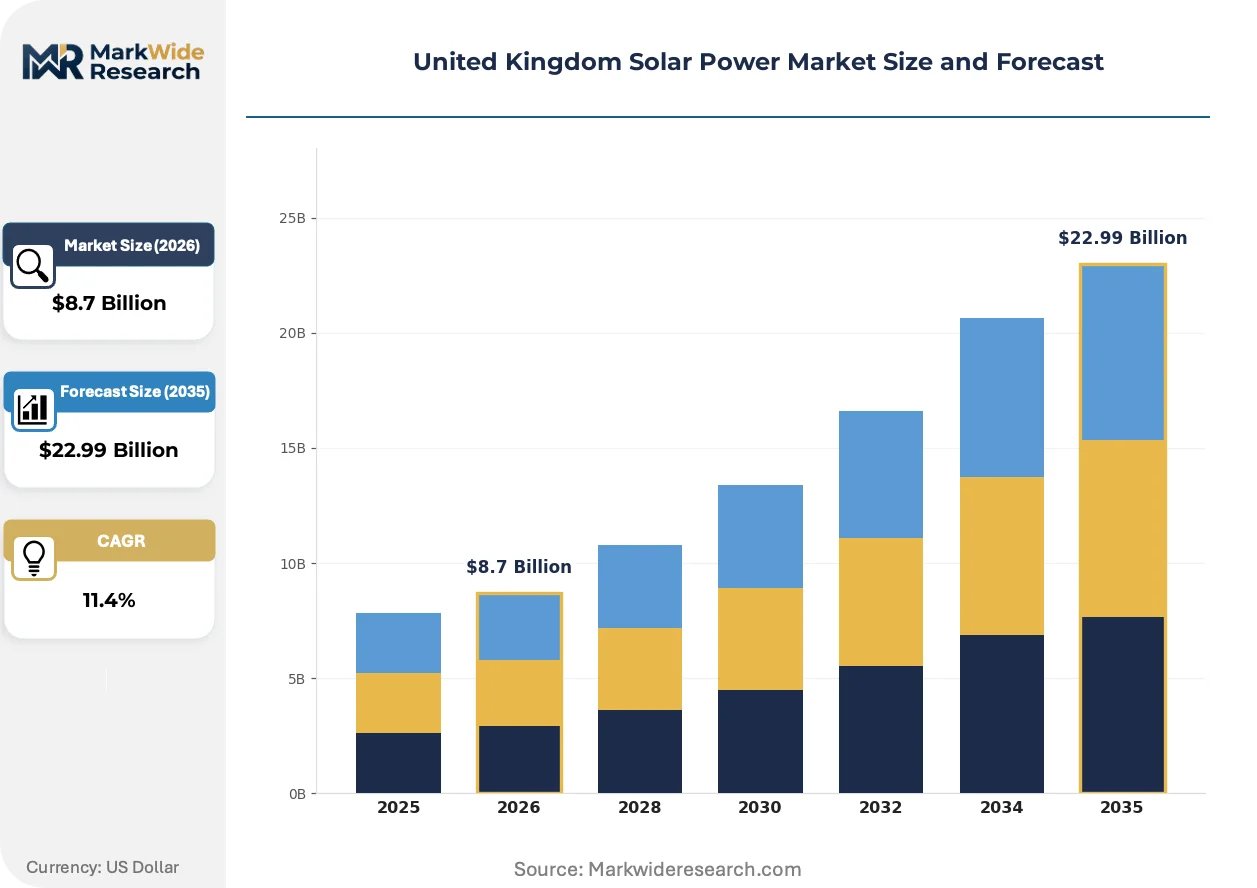
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Thermal Systems, Inverters, Solar Batteries Application: Residential, Commercial, Industrial, Utilities Installation Type: Rooftop, Ground-mounted, Building-integrated, Off-grid Technology: Thin Film, Crystalline Silicon, Concentrated Solar Power, Bifacial Modules |
| Companies Covered | Foresight Solar Fund Ltd, SSE Renewables, Lightsource bp Renewable Energy Investments Ltd, RES, Statkraft UK, EDF Renewables UK, ScottishPower Renewables, Anesco Ltd, Octopus Energy Generation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Solar Power Market Evolving Landscape
Bifacial module architectures and integrated electrochemical storage are converging to reshape project economics across residential and utility contexts in the United Kingdom.
Bifacial photovoltaic modules capture reflected irradiance from ground surfaces and elevated mounting structures, boosting energy yield by 8-15% over monofacial equivalents. Utility-scale developers in Norfolk and Cambridgeshire are integrating these systems into new procurement specifications. The technology is integrating tracking systems and agrivoltaic configurations that dual-purpose land for energy generation and agricultural production.
The Contracts for Difference scheme's administrative reforms are tightening strike price bands and introducing technology-neutral auction rounds. This industrial consequence pressures solar developers to compress construction timelines and optimize capital structures. Utility-scale projects in England's southern counties are responding by pre-securing grid connection agreements before auction participation.
Corporate power purchase agreements are displacing traditional utility tariffs as the dominant offtake mechanism for commercial rooftop installations. Energy-intensive manufacturers and data center operators are negotiating 10-15 year fixed-price contracts directly with solar asset owners. This pattern concentrates in the Midlands and northern England where industrial load centers cluster near transmission infrastructure.
United Kingdom Solar Power Market Segmentation
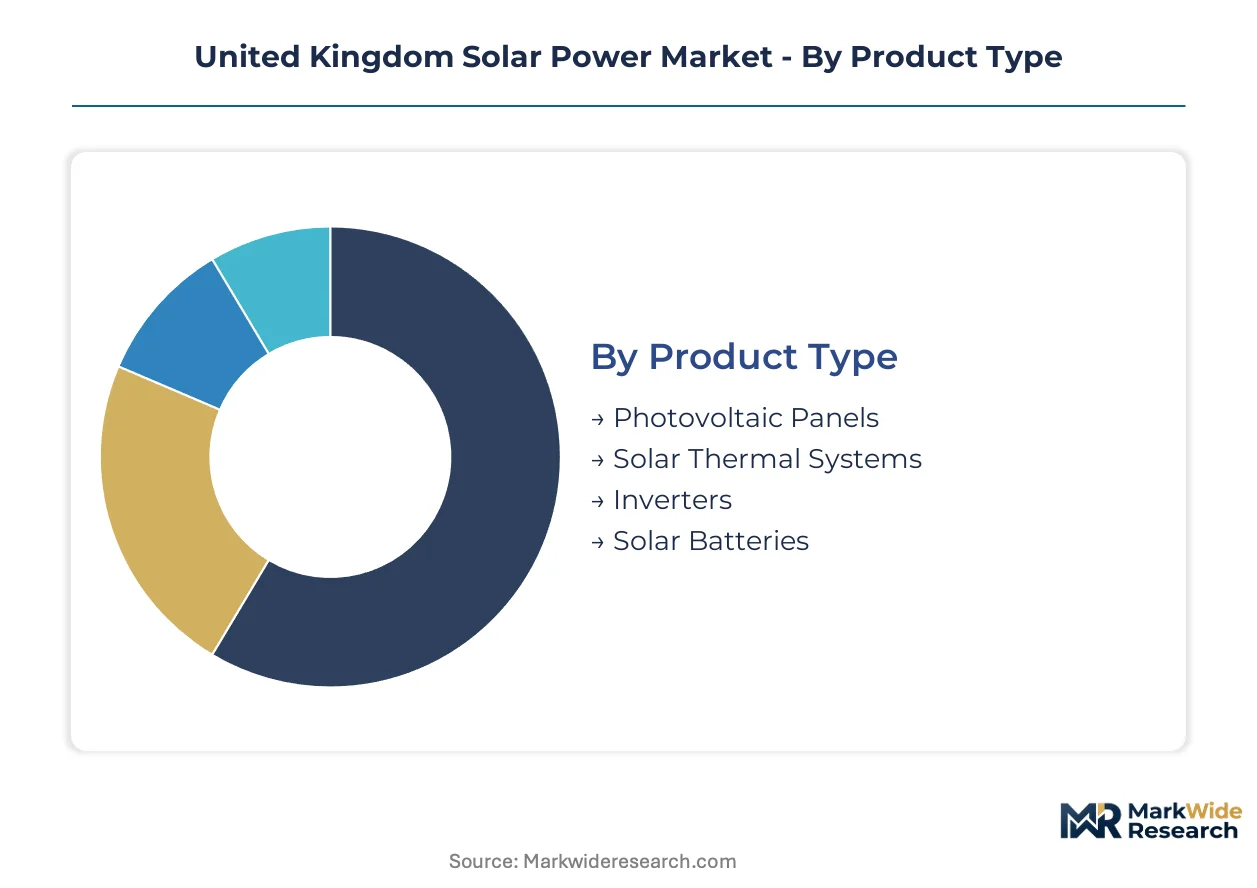
Technology and installation configurations fragment the United Kingdom solar power market into distinct margin pools. Procurement patterns bifurcate between subsidy-dependent utility-scale projects and self-financed distributed systems.
Product Type:
Supply concentration in module manufacturing favors crystalline silicon producers with established distribution networks.
- Photovoltaic Panels:Crystalline silicon modules dominate procurement specifications with 20-22% conversion efficiency under standard test conditions. Utility-scale developers in Norfolk and Cambridgeshire anchor demand for utility-scale bifacial configurations.
- Solar Batteries:Lithium-ion electrochemical storage systems enable dispatchable renewable capacity and behind-the-meter aggregation. Residential installers in Greater London prioritize AC-coupled units for retrofit compatibility.
- Inverters:Power electronics manufacturers face margin compression from string inverter commoditization.
- Solar Thermal Systems:Flat-plate and evacuated tube collectors serve niche domestic hot water applications.
Today's leader: Photovoltaic Panels. Tomorrow's challenger: Solar Batteries.
Application:
Customer type determines financing structure and regulatory exposure across deployment contexts.
- Utilities:Contracts for Difference auctions drive procurement of multi-hundred-megawatt solar farms. Scottish Highlands clusters concentrate land-rich development opportunities.
- Residential:MCS-certified rooftop systems qualify for export tariff schemes. Octopus Energy Generation's aggregation platforms optimize self-consumption economics.
- Commercial:Corporate power purchase agreements displace traditional utility tariffs for energy-intensive manufacturers.
- Industrial:Data center operators negotiate fixed-price contracts directly with asset owners.
Utilities command capital deployment volumes. Residential segments gain share fastest through financing innovation.
Installation Type:
Geography and grid access dictate configuration selection across England's southern counties and urban corridors.
- Ground-mounted:Elevated tracking structures maximize bifacial module yield in agricultural zones. Land use competition constrains site availability in England's southern counties.
- Rooftop:Distributed deployment dominates urban density constraints in Greater London and Birmingham corridors.
- Building-integrated:Facade-mounted and agrivoltaic configurations dual-purpose land for energy and production.
- Off-grid:Standalone systems serve rural electrification in Scottish Highlands beyond distribution network reach.
Ground-mounted arrays absorb utility-scale capital. Building-integrated configurations expand the addressable market in constrained geographies.
Technology:
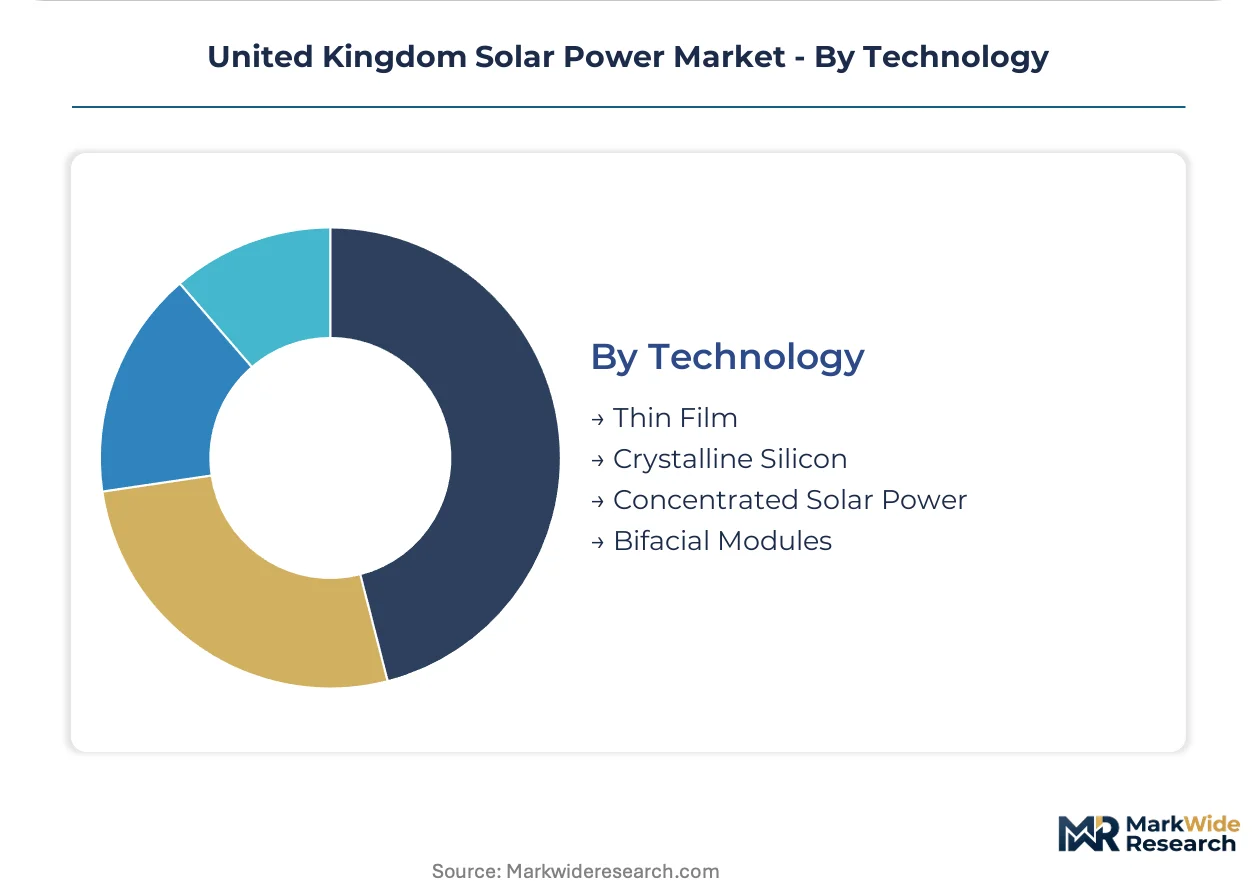
Module efficiency benchmarks recalibrate as perovskite-silicon tandem research advances through domestic supply chains.
- Crystalline Silicon:Passivated emitter and rear contact architectures anchor utility-scale procurement specifications. Lightsource bp Renewable Energy Investments Ltd specifies these modules for southern England pipelines.
- Bifacial Modules:Dual-sided energy capture boosts yield 8-15% over monofacial equivalents through reflected irradiance harvesting.
- Thin Film:Cadmium telluride and copper indium gallium selenide technologies occupy niche building-integrated applications.
- Concentrated Solar Power:Thermal collection with molten salt storage remains marginal in the United Kingdom's irradiance profile.
Crystalline Silicon maintains incumbent position. Bifacial Modules climb the fastest as tracking system integration spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's southern counties anchor United Kingdom solar deployment through superior irradiance profiles and established grid infrastructure. The Contracts for Difference scheme channels capital toward Norfolk and Cambridgeshire clusters where land availability intersects with transmission access. Scotland's northern Highlands emerge as secondary concentration zones through grid connection reforms and renewable energy zone designations.
London and the Southeast
Urban density constraints concentrate rooftop installations across Greater London and Home Counties corridors. Ofgem administers connection queues that extend project timelines by 18-36 months in high-penetration zones. Lightsource bp Renewable Energy Investments Ltd anchors utility-scale pipelines across Kent and Sussex agricultural zones.
Midlands
Industrial load centers in Birmingham and Leicester drive corporate power purchase agreement demand from energy-intensive manufacturers. The Contracts for Difference scheme supports multi-hundred-megawatt solar farm procurement across Warwickshire and Northamptonshire. Anesco Ltd operates distributed commercial portfolios throughout the East Midlands corridor.
North England
Transmission infrastructure proximity attracts utility-scale developers to Yorkshire and Lancashire renewable energy zones. The Low Carbon Contracts Company strike price floors de-risk capital deployment across former industrial land sites. EDF Renewables UK maintains development pipelines across Cumbria and Northumberland coastal zones.
Scotland
Scottish Highlands clusters concentrate land-rich utility-scale opportunities through grid connection queue reforms. ScottishPower Renewables leverages integrated grid infrastructure control across Perthshire and Aberdeenshire wind-solar hybrid zones. Statkraft UK anchors Norwegian capital flows into Scottish renewable energy auctions.
Wales
Agricultural land availability supports ground-mounted array deployment across Pembrokeshire and Anglesey coastal plains. The Welsh Government renewable energy targets complement Contracts for Difference scheme participation. RES maintains development presence across Welsh solar and onshore wind convergence zones.
United Kingdom Solar Power Market Competitive Landscape
Global majors compete with regional champions across capital structure sophistication and grid infrastructure integration. The vendor base stratifies between utility-scale developers with CfD auction expertise and distributed operators with residential aggregation platforms. Three archetypes dominate: integrated utilities with captive grid control, independent power producers with CfD specialization, and agile aggregators with behind-the-meter optimization capabilities. Competitive intensity concentrates on pre-securing grid connection agreements and compressing construction timelines ahead of technology-neutral auction rounds.
Within the utility-scale developer tier, Foresight Solar Fund Ltd and SSE Renewables exemplify contrasting capital approaches to CfD participation. Foresight Solar Fund Ltd represents infrastructure fund models that securitize operational assets through yield-focused vehicles. SSE Renewables occupies a position within integrated utility structures that leverage transmission network control for locational pricing optimization. Octopus Energy Generation anchors the residential aggregation archetype through agile platforms that optimize export tariff economics across distributed portfolios. These three entities collectively illustrate the strategic segmentation between scale-driven utility development and technology-enabled distributed energy resource management.
| Leading Market Players |
|---|
| Foresight Solar Fund Ltd |
| SSE Renewables |
| Lightsource bp Renewable Energy Investments Ltd |
| RES |
| Statkraft UK |
| EDF Renewables UK |
| ScottishPower Renewables |
| Anesco Ltd |
| Octopus Energy Generation |
| Others |
Value Network & Pricing Analysis
The Contracts for Difference scheme's strike price floors gate qualified supply access and premium-tier pricing power for United Kingdom solar developers bidding into Low Carbon Contracts Company auctions. Polysilicon input volatility and Ofgem grid connection queue delays compress margins across module procurement and project development timelines.
Pricing Analysis
Polysilicon cost pass-through from Chinese and Malaysian refiners shapes crystalline silicon module pricing across United Kingdom procurement channels. Pricing stratifies across MCS-certified residential tiers, utility-scale CfD auction bands, and corporate PPA offtake structures based on grid connection certainty and technology configuration. Cost compression in standard-tier string inverters is intensifying because manufacturer commoditization erodes differentiation. Residential installers exhibit highest price sensitivity due to retrofit financing constraints, while utility developers prioritize strike price certainty over unit cost.
Supply Chain Analysis
End-of-life module collection networks and battery refurbishment flows are emerging as reverse-logistics priorities for United Kingdom circular economy compliance. Manufacturing concentration in China, Vietnam, and Malaysia for crystalline silicon cells and lithium-ion cells creates single-source vulnerability for domestic developers. The supply chain draws from Southeast Asian module assembly hubs and European inverter production centers. Distribution runs through EPC contractor procurement channels and direct developer agreements with tier-one manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United Kingdom solar power represents a margin-expansion story as bifacial module yield premiums and integrated storage dispatchability shift developer economics toward premium-tier revenue stacks.
For Market Incumbents: Deepen backward integration into battery storage system assembly to capture margin pools currently flowing to Asian cell manufacturers. Secure pre-approved grid connection agreements ahead of technology-neutral CfD auction rounds to compress development timelines against emerging independent power producers.
For New Entrants and Emerging Players: Residential aggregation platforms offer the lowest barrier-to-entry route for distributed energy resource management capability building. Target Scottish Highlands utility-scale clusters where land availability and grid queue reforms concentrate development opportunity. Pursue corporate PPA origination for Midlands industrial load centers as anchor offtake strategy.
For Investors and Strategic Acquirers: Roll-up economics work for distributed commercial solar portfolios because fragmented installer networks and inconsistent MCS certification standards create consolidation value. Five-to-ten year viability hinges on regulatory continuity for export tariffs and capacity market participation. Monitor Ofgem queue reform implementation velocity as inflection indicator for development timeline compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid Connection Pre-Approval | Securing Ofgem queue positions ahead of CfD auctions de-risks capital deployment timelines for utility-scale pipelines. |
| Battery Storage Integration | AC-coupled lithium-ion systems enable behind-the-meter aggregation and capacity market revenue stacking for residential installers. |
| Corporate PPA Origination | Direct offtake negotiations with Midlands manufacturers displace traditional utility tariffs for commercial rooftop assets. |
| MCS Certification Streamlining | Accelerated accreditation for bifacial and perovskite-silicon modules opens export tariff eligibility to next-generation technologies. |
| Scottish Highlands Expansion | Land-rich development zones and grid connection reforms concentrate utility-scale opportunity in northern Scotland renewable energy corridors. |
Research Methodology
Bottom-up residential and utility-scale deployment modeling reconciled against top-down module import and grid connection tracking forms the analytical core of this study. Primary interviews with utility planning officers, independent power project developers, EPC contractors, and grid operators at distribution network operators were cross-validated against secondary sources including Low Carbon Contracts Company auction results, Ofgem connection queue databases, and MCS certification registries.
Input-output matrices map crystalline silicon module supply flows through Southeast Asian assembly hubs into United Kingdom port infrastructure and downstream EPC channels. Segmentation dimensions span technology type, installation configuration, application context, and regional grid constraint profiles across the projection horizon. CAGRs derive from installed capacity build-up trajectories reconciled against CfD auction round forecasts and corporate PPA origination pipelines.
Polysilicon price volatility, Ofgem administrative reform implementation delays, and technology-neutral auction design shifts are the dominant revision risks to forecast outputs. Practitioners should monitor queue clearance rates, strike price band tightening, and perovskite-silicon tandem cell commercialization timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
GCC Solar Water Heater Market
Solar Power Systems
Spray-On Solar Cells Market
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Solar Module Racking Market
Solar Power Systems
On-Site Photovoltaic Solar Power for Data Centers Market
Solar Power Systems
Global Ultra Efficient Solar Power Market
Solar Power Systems
Germany Solar Energy Market
Solar Power Systems
Europe Concentrated Solar Power Market
Solar Power Systems
Iran Solar Energy Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Solar Panel Cleaning System Market
Solar Power Systems
Asia-Pacific Solar Tracker Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Greece Solar Energy Market