
 UV Solar Simulators Market | 2026-2036
UV Solar Simulators Market Size, Share, and Industry Trends Forecast 2026-2036
UV Solar Simulators Market Insights
China's photovoltaic testing infrastructure expansion is reshaping procurement patterns for UV solar simulators. Newport Corporation leverages its Newport-Oriel lamp portfolio to dominate xenon-arc supply for IEC-compliant aging chambers. Abet Technologies specializes in LED-based simulator architectures that sustain lower operational costs for university laboratories. OAI competes through precision optical calibration services that anchor repeatability claims for third-party certification bodies.
UV solar simulators are engineered light sources that replicate the spectral distribution, intensity, and temporal stability of terrestrial solar ultraviolet radiation, typically spanning 280–400 nm with irradiance uniformity within ±2% across target planes. These systems employ xenon short-arc lamps, metal halide arrays, or solid-state LED engines filtered to match AM 1.5G spectral weighting for accelerated degradation studies and photovoltaic performance verification. Benchtop simulators occupy the highest volume tier as research laboratories standardize compact formats for perovskite and tandem cell screening, while LED technology captures the fastest expansion trajectory due to programmable spectral tuning and elimination of mercury-bearing consumables. Materials testing applications command the deepest margin pools because module manufacturers require continuous batch qualification under evolving IEC protocols.
IEC standards 61215 and 61646 mandate specific UV preconditioning sequences that directly determine simulator spectral matching requirements for market access in Europe and Asia. China's GB/T 9535 national standard and Japan's JIS C 8990 incorporate equivalent UV exposure clauses, compelling manufacturers to align optical engine designs across multiple certification regimes. METI's renewable energy equipment testing directives in Japan further tighten irradiance monitoring tolerances for grid-connected module approvals. Stakeholders must monitor divergence between regional spectral weighting definitions as next-generation perovskite-silicon tandems introduce sensitivity to wavelengths below 300 nm that existing standards do not fully address.
Market Dynamics
Photovoltaic certification protocols are tightening spectral matching requirements for UV preconditioning, forcing simulator manufacturers to recalibrate optical engines across multiple jurisdictional standards simultaneously.
Growth Catalysts
- IEC 61215/61646 Sequences:Extended UV exposure mandates for crystalline silicon certification in Europe and Asia are expanding replacement cycles for aging xenon-arc systems.
- Perovskite Tandem Screening:Research laboratories in China and Japan are procuring benchtop LED simulators for high-throughput stability testing of next-generation cell architectures.
- Jiangsu-Zhejiang Cluster Expansion:Gigawatt-scale module factories in these provinces are installing continuous-batch qualification lines that require dedicated UV aging chambers.
Market Restraints
- Xenon Lamp Supply Concentration:Short-arc lamp manufacturing concentrates among German and Japanese suppliers, creating input vulnerability for arc-based system builders.
- Spectral Calibration Complexity:Matching AM 1.5G weighting below 300 nm demands specialized spectroradiometry that extends factory acceptance testing timelines.
- Mercury Disposal Compliance:RoHS and REACH restrictions on mercury-bearing consumables are elevating total cost of ownership for legacy metal halide architectures.
Strategic Opportunities
- Perovskite-Silicon Tandem Sensitivity:Next-generation cells exhibit degradation at wavelengths below 300 nm that existing IEC protocols do not fully address, creating demand for sub-300 nm capable systems.
- University Laboratory LED Conversion:Lower operational costs and programmable spectral tuning are opening replacement demand in academic research settings previously served by lamp-based systems.
- GB/T 9535 Alignment Services:China's national standard incorporates UV exposure clauses equivalent to IEC mandates, creating calibration service opportunities for third-party certification bodies.
Industry Challenges
- Optical Engineer Scarcity:Spectroradiometry and filter design expertise required for AM 1.5G matching resides within a narrow talent pool concentrated in Germany and Japan.
- Multi-Standard Calibration Burden:Simultaneous compliance with IEC, GB/T, and JIS C 8990 spectral definitions extends engineering validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UV Solar Simulators Market |
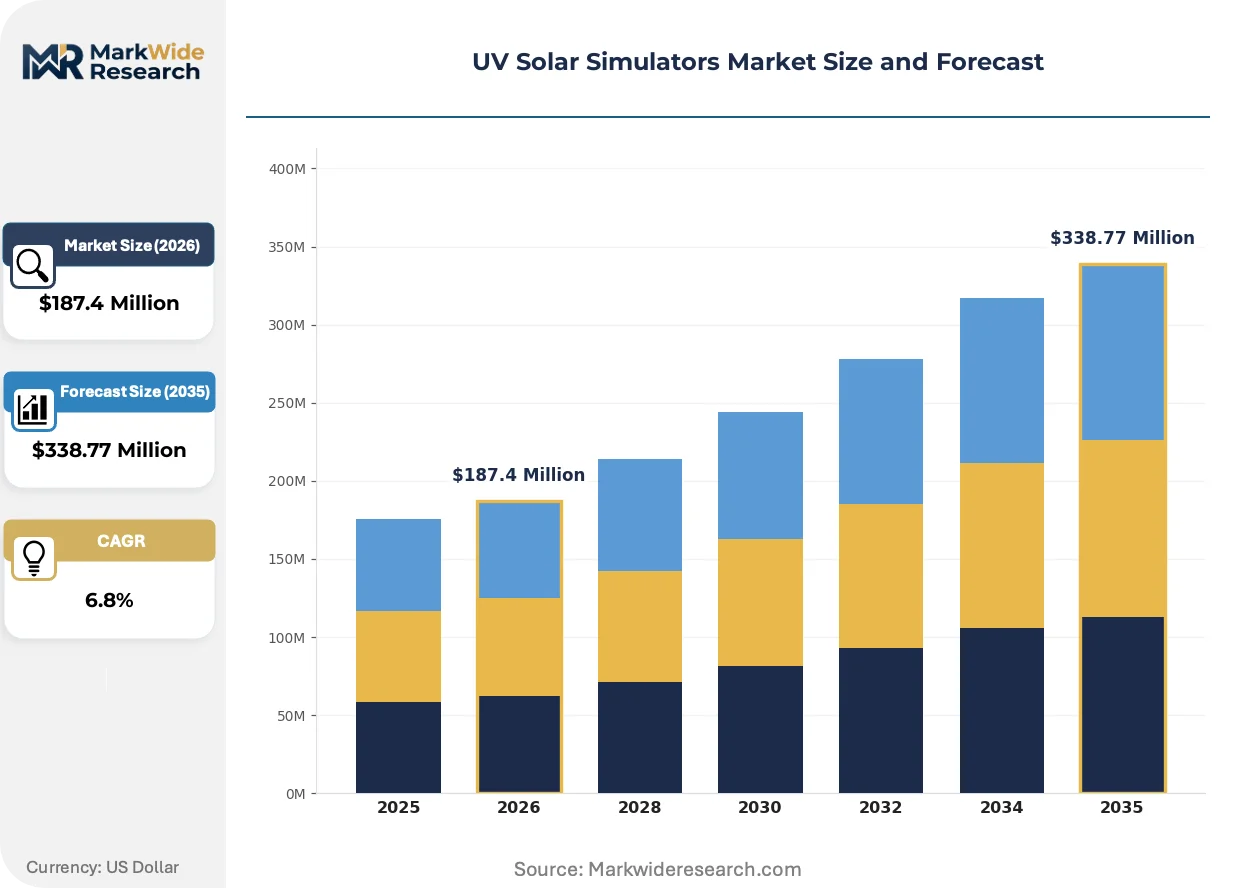
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Simulators, Portable Simulators, High-Intensity Simulators, LED Simulators Application: Materials Testing, Biological Research, Environmental Testing, Product Development End User: Research Laboratories, Universities, Material Manufacturers, Testing Agencies Technology: Quartz Lamp, Metal Halide Lamp, LED Technology, Xenon Lamp |
| Companies Covered | Newport Corporation, Abet Technologies, Inc., OAI (Optical Associates Inc.), Solar Light Company, LLC, Sciencetech, Inc., Wacom Electric Co., Ltd., Asahi Spectra Co., Ltd., Iwasaki Electric Co., Ltd., Gsolar Power Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UV Solar Simulators Market Trends and Innovations
Optical engine architectures are diverging along application lines, with research laboratories and production facilities adopting fundamentally different spectral generation strategies.
Solid-state LED engines are migrating from niche academic applications toward mainstream adoption in perovskite and tandem cell screening. Materials science departments in Chinese and Japanese universities are replacing xenon-arc benchtop units with programmable LED arrays that enable wavelength-specific degradation studies. This migration from lamp-based to solid-state architectures is compressing maintenance intervals and eliminating mercury compliance burdens for institutional buyers.
Japan's METI renewable energy equipment testing directives are tightening irradiance monitoring tolerances for grid-connected module approvals. These directives mandate redundant pyrometer validation that extends chamber commissioning timelines. Tier-one module manufacturers in Japan are responding by specifying simulators with integrated traceable calibration references.
Batch qualification protocols are fragmenting procurement authority between R&D and quality engineering functions. Module manufacturers in China's Jiangsu province are unbundling simulator acquisition decisions, with research groups specifying benchtop LED systems while production engineering selects xenon-arc chambers for IEC compliance. This organizational split is visible in purchasing patterns where single facilities now maintain divergent optical engine technologies.
UV Solar Simulators Market Segmentation
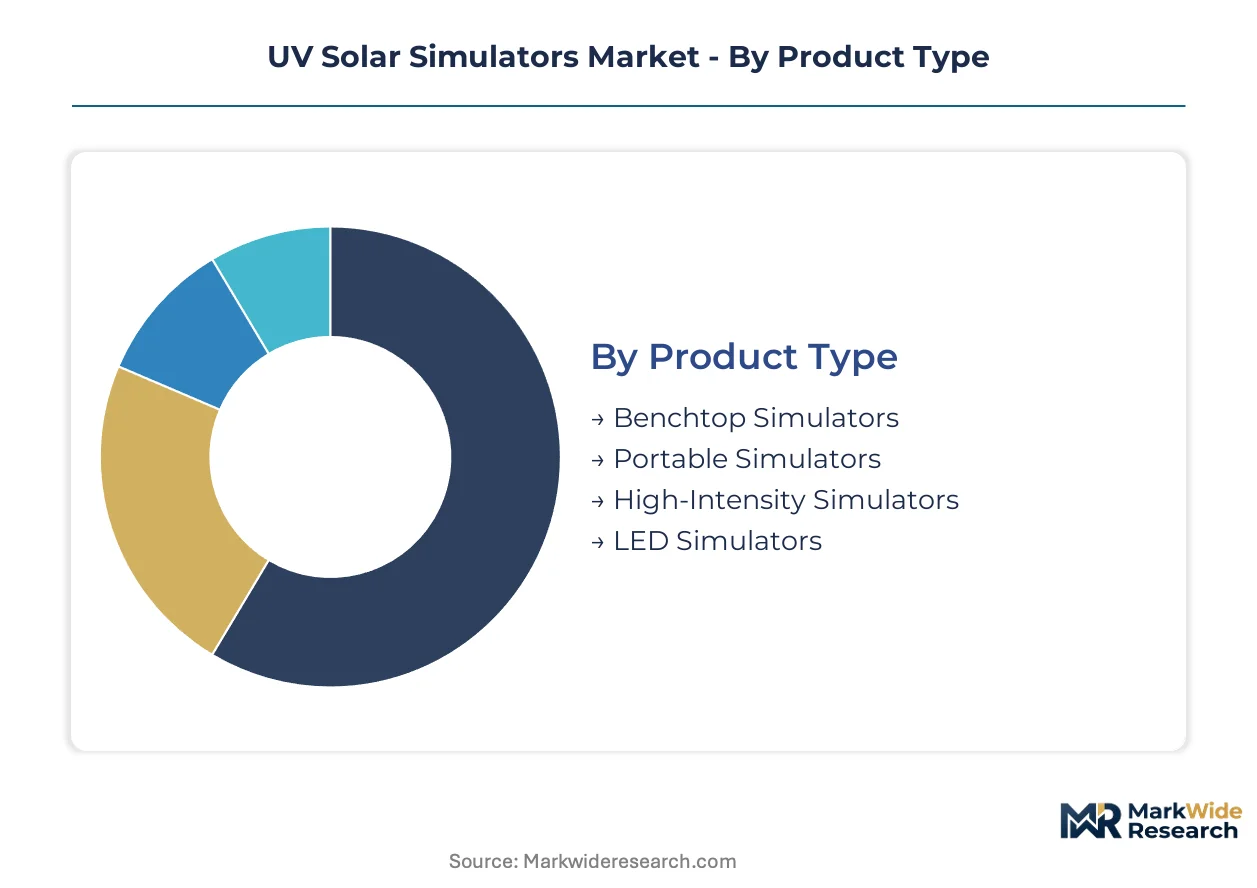
UV solar simulator procurement patterns diverge sharply across product formats, with research laboratories prioritizing compact footprints while production facilities demand continuous-batch architectures. Understanding these segment boundaries clarifies why optical engine technologies and service intensity requirements vary so dramatically between academic and industrial buyers.
Product Type:
After-sales service intensity escalates with lamp replacement frequency and optical calibration complexity, creating divergent vendor economics across simulator formats.
- Benchtop Simulators:Compact optical engines designed for laboratory workbenches, typically employing filtered xenon short-arc or LED arrays with target plane dimensions under 300mm. Perovskite and tandem cell screening in Chinese and Japanese university laboratories drives procurement volume, with maintenance contracts concentrated on annual spectral recalibration rather than lamp replacement.
- LED Simulators:Solid-state architectures using programmable diode arrays spanning 280–400nm with electronic rather than mechanical spectral tuning. Materials science departments in China are displacing legacy xenon-arc units to eliminate mercury compliance burdens and enable wavelength-specific degradation studies.
- Portable Simulators:Battery-powered or lightweight mains units for field validation and temporary installation testing. Field service organizations in Germany and Japan utilize these for on-site module qualification where chamber access is impractical.
- High-Intensity Simulators:Large-format systems with irradiance exceeding 1000 W/m² across target planes exceeding 2m² for production-scale batch testing. Jiangsu province module factories install these for continuous IEC 61215 preconditioning cycles.
By volume, Benchtop Simulators lead. By growth pace, LED Simulators is ahead.
Application:
Margin structures compress toward commodity levels in standardized certification testing while widening in exploratory research applications where spectral programmability commands premium positioning.
- Materials Testing:Accelerated degradation protocols for photovoltaic modules, encapsulants, and backsheets under controlled UV exposure. Gigawatt-scale factories in China's Zhejiang province operate dedicated aging chambers for IEC-compliant batch qualification, with service contracts structured around uptime guarantees rather than per-incident repair.
- Biological Research:Photobiology studies examining cellular responses to specific UV wavelengths, requiring precise irradiance control below dermatological damage thresholds. Japanese university medical schools and agricultural research stations procure specialized units with biological sample holders and temperature-controlled environments.
- Environmental Testing:Corrosion acceleration and polymer weathering studies that combine UV exposure with thermal cycling and humidity control. Automotive and construction material suppliers in Germany utilize these for exterior component validation.
- Product Development:Pre-commercial screening of new photovoltaic architectures and encapsulation materials. Research divisions of tier-one module manufacturers in Japan operate hybrid facilities combining benchtop LED systems for early-stage screening with xenon-arc chambers for final certification.
Materials Testing dominates revenue contribution. Biological Research claims the steepest expansion trajectory.
End User:
Procurement authority fragmentation between R&D and quality engineering functions creates dual-vendor relationships at single facilities, with research groups specifying technical performance while production departments dictate compliance documentation requirements.
- Research Laboratories:Corporate and government facilities conducting fundamental materials science and next-generation cell development. METI-funded renewable energy centers in Japan specify redundant pyrometer validation and traceable calibration references that extend commissioning timelines.
- Universities:Academic materials science and engineering departments with constrained capital budgets and high student throughput requirements. Chinese university procurement favors LED architectures for lower operational costs and elimination of mercury-bearing consumables.
- Material Manufacturers:Producers of encapsulants, backsheets, and junction box materials requiring in-house qualification before customer submission. German chemical suppliers maintain aging chambers for internal validation against IEC spectral weighting requirements.
- Testing Agencies:Third-party certification bodies performing independent module qualification for market access. These organizations require simulators with documented traceability to national metrology institutes and multi-standard calibration capabilities spanning IEC, GB/T, and JIS protocols.
Research Laboratories account for the largest installed base. Universities are climbing the fastest.
Technology:
Supply concentration in short-arc lamp manufacturing creates input vulnerability for legacy architectures, while solid-state alternatives face calibration expertise bottlenecks in spectral matching below 300nm.
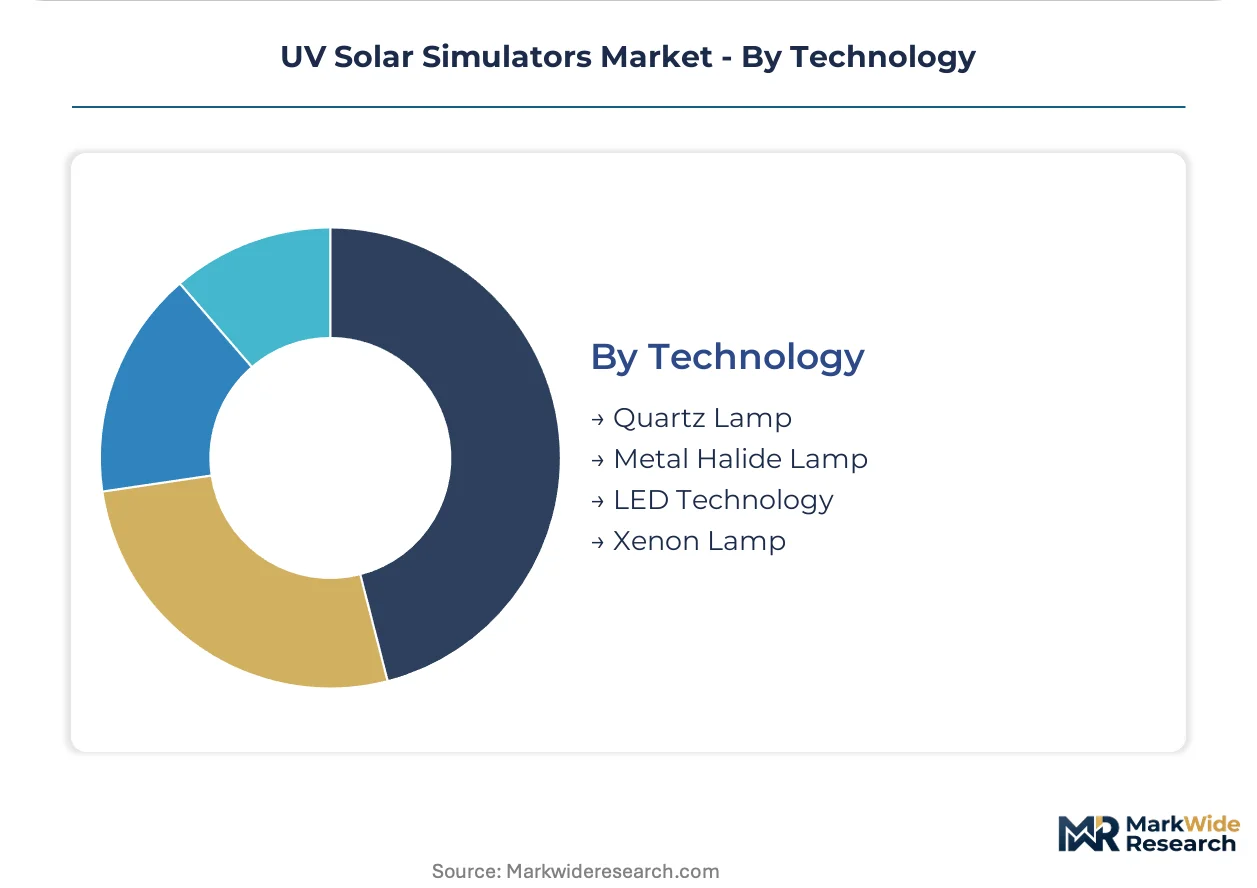
- Xenon Lamp:Short-arc gas discharge lamps producing continuous spectra across 200–2500nm with filtered output matching AM 1.5G weighting. Newport Corporation dominates supply for IEC-compliant aging chambers through its Newport-Oriel portfolio, though German and Japanese lamp manufacturing concentration creates supply risk.
- LED Technology:Solid-state emitters with discrete wavelength selection and electronic intensity control. Perovskite-silicon tandem sensitivity to sub-300nm wavelengths that existing IEC protocols do not address is opening replacement demand in academic settings previously served by lamp-based systems.
- Metal Halide Lamp:Mercury-bearing arc lamps with strong UV-B and UV-C output for aggressive acceleration factors. RoHS and REACH restrictions on mercury disposal are elevating total cost of ownership and accelerating phase-out in European installations.
- Quartz Lamp:Tungsten-halogen or deuterium sources with specialized UV transmission envelopes for specific wavelength bands. Niche applications in semiconductor photoresist testing and specialized photobiology studies maintain limited demand.
Xenon Lamp retains the largest installed base. LED Technology is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's GB standards and Japan's METI directives anchor regulatory frameworks across East Asia, where photovoltaic manufacturing clusters drive concentrated procurement of IEC-compliant aging equipment.
China
Gigawatt-scale module factories in Jiangsu and Zhejiang provinces require continuous-batch UV aging chambers for GB/T 9535 certification. The national standard incorporates UV exposure clauses equivalent to IEC mandates, compelling alignment across multiple certification regimes. Suzhou-based testing agencies now specify simulators with documented traceability for third-party module qualification.
Japan
METI's renewable energy equipment testing directives tighten irradiance monitoring tolerances for grid-connected approvals. Research laboratories at METI-funded renewable energy centers specify redundant pyrometer validation that extends commissioning timelines. Osaka and Nagoya host hybrid facilities combining benchtop LED systems with xenon-arc chambers for final certification.
Germany
RoHS and REACH restrictions on mercury-bearing consumables accelerate phase-out of legacy metal halide architectures in European installations. German chemical suppliers maintain aging chambers for internal validation against IEC spectral weighting requirements. Munich and Stuttgart house field service organizations utilizing portable units for on-site module qualification.
United States
EPA compliance frameworks influence disposal protocols for mercury-bearing simulator consumables in institutional settings. Research universities prioritize LED architectures to eliminate hazardous waste burdens and reduce operational costs. California and Massachusetts materials science departments lead procurement volume for perovskite screening equipment.
South Korea
MFDS-equivalent testing protocols for renewable energy components incorporate IEC-aligned UV preconditioning sequences. Domestic module manufacturers invest in qualification infrastructure to serve export markets requiring multi-standard calibration. Gyeonggi-do province clusters house production facilities installing dedicated aging chambers for continuous batch testing.
UV Solar Simulators Market Competitive Landscape
Capability concentration sits with optical calibration specialists; scale advantage sits with lamp portfolio incumbents. The vendor base organizes around three archetypes: xenon-arc system builders with legacy IEC chamber dominance, LED architecture specialists capturing academic replacement cycles, and precision calibration service providers anchoring third-party certification relationships. Competitive moves concentrate on spectral engine diversification and multi-standard calibration service expansion.
Within the optical calibration tier, OAI anchors third-party certification body relationships through precision services. Among lamp-portfolio incumbents, Newport Corporation exemplifies xenon-arc supply concentration for aging chamber applications. LED architecture specialists include Abet Technologies, which occupies a position in solid-state simulator provision for university laboratory settings.
| Leading Market Players |
|---|
| Newport Corporation |
| Abet Technologies, Inc. |
| OAI (Optical Associates Inc.) |
| Solar Light Company, LLC |
| Sciencetech, Inc. |
| Wacom Electric Co., Ltd. |
| Asahi Spectra Co., Ltd. |
| Iwasaki Electric Co., Ltd. |
| Gsolar Power Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shanghai-to-Rotterdam container freight corridors impose cost volatility that amplifies price spreads between xenon-arc system builders and LED architecture specialists, with supply concentration in German and Japanese lamp manufacturing tightening margin structures for legacy technologies while programmable solid-state alternatives capture pricing power through spectral customization.
Pricing Analysis
Geographic price spreads between European and East Asian procurement run 15-25% for equivalent IEC-compliant chambers, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. Xenon-arc systems with integrated traceable calibration references command premium positioning against benchtop LED units sold to Chinese universities. Pricing pressure stems from mercury disposal compliance costs elevating total cost of ownership for metal halide architectures. University laboratories exhibit highest price sensitivity, while Japanese module manufacturers prioritize uptime guarantees over unit economics.
Supply Chain Analysis
Upstream feedstock concentration in xenon short-arc lamp manufacturing centers on Germany and Japan, with optical filter substrates drawing from specialized glass foundries in Schott AG's supply network and Japanese precision optics houses. Critical dependencies span high-purity xenon gas, fused silica envelopes, and spectroradiometric calibration standards traceable to national metrology institutes. Single-source vulnerability concentrates in pyrometer validation equipment required by METI directives. Distribution runs through direct OEM relationships for production-scale chambers and academic distributors for benchtop research systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
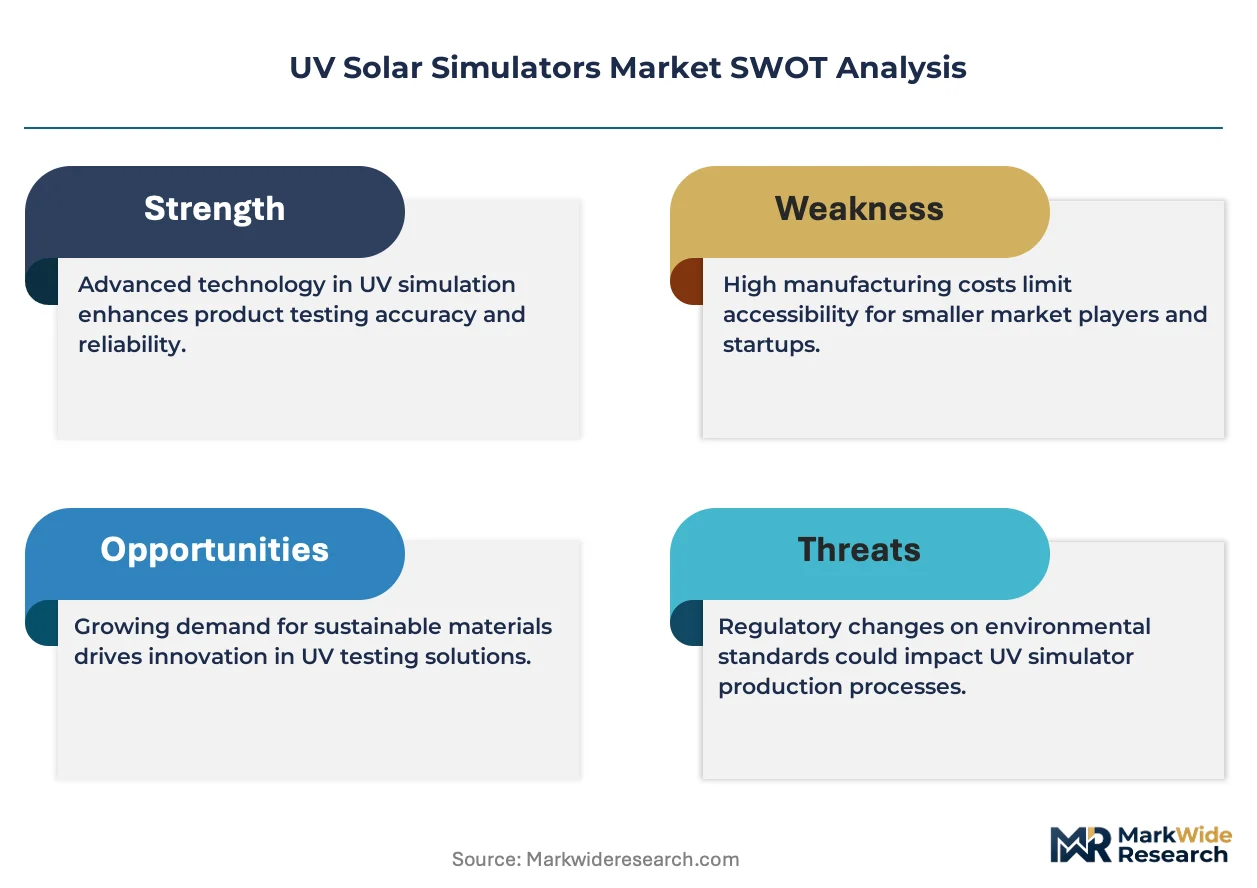
This market functions as a regulatory-entrenchment defensive moat, where IEC 61215/61646 certification requirements and METI irradiance monitoring tolerances create switching costs that protect incumbent optical calibration relationships and lamp-portfolio positions.
For Market Incumbents: Pre-empt LED architecture displacement in academic segments by acquiring solid-state spectral tuning capabilities before Chinese university procurement fully transitions away from xenon-arc systems. Defend certification-body relationships through multi-standard calibration service expansion covering GB/T 9535 alignment, while adding redundant pyrometer validation to chamber specifications in anticipation of METI directive tightening. Lamp supply concentration in Germany and Japan represents the critical vulnerability requiring backward integration or long-term offtake agreements. For New Entrants and Emerging Players: Build out sub-300 nm capable LED systems targeting perovskite-silicon tandem sensitivity that existing IEC protocols do not address, capturing replacement demand in Japanese METI-funded research centers. University laboratories in China offer the most penetrable white space, with procurement authority fragmenting toward research groups specifying technical performance independently from quality engineering. A calibration-service-first go-to-market angle bypasses capital-intensive chamber manufacturing while anchoring third-party certification body relationships. For Investors and Strategic Acquirers: Precision optical calibration specialists with documented traceability to national metrology institutes present the most compelling acquisition target archetype, given their anchor position in third-party certification workflows and scarcity of spectroradiometry expertise. Long-term viability hinges on spectral engine diversification capability across the analysis window. The signal to monitor is divergence between regional spectral weighting definitions as next-generation cell architectures introduce sensitivity below 300 nm.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Calibration Service Expansion | GB/T 9535 alignment capabilities capture Chinese third-party certification body procurement as Jiangsu testing agencies upgrade traceability requirements. |
| LED Architecture Acquisition | Programmable spectral tuning capabilities address perovskite tandem screening demand displacing legacy xenon-arc units in university laboratories. |
| Xenon Lamp Supply Agreement | Long-term offtake contracts with German and Japanese short-arc manufacturers mitigate input vulnerability for IEC-compliant aging chamber production. |
| Sub-300 nm System Development | Wavelength-specific degradation studies for next-generation cells open premium positioning as existing IEC protocols lag technological requirements. |
| Redundant Pyrometer Integration | METI irradiance monitoring tolerance tightening extends commissioning timelines, favoring vendors with integrated traceable calibration references. |
Research Methodology
A standing panel of optical calibration engineers, photovoltaic module quality directors, university materials science procurement officers, and third-party certification body technical managers provided ongoing calibration against secondary validation from IEC standard documentation, METI directive filings, Chinese GB/T standard publications, and SEC filings from listed test equipment manufacturers. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis and equipment import records.
Scenario-bracketing framed low, base, and high cases across the projection horizon, with segmentation dimensions spanning product format, optical engine technology, application vertical, and end-user procurement authority structure. CAGRs derived from installed base replacement cycles, academic research funding trajectories, and gigawatt-scale factory expansion timelines in Jiangsu and Zhejiang provinces. Forecast inputs incorporated perovskite-silicon tandem commercialization pace and divergence between regional spectral weighting definitions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese LED architecture specialists or German lamp manufacturers pursuing vertical integration would shift outcomes substantially. Cross-checking against IEC standard revision timelines and METI directive implementation schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Solar Panel Tracking Mount Market
Solar Power Systems
US Solar Carport Market
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Ghana Solar Energy Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
United States Fixed-Tilt Solar PV Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Distributed Solar Power Generation System Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Chile Renewable Energy Market