
 Asia Pacific Solar Backsheet Market | 2026-2036
Asia Pacific Solar Backsheet Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Solar Backsheet Market Outlook
A shift from imported fluoropolymer films toward domestic multi-source supply is restructuring procurement economics across the Asia Pacific solar backsheet value chain. Jolywood Solar Technology Co., Ltd. leverages captive fluorine chemistry capabilities to anchor cost positions in high-efficiency bifacial modules. Hangzhou First Applied Material Co. Ltd competes through integrated PET film and adhesive operations that sustain margin capture across the laminate stack. Toray Industries Inc differentiates via polyimide and advanced polymer R&D pipelines that extend performance thresholds for harsh-climate installations.
The Asia Pacific solar backsheet constitutes a multi-layer polymer laminate, typically 250–350 micrometers thick, engineered to shield photovoltaic modules from moisture ingress, ultraviolet degradation, and electrical insulation failure while ensuring thermal stability across -40°C to +85°C operational ranges. Polyester-based constructions dominate volume shipments due to cost scalability and established lamination compatibility with crystalline silicon modules. Fluoropolymer-skinned laminates occupy premium tier positioning where 25-year performance warranties and desert or coastal climate exposure justify material cost premiums. Polyethylene formulations are gaining traction in floating solar installations across Thailand and Vietnam where hydrolysis resistance determines product selection.
China's MIIT enforces GB standards for photovoltaic backsheet mechanical and electrical durability, while India's BIS certification mandates localize testing protocols that condition import access. Japan's METI JIS standards and South Korea's MFDS alignment with IEC 62788-2-1 create a fragmented compliance landscape that elevates certification costs for pan-regional suppliers. Stakeholders must monitor evolving national content requirements and carbon footprint disclosure rules that will determine qualification for government-backed solar auctions across the region.
Market Dynamics
China's dual carbon goals and India's PLI scheme for solar module manufacturing are compressing import dependency timelines and forcing rapid localization of fluoropolymer and co-extruded backsheet supply chains across the Asia Pacific.
Growth Catalysts
- India's PLI scheme:Production-linked incentives for solar module manufacturing are pulling backsheet procurement volumes toward domestic integrated PV clusters in Gujarat and Tamil Nadu.
- Floating solar proliferation:Hydrolysis-resistant polyethylene backsheet formulations are capturing procurement share across Thailand and Vietnam reservoir installations.
- Utility-scale procurement:Southeast Asian IPPs and Indian renewable energy developers are consolidating specification power around 25-year performance warranties.
Market Restraints
- Fluoropolymer feedstock concentration:PTFE and PVDF resin supply concentrates among Chinese chemical conglomerates, exposing laminators to input cost volatility and allocation risk.
- BIS certification timelines:India's Bureau of Indian Standards mandates localized testing protocols that extend product qualification cycles by 8-14 months for non-domestic suppliers.
- Co-extruded PET substitution:Lower-cost fluorine-free constructions are compressing margin pools for premium fluoropolymer-skinned laminates in price-sensitive distributed solar segments.
Strategic Opportunities
- Vietnam manufacturing:Underdeveloped domestic backsheet capacity creates white space for integrated PET film and adhesive operations serving ASEAN export markets.
- Agrivoltaic convergence:Bifacial module specifications demanding enhanced mechanical durability are opening specification windows for advanced polyimide hybrid laminates.
- Carbon footprint disclosure mandates:South Korea's alignment with IEC lifecycle standards and emerging Chinese MEE rules are creating first-mover advantage for low-carbon resin sourcing.
Industry Challenges
- Fluorine chemistry talent scarcity:Captive resin production capabilities require polymer scientists and process engineers concentrated among Japanese and Korean industrial conglomerates.
- Multi-jurisdiction certification burden:Simultaneous compliance with China's GB standards, India's BIS, and Japan's METI JIS protocols fragments product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Solar Backsheet Market |
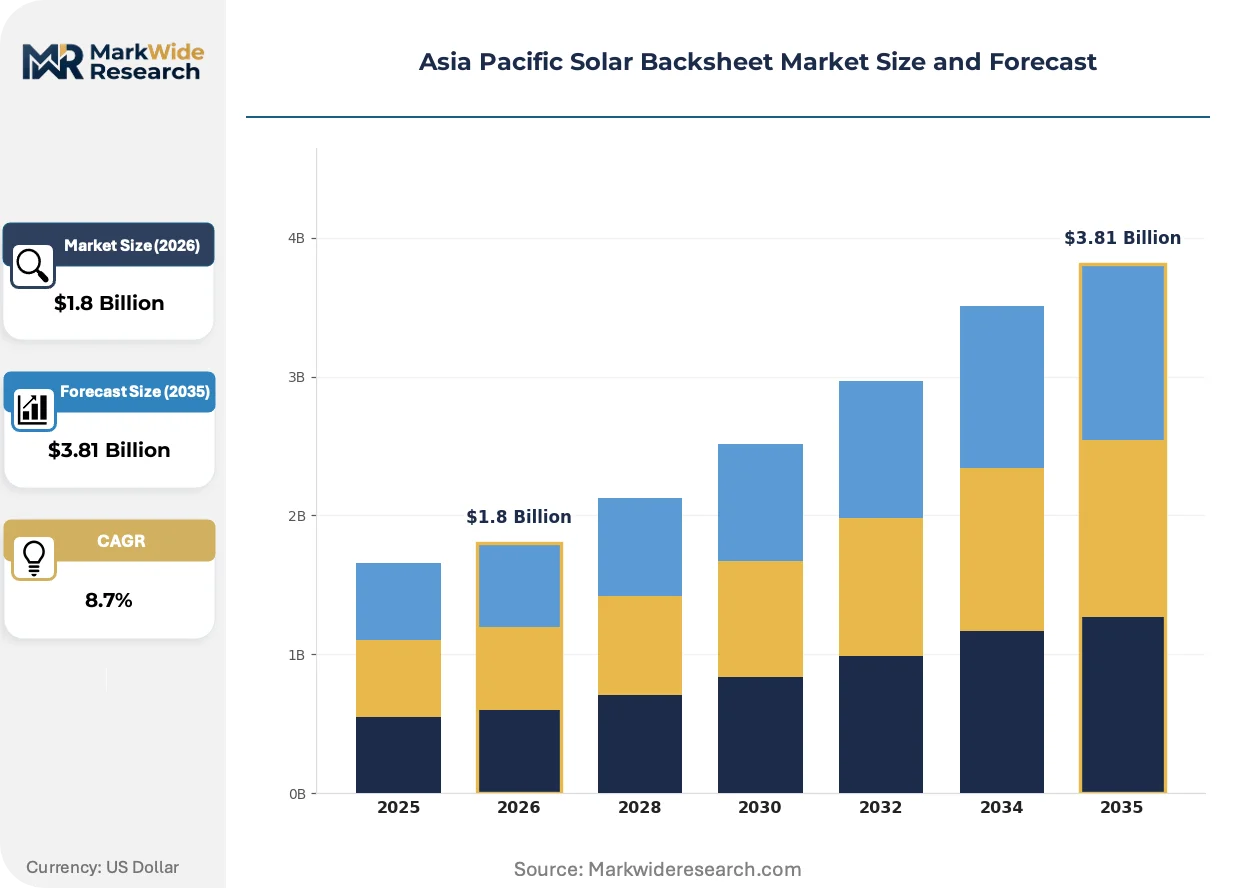
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Polyvinyl Fluoride, Polyethylene, Others Installation Type: Roof Mounted, Ground Mounted, Building Integrated, Floating End User: Residential, Commercial, Industrial, Utility Thickness: Thin Film, Standard, Heavy Duty, Ultra-thin |
| Companies Covered | Jolywood Solar Technology Co., Ltd., Hangzhou First Applied Material Co. Ltd, Toray Industries Inc, Arkema SA, Cybrid Technologies Inc., Toyo Aluminium KK, Taiflex Scientific Co. Ltd, 3M Co., DuPont de Nemours Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Solar Backsheet Market Strategic Shifts
Active materials R&D and procurement model compression are restructuring how backsheet specifications get locked into module supply agreements across the Asia Pacific solar value chain.
Co-extruded fluoropolymer-free laminates are decentralizing specification authority away from traditional premium-tier suppliers toward integrated module manufacturers with captive polymer compounding capabilities. JinkoSolar and LONGi are accelerating internal qualification of PET-based constructions for their bifacial product lines. This technology shift is decentralizing margin capture from specialized backsheet producers to vertically integrated module giants.
China's MIIT enforcement of updated GB/T 31034 photovoltaic backsheet standards is mandating accelerated UV-aging and damp-heat test protocols. The industrial consequence is disqualification of legacy adhesive formulations and accelerated qualification timelines for fluorine-modified ethylene copolymers. Jiangsu and Zhejiang province module clusters are responding by consolidating supplier lists around domestic laminators with in-house resin synthesis.
Direct procurement relationships between utility-scale developers and backsheet manufacturers are compressing distributor and trading house intermediation. Indian renewable energy IPPs and Vietnamese project sponsors are establishing multi-year offtake agreements that bypass traditional module-integrated sourcing. This channel disintermediation is most visible in Maharashtra and Karnataka, where Adani Green and Azure Power are qualifying backsheet suppliers independently of their module OEM relationships.
Asia Pacific Solar Backsheet Market Segmentation
Backsheet specification directly determines certification pathways and warranty eligibility across Asia Pacific solar procurement. Module OEMs and project developers segment demand by polymer chemistry, mechanical durability, and installation environment to align with BIS, MIIT GB standards, and IEC 62788-2-1 protocols.
Product Type:
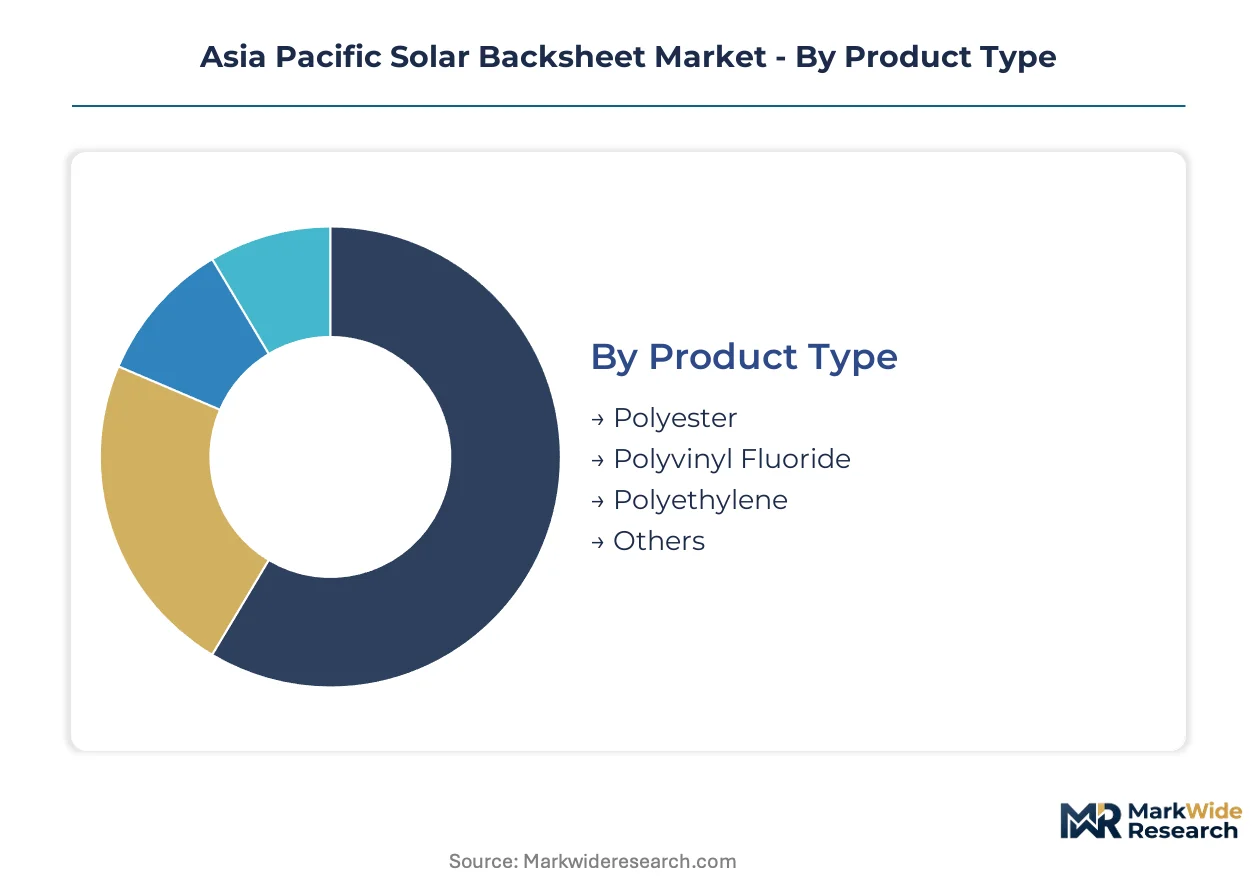
Fluoropolymer-skinned laminates require BIS laboratory testing in India and MIIT GB/T 31034 compliance in China, while fluorine-free PET constructions face accelerated qualification under updated damp-heat protocols.
- Polyester:PET-based multi-layer laminates dominate procurement volumes through cost scalability and lamination compatibility with crystalline silicon modules. Jiangsu and Zhejiang province module clusters consolidate sourcing around domestic laminators with captive resin synthesis capabilities.
- Polyvinyl Fluoride:PVDF-skinned constructions occupy premium tier positioning where 25-year performance warranties and desert or coastal climate exposure justify material cost premiums. Indian renewable energy IPPs in Gujarat and Rajasthan specify these for utility-scale installations.
- Polyethylene:Hydrolysis-resistant formulations capture procurement share across Thailand and Vietnam floating solar reservoir installations where moisture ingress resistance determines product selection.
- Others:Polyimide hybrid laminates address bifacial module specifications demanding enhanced mechanical durability for agrivoltaic convergence applications.
Polyester sits at the top of the volume ranking, with polyethylene climbing the fastest.
Installation Type:
Ground-mounted arrays concentrate procurement scale and compress per-watt backsheet costs through standardized specifications, while floating installations impose specialized hydrolysis resistance requirements that fragment supplier qualification.
- Roof Mounted:Distributed solar segments in India and Southeast Asia drive demand for cost-optimized fluorine-free PET constructions. Price sensitivity among residential installers compresses margin pools for premium fluoropolymer-skinned laminates.
- Ground Mounted:Utility-scale solar farms across India and Southeast Asia consolidate specification power around 25-year performance warranties and direct multi-year offtake agreements with backsheet manufacturers.
- Building Integrated:Aesthetic and fire-safety requirements from Japan's METI and South Korea's MFDS alignment with IEC standards create specialized qualification windows for advanced polymer constructions.
- Floating:Reservoir installations in Thailand and Vietnam mandate hydrolysis-resistant polyethylene formulations that extend operational lifespans under continuous moisture exposure conditions.
Ground mounted commands the largest procurement volumes, with floating solar expanding most quickly.
End User:
Utility-scale developers wield direct specification authority through independent supplier qualification, while residential and commercial segments route procurement through module OEM channels.
- Residential:Distributed solar installations across India and Southeast Asia prioritize cost-optimized PET-based constructions. Price-sensitive procurement compresses specification requirements toward standard durability tiers.
- Commercial:C&I rooftop projects in Maharashtra and Karnataka balance performance warranties against capital expenditure constraints through mid-tier fluoropolymer-skinned laminates.
- Industrial:Self-consumption solar arrays at manufacturing facilities specify enhanced mechanical durability for harsh operational environments.
- Utility:Indian IPPs and Vietnamese project sponsors establish direct procurement relationships with backsheet manufacturers, bypassing traditional module-integrated sourcing channels entirely.
Utility end users generate the steepest revenue concentration, with commercial installations gaining share fastest.
Thickness:
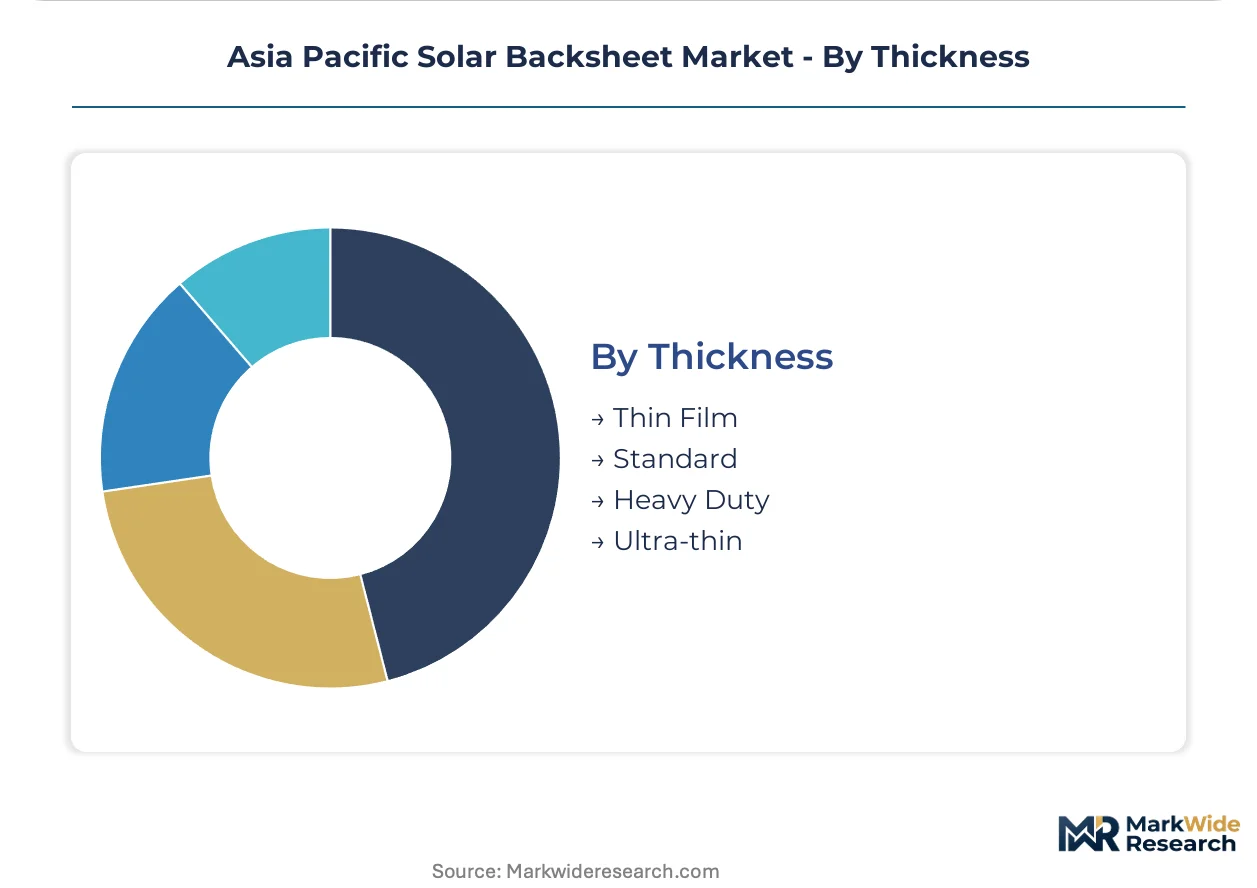
Standard and heavy-duty constructions align with mainstream crystalline silicon module specifications, while ultra-thin variants address emerging lightweight and flexible substrate applications.
- Thin Film:Reduced-thickness laminates serve specialized applications where weight reduction and flexibility outweigh mechanical durability requirements.
- Standard:250–350 micrometer constructions dominate volume shipments through established lamination compatibility and cost scalability across integrated PV component clusters.
- Heavy Duty:Enhanced-thickness formulations address bifacial module specifications and agrivoltaic installations demanding superior mechanical durability under agricultural operational stresses.
- Ultra-thin:Experimental constructions target emerging flexible substrate and building-integrated applications requiring radical weight reduction.
Standard thickness captures the dominant procurement share, with heavy duty showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor procurement volumes for the Asia Pacific solar backsheet market, where integrated PV component clusters operate at scale and domestic laminators consolidate supplier relationships around captive resin synthesis capabilities.
China
Utility-scale solar farms across Inner Mongolia and Qinghai drive bulk procurement of fluoropolymer-skinned laminates. MIIT enforces updated GB/T 31034 standards that mandate accelerated UV-aging test protocols. Eastern province module clusters in Jiangsu and Zhejiang are consolidating supplier lists around domestic laminators with in-house fluorine chemistry capabilities.
India
Production-linked incentives for solar module manufacturing are pulling backsheet procurement toward integrated PV clusters in Gujarat and Tamil Nadu. BIS certification mandates localized testing protocols that extend product qualification cycles for non-domestic suppliers. Maharashtra and Karnataka project sponsors are establishing direct multi-year offtake agreements with backsheet manufacturers.
Japan
Building-integrated and agrivoltaic installations create specialized demand for advanced polymer constructions with enhanced mechanical durability. METI JIS standards alignment with IEC protocols elevates certification requirements for imported laminates. Kanto and Kansai industrial corridors concentrate R&D-intensive backsheet development for harsh-climate premium applications.
Vietnam
Floating solar reservoir installations mandate hydrolysis-resistant polyethylene formulations that extend operational lifespans under continuous moisture exposure. Underdeveloped domestic backsheet capacity creates white space for integrated PET film operations serving ASEAN export markets. Southern province project sponsors are qualifying suppliers independently of module OEM channels.
Thailand
Utility-scale renewable energy developers specify 25-year performance warranties that compress procurement toward premium-tier fluoropolymer constructions. Hydrolysis-resistant backsheet demand concentrates at floating solar installations across northeastern reservoir complexes. Eastern seaboard industrial zones host emerging laminate assembly operations targeting regional distribution.
Asia Pacific Solar Backsheet Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue co-extruded fluoropolymer-free constructions and captive resin synthesis capabilities. The vendor base stratifies across three tiers: integrated chemical conglomerates with captive fluorine chemistry, specialized laminators with backward PET film operations, and regional trading houses facing channel disintermediation. Three strategic archetypes dominate: vertically integrated module manufacturers internalizing backsheet qualification, domestic Chinese laminators leveraging GB standard alignment, and Japanese-Korean industrial groups deploying advanced polymer R&D. Competitive intensity centers on capacity expansion in Vietnam and strategic partnerships for BIS certification facilitation in India.
Among Chinese producers, Jolywood Solar Technology Co., Ltd. and Hangzhou First Applied Material Co., Ltd. exemplify the integrated laminator archetype with positions spanning resin synthesis through module supply relationships. Toray Industries Inc. occupies a position within the advanced materials tier, representing Japanese industrial conglomerate investment in polyimide and specialty polymer pipelines. These three entities anchor distinct competitive vectors: cost-optimized domestic supply, integrated PET-adhesive operations, and premium-performance harsh-climate formulations.
| Leading Market Players |
|---|
| Jolywood Solar Technology Co., Ltd. |
| Hangzhou First Applied Material Co. Ltd |
| Toray Industries Inc |
| Arkema SA |
| Cybrid Technologies Inc. |
| Toyo Aluminium KK |
| Taiflex Scientific Co. Ltd |
| 3M Co. |
| DuPont de Nemours Inc |
| Others |
Value Chain & Pricing Dynamics
South Korea's alignment with IEC lifecycle standards and emerging Chinese MEE carbon footprint disclosure rules gate qualified supply and premium-tier pricing access for low-carbon resin sourcing, compressing margin pools for non-compliant laminators while elevating cost positions for first-movers with certified low-carbon footprints.
Pricing Analysis
Input-cost pass-through from fluoropolymer resin volatility anchors pricing dynamics across the laminate stack. Three-tier pricing structure across premium fluoropolymer-skinned, standard PET-based, and economy fluorine-free constructions differentiates by certification grade and volume scale. Pricing pressure stems from co-extruded PET substitution compressing margins in distributed solar segments. Residential installers in India and Southeast Asia exhibit highest price sensitivity, while utility-scale IPPs in Gujarat and Rajasthan absorb premium tiers for 25-year warranty coverage.
Supply Chain Analysis
Certification and qualification gating through China's MIIT GB/T 31034, India's BIS, and Japan's METI JIS fragments supplier access and extends product development cycles. Geographic supply concentrates in China, Japan, and South Korea, with Jiangsu and Zhejiang province clusters anchoring captive resin synthesis capabilities. Raw material dependencies center on PTFE and PVDF fluoropolymer resins, PET film substrates, and adhesive formulations. Single-source vulnerability from Chinese chemical conglomerate resin concentration elevates allocation risk. Distribution runs through direct multi-year offtake agreements between utility-scale developers and laminators, bypassing traditional module-integrated channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific solar backsheet market functions as a stable compounder, with utility-scale solar procurement across India and Southeast Asia providing steady volume foundations that resist cyclical downturns.
For Market Incumbents: To counter co-extruded fluoropolymer-free substitution threatening premium-tier positioning, deepen backward integration into captive fluorine chemistry capabilities and consolidate supplier relationships around in-house resin synthesis. Accelerate qualification timelines for fluorine-modified ethylene copolymers under updated GB/T 31034 protocols to defend specification windows in Jiangsu and Zhejiang province clusters.
For New Entrants and Emerging Players: Floating solar developers across Thailand and Vietnam represent an underserved buyer archetype demanding hydrolysis-resistant polyethylene formulations with limited qualified supply. Target Vietnam's underdeveloped domestic backsheet capacity for integrated PET film and adhesive operations serving ASEAN export markets. Establish direct procurement relationships with reservoir project sponsors independently of module OEM channels.
For Investors and Strategic Acquirers: Roll-up economics work for specialized laminators with backward PET film operations because certification fragmentation across BIS, MIIT GB, and METI JIS protocols creates scale advantages for multi-jurisdiction-qualified platforms. Five-to-ten year viability hinges on carbon footprint disclosure compliance positioning. Watch South Korea's MFDS alignment with IEC lifecycle standards and emerging Chinese MEE rules as inflection indicators for low-carbon resin sourcing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorine Chemistry | Jolywood and Hangzhou First anchor cost positions through captive resin synthesis capabilities. |
| Multi-Jurisdiction Certification Investment | Simultaneous BIS, MIIT GB, and METI JIS qualification expands addressable procurement pools. |
| Vietnam Manufacturing Footprint | Underdeveloped domestic capacity creates white space for ASEAN-serving integrated operations. |
| Direct Developer Offtake Agreements | Adani Green and Azure Power in Maharashtra bypass module OEM channels for backsheet procurement. |
| Low-Carbon Resin Sourcing Program | First-mover positioning under South Korean IEC alignment and Chinese MEE rules captures premium tiers. |
Study Parameters
Coverage spans China, India, Japan, South Korea, Vietnam, and Thailand, with primary inputs from each market combining interviews with module OEM procurement directors, fluoropolymer resin plant managers, utility-scale IPP project developers, BIS and MIIT certification specialists, and PET film operations engineers. Secondary validation draws from MIIT GB standard filings, BIS laboratory test records, IEC 62788-2-1 protocol documentation, customs trade data for fluoropolymer resin imports, and SEC filings of listed laminators. Bottom-up volume builds from project-level procurement data triangulate against top-down market sizing from integrated PV cluster production statistics.
Rate-of-change decomposition separates volume growth from value expansion across the projection horizon. Segmentation dimensions modeled include polymer chemistry tier, installation environment specification, end-user procurement channel, and regional regulatory framework cluster. CAGRs derive from polynomial trend fitting of historical procurement volumes adjusted for policy incentive phase-outs and technology substitution curves. Industry-specific forecast inputs incorporate PLI scheme capacity addition timelines in Gujarat and Tamil Nadu and floating solar reservoir development pipelines across Thailand and Vietnam.
Underlying measurement precision varies by segment; utility-scale ground-mounted installations carry tighter precision than emerging floating solar applications due to consolidated procurement data availability. Forecasts reflect assumptions around BIS certification timeline stability, fluoropolymer resin supply allocation continuity, and carbon footprint disclosure rule implementation schedules. A model refresh is warranted upon material change in India's PLI scheme disbursement rates or China's MEE enforcement intensity for backsheet lifecycle carbon reporting.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
Solar Powered Elevator Market
Solar Power Systems
Off-Grid Solar Lighting Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Solar Thermal Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Dual Axis Solar Tracker Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Non-Concentrating Solar Collector Market
Solar Power Systems
Bifacial Solar Panels Market
Solar Power Systems
Asia-Pacific Bifacial Solar Market
Solar Power Systems
Asia-Pacific Rooftop Solar Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Alternative Solar Photovoltaic Technologies Market