
 Belgium Solar Energy Market | 2026-2036
Belgium Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Solar Energy Market Analysis
Modular battery-solar bundling is expanding buyer choice across Belgian commercial and residential segments. Engie Electrabel leverages its utility-scale development pipeline to anchor large-scale hybrid project deployment. EDF Luminus competes through regional grid-balancing services tied to its photovoltaic fleet. Ikaros Solar specializes in tailored commercial rooftop systems that navigate complex Flemish and Wallonian permitting variations.
Belgium solar energy encompasses photovoltaic systems converting sunlight into direct-current electricity through semiconductor cells, typically silicon-based modules with peak outputs ranging from 300W to 700W per panel, deployed to offset grid consumption or feed power into distribution networks. Concentrated solar power remains marginal in Belgium's latitude and climate, leaving photovoltaic systems to dominate installed capacity across residential and utility-scale installations. Monocrystalline technology leads the technology segment due to superior efficiency in Belgium's diffuse-light conditions, while energy cooperatives represent the fastest-growing end-user category as Flemish and Wallonian communities pool capital for shared generation assets.
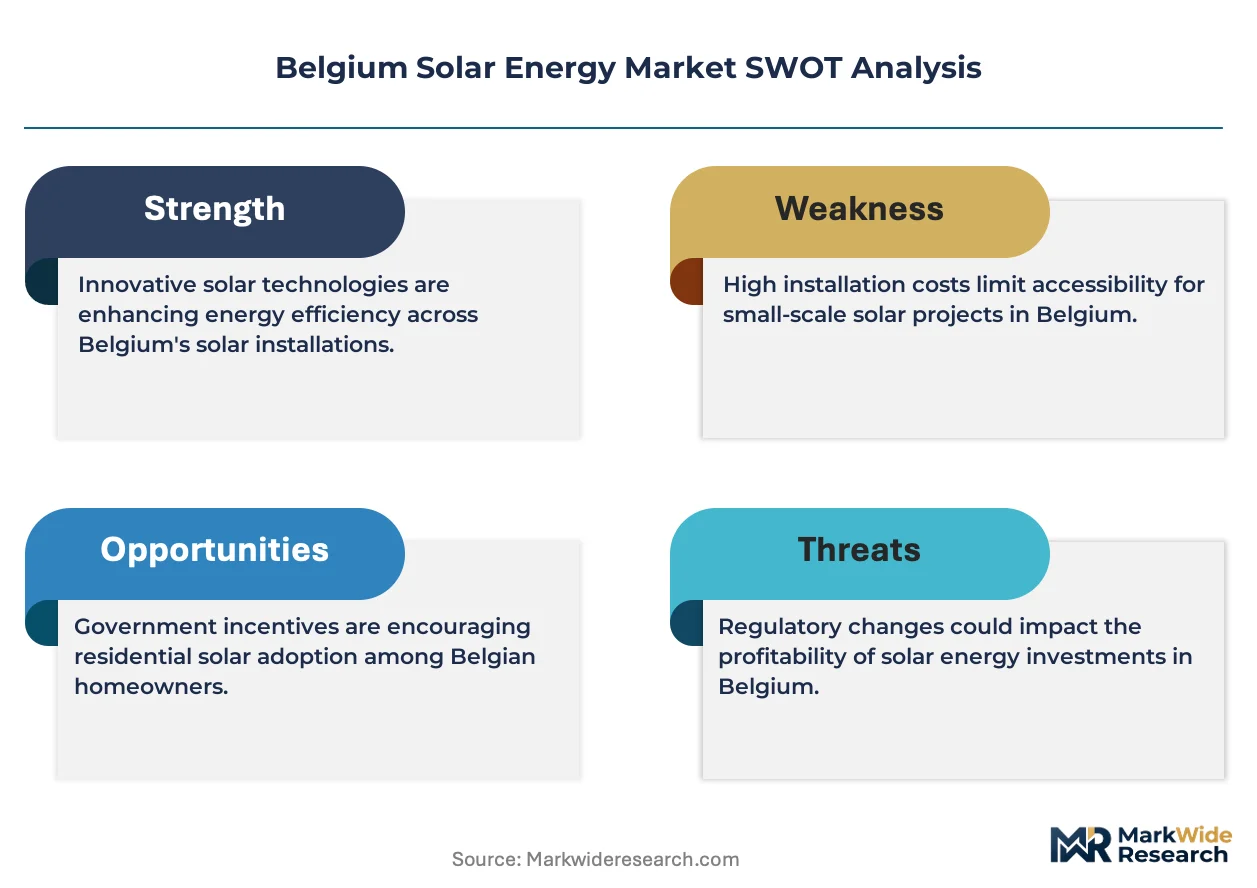
Federal green certificate schemes and regional net-metering frameworks administered by the Flemish Energy and Climate Agency and Walloon public service for energy shape project economics and interconnection queues. CE marking and IEC 61215 certification standards govern module eligibility for subsidy programs, filtering non-compliant suppliers from Belgian procurement channels. Stakeholders must monitor forthcoming capacity-based tariff reforms that will determine whether battery-coupled systems retain economic viability against evolving grid service compensation structures.
Market Dynamics
Flemish net-metering reforms and capacity-based tariff restructuring are compressing project payback periods and redirecting capital toward battery-coupled solar arrays across Belgian commercial and residential segments.
Growth Catalysts
- Walloon green certificate premiums:The region's public service for energy maintains elevated certificate values for installations under 10kW, sustaining residential deployment in Hainaut and Namur provinces.
- East Flanders grid congestion relief:Distribution system operator incentives for behind-the-meter generation reduce interconnection queues for logistics park developers seeking peak demand reduction.
- Monocrystalline PERC efficiency gains:Module outputs reaching 700W per panel cut rooftop space requirements for commercial buildings in dense Flemish urban zones.
Market Restraints
- Polysilicon supply concentration:Belgian developers remain exposed to Xinjiang-sourced silicon supply chain disruptions and associated due diligence compliance costs under EU forced labor regulations.
- Grid interconnection timelines:Elia's transmission upgrade backlog extends project energization dates by 18-24 months for utility-scale sites in Limburg.
- Gas-fired peaker economics:Relatively low natural gas prices in Northwest Europe undercut the grid services revenue case for battery-solar hybrids in wholesale arbitrage markets.
Strategic Opportunities
- Agrivoltaic pilot zones:The Flemish Energy and Climate Agency's 2024 land-use framework opens agricultural parcels in West Flanders for elevated panel installations preserving crop cultivation.
- Energy cooperative aggregation:Community-owned generation pools in Wallonia bypass traditional utility intermediaries through direct peer-to-peer trading platforms.
- Building-integrated photovoltaics:Brussels-Capital Region mandates for near-zero energy buildings create embedded demand for facade-integrated thin-film systems in commercial construction.
Industry Challenges
- Certification timeline compression:CE marking and IEC 61215 testing backlogs at notified bodies delay module eligibility for federal subsidy programs by 8-12 weeks.
- Electrical engineering specialization gaps:Flemish technical colleges produce insufficient inverter commissioning technicians to match deployment velocity in Antwerp port industrial zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Solar Energy Market |
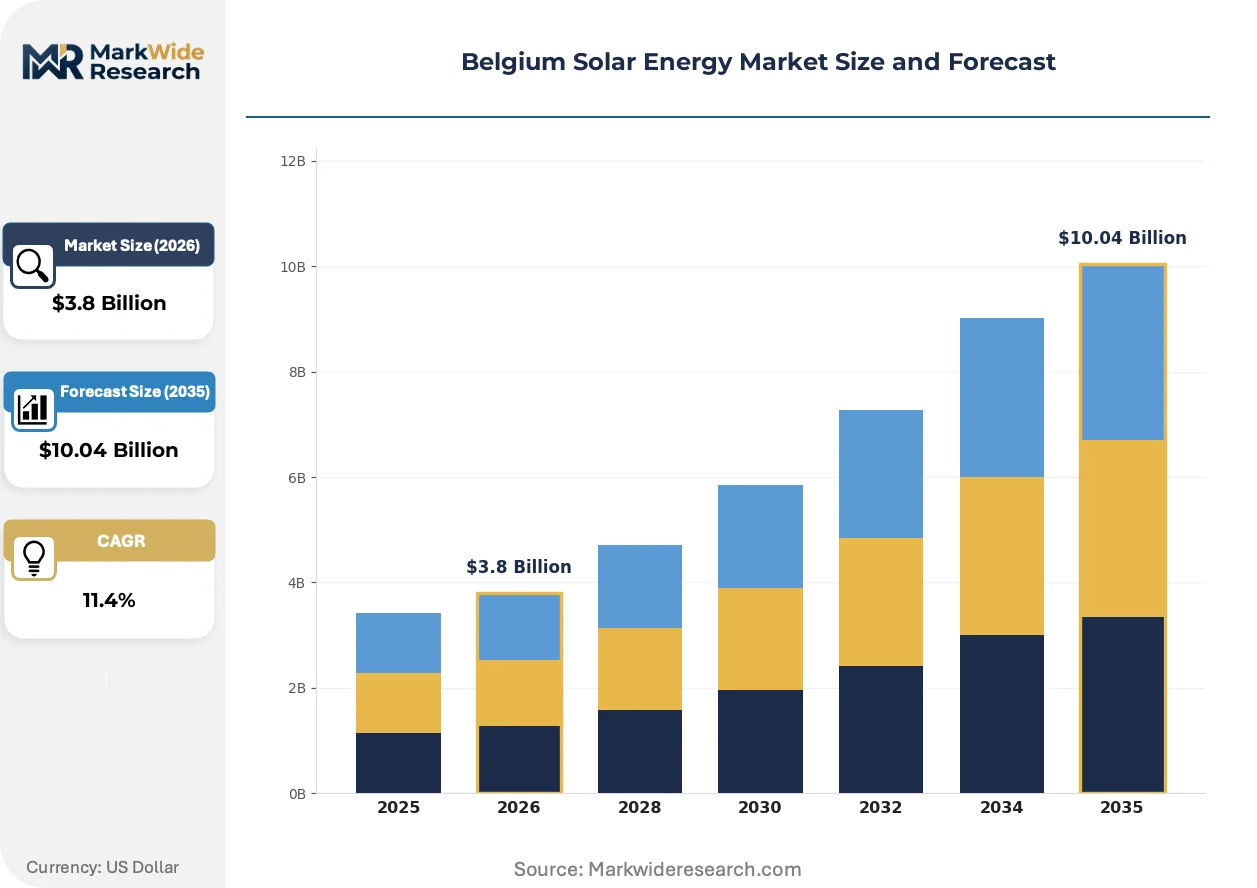
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Photovoltaic, Concentrated Solar Power, Hybrid Systems, BIPV Installation Type: Residential, Commercial, Utility-Scale, Off-Grid End User: Households, Businesses, Public Institutions, Energy Cooperatives Technology: Monocrystalline, Polycrystalline, Thin-Film, Organic Photovoltaics |
| Companies Covered | 7C Solarparken AG, Ikaros Solar, Engie Electrabel, Invictus, ENGIE Fabricom, EDF Luminus, Orka Power, Perpetum Energy, Eneco Belgium, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Solar Energy Market Emerging Trajectories
Technology convergence, regulatory recalibration, and buyer behavior evolution are restructuring how Belgian solar projects are financed, constructed, and operated across residential, commercial, and utility-scale segments.
Bifacial glass-glass modules are overtaking traditional monofacial designs in Belgian commercial rooftop deployments. Logistics operators in Flanders prioritize dual-sided generation to capture diffuse albedo reflection from warehouse roofing membranes. This technology shift is compressing levelized cost thresholds for behind-the-meter installations below grid parity benchmarks.
Brussels-Capital Region's mandatory Building Energy Performance Certificate upgrades are forcing commercial retrofits to incorporate photovoltaic generation. Property owners face 2027 compliance deadlines for Class A ratings. Large-format office buildings in the European Quarter are responding with integrated rooftop and facade systems to avoid rental value penalties.
Energy cooperatives are displacing individual household procurement as the dominant residential acquisition channel. Flemish and Wallonian community associations pool capital through not-for-profit structures to negotiate volume discounts on module and inverter packages. This collective purchasing model concentrates most visibly in Limburg municipalities where municipal energy agencies facilitate group-buying frameworks.
Belgium Solar Energy Market Segmentation
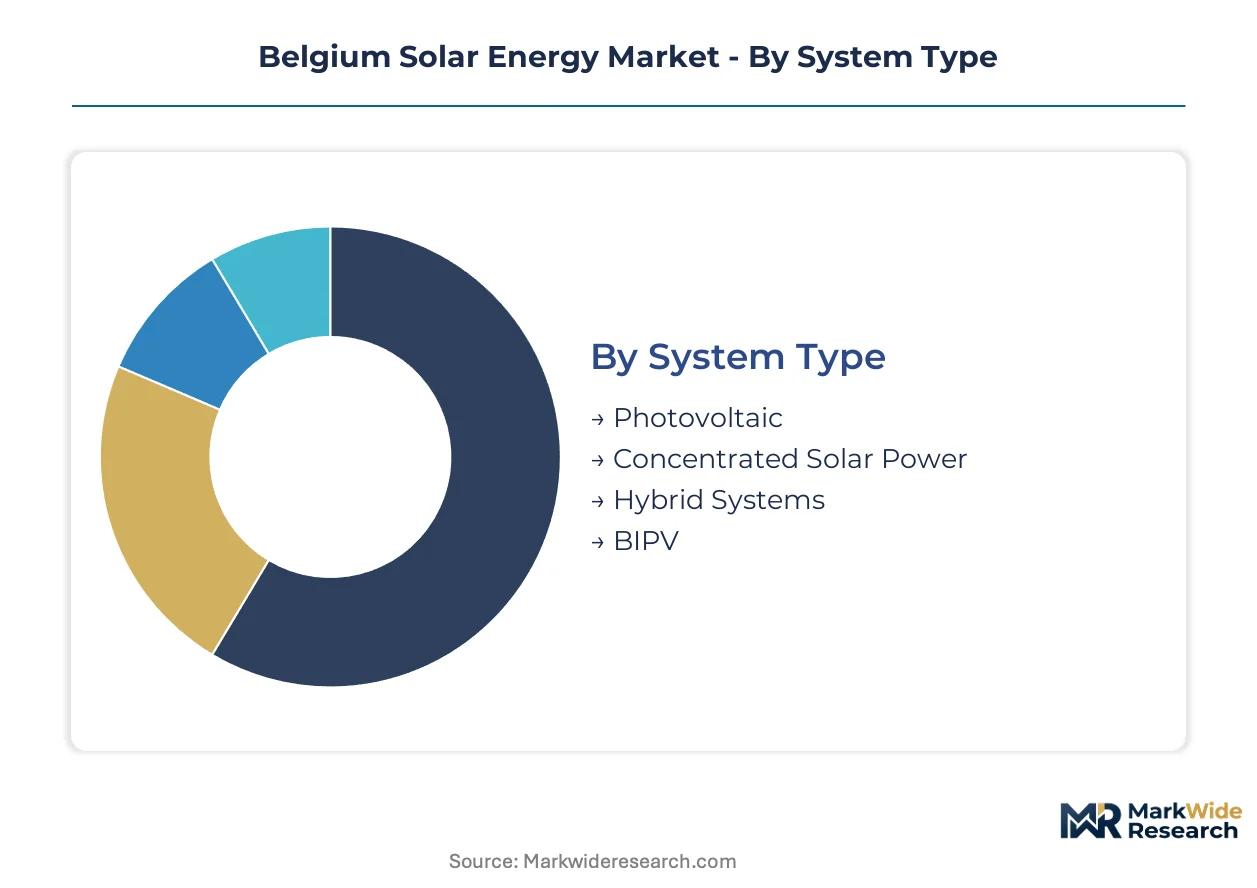
Belgium's solar energy market segments reflect divergent supply chain configurations and regulatory exposure profiles. Each category channels capital toward distinct technology bets and geographic deployment patterns across Flemish, Walloon, and Brussels-Capital jurisdictions.
System Type:
Supply concentration in module manufacturing favors certain system architectures over others in Belgian procurement channels.
- Photovoltaic:Silicon-based semiconductor cells convert sunlight into direct-current electricity through p-n junction physics. Demand clusters in East Flanders and Limburg provinces where distribution system operator incentives reward behind-the-meter generation at logistics parks. CE marking and IEC 61215 certification requirements filter non-compliant suppliers from federal subsidy eligibility.
- Hybrid Systems:Battery-coupled photovoltaic arrays store surplus generation for discharge during peak tariff periods. Federal green certificate reforms and net-metering adjustments redirect investment toward this architecture as pure export economics deteriorate.
- BIPV:Building-integrated photovoltaics embed generation capacity within facade and roofing structural elements.
- Concentrated Solar Power:Parabolic trough and tower configurations using thermal transfer fluids remain marginal at Belgium's latitude.
Today's leader: Photovoltaic. Tomorrow's challenger: Hybrid Systems.
Installation Type:
Application scale determines interconnection queue priority and subsidy access tier across Belgian regions.
- Commercial:Rooftop and ground-mounted systems serving business electricity loads with peak demand reduction contracts. Flemish logistics parks in Antwerp port industrial zones drive deployment velocity as monocrystalline PERC modules reach 700W outputs.
- Residential:Distributed generation assets offsetting household grid consumption through net-metering frameworks. Walloon green certificate premiums for installations under 10kW sustain deployment in Hainaut and Namur provinces.
- Utility-Scale:Grid-connected solar farms feeding bulk power into transmission networks.
- Off-Grid:Standalone systems with battery storage serving locations without distribution network access.
Commercial installations command current capital flows. Residential segments are expanding most quickly through energy cooperative aggregation models.
End User:
Customer type shapes financing structures and regulatory compliance obligations under regional energy agency administration.
- Energy Cooperatives:Community-owned not-for-profit structures pooling capital for shared generation assets. Limburg municipalities facilitate group-buying frameworks that negotiate volume discounts on module and inverter packages.
- Businesses:Corporate offtakers seeking electricity cost stabilization and sustainability commitments. Brussels-Capital Region mandates for near-zero energy buildings force commercial retrofits to incorporate photovoltaic generation.
- Households:Individual residential prosumers participating in net-metering schemes.
- Public Institutions:Government and municipal buildings deploying solar under public procurement frameworks.
Energy cooperatives show the steepest expansion trajectory. Businesses retain the largest absolute deployment volumes.
Technology:
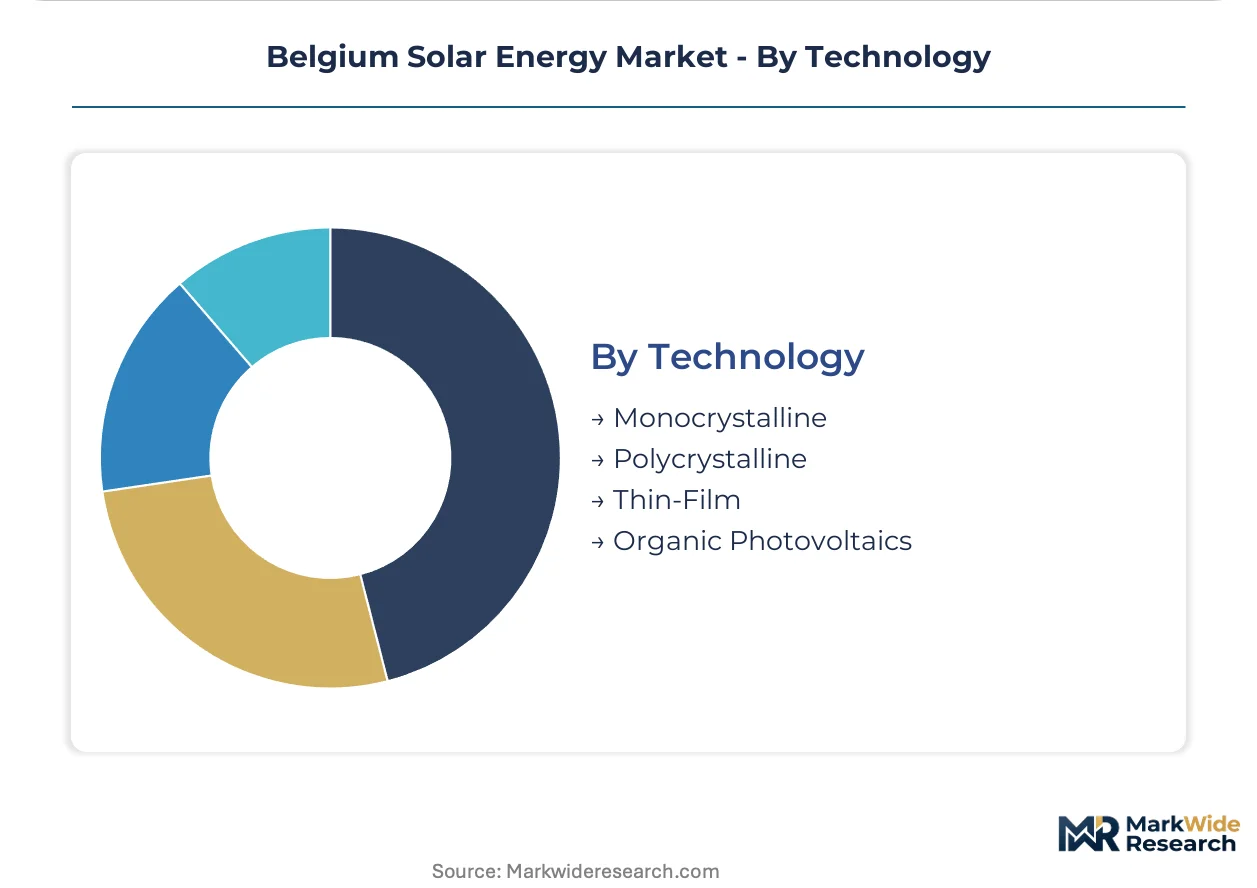
Cell architecture selection responds to Belgium's diffuse-light climate conditions and rooftop space constraints.
- Monocrystalline:Single-crystal silicon wafers delivering superior conversion efficiency under low-irradiance conditions. Bifacial glass-glass variants capture albedo reflection from warehouse roofing membranes in Flemish commercial deployments.
- Thin-Film:Cadmium telluride and copper indium gallium selenide layers deposited on flexible substrates. Brussels-Capital Region facade integration mandates create embedded demand for lightweight building-integrated configurations.
- Polycrystalline:Multi-crystal silicon cells with lower manufacturing cost but reduced efficiency.
- Organic Photovoltaics:Carbon-based semiconductor materials enabling semi-transparent and flexible module designs.
Monocrystalline technology dominates installed capacity. Thin-Film segments gain share fastest through building-integrated applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Belgium's solar industry traces its commercial roots to early Flemish feed-in tariff programs that scaled distributed generation from 2007 onward. Three regional energy markets now operate under distinct regulatory frameworks, creating heterogeneous deployment patterns across the national territory.
Flanders
Logistics parks in Antwerp port industrial zones drive commercial rooftop demand as monocrystalline PERC modules reach 700W outputs. The Flemish Energy and Climate Agency administers net-metering reforms that redirect investment toward battery-coupled arrays. East Flanders concentrates deployment velocity where distribution system operator incentives reward behind-the-meter generation at warehouse complexes.
Wallonia
Green certificate premiums for installations under 10kW sustain residential deployment across Hainaut and Namur provinces. The region's public service for energy maintains elevated subsidy values that buffer smaller prosumers from federal tariff adjustments. Liège and Charleroi industrial basins anchor commercial ground-mounted development on remediated brownfield sites.
Brussels-Capital Region
Mandatory Building Energy Performance Certificate upgrades force commercial retrofits to incorporate photovoltaic generation by 2027 compliance deadlines. Near-zero energy building mandates create embedded demand for facade-integrated thin-film systems in the European Quarter. Large-format office buildings respond with integrated rooftop arrays to avoid rental value penalties.
Limburg Province
Grid congestion relief programs incentivize distributed generation across logistics corridors bordering the Netherlands. Municipal energy agencies facilitate energy cooperative aggregation models that negotiate volume discounts on module packages. Peer-to-peer trading platforms in Hasselt and Genk bypass traditional utility intermediaries for community-owned generation pools.
West Flanders
Agrivoltaic pilot zones open agricultural parcels for elevated panel installations preserving crop cultivation under 2024 land-use frameworks. Coastal municipalities test bifacial ground-mounted systems on saline-tolerant pasture lands. Bruges and Ostend harbor zones explore floating solar configurations on inland waterway reservoirs.
Belgium Solar Energy Market Vendor Landscape
The competitive structure tilts toward utility-affiliated developers with scale advantages in interconnection queue management. Belgian solar deployment channels capital through three archetypes: integrated energy majors leveraging transmission relationships, specialized commercial rooftop installers navigating permitting complexity, and community cooperative aggregators pooling residential demand. Consolidation pressure intensifies as federal subsidy reforms compress project development timelines and favor balance-sheet capacity.
Among utility-affiliated developers, Engie Electrabel and EDF Luminus occupy positions anchored by grid-balancing service relationships and regional regulatory familiarity. Ikaros Solar exemplifies the specialized commercial installer archetype, with project origination capabilities concentrated in Flemish logistics corridors. These three entities represent distinct strategic postures: scale-driven hybrid project deployment, regulated utility service integration, and tailored permitting navigation across Belgium's tripartite energy governance structure.
| Leading Market Players |
|---|
| 7C Solarparken AG |
| Ikaros Solar |
| Engie Electrabel |
| Invictus |
| ENGIE Fabricom |
| EDF Luminus |
| Orka Power |
| Perpetum Energy |
| Eneco Belgium |
| Others |
Supply Flow & Price Mechanics
Bifacial glass-glass module adoption in Flemish logistics parks simultaneously compresses levelized cost thresholds and concentrates procurement power among certified Tier 1 suppliers capable of IEC 61215-compliant production at scale.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Belgian module procurement, with CE marking tier and volume scale as primary differentiation drivers. Premium monocrystalline PERC modules with extended warranties command spreads over economy-grade polycrystalline alternatives. Cost compression in the standard tier is intensifying because logistics park developers negotiate aggregate procurement contracts. Residential energy cooperatives exhibit highest price sensitivity, while utility-scale developers prioritize performance guarantees over unit economics.
Supply Chain Analysis
CE marking and IEC 61215 certification gating filters non-compliant suppliers from federal subsidy eligibility, compressing viable sourcing to China, Vietnam, and Malaysia for silicon wafer and cell production. Polysilicon feedstock draws from Xinjiang-sourced supply chains exposed to EU forced labor due diligence requirements. Single-source vulnerability concentrates in ingot and wafer processing capacity. Distribution runs through Antwerp port industrial zones for Flemish commercial deployment, with regional logistics hubs serving Walloon and Brussels-Capital markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Belgium's solar market functions as a regulatory compounder where Brussels-Capital Region's 2027 near-zero energy building mandates force commercial retrofit incorporation of photovoltaic generation.
For Market Incumbents: Anticipate margin compression from energy cooperative aggregation models by securing exclusive supply agreements with municipal energy agencies in Limburg. Prioritize backward integration into battery storage assembly to capture hybrid system economics as net-metering reforms deteriorate pure export revenue cases. Defend against specialized commercial installers through expedited permitting navigation capabilities across Flemish and Wallonian jurisdictions. For New Entrants and Emerging Players: Begin with agrivoltaic pilot zones in West Flanders where 2024 land-use frameworks open agricultural parcels for elevated panel installations preserving crop cultivation. Target energy cooperative aggregation platforms in Hasselt and Genk municipalities as the most penetrable channel, bypassing traditional utility intermediaries through peer-to-peer trading infrastructure. Pursue direct OEM relationships with monocrystalline PERC module manufacturers to secure volume pricing without incumbent distributor markups. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized commercial rooftop installers with established Flemish permitting expertise and logistics park developer relationships. Five-to-ten year viability hinges on battery-coupled system deployment capabilities and regional grid-balancing service contracts. Monitor federal capacity-based tariff reform announcements as the signal to watch for inflection in hybrid project economic viability.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Coupled Array Deployment | Captures value from Flemish net-metering reforms redirecting investment toward storage-integrated systems. |
| Agrivoltaic Land-Use Partnerships | Unlocks West Flanders agricultural parcels under 2024 Flemish Energy and Climate Agency frameworks. |
| Energy Cooperative Aggregation Platforms | Concentrates Limburg residential demand through municipal-facilitated group-buying frameworks. |
| Building-Integrated Photovoltaic Certification | Meets Brussels-Capital Region near-zero energy building mandates for facade-integrated thin-film systems. |
| Grid Congestion Relief Contracting | Secures East Flanders distribution system operator incentives for behind-the-meter generation at logistics parks. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up capacity installation tracking and top-down regulatory framework analysis were triangulated to reconcile segmentation estimates.
Historical reference periods anchored the forecast window to pre-reform baseline conditions, enabling measurement of net-metering adjustment impacts across the projection horizon. The analytical framework modeled system type, installation scale, end-user category, technology architecture, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from capacity deployment trajectories and tariff evolution assumptions, incorporating module efficiency improvement curves and battery cost decline rates as industry-specific inputs.
Several conditions sit outside the modeled scope, including unannounced federal subsidy program discontinuations, Elia transmission upgrade timeline accelerations, and EU forced labor regulation enforcement severity. Forecasts reflect assumptions about regulatory stability and technology cost curves. A model refresh is warranted upon material change in federal green certificate valuation methodology or capacity-based tariff implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Encapsulation Market
Solar Power Systems
AR Photovoltaic Glass Market
Solar Power Systems
Solar Simulator Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Canada Solar Energy Market
Solar Power Systems
Half-Cell Solar Module Market
Solar Power Systems
Residential Solar Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
India Solar Tracker Market
Solar Power Systems
IBC Solar Cells Market
Solar Power Systems
Solar Freezer Market
Solar Power Systems
Solar Phone Chargers Market
Solar Power Systems
Plastic Solar Cell Market
Solar Power Systems
Building-Integrated Photovoltaic (BIPV) Skylights Market
Solar Power Systems
Netherlands Solar Energy Market