
 Solar Vegetable Dryer Market | 2026-2036
Solar Vegetable Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Vegetable Dryer Market Insights
Modular kit configurations bundling photovoltaic panels with adjustable drying racks and humidity sensors is rebalancing procurement decisions for small and mid-scale agro-processors. Rudra Solar Energy leverages its Gujarat manufacturing base to supply standardized batch dryer kits across South Asian markets. Suncue Company Ltd. anchors its position through proprietary conductive drying technology optimized for high-moisture leafy vegetables. Ecozen Solutions differentiates by integrating IoT monitoring with solar thermal hybrid designs for Indian food processing cooperatives.
A solar vegetable dryer harnesses solar radiation to reduce moisture content in agricultural produce through convection, conductive, or radiative heat transfer, typically achieving temperatures between 40°C and 70°C with airflow rates of 0.5 to 2.5 m/s to preserve nutritional value and extend shelf life without grid electricity dependency. Batch dryers occupy the largest installed base due to lower capital requirements and simpler maintenance protocols suitable for smallholder farmers. Continuous dryers represent the fastest-expanding segment as commercial agro-processors in India and East Africa scale throughput for export-grade dried vegetable products. Hybrid dryers integrating solar thermal with biomass backup command premium positioning where grid reliability remains inconsistent.
India's Bureau of Indian Standards (BIS) certification requirements for solar thermal equipment and the European Union's Ecodesign Directive for energy-consuming products shape product compliance pathways for manufacturers seeking cross-border sales. The Food Safety and Standards Authority of India (FSSAI) hygienic processing standards for dried foods mandate stainless steel construction and temperature documentation that elevates equipment specifications for formal-sector buyers. Stakeholders must monitor evolving national renewable energy subsidy eligibility criteria and food safety certification harmonization between export markets and domestic processing standards.
Market Dynamics
Modular solar drying configurations are rewriting procurement economics for small and mid-scale agro-processors, compressing capital deployment timelines from centralized infrastructure to distributed, kit-based installations.
Growth Catalysts
- India's MNRE subsidy programs:Off-grid solar application incentives accelerate rural deployment of batch dryer systems across Maharashtra and Gujarat food processing clusters.
- Smallholder cooperative expansion:Sub-Saharan African producer groups are consolidating procurement of standardized solar drying units to achieve export-grade vegetable certification.
- Hybrid thermal-biomass integration:Backup heating systems address intermittency constraints in Kenya's Rift Valley tomato and mango processing corridors.
Market Restraints
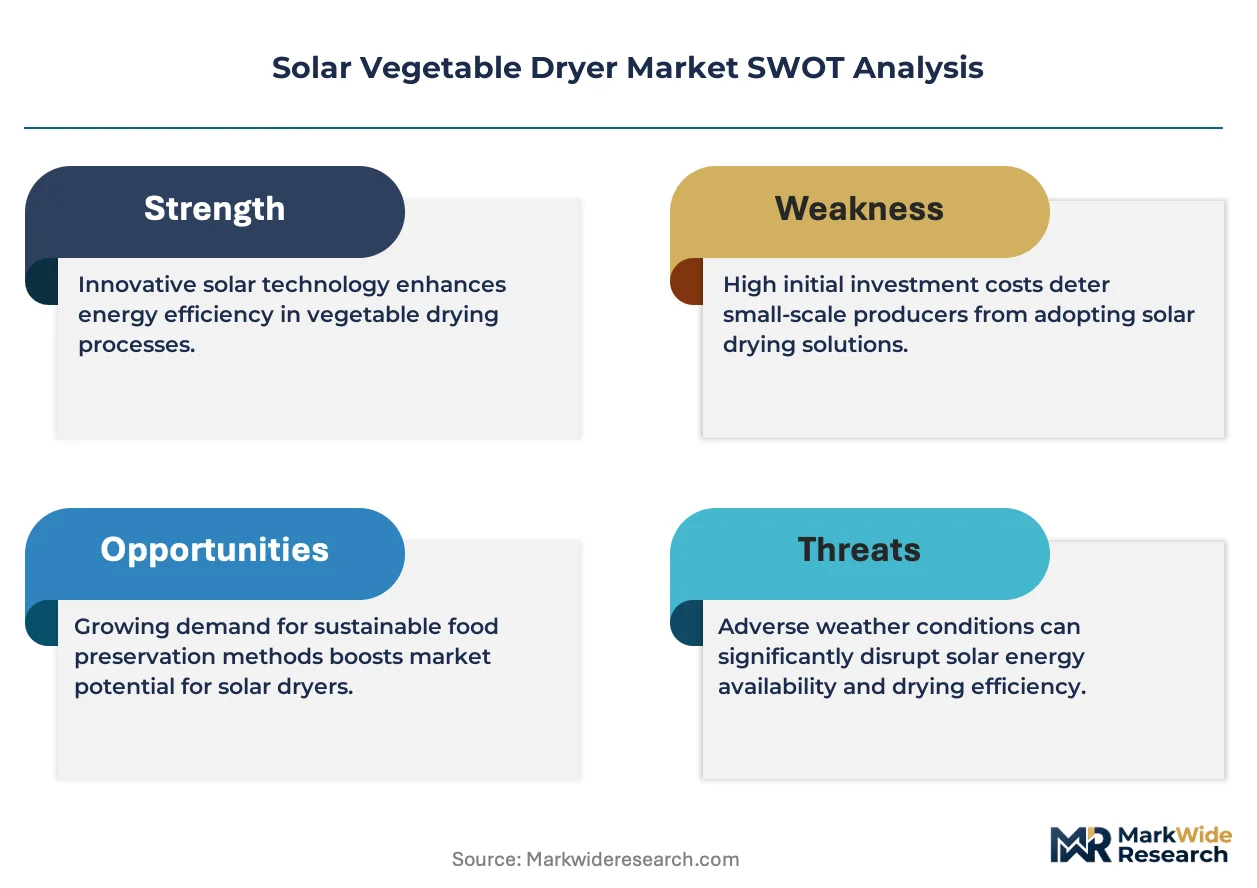
- Photovoltaic panel cost volatility:Silicon supply fluctuations and freight rate instability compress equipment manufacturer margins on standardized kits.
- Stainless steel input concentration:FSSAI-mandated hygienic construction specifications tie formal-sector equipment costs to global metal commodity cycles.
- Technical moisture uniformity limits:Passive convection designs struggle to achieve consistent 12% final moisture content across high-moisture leafy vegetable batches.
Strategic Opportunities
- IoT-enabled predictive maintenance:Remote humidity and temperature monitoring systems create aftermarket revenue streams for equipment suppliers serving Indian cooperatives.
- East African export corridor penetration:Uganda and Tanzania horticulture clusters remain underpenetrated relative to Kenyan adoption rates.
- BIS-CE dual certification pathways:Manufacturers achieving concurrent Indian and European equipment standards access premium pricing in cross-border agro-processor procurement.
Industry Challenges
- Skilled technician scarcity:Solar thermal system maintenance and humidity sensor calibration require training pipelines that rural vocational institutions have not scaled.
- FSSAI documentation timelines:Stainless steel construction verification and temperature logging protocol certification delay formal-sector sales cycles by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Vegetable Dryer Market |
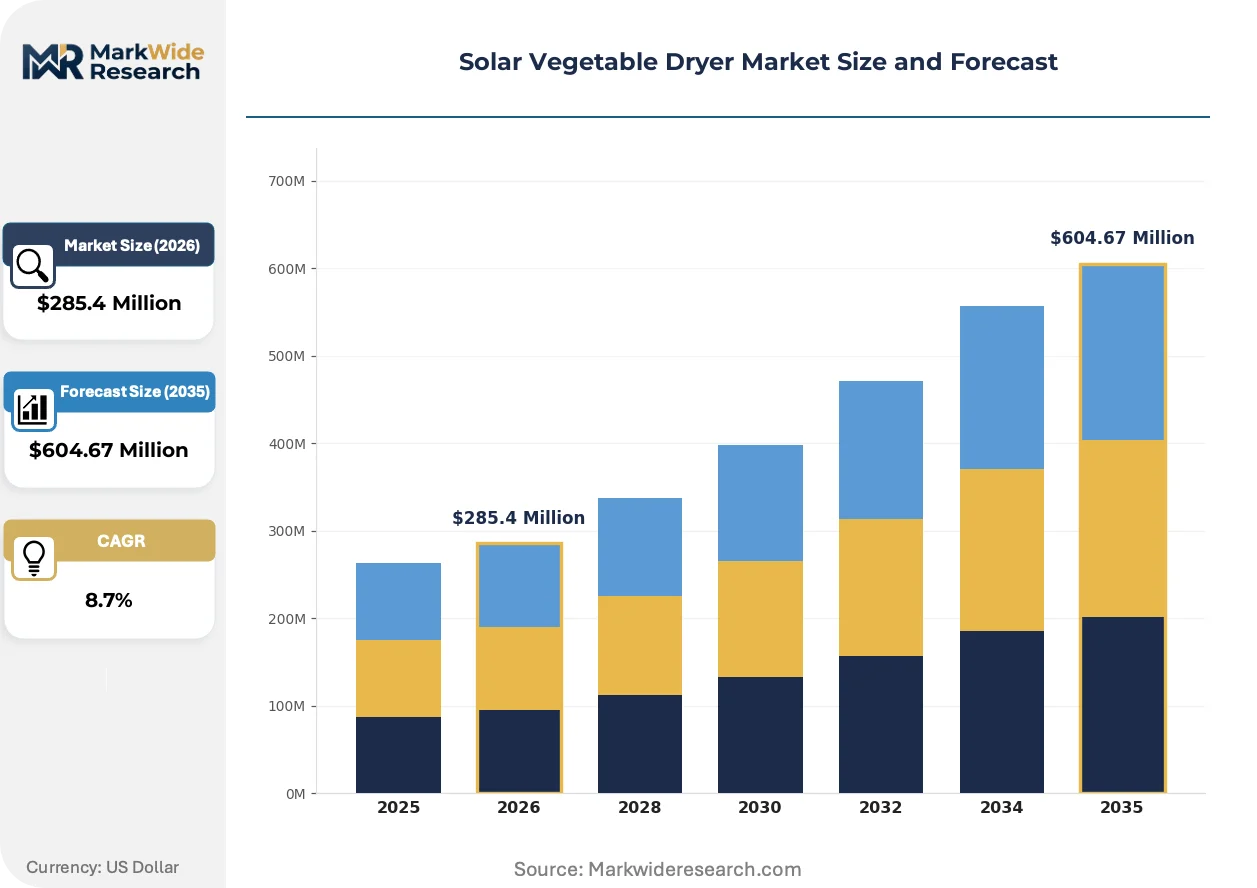
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $604.67 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Dryer, Continuous Dryer, Hybrid Dryer, Tunnel Dryer End User: Farmers, Agro-Processors, Food Manufacturers, Research Institutions Technology: Convection, Conductive, Radiative, Integrated Systems Distribution Channel: Direct Sales, Retail, Online, Distributors |
| Companies Covered | Rudra Solar Energy, Suncue Company Ltd., Solar Dryers Australia, Ecozen Solutions, Advanced Energy Industries Inc., Azimuth Solar Products Inc., SunPower Corporation, Vikram Solar, Agro Solar Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Vegetable Dryer Market Trends and Innovations
Equipment intelligence and thermal efficiency convergence are compressing the performance gap between artisanal drying methods and industrial dehydration, reshaping competitive positioning across emerging market agro-processing.
Conductive drying technology optimized for high-moisture leafy vegetables is rewriting throughput benchmarks for commercial operators. East African export-oriented processors are adopting these systems at twice the pace of passive convection alternatives. The technology is compressing drying cycle duration from seventy-two hours to under twenty-four hours for spinach and kale batches.
India's BIS certification requirements for solar thermal equipment are elevating construction standards across South Asian supply chains. Manufacturers must document thermal efficiency testing and material traceability to access MNRE subsidy eligibility. Formal-sector buyers in Maharashtra and Gujarat now require BIS compliance as a baseline procurement filter, displacing uncertified imports from regional markets.
Cooperative procurement consortia are consolidating equipment specification power across sub-Saharan African agricultural corridors. Aggregated demand from Kenyan Rift Valley producer groups is displacing individual smallholder purchases. This concentration is most visible in tomato and mango processing clusters where shared drying infrastructure achieves FSSAI-equivalent export certification thresholds.
Solar Vegetable Dryer Market Segmentation
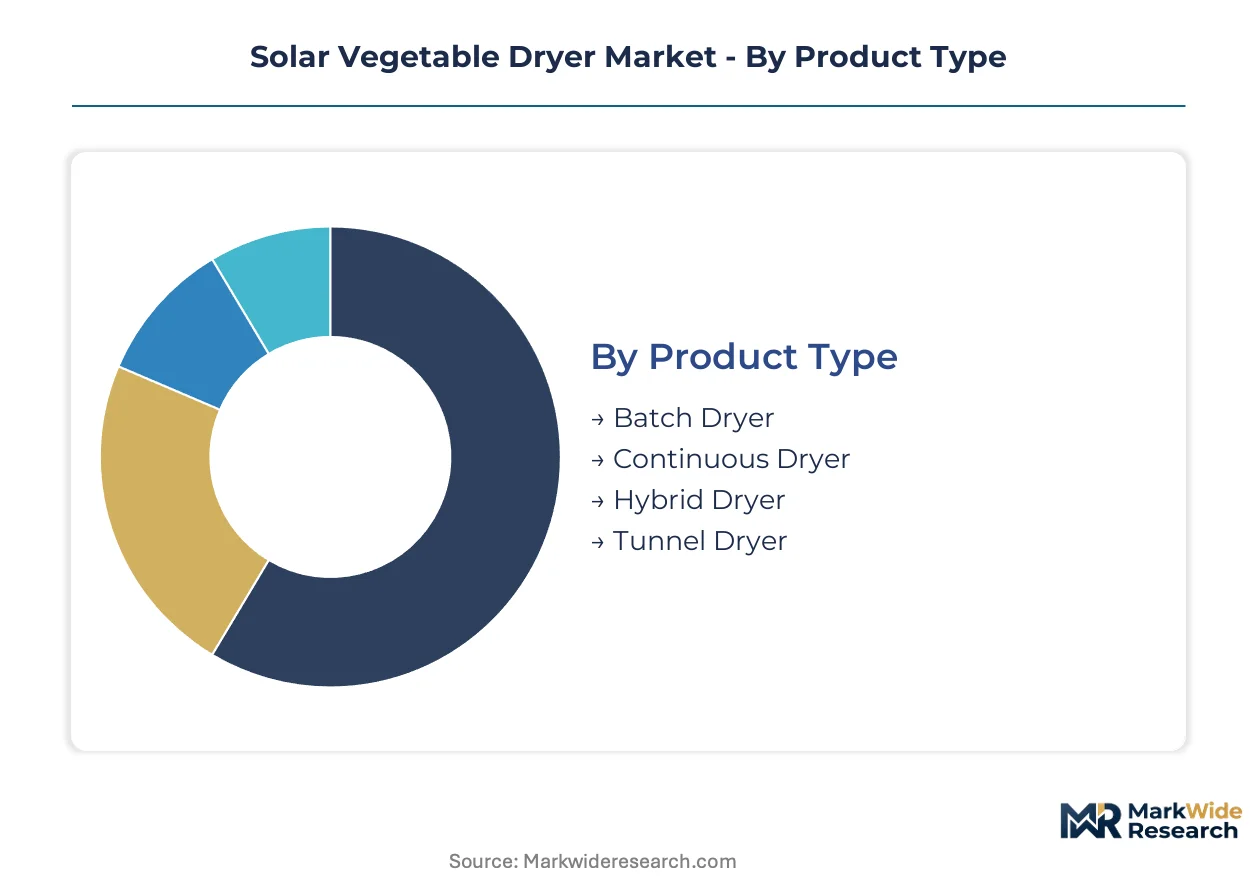
Procurement patterns in solar vegetable drying diverge sharply by operational scale and thermal engineering approach. Buyers prioritize capital efficiency, throughput requirements, and backup reliability when selecting across these segment boundaries.
Product Type:
Capital deployment thresholds and maintenance capabilities separate buyers across dryer configurations.
- Batch Dryer:Self-contained units process discrete loads through passive or active convection, typically housing 50-200 kg fresh produce per cycle. Smallholder cooperatives in Kenya's Rift Valley anchor procurement volumes, driven by MNRE-equivalent subsidy accessibility and minimal technician requirements.
- Continuous Dryer:Conveyor-fed systems enable uninterrupted processing with automated temperature zoning and moisture extraction. Indian agro-processors in Maharashtra's food processing corridors concentrate adoption, compelled by export-grade throughput demands and FSSAI documentation requirements for formal-sector sales.
- Hybrid Dryer:Solar thermal systems integrate biomass or LPG backup burners for weather-independent operation. Deployment clusters where grid reliability fluctuates.
- Tunnel Dryer:Long-chamber designs with forced airflow accommodate high-volume commercial operations. Specialized installations for mango and tomato processing clusters.
Volume sits with Batch Dryer configurations; growth tilts toward Continuous Dryer systems.
End User:
Regulatory exposure and certification requirements stratify buyer sophistication across end-use categories.
- Farmers:Individual smallholders and cooperative members operating sub-500 kg daily processing capacity. Sub-Saharan African producer groups in Uganda and Tanzania drive equipment consolidation through shared procurement.
- Agro-Processors:Mid-scale operations serving domestic and regional markets with 500 kg-5 tonne daily throughput. Kenya's horticulture export corridors concentrate demand, shaped by FSSAI-equivalent hygienic processing mandates.
- Food Manufacturers:Large-scale industrial dehydration facilities supplying retail and institutional channels. Stainless steel construction and BIS certification compliance filter procurement decisions.
- Research Institutions:Agricultural universities and food technology centers validating drying protocols and moisture uniformity benchmarks. Limited volume but specification influence across commercial segments.
Procurement scale concentrates with Agro-Processors; specification authority rests with Food Manufacturers.
Technology:
Moisture content targets and vegetable morphology dictate heat transfer mechanism selection.
- Convection:Forced or natural airflow systems circulate heated air across produce surfaces. Passive designs dominate smallholder installations in East African agricultural corridors.
- Conductive:Direct heat transfer through solid surfaces optimized for high-moisture leafy vegetables. Suncue Company's proprietary implementations compress drying cycles for spinach and kale batches in commercial operations.
- Radiative:Infrared and solar thermal radiation targeting surface moisture without convective airflow. Specialized applications for delicate produce with low thermal tolerance.
- Integrated Systems:Multi-mode combinations sequencing convection, conduction, and radiative phases. Premium positioning for export-grade dehydration requiring precise moisture uniformity.
Installed base favors Convection; technology transition accelerates toward Integrated Systems.
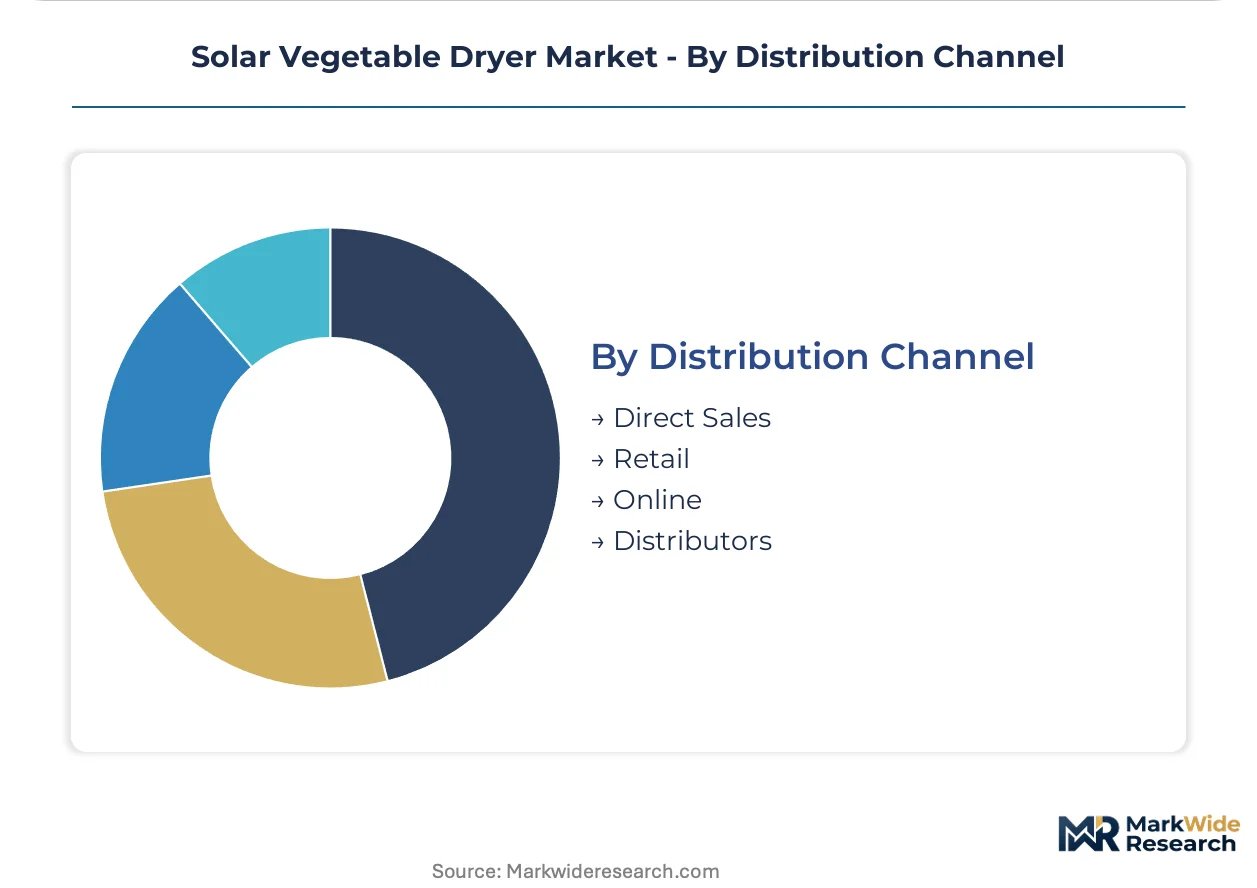
Distribution Channel:
Buyer technical sophistication and after-service requirements determine channel preference.
- Direct Sales:Manufacturer-to-buyer relationships with installation support and warranty servicing. Formal-sector Agro-Processors and Food Manufacturers in India and Kenya prioritize this channel for BIS and FSSAI compliance documentation.
- Retail:Agricultural equipment dealers and renewable energy storefronts stocking standardized batch dryer kits. Smallholder access point in Gujarat and Maharashtra manufacturing clusters.
- Online:E-commerce platforms and manufacturer-direct digital channels for specification comparison and kit ordering. Emerging route for modular configurations with IoT monitoring bundles.
- Distributors:Regional wholesale networks aggregating multiple manufacturer lines with local spare parts inventory. Critical for sub-Saharan African markets where technician scarcity elevates maintenance responsiveness requirements.
Transaction volume flows through Direct Sales; channel expansion concentrates in Online platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters in India and East Africa dominate production capacity while procurement demand concentrates across sub-Saharan agricultural corridors and South Asian food processing zones. Subsidy accessibility and export certification requirements reshape deployment patterns more than raw solar resource availability.
India
Maharashtra and Gujarat food processing clusters anchor domestic demand for BIS-certified batch and continuous dryer systems. MNRE subsidy programs for off-grid solar applications accelerate rural deployment across these western states. Stainless steel construction mandates from FSSAI elevate equipment specifications for formal-sector buyers in Mumbai and Ahmedabad processing corridors.
Kenya
Rift Valley tomato and mango processing clusters drive concentrated equipment procurement from agro-processor cooperatives. Hybrid thermal-biomass configurations address intermittency constraints in this export-oriented horticulture corridor. Nairobi-based distributor networks service maintenance requirements for humidity sensor calibration and spare parts inventory.
Uganda
Underpenetrated horticulture clusters in the Central and Western regions present expansion opportunities relative to Kenyan adoption rates. Smallholder cooperative consolidation is beginning to displace individual farmer purchases of passive convection units. Kampala-proximate equipment distributors are establishing regional spare parts depots to address technician scarcity.
Tanzania
Arusha and Dodoma agricultural corridors show emerging demand for modular solar drying kits among vegetable export cooperatives. The country's national renewable energy agency is evaluating subsidy eligibility criteria for solar thermal equipment. Dar es Salaam port access shapes procurement logistics for Indian-manufactured stainless steel dryer components.
Australia
Solar Dryers Australia represents localized fabrication capacity serving domestic bushfood and specialty crop processors. Remote agricultural operations in Queensland and Western Australia drive demand for grid-independent dehydration systems. Australian equipment standards influence specification requirements for export-oriented Pacific Island deployments.
Solar Vegetable Dryer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a structurally fragmented vendor base. Equipment manufacturers cluster by thermal engineering approach and geographic manufacturing footprint rather than scale-driven consolidation. Three archetypes dominate: Gujarat-based standardized kit fabricators, East Asian conductive technology specialists, and IoT-integrated hybrid system developers. Competitive moves center on BIS-CE dual certification achievement and cooperative procurement consortium penetration.
Among India-based fabricators, Rudra Solar Energy occupies a position within the standardized batch dryer archetype serving South Asian markets. Suncue Company Ltd. exemplifies the conductive technology specialist tier with proprietary implementations for high-moisture vegetable applications. Ecozen Solutions represents the IoT-integrated hybrid segment, anchoring its positioning through solar thermal monitoring systems for cooperative buyers. These three entities collectively span the technology diversification spectrum visible across competitive filings.
| Leading Market Players |
|---|
| Rudra Solar Energy |
| Suncue Company Ltd. |
| Solar Dryers Australia |
| Ecozen Solutions |
| Advanced Energy Industries Inc. |
| Azimuth Solar Products Inc. |
| SunPower Corporation |
| Vikram Solar |
| Agro Solar Europe GmbH |
| Others |
Pricing and Supply Chain Analysis
Conductive drying technology migration from passive convection systems is compressing manufacturing cost curves while concentrating procurement power among stainless steel fabricators in Gujarat and Maharashtra. This dual shift elevates equipment specifications for FSSAI-compliant buyers while exposing standardized kit producers to photovoltaic panel cost volatility.
Pricing Analysis
Margin tightening in the batch dryer tier reflects silicon supply fluctuations and freight rate instability compressing equipment manufacturer returns. Three-tier pricing structure across BIS-certified premium, FSSAI-equivalent standard, and uncertified economy levels segments buyer access. Cost-down pressure on continuous dryer systems accelerates because agro-processors demand export-grade throughput documentation. Individual smallholders in Uganda and Tanzania exhibit highest price sensitivity; Indian food manufacturers with MNRE subsidy access show lowest.
Supply Chain Analysis
Freight cost volatility from Indian manufacturing clusters to East African ports elevates landed equipment costs for Kenyan and Ugandan cooperatives. Supply concentrates in India, China, and Australia for photovoltaic panels, stainless steel components, and humidity sensors respectively. Raw material dependencies on silicon wafers, nickel-alloy steel, and polymer glazing create tariff exposure at multiple nodes. Distribution runs through Nairobi-based distributor networks with regional spare parts depots addressing technician scarcity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT-enabled predictive maintenance systems are displacing passive convection legacy equipment across Indian and East African agro-processing corridors. This technology transition compresses drying cycle duration while elevating aftermarket revenue capture for equipment suppliers.
For Market Incumbents: To counter conductive drying technology specialists capturing commercial spinach and kale processing share, Rudra Solar Energy and Gujarat-based fabricators should deepen backward integration into stainless steel component forging and accelerate BIS-CE dual certification achievement. Channel control through cooperative procurement consortium penetration in Kenya's Rift Valley anchors defensive positioning against East Asian technology entrants. For New Entrants and Emerging Players: Agricultural equipment distributors in Kampala and Dodoma corridors offer the most penetrable channel partnership structure for modular solar drying kit deployment. Underpenetrated Ugandan and Tanzanian horticulture clusters present white-space expansion relative to Kenyan adoption saturation. Direct-to-cooperative go-to-market angles leveraging MNRE-equivalent subsidy navigation support differentiate against established Indian exporters. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified renewable energy conglomerates seeking agro-processing equipment verticals. Long-term viability hinges on regulatory subsidy durability across Indian and East African jurisdictions. Acquisition target archetypes include IoT-integrated hybrid system developers with FSSAI documentation capabilities. The inflection signal to watch is harmonization between export market food safety standards and domestic processing certification requirements.| Strategic Initiative | Industry Significance |
|---|---|
| BIS-CE Dual Certification Investment | Unlocks premium pricing in cross-border agro-processor procurement between India and European export corridors. |
| IoT Monitoring Platform Integration | Ecozen Solutions and competitors capture aftermarket revenue through remote humidity sensor calibration services. |
| Backward Integration into Stainless Steel Forging | Gujarat fabricators reduce FSSAI-mandated construction cost exposure to global nickel commodity cycles. |
| East African Distributor Network Expansion | Nairobi and Kampala spare parts depots address technician scarcity constraining rural maintenance responsiveness. |
| Cooperative Procurement Consortium Penetration | Kenyan Rift Valley tomato and mango processor groups consolidate demand displacement of individual smallholder purchases. |
Research Methodology
Multi-period observation of MNRE subsidy disbursement patterns, BIS certification timelines, and FSSAI compliance documentation anchored the trend analysis, supplemented by interviews with equipment manufacturing executives, agro-processor cooperative managers, stainless steel procurement leads, and renewable energy distributor principals. Secondary validation drew from Indian Bureau of Energy Efficiency filings, Kenya National Bureau of Statistics horticulture export data, Tanzania Renewable Energy Agency policy documents, and customs records for solar thermal equipment imports. Bottom-up installation tracking across Maharashtra, Gujarat, Rift Valley, Central Uganda, and Dodoma corridors triangulated against top-down market sizing.
The input-output matrix framed demand as a function of smallholder cooperative consolidation rates, export certification penetration, and subsidy eligibility evolution across the projection horizon. Segmentation dimensions modeled include dryer configuration type, end-user operational scale, heat transfer technology approach, and distribution channel structure. CAGRs were derived from equipment procurement velocity indices calibrated against agro-processor throughput expansion and MNRE disbursement trajectories. Forecast inputs incorporated photovoltaic panel cost volatility assumptions and stainless steel price cycle sensitivity.
Caveats apply where silicon supply disruptions, FSSAI documentation timeline extensions, or East African subsidy program suspensions could materially shift the outlook. Forecasts reflect documented assumptions about cooperative procurement consolidation velocity and cross-border certification harmonization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Power Market
Solar Power Systems
Global Micro Solar Inverter Market
Solar Power Systems
Belgium Solar Energy Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
US Solar Films Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Global Concentrating Solar Power Market
Solar Power Systems
Solar Sunlight Control System Market
Solar Power Systems
South America Rooftop Solar Market
Solar Power Systems
High Concentration Photovoltaics Market
Solar Power Systems
Kuwait Solar Energy Market
Solar Power Systems
Australia Solar Power Market