
 GCC Solar Photovoltaic (PV) Market | 2026-2036
GCC Solar Photovoltaic (PV) Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Solar Photovoltaic (PV) Market Foresight
Utility-grade module specifications are rotating toward higher-wattage bifacial and monocrystalline products across GCC tender pipelines. JinkoSolar leverages its n-type TOPCon capacity to compete for Saudi PPA awards, while Longi Green Energy Technology anchors supply relationships with ACWA Power for gigawatt-scale projects. Canadian Solar differentiates through integrated project development capabilities that extend beyond module sales into EPC and O&M services.
Solar photovoltaic systems convert sunlight into direct-current electricity through semiconductor junctions, with monocrystalline silicon cells achieving conversion efficiencies above 22% under standard test conditions. Cadmium telluride thin-film technology occupies niche positions in utility-scale desert installations where temperature coefficients favor its performance profile. Crystalline silicon technology dominates procurement volumes across GCC utility-scale power plants, while bifacial modules represent the fastest-growing product category as developers seek enhanced energy yield from albedo-reflected irradiance on sandy terrain. Residential installations remain underpenetrated relative to commercial rooftops and utility-scale segments, creating divergent margin pools across application channels.
Saudi Arabia's National Renewable Energy Programme and the UAE's net metering frameworks administered by the Emirates Water and Electricity Company shape offtake structures and grid interconnection standards for project developers. The Saudi Standards, Metrology and Quality Organization and the UAE's Regulation and Supervision Bureau enforce module certification and inverter compliance requirements that filter market access for non-conforming suppliers. Stakeholders must monitor evolving local content mandates and domestic manufacturing incentives that could restructure supply chain economics for imported components.
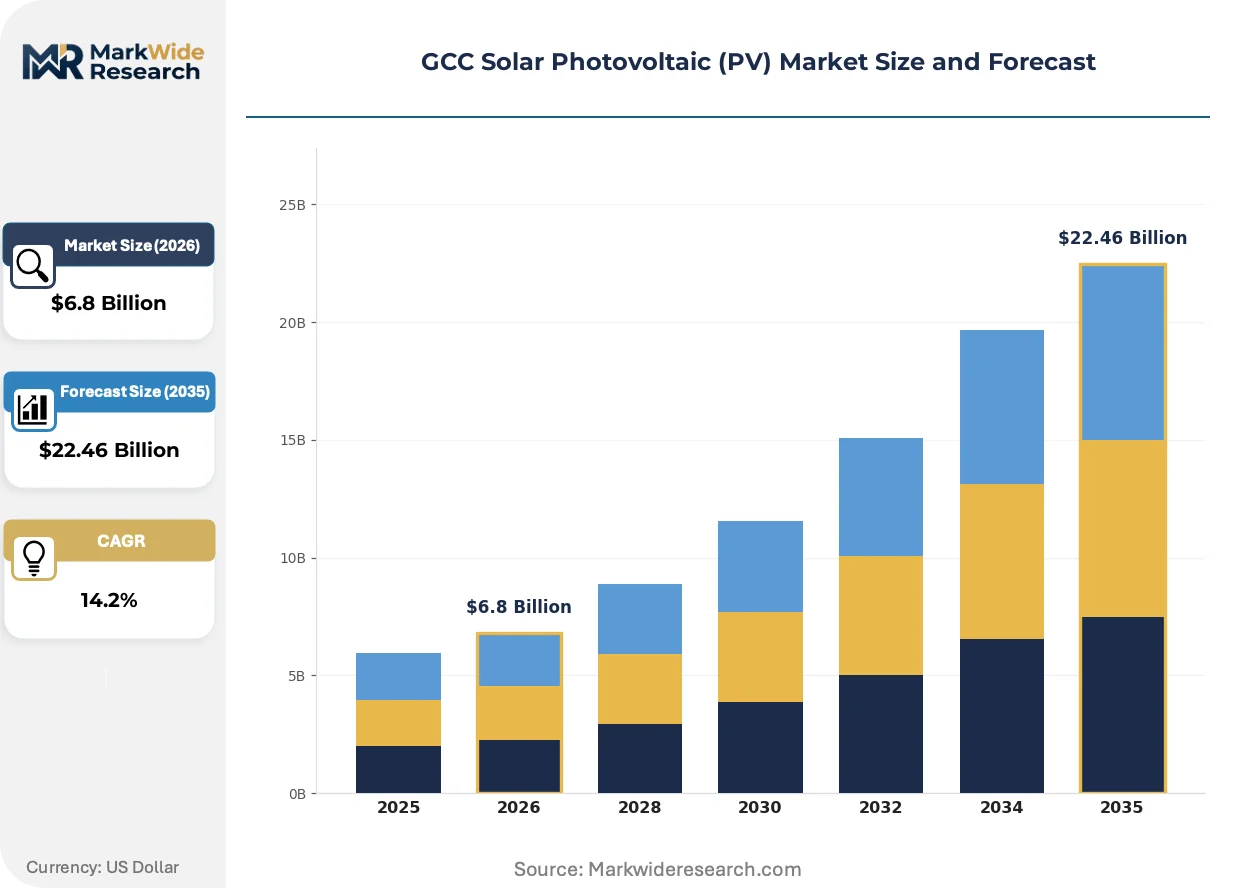
Market Dynamics
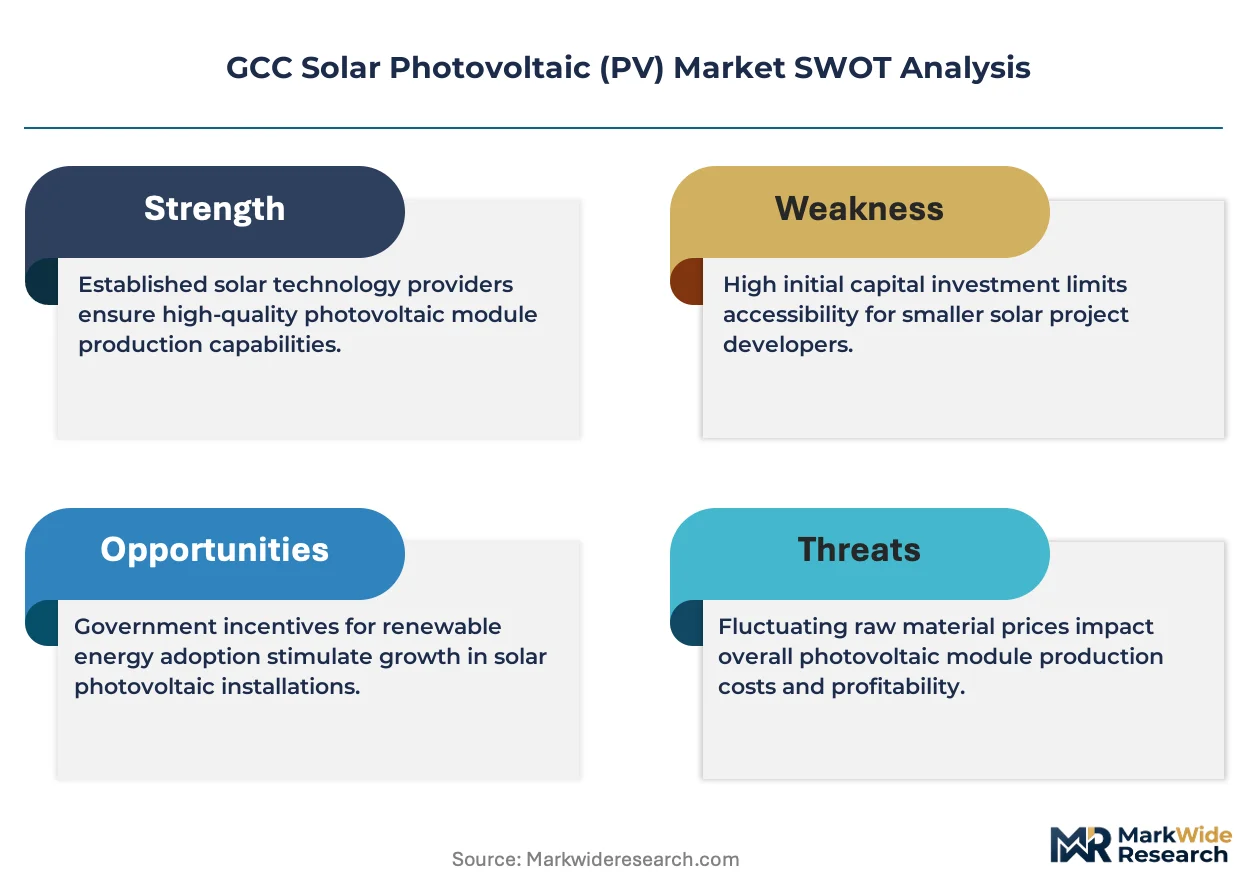
Bifacial module technology is redirecting developer capital toward higher-efficiency installations across Saudi Arabia and the UAE, compressing procurement timelines for utility-scale projects while reshaping supplier qualification criteria.
Growth Catalysts
- Saudi Arabia's National Renewable Energy Programme:State-backed offtake guarantees de-risk project finance for gigawatt-scale developments, accelerating pipeline origination in Riyadh and surrounding regions.
- Albedo-reflected irradiance capture:Bifacial modules exploit sandy terrain reflectivity to boost energy yield, making desert installations economically superior to single-sided alternatives.
- ACWA Power's procurement scale:The Saudi developer's multi-gigawatt tendering creates demand concentration that justifies dedicated production lines from module suppliers.
Market Restraints
- Polysilicon supply concentration:Upstream ingot and wafer production clusters in China create exposure to trade policy shifts and logistics disruptions for GCC developers.
- Saudi Standards, Metrology and Quality Organization certification:Module testing protocols and inverter compliance requirements filter market access, extending qualification timelines for non-conforming suppliers.
- Grid interconnection standards:Emirates Water and Electricity Company technical specifications impose costly grid-forming inverter requirements that inflate balance-of-system costs.
Strategic Opportunities
- Residential rooftop underpenetration:Distributed solar adoption lags commercial installations across Dubai and Sharjah, creating margin pools for segment-focused installers.
- Domestic manufacturing incentives:Saudi Arabia's local content mandates and industrial zone subsidies could restructure supply chain economics for module assembly within the Kingdom.
- Integrated EPC and O&M services:Developers seek single-contractor accountability for multi-decade asset performance, rewarding suppliers with project development capabilities beyond component sales.
Industry Challenges
- Skilled EPC labor scarcity:Gigawatt-scale construction schedules strain the pool of certified installation technicians and grid interconnection specialists across the GCC.
- Permitting timeline unpredictability:Land allocation and environmental clearance procedures vary across Saudi Arabia's regions, compressing construction windows and inflating carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Solar Photovoltaic (PV) Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Technology: Crystalline Silicon, Cadmium Telluride, Copper Indium Gallium Selenide, Perovskite Application: Residential Installations, Commercial Rooftops, Utility-Scale Power Plants, Off-Grid Systems, Agriculture End User: Power Producers, Government Entities, Industrial Facilities, Real Estate Developers |
| Companies Covered | Dubai Electricity and Water Authority, JinkoSolar Holding Co. Ltd, Canadian Solar Inc, Longi Green Energy Technology Co. Ltd, Trina Solar Co. Ltd, First Solar Inc, ACWA Power, JA Solar Technology Co. Ltd, Masdar Abu Dhabi Future Energy Company, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Solar Photovoltaic (PV) Market Shifts & Advancements
Module efficiency thresholds and procurement contract structures are actively reshaping competitive positioning across the GCC solar value chain, compressing margins for legacy product categories while rewarding technology differentiation.
Monocrystalline silicon cell architecture is bifurcating procurement specifications across utility tenders. Conversion efficiencies above 22% under standard test conditions now define qualification criteria for Saudi PPA awards. Developers in Abu Dhabi emirate specify n-type TOPCon cells exclusively, marginalizing p-type PERC inventory. The technology divide is compressing pricing for legacy mono-PERC modules while bifurcating supplier tiers.
Net metering frameworks administered by Emirates Water and Electricity Company are tightening grid export compensation structures. Commercial rooftop owners face declining feed-in tariffs that alter project return profiles. The policy shift is forcing distributed solar developers toward behind-the-meter storage pairing and self-consumption optimization across Dubai's industrial zones.
Buyer concentration among state-backed offtakers is consolidating procurement decision-making. ACWA Power and Saudi Power Procurement Company now originate the majority of pipeline capacity, replacing fragmented commercial offtake. The pattern compresses vendor negotiation leverage and rewards established supply relationships with tier-one module manufacturers across Riyadh-based tender processes.
GCC Solar Photovoltaic (PV) Market Segmentation
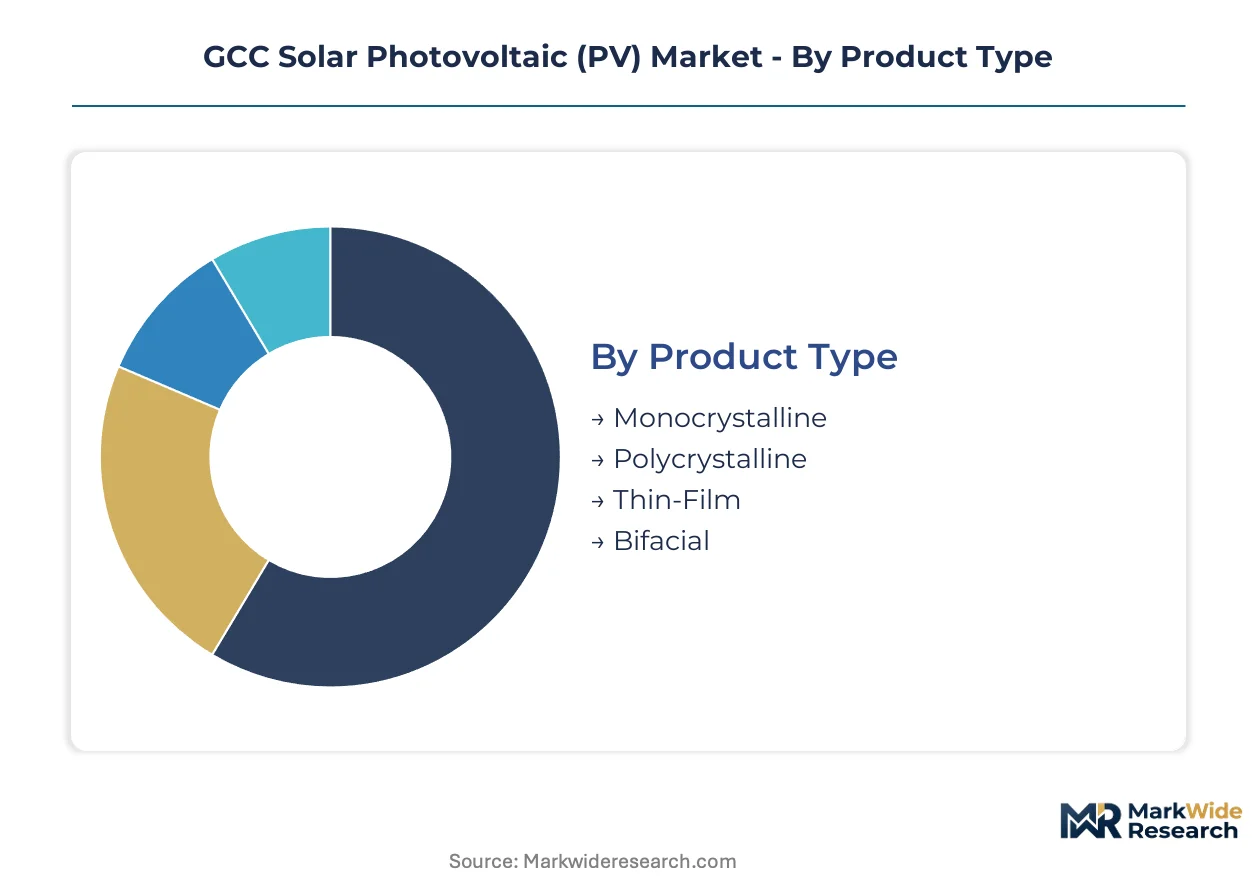
Technology and application segments in the GCC solar PV market exhibit divergent margin structures driven by procurement scale, certification requirements, and terrain-specific performance optimization. Understanding these segment boundaries enables suppliers to allocate R&D and manufacturing capacity toward the highest-yield contract categories.
Product Type:
Margin pools concentrate in high-efficiency modules that qualify for Saudi PPA awards and Abu Dhabi utility tenders, while legacy technologies face pricing compression from oversupply.
- Monocrystalline:Single-crystal silicon ingots deliver conversion efficiencies above 22% under standard test conditions. Procurement concentrates in Riyadh and Abu Dhabi emirate where state-backed offtakers mandate premium performance specifications for gigawatt-scale developments.
- Bifacial:Dual-sided module architecture captures direct and albedo-reflected irradiance, boosting energy yield on sandy desert terrain. ACWA Power tenders specify bifacial exclusively for new utility-scale capacity, redirecting developer capital toward higher-wattage installations across Saudi Arabia's National Renewable Energy Programme pipeline.
- Polycrystalline:Multi-crystalline silicon cells occupy cost-sensitive commercial rooftop segments in Dubai's industrial zones where feed-in tariff compression favors lower capital intensity.
- Thin-Film:Cadmium telluride technology retains niche positioning in high-temperature desert environments where temperature coefficients favor its performance profile.
The dominant share belongs to Monocrystalline, while Bifacial is closing the gap fastest.
Technology:
Cell architecture choices determine qualification for premium procurement tiers, with n-type platforms displacing p-type inventory across GCC tender specifications.
- Crystalline Silicon:Dominant semiconductor platform spanning monocrystalline and polycrystalline variants. Procurement volumes anchor utility-scale power plants across Saudi Arabia and the UAE, with conversion efficiency thresholds now filtering supplier access to state-backed offtake contracts.
- Cadmium Telluride:Thin-film compound semiconductor optimized for high-irradiance, high-temperature operation. Desert installations in Saudi Arabia's central regions specify cadmium telluride where thermal performance offsets lower efficiency ratings.
- Copper Indium Gallium Selenide:Flexible thin-film technology targets building-integrated applications and weight-constrained commercial rooftops in Dubai and Sharjah.
- Perovskite:Emerging tandem-cell architecture in pilot deployment, with laboratory efficiencies challenging crystalline silicon benchmarks but commercial durability unproven in GCC climate stress testing.
Crystalline Silicon commands procurement volumes, though Cadmium Telluride defends niche positions in thermally stressed installations.
Application:
Revenue concentration tracks procurement scale, with utility-scale developments generating multi-year equipment contracts that dwarf distributed segment economics.
- Utility-Scale Power Plants:Centralized generation facilities exceeding 50MW capacity anchor GCC solar deployment. Saudi Power Procurement Company and Emirates Water and Electricity Company originate pipeline capacity that justifies dedicated module production lines from tier-one suppliers.
- Commercial Rooftops:Behind-the-meter installations on industrial and logistics facilities across Dubai's Jebel Ali corridor. Net metering framework tightening by EWEC is forcing self-consumption optimization and storage pairing to preserve project returns.
- Residential Installations:Distributed solar adoption remains underpenetrated relative to commercial segments across Sharjah and northern emirates, creating margin pools for segment-focused installers with local permitting expertise.
- Off-Grid Systems:Standalone solar-plus-storage configurations serve remote industrial and agricultural loads in Saudi Arabia's peripheral regions beyond centralized grid reach.
- Agriculture:Solar-powered irrigation and desalination applications in Saudi Arabia's agricultural investment zones, integrating PV with water infrastructure under state development mandates.
Utility-Scale Power Plants capture the dominant procurement volume, while Commercial Rooftops face the steepest policy-driven transformation.
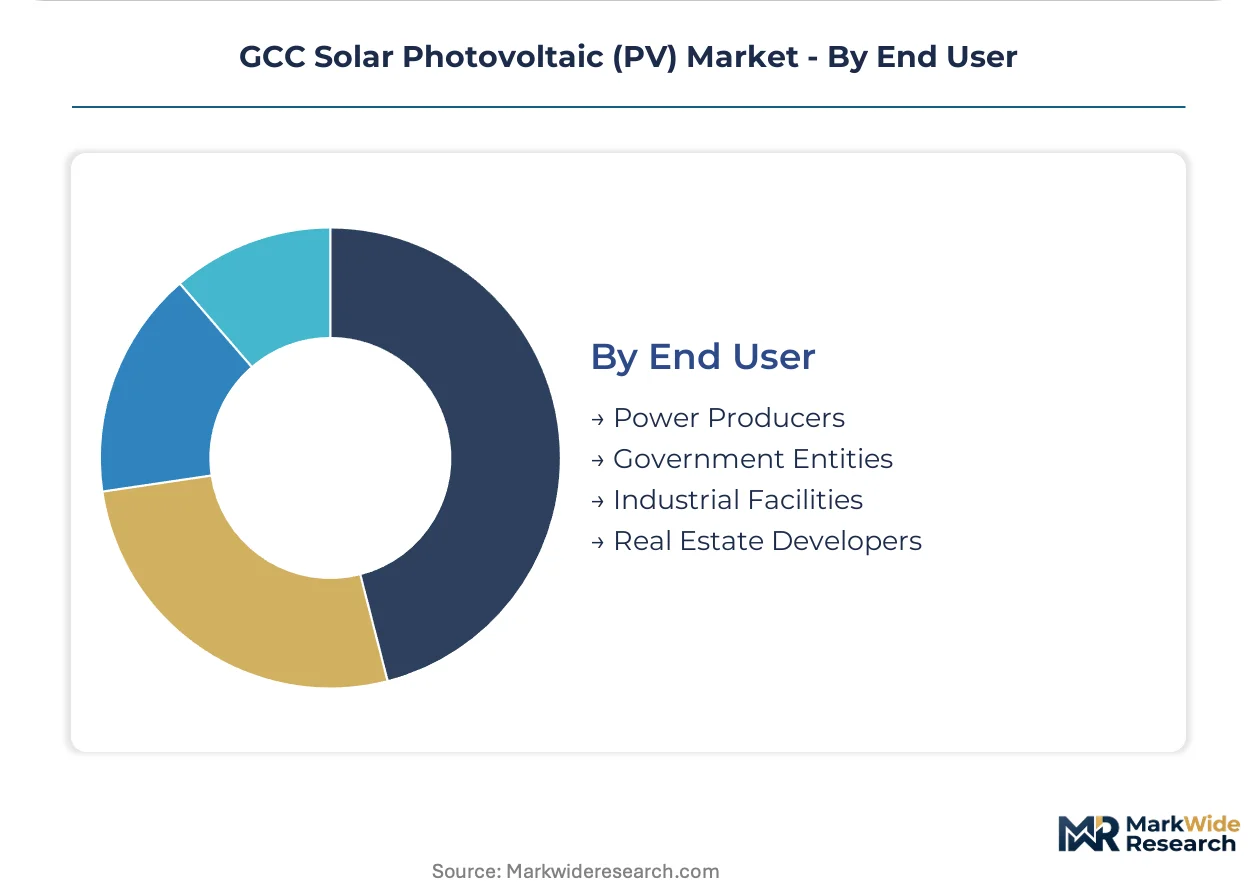
End User:
Customer concentration among state-backed entities compresses vendor negotiation leverage while rewarding established supply relationships with procurement decision-makers.
- Power Producers:ACWA Power and Saudi Power Procurement Company originate majority pipeline capacity, consolidating procurement decision-making across Riyadh-based tender processes and replacing fragmented commercial offtake structures.
- Government Entities:Ministry of Energy and related agencies administer Saudi Arabia's National Renewable Energy Programme, setting technical specifications and local content mandates that filter supplier qualification.
- Industrial Facilities:Energy-intensive manufacturing and petrochemical operations in Jubail and Yanbu industrial cities pursue behind-the-meter solar to hedge grid electricity exposure.
- Real Estate Developers:Master-planned community developers across Dubai South and Saudi giga-projects integrate rooftop solar into building specifications, responding to green building certification requirements.
Power Producers dominate procurement origination, with Government Entities controlling policy levers that reshape competitive access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC solar PV market relies entirely on imported modules and inverters, with no indigenous polysilicon or cell manufacturing capacity. This import dependency concentrates procurement leverage with Chinese suppliers while exposing developers to shipping cost volatility and currency fluctuation risks.
Saudi Arabia
Riyadh and the Eastern Province anchor utility-scale deployment through the National Renewable Energy Programme. The Saudi Standards, Metrology and Quality Organization enforces module certification protocols that filter supplier access. ACWA Power originates gigawatt-scale tenders from its Riyadh headquarters, consolidating procurement decision-making for central region solar parks.
United Arab Emirates
Abu Dhabi emirate dominates pipeline origination through Emirates Water and Electricity Company offtake guarantees. The Regulation and Supervision Bureau administers grid interconnection standards that impose costly inverter requirements. Masdar anchors project development in the emirate's industrial zones, integrating solar into port and logistics infrastructure.
Qatar
State-backed power procurement through Qatar General Electricity and Water Corporation drives utility-scale additions. The Ministry of Commerce and Industry oversees local content requirements that increasingly favor contractors with domestic assembly presence. Ras Laffan Industrial City concentrates solar-for-gas substitution projects at liquefaction facilities.
Oman
Independent power project frameworks administered by the Authority for Electricity Regulation attract developer consortia for utility-scale bids. Petroleum Development Oman integrates solar into enhanced oil recovery operations in the interior. Duqm Special Economic Zone hosts renewable-powered desalination and industrial load centers.
Kuwait
Shagaya Renewable Energy Park anchors the national transition strategy with phased solar and wind capacity. The Ministry of Electricity and Water oversees procurement that has faced repeated tender delays. Al-Jahra governorate concentrates early-phase installations with grid infrastructure proximity.
GCC Solar Photovoltaic (PV) Market Competitive Landscape
Concentration sits with integrated module suppliers possessing n-type TOPCon fabrication capacity and established relationships with Saudi and Emirati offtakers. Tier-one Chinese manufacturers anchor supply commitments through multi-year framework agreements, while regional developers like ACWA Power and Masdar consolidate origination leverage. Two strategic archetypes dominate: technology-differentiated cell manufacturers competing on conversion efficiency thresholds, and vertically integrated project developers bundling EPC and long-term O&M accountability. Competitive dynamics center on qualification for state-backed tender shortlists and backward integration into wafer and ingot production to secure polysilicon supply.
Among Chinese module suppliers, JinkoSolar Holding Co. Ltd, Longi Green Energy Technology Co. Ltd, and Trina Solar Co. Ltd occupy positions within the premium-tier supply segment. These manufacturers exemplify the technology-differentiated archetype, with n-type cell architectures qualifying for Saudi PPA awards and Abu Dhabi utility specifications. Canadian Solar Inc represents the integrated project development model, extending beyond component supply into EPC and O&M service bundling. First Solar Inc anchors the thin-film technology vector, occupying niche positioning where temperature coefficients favor its performance profile in high-irradiance desert conditions. Regional developers ACWA Power and Masdar Abu Dhabi Future Energy Company concentrate procurement origination, replacing fragmented commercial offtake with consolidated state-backed demand.
| Leading Market Players |
|---|
| Dubai Electricity and Water Authority |
| JinkoSolar Holding Co. Ltd |
| Canadian Solar Inc |
| Longi Green Energy Technology Co. Ltd |
| Trina Solar Co. Ltd |
| First Solar Inc |
| ACWA Power |
| JA Solar Technology Co. Ltd |
| Masdar Abu Dhabi Future Energy Company |
| Others |
Supply & Pricing Matrix
Bifacial module substitution for mono-PERC legacy inventory is simultaneously relocating procurement leverage toward Chinese n-type TOPCon manufacturers and compressing price premiums for single-sided alternatives across Saudi PPA and Abu Dhabi utility tenders.
Pricing Analysis
Industrial OEM buyers anchor project-based contract structures across GCC utility-scale developments. Three-tier pricing stratifies across premium n-type TOPCon, standard mono-PERC, and economy polycrystalline tiers differentiated by conversion efficiency certification and volume scale. Cost compression in standard-tier modules is intensifying because Chinese ingot and wafer oversupply is flooding procurement pipelines. State-backed offtakers exhibit lowest price sensitivity given sovereign guarantee backing, while commercial rooftop developers in Dubai face acute margin pressure from feed-in tariff compression.
Supply Chain Analysis
Module inventory lead times stretch from polysilicon ingot production through wafer slicing, cell fabrication, and final assembly across concentrated manufacturing zones. Upstream crystalline silicon supply draws from China, South Korea, and Malaysia, with polysilicon and wafer output clustered in Xinjiang and Jiangsu provinces. Logistics chokepoint exposure concentrates at Red Sea shipping corridors and Jebel Ali port clearance. Distribution runs through tier-one manufacturer direct sales to ACWA Power and Masdar, supplemented by regional EPC contractor procurement for smaller developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology bifurcation between n-type and p-type cell architectures fragments vendor tiers, creating white-space opportunities for specialists with certification agility and local content compliance capabilities.
For Market Incumbents: Fortify supply relationships with Saudi Power Procurement Company and Emirates Water and Electricity Company through dedicated n-type TOPCon production lines and backward integration into wafer manufacturing. Certification investment with Saudi Standards, Metrology and Quality Organization filters competitor access. Capacity addition in Saudi industrial zones responds to local content mandates threatening import-dependent suppliers.
For New Entrants and Emerging Players: Lead with residential rooftop installation and O&M service bundling across Sharjah and northern UAE emirates where state-backed offtaker concentration has left distributed segments underserved. Agricultural solar-for-water applications in Saudi investment zones offer penetrable entry points with less procurement competition than utility-scale tenders.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors integrated EPC-service providers with multi-decade asset accountability contracts. Long-term viability hinges on qualification for state-backed tender shortlists rather than commodity module sales. Signal to watch: Saudi domestic manufacturing incentive implementation altering import cost structures.
| Strategic Initiative | Industry Significance |
|---|---|
| n-Type TOPCon Capacity Expansion | Qualifies suppliers for Saudi PPA awards and Abu Dhabi utility specifications above 22% efficiency thresholds. |
| Backward Integration into Wafer Production | Reduces polysilicon supply concentration exposure and secures margin capture upstream from cell fabrication. |
| Saudi Manufacturing Joint Venture | Responds to local content mandates and industrial zone subsidies restructuring import-dependent supply economics. |
| Integrated EPC-O&M Service Bundling | Meets developer demand for single-contractor accountability across multi-decade asset performance obligations. |
| Residential Rooftop Channel Development | Captures underpenetrated distributed solar margins in Sharjah and Dubai commercial zones facing feed-in tariff compression. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with utility planning officers at Saudi Power Procurement Company, IPP project developers at ACWA Power, EPC contractors, grid interconnection specialists at Emirates Water and Electricity Company, and module procurement leads at tier-one manufacturers. Secondary validation drew from IEA renewable energy databases, FERC-style regulatory filings, project development pipeline trackers, customs import records, and technical certification registries. Bottom-up project-level capacity aggregation triangulated against top-down national renewable energy program targets.
Across the analysis window, volume and value outputs reflect segmented modeling across technology type, application tier, and end-user concentration. Crystalline silicon versus thin-film technology splits, utility-scale versus distributed application boundaries, and state-backed versus commercial offtaker categories anchored the analytical framework. CAGRs were derived from installed capacity trajectories and module price evolution curves, incorporating albedo-capture yield assumptions for bifacial deployment on desert terrain and grid interconnection cost inflation factors.
The analysis sits within stated boundaries; outcomes outside sustained Saudi National Renewable Energy Programme tendering velocity or significant trade policy disruption would require recalibration. Forecasts reflect documented assumptions regarding module efficiency improvement curves and polysilicon supply availability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Global Rooftop Solar Photovoltaic Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Frameless Solar Panel Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Mexico Solar Energy Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
United States Distributed Solar Power Generation Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Middle-East Solar Power Market
Solar Power Systems
Solar Metal Roof Market
Solar Power Systems
Global Solar Panel Materials Market
Solar Power Systems
Floating Photovoltaics (FPV) Market
Solar Power Systems
Bifacial Solar Module Market