
 Solar Panel Cleaning Equipment Market | 2026-2036
Solar Panel Cleaning Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Panel Cleaning Equipment Market Outlook
Subscription-based maintenance programs are decoupling equipment sales from long-term revenue models across the solar cleaning sector. Ecoppia leverages its robotic-as-a-service platform to anchor recurring contracts in desert climates. Serbot AG sustains European market presence through specialized gantry systems for agrivoltaic installations. SolarCleano differentiates via compact robotic units designed for residential rooftop access.
Solar panel cleaning equipment comprises mechanical, chemical, and automated systems engineered to remove soiling from photovoltaic surfaces without damaging anti-reflective coatings or frame seals. Robotic systems integrate soft-bristle brushes, deionized water jets, and autonomous navigation to restore optical transmittance and maintain nameplate efficiency. Waterless technology leads product-type growth in arid regions where conservation mandates restrict freshwater allocation for O&M activities. Automated systems command premium positioning in utility-scale deployments where labor costs and safety protocols favor machine-driven schedules. Chemical solutions occupy a mature niche concentrated in temperate climates with moderate soiling rates.
FERC grid interconnection standards and state-level renewable portfolio requirements in the US shape O&M budget allocations for utility operators. The EU Green Deal and REACH chemical restrictions influence formulation choices for European chemical solution providers. Saudi Arabia's dual carbon goals and national renewable targets drive procurement specifications for desert-adapted equipment. Stakeholders must weigh water-access constraints against automation capital requirements when configuring regional service portfolios.
Market Dynamics
Water scarcity mandates across arid solar belts are forcing equipment vendors to engineer dry-cleaning architectures that eliminate freshwater dependence entirely. This pressure is compressing development cycles for electrostatic and vibration-based removal systems.
Growth Catalysts
- EU Green Deal carbon-neutrality targets:European utility operators must maintain peak photovoltaic efficiency to meet renewable portfolio standards, expanding automated O&M budgets.
- Agrivoltaic dual-use installations:Farmers in France and Germany deploy specialized gantry cleaners that navigate between crop rows without disturbing vegetation.
- Saudi Arabia's renewable procurement surge:The national renewable program mandates sustained cleaning operations across gigawatt-scale desert deployments.
Market Restraints
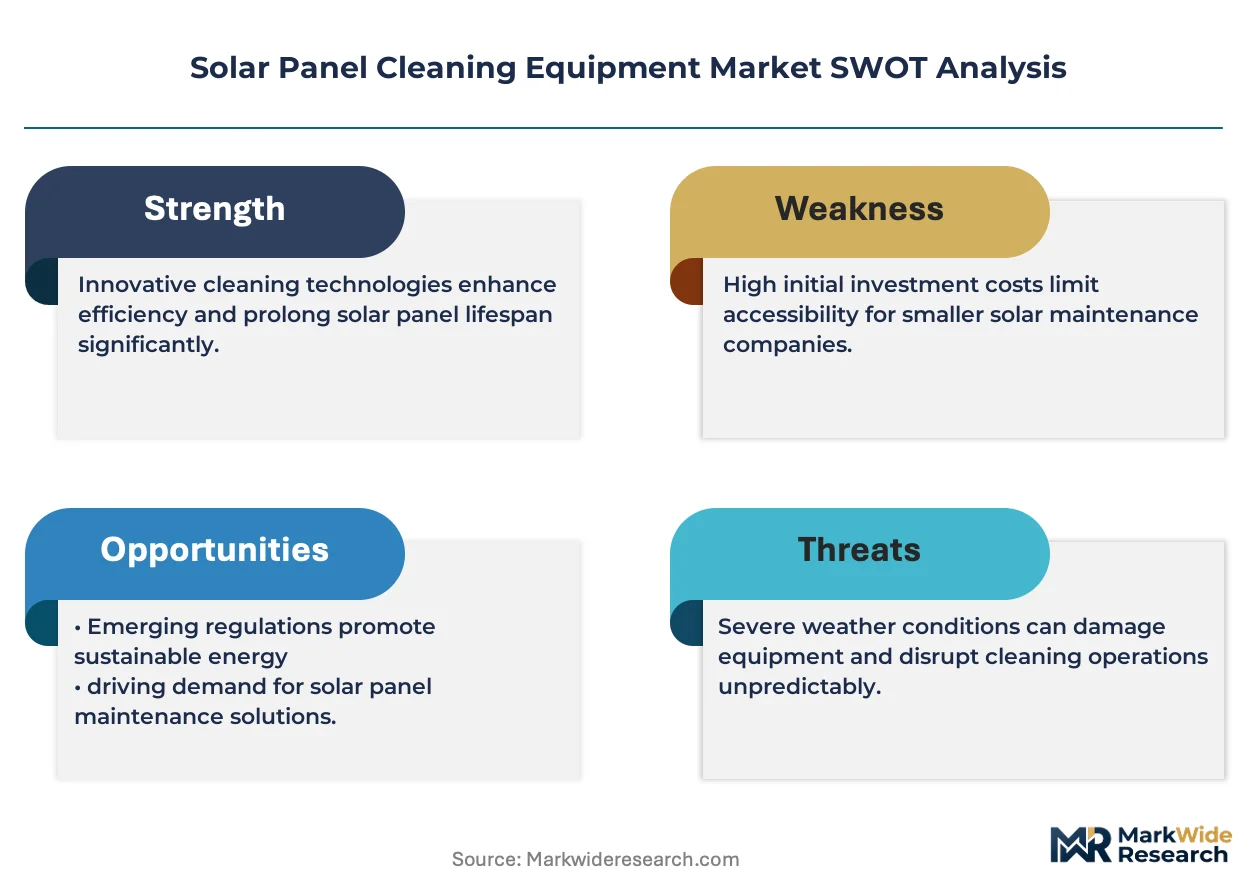
- Capital intensity of robotic fleets:Utility-scale automated systems require substantial upfront investment that strains independent service provider balance sheets.
- Silicon supply concentration:Photovoltaic module manufacturing clusters in China create downstream dependency that amplifies O&M timing uncertainty.
- REACH chemical authorization delays:European surfactant-based cleaning formulations face extended regulatory review timelines that freeze product launches.
Strategic Opportunities
- Residential rooftop penetration gaps:Compact robotic units for single-family homes remain underdeveloped relative to utility-scale solutions.
- FERC interconnection standardization:US grid reliability rules create predictable O&M budget lines that equipment vendors can target with service contracts.
- Electrostatic-vibration convergence:Hybrid dry-cleaning systems combining charge induction with micro-oscillation promise waterless performance in moderate soiling environments.
Industry Challenges
- Autonomous navigation certification:Safety validation for unmanned aerial and ground-based cleaners lacks harmonized standards across jurisdictions.
- Anti-reflective coating compatibility testing:Equipment manufacturers must verify brush materials and chemical formulations against proprietary photovoltaic surface treatments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Panel Cleaning Equipment Market |
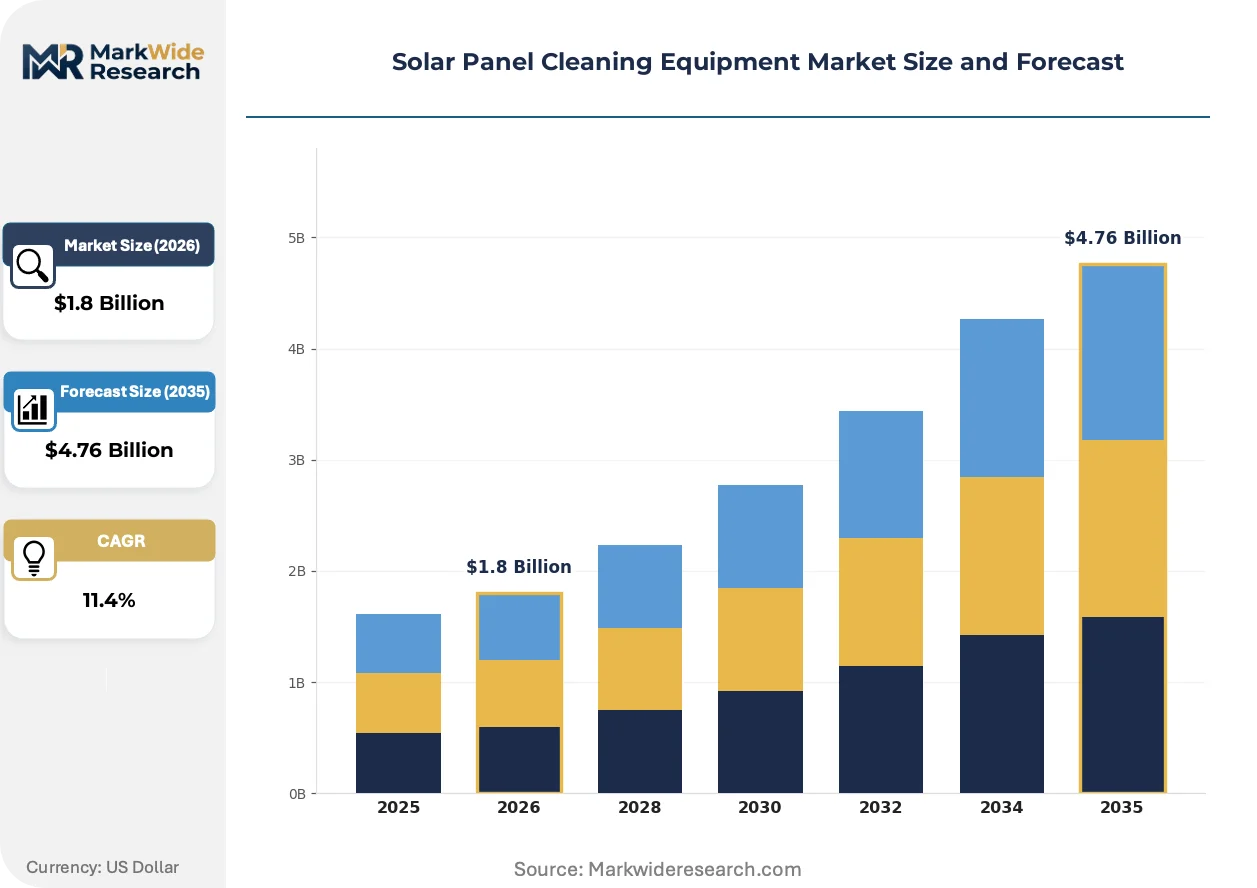
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Cleaners, Robotic Systems, Chemical Solutions, Pressure Washers Application: Residential, Commercial, Industrial, Utility Technology: Waterless, Automated, Conventional, Hybrid End User: Homeowners, Facility Managers, Energy Providers, Service Companies |
| Companies Covered | SolarCleano, Serbot AG, Ecoppia, Nomadd Desert Solar Solutions, Aegeus Technologies, BladeRanger, SunBrush mobil, Boson Robotics, Heliotex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Panel Cleaning Equipment Market Strategic Shifts
Equipment architecture is pivoting from standalone machines to integrated fleet-management platforms that synchronize cleaning schedules with weather forecasts and grid dispatch signals.
Electrostatic dry-cleaning systems are rewriting competitive positioning in water-stressed markets. These installations use charged particle attraction to lift dust without mechanical contact or liquids. Saudi Arabian and UAE solar farms are piloting these systems at 50-100 megawatt sites. The technology is compressing operational expenditure structures by eliminating water logistics entirely.
REACH chemical restrictions are reshaping formulation development priorities for European maintenance providers. Biodegradable surfactant alternatives now dominate R&D pipelines as legacy chemistries face authorization sunsets. German and Spanish chemical suppliers are accelerating plant-based compound testing to preserve market access.
Subscription-based service contracts are displacing capital-equipment purchases across Middle Eastern utility portfolios. Long-term performance guarantees now bundle hardware, software, and labor into single-line O&M budgets. This restructuring is most visible in Saudi Arabia's renewable tender documents, which specify outcome-based cleaning availability rather than asset ownership.
Solar Panel Cleaning Equipment Market Segmentation
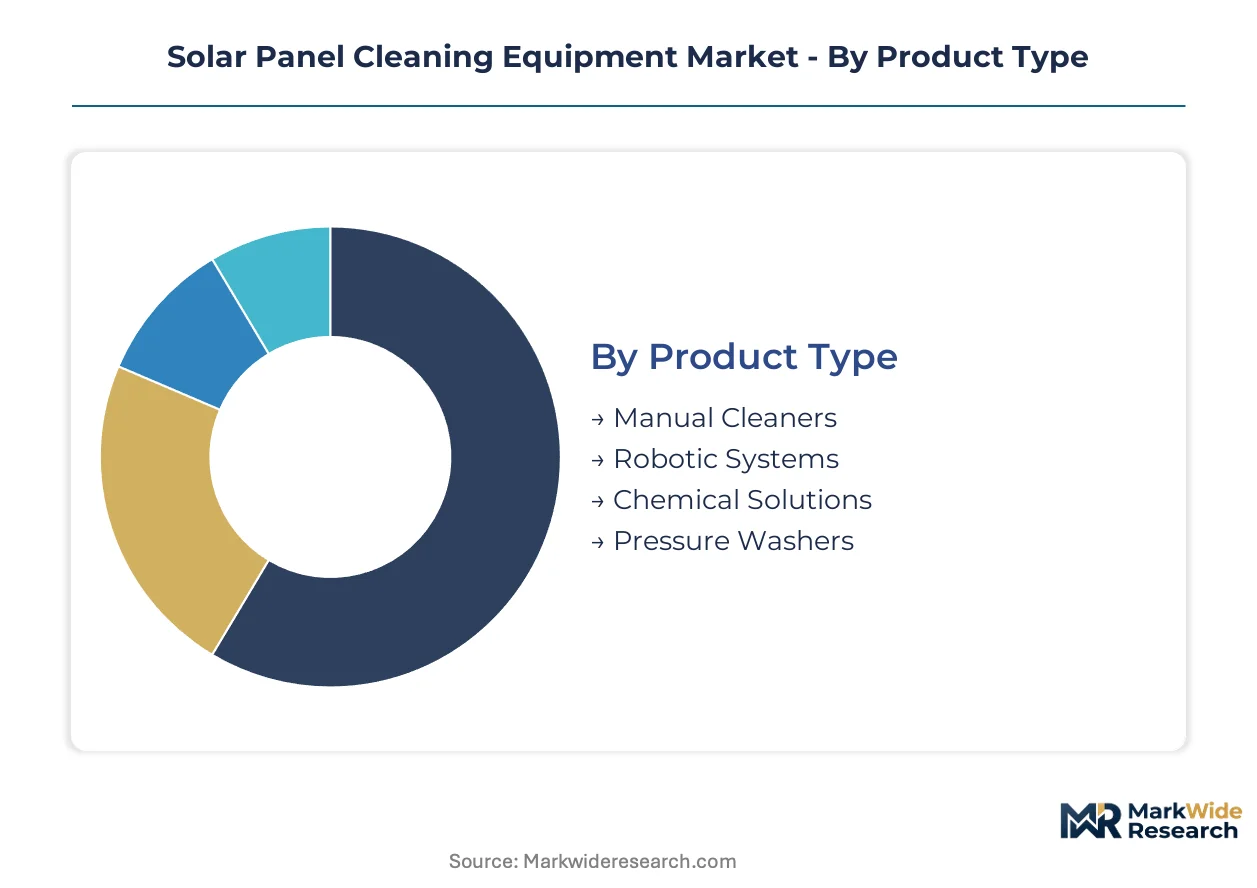
Equipment segmentation in the solar cleaning sector determines capital deployment patterns, O&M contract structures, and vendor specialization strategies. Procurement teams configure portfolios across product types, applications, and technologies based on site-specific soiling rates, water access constraints, and labor cost differentials.
Product Type:
Capital intensity varies sharply across this category, with robotic systems demanding the heaviest upfront investment while manual solutions preserve balance-sheet flexibility for smaller operators.
- Manual Cleaners:Handheld brushes, squeegees, and pole-mounted tools constructed from soft polymers to prevent anti-reflective coating damage. Demand clusters in residential Germany and commercial rooftops across France where labor costs remain manageable and site access restricts mechanized deployment.
- Robotic Systems:Autonomous ground-based and aerial units integrating soft-bristle brushes, deionized water jets, and GPS navigation for scheduled maintenance. Saudi Arabian utility-scale deployments absorb the majority of fleet orders as dust accumulation rates exceed 1% daily efficiency loss during shamal wind seasons.
- Chemical Solutions:Surfactant-based and biodegradable formulations engineered for moderate soiling in temperate climates. REACH authorization timelines in Europe constrain formulation launches.
- Pressure Washers:High-pressure water systems delivering targeted cleaning for ground-mounted installations with accessible infrastructure. Water-scarcity mandates in UAE and Jordan limit addressable market expansion.
Robotic systems absorb the bulk of installed capacity; waterless technology variants within this segment are expanding most quickly.
Application:
Site scale and ownership structure dictate equipment selection, with utility operators prioritizing automated fleets while residential adopters favor compact, manually operated solutions.
- Residential:Single-family and small multi-family rooftop installations requiring lightweight, portable equipment. German homeowners and Australian suburban markets drive procurement of compact robotic units designed for pitched-surface navigation.
- Commercial:Office buildings, warehouses, and retail facilities with flat or low-slope rooftop arrays. French agrivoltaic installations deploy specialized gantry systems that traverse crop rows without vegetation disturbance.
- Industrial:Manufacturing facilities and logistics centers with large rooftop footprints and 24/7 operational schedules. Night-cleaning protocols favor quiet robotic systems over pressure-based alternatives.
- Utility:Ground-mounted solar farms exceeding 10 megawatts with standardized panel configurations. Saudi Arabia's renewable procurement program specifies outcome-based cleaning availability across gigawatt-scale desert sites.
Utility applications command the largest equipment budgets; residential penetration gaps present the steepest expansion trajectory for compact automated solutions.
Technology:
Water dependence serves as the primary axis of technical differentiation, with arid-region mandates accelerating dry-cleaning architecture development cycles.
- Waterless:Electrostatic particle attraction and vibration-based dust removal eliminating freshwater logistics entirely. UAE and Saudi Arabian pilot programs at 50-100 megawatt sites validate operational expenditure compression.
- Automated:Machine-driven scheduling with weather-integrated fleet management platforms synchronizing cleaning cycles with grid dispatch signals. European utility operators under EU Green Deal targets expand automated O&M budgets.
- Conventional:Manual labor combined with basic water-fed pole systems for low-soiling environments. Mature technology with compressed margins.
- Hybrid:Combined electrostatic-vibration architectures promising waterless performance in moderate soiling conditions. Development pipelines concentrate in Israeli and Australian engineering centers.
Automated technology dominates current procurement volumes; waterless systems are gaining share fastest amid tightening conservation mandates.
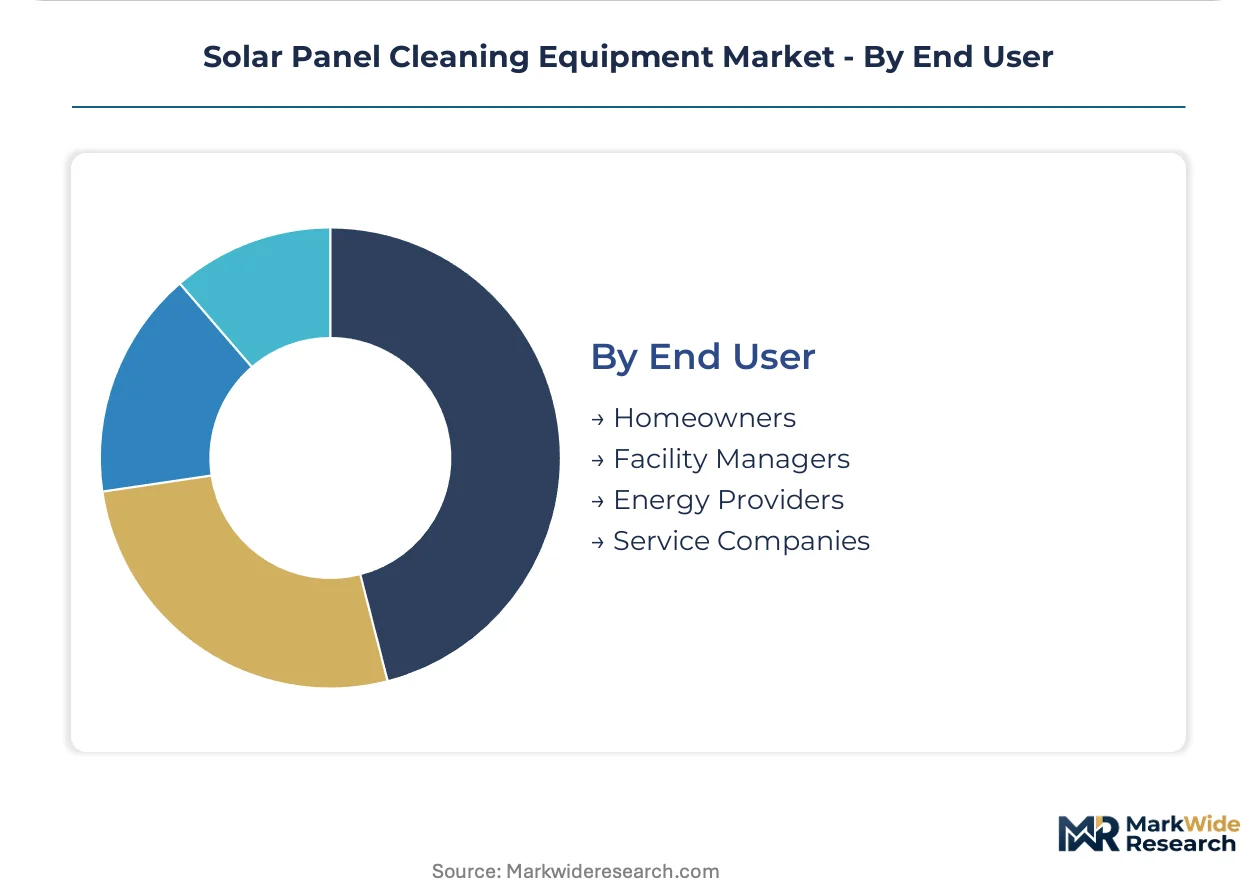
End User:
Procurement authority and technical sophistication vary across user types, with energy providers consolidating fleet purchasing power while service companies fragment across regional specialization.
- Homeowners:Individual residential adopters purchasing compact equipment through retail channels or bundled solar installation contracts. German and Australian markets show highest penetration.
- Facility Managers:Commercial and industrial property operators managing rooftop arrays as part of broader building maintenance portfolios. Subscription-based service contracts reduce capital burden.
- Energy Providers:Utility-scale solar operators with dedicated O&M departments and multi-site fleet standardization requirements. Saudi ACWA Power and similar entities drive tender specifications.
- Service Companies:Independent O&M contractors supplying cleaning labor and equipment across heterogeneous client bases. Balance-sheet constraints limit robotic fleet ownership.
Energy providers absorb the bulk of installed capacity; service companies are expanding most quickly through robotic-as-a-service platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment production clusters in Germany and China while consumption concentrates in Saudi Arabia and the southwestern United States. Desert solar belts generate disproportionate demand for automated cleaning fleets. Water-scarcity mandates in arid jurisdictions accelerate dry-cleaning technology deployment cycles.
Saudi Arabia
ACWA Power and other national renewable operators drive procurement of robotic cleaning fleets across gigawatt-scale desert installations. The national renewable program mandates sustained cleaning operations with outcome-based availability contracts rather than equipment ownership. Riyadh-based engineering centers coordinate fleet deployment across the Kingdom's western and eastern solar corridors.
United States
Utility-scale operators in California and Arizona expand automated O&M budgets to maintain peak efficiency under FERC grid interconnection standards. The Inflation Reduction Act extends tax credits that indirectly support cleaning equipment capitalization. Phoenix and Las Vegas metropolitan clusters host service company headquarters targeting southwestern desert installations.
Germany
Agrivoltaic dual-use installations in Bavaria and Baden-Württemberg deploy specialized gantry cleaners navigating between crop rows. REACH chemical restrictions from ECHA reshape formulation priorities for European maintenance providers. Stuttgart engineering firms concentrate development of biodegradable surfactant alternatives.
United Arab Emirates
Mohammed bin Rashid Al Maktoum Solar Park and similar utility-scale sites pilot electrostatic dry-cleaning systems at 50-100 megawatt installations. MOHAP water conservation mandates eliminate freshwater allocation for O&M activities. Dubai-based project developers specify waterless technology in tender documentation for new solar phases.
Australia
Residential rooftop markets in New South Wales and Queensland absorb compact robotic units designed for pitched-surface navigation. State-level renewable energy targets pressure homeowners to maintain panel efficiency without manual labor exposure. Sydney and Melbourne distributors expand retail channels for automated cleaning equipment.
Solar Panel Cleaning Equipment Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the solar cleaning equipment sector. The vendor base separates into integrated system manufacturers, specialized component suppliers, and robotic-as-a-service platform operators. Three strategic archetypes dominate: desert-adapted utility-scale specialists, European agrivoltaic gantry providers, and compact residential robotics developers. Competitive dynamics center on strategic partnerships with EPC contractors and technology licensing agreements for dry-cleaning architectures.
Among Israeli and Middle Eastern automation specialists, Ecoppia anchors the robotic-as-a-service archetype through recurring contract structures. Serbot AG exemplifies European gantry specialization for agricultural co-location sites. SolarCleano occupies a position within the residential compact robotics tier. These three entities represent distinct geographic and application-focused strategies without overlapping core market positions.
| Leading Market Players |
|---|
| SolarCleano |
| Serbot AG |
| Ecoppia |
| Nomadd Desert Solar Solutions |
| Aegeus Technologies |
| BladeRanger |
| SunBrush mobil |
| Boson Robotics |
| Heliotex |
| Others |
Value Chain & Pricing Dynamics
Automation engineering talent concentration in Stuttgart and Tel Aviv generates labor-cost differentials that widen pricing-tier spreads between European precision systems and Middle Eastern desert-adapted fleets. Tiered pricing separates premium robotic-as-a-service contracts from standard equipment sales and economy-grade manual toolkits.
Pricing Analysis
Margin tightening in economy manual-cleaner tiers traces to oversupply of basic pole-mounted tools from Chinese manufacturers. Three-tier pricing structure across premium robotic fleets, standard automated units, and economy manual equipment dominates procurement. Pricing pressure intensifies in standard tiers as Saudi utility tenders mandate outcome-based availability over asset ownership. Residential homeowners exhibit highest price sensitivity; Middle Eastern energy providers accept premium positioning for guaranteed uptime.
Supply Chain Analysis
Freight cost volatility from Red Sea routing disruptions amplifies landed cost variance for European gantry systems destined for Gulf solar corridors. Component manufacturing concentrates in Germany, China, and Israel. Brush assembly and navigation modules draw from precision engineering clusters; steel framing and waterless electrostatic components rest on specialty chemical supply. Single-source vulnerability in lithium-ion battery cells for robotic fleets threatens fleet deployment timelines. Distribution runs through EPC contractor integration and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar panel cleaning equipment sector occupies a technology-transition phase where electrostatic dry-cleaning architectures displace water-dependent legacy systems across desert solar belts.
For Market Incumbents: Lock in recurring revenue streams by converting capital-equipment buyers to subscription-based robotic-as-a-service contracts. Deepen backward integration into brush material production to defend margin position against commodity polymer price swings. Prioritize certification investment for autonomous navigation safety standards before harmonized EU-US frameworks emerge.
For New Entrants and Emerging Players: Residential rooftop owners in Australian and German suburban markets remain underserved by compact robotic solutions. Agrivoltaic dual-use installations in France present penetrable white-space for specialized gantry developers. Pursue channel partnerships with residential solar installers rather than direct retail distribution.
For Investors and Strategic Acquirers: Re-rating potential sits with waterless technology specialists given tightening conservation mandates across Middle Eastern and southwestern US jurisdictions. Long-term viability hinges on electrostatic-vibration hybrid platform adoption. Target acquisition archetypes include Israeli dry-cleaning engineering firms with validated pilot data. Watch for Saudi ACWA Power tender specifications mandating waterless technology as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Robotic-as-a-Service Platform Launch | Ecoppia's recurring contract model anchors long-term revenue visibility in desert climates. |
| Waterless Technology Licensing | Electrostatic system patents from Israeli engineering centers unlock UAE and Saudi market access. |
| Agrivoltaic Gantry Specialization | Serbot AG's crop-row navigation systems capture French dual-use installation growth. |
| Residential Compact Robotics Development | SolarCleano's pitched-surface units address Australian homeowner demand without manual labor exposure. |
| REACH-Compliant Formulation Transition | German chemical suppliers' biodegradable surfactant pipelines preserve European market access amid authorization sunsets. |
Study Parameters
Independent corroboration across EPC contractor interviews, utility O&M director consultations, and robotic fleet operator surveys underwrites the qualitative findings. Primary fieldwork engaged plant engineers at Saudi ACWA Power installations, procurement leads at French agrivoltaic developers, and aftermarket service heads at German distribution channels. Secondary validation drew from FERC interconnection filings, EU Green Deal implementation documents, and Saudi renewable tender databases. Bottom-up equipment shipment tracking triangulates against top-down utility O&M budget allocations.
Comparable-period anchoring to historical deployment cycles across the analysis window informs growth trajectory calibration. Segmentation modeling spans product type, application scale, technology architecture, and end-user procurement authority. CAGRs derive from installed base expansion rates and replacement cycle timing. Forecast inputs incorporate REACH authorization timelines for European chemical formulations and MOHAP water conservation mandate enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrostatic technology validation at scale and autonomous navigation regulatory harmonization. Forecasts reflect documented assumptions around Saudi renewable procurement pace and silicon supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Global Solar PV Balance of System Market
Solar Power Systems
Organic PV Solar Cells Market
Solar Power Systems
Solar Polysilicon Ingot Wafer Cell Module Market
Solar Power Systems
Global Dye-Sensitized Solar Cells (Dssc) Market
Solar Power Systems
Canada Distributed Solar Power Generation Market
Solar Power Systems
Solar Panel Bracket Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Solar PV Inverter Market
Solar Power Systems
Biohybrid Solar Cell Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Residential Solar Panels Market
Solar Power Systems
Europe Solar Charging Station Market
Solar Power Systems
Hybrid Solar Panel Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Global Solar Panel Materials Market