
 Oil and Gas Pipeline Coatings Market | 2026-2036
Oil and Gas Pipeline Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Pipeline Coatings Market Outlook
EPA methane performance standards and buyer ESG mandates is hardening requirements for corrosion-resistant, low-emission pipeline coatings across North American infrastructure networks. AkzoNobel N.V. leverages its marine and protective coatings heritage to sustain long-term supply relationships with offshore operators. PPG Industries, Inc. anchors its position through specialized fusion bonded epoxy formulations designed for extreme temperature differentials. The Sherwin-Williams Company dominates distribution channels across the United States midstream sector, controlling access to maintenance procurement networks.
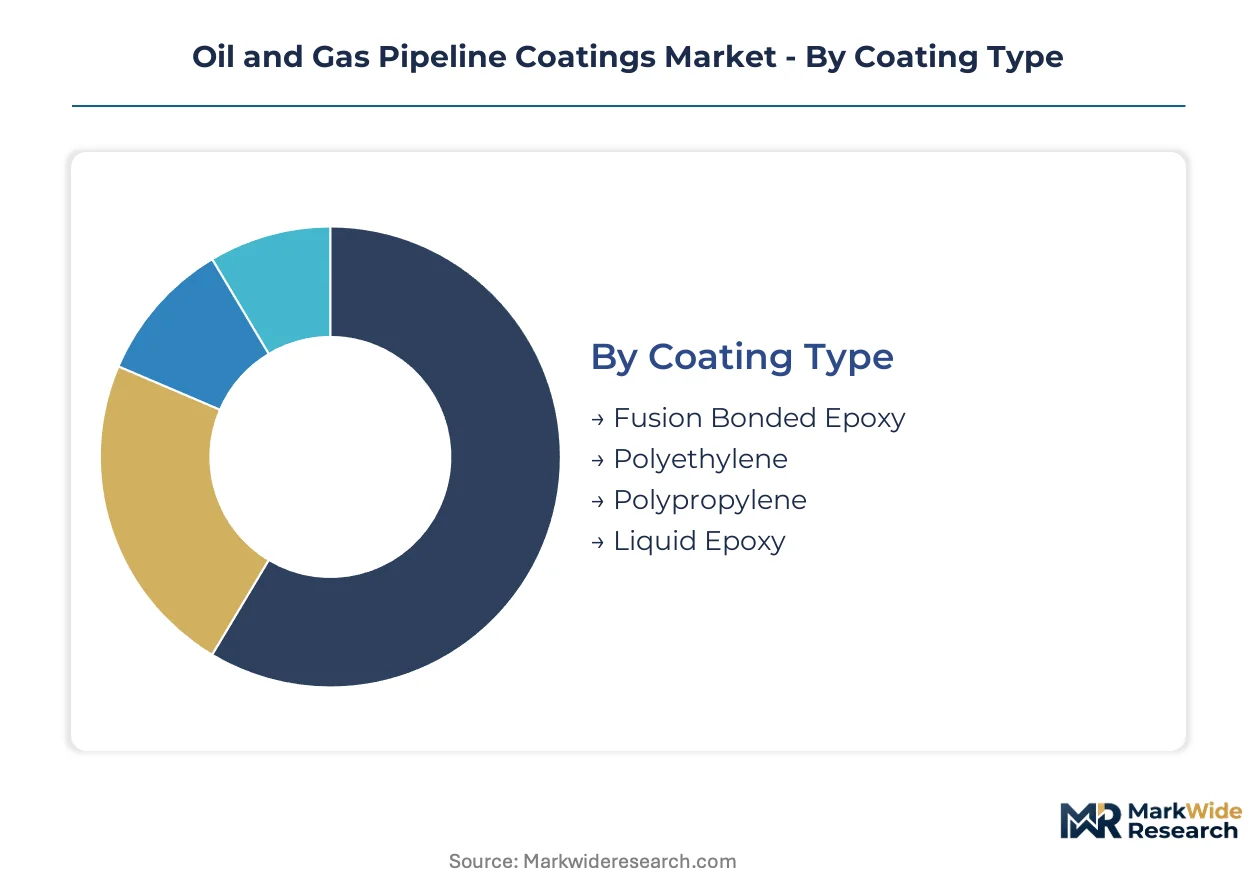
Oil and gas pipeline coatings comprise engineered barrier systems—typically 250–600 micron dry film thickness for fusion bonded epoxy layers—applied to steel substrates to prevent electrochemical degradation, reduce thermal losses, and maintain hydrocarbon flow efficiency. Fusion Bonded Epoxy coatings occupy the largest value share due to proven cathodic disbondment resistance and decades of field verification in buried pipelines. Polypropylene segments are gaining traction in deepwater installations where mechanical protection and thermal insulation requirements converge. Liquid Epoxy formulations compete in rehabilitation markets where in-situ application constraints exclude factory-applied powder systems.
EPA standards, NACE International guidelines, and ISO 21809 specifications collectively define qualification protocols for coating adhesion, impact resistance, and cathodic compatibility in oil and gas transmission infrastructure. These frameworks create differentiated market access tiers: coatings certified to full ISO 21809-2 pipeline standards command premium positioning in cross-border projects, while formulations meeting only regional utility specifications serve localized distribution networks. Stakeholders must monitor evolving EPA methane rules and emerging state-level pipeline integrity mandates to anticipate specification shifts before contract renewal cycles.
Market Dynamics
Offshore pipeline infrastructure aging across the North Sea, Gulf of Mexico, and South China Sea is forcing operators to triple protective coating maintenance cycles. Subsea corrosion rates accelerate as water depths increase thermal stress differentials, while REACH and EPA volatile organic compound thresholds harden formulation requirements.
Growth Catalysts
- Deepwater Polypropylene Adoption:Brazil's pre-salt fields and Angola's offshore blocks drive demand for thermal insulation coatings that merge mechanical protection with flow assurance.
- EPA Methane Performance Standards:New leak detection mandates require corrosion-resistant barrier systems that eliminate pinhole failures triggering fugitive emissions.
- United States Gulf Coast Petrochemical Density:Concentrated refinery and export terminal clusters generate recurring recoating demand from cyclic maintenance programs.
Market Restraints
- Epoxy Resin Price Volatility:Benzene and bisphenol-A feedstock fluctuations compress coating manufacturer margins unpredictably.
- Specialized Applicator Concentration:Factory-applied fusion bonded epoxy capacity clusters among three United States Gulf Coast coating yards, creating queue bottlenecks.
- Cathodic Disbondment Thresholds:ISO 21809-2 adhesion requirements exclude lower-cost liquid epoxy alternatives from cross-border transmission projects.
Strategic Opportunities
- India Pipeline Network Expansion:The country's national petroleum regulator mandates 15,000 kilometers of new transmission lines by 2030, opening specification contests for imported coating systems.
- Carbon Capture Transport Infrastructure:CO2 pipeline metallurgy requires modified coating chemistries resistant to supercritical acid gas permeation.
- Robotic In-Situ Rehabilitation:Crawler-deployed spray systems enable recoating without pipeline shutdown, unlocking maintenance revenue from operating assets.
Industry Challenges
- Certified Coating Inspector Shortage:NACE International-qualified professionals for holiday detection and thickness verification command premium wages, extending project timelines.
- Legacy Pipeline Substrate Variability:Inconsistent surface preparation standards from 1970s construction complicate rehabilitation adhesion guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Pipeline Coatings Market |
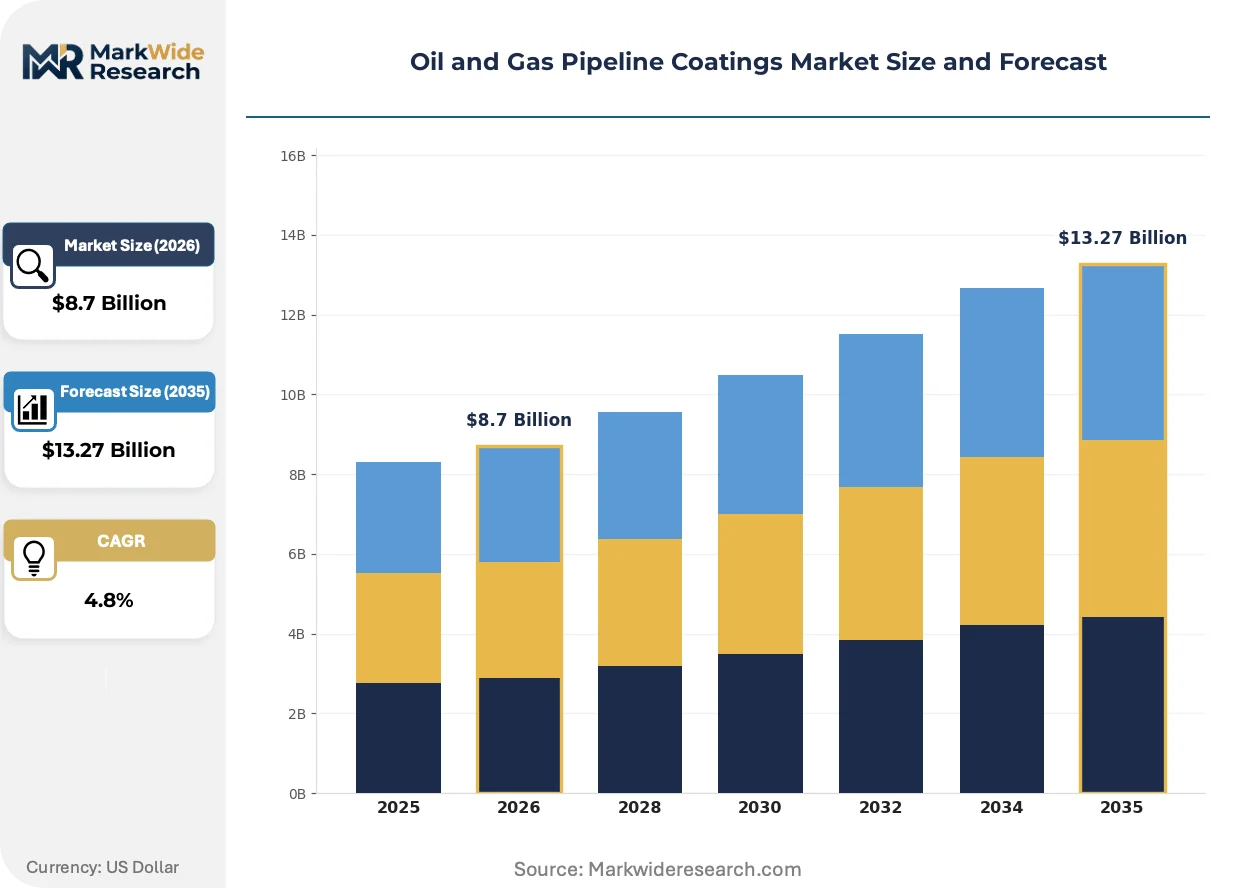
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Fusion Bonded Epoxy, Polyethylene, Polypropylene, Liquid Epoxy End User: Upstream, Midstream, Downstream, Oil Refineries Application: Corrosion Protection, Thermal Insulation, Flow Assurance, Safety Enhancement Form: Liquid, Powder, Tape, Multi-layer |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Shawcor Ltd., 3M Company, Axalta Coating Systems Ltd., BASF SE, Hempel A/S, Jotun Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Pipeline Coatings Market Strategic Shifts
Pipeline coating specification is fragmenting as digital inspection technologies compress quality verification cycles. Buyers now demand real-time thickness mapping and automated holiday detection, forcing applicators to integrate sensor platforms into production lines.
Ultrasonic robotic crawlers is automating coating thickness verification across subsea pipelines previously requiring diver inspection. Offshore operators in the North Sea deploy these platforms quarterly, eliminating weather-dependent manual surveys. The technology is compressing maintenance scheduling from calendar-based to condition-based intervals.
REACH authorization requirements for chromium trioxide in corrosion inhibitors are forcing reformulation of primer systems used in European transmission networks. Coating manufacturers must submit substitution plans to ECHA by fixed deadlines or lose market access. German and Dutch pipeline operators now specify trivalent chromium alternatives in new procurement tenders.
Integrated service contracts now bundle coating application with cathodic protection installation and integrity monitoring. United States midstream companies favor single-source accountability over fragmented subcontractor management. This procurement consolidation favors applicators with in-house electrical engineering capabilities for sacrificial anode systems.
Oil and Gas Pipeline Coatings Market Segmentation
Pipeline coating selection hinges on substrate metallurgy, operating temperature, and cathodic protection compatibility. Specification mismatches trigger premature disbondment, forcing recoating cycles that multiply lifecycle costs. Buyers segment procurement by performance tier rather than price alone.
Coating Type:
Specification hierarchies separate factory-applied powder systems from field-applied liquid alternatives, with thermal insulation demands creating a third tier for deepwater service.
- Fusion Bonded Epoxy:Thermosetting powder coatings cure at 200–250°C to form 250–600 micron barrier films with proven cathodic disbondment resistance. United States Gulf Coast transmission projects specify this grade exclusively for cross-border lines requiring ISO 21809-2 certification. Demand concentrates in new-build onshore infrastructure where factory application ensures uniform thickness.
- Polypropylene:Multi-layer systems combine fusion bonded epoxy primers with thick polypropylene topcoats for mechanical protection plus thermal insulation. Brazil's pre-salt fields and Angola's offshore blocks drive procurement for flow assurance in deepwater production risers. Operators specify these systems where temperature differentials exceed 50°C across the pipe wall.
- Polyethylene:Extruded or tape-applied systems serve distribution networks and lower-pressure gathering lines where impact resistance outweighs thermal performance. Municipal gas utilities in Germany and the Netherlands specify polyethylene for localized rehabilitation projects.
- Liquid Epoxy:Two-component solvent-free formulations enable in-situ application on operating pipelines where shutdown is economically prohibitive. Maintenance contractors deploy these systems for spot repairs and girth weld coatings in mature North Sea infrastructure.
Fusion Bonded Epoxy leads on scale; Polypropylene leads on momentum.
End User:
Procurement authority and specification stringency vary sharply across the hydrocarbon value chain, with midstream operators commanding the largest coating volumes.
- Midstream:Transmission pipeline operators manage the highest coating expenditures, specifying fusion bonded epoxy for cross-border trunk lines and liquid epoxy for integrity management programs. United States interstate systems under FERC jurisdiction mandate coating performance verification through hydrostatic testing protocols.
- Upstream:Exploration and production companies drive specialty demand for thermal insulation coatings in subsea tiebacks and flowlines. Offshore operators in the Gulf of Mexico specify multi-layer polypropylene for high-pressure high-temperature reservoirs.
- Downstream:Product pipeline operators prioritize chemical resistance for refined product service, specifying modified epoxy formulations for gasoline and diesel transmission. Terminal operators in Rotterdam and Singapore harbor districts drive recurring maintenance demand.
- Oil Refineries:Process unit piping and tankage require high-temperature resistant coatings for service above 120°C. Refinery turnarounds in the United States Gulf Coast petrochemical cluster generate concentrated procurement windows.
Midstream dominates absolute volume; Upstream commands the steepest expansion trajectory.
Application:
Functional requirements determine coating thickness, chemistry, and inspection protocols, with corrosion protection forming the baseline specification across all installations.
- Corrosion Protection:Electrochemical barrier systems prevent substrate oxidation through dielectric isolation combined with cathodic protection compatibility. Buried steel pipelines in saline soils require enhanced adhesion grades to prevent underfilm corrosion.
- Thermal Insulation:Thick-film syntactic foam and polypropylene systems minimize heat loss in subsea production flowlines. Deepwater Brazil pre-salt developments specify these coatings to maintain crude oil temperature above wax appearance points.
- Flow Assurance:Low-surface-energy coatings reduce paraffin and asphaltene deposition in waxy crude service. Operators in Angola and Nigeria deploy these systems to minimize pigging frequency.
- Safety Enhancement:Fire-resistant coatings provide hydrocarbon pool fire protection for platform risers and process piping. North Sea regulatory authorities mandate these systems for personnel evacuation route protection.
Corrosion Protection anchors installed base; Thermal Insulation is gaining share fastest.
Form:
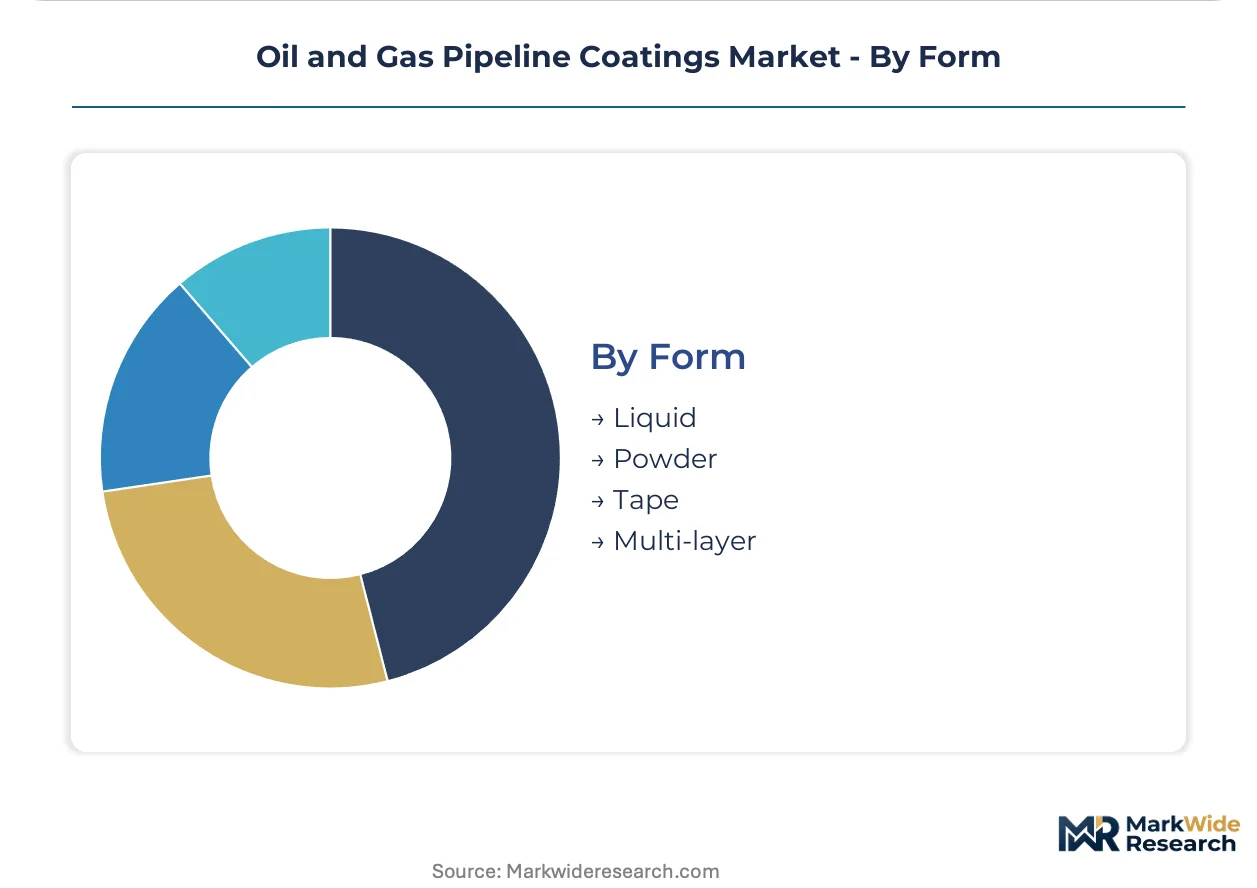
Application methodology constrains form selection, with powder systems requiring dedicated coating yards while liquid and tape systems enable field deployment.
- Powder:Electrostatically applied fusion bonded epoxy requires heated substrate conditions achievable only in factory environments. Three United States Gulf Coast coating yards control the majority of new pipe pre-coating capacity.
- Liquid:Brush, spray, or roller-applied formulations serve rehabilitation markets and girth weld field joints. Robotic crawler systems now enable subsea liquid epoxy application without diver intervention.
- Tape:Cold-applied polyethylene and polypropylene tapes provide mechanical protection for pipeline bends and fittings. These systems dominate repair and maintenance procurement for operating assets.
- Multi-layer:Factory-applied systems combine fusion bonded epoxy, adhesive, and polyolefin layers in single-pass extrusion. Deepwater projects in the South China Sea specify these systems for combined corrosion and mechanical protection.
Powder commands manufacturing scale; Multi-layer systems are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pipeline coating technology originated in the United States Gulf Coast petrochemical corridor during the 1950s, where fusion bonded epoxy formulations first achieved commercial scale for buried transmission lines. This heritage established technical standards that now propagate through offshore developments across three continents.
United States
The Gulf Coast petrochemical cluster generates recurring maintenance demand from cyclic turnaround programs at refineries in Texas and Louisiana. EPA methane performance standards harden specifications for corrosion-resistant barrier systems that eliminate pinhole failures. Houston anchors the nation's factory-applied coating capacity, with three specialized yards controlling majority pre-coating throughput for new pipeline construction.
Brazil
Pre-salt deepwater fields drive procurement for multi-layer polypropylene systems that merge thermal insulation with mechanical protection. The national petroleum regulator mandates flow assurance coatings to maintain crude temperature above wax appearance points. Operators in the Santos Basin specify these systems where temperature differentials exceed 50°C across pipe walls.
Germany
REACH authorization requirements for chromium trioxide force reformulation of primer systems used in transmission networks. ECHA deadlines compel coating manufacturers to submit substitution plans or surrender market access. Pipeline operators in the Ruhr industrial district now specify trivalent chromium alternatives in procurement tenders for rehabilitation projects.
China
The national petroleum regulator mandates 15,000 kilometers of new transmission lines by 2030, opening specification contests for imported coating systems. GB standards and evolving environmental regulations tighten volatile organic compound thresholds for formulation approval. Manufacturing clusters in Shandong Province concentrate domestic production capacity for fusion bonded epoxy powders serving Central Asian export routes.
Norway
North Sea regulatory authorities mandate fire-resistant coatings for platform risers and process piping protecting personnel evacuation routes. Offshore operators deploy ultrasonic robotic crawlers quarterly for coating thickness verification, eliminating weather-dependent diver surveys. Stavanger-based engineering firms specify these systems for subsea tiebacks in high-pressure high-temperature reservoirs.
Oil and Gas Pipeline Coatings Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the coating value chain, creating a tiered structure where integrated chemical conglomerates face specialized applicators with dedicated yard capacity. The market fragments across three strategic archetypes: diversified coatings multinationals with marine heritage, industrial chemical suppliers with resin backward integration, and regional service contractors with captive application infrastructure. Dominant competitive moves include portfolio diversification into adjacent protective coatings segments and geographic expansion through licensing arrangements with national oil companies.
Within the diversified multinational tier, AkzoNobel N.V. and PPG Industries, Inc. occupy positions reflecting decades of marine and protective coatings heritage. The Sherwin-Williams Company exemplifies distribution-channel dominance through midstream sector procurement network control. Among European chemical suppliers, BASF SE and Hempel A/S represent resin integration strategies that compress formulation cost structures. These archetypes illustrate how competitive positioning hinges on whether players control raw material supply, application capacity, or downstream distribution access.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Shawcor Ltd. |
| 3M Company |
| Axalta Coating Systems Ltd. |
| BASF SE |
| Hempel A/S |
| Jotun Group |
| Others |
Value Chain & Pricing Dynamics
ISO 21809-2 certification tiers split the market into premium cross-border specifications and regional utility grades, with this bifurcation driving divergent sourcing strategies and margin structures across coating manufacturers. Premium formulations command dedicated production lines at United States Gulf Coast coating yards, while commodity liquid epoxies flow through distributed applicator networks serving maintenance markets.
Pricing Analysis
Project-based contract pricing dominates, with coating applicators bidding fixed-price packages for new-build factory application and time-and-materials arrangements for rehabilitation work. Price differentiation rests on certification grade and volume scale, with ISO 21809-2 qualified systems carrying substantial premiums over regional utility specifications. Pricing pressure stems from benzene and bisphenol-A feedstock volatility compressing manufacturer margins. Midstream transmission operators show least price sensitivity due to lifecycle cost focus, while municipal gas utilities in rehabilitation markets drive hardest bargain negotiations.
Supply Chain Analysis
Epoxy resin supply rests on petrochemical producers in the United States Gulf Coast, German chemical conglomerates, and Chinese manufacturing clusters in Shandong Province. Critical inputs include benzene feedstock, bisphenol-A intermediates, and specialty curing agents. Single-source vulnerability concentrates in fusion bonded epoxy powder production, where three United States Gulf Coast coating yards control majority pre-coating capacity. Distribution runs through applicator-owned yards for factory-applied systems and regional service contractors for field deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market has entered a late-cycle quality phase where specification premiums widen as offshore operators prioritize thermal insulation performance and EPA methane compliance hardens barrier system requirements.
For Market Incumbents: Lock in applicator yard capacity through long-term offtake agreements with United States Gulf Coast coating facilities to defend against queue bottlenecks. Secure backward integration into specialty epoxy resin supply to buffer benzene price volatility. Prioritize ISO 21809-2 certification maintenance to sustain premium positioning as REACH and EPA thresholds tighten.
For New Entrants and Emerging Players: Regional service contractors with robotic crawler deployment capabilities offer the most penetrable entry point, as ultrasonic thickness verification and in-situ rehabilitation demand outpaces qualified applicator supply. Target India's 15,000 kilometer pipeline expansion program where imported coating specifications remain contested. Lead with integrated service contracts bundling coating application with cathodic protection installation.
For Investors and Strategic Acquirers: Consolidation pressure builds where factory-applied coating capacity concentrates among three United States Gulf Coast yards and certified NACE inspector shortages extend project timelines. Acquisition target archetype: regional applicators with captive yard infrastructure and in-house electrical engineering capabilities for sacrificial anode systems. Watch carbon capture transport infrastructure specifications as inflection indicator for modified coating chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | United States Gulf Coast coating yards add fusion bonded epoxy lines to relieve queue bottlenecks for cross-border transmission projects. |
| Backward Integration | Coating manufacturers secure captive benzene and bisphenol-A supply to compress formulation cost structures against feedstock volatility. |
| Long-term Supply Agreement | Offshore operators in Brazil's pre-salt fields lock in multi-layer polypropylene procurement for deepwater flow assurance requirements. |
| Joint Venture | European coating suppliers partner with Indian applicators to meet national petroleum regulator mandates for 15,000 kilometers of new transmission lines. |
| Technology Licensing | Robotic crawler spray system developers license platforms to regional maintenance contractors for subsea rehabilitation without pipeline shutdown. |
Study Parameters
Coverage spans the United States Gulf Coast, Brazil, Germany, China, and Norway, with primary inputs from each region's coating applicators, midstream procurement directors, offshore project engineers, and regulatory compliance officers. Secondary validation draws from EPA methane rule filings, REACH authorization submissions to ECHA, ISO 21809 certification registries, and FERC interstate pipeline integrity reports. Bottom-up volume estimates triangulate against top-down petrochemical infrastructure spending analysis.
Granularity-level modeling operates at coating type, end user segment, application function, and form factor dimensions across the projection horizon. CAGRs derive from segment-level volume trajectories weighted by regional infrastructure investment cycles. Industry-specific forecast inputs include subsea tieback project pipelines in Brazil and Angola, United States Gulf Coast petrochemical turnaround schedules, and India's national transmission expansion mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA methane rule evolution, REACH authorization timelines for chromium trioxide substitution, and carbon capture transport infrastructure specification development. Forecasts reflect documented assumptions regarding regulatory trajectory and feedstock price normalization. A small set of triggers—robotic crawler deployment rates, certified inspector training pipeline throughput, and pre-salt field development pace—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Europe Oil and Gas Storage Tank Market
Oil & Gas
Qatar Oilfield Service Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
Oil and Gas Industry Turbomachinery Market
Oil & Gas
Crown Block Market
Oil & Gas
Middle East Wireline Services Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Peru Oil and Gas Downstream Market
Oil & Gas
Injection Well Market
Oil & Gas
Oil and Gas Nuclear Magnetic Resonance Market
Oil & Gas
Cuttings Re-Injection Services Market
Oil & Gas
Sidetracking Market
Oil & Gas
Kuwait & Iraq Oilfield Chemicals Market
Oil & Gas
Middle East and Africa Digital Oilfield Market
Oil & Gas
Algeria Oil and Gas Downstream Market
Oil & Gas
Well Abandonment Services Market