
 Bangladesh Solar Energy Market | 2026-2036
Bangladesh Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Bangladesh Solar Energy Market Outlook
The industrial end-user segment is realigning Bangladesh's solar demand profile as export-oriented garment factories pursue captive renewable capacity to meet buyer compliance requirements. Rahimafrooz Renewable Energy Ltd anchors the domestic assembly ecosystem through its battery and module operations. LONGi Solar Technology Co. Ltd leverages its monocrystalline wafer scale to supply high-efficiency modules into utility-scale tenders. Infrastructure Development Company Limited (IDCOL) controls the rural financing architecture that has deployed millions of solar home systems since the early 2000s.
Bangladesh solar energy encompasses photovoltaic systems converting sunlight into direct-current electricity through silicon-based cells, with monocrystalline modules achieving conversion efficiencies above 21% in tropical high-humidity conditions. These installations serve grid-connected generation, industrial self-consumption, and off-grid rural electrification across a nation where per capita electricity consumption remains below regional averages. Rooftop installations dominate the commercial application segment as Dhaka's dense manufacturing zones face land scarcity for ground-mounted arrays. The off-grid application category retains structural importance in char and haor regions beyond grid extension reach, though its growth rate now trails behind grid-connected industrial procurement.
The Bangladesh Energy Regulatory Commission governs wheeling and net metering arrangements that determine project bankability, while the Sustainable and Renewable Energy Development Authority administers fiscal incentives and the national renewable energy policy framework. The Power Division's renewable energy targets and IDCOL's refinancing mechanisms collectively shape developer participation and technology selection criteria. Stakeholders must monitor grid interconnection queue delays and land-use clearance timelines that routinely extend project commissioning schedules beyond original estimates.
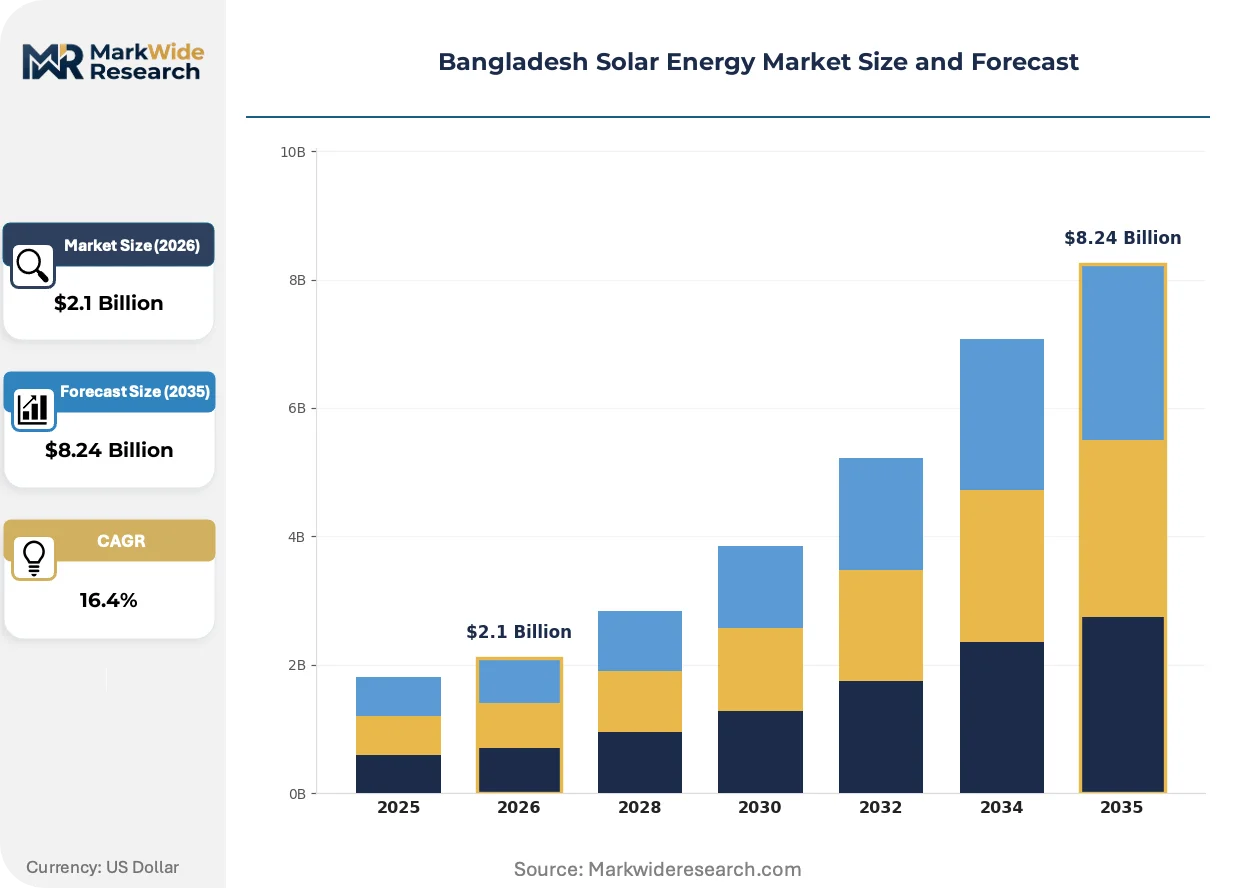
Market Dynamics
The Bangladesh solar energy market is being fundamentally restructured by captive industrial procurement from export-oriented garment factories facing buyer-mandated renewable energy compliance requirements. This demand pull is compressing project development timelines and reshaping financing structures away from traditional rural electrification models toward commercial offtake agreements.
Growth Catalysts
- Net Metering Policy:The Bangladesh Energy Regulatory Commission's wheeling arrangements enable industrial facilities to monetize surplus generation, improving project bankability for rooftop installations in Dhaka's manufacturing zones.
- Garment Sector Compliance Pressure:International apparel brands are requiring Bangladeshi suppliers to demonstrate renewable energy procurement, forcing factories to install captive solar capacity or risk contract cancellation.
- IDCOL Refinancing Architecture:Infrastructure Development Company Limited's long-established rural financing mechanisms are now being adapted for commercial and industrial deployment, lowering capital costs for qualified developers.
Market Restraints
- Grid Interconnection Queue Delays:Bangladesh Power Development Board's limited technical capacity to process connection applications routinely extends commissioning timelines by 12-18 months beyond original estimates.
- Land Scarcity in Manufacturing Zones:Dhaka Division's dense industrial corridors lack available parcels for ground-mounted arrays, forcing developers toward more expensive rooftop and floating configurations.
- Import Dependency for Wafers and Cells:Domestic module assembly relies entirely on imported monocrystalline wafers, exposing project economics to currency fluctuation and supply chain disruption risks from East Asian suppliers.
Strategic Opportunities
- Char and Haor Off-Grid Electrification:Riverine island regions beyond grid extension reach remain structurally underserved, creating sustained demand for solar home systems and mini-grids with embedded storage.
- Floating Solar on Reservoirs:Kaptai Lake and other water bodies offer land-neutral deployment potential, with lower evaporation and improved module cooling performance in tropical conditions.
- Renewable Energy Certificate Trading:Proposed amendments to the Sustainable and Renewable Energy Development Authority framework would enable garment exporters to monetize surplus generation through bilateral certificate sales.
Industry Challenges
- Skilled Installer Shortage:Bangladesh Technical Education Board's certification pipeline produces insufficient qualified technicians for utility-scale and commercial rooftop commissioning, forcing developers to rely on expensive foreign supervision.
- Legacy Grid Infrastructure Incompatibility:Southwestern grid zones near Khulna and Barisal lack voltage regulation capacity to absorb variable solar injection, requiring costly network reinforcement before project energization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bangladesh Solar Energy Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $8.24 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Off-grid Installation Type: Rooftop, Ground-mounted, Community Solar, Building-integrated End User: Households, Corporates, Utilities, NGOs |
| Companies Covered | Solarland Bangladesh Co. Ltd, Solar Electro Bangladesh Ltd, Super Star Renewable Energy Ltd, Infrastructure Development Company Limited (IDCOL), Green Power Ltd, Rahimafrooz Renewable Energy Ltd, Alfanar Group, LONGi Solar Technology Co. Ltd, Sungrow Power Supply Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bangladesh Solar Energy Market Strategic Shifts
Technology deployment patterns in Bangladesh are pivoting from donor-funded rural electrification toward commercially financed industrial self-consumption, with module efficiency standards and financing structures evolving accordingly.
Monocrystalline PERC technology with conversion efficiencies exceeding 21% is rewriting the economics of rooftop installations in Dhaka's garment manufacturing zones. Factory owners are specifying high-efficiency modules to maximize generation per square meter of constrained roof space. This technology compression is enabling viable project returns on smaller footprints where lower-efficiency polycrystalline configurations would fail.
The Sustainable and Renewable Energy Development Authority's proposed renewable energy certificate framework is creating new revenue streams for commercial generators. Industrial facilities with surplus generation will gain tradable instruments to monetize environmental attributes separately from physical electricity. Garment exporters in Dhaka Division are positioning to capture this dual-revenue structure ahead of anticipated buyer compliance timeline tightening.
Buyer aggregation through industrial park developers is consolidating procurement for multiple garment factories under single power purchase agreements. These pooled arrangements reduce transaction costs and enable larger project scales than individual factory rooftops could support. The model is concentrating in export processing zones where park management entities control land and infrastructure coordination.
Bangladesh Solar Energy Market Segmentation
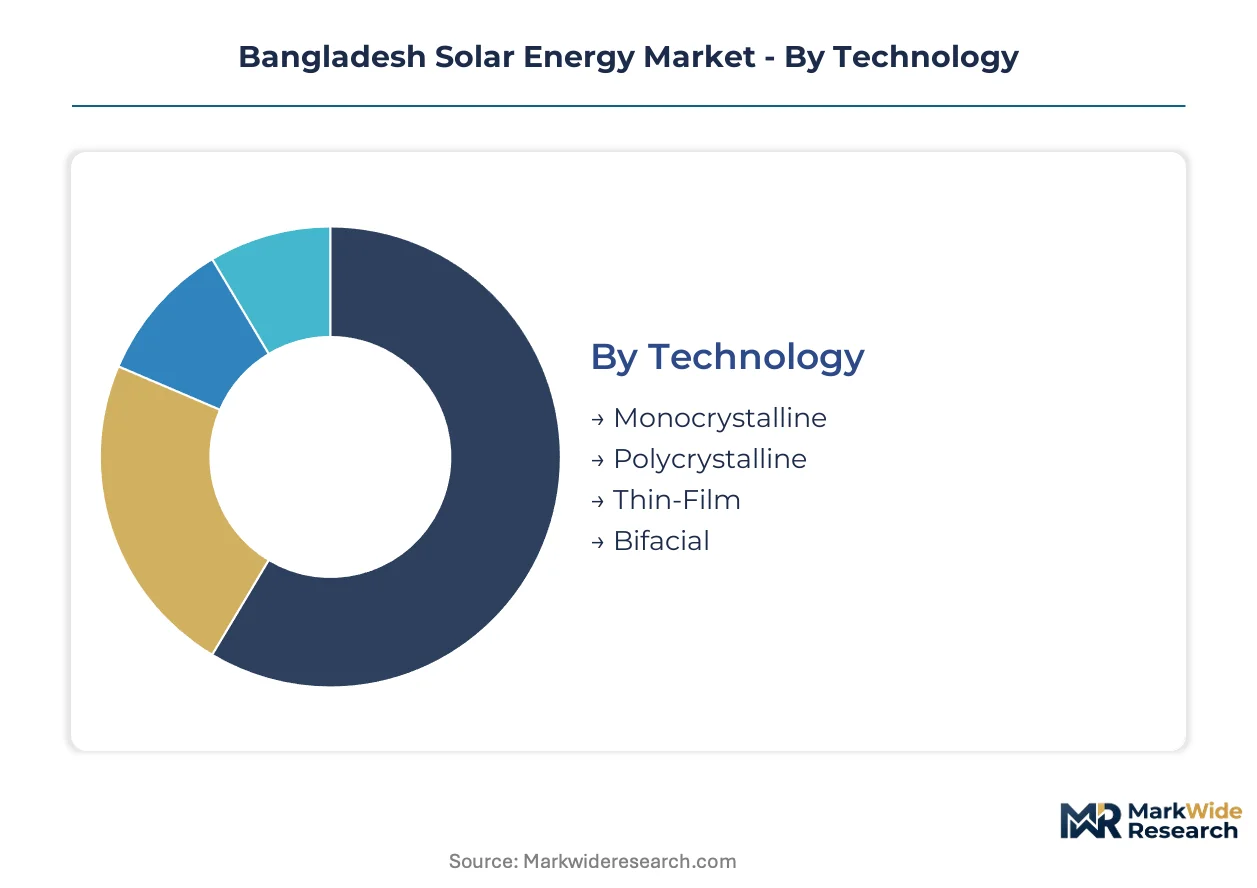
Bangladesh's solar market segments reflect a bifurcation between embedded industrial systems and standalone rural installations. Technology selection and financing structures diverge sharply across these deployment modes, with captive generation commanding premium efficiency specifications while off-grid applications prioritize cost minimization.
Technology:
Monocrystalline and polycrystalline technologies serve fundamentally different integration depths—monocrystalline dominates embedded industrial rooftops where space constraints demand maximum output per square meter, while polycrystalline persists in standalone rural systems where upfront cost sensitivity outweighs efficiency premiums.
- Monocrystalline:Silicon ingots sliced from single-crystal boules achieve conversion efficiencies above 21% in Bangladesh's tropical high-humidity conditions. Dhaka Division's garment manufacturing zones specify these modules exclusively to maximize generation on constrained rooftop footprints where land scarcity prevents ground-mounted alternatives.
- Polycrystalline:Multi-crystalline silicon cells manufactured through directional solidification offer lower production costs at 17-19% efficiency. Rural electrification programs through IDCOL's financing architecture continue procuring these modules for solar home systems in char and haor regions where capital constraints dominate technology selection.
- Thin-Film:Cadmium telluride and amorphous silicon technologies provide flexibility and temperature coefficient advantages in Bangladesh's heat-intensive climate.
- Bifacial:Dual-sided energy capture modules accessing reflected light from rooftops and ground surfaces.
Monocrystalline leads volumes today; bifacial is gaining share fastest in utility-scale tenders.
Application:
Cost-tier segmentation separates premium industrial compliance-driven procurement from subsidized rural access programs, with commercial mid-market applications emerging as a contested zone between these poles.
- Industrial:Captive solar installations at export-oriented garment factories address buyer-mandated renewable energy compliance requirements from international apparel brands. These facilities leverage net metering arrangements to monetize surplus generation, with wheeling agreements through Bangladesh Energy Regulatory Commission improving project bankability.
- Commercial:Retail and office building rooftops in Dhaka's dense urban core face competing claims for HVAC equipment space, forcing smaller system sizes than industrial counterparts. Banking and telecommunications sectors are emerging as anchor tenants for shared solar infrastructure in multi-tenant commercial complexes.
- Residential:Grid-connected rooftop systems for affluent urban households.
- Off-grid:Standalone solar home systems and mini-grids in riverine island regions beyond grid extension reach.
Industrial applications command the highest revenue per installation; commercial is expanding most quickly as net metering awareness spreads.
Installation Type:
Geographic constraints in Bangladesh's manufacturing corridors favor vertical deployment over horizontal, with floating configurations emerging as a land-neutral alternative for utility-scale capacity.
- Rooftop:Elevated mounting structures on factory and commercial buildings dominate Dhaka Division deployment, avoiding land acquisition complexities that routinely extend ground-mounted project timelines. These installations integrate directly with facility electrical infrastructure for self-consumption.
- Ground-mounted:Utility-scale arrays requiring land parcels face scarcity in southwestern grid zones near Khulna and Barisal, where agricultural land-use conflicts and clearance timelines delay commissioning.
- Community Solar:Shared generation assets serving multiple households or small businesses through pooled subscription models.
- Building-integrated:Photovoltaic elements replacing conventional building materials in facade and roofing applications.
Rooftop leads volumes today; floating solar on Kaptai Lake represents the steepest expansion trajectory for utility-scale capacity.
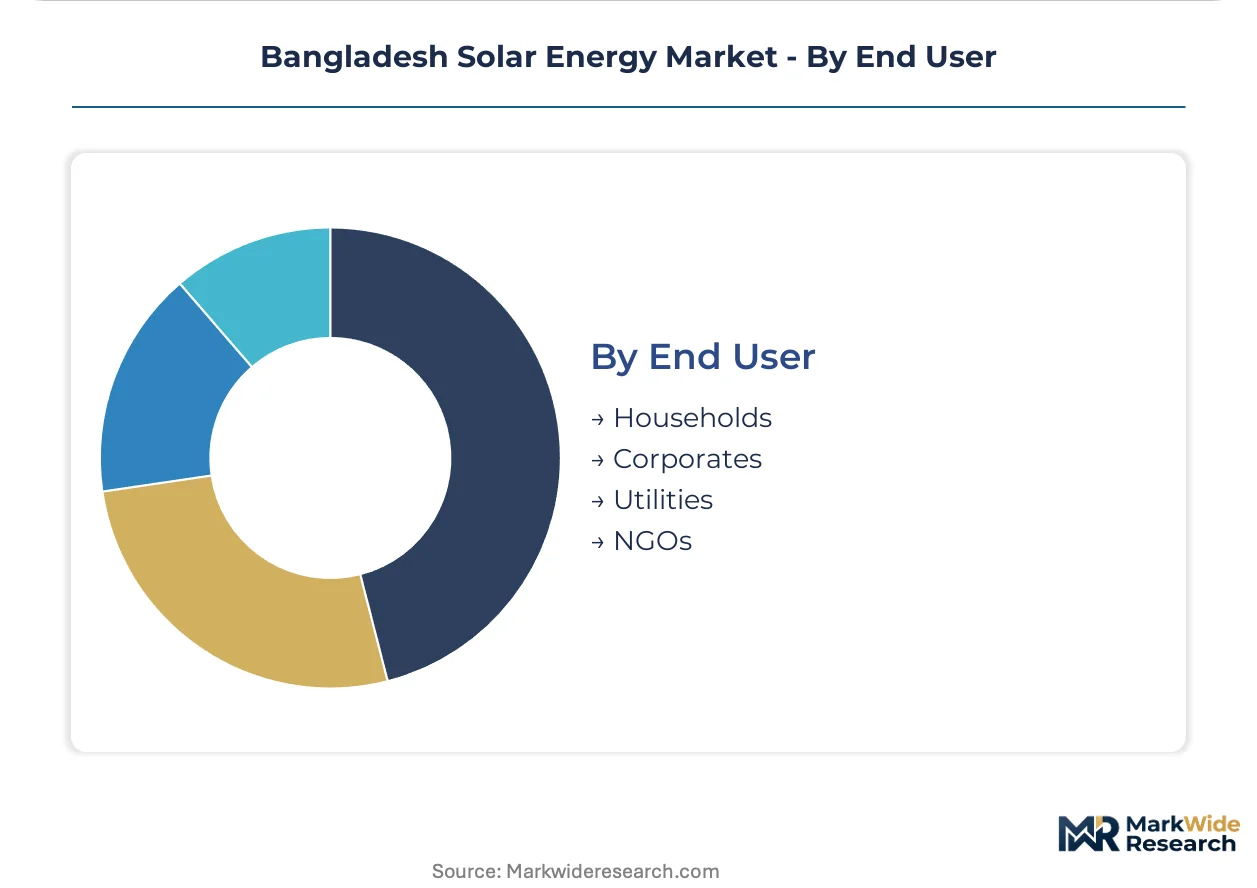
End User:
Customer-type segmentation reveals divergent procurement sophistication, with corporate offtakers negotiating power purchase agreements while household participation depends on intermediary financing structures.
- Corporates:Garment exporters and multinational manufacturing subsidiaries drive procurement volume through direct equipment ownership and long-term offtake contracts. These entities employ dedicated energy managers to navigate Bangladesh Energy Regulatory Commission wheeling arrangements and Sustainable and Renewable Energy Development Authority incentive applications.
- Utilities:Bangladesh Power Development Board and rural electric cooperatives procure utility-scale generation through competitive tendering, though grid interconnection queue delays constrain their absorption capacity.
- Households:Individual consumers accessing solar home systems through IDCOL's microfinance intermediaries.
- NGOs:Development organizations deploying donor-funded installations in underserved regions.
Corporates lead volumes today; utilities are climbing the fastest as tender volumes expand for grid-connected capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting solar module procurement toward jurisdictions with streamlined permitting and stronger fiscal incentives, as manufacturers seek to minimize compliance costs while maintaining supply chain proximity to Bangladesh's garment manufacturing clusters.
Dhaka Division
Garment export zones in Gazipur and Narayanganj drive concentrated rooftop demand as factories install captive capacity to meet buyer compliance mandates. The Bangladesh Energy Regulatory Commission's net metering wheeling arrangements enable surplus monetization, improving project economics for industrial offtakers. Dhaka's dense manufacturing corridors face acute land scarcity, forcing developers toward vertical deployment configurations on factory rooftops.
Khulna Division
Southwestern grid zones near Mongla Port attract utility-scale tender participation due to available land parcels and port access for equipment import. The Power Division's renewable energy targets channel public procurement toward this region, though Bangladesh Power Development Board interconnection queues delay commissioning timelines. Bagerhat and Khulna districts host emerging ground-mounted arrays serving regional load centers.
Barisal Division
Riverine island regions in Patuakhali and Bhola districts sustain off-grid solar home system deployment through IDCOL's microfinance architecture. The Sustainable and Renewable Energy Development Authority's rural electrification framework prioritizes these char areas beyond grid extension reach. Local assembly operations supply lower-specification modules for cost-sensitive household applications.
Chittagong Division
Port infrastructure and emerging export processing zones in Chattogram and Cox's Bazar create dual-demand channels for commercial rooftop and utility-scale procurement. The Chittagong Port Authority's industrial park developments incorporate shared solar infrastructure for multiple tenant factories. Southeastern grid capacity constraints limit absorption rates despite strong developer interest.
Bangladesh Solar Energy Market Competitive Environment
Capacity expansion dominates the current landscape as domestic assemblers and international suppliers race to capture garment sector procurement volume. The vendor base separates into three functional tiers: local battery and module integrators serving rural electrification programs, Chinese wafer-scale suppliers penetrating utility tenders, and regional EPC specialists executing industrial rooftop projects. Strategic archetypes include technology licensors leveraging monocrystalline efficiency advantages, financing intermediaries controlling capital access, and vertically integrated fabricators managing component supply. Competitive intensity centers on module efficiency specifications and offtake agreement structuring.
Among Bangladesh-based system integrators, Rahimafrooz Renewable Energy Ltd anchors domestic assembly operations through its battery and module manufacturing presence. Infrastructure Development Company Limited (IDCOL) occupies a distinctive position as the rural financing intermediary that has shaped deployment economics since the early 2000s. At the international supply tier, LONGi Solar Technology Co. Ltd represents the wafer-scale efficiency leader supplying high-specification modules into space-constrained industrial applications. These three entities exemplify the competitive structure: domestic manufacturing, financing architecture, and technology import respectively.
| Leading Market Players |
|---|
| Solarland Bangladesh Co. Ltd |
| Solar Electro Bangladesh Ltd |
| Super Star Renewable Energy Ltd |
| Infrastructure Development Company Limited (IDCOL) |
| Green Power Ltd |
| Rahimafrooz Renewable Energy Ltd |
| Alfanar Group |
| LONGi Solar Technology Co. Ltd |
| Sungrow Power Supply Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
IDCOL-backed financing intermediaries and family-owned module assemblers anchor Bangladesh's procurement architecture, linking rural microfinance distribution to industrial offtake pricing discipline through shared import dependency on East Asian wafer supply.
Pricing Analysis
Distributor margins on imported monocrystalline modules absorb currency fluctuation risk before factory gate delivery. Project-based contract pricing dominates industrial procurement, with premium efficiency tiers commanding spreads based on conversion performance certification and net metering eligibility documentation. Cost compression in polycrystalline rural systems is intensifying because IDCOL's refinancing rates face sovereign debt pressure. Garment exporters show least price sensitivity; household solar home system buyers exhibit highest.
Supply Chain Analysis
Technician training pipeline gaps in Bangladesh and eastern India's manufacturing zones constrain module assembly scale-up despite available plant capacity. Wafer supply concentrates in China, Vietnam, and Malaysia; domestic Bangladesh operations draw entirely from these sources. Silver paste, aluminum frames, and ethylene-vinyl acetate encapsulant constitute critical input dependencies. Single-source vulnerability from Chinese polysilicon feedstock creates exposure. Distribution runs through IDCOL's rural microfinance intermediaries and direct EPC contracts for industrial rooftops.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bangladesh's solar market functions as a regulatory-arbitrage corridor where net metering wheeling arrangements offer superior project bankability against comparable South Asian jurisdictions lacking surplus monetization frameworks.
For Market Incumbents: Hedge against import duty volatility by securing long-term wafer supply agreements with Vietnamese and Malaysian suppliers before potential tariff realignment. Anchor backward integration into battery assembly through Rahimafrooz's existing lead-acid infrastructure to defend margin position against Chinese integrated storage entrants. For New Entrants and Emerging Players: Capture floating solar development rights on Kaptai Lake before utility-scale tender saturation in southwestern grid zones. Target char and haor mini-grid deployment through IDCOL's adapted commercial financing window, leveraging the most penetrable off-grid segment with embedded storage requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among domestic EPC specialists with established Bangladesh Power Development Board interconnection relationships and garment sector offtake track records. Long-term viability hinges on renewable energy certificate framework implementation. Watch Sustainable and Renewable Energy Development Authority policy amendments as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Assembly | Rahimafrooz leverages existing lead-acid infrastructure to capture storage attach rates in rural electrification. |
| Floating Solar Capacity Buildout | Kaptai Lake deployments bypass Dhaka Division land scarcity while improving module cooling efficiency. |
| Power Purchase Agreement Aggregation | Industrial park developers pool garment factory demand to achieve scale economies unavailable to individual rooftops. |
| Net Metering Compliance Certification | Bangladesh Energy Regulatory Commission documentation unlocks wheeling revenue streams for commercial generators. |
| IDCOL Financing Channel Expansion | Rural microfinance architecture adapts toward commercial and industrial deployment, lowering qualified developer capital costs. |
Study Parameters
Bottom-up garment factory procurement modeling reconciled against top-down wafer import tracking forms the analytical core of this study. Primary interviews with IPP project developers, EPC contractors, Bangladesh Power Development Board planning officers, and IDCOL rural financing administrators combined with secondary validation against Bangladesh Bank import data, Sustainable and Renewable Energy Development Authority incentive registries, and Power Division tender announcements. Triangulation between installation volume estimates and module shipment customs records ensures consistency.
Input-output matrices map capacity additions across technology, application, and installation type dimensions throughout the forecast period. CAGRs derive from segment-level deployment trajectories weighted by net metering eligibility and garment sector compliance timeline assumptions. Grid interconnection queue processing rates and IDCOL refinancing availability function as key forecast sensitivity inputs.
Policy reversal on net metering wheeling, garment buyer mandate acceleration, and taka depreciation against yuan-denominated wafer contracts are the dominant revision risks to modeled outputs. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Residential Solar Shading System Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Solar Pontoon Market
Solar Power Systems
Commercial Solar Panel Market
Solar Power Systems
Solar EVA Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Crystalline Silicon Solar PV Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
Perovskite Solar Module Market
Solar Power Systems
Colombia Solar Energy Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Israel Solar Energy Market
Solar Power Systems
Middle East and Africa Solar PV Inverters Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
CPV Solar Sales Market
Solar Power Systems
Solar Rack Market